


Overview
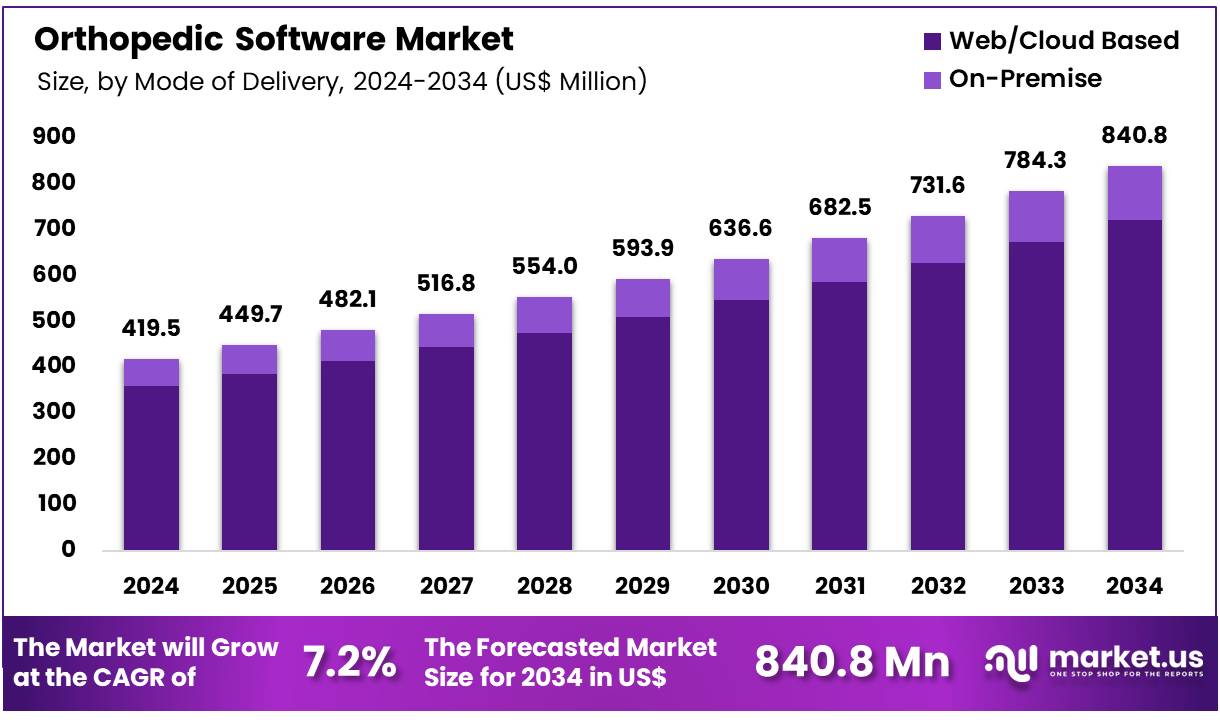
Global Orthopedic Software Market size is expected to be worth around US$ 840.8 Million by 2034 from US$ 419.5 Million in 2024, growing at a CAGR of 7.2% during the forecast period from 2025 to 2034. In 2024, North America led the market, achieving over 41.1% share with a revenue of US$ 172.4 Million.
The global orthopedic software market is witnessing sustained growth as healthcare providers increasingly adopt digital technologies to improve musculoskeletal care, streamline clinical workflows, and support data-driven surgical planning.
The growing burden of orthopedic disorders, combined with rising demand for precision medicine and value-based healthcare, is encouraging hospitals and specialty orthopedic clinics to invest in advanced software platforms for imaging, electronic health records, practice management, surgical planning, and post-operative monitoring.
According to the World Health Organization (WHO), approximately 1.71 billion people worldwide are affected by musculoskeletal conditions, making them the leading contributor to disability globally. This substantial disease burden is accelerating the adoption of digital orthopedic solutions that enhance diagnosis, treatment planning, rehabilitation, and long-term patient management.
Healthcare regulators are also supporting innovation in orthopedic software. In 2025, the U.S. Food and Drug Administration (FDA) granted 510(k) clearance for new orthopedic surgical planning software, reflecting continued regulatory acceptance of digital tools that improve surgical precision and clinical decision-making. The FDA also classifies orthopedic diagnostic and treatment software as regulated medical devices, reinforcing the importance of quality, safety, and performance standards in this rapidly evolving field.
With ongoing advancements in artificial intelligence, cloud computing, and digital imaging, orthopedic software is expected to play an increasingly important role in enhancing patient outcomes, improving operational efficiency, and supporting personalized orthopedic care across healthcare systems worldwide.
Key Takeaways
- The Global Orthopedic Software Market was valued at US$ 419.5 million in 2024 and is projected to reach US$ 840.8 million by 2034, expanding at a CAGR of 7.2% during the forecast period from 2025 to 2034.
- In 2024, the Orthopedic Electronic Health Record (EHR) segment emerged as the leading product category, accounting for 26.7% of the total market share.
- Based on mode of delivery, the Web/Cloud-Based segment dominated the market in 2024, capturing a significant 85.9% share.
- By patient type, the Adult segment held the largest market share of 55.2% in 2024.
- Among applications, the Joint Replacement segment led the market, representing approximately 23.b6% of the total market share in 2024.
- By end use, Hospitals and Clinics remained the dominant segment, accounting for approximately 57.0% of the overall market share in 2024.
- Regionally, North America led the global orthopedic software market in 2024, securing a 41.1% market share and generating US$ 172.4 million in revenue.
Statistical Information
- 95.0% of U.S. office-based physicians had adopted an Electronic Health Record (EHR) system in 2024, while 83.6% used a certified EHR, demonstrating the widespread digital infrastructure supporting orthopedic software adoption.
- More than 99% of U.S. non-federal acute care hospitals had adopted certified EHR technology by 2024, enabling broader deployment of orthopedic imaging, documentation, and surgical planning software.
- The World Health Organization estimates that 1.7 billion people worldwide are living with musculoskeletal conditions, making them the leading cause of disability and a major driver for orthopedic digital health solutions.
- Low back pain affected approximately 619 million people globally in 2020 and is projected to impact 843 million people by 2050, increasing demand for orthopedic diagnosis, treatment planning, and rehabilitation technologies.
- According to the Office of the National Coordinator for Health IT (ONC), 91% of U.S. office-based physicians had adopted certified EHR technology by 2024, more than double the adoption rate recorded in 2008.
- The FDA classifies software used for the diagnosis or treatment of traumatic and reconstructive orthopedic conditions as Class II medical devices requiring 510(k) premarket review, ensuring safety and clinical performance before commercialization.
- In 2026, the FDA and CMS proposed integrating Unique Device Identifier (UDI) capture into certified EHR systems for implantable medical devices, improving traceability, post-market surveillance, and patient safety for orthopedic implants.
- CMS Fast Facts 2026 reports that Medicare data include information from 2024 on institutional providers, physician specialties, and durable medical equipment providers, highlighting the scale of digital healthcare data supporting orthopedic care and health IT integration.
Regional Analysis
In 2024, North America accounted for the largest share of the global orthopedic software market, representing 41.1% of total revenue and reaching US$ 172.4 million. The region’s leadership is supported by its advanced healthcare infrastructure, widespread adoption of digital health technologies, and strong implementation of electronic health record (EHR) systems across hospitals and orthopedic practices.
The U.S. Centers for Disease Control and Prevention (CDC) continues to monitor nationwide EHR adoption through the National Electronic Health Records Survey, highlighting the maturity of digital health infrastructure in the region.
Another major growth driver is the high burden of musculoskeletal disorders, which increases demand for digital orthopedic solutions that improve diagnosis, surgical planning, and patient management. The U.S. Food and Drug Administration (FDA) also provides a well-defined regulatory pathway for orthopedic diagnostic and treatment software, supporting innovation while ensuring safety and effectiveness of software-based medical devices.
Furthermore, healthcare providers across the United States and Canada are increasingly investing in cloud-based platforms, AI-enabled clinical tools, and interoperable healthcare systems to improve workflow efficiency and patient outcomes. Continued investments in digital transformation and supportive regulatory frameworks are expected to reinforce North America’s leading position in the orthopedic software market.
Emerging Trends
- AI-powered orthopedic planning is expanding rapidly. A 2026 review identified 70 FDA-cleared AI-enabled orthopedic medical devices by February 2025. The annual average of new clearances increased from 3.0 devices (2017–2019) to 16.6 devices (2022–2024), showing growing clinical adoption of AI-assisted orthopedic software.
- Deep learning is becoming the preferred technology in orthopedic software. Among FDA-cleared AI orthopedic devices approved between 2022 and 2024, 57.3% used deep learning algorithms, enabling more accurate fracture detection, surgical planning, and image interpretation while supporting faster clinical decisions.
- Software validation standards are improving. The share of AI orthopedic devices without clinical testing declined from 62.2% (2017–2019) to 19.7% (2022–2024), reflecting stronger regulatory expectations and greater confidence in clinically validated orthopedic software solutions.
- Interoperable digital health systems are strengthening orthopedic workflows. The CDC reported that U.S. office-based physicians used EHR systems in 2024, supporting seamless integration of orthopedic software with patient records, imaging systems, and clinical decision tools.
- Real-world clinical data is becoming essential for orthopedic software development. The FDA increasingly supports the use of electronic health records, patient registries, and device-generated data as real-world evidence to evaluate medical devices and improve software performance throughout their lifecycle.
Use Cases
- AI-assisted fracture diagnosis is improving radiology workflows. Modern orthopedic software automatically analyzes X-rays and CT scans, helping clinicians detect fractures earlier and prioritize urgent cases, reducing interpretation time while improving diagnostic consistency across healthcare facilities.
- Digital surgical planning is enhancing joint replacement procedures. Orthopedic software combines 3D imaging, patient anatomy, and predictive analytics to support implant selection and preoperative planning, enabling surgeons to improve precision and personalize treatment before surgery begins.
- Cloud-connected orthopedic platforms improve multidisciplinary care. Hospitals use integrated software to securely share orthopedic imaging, laboratory results, operative notes, and rehabilitation data, allowing orthopedic surgeons, radiologists, and physiotherapists to collaborate more efficiently through connected EHR systems.
- Predictive analytics supports postoperative patient management. Orthopedic software analyzes electronic medical records and clinical data to identify patients at higher risk of complications, readmissions, or delayed recovery, allowing healthcare teams to intervene earlier with personalized follow-up care.
- Orthopedic software strengthens registry-based outcome tracking. Healthcare providers increasingly use digital platforms linked with clinical registries and routine patient data to monitor implant performance, treatment outcomes, and long-term recovery, supporting evidence-based orthopedic care and continuous quality improvement.
Frequently Asked Questions About Orthopedic Software
- What is orthopedic software and how does it help healthcare providers?
Orthopedic software is a specialized digital healthcare solution that helps orthopedic professionals manage patient records, analyze medical images, plan surgeries, track implants, and monitor treatment outcomes. It improves workflow efficiency, supports clinical decisions, and enables more personalized orthopedic care. - What are the main applications of orthopedic software?
Orthopedic software is mainly used for electronic health records (EHR), surgical planning, imaging analysis, implant management, orthopedic practice management, rehabilitation tracking, and patient monitoring. These applications help surgeons improve accuracy, reduce administrative workload, and enhance coordination across healthcare teams. - How does artificial intelligence impact orthopedic software?
Artificial intelligence enhances orthopedic software by analyzing medical images, detecting abnormalities, supporting diagnosis, and providing predictive insights. AI-powered tools assist surgeons in fracture assessment, surgical planning, and treatment decisions by improving speed, accuracy, and consistency in orthopedic workflows. - Why is cloud-based orthopedic software gaining adoption?
Cloud-based orthopedic software allows healthcare providers to securely access patient information, imaging files, and clinical data from multiple locations. It improves collaboration between orthopedic specialists, supports remote access, reduces infrastructure requirements, and enables easier software updates and scalability. - What factors are driving the growth of the orthopedic software market?
The orthopedic software market is growing due to increasing adoption of digital healthcare systems, rising demand for advanced surgical technologies, growing orthopedic disease burden, integration of artificial intelligence, and the need for efficient patient data management across hospitals and specialty clinics. - Is orthopedic software considered a medical device?
Certain orthopedic software products are regulated as medical devices when they perform functions such as diagnosis, surgical planning, navigation, or clinical decision support. Regulatory agencies, including the U.S. FDA, evaluate these solutions to ensure safety, reliability, and effectiveness. - What are the future trends in the orthopedic software market?
Future trends in orthopedic software include increased adoption of AI-based analytics, 3D surgical visualization, cloud platforms, interoperability with electronic health records, and patient-specific treatment planning. These advancements are expected to improve clinical efficiency, surgical accuracy, and personalized orthopedic care.
Conclusion
The global orthopedic software market is advancing as healthcare providers increasingly adopt digital solutions to improve orthopedic diagnosis, surgical planning, patient management, and clinical workflows. Rising demand for AI-powered tools, cloud-based platforms, and interoperable healthcare systems is transforming orthopedic care delivery. Regulatory support for software-based medical technologies, including FDA oversight of Software as a Medical Device (SaMD), is encouraging innovation while maintaining safety standards.
With continued digital transformation, increasing musculoskeletal disease burden, and growing adoption of personalized treatment approaches, orthopedic software is expected to become an essential component of modern healthcare infrastructure, supporting improved outcomes, operational efficiency, and data-driven decision-making worldwide.





