


Report Overview
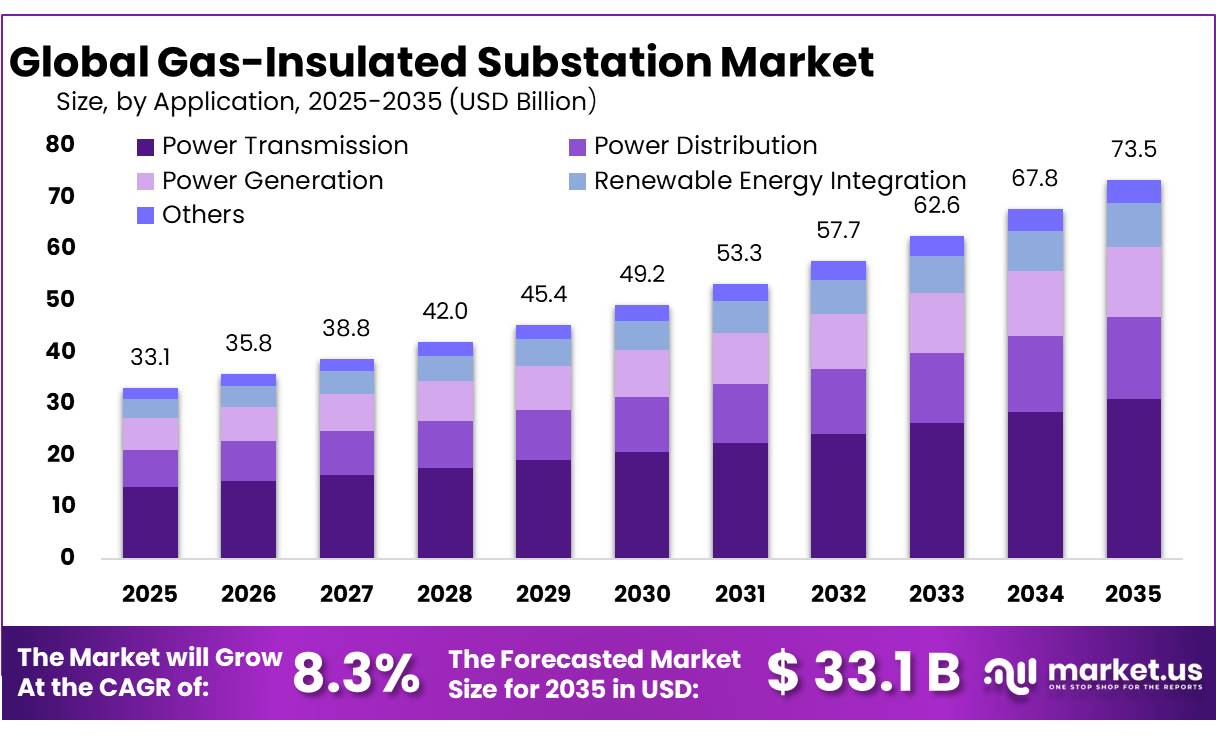
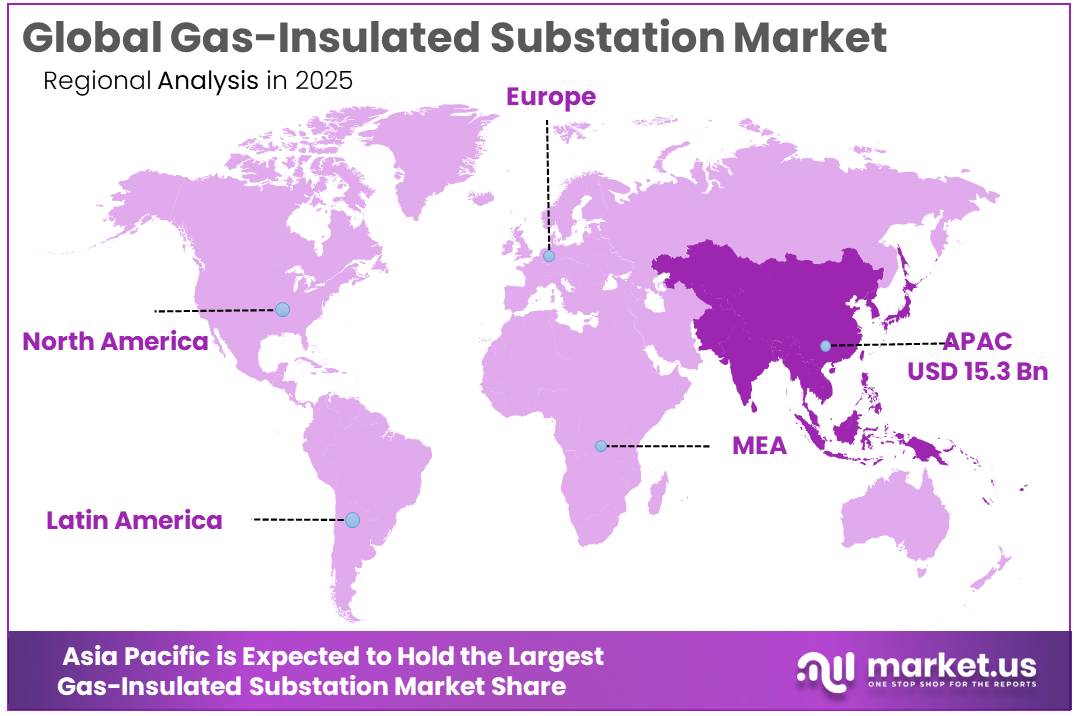
The Global Gas-Insulated Substation Market size is expected to be worth around USD 73.5 Billion by 2035, from USD 33.1 Billion in 2025, growing at a CAGR of 8.3% during the forecast period from 2026 to 2035. In 2025, Asia Pacific held a dominant market position, capturing more than a 46.50% share, holding USD 15.3 Billion revenue.
Gas-insulated substations (GIS) are compact high-voltage installations in which circuit breakers, busbars, disconnectors and other energized equipment are enclosed inside metal compartments and insulated with gas. They are suited to dense cities, industrial sites, offshore wind connections and constrained locations.
- The International Energy Agency reported that global electricity demand reached about 28,600 TWh in 2025 and is expected to rise to 30,700 TWh by 2027. Demand is forecast to increase 3.6% in 2026, supported by industry, data centers, electric vehicles and cooling.
Investment in grids is also creating a strong project pipeline. The IEA estimated that around USD 400 billion is now spent on electricity grids worldwide each year, while total electricity-sector investment was set to reach USD 1.5 trillion in 2025. In the United States, the Department of Energy announced approximately USD 1.9 billion in March 2026 under its SPARK program to accelerate transmission upgrades.
Europe is another important growth area because transmission expansion and cross-border interconnection remain policy priorities. ENTSO-E stated in January 2025 that around 108 GW of additional cross-border capacity would be economically beneficial by 2040, while 224 GW of extra cross-border transmission capacity could be efficient by 2050. It also estimated that every euro invested in electricity infrastructure could save more than two euros in total system costs.
- Environmental regulation is reshaping product development. Under the European Union’s fluorinated-gas rules, restrictions apply to new high-voltage switchgear above 52 kV and up to 145 kV from January 2028, while equipment above 145 kV faces tighter requirements from January 2032. This creates a direct opportunity for SF₆-free GIS. Hitachi Energy already offers a 420 kV EconiQ GIS with rated current of 5,000 A and short-time withstand current of 63 kA, showing that alternative-gas technology has moved into transmission-class applications.
GE Vernova’s F35g GIS, for example, operates up to 145 kV and its g³ insulation technology can reduce the gas-related CO₂-equivalent contribution by 99%. As renewable generation, electrification and data-center loads expand, utilities are likely to favor compact, digitally monitored GIS platforms that combine high reliability with lower environmental impact. GE Vernova F35g SF₆-Free GIS
Key Takeaways
- Gas-Insulated Substation Market size is expected to be worth around USD 73.5 Billion by 2035, from USD 33.1 Billion in 2025, growing at a CAGR of 8.3%.
- High Voltage held a dominant market position, capturing more than a 51.90% share in the Gas-Insulated Substation Market.
- Indoor held a dominant market position, capturing more than a 58.70% share in the Gas-Insulated Substation Market.
- Indoor GIS held a dominant market position, capturing more than a 58.70% share in the Gas-Insulated Substation Market.
- Power Transmission held a dominant market position, capturing more than a 42.00% share in the Gas-Insulated Substation Market.
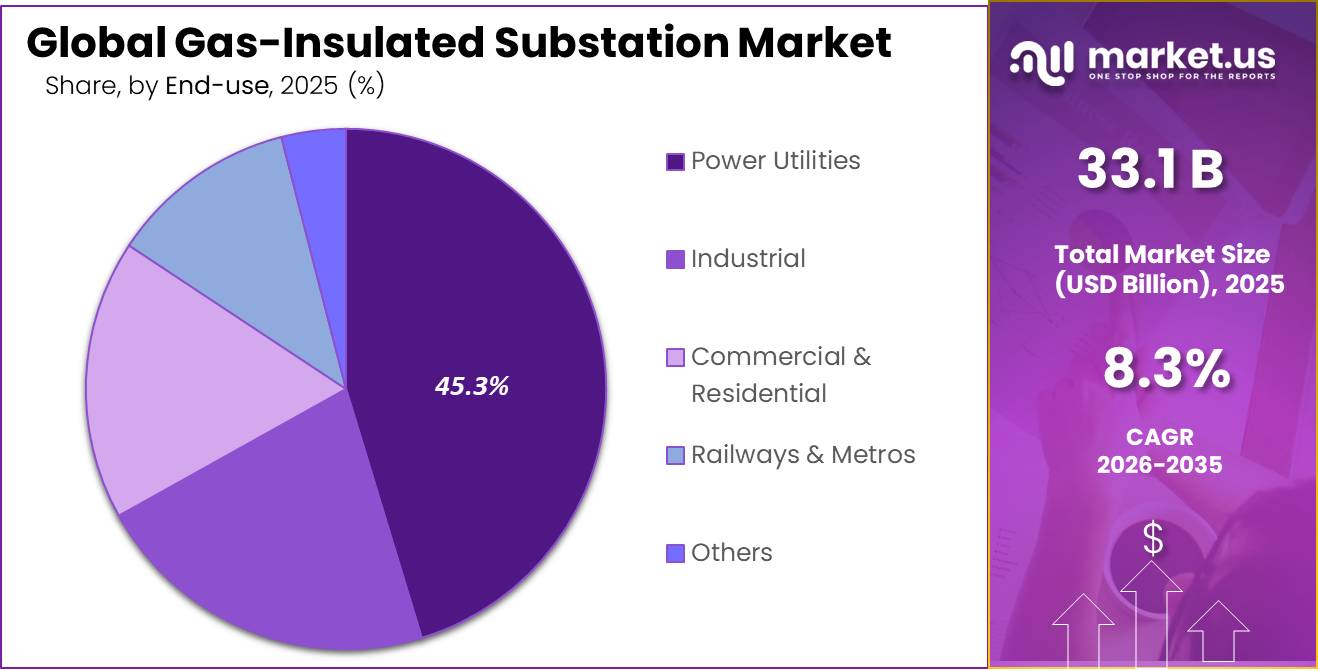
- Power Utilities held a dominant market position, capturing more than a 45.30% share.
By Voltage Analysis
High Voltage Leads with 51.90% Share as Transmission Networks Expand
In 2025, “High Voltage” held a dominant market position, capturing more than a 51.90% share in the Gas-Insulated Substation Market. Its leading position is supported by the growing need for compact substations in transmission networks, renewable power connections, dense urban areas, and large industrial power systems. In June 2025, the European Commission estimated that around EUR 477 billion would be required for transmission-grid development by 2040, showing the scale of infrastructure investment supporting high-voltage substations.
In March 2026, the U.S. Department of Energy also announced approximately USD 1.9 billion for critical grid upgrades under the SPARK program, while the wider GRIP program was authorized for up to USD 10.5 billion over five years. These investments support replacement and expansion of transmission equipment, including high-voltage GIS where space efficiency and reliability are important.
Medium Voltage remained an important segment of the Gas-Insulated Substation Market in 2025, supported by distribution-grid modernization, renewable-energy connections, electric-vehicle charging, industrial facilities, and urban power networks. In June 2025, the European Commission estimated that approximately EUR 730 billion of investment would be required for electricity distribution grids by 2040, considerably expanding the need for modern medium-voltage substations and switchgear.
A European Commission-backed medium-voltage modernization program scheduled for completion in June 2026 also allocated EUR 20 million to build or reconstruct at least 279 kilometres of medium-voltage distribution network. The program includes new control systems and sensor technologies, showing how medium-voltage infrastructure is moving toward more digital, compact, and flexible designs suitable for distributed generation and changing electricity demand.
By Installation Analysis
Indoor installation dominates with a 58.70% share, supported by compact GIS deployment in high-voltage transmission projects.
In 2025, Indoor held a dominant market position, capturing more than a 58.70% share in the Gas-Insulated Substation Market. Indoor GIS is widely selected where utilities need high-voltage equipment within a smaller and protected footprint, particularly in urban areas, industrial sites, and space-constrained transmission locations. In November 2025, Neath Port Talbot Council recorded a proposal to expand the Margam 275 kV substation with a dedicated gas-insulated switchgear hall. A separate UK planning application submitted in November 2025 covered a new 400 kV GIS substation at Whiston, and the project received conditional approval in August 2026.
Outdoor installation continued to hold an important position in the Gas-Insulated Substation Market in 2025, particularly for large transmission corridors, renewable-energy connections, and utility sites with more available land. Government planning documents for major UK energy projects show that substation designs can combine outdoor transmission equipment with GIS where project layout and space requirements allow.
In April 2026, planning documents for the Eaton Socon connection included a new 400 kV generation bay and allowed either outdoor air-insulated equipment or indoor GIS, showing how installation choice remains closely tied to site conditions and grid design. In July 2026, Somerset Council also registered a project containing 132 kV and 400 kV GIS substations with five 460 MVA super-grid transformers, highlighting continued investment in large utility-scale substation infrastructure.
By Insulation Type Analysis
Indoor GIS dominates with a 58.70% share, supported by compact 400 kV transmission projects and rising grid investment.
In 2025, Indoor GIS held a dominant market position, capturing more than a 58.70% share in the Gas-Insulated Substation Market. Indoor GIS is preferred where utilities need high-capacity electrical equipment within a protected and compact building, especially at urban, industrial, and space-constrained sites. In September 2025, official UK Planning Inspectorate documents for the East Park Energy project included an option for an indoor GIS generation bay operating at 400 kV at the Eaton Socon Substation.
In June 2025, the European Commission estimated that around EUR 477 billion would be required for transmission-grid development by 2040. This large investment requirement supports future installation of compact GIS equipment as transmission capacity expands and existing substations are modernized.
Outdoor GIS continued to support the Gas-Insulated Substation Market in 2025, particularly in large transmission projects, renewable-energy connections, and utility sites with greater available space. Official UK Sea Link documents published in 2025 describe new GIS bays together with associated outdoor structures at the Friston Substation and a new 400 kV GIS substation at Minster.
The Minster site is planned to occupy approximately 9 hectares, while its wider connection includes about 3.5 km of new overhead transmission line and replacement of another 2.2 km. In March 2026, the U.S. Department of Energy also announced approximately USD 1.9 billion for grid upgrades, supporting continued investment in transmission substations, advanced switchgear, and related high-voltage infrastructure.
By Application Analysis
Power Transmission dominates with a 42.00% share, supported by large-scale grid expansion and rising electricity-transfer requirements.
In 2025, “Power Transmission” held a dominant market position, capturing more than a 42.00% share in the Gas-Insulated Substation Market. The segment benefits from the need for reliable high-voltage connections between generation plants, renewable projects, cities, and major industrial loads. In June 2025, the European Commission estimated that around EUR 477 billion would be required for transmission-grid development, including offshore networks, through 2040.
In March 2026, the U.S. Department of Energy also announced approximately USD 1.9 billion under the SPARK program for transmission and grid-capacity upgrades. These investments support demand for compact high-voltage GIS installations where reliability, limited land availability, and higher power-transfer capability are important.
Power Distribution continued to represent an important application of gas-insulated substations in 2025, particularly across urban networks, industrial areas, renewable connections, data centers, and other locations where compact electrical infrastructure is required.
In June 2025, the European Commission estimated that electricity distribution networks would require around EUR 730 billion of investment through 2040. It also noted that distribution-level investment could account for roughly two-thirds of future European grid investment, compared with around one-third for transmission.
By End User Analysis
Power Utilities dominate with a 45.30% share, supported by rising spending on transmission capacity
In 2025, “Power Utilities” held a dominant market position, capturing more than a 45.30% share in the Gas-Insulated Substation Market. Power utilities remain the main users of GIS because they require compact, reliable equipment for transmission upgrades, renewable connections, and urban substations.
In 2025, the International Energy Agency reported that around USD 400 billion was being spent on electricity grids worldwide each year, while roughly USD 1 trillion was being invested in generation assets. In March 2026, the U.S. Department of Energy announced approximately USD 1.9 billion for advanced transmission and grid upgrades under the SPARK program. The wider GRIP program was authorized for up to USD 10.5 billion over five years, supporting utility investment in stronger and more flexible networks.
Industrial remained an important end-user segment of the Gas-Insulated Substation Market in 2025, supported by manufacturing plants, mining operations, processing facilities, large industrial complexes, and other electricity-intensive sites. U.S. Energy Information Administration data showed that industrial customers consumed around 1.042 trillion kWh of electricity in 2025, highlighting the large power requirement of industrial operations.
Key Market Segments
By Voltage
- Medium Voltage
- High Voltage
- Extra-High Voltage
By Installation
- Indoor
- Outdoor
By Insulation Type
- Indoor GIS
- Outdoor GIS
By Application
- Power Transmission
- Power Distribution
- Power Generation
- Renewable Energy Integration
- Others
By End User
- Power Utilities
- Industrial
- Commercial & Residential
- Railways & Metros
- Others
Driver Analysis
Grid Expansion and Renewables Integration
Grid reinforcement is the largest GIS demand accelerator because variable renewable generation requires additional switching nodes, transformation capacity and high-reliability interconnections near generation clusters and load centers: global renewable additions reached 473 GW in 2023, equal to 86% of all power-capacity additions, including 346 GW of solar alone, while the IEA estimates grid investment must rise from the recent level of about USD 320 billion annually to more than USD 600 billion by 2030, with emerging and developing economies needing roughly twice their 2022 annual investment and advanced economies requiring a one-third increase under the Announced Pledges Scenario.
The national pipelines convert that macro requirement into bankable equipment orders: India plans more than 191,000 circuit-km of lines, 1,270 GVA of transformation capacity and 33 GW of HVDC links over 2022–2032, supported by over INR 9.15 trillion of transmission investment, while interregional capacity is scheduled to rise from 119 GW to 168 GW; China, meanwhile, announced approximately CNY 4 trillion of State Grid fixed-asset investment for 2026–2030, 40% above the previous five-year cycle.
GIS captures a disproportionate share where substations must be compact, sealed, pollution-resistant or integrated into HVDC converter complexes, shifting supplier economics from isolated switchgear sales toward multi-year turnkey packages covering busbars, breakers, protection, civil integration, commissioning and lifecycle service; weighting the investable grid pipeline by the GIS-suitable urban, coastal and high-voltage share supports an estimated +2.6 percentage-point contribution to 2026–2031 market CAGR, with China and India providing volume and Europe and North America supplying higher-value modernization demand.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Grid expansion and renewables | +2.6 pp | China, India, EU, North America | Medium term (2–4 years) |
| Urban space-constrained substations | +1.5 pp | APAC cities, GCC, EU metros | Long term (≥4 years) |
| Data-center load concentration | +1.3 pp | US, China, EU, India, ASEAN | Short term (≤2 years) |
| SF6-free replacement cycle | +1.2 pp | EU core; global spill-over | Medium term (2–4 years) |
| Offshore-grid buildout | +0.9 pp | Europe, China, Korea, Japan, US | Medium term (2–4 years) |
| Digital substation conversion | +0.8 pp | North America, EU, China, GCC | Medium term (2–4 years) |
Restraint Analysis
High Upfront Capital
GIS remains economically selective because its sealed metal-enclosed bays, precisionmachined conductors, interrupters, gas compartments, factory testing and specialist erection concentrate expenditure before energization, whereas AIS can often be staged with simpler outdoor equipment; a utility study of a 400/110 kV double-busbar project estimated GIS switchgear, installation and maintenance at roughly 11% above AIS on a directly comparable basis, although adding land, civil works and common systems narrowed the full-project totals to EUR 25.39 million for GIS versus EUR 25.29 million for AIS.
This near parity depended on GIS using only 2.6 acres against 11.6 acres for AIS—about 78% less land—so the value proposition weakens sharply where land is inexpensive, pollution is moderate and permitting does not penalize a larger footprint; a separate Indian feasibility model found positive conversion economics only when urban land exceeded approximately INR 45 million per acre at 132 kV, INR 75 million at 220 kV or INR 70 million at 400 kV, with estimated GIS all-in bay costs of INR 30 million, INR 50 million and INR 80 million, respectively.
High interest rates and weak utility balance sheets therefore delay GIS in emerging markets even when lifecycle reliability is attractive, because a 10–20% initial equipment premium on a USD 30–100 million substation can add USD 3–20 million to financing needs and expose the EPC contractor to milestonepayment and currency risk; the resulting substitution toward AIS, hybrid substations or deferred capacity underpins an estimated -1.9 percentage-point drag on potential CAGR, persistent beyond four years in Africa, Latin America and price-sensitive Asian utilities unless urban land monetization, concessional finance or availability-based procurement internalizes GIS’s footprint and outage benefits.
Restraint Impact Analysis
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High upfront capital | -1.9 pp | Emerging APAC, Africa, LatAm | Long term (≥4 years) |
| SF6 compliance transition | -1.5 pp | EU core, US states, global tenders | Medium term (2–4 years) |
| Equipment supply bottlenecks | -1.3 pp | North America, EU, India, GCC | Short term (≤2 years) |
| Long approval cycles | -1.0 pp | EU, North America, South Asia | Long term (≥4 years) |
| Material-cost volatility | -0.8 pp | Global; import-dependent markets | Short term (≤2 years) |
| Skills and service scarcity | -0.7 pp | North America, EU, GCC, Africa | Medium term (2–4 years) |
Opportunity Analysis
SF6-Free Fleet Conversion
This opportunity is not the existing regulatory driver itself, but the still-underdeveloped service layer around it: multi-site asset audits, insulation-gas migration engineering, bay-by-bay replacement, outage sequencing, operator training, warranties and guaranteed-emissions contracts. Regulation (EU) 2024/573 creates successive commissioning cut-offs—1 January 2026 for switchgear up to 24 kV, 1 January 2028 for 52–145 kV equipment up to 50 kA, 1 January 2030 for above 24–52 kV, and 1 January 2032 for equipment above 145 kV or 50 kA—while SF6 carries a 100-year global-warming potential of 24,300, making board-level decarbonisation unavoidable even where formal bans do not yet apply.
Europe estimates €584 billion of grid investment is required by 2030 and reports that 40% of distribution grids are more than 40 years old; applying an analyst assumption that 2–4% of this programme touches GIS replacement, extension or associated engineering yields a €11.7–23.4 billion conversion pool, and an 8–12% services attach rate creates approximately €0.9–2.8 billion of incremental, higher-margin revenue beyond equipment sales. Vendors can capture this white space through five-to-ten-year framework agreements priced per bay, avoided tonne of CO2-equivalent or achieved availability, thereby replacing episodic tender revenue with backlog visibility and recurring inspection income; under a 20–30% addressable-vendor capture scenario and 2027–2031 ramp, this model supports roughly +2.0 percentage points of potential market CAGR upside.
Opportunity Impact Analysis
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| SF6-free fleet conversion | +2.0 pp | EU core; UK, APAC spillover | Short term (≤2 years) |
| Digital lifecycle subscriptions | +1.4 pp | North America, EU, Japan, GCC | Medium term (2–4 years) |
| Modular GIS leasing pools | +1.1 pp | North America, Caribbean, APAC | Short term (≤2 years) |
| Offshore grid interface modules | +1.3 pp | North Sea, Baltic, China, Korea | Medium term (2–4 years) |
| Circular gas services | +0.8 pp | EU first; North America, Japan | Medium term (2–4 years) |
| Financed emerging-market EPC | +1.2 pp | India, ASEAN, Africa, Latin America | Long term (≥4 years) |
Challenges Analysis
Gas-Transition Fragmentation
The structural challenge is not the existence of an SF6 phase-down itself, but the simultaneous qualification of multiple insulating architectures—clean air, fluoronitrile mixtures, fluoroketone mixtures, vacuum interruption, and hybrid designs—across voltage classes, climatic envelopes, pressure regimes, and utility specifications; the EU timetable now prohibits commissioning affected F-gas switchgear up to 24 kV from 1 January 2026, extends to above 52 kV through 145 kV and up to 50 kA from 1 January 2028, covers above 24 kV through 52 kV from 2030, and reaches above 145 kV or above 50 kA from 2032, creating four overlapping redesign and tender-conversion waves rather than one standardized replacement cycle.
CIGRE reported that minor modifications can deliver SF6-free performance and comparable dimensions up to 170 kV, but that boundary still leaves ultra-high-voltage applications, atypical fault duties, cold-climate derating, gas-handling procedures, and installed-fleet compatibility requiring project-specific validation. Alternative fluorinated mixtures can cut lifecycle climate impact by more than 99% versus SF6, yet they introduce different occupational exposure limits—65 ppm for one fluoronitrile and 225 ppm for one fluoroketone on an eight-hour basis—and therefore different filling, recovery, ventilation, training, and emergency-response protocols.
The model assumes that duplicate type testing, spare-gas inventories, technician certification, and utility approval add roughly 3–8% to engineering and qualification cost and 3–9 months to first-of-kind project schedules through 2028–2030, imposing about 1.4 percentage points of attainable CAGR friction; mitigation requires platform rationalization by voltage tier, common gas-quality and recovery specifications, cross-OEM service tooling, and framework contracts that convert fragmented pilots into repeatable product families.
Challenges Impact Analysis
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Gas-transition fragmentation | -1.4 pp | EU core; global spillover | Long term (≥ 4 years) |
| Capacity coordination gaps | -1.2 pp | North America; EU; APAC | Medium term (2–4 years) |
| Specialist workforce scarcity | -1.0 pp | North America; EU; Australia; GCC | Long term (≥ 4 years) |
| Digital interoperability exposure | -0.8 pp | North America; EU; East Asia | Medium term (2–4 years) |
| Condition-monitoring uncertainty | -0.7 pp | Global installed base | Medium term (2–4 years) |
| Brownfield integration complexity | -0.6 pp | Europe; Japan; North America | Long term (≥ 4 years) |
Geopolitical Impact Analysis
The ongoing Russia–Ukraine war continues to affect the Gas-Insulated Substation market by damaging transmission assets while creating urgent demand for replacement, protection, and grid reconstruction. The International Energy Agency reported in February 2026 that Russian attacks have repeatedly targeted critical electricity nodes, including substations, because failures at these points can disconnect generators and require costly, time-consuming repairs. This is increasing the importance of compact GIS, mobile substations, digital monitoring, spare equipment, and more resilient grid layouts.
The World Bank, European Commission, United Nations, and Government of Ukraine estimated in February 2026 that Ukraine’s reconstruction and recovery requirement had reached almost USD 588 billion over the next decade. Energy-sector assets damaged or destroyed increased by about 21% compared with the previous assessment, covering generation, transmission, distribution, and district-heating infrastructure.
For GIS suppliers, the war creates a mixed market effect. Reconstruction and cross-border grid integration support new substation orders, while security risks, transport disruption, higher insurance costs, and pressure on equipment supply can slow project execution. Utilities are also placing greater value on protected indoor GIS, decentralized networks, redundancy, remote operation, and faster equipment replacement, strengthening long-term demand for resilient high-voltage substation technology.
Regional Insights
In 2025, Asia Pacific held a dominant market position, capturing more than a 46.50% share and reaching USD 15.38 billion. China remains a major regional demand center. During the first nine months of 2025, Chinese power-grid investment reached CNY 437.8 billion, while installed generation capacity climbed to 3.72 billion kW by September, up 17.5% year over year. State Grid also reported 41 ultra-high-voltage projects in operation during 2025. Growing solar, wind, industrial loads, and cross-regional power transfers are increasing requirements for compact, reliable high-voltage substations, giving GIS technology a strong role in Asia Pacific grid modernization.
- Asia Pacific remains the strongest market because utilities are adding high-voltage lines, substations, and renewable connections at scale. In China, national power-grid investment reached CNY 639.5 billion in 2025, while electricity consumption moved above 10 trillion kWh. The country also operated more than 1 million kilometres of transmission lines rated 220 kV and above.
The Middle East is emerging as the fastest-growing regional segment, supported by higher electricity demand, renewable integration, and accelerated transmission construction. The IEA reported that Middle Eastern electricity demand increased by nearly 4% in 2025, while solar generation across the region rose by at least 20%. Saudi Arabia illustrates this expansion clearly. By the first half of 2026, its transmission network reached 108,141 circuit-kilometres, while transmission substations increased to 1,364 and transformer capacity reached 559,831 MVA.
Key Regions and Countries Insights
- North America
- US
- Canada
- Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Key Players Analysis
ABB Ltd. supports substation modernization through electrification, switchgear, protection, automation, and distribution technologies. In 2025, ABB generated USD 33.22 billion in group revenue, while its Electrification business recorded USD 17.36 billion in revenue and USD 18.76 billion in orders. Electrification backlog reached USD 9.44 billion, rising 26% year over year. ABB’s former high-voltage Power Grids business, including major GIS activities, was fully transferred to Hitachi Energy after ABB sold its remaining 19.9% stake in 2022.
Siemens Energy AG is a major supplier of transmission substations, high-voltage switchgear, transformers, grid stabilization systems, and digital grid solutions. In fiscal 2025, its Grid Technologies business generated EUR 11.31 billion in revenue and secured EUR 21.42 billion in orders. Profit before special items reached EUR 1.79 billion, while the segment’s margin stood at 15.8%. Siemens Energy reported EUR 39.1 billion in total company revenue and a group order backlog of EUR 138 billion, supporting continued GIS project activity.
Hitachi Energy Ltd. holds a strong position in high-voltage GIS, substations, transformers, HVDC systems, and SF₆-free switchgear. In April 2025, the company increased its Pennsylvania investment to more than USD 70 million, expanding production of EconiQ high-voltage switchgear and creating over 100 jobs. Its EconiQ portfolio includes SF₆-free GIS reaching 420 kV. Hitachi Energy India also reported FY2025 orders of INR 18,173.8 crore, up 228%, while revenue reached INR 6,442.1 crore, increasing 23%.
Top Key Players Outlook
- ABB Ltd.
- Siemens Energy AG
- Hitachi Energy Ltd.
- GE Vernova Inc.
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Toshiba Energy Systems & Solutions Corporation
- HD Hyundai Electric Co., Ltd.
- Larsen & Toubro Limited
- CG Power and Industrial Solutions Limited
- Hyosung Heavy Industries Corporation
- Bharat Heavy Electricals Limited
- Fuji Electric Co., Ltd.
- Eaton Corporation plc
- Nissin Electric Co., Ltd.
Recent Developments
- July 2025, GE Vernova announced investment of up to USD 100 million across Pennsylvania grid factories and planned around 700 new jobs, including expansion of high-voltage switchgear production. By July 2026, the Charleroi facility alone was part of a USD 138 million expansion program.
- In FY2026, Mitsubishi Electric Corporation recorded JPY 5,894.7 billion in total revenue, while its Energy Systems business generated JPY 473.3 billion, up 19%, supported partly by stronger transmission and distribution demand worldwide.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 33.1 Bn |
| Forecast Revenue (2035) | USD 73.5 Bn |
| CAGR (2026-2035) | 8.3% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Voltage (Medium Voltage, High Voltage, Extra-High Voltage), By Installation (Indoor, Outdoor), By Insulation Type (Indoor GIS, Outdoor GIS), By Application (Power Transmission, Power Distribution, Power Generation, Renewable Energy Integration, Others), By End User (Power Utilities, Industrial, Commercial & Residential, Railways & Metros, Others) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | ABB Ltd., Siemens Energy AG, Hitachi Energy Ltd., GE Vernova Inc., Mitsubishi Electric Corporation, Schneider Electric SE, Toshiba Energy Systems & Solutions Corporation, HD Hyundai Electric Co., Ltd., Larsen & Toubro Limited, CG Power and Industrial Solutions Limited, Hyosung Heavy Industries Corporation, Bharat Heavy Electricals Limited, Fuji Electric Co., Ltd., Eaton Corporation plc, Nissin Electric Co., Ltd. |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








