


Report Overview
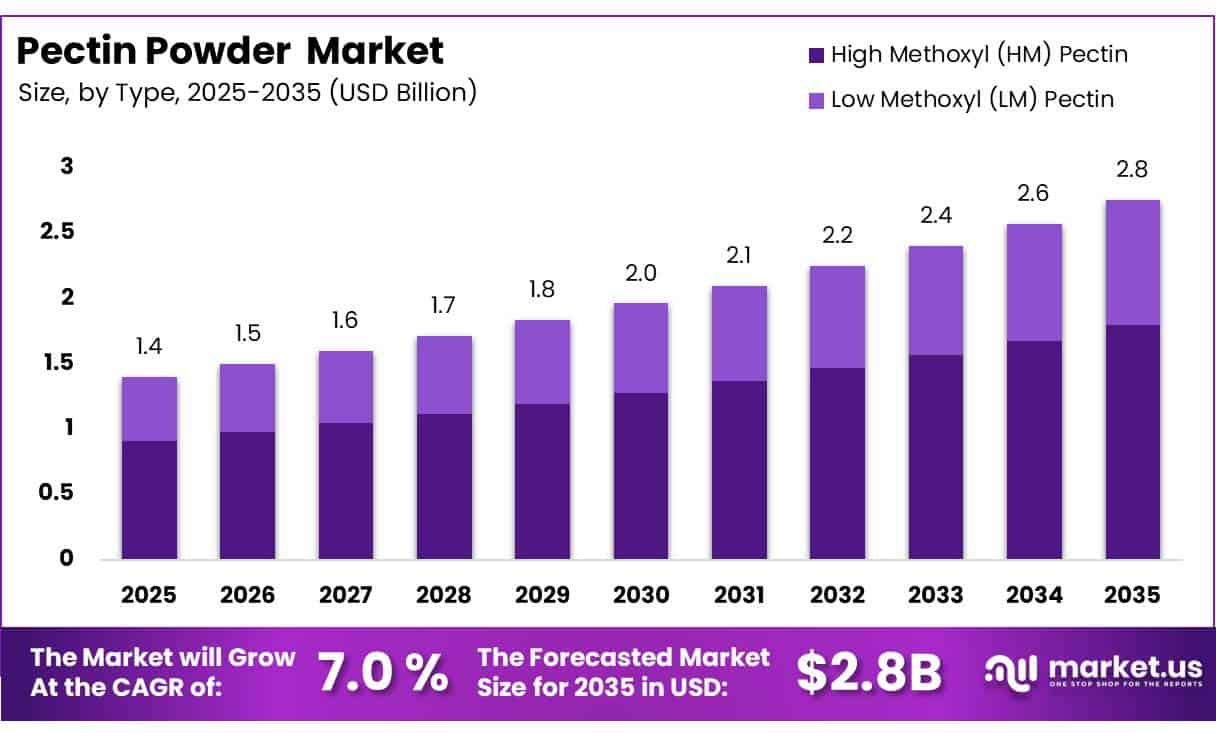
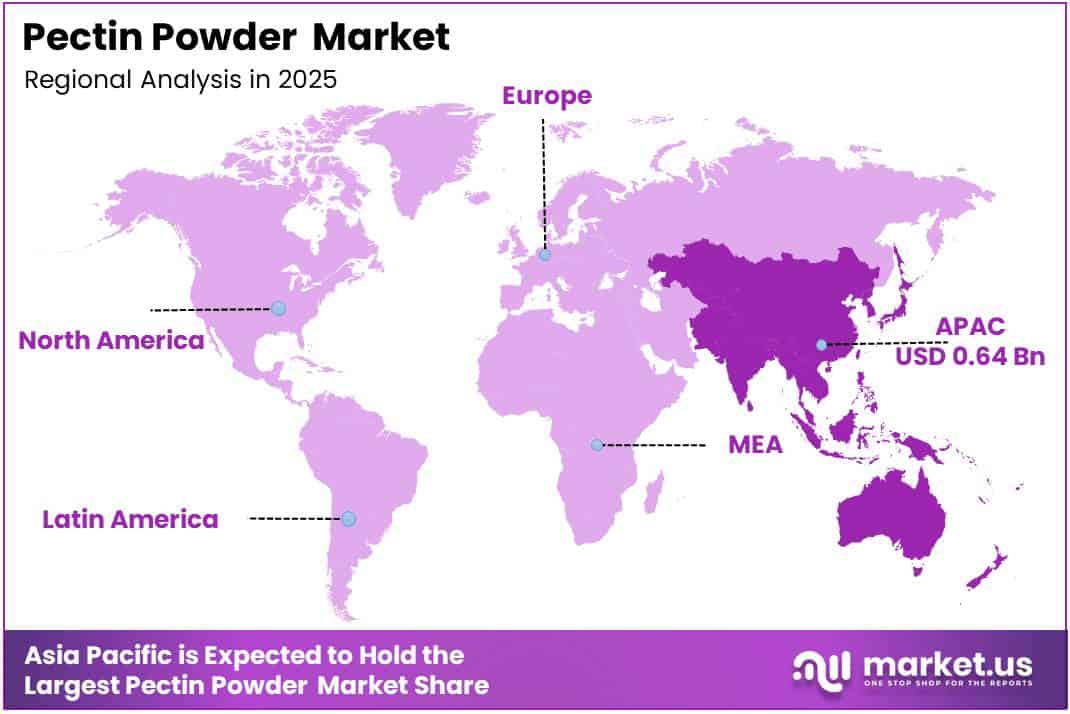
In 2025, the Global Pectin Powder Market was valued at USD 1.4 billion, and between 2026 and 2035, this market is estimated to register a CAGR of 7.0%, reaching about USD 2.8 billion by 2035. Asia Pacific held a dominant market position, capturing more than a 45.4% share, holding USD 0.64 billion in revenue.
Pectin powder is a plant-derived hydrocolloid obtained mainly from citrus peel and apple pomace. It is used as a gelling, thickening, stabilizing and texturizing ingredient in jams, confectionery, beverages, dairy products, bakery fillings and pharmaceutical preparations. Commercial demand is supported by its natural origin, compatibility with clean-label formulations and ability to control texture, water binding and product stability.
- The U.S. Food and Drug Administration lists pectin under 21 CFR 184.1588 and recognizes functions including stabilizer, thickener, firming agent and texturizer.
In January 2026, the USDA forecast 2025/26 global fresh-orange production at 45.9 million tonnes, with 17.1 million tonnes delivered for processing, up 3%. Global lemon and lime production was projected at 10.1 million tonnes, while processing volume reached 2.6 million tonnes. Apple supply also remains substantial: the USDA forecast global 2025/26 production at 81.7 million tonnes. These volumes provide extensive peel and pomace streams for pectin extraction, although weather disruption, citrus greening, energy costs and variable raw-material quality can affect yields and pricing.
Growth is being driven by reduced-sugar foods, plant-based beverages, functional nutrition and manufacturers replacing synthetic texture systems with recognizable ingredients. Low-methoxyl pectin offers particular potential because it gels with calcium and supports lower-sugar formulations.
- Regulatory acceptance strengthens industrial use: EFSA identifies pectin as E440, while more than 300 food additives are authorized in the European Union and must meet defined purity and labelling requirements.
Future opportunities lie in advanced extraction, higher-value pharmaceutical and personal-care grades, customised pectin functionality and circular biorefineries that recover pectin, oils and bioactive compounds from fruit residues. Producers investing in energy-efficient drying, traceable sourcing and consistent specification control are likely to secure stronger partnerships with food processors and broaden applications across premium, health-focused product categories across both mature and emerging international food manufacturing markets.
Key Takeaways
- The Global pectin powder market was valued at US$ 1.4 billion in 2025.
- The Global market is projected to grow at a CAGR of 7.0% and is estimated to reach US$ 2.8 billion by 2035.
- On the basis of type, high methoxyl (HM) pectin dominated the market, constituting 2% of the total market share.
- Based on the source, citrus fruits dominated the pectin powder market, with a substantial market share of around 1%.
- Based on the function, gelling agents led the market, comprising 1% of the total market.
- Among the applications, the food and beverage industry held a major share in the pectin powder market, accounting for 1% of the market share.
- Among the distribution channels, direct/B2B sales were the most considerable within the market, accounting for around 0% of the revenue.
- In 2025, Asia-Pacific was the most dominant region in the pectin powder market, accounting for 4% of the total global market.
Type Analysis
High Methoxyl (HM) Pectin dominates with 65.2% through reliable food gelling performance
In 2025, High Methoxyl (HM) Pectin held a dominant market position, capturing more than a 65.2% share. The segment remained widely used in jams, jellies, fruit preparations, confectionery, and bakery fillings because it forms reliable gels in acidic, sugar-containing formulations. Food processors value its dependable texture, clean flavor profile, and established performance during heating, filling, cooling, and storage, supporting consistent use across large-scale food manufacturing.
- In January 2026, according to the European Food Safety Authority, a pectin-rich extract derived from Coffea arabica was evaluated with 70% to 85% dietary fibres, of which pectin formed the major part, alongside 4% to 6.5% protein. The scientific assessment was adopted in December 2025 and published in January 2026.
Low Methoxyl (LM) Pectin is the fastest-growing segment, supported by demand for reduced-sugar, low-calorie, and calcium-set formulations. Unlike conventional high-sugar systems, LM pectin can form gels in products with lower soluble solids, making it useful for healthier fruit spreads, dairy preparations, confectionery, and specialty foods. Growing reformulation activity and demand for flexible texture control are strengthening adoption among food developers and processors in global markets.
Source Analysis
Citrus Fruits dominate with 56.1% through established processing and raw-material availability
In 2025, Citrus Fruits held a dominant market position, capturing more than a 56.1% share. Citrus peel remains a preferred feedstock because juice processing generates large volumes of peel that can be converted into value-added pectin. Manufacturers favor citrus-based pectin for consistent gelling performance, light color, neutral taste, and suitability across jams, beverages, confectionery, dairy, sauces, and fillings. Established citrus-processing networks also support dependable raw-material availability.
- In March 2026, according to the United States Department of Agriculture Economic Research Service, 2025/26 United States early, midseason, and Navel orange production was forecast at 1.746 million tons. California accounted for more than 80% of production in this category, while the department noted that most Florida output was directed toward processing.
Sugar Beet is the fastest-growing source segment, supported by interest in extracting additional value from fibre-rich residues generated during sugar processing. Beet pulp offers manufacturers another plant-based feedstock for specialized pectin and functional fibre applications. Wider adoption can strengthen waste valorization, diversify raw-material sourcing, and reduce dependence on traditional citrus and apple streams while creating opportunities for tailored pectin grades in formulations.
Function Analysis
Gelling Agent dominates with 47.10% through dependable texture and setting performance
In 2025, Gelling Agent held a dominant market position, capturing more than a 47.10% share. Pectin remained widely used for setting jams, jellies, fruit preparations, confectionery, bakery fillings, and dairy products. Its ability to create gel structures, improve mouthfeel, and stabilize water within food systems supports consistent processing results. Food manufacturers also value pectin because it can deliver texture while maintaining fruit character and fitting plant-based ingredient strategies across formulations.
- In April 2026, according to the European Food Safety Authority, more than 300 substances were authorized for use as food additives in the European Union. Pectin is identified as E 440 and is recognized as a natural additive found in fruit, supporting its established regulatory role within food formulation.
Fat Replacer is the fastest-growing function segment as manufacturers develop reduced-fat and lower-calorie foods while maintaining texture. Pectin can help build viscosity, smoothness, and body in dairy products, spreads, sauces, bakery formulations, and processed foods. Growing demand for reformulated products with simpler ingredient profiles is encouraging food developers to use pectin for partial fat replacement and mouthfeel improvement across product development.
Application Analysis
Food & Beverage dominates with 77.10% through broad functional ingredient use
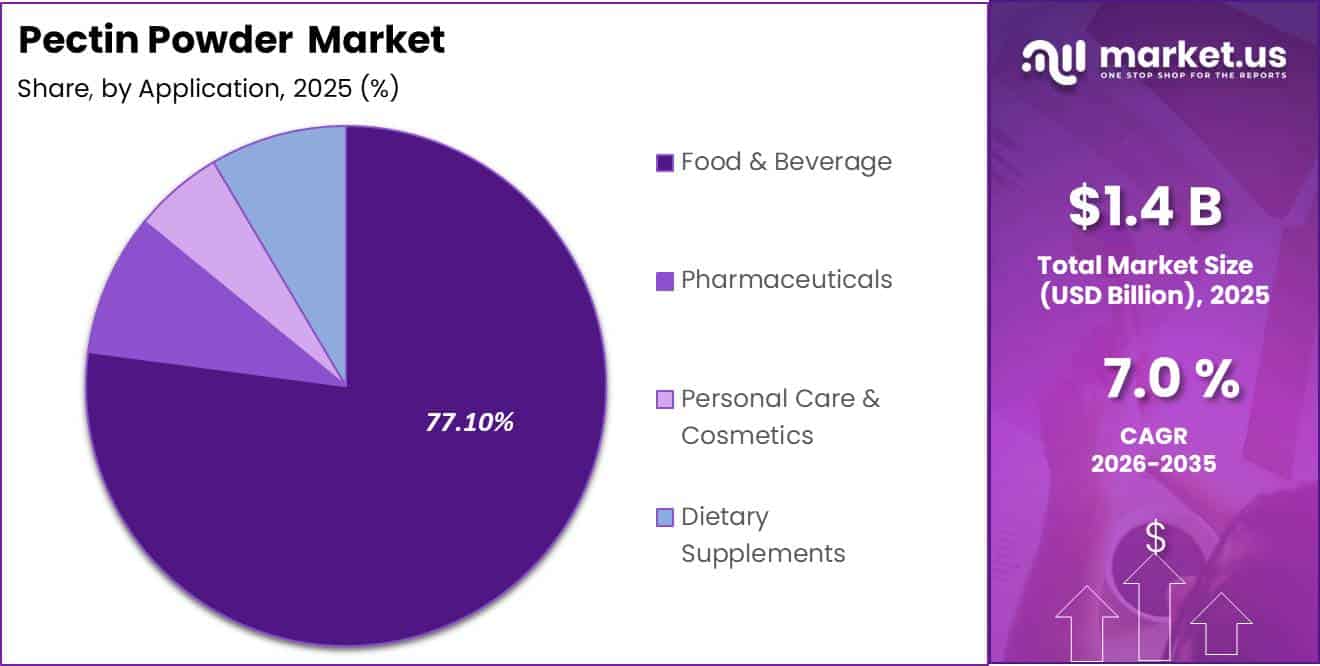
In 2025, Food & Beverage held a dominant market position, capturing more than a 77.10% share. Pectin powder remained widely used in jams, jellies, beverages, confectionery, dairy products, fruit preparations, sauces, and bakery fillings because it provides gelling, thickening, and stabilizing functions. Its plant-based origin also supports clean-label positioning, while reliable processing performance helps manufacturers maintain texture and consistency across repeated production batches and diverse food formulations.
- In June 2026, according to the United States Department of Agriculture Economic Research Service, total United States food spending reached $2.51 trillion in 2025. Food-away-from-home spending totaled $1.41 trillion, while food-at-home expenditures reached $1.10 trillion, showing the scale of commercial and household food channels that use processed ingredients and functional additives.
Pharmaceuticals is the growing application segment, supported by research into pectin for controlled-release systems, tablet binding, films, coatings, wound-care materials, and digestive-health formulations. Its biocompatibility, gel-forming behavior, and ability to interact with other formulation components make it useful in specialized delivery systems. Continued pharmaceutical research and development is expanding interest in purified and modified pectin grades beyond conventional food applications worldwide today.
Distribution Channel Analysis
Direct/B2B Sales dominates with 79.00% through bulk industrial ingredient procurement
In 2025, Direct/B2B Sales held a dominant market position, capturing more than a 79.00% share. The channel remained preferred by food manufacturers, pharmaceutical producers, and ingredient formulators purchasing pectin powder in bulk. Direct supplier relationships allow buyers to secure technical support, grades, quality documentation, contract pricing, traceability, and planned deliveries. These advantages are important where consistent gelling, stabilizing, and thickening performance must be maintained across industrial production batches.
- In March 2026, according to the United States Census Bureau, retail e-commerce sales reached $316.1 billion in the fourth quarter of 2025. Online sales increased 5.3% from the fourth quarter of 2024 and accounted for 16.6% of total retail sales during the quarter.
Online Sales is the fastest-growing segment as smaller food businesses, laboratories, product developers, and independent formulators increasingly use digital channels to purchase specialty ingredients. Online platforms enable comparison of pectin grades, pack sizes, technical specifications, supplier options, and pricing. Greater digital procurement adoption, faster ordering, and direct access to specialized ingredient suppliers are supporting wider online availability of pectin powder for product trials, small-batch manufacturing, and recurring commercial purchases.
Key Market Segments
By Type
- High Methoxyl (HM) Pectin
- Low Methoxyl (LM) Pectin
By Source
- Citrus Fruits
- Apple
- Sugar Beet
- Others
By Function
- Gelling Agent
- Stabilizer
- Thickener
- Fat Replacer
By Application
- Food & Beverage
- Pharmaceuticals
- Personal Care & Cosmetics
- Dietary Supplements
By Distribution Channel
- Direct/B2B Sales
- Ingredient Distributors
- Online Sales
Driver Analysis
Clean-Label Reformulation Demand
Clean-label reformulation is the strongest underlying driver because global food manufacturers are replacing artificial stabilizers, gelatin, synthetic thickeners, and multi-ingredient texture blends with plant-derived ingredients that can be declared more simply on packaging; pectin benefits because it is naturally sourced from fruit-cell-wall material, is accepted as food additive E440 in the European Union, and is approved in the United States as a stabilizer, thickener, and texturizer under food-additive and GRAS-related regulations.
Powder pectin captures a large share of the commercial format because it has relatively long shelf life, low transport weight, controlled dosing, and compatibility with dry-blending systems; in practical formulation economics, pectin inclusion often ranges from about 0.2–1.0% depending on application, so a 0.1 percentage-point dosage optimization can influence texture cost materially at industrial production scale.
Suppliers are consequently moving beyond bulk sales toward technical-service contracts, where product-development teams provide gel-strength testing, pH optimization, calcium-balance control, and thermal-stability validation, increasing customer retention and enabling estimated 10–20% price premiums for validated clean-label grades relative to undifferentiated standard material.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Clean-label reformulation demand | +1.8% | EU, North America, APAC | Medium term (2–4 years) |
| Reduced-sugar food launches | +1.5% | North America, EU, Japan | Short term (≤2 years) |
| Plant-based texture systems | +1.4% | North America, EU, China | Medium term (2–4 years) |
| Functional beverage expansion | +1.2% | APAC, North America, EU | Short term (≤2 years) |
| Pharma-nutrition applications | +1.0% | EU, North America, India, China | Long term (≥4 years) |
| Fruit-waste valorization supply | +0.8% | Brazil, Mexico, EU, China | Medium term (2–4 years) |
Restraint Analysis
Citrus-Greening Feedstock Shock
Brazil is the most exposed upstream source: the Fundecitrus forecast for the São Paulo and Triângulo/Southwest Minas Gerais citrus belt placed the 2026–27 orange crop at 255.2 million 40.8-kg boxes, 12.9% below the previous season and 14.7% below the preceding 10-year average, while the September 2025 disease survey found greening in 47.6% of orange trees and reported average productivity of 697 boxes per hectare, down 13.8% year on year.
USDA data similarly showed greening incidence in the region reaching 47.63% in 2025, up from 18.7% in 2024 when measured by disease severity, with premature fruit drop increasing as psyllid pressure remained elevated. For pectin processors, a 10–15% contraction in peel availability can translate into a 15–25% increase in feedstock procurement cost because plants require minimum batch volumes to sustain efficient acid extraction, filtration, alcohol precipitation, and drying.
The resulting impact includes lower plant-utilization rates, inventory-building requirements of roughly 4–8 months instead of 2–4 months, higher working-capital needs, and gross-margin compression estimated at 250–450 basis points where annual supply contracts limit immediate customer price pass-through.
Restraint Impact Analysis
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Citrus-greening feedstock shock | -2.3% | Brazil core, North America, EU, APAC | Medium term (2–4 years) |
| Crop and weather volatility | -1.8% | Brazil, Mexico, Mediterranean EU, China | Medium to long term (≥4 years) |
| Pectin-price pass-through limits | -1.5% | North America, EU, APAC import markets | Short term (≤2 years) |
| E440 compliance tightening | -1.2% | EU core, UK, export suppliers | Short term (≤2 years) |
| Lower-cost hydrocolloid substitution | -1.1% | Global, APAC cost-led markets | Medium term (2–4 years) |
| Specialty-grade processing costs | -0.9% | EU, North America, India, China | Medium term (2–4 years) |
Opportunity Analysis
Low-Sugar Specialty Platform
The major white-space opportunity lies in converting commodity high-methoxyl pectin portfolios into specialized low-methoxyl, amidated, calcium-reactive, acid-stable, and heat-stable powder platforms for reduced-sugar jams, fruit spreads, gummies, dessert sauces, bakery fillings, dairy inclusions, and medical-nutrition products; this is not a current driver because conventional high-methoxyl grades still dominate legacy jam and preserve volumes, whereas the incremental value pool comes from technical reformulation programs that replace the traditional 55–65% soluble-solids gel system with formulations containing 30–70% less added sugar.
The commercial model shifts from bulk powder supply toward formulation-led contracts that bundle pectin, calcium salts, pH management, recipe optimization, pilot trials, and application support; this can raise realized pectin selling prices by an estimated 20–35% and reduce customer switching once the final recipe has passed shelf-life, sensory, thermal-process, and regulatory validation.
Producers that develop 8–15 validated specialty SKUs and secure design wins with branded food companies over the next 24 months could capture margin expansion of roughly 400–700 basis points, while shortening customer development timelines from a typical 9–12 months to 3–6 months through prevalidated formulation templates.
Opportunity Impact Analysis
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Low-sugar specialty platform | +2.1% | North America, EU, Japan, Australia | Short term (≤2 years) |
| Regional waste-to-pectin hubs | +1.9% | Brazil, Mexico, India, Mediterranean EU | Medium term (2–4 years) |
| Pharmaceutical excipient expansion | +1.6% | North America, EU, India, China | Long term (≥4 years) |
| Pectin packaging-film conversion | +2.2% | EU, North America, APAC export hubs | Medium term (2–4 years) |
| Plant-protein texture systems | +1.5% | EU, North America, China, South Korea | Medium term (2–4 years) |
| Feedstock-network M&A roll-ups | +1.7% | Latin America, India, Southeast Asia | Medium term (2–4 years) |
Challenges Analysis
Feedstock Quality Variability
Pectin powder production depends on fruit-processing residues rather than a uniform dedicated crop, so the chemistry and recoverability of citrus peel and apple pomace vary continuously by fruit variety, maturity, growing region, harvest timing, disease incidence, juice-extraction method, peel storage, moisture, microbial load, pesticide profile, and pre-drying conditions; citrus peel represents approximately 75–86% of the global pectin feedstock base, while citrus peel and apple pomace together account for about 85% of commercial pectin supply.
A 5–10 percentage-point variation in peel moisture or esterification can reduce extraction efficiency by an estimated 5–15%, increase blending and rework requirements, and force suppliers to downgrade material from premium beverage, dairy, pharmaceutical, or low-sugar grades into lower-margin standard food grades.
Brazilian citrus conditions illustrate the persistence of the risk: Fundecitrus forecast the 2026–27 São Paulo and Triângulo/Southwest Minas Gerais crop at 255.2 million 40.8-kg boxes, 12.9% below the preceding season, while greening affected 47.6% of orange trees and disease-linked fruit drop continued to pressure raw-material consistency.
Effective mitigation requires multi-origin procurement, lot-level incoming-material testing, rapid peel dehydration, near-infrared composition screening, and 4–8 months of buffer inventory, but these measures raise working-capital requirements and add an estimated 150–300 basis points of operating-cost friction versus a standardized synthetic hydrocolloid supply chain.
Challenges Impact Analysis
| Challenge | (~) % CAGR Friction | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Feedstock quality variability | -1.3% | Brazil, Mexico, EU, China | Medium term (2–4 years) |
| Extraction-yield inconsistency | -1.1% | Global processing hubs | Medium term (2–4 years) |
| Acid-effluent treatment burden | -0.9% | EU, North America, China | Long term (≥4 years) |
| Specialty formulation complexity | -1.0% | North America, EU, APAC | Medium term (2–4 years) |
| Traceability-data integration gaps | -0.7% | Global export corridors | Medium term (2–4 years) |
| Food-science talent scarcity | -0.6% | EU, North America, India, China | Long term (≥4 years) |
Geopolitical Impact Analysis
Geopolitical Realignment and Supply Chain Fragmentation Reshaping Pectin Powder Manufacturing.
Current geopolitical tensions are reshaping the pectin powder market through concentrated citrus-processing capacity, trade-policy differences, maritime insecurity, and regional sourcing strategies. USDA forecast Brazilian frozen concentrated orange juice production at 1.03 million tonnes for 2025/26, while processing efficiency improved to 276.9 boxes per tonne. Because citrus peel availability follows juice production, disruption at major processing hubs can quickly affect pectin feedstock procurement and contract planning.
Shipping instability is adding another layer of exposure. UNCTAD reported that, by May 2025, tonnage moving through the Suez Canal remained 70% below 2023 levels. Longer routes around Africa increase transit times, freight charges, insurance exposure, and working-capital requirements for pectin moving between Asian, European, and American manufacturing centres.
- In parallel, customs treatment can create unequal landed costs. The 2025 U.S. Harmonized Tariff Schedule lists pectic substances under HS 1302.20 with a free general duty rate but a 25% Column 2 rate. Such differences encourage buyers to review origin, customs classification, and supplier documentation before signing longer-term contracts.
These developments are encouraging multi-country sourcing, regional warehousing, safety-stock policies, and closer links with juice processors. Producers are also qualifying alternative citrus and apple-pomace suppliers to reduce dependence on single corridors. However, feedstock seasonality, slower approvals, documentation demands, and higher logistics costs continue to expose manufacturers to price volatility and supply interruptions across international food ingredient supply networks.
Regional Analysis
Asia Pacific Held the Largest Share of the Global Pectin Powder Market.
In 2025, Asia Pacific dominated the global pectin powder market, holding about 45.40% of total revenue and reaching approximately USD 0.64 billion, due to its extensive food-processing base, growing demand for natural ingredients, and strong production of beverages, dairy products, confectionery, jams, and bakery fillings. In 2025, China’s food and agricultural processing industry included around 100,000 registered companies and generated an estimated USD 2.5 trillion in revenue. This large manufacturing network creates steady demand for pectin as a gelling, thickening, and stabilizing ingredient in processed food formulations.
Similarly, Japan and South Korea contribute significantly through advanced food manufacturing, strict quality standards, and strong demand for health-focused and convenience products. South Korea had more than 31,075 food-processing companies, generating approximately USD 65.0 billion in sales. Meanwhile, Thailand is strengthening its processed-food industry and aims to become one of the world’s ten leading processed-food exporters by 2027. This geographically broad manufacturing structure ensures that Asia Pacific remains the central production and consumption region for pectin powder.
Key Regions and Countries Covered
- North America
- The US
- Canada
- Europe
- Germany
- France
- The UK
- Spain
- Italy
- Russia & CIS
- Rest of Europe
- APAC
- China
- Japan
- South Korea
- India
- ASEAN
- Rest of APAC
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Key Players Analysis
In May 2026, Tate & Lyle reported that CP Kelco integration was complete, while CP Kelco ingredient volumes increased 2%. The company also delivered US$24 million in cost synergies, strengthening its combined texture and mouthfeel platform.
Competitive positioning is increasingly influenced by geographic production, citrus sourcing, and specialized low-sugar formulations. In 2025, dsm-firmenich increased its ownership in Yantai Andre Pectin from 75% to 90.5%, strengthening control over one of the world’s largest pectin plants.
Cargill maintains four pectin production facilities and offers both High Methoxyl and Low Methoxyl grades, while CEAMSA supplies natural hydrocolloids, including citrus-derived pectin, across five continents. These capabilities support supply reliability, customized formulations, technical service, and wider access to food, beverage, pharmaceutical, and nutrition customers.
The Major Players in The Industry
- CP Kelco
- Cargill
- DuPont Nutrition & Biosciences
- Herbstreith & Fox
- Yantai Andre Pectin Co., Ltd.
- Naturex
- Silvateam
- CEAMSA
- FMC BioPolymer
- Lucid Colloids Ltd.
- DSM-Firmenich
- Ingredion Incorporated
- Naturex SA
- Compañía Española de Algas Marinas (CEAMSA)
- Yuning Bio-Tec Co., Ltd.
Key Development
- In January 2026, CEAMSA acquired the fibre product line and associated intellectual property of Netherlands-based PeelPioneers. The transaction expanded CEAMSA’s citrus-fibre portfolio and strengthened its position in natural texturizing ingredients by integrating PeelPioneers’ technology and expertise into its existing operations.
- In June 2026, CEAMSA moved its FABRINTYSO project into the testing and validation phase. The project is developing a flexible, intelligent, and sustainable pilot line for new natural hydrocolloids, helping shorten the transition from laboratory development to industrial production while improving process flexibility, traceability, and sustainability.
- In July 2026, Ingredion Incorporated introduced its latest food-ingredient innovations at IFT FIRST 2026, focusing on texture, clean-label formulations, sugar reduction, protein and fibre fortification. The company also presented an Artificial Intelligence-powered formulation assistant designed to help research and development teams identify ingredient solutions and accelerate food product development.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 1.4 Bn |
| Forecast Revenue (2035) | USD 2.8 Bn |
| CAGR (2026-2035) | 7.0% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Type (High Methoxyl (HM) Pectin and Low Methoxyl (LM) Pectin), By Source (Citrus Fruits, Apple, Sugar Beet, and Others), By Function (Gelling Agent, Stabilizer, Thickener, and Fat Replacer), By Application (Food & Beverage, Pharmaceuticals, Personal Care & Cosmetics, and Dietary Supplements), By Distribution Channel (Direct/B2B Sales, Ingredient Distributors, and Online Sales) |
| Regional Analysis | North America – The US & Canada; Europe – Germany, France, The UK, Spain, Italy, Russia & CIS, Rest of Europe; APAC– China, Japan, South Korea, India, ASEAN & Rest of APAC; Latin America– Brazil, Mexico & Rest of Latin America; Middle East & Africa– GCC, South Africa, & Rest of MEA |
| Competitive Landscape | CP Kelco, Cargill, DuPont Nutrition & Biosciences, Herbstreith & Fox, Yantai Andre Pectin Co., Ltd., Naturex, Silvateam, CEAMSA, FMC BioPolymer, Lucid Colloids Ltd., DSM-Firmenich, Ingredion Incorporated, Naturex SA, Compañía Española de Algas Marinas (CEAMSA), and Yuning Bio-Tec Co., Ltd. |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited Users and Printable PDF) |








