


Report Overview
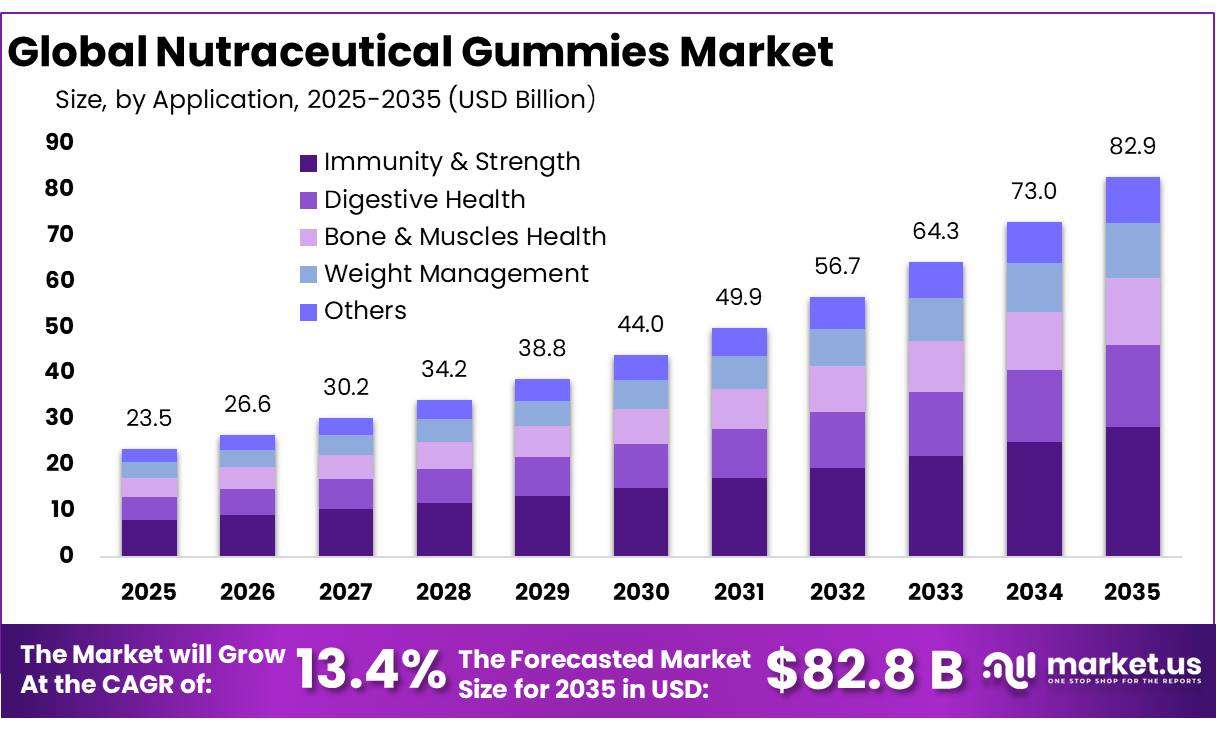
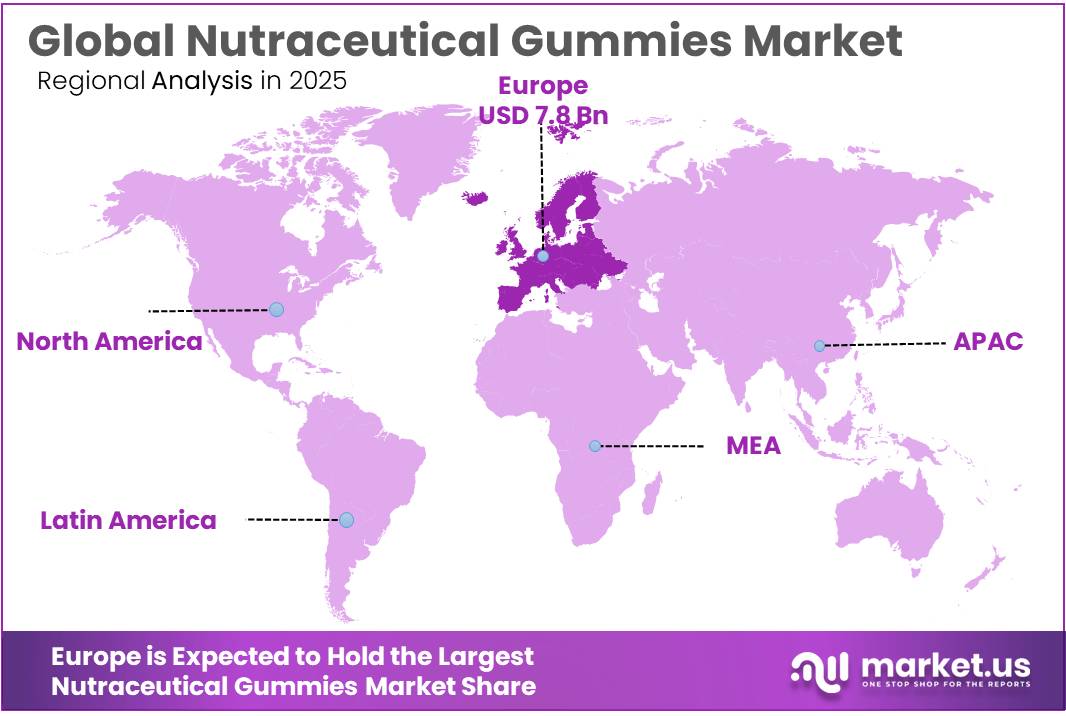
The Global Nutraceutical Gummies Market size is expected to be worth around USD 82.8 Billion by 2035, from USD 23.5 Billion in 2025, growing at a CAGR of 13.4% during the forecast period from 2026 to 2035. In 2025, Europe held a dominant market position, capturing more than a 33.2% share, holding USD 7.8 Billion revenue.
The nutraceutical gummies industry is expanding as manufacturers offer vitamins, minerals, probiotics, botanical extracts, and other nutritional ingredients in a chewable format. Gummies provide an alternative to traditional tablets and capsules, with appealing flavours, convenient portioning, and easy-to-use packaging. They are used in products targeting immunity, digestive health, sleep, healthy ageing, and general wellness.
Their development requires careful selection of active ingredients, gelling agents, sweeteners, flavours, and stabilizers to maintain texture, taste, and nutrient quality. The United States Pharmacopeia recognizes chewable gels, commonly marketed as gummies, as one of the dosage forms used for multi-ingredient dietary supplements.
The industrial scenario is shaped by supplement brands, contract manufacturers, ingredient suppliers, flavour specialists, and producers of pectin, gelatin, and other gelling systems. Manufacturers are working to improve nutrient stability, reduce sugar, and develop formulations suitable for different consumer groups. According to the United States Centers for Disease Control and Prevention, 60.2% of adults aged 20 and older used dietary supplements during August 2021 to August 2023. This provides a useful indicator of the broader consumer base for supplement products, although the statistic does not measure gummy use specifically.
Driving factors include the convenience of chewable supplements, interest in preventive nutrition, and demand for products with attractive flavours and easy-to-manage serving sizes. Product innovation is also creating opportunities for sugar-free, plant-based, gelatin-free, and clean-label gummies. In April 2026, Lubrizol introduced a sugar-free pectin gummy concept containing 100 milligrams of Curcushine™ microencapsulated curcumin per gummy, demonstrating how ingredient technology can help improve taste, stability, and suitability for functional nutrition applications.
Future growth opportunities lie in combining vitamins with probiotics, minerals, collagen, and botanical extracts, along with developing formulations for specific nutritional needs. However, manufacturers must manage moisture sensitivity, heat exposure, ingredient compatibility, texture, and shelf life.
Sugar content is another important consideration because the United States Food and Drug Administration sets the Daily Value for added sugars at 50 grams per day on a 2,000-calorie diet. Compliance with manufacturing standards, accurate labelling, and product testing will remain essential. Companies that combine reliable ingredient delivery with appealing taste, stable formulations, and clear nutritional information are positioned to capture future opportunities in the nutraceutical gummies industry.
Key Takeaways
- Nutraceutical Gummies Market size is expected to be worth around USD 82.8 Billion by 2035, from USD 23.5 Billion in 2025, growing at a CAGR of 13.4%.
- Vitamins & Multivitamins held a dominant market position, capturing more than a 33.21% share.
- Adult held a dominant market position, capturing more than a 42.34% share.
- Animal Source held a dominant market position, capturing more than a 41.21% share.
- Immunity & Strength held a dominant market position, capturing more than a 34.21% share.
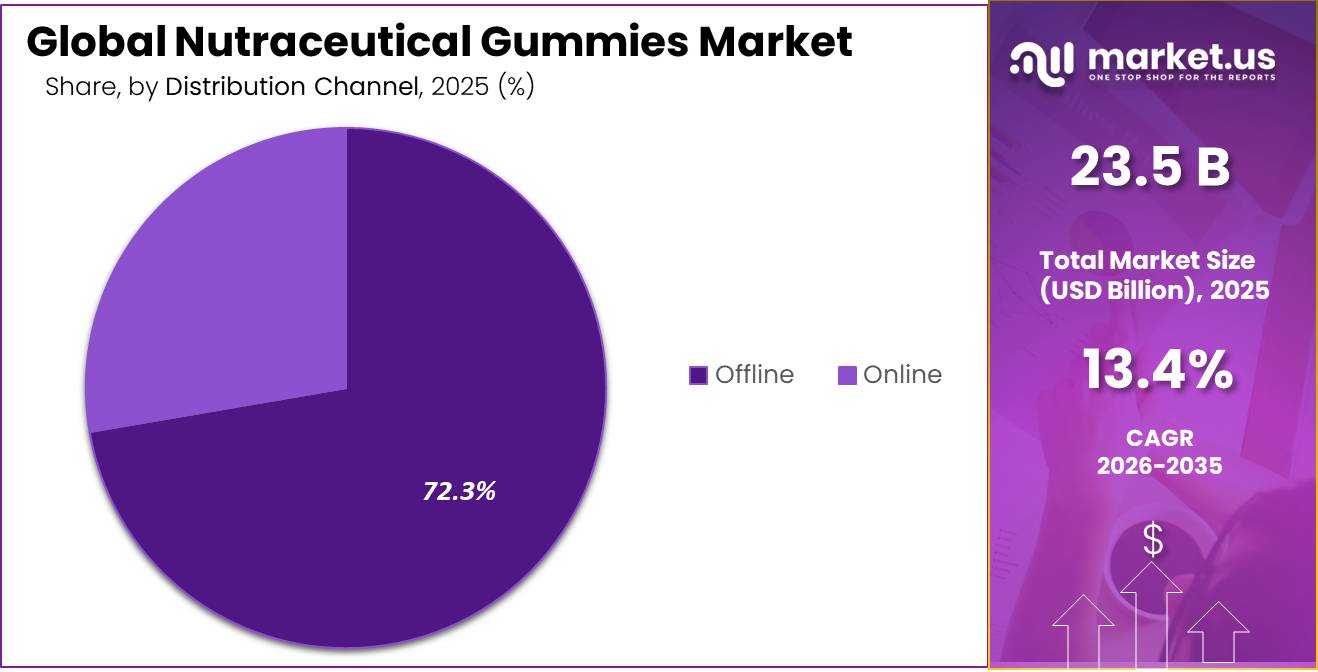
- Offline held a dominant market position, capturing more than a 72.34% share.
- Europe dominated the Nutraceutical Gummies Market, accounting for a 33.21% share, with a market value of USD 7.8 billion.
By Product Type Analysis
Vitamins and multivitamins lead the segment through their broad use in everyday nutritional support and convenient chewable supplements.
In 2025, “Vitamins & Multivitamins” held a dominant market position, capturing more than a 33.21% share of the nutraceutical gummies market by product type. These gummies provide vitamins in a convenient format for consumers seeking nutritional support without swallowing traditional tablets or capsules. Manufacturers use vitamins such as A, C, D, E, and selected B vitamins in single-nutrient and multivitamin formulations. Product development focuses on taste, nutrient stability, serving accuracy, and reduced added sugar. The segment also benefits from demand for products designed to support general wellness and meet specific nutritional needs.
According to the United States National Institutes of Health, vitamin D is important for bone health and supports several functions in the body. This reinforces the relevance of vitamin ingredients in nutritional products, although government data do not establish the market share of vitamin gummies specifically.
According to the United States National Institutes of Health, adults aged 19–50 generally require 1,000 milligrams of calcium per day, while the recommended daily allowance for zinc is 11 milligrams for adult men and 8 milligrams for adult women. These recommendations provide a government-backed nutritional reference for product formulation, but they do not measure the market share of mineral gummies.
By Cosnumer Age Group Analysis
Adults lead the market due to their broad demand for convenient nutritional supplements and daily wellness products.
In 2025, “Adult” held a dominant market position, capturing more than a 42.34% share of the nutraceutical gummies market by consumer age group. Adult consumers use vitamin and multivitamin gummies to supplement their diets and support general wellness, bone health, and immune function. The format appeals to consumers who prefer flavoured, chewable supplements over traditional tablets and capsules.
According to the United States Centers for Disease Control and Prevention (CDC), 60.2% of adults aged 20 and older used dietary supplements during August 2021 to August 2023. This government statistic demonstrates established supplement use among adults, although it does not measure gummy consumption specifically.
According to the United States National Institutes of Health, children aged 1–3 years require 600 international units (IU) of vitamin D per day, while children aged 4–8 years also require 600 IU per day. These recommendations provide a government-backed reference for vitamin D product development, but they do not establish the market share of pediatric gummies.
By Source Type Analysis
Animal Source: Strong demand for animal-derived ingredients supports its leading position
In 2025, “Animal Source” held a dominant market position, capturing more than a 41.21% share of the Nutraceutical Gummies Market by source type. Animal-derived ingredients can include gelatin, collagen, and certain nutrients obtained from animal-based materials. Gelatin is especially relevant to gummy production because it helps create the chewy texture and structure commonly associated with these products.
Manufacturers use these ingredients when developing gummies for adults and children, depending on the formulation and intended use. However, animal-derived ingredients may not suit vegetarian or vegan consumers, which encourages manufacturers to offer alternatives. The segment’s position reflects the supplied 41.21% share; no additional market-share figures are assumed.
Plant Source ingredients are used in nutraceutical gummies to provide nutrients and botanical compounds from herbs, fruits, vegetables, and other plant materials. These ingredients can support formulations aimed at general wellness, digestive health, and other nutritional needs. Plant-based gelling agents, such as pectin, also give manufacturers an alternative to animal-derived gelatin.
Government data provide context for interest in plant-based supplements: the U.S. National Center for Complementary and Integrative Health reported that 17.7% of American adults used non-vitamin and non-mineral natural products in 2012. This figure covers a broad supplement category and does not measure plant-source gummy use specifically. The data nevertheless show established consumer use of natural products, while plant-source gummy demand also depends on ingredient quality, formulation stability, taste, and clear product labelling.
By Application Analysis
Immunity & Strength: Everyday wellness needs support its leading application share
In 2025, “Immunity & Strength” held a dominant market position, capturing more than a 34.21% share of the Nutraceutical Gummies Market by application. This segment benefits from consumer interest in products that support normal immune function and help meet daily nutrient needs. Gummies containing vitamins and minerals offer a convenient option for consumers who prefer chewable supplements over tablets or capsules. Vitamin C, vitamin D, and zinc are commonly associated with immune health, although the benefits depend on the nutrient, dosage, and an individual’s nutritional status.
Digestive Health gummies are designed to provide ingredients such as probiotics, prebiotics, and selected fibres that support digestive wellness. Their chewable format offers an alternative for consumers who prefer not to take capsules or tablets. Manufacturers may develop products for gut microbiome support and regular digestive function, depending on the ingredients used and the evidence behind their intended benefits.
Government data provide context for the broader supplement market: in 2021–2023, 60.2% of U.S. adults aged 20 and older reported using a dietary supplement in the previous 30 days, according to the National Center for Health Statistics. This figure covers all dietary supplements, not digestive health gummies specifically, but it indicates established supplement use among adults. Product development in this segment depends on ingredient stability, taste, suitable dosages, and clear labelling.
By Distribution Channel Analysis
Offline: Physical stores lead through product access and direct customer support
In 2025, “Offline” held a dominant market position, capturing more than a 72.34% share of the Nutraceutical Gummies Market by distribution channel. Pharmacies, supermarkets, health stores, and other physical retailers help consumers compare products, read labels, and seek guidance from store staff before making a purchase. Offline outlets also allow brands to display products alongside vitamins, minerals, and other nutritional supplements, making them easier to find during routine shopping.
This channel can be especially useful for customers who prefer to purchase health products in person rather than rely on online descriptions. The supplied 72.34% share reflects the segment’s stated market position in 2025; it is not an independently verified government statistic.
Online distribution allows consumers to browse nutraceutical gummies, compare ingredients, check product information, and order from brand websites and e-commerce platforms. This channel also helps brands reach customers who may have limited access to specialist health stores.
In 2025, U.S. retail e-commerce sales reached USD 1,233.7 billion, accounting for 16.4% of total retail sales, according to the U.S. Census Bureau. Although these figures cover retail e-commerce across product categories rather than nutraceutical gummies alone, they show the scale of online purchasing. Growth in this channel depends on reliable delivery, clear ingredient and dosage information, consumer trust, and compliance with applicable rules for dietary supplement claims and labelling.
Key Market Segments
By Product Type
- Vitamins & Multivitamins
- Minerals
- Omega-3 Fatty Acids
- Probiotics & Prebiotics
- Collagen
- Others
By Cosnumer Age Group
- Adult
- Pediatric
- Geriatric
By Source Type
- Animal Source
- Plant Source Fastest Growing
- Microbial / Fermentation-Derived
By Application
- Immunity & Strength
- Digestive Health
- Bone & Muscles Health
- Weight Management
- Others
By Distribution Channel
- Offline
- Hypermarket & Supermarket
- Pharmacies
- Others
- Online
Driver Analysis
Adult-Format Preference Shift — +0.7 Percentage Points
The shift from pills and capsules toward chewable, palatable formats is an active demand driver because it changes the consumption experience without requiring consumers to adopt an entirely new health category. Gummies reduce swallowing barriers and can support higher adherence in users who dislike tablets, but the commercial effect depends on whether the format sustains repeat purchase rather than merely attracting trial. In a modeled brand with 500,000 annual purchasers spending $120 each, revenue is $60 million; if gummy preference raises conversion by 10% and average order value by 5%, revenue rises to $69.3 million, a 15.5% uplift before retention effects.
At a 25% ingredient and packaging cost ratio, the incremental $9.3 million of revenue carries approximately $2.33 million of variable cost, leaving $6.98 million of incremental contribution before marketing and fixed overhead. The +0.7-point sensitivity assumes that adult format preference raises terminal market revenue by approximately 3.9%, net of cannibalization from capsules and tablets. The business-model implication is a shift from ingredient-led claims toward sensory differentiation, dose convenience and subscription-friendly packaging; however, gummies must still deliver credible nutrition, and sugar, texture and stability constraints can limit how much active ingredient a format can carry.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Adult-format preference shift | +0.7 pp | US, Canada, UK, Australia | Medium term (2–4 years) |
| Preventive wellness demand | +0.6 pp | US, EU, Japan, India | Long term (≥ 4 years) |
| Weight-management support formats | +0.5 pp | US, EU, UK, Australia | Medium term (2–4 years) |
| E-commerce subscription models | +0.5 pp | US, UK, Germany, India | Medium term (2–4 years) |
| Clean-label and vegan reformulation | +0.4 pp | EU, UK, US, Germany | Medium term (2–4 years) |
| Pediatric and family formats | +0.5 pp | US, India, Brazil, Southeast Asia | Long term (≥ 4 years) |
Restraint Analysis
Dose and Matrix Limitations — −0.5 Percentage Points
The structural restraint is that a palatable gummy matrix cannot always carry the active load, stability profile or release behavior required for higher-dose nutrition, causing brands to reduce dosage, use multiple gummies or choose another format. A practical illustration shows the constraint: a 20 g protein target requires 25 g of an 80%-protein ingredient, while a 10 g fiber target requires 12.5 g of an 80%-fiber ingredient; either load would be difficult to incorporate into a conventional 3–5 g gummy without changing texture, moisture, sweetness or serving count.
In a modeled product requiring 2 g of active ingredient per 3 g gummy, the active represents 66.7% of finished mass, leaving limited room for gelling agents, sweeteners, flavor and color; if the active is reduced to 1 g, the brand must either double the serving count or accept a lower nutritional proposition. The −0.5-point sensitivity assumes 30% of terminal market revenue is exposed to high-dose or stability-sensitive applications and that matrix limitations reduce realization within that exposure by 8%, producing approximately 2.4% aggregate terminal revenue loss.
The strategic consequence is a shift toward multi-gummy packs, chewable tablets, soft chews or alternative delivery formats, which can raise packaging and fulfillment cost; this is a formulation ceiling, not a claim that gummies cannot serve lower-dose vitamins, melatonin, fiber or beauty ingredients.
Restraint Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Dose and matrix limitations | −0.5 pp | US, EU, UK, India | Long term (≥ 4 years) |
| Sugar and dental concerns | −0.4 pp | US, EU, UK, Australia | Medium term (2–4 years) |
| Label-accuracy trust deficit | −0.4 pp | US; exporters serving US | Medium term (2–4 years) |
| Pediatric safety expectations | −0.4 pp | US, Canada, EU, India | Medium term (2–4 years) |
| Consumer affordability pressure | −0.4 pp | US, EU, India, Brazil | Medium term (2–4 years) |
| GLP-1 spending reallocation | −0.4 pp | US, EU, UK, Australia | Medium term (2–4 years) |
Opportunity Analysis
Clinician-Aligned Gummy Systems — +0.5 Percentage Points
The white space is to develop gummy systems specifically designed for people using or transitioning from obesity pharmacotherapy, rather than relying on the existing broad wellness demand already counted as a driver. WHO’s December 2025 guideline recommends GLP-1-based therapies for eligible adults with obesity as part of comprehensive care that includes behavioral support, healthy diet, physical activity and follow-up, while explicitly stating that these medicines should not be standalone solutions.
The untapped commercial mechanism is formulation for nutritional adequacy and adherence during reduced food intake: a 20 g daily protein target requires 25 g of an 80%-protein ingredient, while a 10 g fiber target requires 12.5 g of an 80%-fiber ingredient; these loads generally exceed a conventional single 3–5 g gummy, making multi-gummy servings, mini-gummies or soft chews more realistic delivery systems.
In a modeled portfolio serving 100,000 users daily with a $0.60 ingredient-and-packaging cost per serving, annual input demand is approximately $21.9 million; a 10% increase in adherence and a 5% increase in average spend would add approximately $3.29 million of retail revenue and $0.82 million of input demand before channel margins. The +0.5-point sensitivity assumes that clinician-aligned systems and associated replenishment formats create approximately 2.4% additional terminal market revenue, net of substitution from existing protein and supplement sales.
The strategic pivot is toward evidence-informed product design, healthcare-professional education and pharmacy or telehealth channels; it is not an assumption that GLP-1 users automatically buy gummies, nor does it treat medical treatment as a substitute for nutritional support.
Opportunity Impact Analysis
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Clinician-aligned gummy systems | +0.5 pp | US, EU, UK, Australia | Medium term (2–4 years) |
| Low-sugar dental-safe formats | +0.5 pp | US, EU, UK, Germany | Medium term (2–4 years) |
| Verified-dose premium brands | +0.4 pp | US, Canada, EU, Japan | Medium term (2–4 years) |
| Pediatric safety-led portfolios | +0.4 pp | US, Canada, EU, India | Medium term (2–4 years) |
| Personalized gummy subscriptions | +0.3 pp | US, UK, Germany, South Korea | Medium term (2–4 years) |
| Capability-led acquisition platforms | +0.3 pp | US, Germany, Switzerland, Singapore | Short term (≤ 2 years) |
Challenges Analysis
Gummy Matrix Stability — −0.4 Percentage Points
The continuing technical challenge is maintaining active-ingredient stability, texture and shelf life as brands increase functional loading, reduce sugar and shift toward plant-based gelling systems; this is a formulation and process-control problem, not a claim that gummies cannot be manufactured reliably. In a modeled 3 g gummy containing 1 g of active ingredient, the active represents 33.3% of finished mass, leaving limited room for gelling agents, sweeteners, flavor and color; if the active is increased to 1.5 g, the active share rises to 50%, often requiring reformulation of moisture, humectancy and gelling balance.
If shelf life falls from 24 to 18 months, a brand holding 60 days of inventory must accelerate turnover by 25% or accept higher write-off risk; on $10 million of annual inventory value, the additional carrying burden is approximately $250,000 at a 15% annual rate, before disposal or discounting.
The −0.4-point sensitivity assumes 25% of opportunity-enabled terminal revenue is exposed to stability-sensitive formulations and that matrix limitations reduce realization within that exposure by 8%, producing approximately 2.0% aggregate terminal revenue loss. Mitigation requires validated moisture control, accelerated stability testing, controlled drying and packaging barriers; current sales continue throughout, but reliable stability becomes essential to sustaining premium and functional-format adoption.
Challenges Impact Analysis
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Gummy Matrix Stability | −0.4 pp | US, EU, India, China | Long term (≥ 4 years) |
| Multi-Format Campaign Scheduling | −0.3 pp | US, Germany, India, Singapore | Medium term (2–4 years) |
| Identity and Release Testing | −0.4 pp | US, EU, India, China | Medium term (2–4 years) |
| Ingredient Logistics Variability | −0.3 pp | India–EU, China–EU, Asia–US | Medium term (2–4 years) |
| Cross-Market Label Governance | −0.3 pp | US, EU, Japan, China | Long term (≥ 4 years) |
| Subscription Data Governance | −0.2 pp | US, UK, Germany, South Korea | Medium term (2–4 years) |
Geopolitical Impact Analysis
Geopolitical Impact of the Iran Conflict and Red Sea Disruptions on the Nutraceutical Gummies Market
The ongoing war in the Middle East in 2026 is creating supply chain challenges for the Nutraceutical Gummies Market. Disruptions around the Strait of Hormuz and continued security risks along Red Sea shipping routes have increased uncertainty in international trade. These conditions can raise freight charges, insurance costs, fuel expenses, and delivery times for ingredients, packaging materials, and finished gummy products.
Manufacturers that depend on imported vitamins, minerals, botanical extracts, gelatin, pectin, and other specialised ingredients may face higher sourcing costs and delays. These pressures could affect production schedules, product availability, and retail prices, particularly for companies with limited supplier alternatives.
According to the United Nations Conference on Trade and Development, ship transits through the Strait of Hormuz fell by more than 95% during the disruption reported in March 2026. The waterway is important for energy and fertiliser shipments, so interruptions can also increase costs across wider manufacturing and transport networks.
Regional Insights
Dominating Region: Europe
In 2025, Europe dominated the Nutraceutical Gummies Market, accounting for a 33.21% share, with a market value of USD 7.8 billion, based on the supplied market estimates. The region benefits from established dietary supplement consumption, broad retail distribution, and consumer interest in convenient wellness products. Gummies offer an easy-to-consume format for vitamins, minerals, and other nutritional ingredients. European Union rules also provide a common regulatory framework for food supplements, including requirements for permitted vitamin and mineral sources and consumer protection against misleading claims. The European Commission outlines these requirements under its food supplement regulations.
Online distribution is an important growth channel for nutraceutical gummies across Europe, supported by convenient ordering, product comparisons, and access to a wider range of brands. Eurostat reported that 78% of people in the European Union bought or ordered goods and services online in 2025, compared with 62% in 2015. This demonstrates the wider adoption of online shopping, although the figures cover all goods and services rather than gummy supplements alone. Digital channels allow brands to provide ingredient information, product instructions, and subscription options while reaching customers beyond physical retail locations. However, competition, delivery costs, product authenticity, and compliance with supplement advertising rules remain important considerations.
Key Regions and Countries Insights
- North America
- US
- Canada
- Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Key Players Analysis
Church & Dwight developed Vitafusion as a major gummy vitamin brand, offering chewable supplements for different age groups and nutritional needs. In December 2025, the company announced an agreement to sell Vitafusion and L’il Critters to Piping Rock Health Products, including relevant trademarks, licenses, and manufacturing and distribution facilities. The transaction was completed on December 31, 2025. Church & Dwight reported total company net sales of USD 6,203.2 million for 2025, although this figure was not specific to Vitafusion.
The Bountiful Company has been associated with Nature’s Bounty, a recognised brand in vitamins and nutritional supplements. In August 2021, Nestlé Health Science completed its acquisition of The Bountiful Company’s core brands in a transaction valued at USD 5.75 billion. The deal included Nature’s Bounty, Solgar, Osteo Bi-Flex, and Puritan’s Pride, strengthening Nestlé Health Science’s nutrition and supplement portfolio. Nature’s Bounty operates across several supplement formats, while the acquisition supports a wider platform for nutritional products.
Unilever participates in the nutraceutical gummies market through OLLY, a wellness supplement brand offering products in convenient gummy formats. In its 2025 annual report, Unilever reported total turnover of €50.5 billion across continuing operations and noted that OLLY achieved high single-digit growth, supported by premium gummy innovation. The company’s broader Beauty & Wellbeing business has increasingly focused on wellness products and consumer-oriented product development. While Unilever does not disclose OLLY’s standalone revenue in the cited report, the brand’s reported performance indicates its continued role in the company’s wellness portfolio.
Top Key Players Outlook
- Church And Dwight Co. Inc. (Vitafusion)
- The Bountiful Company (Nature’s Bounty)
- Unilever Plc (OllY)
- The Clorox Company (SmartyPants)
- Hero Nutritionals LLC
- Nature’s Way (Schwabe)
- Jamieson Wellness Inc.
- Bayer AG (One A Day)
- Pharmavite LLC (Nature Made)
- Nestlé S.A. (Garden Of Life)
- Zarbee’s Inc. (J&J)
- Other Key Players
Recent Developments
- In July 2025, Clorox reported full-year net sales of approximately USD 7.1 billion for fiscal year 2025, reflecting its broader consumer-products business rather than nutraceutical gummies.
- In January 2025, Nature’s Way reformulated 8 core Alive! multivitamin products with a Superfood Antioxidant Powder Blend containing 50 mg per 2-gummy serving, including 10 mg of polyphenols from plant ingredients.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 23.5 Bn |
| Forecast Revenue (2035) | USD 82.8 Bn |
| CAGR (2026-2035) | 13.4% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Vitamins & Multivitamins, Minerals, Omega-3 Fatty Acids, Probiotics & Prebiotics, Collagen, Others), By Cosnumer Age Group (Adult, Pediatric, Geriatric), By Source Type (Animal Source, Plant Source Fastest Growing, Microbial / Fermentation-Derived), By Application (Immunity & Strength, Digestive Health, Bone & Muscles Health, Weight Management, Others), By Distribution Channel (Offline, Hypermarket & Supermarket, Pharmacies, Others, Online) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | Church And Dwight Co. Inc., The Bountiful Company, Unilever Plc, The Clorox Company, Hero Nutritionals LLC, Nature’s Way, Jamieson Wellness Inc., Bayer AG, Pharmavite LLC, Nestlé S.A., Zarbee’s Inc. (J&J), Other Key Players |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |





































