


Report Overview
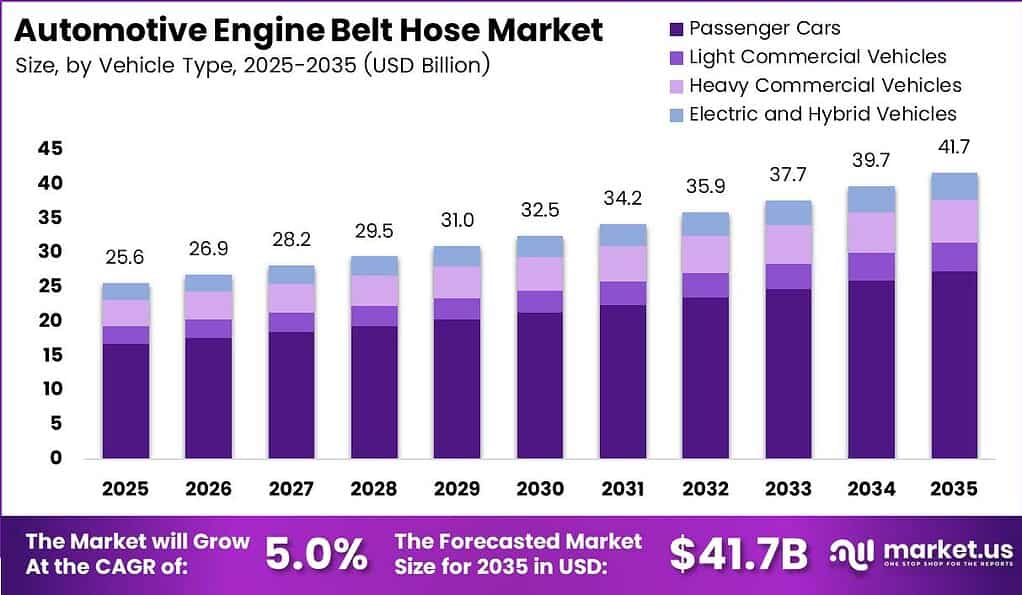
Global Automotive Engine Belt Hose Market size is expected to be worth around USD 41.7 Billion by 2035 from USD 25.6 Billion in 2025, growing at a CAGR of 5.0% during the forecast period 2026 to 2035.
The automotive engine belt and hose market covers power-transmission belts, timing-drive systems, and fluid-handling hoses fitted to internal-combustion, hybrid, and electric powertrains. Products span serpentine and V-belts, toothed timing belts, accessory stretch-fit belts, and cooling, fuel, turbocharger, braking, power-steering, vacuum, and air-conditioning hoses. Demand flows through two channels: original-equipment manufacturing and the replacement aftermarket.
Key Takeaways
- Automotive Engine Belt Hose Market Market value in 2025 stands at USD 25.6 Billion, reaching USD 41.7 Billion by 2035 at a CAGR of 5.0%.
- Drive Belts dominate the Belt Type segment with a 46.35% share in 2025.
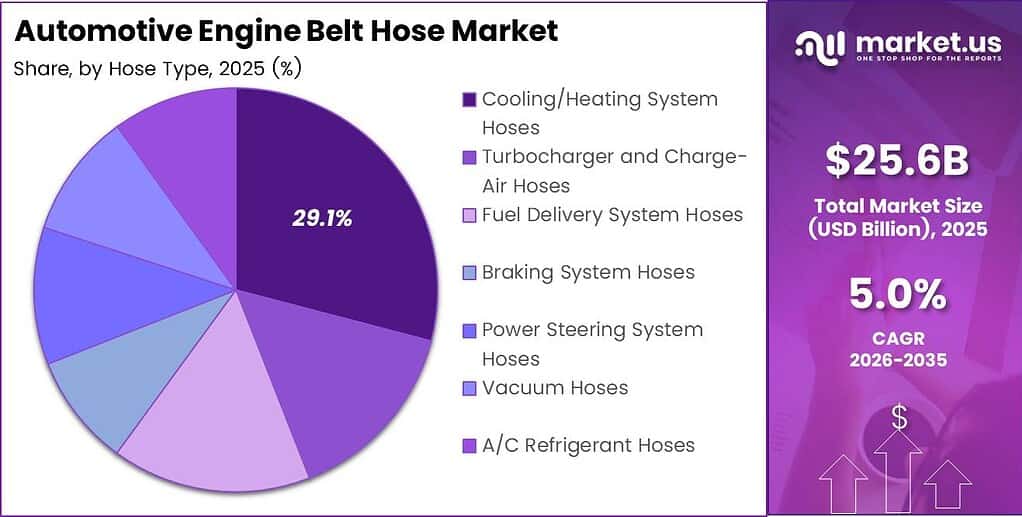
- Cooling and Heating System Hoses lead the Hose Type segment with a 29.10% share in 2025.
- Passenger Cars hold the largest Vehicle Type share at 65.60% in 2025.
- The Aftermarket channel dominates Sales Channel with a 56.20% share in 2025.
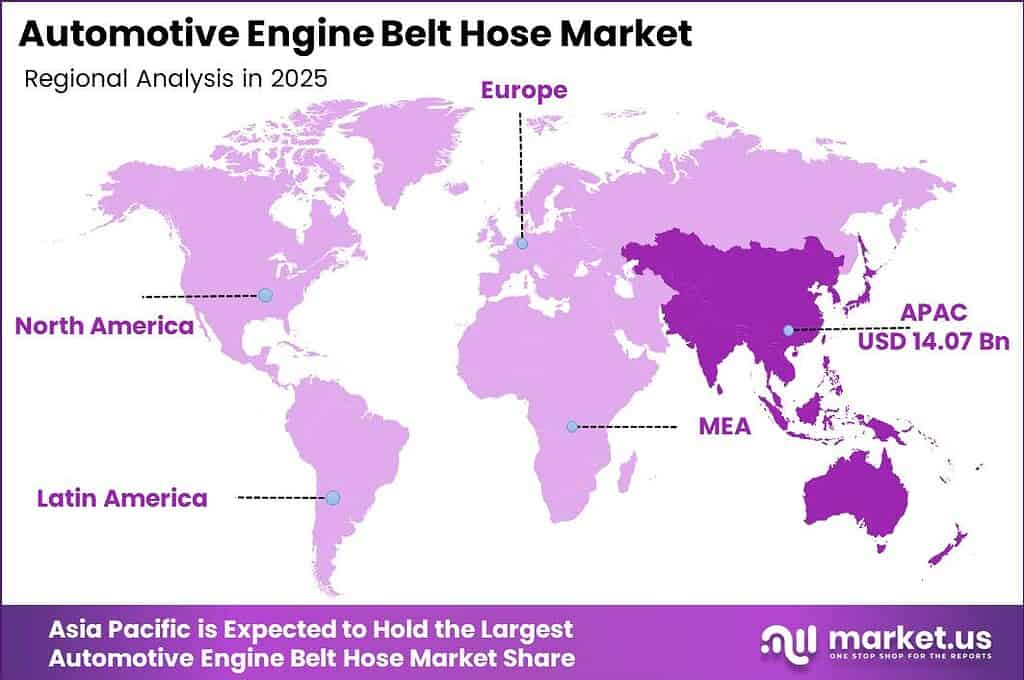
- Asia Pacific is the dominant region with a 54.90% market share, valued at USD 14.07 Billion in 2025.
- Europe is the fastest-growing regional market during the forecast period.
According to the International Organization of Motor Vehicle Manufacturers (OICA), global vehicle production rose to 96.4 million units in 2025, a 3.9% increase from 2024. This production volume directly expands the OEM fitment base for belts and hoses, sustaining near-term demand across every major manufacturing hub.
As reported by the European Automobile Manufacturers’ Association (ACEA), global car production reached 37.7 million units in the first half of 2025, up 3.5% year on year. This output pace confirms that conventional powertrain assembly lines remain active at scale, preserving OEM sourcing volumes for belt and hose suppliers through the medium term.
Continental launched its Vantage hose range in November 2025, comprising Nitrile and EPDM variants in 200-PSI and 300-PSI versions with lightweight construction. This product entry signals that established suppliers are investing in aftermarket-specific line extensions, a strategy that raises brand differentiation and average selling prices in the high-margin replacement channel.
Belt Type Analysis
Drive Belts dominate with 46.35% due to universal fitment across ICE and hybrid platforms.
In 2025, Drive Belts held a dominant market position in the By Belt Type segment of the Automotive Engine Belt Hose Market, with a 46.35% share. Serpentine and V-belt configurations appear on virtually every gasoline and diesel passenger vehicle and commercial unit in operation today. This universal fitment requirement means every new vehicle built and every aging vehicle retained in service generates a predictable OEM or replacement order cycle.
Timing Belts occupy the second-largest position within this segment. These toothed components govern valve-train synchronization on engines where chain-drive systems have not replaced them, and a single timing-belt failure causes catastrophic engine damage. This failure-consequence severity drives adherence to strict replacement intervals, creating a durable, interval-led demand stream that is less price-elastic than most other replacement categories.
Accessory and Stretch-Fit Belts serve the remaining share of this segment. These components route power to alternators, air-conditioning compressors, and ancillary systems on modern downsized engines. As per our research, stretch-fit designs reduce the need for mechanical tensioners, lowering assembly costs for OEMs and creating a growing sub-category that favors suppliers capable of precision elastic-polymer engineering.
Hose Type Analysis
Cooling and Heating System Hoses dominate with 29.10% due to mandatory fitment on every ICE and hybrid powertrain.
In 2025, Cooling and Heating System Hoses held a dominant market position in the By Hose Type segment of the Automotive Engine Belt Hose Market, with a 29.10% share. Coolant circulation is a non-negotiable function on every internal-combustion and hybrid vehicle, making these hoses the single largest volume category in the segment. Thermal-management complexity in hybrid architectures has extended the circuit length and connection-point count per vehicle, raising average content value per unit.
Turbocharger and Charge-Air Hoses represent the fastest-growing sub-category within hose types. The structural shift toward smaller turbocharged engines across passenger and light-commercial platforms has widened the addressable fitment base for charge-air and intercooler plumbing. These hoses must withstand elevated temperature and pressure cycles, positioning specialty-elastomer suppliers at an advantage over commodity producers.
Fuel Delivery System Hoses, Braking System Hoses, Power Steering System Hoses, Vacuum Hoses, and A/C Refrigerant Hoses collectively hold the remaining share of this segment. Each sub-category serves a distinct circuit with specific pressure, chemical, and temperature requirements, preventing commodity consolidation and supporting a range of material-formulation specialists across the supplier landscape.
Vehicle Type Analysis
Passenger Cars dominate with 65.60% due to the largest global fleet volume and shortest replacement cycles.
In 2025, Passenger Cars held a dominant market position in the By Vehicle Type segment of the Automotive Engine Belt Hose Market, with a 65.60% share. The Society of Indian Automobile Manufacturers (SIAM) reported India’s passenger-vehicle sales reached a record 4.3 million units in FY2024–25, up 2%. This expansion in one of the world’s fastest-growing car markets adds direct OEM fitment demand and builds the replacement base that matures over the following three to seven years.
Light Commercial Vehicles form the second-largest vehicle-type sub-segment. Urban delivery growth and last-mile logistics expansion across Asia and Latin America have kept van and small-truck registration rates positive, sustaining a steady secondary belt-and-hose fitment stream alongside passenger-car volumes.
Heavy Commercial Vehicles carry disproportionate belt-and-hose content per unit relative to passenger cars. International Organization of Motor Vehicle Manufacturers (OICA) data shows global vehicle sales rose to 99.8 million units in 2025, up 4.7%, reflecting fleet-wide growth that includes commercial segments. Longer heavy-vehicle service lives translate into more frequent replacement events per unit, supporting aftermarket revenue density.
Electric and Hybrid Vehicles hold the smallest share within this segment today. Their belt-and-hose content per unit is structurally lower than conventional ICE platforms for accessory-drive and combustion-circuit components. However, thermal-management hose content per electric vehicle is rising as battery and e-motor cooling circuits grow more complex, partially offsetting the conventional-content reduction.
Sales Channel Analysis
Aftermarket dominates with 56.20% due to aging global fleet and high replacement frequency.
In 2025, the Aftermarket held a dominant market position in the By Sales Channel segment of the Automotive Engine Belt Hose Market, with a 56.20% share. United Nations Trade and Development (UNCTAD) data shows global maritime trade grew 2.2% in volume in 2024, while seaborne ton-miles expanded 5.9%. This trade expansion supports parts distribution logistics that feed organized aftermarket channels across emerging and developed markets alike.
OEM supply constitutes the remaining channel share and anchors supplier relationships, technical approval cycles, and application-engineering investments. Data from UNCTAD shows the average maritime voyage haul increased from 4,831 miles in 2018 to 5,245 miles in 2024. Longer supply chains create both logistical complexity and opportunity for regionally manufactured replacement inventory positioned closer to end-market demand centers.
Key Market Segments
By Belt Type
- Drive Belts
- Serpentine Belts
- V-Belts
- Timing Belts (Toothed)
- Accessory and Stretch-Fit Belts
By Hose Type
- Cooling/Heating System Hoses
- Turbocharger and Charge-Air Hoses
- Fuel Delivery System Hoses
- Braking System Hoses
- Power Steering System Hoses
- Vacuum Hoses
- A/C Refrigerant Hoses
By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Electric and Hybrid Vehicles
By Sales Channel
- OEM
- Aftermarket
Regional Analysis
Asia Pacific Dominates the Automotive Engine Belt Hose Market with a Market Share of 54.90%, Valued at USD 14.07 Billion
Asia Pacific commands this market through the sheer concentration of vehicle manufacturing capacity on the continent. European Automobile Manufacturers’ Association (ACEA) data confirms Asia accounted for 60.1% of global car production in the first half of 2025. This production concentration means belt and hose suppliers operating within Asian manufacturing corridors hold a structural proximity advantage for OEM fitment contracts.
Europe is the fastest-growing regional market during the forecast period. ACEA data shows the European Union accounted for 15.9% of global car production in H1 2025. Continental announced an approximately $90 million hydraulic-hose plant in Aguascalientes, Mexico, while Yokohama Rubber announced closure of its Kentucky automotive-hose assembly plant and consolidation into two North American assembly plants, targeting a 10% business-profit margin for its MB Business in 2026. These restructuring moves reflect manufacturers repositioning supply chains to serve European aftermarket demand more efficiently.
Other regions contribute incremental but strategically important volumes. The Society of Indian Automobile Manufacturers (SIAM) reported India produced over 31 million total vehicles across all categories in FY2024–25. International Energy Agency (IEA) data shows China produced 12.4 million electric cars in 2024, while global electric-car exports reached approximately 3.2 million units, nearly 20% higher year on year. These export flows carry embedded thermal-management hose content into markets worldwide.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Drivers
Longer vehicle ownership cycles are expanding the installed base reaching preventive-maintenance intervals for serpentine belts, timing systems, and coolant hoses. European Automobile Manufacturers’ Association (ACEA) data shows 256 million cars on EU roads in 2024, up 1.4% annually, alongside 31.1 million vans, up 1.9% year on year. A single accessory-belt replacement event commonly pulls through tensioner, coolant-hose, clamp, and fluid-service demand, raising average invoice value by roughly 15–30% versus a belt-only repair.
Commercial fleet activity adds a separate demand layer. As reported by ACEA, 6.2 million trucks operated on EU roads in 2024, up 0.9% year on year. Aftermarket orders typically carry gross-margin potential around 5–10 percentage points above large-volume OEM supply, making replacement-led business commercially attractive for distributors and branded-parts suppliers across North America, Europe, India, and Latin America.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Aging vehicle parc replacement | +1.2% | North America, Europe, India, Latin America | Short term (≤ 2 years) |
| ICE and hybrid production | +1.0% | Asia-Pacific, North America, Europe | Short term (≤ 2 years) |
| Hybrid thermal-system complexity | +0.8% | China, Japan, Europe, North America | Medium term (2–4 years) |
| Commercial fleet utilization | +0.7% | India, Southeast Asia, North America, Middle East | Short term (≤ 2 years) |
| Premium replacement-part adoption | +0.6% | Europe, North America, urban Asia-Pacific | Medium term (2–4 years) |
| Localized OEM sourcing | +0.5% | India, Mexico, China, Central Europe | Medium term (2–4 years) |
Restraints
Battery-electric vehicles eliminate timing-drive architecture and sharply reduce conventional engine cooling, fuel, vacuum, and accessory-drive belt demand. International Energy Agency (IEA) data shows global electric-car sales exceeded 17 million in 2024, rising more than 25%, while electric cars represented more than 20% of worldwide car sales that year. Belt-and-hose content per BEV can be lower by approximately 60–80% than a conventional ICE platform, directly compressing OEM fitment volumes for legacy product lines.
As reported by the International Energy Agency, worldwide electric-car production reached 17.3 million units in 2024, about one-quarter higher than in 2023. ACEA data shows electrically chargeable vehicles accounted for 1.3% of the EU van fleet and 0.3% of the EU truck fleet in 2024. The EU average truck age stood at 14 years in 2024, confirming that a large legacy ICE commercial base still requires replacement parts, partially cushioning the BEV displacement effect in the short term.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Battery-electric vehicle substitution | -1.4% | China, Europe, North America | Medium term (2–4 years) |
| Automotive tariff cost escalation | -0.9% | North America, export-oriented Asian suppliers | Short term (≤ 2 years) |
| OEM cost-down procurement | -0.8% | Global | Short term (≤ 2 years) |
| Counterfeit replacement components | -0.6% | India, Southeast Asia, Africa, Latin America | Short term (≤ 2 years) |
| Reduced engine-bay component count | -0.5% | Europe, China, Japan, North America | Long term (≥ 4 years) |
| Low-cost unorganized supply | -0.4% | South Asia, Southeast Asia, Latin America | Short term (≤ 2 years) |
Challenges
Raw-material input stacks for engine belts and hoses span natural rubber, synthetic rubber, carbon black, textile cord, aramid reinforcement, steel wire, plasticizers, and adhesives. Movements of roughly 10–25% across an annual sourcing cycle can affect conversion economics because polymeric and reinforcement inputs account for about 45–65% of direct material cost. Customer contracts frequently reset prices quarterly or semiannually, creating timing mismatches that compress gross margin by approximately 200–500 basis points during sharp input spikes.
Trade flow uncertainty adds further complexity. World Trade Organization (WTO) forecast world merchandise-trade volume growth to decelerate from 4.6% in 2025 to 1.9% in 2026. UNCTAD forecast maritime-trade volume growth of only 0.5% for 2025, while the available electric-car model count globally rose 15% year on year to nearly 785 models in 2024. Platform proliferation fragments tooling investment across more variants, raising engineering and validation costs without a proportional revenue increase.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Elastomer feedstock volatility | -1.0% | Global, especially Asia-Pacific manufacturing hubs | Medium term (2–4 years) |
| High-temperature material validation | -0.8% | Europe, China, Japan, North America | Medium term (2–4 years) |
| Multi-tier supply visibility | -0.7% | Global | Medium term (2–4 years) |
| Aftermarket fitment-data accuracy | -0.6% | Global aftermarket channels | Short term (≤ 2 years) |
| Skilled tooling labor shortages | -0.5% | Europe, North America, India, Mexico | Long term (≥ 4 years) |
| Platform lifecycle fragmentation | -0.4% | China, Europe, North America | Medium term (2–4 years) |
Opportunities
Battery-electric thermal-management circuits represent a high-value adjacency for suppliers willing to invest in validated assembly capabilities. Suppliers that shift from individual hose supply to pre-assembled, tested thermal modules can raise value capture per vehicle by approximately 20–40% and expand gross-margin potential by 300–600 basis points through engineering and connector-integration content. Successful execution in this category could add approximately +1.3% above the 5.0% baseline CAGR.
Sustainability commitments are reshaping material sourcing requirements across the supplier base. Sumitomo Riko reduced total greenhouse-gas emissions by 29.3% by FY2025 against its stated baseline, while reporting fluorocarbon leakage of 486 tonnes of CO₂ equivalent in FY2025. UNCTAD forecast average annual seaborne-trade volume growth of 2.0% for 2026–2030, confirming that global parts distribution networks will keep expanding. Suppliers that invest in circular rubber material recovery early will gain procurement preference from OEMs with Scope 3 emissions targets, creating a long-term competitive differentiator.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| EV thermal-management hose systems | +1.3% | China, Europe, North America, South Korea | Medium term (2–4 years) |
| Predictive maintenance service kits | +1.0% | North America, Europe, India, Gulf markets | Medium term (2–4 years) |
| Fleet lifecycle contracts | +0.9% | North America, India, Southeast Asia, Europe | Short term (≤ 2 years) |
| Circular rubber material recovery | +0.7% | Europe, Japan, South Korea, North America | Long term (≥ 4 years) |
| Emerging-market distribution consolidation | +0.6% | India, Africa, Latin America, Southeast Asia | North America, India, Southeast Asia, Europe |
| High-pressure hybrid cooling modules | +0.5% | China, Japan, Europe, North America | Medium term (2–4 years) |
Key Company Insights
Continental AG reported ContiTech sales of €6,005 million in 2025, down 6.0% from €6,387 million in 2024. This revenue contraction reflects the revenue pressure that BEV substitution and OEM cost-down clauses are creating across legacy product lines. Continental AG’s announced sale of the ContiTech group sector to a Lone Star Funds affiliate for €4.0 billion signals a strategic exit from belt-and-hose manufacturing toward higher-margin automotive technology businesses.
Gates Industrial Corporation reported full-year 2025 net sales of $3,443.2 million, up 1.0%, with net income attributable to shareholders of $251.4 million. Modest top-line growth alongside positive profitability confirms Gates’ aftermarket diversification strategy is providing revenue stability even as OEM pricing pressure persists. Goodyear’s estimated $140 million investment in 100% renewable electricity across manufacturing facilities worldwide during 2025–2030 illustrates the capital commitment sustainability transitions now demand from all major suppliers.
Key Players
- Continental AG (ContiTech)
- Gates Industrial Corporation plc
- Sumitomo Riko Company Limited
- Toyoda Gosei Co., Ltd.
- Dayco IP Holdings LLC
- The Goodyear Tire and Rubber Company
- Hutchinson SA
- Cooper-Standard Holdings Inc.
- The Yokohama Rubber Co., Ltd.
- Bando Chemical Industries, Ltd.
- Schaeffler AG
- Mitsuboshi Belting Ltd.
- Nichirin Co., Ltd.
- SKF Group
- Optibelt GmbH
Recent Developments
- October 2025 – Continental AG planned an investment of more than $85 million to expand its Mount Pleasant, Iowa facility, including 2 mixing lines expected to create approximately 50 jobs, with construction anticipated to begin in Q2 2026.
- April 2025 – Dayco IP Holdings LLC began full-scale belt production at its San Luis Potosí, Mexico facility. The 73,000-square-foot plant can produce up to 4.2 million Poly-V belts annually and has scope for EPS and timing-belt production.
- 2025 – The Goodyear Tire and Rubber Company completed sales of its OTR tire business, Dunlop brand, and polymer chemicals business, generating approximately $2.2 billion in gross proceeds during the year.
- Q2 2025 – The Goodyear Tire and Rubber Company approved closure of its Kariega, South Africa manufacturing facility, including approximately 900 job reductions and expected charges beginning at $100 million.
- May 2025 – Dayco expanded its North American aftermarket portfolio with 30 new part numbers, including 8 timing-chain kits, 9 tensioners, and 13 hoses, providing coverage opportunities for approximately 28.8 million vehicles in operation.
- January 2026 – Dayco launched its ELA® 6PK1742EE serpentine belt in North America for selected GM full-size pickup trucks and SUVs with 5.3L and 6.2L engines, using EPDM rib and cushion rubber with a polyamide tensile cord.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 25.6 Billion |
| Forecast Revenue (2035) | USD 41.7 Billion |
| CAGR (2026-2035) | 5.0% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Belt Type (Drive Belts, Timing Belts, Accessory and Stretch-Fit Belts), By Hose Type (Cooling/Heating System Hoses, Turbocharger and Charge-Air Hoses, Fuel Delivery System Hoses, Braking System Hoses, Power Steering System Hoses, Vacuum Hoses, A/C Refrigerant Hoses), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Electric and Hybrid Vehicles), By Sales Channel (OEM, Aftermarket) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Continental AG (ContiTech), Gates Industrial Corporation plc, Sumitomo Riko Company Limited, Toyoda Gosei Co. Ltd., Dayco IP Holdings LLC, The Goodyear Tire and Rubber Company, Hutchinson SA, Cooper-Standard Holdings Inc., The Yokohama Rubber Co. Ltd., Bando Chemical Industries Ltd., Schaeffler AG, Mitsuboshi Belting Ltd., Nichirin Co. Ltd., SKF Group, Optibelt GmbH |
| Customization Scope | Customization for segments, region/country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








