


Report Overview
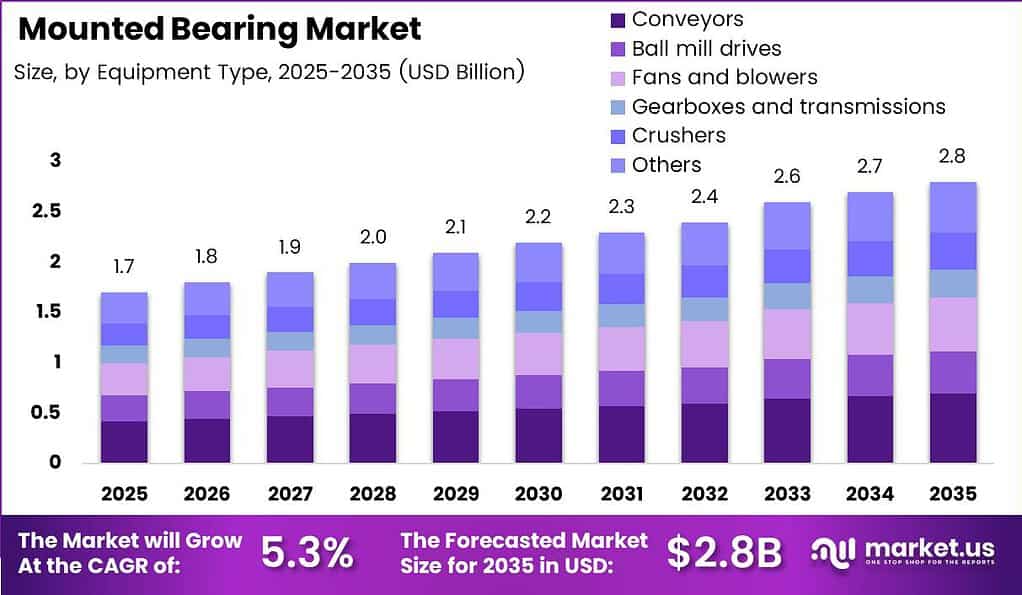
Global Mounted Bearing Market size is expected to be worth around USD 2.8 Billion by 2035 from USD 1.7 Billion in 2025, growing at a CAGR of 5.3% during the forecast period 2026 to 2035.
The mounted bearing market covers housed bearing assemblies where a bearing insert is pre-fitted into a housing unit, enabling direct mounting onto structural frames, shafts, and equipment without custom machining. Products span pillow blocks, flanged units, take-up blocks, and cartridge assemblies used across conveyor systems, agricultural equipment, food processing lines, and industrial machinery. This structure reduces installation time, cuts maintenance complexity, and standardizes replacement cycles across high-volume industrial operations.
Key Takeaways
- The global mounted bearing market is valued at USD 1.7 Billion in 2025 and is forecast to reach USD 2.8 Billion by 2035.
- The market grows at a CAGR of 5.3% during the forecast period 2026 to 2035.
- By Product Type, Ball Bearings dominate with a 65.00% share in 2025.
- By Housing Block Type, Pillow or Plummer Blocks hold the dominant share at 42.50% in 2025.
- By Housing Material, Cast Iron leads with a 70.00% market share in 2025.
- By Equipment Type, Conveyors account for the largest share at 25.00% in 2025.
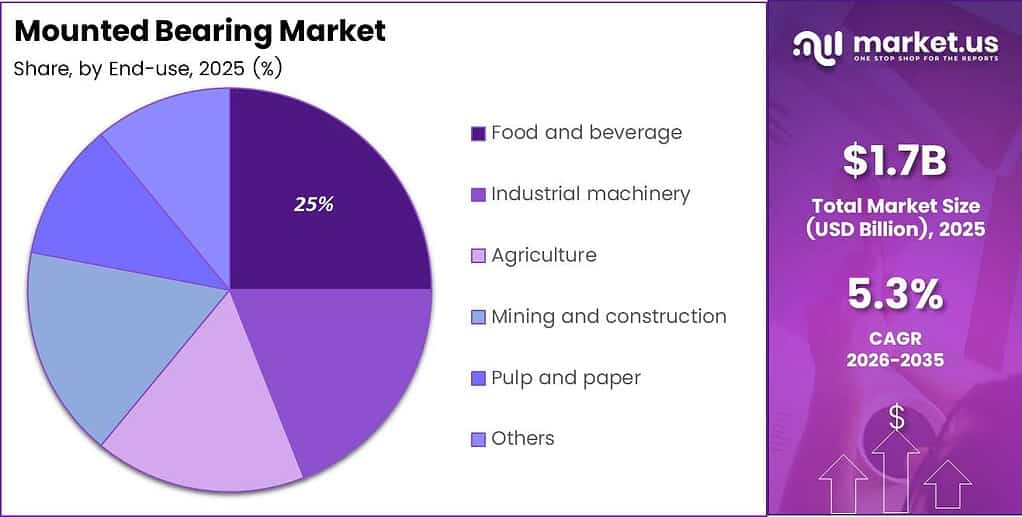
- By End-use Industry, Food and Beverage holds the top position with a 25.00% share in 2025.
- By Distribution Channel, OEM leads with a 68.20% share in 2025.
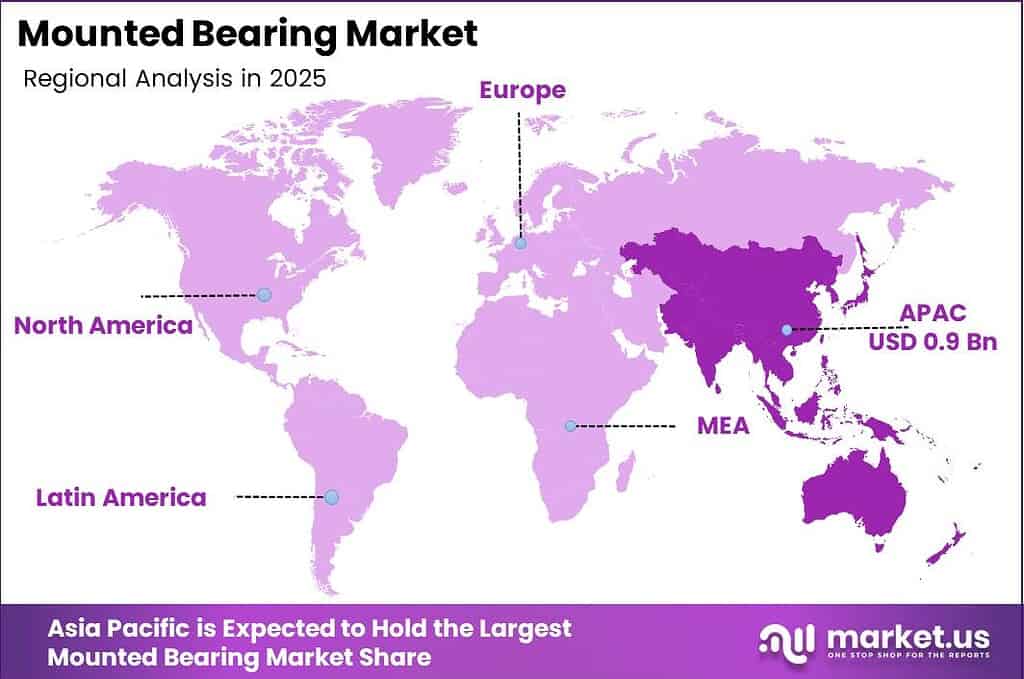
- Asia Pacific dominates the regional landscape with a 55.00% share, valued at USD 0.9 Billion in 2025.
Asia and Oceania have accounted for more than half of global manufacturing value added since 2015, establishing the region as the structural engine of industrial output. This concentration of production activity drives sustained demand for mounted bearing assemblies across conveyors, machinery, and processing equipment. Suppliers that prioritize Asia Pacific distribution and local stocking will capture disproportionate share during this growth cycle.
As per our research, 542,000 industrial robots were installed globally in 2024, signaling an accelerating shift toward automated production environments. Each automated line requires multiple housed bearing positions across drive shafts, conveyors, and transfer systems. This raises bearing-content intensity per facility and shifts procurement toward engineered, sensor-compatible units rather than commodity replacements.
Schaeffler’s completed integration of Vitesco Technologies in October 2024, creating a combined entity with pro-forma annual sales of approximately €25 Billion and over 120,000 employees, illustrates how tier-one bearing suppliers are consolidating to broaden their industrial drivetrain portfolios. This consolidation compresses the competitive space for mid-tier players. Distributors and OEM buyers must reassess supplier agreements as merged entities gain pricing leverage and product bundling capability.
Product Type Analysis
Ball Bearings dominate with 65.00% due to low friction, speed versatility, and wide availability.
In 2025, Ball Bearings held a dominant market position in the By Product Type segment of the Mounted Bearing Market, with a 65.00% share. Their combination of low rotational friction, broad speed-range capability, and standardized dimensions makes them the default choice across conveyors, fans, and light-to-medium industrial machinery. OEM procurement teams favor ball-insert housed units for their interchangeability, which reduces spare-parts SKU complexity and cuts inventory carrying costs.
Roller Bearings serve applications where radial and axial load demands exceed ball bearing capacity, including crushers, heavy conveyors, and mining equipment. Their higher load rating per unit size makes them the preferred insert for pillow blocks in shock-load environments. Buyers pay a price premium for roller-type housed units, which supports higher average selling prices for suppliers serving heavy-industry end markets.
Other bearing types, including spherical plain and specialized insert variants, serve niche applications in agriculture, construction, and process industries where misalignment tolerance or corrosion resistance matters more than rotational speed. These sub-segments collectively hold the remaining share outside ball and roller categories. Their lower volume does not reduce their strategic value, as specialty units carry stronger margins and require application engineering support.
Housing Block Type Analysis
Pillow or Plummer Blocks dominate with 42.50% due to simple two-bolt mounting and universal shaft compatibility.
In 2025, Pillow or Plummer Blocks held a dominant market position in the By Housing Block Type segment of the Mounted Bearing Market, with a 42.50% share. Their two-bolt base design allows horizontal shaft mounting on flat surfaces without custom machined seats, which reduces installation labor and downtime on conveyor lines, fan drives, and general industrial equipment. This installation simplicity makes pillow blocks the default stocking unit for MRO distributors globally.
Flanged Blocks serve applications where shafts run perpendicular to a mounting surface, including wall-mounted fan drives, vertical conveyor take-offs, and gearbox output stages. Their four-bolt or two-bolt flanged face provides rigidity under combined radial and axial loads. This design versatility makes them the second most stocked housed-bearing format across food processing and packaging equipment lines.
Take-up Blocks provide adjustable frame-mounted positions that allow belt tension management on conveyor systems, making them essential for aggregate handling, grain elevators, and long-span material transfer lines. Cartridge Units fit into bored housings already machined into equipment frames, reducing overall envelope while maintaining easy insert replacement. Timken’s August 2024 acquisition of CGI Inc., a precision drive-system manufacturer with approximately US$45 Million in expected 2024 sales, signals that leading players are extending their motion control portfolios beyond standard housed-bearing formats to capture higher-value drivetrain positions. Other housing formats hold the remaining share.
Housing Material Analysis
Cast Iron dominates with 70.00% due to cost efficiency, machinability, and broad load capacity.
In 2025, Cast Iron held a dominant market position in the By Housing Material segment of the Mounted Bearing Market, with a 70.00% share. Cast iron housings offer compressive strength, vibration damping, and low material cost compared with steel or polymer alternatives. These properties make cast iron the standard housing choice for pillow blocks, flanged units, and take-up assemblies used across general industrial, agricultural, and mining applications.
Stainless Steel housings serve food processing, pharmaceutical, and chemical applications where corrosion resistance and washdown compliance are non-negotiable. Their higher material and machining cost is justified by regulatory requirements and reduced replacement frequency in wet or chemically aggressive environments. This creates a structurally protected sub-segment where price competition is secondary to certification and performance validation.
Other housing materials, including ductile iron, thermoplastic composites, and aluminum alloys, address weight-sensitive or electrically insulating applications in packaging machinery, agriculture, and light assembly equipment. These materials hold the remaining share outside cast iron and stainless steel. Their adoption is growing in cost-driven segments where weight reduction or corrosion resistance is prioritized over the load capacity of traditional metal housings.
Equipment Type Analysis
Conveyors dominate with 25.00% due to continuous-duty bearing loads and high replacement frequency.
In 2025, Conveyors held a dominant market position in the By Equipment Type segment of the Mounted Bearing Market, with a 25.00% share. Conveyor systems require multiple housed bearing positions per line, covering drive ends, tail pulleys, idler frames, and take-up stations, creating high per-installation bearing counts. Continuous-duty cycles accelerate wear rates and shorten replacement intervals, making conveyors the single largest aftermarket demand engine in the mounted bearing segment.
Ball Mill Drives operate under sustained radial loading from rotating drum mass in cement, mining, and mineral-processing facilities. The high torque and shock-load profile demands heavy-duty roller-insert housed units with reinforced housings and extended relubrication intervals. This equipment type supports premium pricing and creates aftermarket attachment opportunities for suppliers offering application-matched unit specifications and scheduled service programs.
According to the IEA, global electricity demand is forecast to grow by an average 3.3% in 2025 and 3.7% in 2026, expanding the installed base of fans and blowers across power generation, HVAC, and industrial ventilation. IEA data also shows global electricity consumption increased by 4.3% in 2024, confirming that fan-drive bearing demand tracks directly with energy infrastructure investment. Suppliers that position housed units for fan and blower applications can capture a share of this expanding installed base before the next replacement cycle peaks.
Gearboxes and Transmissions, Crushers, and other equipment types including pumps, mixers, and agitators account for the remaining share of the Equipment Type segment. Each sub-segment carries distinct load, speed, and environmental requirements that create application-engineering opportunities for suppliers with broad product portfolios. These segments collectively represent a diversified demand base that reduces revenue concentration risk for established distributors.
End-use Industry Analysis
Food and Beverage dominates with 25.00% due to strict hygiene standards and high equipment uptime requirements.
In 2025, Food and Beverage held a dominant market position in the By End-use Industry segment of the Mounted Bearing Market, with a 25.00% share. Hygiene-grade regulations require stainless steel or food-safe polymer housed units with sealed inserts and NSF-compliant lubrication, creating a specification-driven procurement process that limits substitution by unbranded imports. High-throughput processing lines also demand predictable replacement schedules, supporting aftermarket attachment and planned-maintenance contracts.
Industrial Machinery represents the second-largest end-use category, covering general-purpose manufacturing equipment across metals, plastics, textiles, and assembly operations. Broad application diversity in this segment means housed bearing demand tracks closely with overall industrial output and capital expenditure cycles. Suppliers serving industrial machinery OEMs benefit from long-term supply agreements and high design-in switching costs once a bearing specification is embedded in a platform.
Agriculture drives demand for housed bearings across grain augers, combine drives, planters, and irrigation equipment, where exposure to dust, moisture, and field debris accelerates bearing wear. Mining and Construction require heavy-duty cast-iron pillow blocks and roller inserts for crushers, screens, bucket elevators, and bulk material-handling systems. Pulp and Paper operations demand corrosion-resistant housed units suited to wet, chemically active environments. These segments, along with others in the end-use base, hold the remaining share collectively.
Distribution Channel Analysis
OEM dominates with 68.20% due to design-in specifications and long-term supply agreements.
In 2025, OEM held a dominant market position in the By Distribution Channel segment of the Mounted Bearing Market, with a 68.20% share. OEM relationships embed bearing specifications directly into equipment designs, locking in preferred suppliers for the production lifetime of each platform. As reported by the WTO, world merchandise-trade volume grew 4.6% in 2025, expanding cross-border equipment shipments and increasing the global reach of OEM-specified bearing content. This dynamic reinforces the structural advantage of suppliers with established OEM design-in positions.
The Aftermarket channel covers MRO replacement demand across the global installed base of conveyor systems, agricultural machinery, industrial fans, and process equipment. Aftermarket buyers prioritize availability, delivery speed, and total replacement cost over initial unit price, creating a distinct commercial model from OEM supply. Distributors that stock broad housed-bearing assortments across bore sizes, housing styles, and material grades capture disproportionate aftermarket share by minimizing customer downtime exposure.
Key Market Segments
By Product Type
- Ball Bearings
- Roller Bearings
- Others
By Housing Block Type
- Pillow or Plummer Blocks
- Flanged Blocks
- Take-up Blocks
- Cartridge Units
- Others
By Housing Material
- Cast Iron
- Stainless Steel
- Others
By Equipment Type
- Conveyors
- Ball Mill Drives
- Fans and Blowers
- Gearboxes and Transmissions
- Crushers
- Others
By End-use Industry
- Food and Beverage
- Industrial Machinery
- Agriculture
- Mining and Construction
- Pulp and Paper
- Others
By Distribution Channel
- OEM
- Aftermarket
Regional Analysis
Asia Pacific Dominates the Mounted Bearing Market with a Market Share of 55.00%, Valued at USD 0.9 Billion
Asia Pacific holds a 55.00% share of the global mounted bearing market, valued at USD 0.9 Billion in 2025. According to World Steel Association data, China produced 1,005.1 Million tonnes of crude steel in 2024, while India produced 149.4 Million tonnes and Japan produced 84.0 Million tonnes. This steel output concentration underpins a dense industrial base that sustains high-volume demand for housed bearing assemblies across manufacturing, construction, and heavy equipment sectors.
World Steel Association figures show Asia and Oceania produced 99.7 Million tonnes of crude steel in December 2025, down 6.3% year on year. This contraction signals a near-term softening in heavy-industry output that may reduce replacement bearing demand in steel-adjacent end markets. However, the long-term regional growth trajectory remains intact, supported by ongoing infrastructure investment, rising automation penetration, and expanding food processing capacity across Southeast Asia and India.
North America and Europe represent the second and third-largest regional markets, respectively, driven by aftermarket replacement demand across aging conveyor infrastructure, food processing facilities, and industrial machinery fleets. Latin America and the Middle East and Africa are earlier-stage markets where agricultural mechanization, mining investment, and logistics infrastructure expansion are beginning to build a foundation for sustained mounted bearing demand. These regions collectively hold the remaining share outside Asia Pacific.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Drivers
Manufacturers are retrofitting aging production lines with automated conveyors, packaging cells, and material-transfer systems, raising bearing-content intensity per production line beyond what new factory construction alone would generate. Automation projects require multiple mounted units across drive ends, idler positions, take-up stations, and auxiliary shafts, while condition-monitoring requirements favor higher-specification housed bearings with improved sealing and relubrication capability. This supports an estimated +1.2% incremental contribution to the 5.3% baseline CAGR.
Suppliers benefit from a mix shift toward engineered units, sensor-ready housings, and application support, which improves price realization and aftermarket attachment while reducing dependence on lower-margin commodity bearing sales. The automation investment cycle strengthened through 2024 and 2025 as manufacturers targeted labor-productivity gains and throughput resilience. Buyers that delay automation procurement risk margin erosion relative to competitors who have already secured engineered supply agreements with preferred bearing manufacturers.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Industrial automation retrofits | +1.2% | Global; strongest in Asia-Pacific, North America and Europe | Short term (≤ 2 years) |
| Conveyor-system investment | +0.9% | Global logistics, warehousing and food processing hubs | Short term (≤ 2 years) |
| Food-grade equipment upgrades | +0.7% | North America, Europe, India, China and Southeast Asia | Medium term (2–4 years) |
| Agricultural mechanization demand | +0.6% | India, Latin America, North America and Eastern Europe | Medium term (2–4 years) |
| Motor efficiency replacements | +0.5% | Europe, North America, Japan and developed Asian markets | Medium term (2–4 years) |
| Aftermarket maintenance cycles | +0.4% | Global installed industrial base | Short term (≤ 2 years) |
Restraints
Mounted-bearing production depends on bearing-grade steel, cast housings, forged rings, and precision-machined components, exposing producers to both raw-material inflation and trade-policy disruptions. United States steel tariffs rose to 50% in June 2025 after a 25% rate took effect in March 2025, raising input costs for manufacturers and distributors with import-dependent supply chains. Where annual supply contracts cannot absorb the full increase, a steel-cost shock can compress gross margin by roughly 100 to 300 basis points on standard housed-bearing lines.
Price pass-through risks deferred purchases by small and mid-sized industrial customers, while higher delivered prices reduce replacement demand and tighten distributor inventory budgets. The estimated -1.1% deduction from the baseline CAGR reflects an immediate sales restraint concentrated in conveyor, pump, and fan-equipment upgrade cycles. Suppliers with diversified sourcing or vertically integrated steel processing hold a structural cost advantage over those reliant on open-market procurement.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Steel-cost and tariff pressure | -1.1% | United States import-dependent supply chains; spillover to global trade | Short term (≤ 2 years) |
| Weak heavy-industry capital expenditure | -0.8% | Europe, China, Latin America and selected mining economies | Short term (≤ 2 years) |
| Customer inventory destocking | -0.6% | North America, Europe and export-oriented Asian manufacturing | Short term (≤ 2 years) |
| Low-cost unbranded imports | -0.5% | India, Southeast Asia, Middle East, Africa and Latin America | Medium term (2–4 years) |
| High financing cost for machinery | -0.4% | Global; most acute in rate-sensitive emerging markets | Short term (≤ 2 years) |
| Mining project deferrals | -0.3% | Australia, Latin America, Africa and Canada | Medium term (2–4 years) |
Challenges
Counterfeit and falsely represented mounted bearings create structural friction because visual similarity does not ensure equivalent steel cleanliness, heat treatment, internal clearance, sealing performance, or load rating. A premature failure in a conveyor, grain-handling line, or process pump can generate downtime costs many times the purchase price of the bearing itself. Fragmented distributor networks make origin verification difficult, slowing customer adoption of premium products and increasing warranty-screening costs for reputable manufacturers.
The resulting -0.9% drag on growth potential arises from higher spending on serialization, distributor audits, and channel enforcement rather than from lost current demand alone. Long-term mitigation requires manufacturers to deploy traceable product identifiers, authenticated digital catalogs, and controlled distributor programs. End users must also strengthen approved-vendor controls and maintenance-record discipline before the market can fully monetize reliability-led product differentiation.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Counterfeit product traceability | -0.9% | Global; elevated in fragmented aftermarket channels | Medium term (2–4 years) |
| Lubrication failure prevention | -0.7% | Global heavy industry, food processing and agriculture | Medium term (2–4 years) |
| Skilled maintenance labor gap | -0.6% | North America, Europe, Japan and industrializing Asia | Long term (≥ 4 years) |
| Multi-tier supplier visibility | -0.5% | Global cross-border manufacturing networks | Medium term (2–4 years) |
| Sensor interoperability standards | -0.4% | North America, Europe, Japan, South Korea and China | Long term (≥ 4 years) |
| Harsh-environment sealing reliability | -0.3% | Mining, aggregates, marine, agriculture and pulp applications | Medium term (2–4 years) |
Opportunities
Condition-monitoring service models remain an underpenetrated area because most mounted-bearing transactions are still unit-based replacement sales, with vibration, temperature, and lubrication data managed separately by plant-maintenance teams. The opportunity lies in converting high-criticality bearing positions into subscription-supported reliability offerings that combine sensor-ready housings, wireless monitoring, anomaly alerts, and planned replacement kits. This model can add an estimated +1.3% upside to the 5.3% baseline CAGR when scaled beyond pilot accounts.
Suppliers that achieve remote-monitoring adoption can reasonably target gross-margin expansion of approximately 200 to 500 basis points at the account level through higher-value product mix and reduced emergency-shipment expense. Predictive intervention reduces unplanned downtime while shifting revenue from episodic parts sales toward recurring service. Early movers that build proprietary monitoring platforms and secure data-sharing agreements with industrial customers will establish switching costs that are difficult for commodity suppliers to replicate.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Condition-monitoring service models | +1.3% | North America, Europe, Japan, South Korea, China and India | Medium term (2–4 years) |
| Food-safe sealed bearing conversions | +0.9% | North America, Europe, China, India and Southeast Asia | Medium term (2–4 years) |
| Localized aftermarket assembly | +0.8% | India, Southeast Asia, Middle East, Africa and Latin America | Medium term (2–4 years) |
| Renewable-material handling systems | +0.7% | China, India, Europe, North America and Australia | Long term (≥ 4 years) |
| Circular remanufacturing programs | +0.6% | Europe, North America and Japan | Long term (≥ 4 years) |
| Distributor consolidation platforms | +0.5% | India, Southeast Asia, Middle East, Africa and Latin America | Medium term (2–4 years) |
Key Company Insights
SKF Group reported SEK 91,583 Million in 2025 annual sales and employed 37,271 people globally. The company reduced scope 1 and scope 2 emissions by 79% from its 2019 baseline, positioning sustainability performance as a procurement differentiator for regulated industrial buyers. In March 2026, SKF published its 2025 Annual and Sustainability Report, reinforcing its commitment to transparent environmental accountability as a competitive signal to ESG-driven OEM customers.
Schaeffler AG reported 2025 revenue of €23,492 Million, down from €24,313 Million in 2024, reflecting macro pressure on European and Chinese heavy-industry demand. However, Schaeffler completed its merger with Vitesco Technologies in October 2024, creating a combined entity with pro-forma annual sales of approximately €25 Billion and over 120,000 employees across more than 100 production facilities. The merger projected an annual EBIT uplift of €600 Million with full synergies expected for the first time in 2029, signaling a structural repositioning from bearing supply toward integrated drivetrain solutions.
Key Players
- SKF Group
- Schaeffler AG
- The Timken Company
- NSK Ltd.
- NTN Corporation
- JTEKT Corporation
- Regal Rexnord Corporation
- ABB Ltd. – Dodge Mounted Bearings
- RBC Bearings Incorporated
- Wafangdian Bearing Group Corporation
- FYH Inc.
- ASAHI SEIKO Co., Ltd.
- P.T. International Corporation
- Peer Bearing Company
- NRB Industrial Bearings Limited
Recent Developments
- 09 March 2026 – SKF signed an agreement to acquire G-Tech Instruments Inc., a condition-monitoring specialist with approximately US$10 Million in 2025 sales and 50 employees; the acquisition was expected to close within six months, strengthening SKF’s sensor-enabled bearing portfolio.
- 04 February 2026 – Timken reported 2025 operating cash flow of US$554.3 Million and free cash flow of US$406.1 Million, demonstrating strong cash generation capacity relative to its US$4.6 Billion revenue base.
- 04 February 2026 – Timken reduced total debt by US$140.7 Million and net debt by US$131.9 Million during 2025, strengthening its balance sheet ahead of the next acquisition or capital deployment cycle.
- 04 February 2026 – Timken issued 2026 guidance for total revenue growth of 2% to 4% and adjusted earnings per share of US$5.50 to US$6.00, signaling management confidence in near-term demand across its bearing and motion control segments.
- 01 October 2024 – Schaeffler projected that its Vitesco merger would generate an annual EBIT impact of €600 Million, with full synergy potential expected for the first time in 2029, reflecting a long-horizon integration strategy across its combined industrial and automotive drivetrain divisions.
- 04 February 2026 – Timken reported 2025 net sales of US$4,581.8 Million with an adjusted EBITDA of US$795.8 Million, equal to a 17.4% adjusted EBITDA margin, with the Engineered Bearings segment contributing US$3,018.1 Million at an 18.9% margin and Industrial Motion generating US$1,563.7 Million at a 19.0% margin.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 1.7 Billion |
| Forecast Revenue (2035) | USD 2.8 Billion |
| CAGR (2026-2035) | 5.3% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Ball Bearings, Roller Bearings, Others), By Housing Block Type (Pillow or Plummer Blocks, Flanged Blocks, Take-up Blocks, Cartridge Units, Others), By Housing Material (Cast Iron, Stainless Steel, Others), By Equipment Type (Conveyors, Ball Mill Drives, Fans and Blowers, Gearboxes and Transmissions, Crushers, Others), By End-use Industry (Food and Beverage, Industrial Machinery, Agriculture, Mining and Construction, Pulp and Paper, Others), By Distribution Channel (OEM, Aftermarket) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | SKF Group, Schaeffler AG, The Timken Company, NSK Ltd., NTN Corporation, JTEKT Corporation, Regal Rexnord Corporation, ABB Ltd. – Dodge Mounted Bearings, RBC Bearings Incorporated, Wafangdian Bearing Group Corporation, FYH Inc., ASAHI SEIKO Co., Ltd., P.T. International Corporation, Peer Bearing Company, NRB Industrial Bearings Limited |
| Customization Scope | Customization for segments, region/country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








