


Key Findings at a Glance
- Japan’s construction market is estimated at USD 558.91 Billion in 2026 and is projected to reach USD 1,010.71 Billion by 2035, a CAGR of 6.8%.
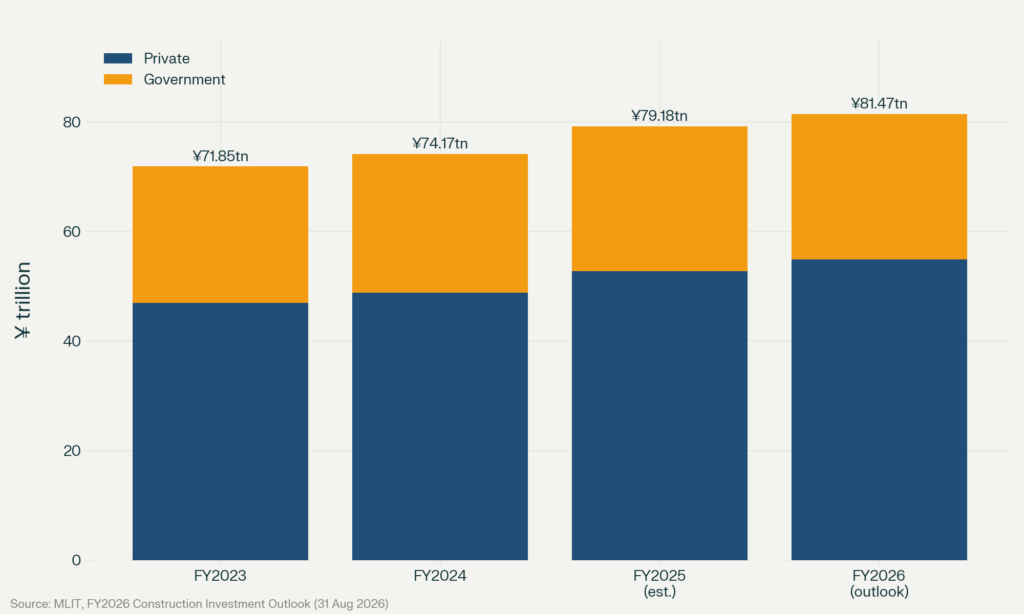
- MLIT expects construction investment of ¥81.47 trillion in FY2026, up 2.9%, after a 6.8% rise in FY2025.
- Private investment makes up 67.35% of the total and is growing faster than public investment (+4.1% vs +0.6% in FY2026).
- The construction workforce has fallen to 4.78 million, down about 30% from its 1997 peak, and about 37% of workers are aged 55 or over.
- Commercial construction (7.9% CAGR) and Hokkaido (8.9% CAGR) are the fastest-growing sector and region.
Market Overview
The Japan Construction Market is estimated at USD 558.91 Billion in 2026 and is projected to reach USD 1,010.71 Billion by 2035, growing at a CAGR of 6.8% over the forecast period.
Japan’s construction sector is at its strongest level in three decades. According to MLIT, construction investment rose 3.2% to ¥74.17 trillion in FY2024 and 6.8% to an estimated ¥79.18 trillion in FY2025. It is forecast to reach ¥81.47 trillion in FY2026. RICE’s July 2026 forecast is higher, at ¥83.26 trillion for FY2026 and ¥86.35 trillion for FY2027, which would beat the record of about ¥84 trillion set in FY1992.
Much of this growth comes from higher prices rather than more building. RICE expects real (inflation-adjusted) investment to grow only 2.4% in FY2026, against 6.3% in nominal terms. Private companies fund 67% of construction, and the government funds 33%.
The market covers residential, commercial and infrastructure projects, both new builds and renovation. Earthquake-safety standards, urban redevelopment and disaster-resilience programmes shape project pipelines across all prefectures. A shrinking workforce is pushing contractors towards digital tools and factory-built (off-site) construction. Japan’s labour shortage is more severe than in most other Asia-Pacific construction markets, which sets it apart.
Analyst insight: “Japan’s construction boom is mainly a price boom. RICE forecasts 6.3% nominal growth in FY2026 but only 2.4% real growth, which means about 60% of the increase comes from higher material and labour costs, not more building. At the same time, the workforce has fallen to 4.78 million. FY2026 investment of ¥81.47 trillion works out to about ¥17.0 million per construction worker. Contractors can’t add volume without adding people, so profits now depend on pricing power and productivity, not on winning more orders. This is why the top contractors posted record profits in the year to March 2026 even as some saw sales fall.”
— Research Team, Market.us 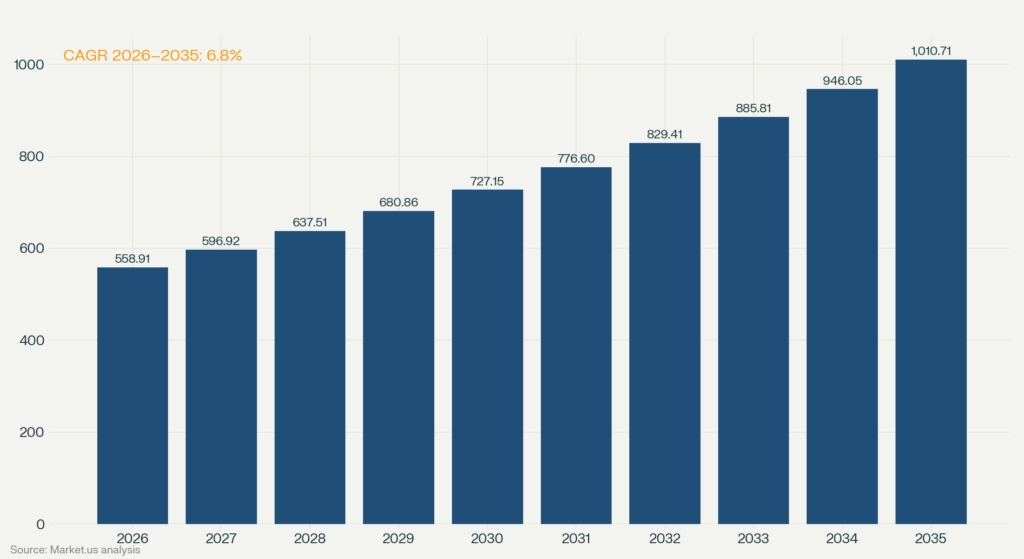
Market Definition
This report measures the total annual value of construction activity in Japan. It includes:
- Construction investment: All building and civil engineering work, both new and renovation, as measured by MLIT on an output basis.
- Construction-related professional services: Architectural design, construction consulting and surveying linked to construction projects.
The report covers residential, commercial and infrastructure construction funded by both private and public sources. It does not include real estate transactions, building materials sold outside construction projects, or construction by Japanese companies overseas.
Key Takeaways
- The market is valued at USD 558.91 Billion in 2026 and is expected to reach USD 1,010.71 Billion by 2035, at a CAGR of 6.8%.
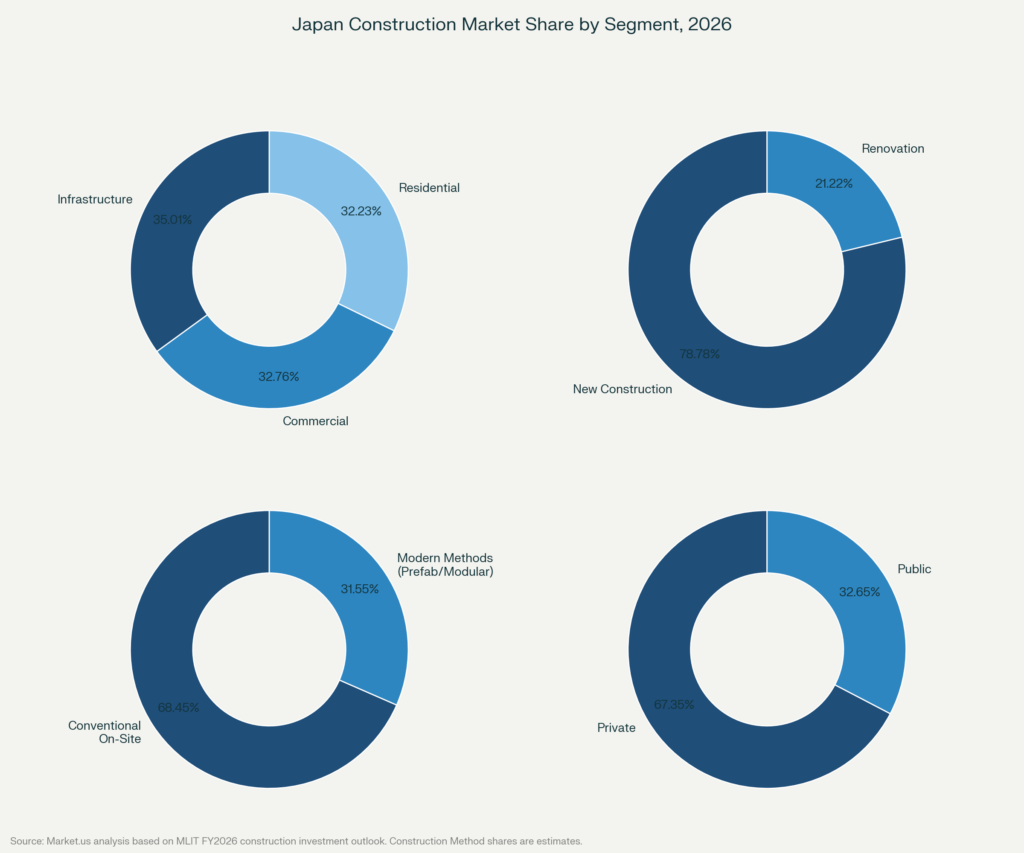
- By Sector: Infrastructure led with a 35.01% share in 2026.
- By Construction Type: New Construction led with a 78.78% share in 2026.
- By Construction Method: Conventional On-Site led with a 68.45% share in 2026.
- By Investment Source: Private led with a 67.35% share in 2026.
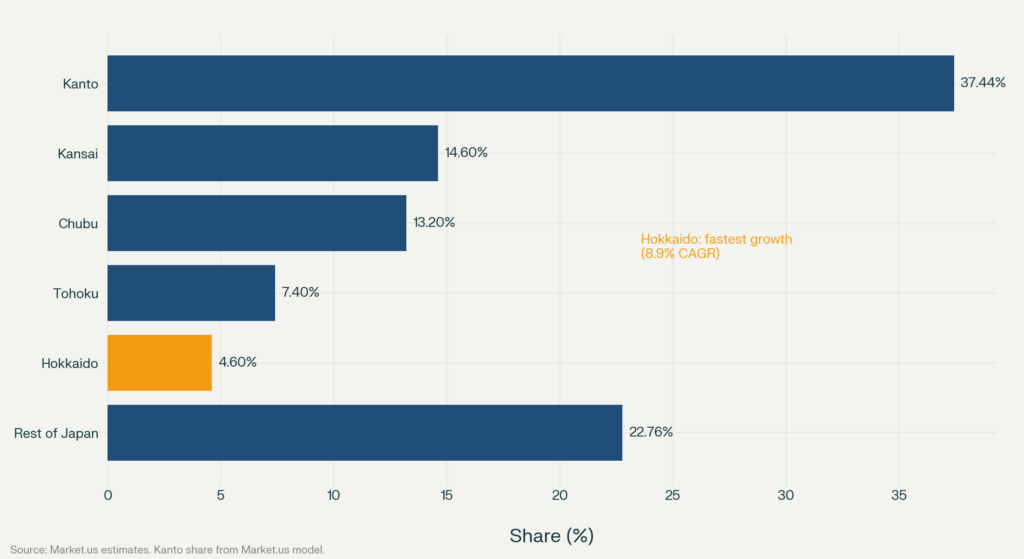
- By Region: Kanto led with a 37.44% share in 2026.
- Fastest-growing categories: Commercial (7.9% CAGR), Renovation (7.6%), Modern Methods of Construction (8.9%), Private (7.22%) and Hokkaido (8.9%).
- Top 5 key players: Obayashi Corporation, Kajima Corporation, Shimizu Corporation, Taisei Corporation, Takenaka Corporation.
Key Market Statistics
| Indicator | Value | Source |
|---|---|---|
| Construction investment, FY2024 | ¥74.17 trillion | MLIT |
| Construction investment, FY2025 (estimate) | ¥79.18 trillion (+6.8%) | MLIT |
| Construction investment, FY2026 (outlook) | ¥81.47 trillion (+2.9%) | MLIT |
| Construction investment, FY2026 (forecast) | ¥83.26 trillion (+6.3% nominal, +2.4% real) | RICE |
| Construction investment, FY2027 (forecast) | ¥86.35 trillion (+3.7%) | RICE |
| Private share of investment, FY2026 | 67% | MLIT |
| Building vs civil engineering, FY2026 | ¥52.95tn vs ¥28.52tn | MLIT |
| Renovation investment, FY2026 | ¥17.29 trillion | MLIT |
| New housing starts, FY2025 | 711,171 units (−12.9%) | MLIT |
| Construction workers, 2025 | 4.78 million (7.0% of all workers) | Japan Federation of Construction Contractors |
| Workers aged 55+ / 29 and under, 2025 | ~37% / ~12% | Japan Federation of Construction Contractors |
| National resilience plan, FY2026–FY2030 | ¥20 trillion+ | Cabinet Secretariat |
| Average exchange rate, 2026 | ¥156.44 per USD | Market exchange rate data |
Research Methodology
How the Market Size Was Built
| Component (2026) | Basis | Value (¥ trillion) | Value (USD Bn) |
|---|---|---|---|
| Construction investment | MLIT FY2026 outlook | 81.47 | 520.77 |
| Construction-related professional services | Design, consulting and surveying linked to projects (est.) | 5.96 | 38.14 |
| Total | 87.43 | 558.91 |
USD values use the 2026 average exchange rate of ¥156.44 per USD. As a cross-check, RICE’s higher FY2026 forecast of ¥83.26 trillion supports the investment component.
Forecast Approach
The 6.8% USD CAGR for 2026–2035 combines two drivers:
- Nominal growth in yen (about 4.5% a year): Construction cost inflation, the ¥20 trillion+ national resilience plan for FY2026–FY2030, and private investment in semiconductor plants, data centres and logistics facilities. MLIT and RICE growth rates for FY2024–FY2027 averaged roughly 4–5%.
- Yen recovery (about 2.2% a year): The forecast assumes the yen gradually strengthens from ¥156 per USD in 2026 to about ¥129 per USD by 2035. At a constant exchange rate, the CAGR would be about 4.5%.
Segment and regional CAGRs are set above or below the national rate based on investment trends and project pipelines. They are balanced so that each segment adds up to the national forecast.
Data and Validation
- Top-down: National totals from MLIT’s FY2026 construction investment outlook, published on 31 August 2026, were split by sector, construction type and investment source using MLIT’s own breakdown.
- Bottom-up: Company results and announced projects were used to check the trends in each segment and region.
- Modelled figures: Construction Method shares, regional shares other than Kanto, and all 2035 values and CAGRs are Market.us estimates. They are labelled as estimates throughout.
- Primary and expert validation: For this 2026 edition, findings were checked against first-hand statements from market participants published between August 2024 and August 2026. Analysts reviewed results for the fiscal year ended 31 March 2026 from Obayashi, Kajima, Taisei and Shimizu, including management guidance for the fiscal year ending March 2027. This guidance was used to test assumptions on orders, margins and project pipelines. Analysts also reviewed 11 developments announced between August 2024 and August 2026, including investments by Bridgestone, DENSO, Mitsui & Co., Takenaka, Toshiba Energy Systems & Solutions, Nitto Denko, Rapidus and Micron. Forecast assumptions were checked against MLIT’s FY2026 outlook (31 August 2026), RICE’s forecast (27 July 2026), and the First National Resilience Mid-term Implementation Plan approved by the Cabinet on 6 June 2025.
How this report was produced: Market.us analysts collected and checked data from government statistics, research institutes and company filings. AI tools assisted with drafting and formatting. All figures, analysis and conclusions were reviewed and approved by [Reviewer Name] before publication.
| Segment | Category | 2026 Share | 2026 Value (USD Bn) | 2035 Value (USD Bn) | CAGR 2026–2035 |
|---|---|---|---|---|---|
| Sector | Infrastructure | 35.01% | 195.67 | 353.57 | 6.79% |
| Sector | Commercial | 32.76% | 183.10 | 362.98 | 7.90% |
| Sector | Residential | 32.23% | 180.14 | 294.16 | 5.60% |
| Construction Type | New Construction | 78.78% | 440.31 | 781.41 | 6.58% |
| Construction Type | Renovation | 21.22% | 118.60 | 229.30 | 7.60% |
| Construction Method | Conventional On-Site | 68.45% | 382.57 | 630.88 | 5.72% |
| Construction Method | Modern Methods of Construction | 31.55% | 176.34 | 379.83 | 8.90% |
| Investment Source | Private | 67.35% | 376.43 | 705.01 | 7.22% |
| Investment Source | Public | 32.65% | 182.48 | 305.70 | 5.90% |
Sector Analysis
Infrastructure accounted for 35.01% of the sector segment in 2026, worth USD 195.67 Billion, the highest of any category.
Infrastructure leads because civil engineering, which covers roads, railways, rivers, ports, energy and utilities, is the largest single type of construction in Japan. MLIT expects civil engineering investment of ¥28.52 trillion in FY2026, of which the government funds ¥18.58 trillion. Under the First National Resilience Mid-term Implementation Plan, the government will spend more than ¥20 trillion between FY2026 and FY2030. The plan targets disaster prevention and the replacement of ageing infrastructure, which gives contractors a stable pipeline of public work.
Commercial construction is the fastest-growing sector, at an estimated 7.9% CAGR. MLIT expects private non-residential construction to rise 6.6% to ¥22.26 trillion in FY2026, and RICE expects ¥24.10 trillion in FY2027. Semiconductor plants, data centres, logistics warehouses and urban redevelopment projects are the main drivers.
Residential holds 32.23% but is growing more slowly, at a 5.6% CAGR. New housing starts fell 12.9% to 711,171 units in FY2025. That is lower than in FY2009, after the global financial crisis, and the second-lowest level since FY1962. The fall followed demand pulled forward before the April 2025 changes to building and energy-efficiency rules, alongside population decline and rising prices. RICE expects starts to recover to about 777,000 units in FY2026, led by rental housing.
Construction Type Analysis
New Construction led the Construction Type segment with a 78.78% share in 2026, worth USD 440.31 Billion.
New construction dominates because of urban redevelopment, factory building and transport projects. MLIT expects building investment of ¥52.95 trillion and civil engineering investment of ¥28.52 trillion in FY2026, and most of both is new work.
Renovation is the fastest-growing construction type, at an estimated 7.6% CAGR. MLIT expects renovation investment of ¥17.29 trillion in FY2026, or 21.2% of the total, with ¥14.59 trillion of it private. RICE estimates that private renovation rose 8.6% in FY2025, helped by government energy-saving housing subsidies and a shift from rebuilding to large-scale refurbishment. Earthquake-safety upgrades, energy upgrades and conversions of buildings to new uses are the main sources of demand.
Construction Method Analysis
Conventional On-Site construction led the Construction Method segment with an estimated 68.45% share in 2026.
Traditional on-site building remains the main method for most projects. Contractors, suppliers and clients are used to it, and equipment suppliers still design their products around on-site work. However, its dominance is weakening. Rising labour costs and scheduling risk are forcing project owners to rethink the cost of building on site.
Modern Methods of Construction, which include prefabricated and modular building, are the fastest-growing method at an estimated 8.9% CAGR. Japan already has a strong base here, because large housebuilders such as Sekisui House and Daiwa House Industry build many homes from factory-made parts. Contractors are investing in factory-built panels and room-sized modules. These cut the number of workers needed on site and shorten build times. Early adopters gain more predictable margins, while firms slow to change their supply chains lose out.
Investment Source Analysis
Private led the Investment Source segment with a 67.35% share in 2026, worth USD 376.43 Billion.
MLIT expects private construction investment to rise 4.1% to ¥54.87 trillion in FY2026, after an estimated 7.9% rise in FY2025. Within this:
- Private housing: ¥18.02 trillion.
- Private non-residential construction: ¥22.26 trillion.
- Private renovation: ¥14.59 trillion.
Private is also the faster-growing source, at an estimated 7.22% CAGR, driven by industrial investment and strong corporate profits.
Public investment holds 32.65% and is expected to grow more steadily, at a 5.9% CAGR. MLIT expects government investment of ¥26.60 trillion in FY2026, up 0.6%. The national resilience plan provides a reliable base of public work. However, growth is limited by Japan’s high government debt and the need to manage public budgets.
Key Market Segments
By Sector
- Residential
- Apartments/Condominiums
- Villas/Landed Houses
- Commercial
- Office
- Retail
- Industrial and Logistics
- Others
- Infrastructure
- Transportation Infrastructure (Roadways, Railways, Airways, Others)
- Energy & Utilities
- Others
By Construction Type
- New Construction
- Renovation
By Construction Method
- Conventional On-Site
- Modern Methods of Construction (Prefabricated, Modular, etc.)
By Investment Source
- Private
- Public
Regional Analysis
| Region | 2026 Share | 2026 Value (USD Bn) | 2035 Value (USD Bn) | CAGR 2026–2035 |
|---|---|---|---|---|
| Kanto (Tokyo) | 37.44% | 209.26 | 376.92 | 6.76% |
| Kansai (Osaka) | 14.60% | 81.60 | 150.02 | 7.00% |
| Chubu (Nagoya) | 13.20% | 73.78 | 136.78 | 7.10% |
| Tohoku | 7.40% | 41.36 | 69.28 | 5.90% |
| Hokkaido | 4.60% | 25.71 | 55.38 | 8.90% |
| Rest of Japan | 22.76% | 127.20 | 222.33 | 6.40% |
| Total | 100% | 558.91 | 1,010.71 | 6.80% |
Note: Shares other than Kanto’s, and all CAGRs, are Market.us estimates. Rest of Japan includes Kyushu-Okinawa, Chugoku, Shikoku and Hokuriku.
Kanto (Tokyo)
Kanto led the regional segment with a 37.44% share in 2026, worth USD 209.26 Billion.
Kanto is Japan’s largest construction market because of Tokyo’s constant redevelopment and the concentration of commercial, transport and housing investment in the capital region. Office tower rebuilding, developments around railway stations and large mixed-use projects keep contractors busy for years at a time. High land values, corporate head offices and a dense population make high-rise construction worthwhile. Kanto also attracts data centre investment, such as Mitsui & Co.’s ¥18 billion hyperscale data centre project in Kanagawa Prefecture.
Hokkaido
Hokkaido is the fastest-growing region, at an estimated 8.9% CAGR. Its main driver is Rapidus, which is building a next-generation semiconductor plant in Chitose. Rapidus started a pilot line in April 2025 and plans mass production of 2-nanometre chips in 2027. In February 2026, it received another ¥267.6 billion in funding: ¥100 billion from the government and ¥167.6 billion from 32 companies, including Sony, SoftBank, Honda and Fujitsu.
Housing, roads, utilities and supplier facilities around the plant add more construction demand. Tourism facilities, renewable energy projects and programmes to protect cold-climate infrastructure add to growth.
Tohoku
Tohoku’s construction is shaped by long-term rebuilding after the 2011 earthquake and ongoing investment to protect coastal and inland infrastructure. Government civil engineering spending is the main source of work. Population decline limits private housing demand, so more of the region’s construction comes from public infrastructure. This explains its slower estimated CAGR of 5.9%.
Chubu (Nagoya)
Chubu benefits from Japan’s largest concentration of car and advanced manufacturing companies, which creates steady demand for factories and logistics buildings. DENSO’s Zenmyo Plant project, worth about ¥69 billion, and Nitto Denko’s ¥39 billion new factory at its Toyohashi Plant show the scale of industrial investment in the region. Nagoya’s central transport links also support logistics and e-commerce warehouse development.
Kansai (Osaka)
Kansai is investing in urban renewal and hotels as tourism grows. Osaka’s pipeline includes mixed-use redevelopment and hotel expansion. Kansai competes with Kanto for corporate tenants, which makes it Japan’s second major urban construction hub. This helps large contractors spread their work across more than one region.
Rest of Japan
The rest of Japan, including Kyushu-Okinawa, Chugoku, Shikoku and Hokuriku, makes up an estimated 22.76% of the market. Semiconductor investment is a major driver. In July 2026, Micron broke ground on a ¥1.5 trillion high-bandwidth memory (HBM) plant in Hiroshima, supported by up to ¥536 billion in government subsidies. Public spending on disaster resilience and regional transport links adds a stable base of work. Wind and solar projects add a growing private layer that reduces dependence on government budgets.
Macroeconomic Impact
Construction is a large part of Japan’s economy. Few advanced economies spend as much on construction relative to their size. Steady public spending on infrastructure and earthquake safety protects the sector from mild downturns. However, the sector depends on government budgets, and Japan’s high public debt could limit future spending growth.
The weak yen is a major factor. At about ¥156–158 per USD in September 2026, it raises the cost of imported materials and specialist equipment. This pushes up project budgets and squeezes contractors’ margins on fixed-price contracts. At the same time, Japanese companies are spending more on factories abroad, such as Panasonic Industry’s planned ¥7.5 billion circuit-board materials line in Guangzhou, China. This means domestic construction competes with overseas expansion for corporate investment.
Market Dynamics
Driver: Public Works, Disaster Resilience and Industrial Investment
The First National Resilience Mid-term Implementation Plan, approved by the Cabinet on 6 June 2025, sets out more than ¥20 trillion of priority projects for FY2026–FY2030. This puts long-term disaster resilience spending on a legal footing for the first time, rather than relying on short-term emergency packages. MLIT expects government civil engineering investment of ¥18.58 trillion in FY2026. Earthquake-safety rules in Japan’s building codes also create steady upgrade demand that does not depend on the economic cycle.
Private industrial investment adds a second driver. Semiconductor plants such as Rapidus in Hokkaido and Micron in Hiroshima, along with data centres and battery and parts factories, are lifting private non-residential construction. MLIT expects it to grow 6.6% to ¥22.26 trillion in FY2026. Automation and site robots are also becoming commercially viable, which reduces dependence on skilled workers who are in short supply.
Restraint: Labour Shortages and Rising Costs Limit Capacity
Japan had 4.78 million construction workers in 2025, about 30% fewer than at the 1997 peak of 6.85 million. About 37% are aged 55 or over and only about 12% are 29 or younger, so many workers will retire within the next ten years. Overtime limits for construction work, introduced in April 2024, further reduce available working hours. Skilled workers in concrete, steel and mechanical systems are now the main limit on how much can be built, more than money.
Contractors are turning down work they cannot staff, and subcontractor prices are rising. Steel, concrete and glass prices remain well above pre-2020 levels, which reduces margins on fixed-price contracts, especially for mid-sized contractors. Shipping costs and logistics bottlenecks in remote prefectures add to delivery times and schedule risk.
Opportunity: Data Centres, Semiconductor Plants and Building Conversions
Digital infrastructure, including data centres and semiconductor plants, is the fastest-growing type of private non-residential construction. In March 2025, Mitsui & Co. took a 50% stake in a hyperscale data centre project in Kanagawa Prefecture and invested ¥18 billion. RICE expects private non-residential construction to reach ¥24.10 trillion in FY2027, about 28% of all construction investment.
Converting offices to homes is also gaining ground in central Tokyo and Osaka, where office vacancy is rising and land for new housing is scarce. Both trends create more work for contractors with specialist fit-out and structural conversion skills.
Analyst insight: “The resilience plan is large but not unlimited. More than ¥20 trillion over five years equals about ¥4 trillion a year, or roughly 15% of FY2026 government construction investment of ¥26.60 trillion. That gives public works a stable floor, but not a growth engine. The real growth is private: MLIT expects private non-residential construction to rise 6.6% in FY2026, against 0.6% for government investment. That’s why we expect Commercial (7.9% CAGR) to outgrow Infrastructure (6.79%), even though Infrastructure remains the largest sector.”
— Research Team, Market.us
Porter’s Five Forces
| Force | Level | Explanation |
|---|---|---|
| Threat of new entrants | Low | Licensing rules, relationship-based contracts, and the capital needed for bonds and equipment create strong barriers |
| Supplier power | High | Equipment suppliers and specialist subcontractors hold strong power, especially in robotics, prefabrication and digital surveying, where alternatives are few |
| Buyer power | Varies | Large developers and government agencies negotiate multi-year agreements from a strong position, while smaller clients have little influence over prices |
| Threat of substitutes | Low | Modular parts made overseas carry logistics risks that remove most of their cost advantage in Japan |
| Competitive rivalry | Moderate | The top five contractors form an oligopoly over major projects. Pricing power sits at the top, and margin pressure builds at the subcontractor level |
AI and Gen AI Impact
Artificial intelligence (AI) is entering Japan’s construction industry first in project management and structural design, not on the building site. Construction technology vendors use generative AI to quickly produce building layouts that meet code, model earthquake loads and optimise construction schedules. For repetitive building types, these tools cut design time from months to weeks. Contractors using AI-based project controls spot schedule risks earlier and move workers between sites more efficiently.
On site, automation using computer vision and AI-linked robots is advancing fastest on repetitive tasks such as placing rebar, pouring concrete and finishing work. Firms that adopted these systems early report fewer workers needed per project. Laggards risk losing contracts, as clients start requiring AI-enabled methods in tenders. This is especially true for public infrastructure projects with government productivity targets.
Market Trends
Renovation and Digital Tools Reshape Contractor Strategy
Renovation is growing faster than new construction as Japan’s buildings age. MLIT expects renovation investment of ¥17.29 trillion in FY2026, and RICE expects private renovation to reach ¥14.22 trillion. Contractors are investing in skills for structural retrofits and energy upgrades.
Building information modelling (BIM), which creates digital 3D models of buildings, is the backbone of this shift, together with connected site equipment and automated project controls. Early adopters charge premium fees on complex retrofit projects that traditional methods cannot deliver within budget and schedule.
Record Profits Despite Flat Sales
Japan’s largest contractors posted record or near-record profits in the year ended March 2026, even though some saw sales fall. Better pricing on new contracts and fewer loss-making legacy projects lifted margins. For example, Taisei’s non-consolidated building construction margin rose from 4.4% to 11.9%. This shows that labour scarcity is giving top contractors stronger pricing power.
Market Competition Overview
Japan’s construction market is an oligopoly at the top and fragmented below. The five major contractors (Obayashi, Kajima, Shimizu, Taisei and Takenaka) dominate large public and commercial projects. Their advantages are long-standing client relationships, financial strength and technical credentials that mid-sized firms cannot quickly match.
Below them, regional contractors and specialist subcontractors are merging to cope with labour costs and rising prices. Acquisitions are bringing technical skills and regional reach together among mid-sized firms willing to invest in digital tools and factory-built construction. Firms that cannot offer BIM-based project management or prefabrication are losing public tenders, as productivity benchmarks increasingly become contract requirements.
Analyst insight: “Housebuilding and factory building are moving in opposite directions. New housing starts fell 12.9% to 711,171 units in FY2025, the second-lowest level since FY1962. Meanwhile, MLIT expects private non-residential construction to rise 6.6% to ¥22.26 trillion in FY2026. Contractors that depend on housing volume face a shrinking market. Those with industrial, data centre and semiconductor experience are gaining share. We expect this divide to shape consolidation among mid-sized contractors through 2035.”
— Research Team, Market.us
Competitive Benchmarking
| Company | Net Sales (¥bn) | Change | Operating Income (¥bn) | Change | Net Income (¥bn) | Data As Of |
|---|---|---|---|---|---|---|
| Kajima Corporation | 3,067.2 | +5.3% | 240.7 | +58.5% | 177.3 | FY ended 31 Mar 2026 |
| Obayashi Corporation | 2,586.2 | −0.2% | 194.6 | +36.6% | 173.7 | FY ended 31 Mar 2026 |
| Taisei Corporation | 2,089.0 | −3.0% | 187.9 | +56.4% | 170.0 | FY ended 31 Mar 2026 |
| Shimizu Corporation | 2,057.8 | +5.8% | 118.6 | +67.1% | 126.6 | FY ended 31 Mar 2026 |
Note: Takenaka Corporation is privately held and is not included in this comparison.
Company Profiles
Obayashi Corporation
Obayashi Corporation reported consolidated net sales of ¥2,586.2 billion for the fiscal year ended 31 March 2026, down 0.2%. Domestic building sales fell after large projects were completed in the previous year. Operating profit rose 36.6% to ¥194.6 billion, and net income rose 19.5% to ¥173.7 billion, helped by strong overseas building and civil engineering work in Japan and abroad. Orders fell 9.3% to ¥3,009.0 billion after an exceptionally strong prior year. Obayashi’s balance of domestic and overseas civil engineering work protects it from weakness in any single segment.
Kajima Corporation
Kajima Corporation posted record results for the fiscal year ended 31 March 2026. Revenues rose 5.3% to ¥3,067.2 billion, and operating income rose 58.5% to ¥240.7 billion, thanks to better gross margins in construction. Net income reached a record ¥177.3 billion. Kajima’s order backlog grew both in Japan and overseas.
Taisei Corporation
Taisei Corporation achieved record profits at every level in the fiscal year ended 31 March 2026. Net sales fell 3.0% to ¥2,089.0 billion, but operating income rose 56.4% to ¥187.9 billion. Its non-consolidated building construction margin improved from 4.4% to 11.9%. Taisei expects net sales to rise to ¥2,420.0 billion in the fiscal year ending March 2027, with operating income steady at ¥188.0 billion.
Shimizu Corporation
Shimizu Corporation’s net sales rose 5.8% to ¥2,057.8 billion in the fiscal year ended 31 March 2026. Operating income rose 67.1% to ¥118.6 billion, and net income nearly doubled, up 91.8% to ¥126.6 billion. Higher margins on construction contracts drove the improvement.
Key Players
- Obayashi Corporation
- Kajima Corporation
- Shimizu Corporation
- Taisei Corporation
- Takenaka Corporation
- Sumitomo Mitsui Construction
- Maeda Corporation
- Penta-Ocean Construction
- Kumagai Gumi
- Hazama Ando Corporation
- Toda Corporation
- Daiwa House Industry
- Sekisui House
- Tokyu Construction
- Mori Building
- Zenitaka Corporation
- Nippon Concrete Industries
- Takada Corporation
- Mitsubishi Heavy Industries (Infrastructure & Plant)
- Toshiba Infrastructure Systems
Pricing Analysis
Construction prices in Japan have a firm floor set by labour shortages and material inflation, and there is no sign of a return to pre-2020 levels. RICE’s forecast shows the gap: 6.3% nominal growth against 2.4% real growth in FY2026. Wages for skilled trades keep rising as more workers retire than new apprentices join. Specialist subcontractors in earthquake engineering, mechanical systems and digital surveying charge premium rates that are now built into project budgets.
Regional price differences are large. Kanto projects have the highest cost per square metre for every building type, because of site setup costs, complex logistics and high subcontractor rates in Tokyo. Remote prefectures have lower labour and land costs but pay more to transport materials and specialist equipment. Contractors working across regions manage these differences through standard procurement frameworks rather than project-by-project negotiation.
Supply Chain and Value Chain Analysis
The value chain runs from material producers and equipment makers through general contractors, specialist subcontractors and fit-out trades to building owners and users. Most value sits with general contractors, who combine project management, design coordination and contract risk. Steel and cement producers work under long-term supply contracts. These soften short-term price swings but include price escalation clauses that feed into project budgets with a delay.
The biggest bottleneck is skilled subcontractor capacity. General contractors can win orders faster than subcontractors can staff them. Factory-built component suppliers offer relief, but their capacity is growing more slowly than contractor orders. Imports of prefabricated parts from Southeast Asia and China are rising, which adds quality certification and delivery-time risks.
Regulatory Landscape
- Building Standards Act: Japan’s Building Standards Act governs structural design for all new buildings. Earthquake-safety requirements are updated after major earthquakes. New buildings and structural changes to existing buildings must meet the latest standards, which creates steady renovation demand regardless of the economic cycle. Revisions to the Building Standards Act and the building energy-efficiency rules took effect in April 2025. Contractors now face stricter structural checks for small buildings and mandatory energy-efficiency standards for all new buildings.
- Public works procurement: MLIT sets procurement standards for public works, including productivity targets. These increasingly require contractors to show BIM adoption and digital delivery skills.
- Labour rules: Overtime limits for construction work took effect in April 2024. They reduce available working hours and push contractors towards productivity tools and better scheduling.
- National resilience: The First National Resilience Mid-term Implementation Plan, approved on 6 June 2025, sets out more than ¥20 trillion of priority projects for FY2026–FY2030. It focuses on disaster prevention and the renewal of ageing infrastructure.
- Environmental rules: Japan’s 2050 carbon-neutrality goal has introduced energy performance standards for buildings and is speeding the phase-out of high-emission heating and cooling systems in public buildings. Contractors with green-building expertise benefit, while firms that have not invested in low-carbon materials and methods fall behind.
Investment and White Space Analysis
Investment is concentrated in two areas:
- Digital infrastructure: Data centres and semiconductor plants.
- Government civil engineering: Disaster resilience and transport programmes backed by the ¥20 trillion+ national resilience plan.
Both offer several years of visibility and are less volatile than housing. Contractors with civil engineering capability and earthquake-engineering credentials are best placed to win this work.
The main white space is in energy and decarbonisation upgrades for Japan’s ageing commercial and public buildings. This segment is growing but remains fragmented. Few contractors have built a repeatable model that combines earthquake strengthening and energy upgrades in a single project. The first firm to standardise this combined offering at competitive cost will capture a large, underserved part of the renovation market that no incumbent currently dominates.
Analyst View
- Japan’s construction market is at a 30-year high in nominal terms, but about 60% of FY2026 growth comes from higher prices rather than more building.
- Labour is the main constraint. With 4.78 million workers and about 37% aged 55 or over, capacity cannot grow quickly, which supports pricing power for top contractors.
- Commercial construction (7.9% CAGR), driven by semiconductor plants and data centres, will outgrow infrastructure and housing.
- Hokkaido (8.9% CAGR) and semiconductor-linked regions offer the strongest regional growth, led by Rapidus in Chitose and Micron in Hiroshima.
- The national resilience plan gives public works a stable floor of about ¥4 trillion a year, but private investment will drive most of the growth.
Report Scope
| Report Characteristics | Details |
|---|---|
| Market Value (2026) | USD 558.91 Billion |
| Forecast Revenue (2035) | USD 1,010.71 Billion |
| CAGR (2026 to 2035) | 6.8% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020 to 2024 |
| Forecast Period | 2026 to 2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Sector (Residential, Commercial, Infrastructure), By Construction Type (New Construction, Renovation), By Construction Method (Conventional On-Site, Modern Methods of Construction), By Investment Source (Public, Private) |
| Regions Covered | Kanto, Kansai, Chubu, Tohoku, Hokkaido, Rest of Japan |
| Competitive Landscape | Obayashi Corporation, Kajima Corporation, Shimizu Corporation, Taisei Corporation, Takenaka Corporation, Sumitomo Mitsui Construction, Maeda Corporation, Penta-Ocean Construction, Kumagai Gumi, Hazama Ando Corporation, Toda Corporation, Daiwa House Industry, Sekisui House, Tokyu Construction, Mori Building, Zenitaka Corporation, Nippon Concrete Industries, Takada Corporation, Mitsubishi Heavy Industries (Infrastructure & Plant), Toshiba Infrastructure Systems |
| Customization Scope | Customization for segments and region or country level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | Three license options: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited Users and Printable PDF) |
Recent Developments
- 31 August 2026: MLIT published its FY2026 construction investment outlook. It forecasts ¥81.47 trillion, up 2.9%, with private investment of ¥54.87 trillion and government investment of ¥26.60 trillion.
- 27 July 2026: RICE forecast FY2026 construction investment of ¥83.26 trillion (+6.3%) and FY2027 investment of ¥86.35 trillion. The FY2027 figure would be the highest ever.
- 4 July 2026: Micron broke ground on a ¥1.5 trillion HBM memory plant in Hiroshima, supported by government subsidies of up to ¥536 billion.
- 27 February 2026: Rapidus received ¥267.6 billion in new funding (¥100 billion from the government and ¥167.6 billion from 32 companies) for its semiconductor plant in Chitose, Hokkaido.
- December 2025: Nitto Denko announced a new factory at its Toyohashi Plant with investment of about ¥39 billion. Completion is scheduled for January 2028.
- October 2025: Toshiba Energy Systems & Solutions raised its total investment to ¥55 billion, adding ¥35 billion to an earlier ¥20 billion programme. The aim is to more than double its transmission and distribution equipment capacity in Japan and India by FY2030, with facilities in Hamakawasaki, Japan and Hyderabad, India.
- September 2025: Takenaka Corporation, Hyatt and Kiraku announced the final close of a ¥22 billion real estate fund.
- 6 June 2025: The Cabinet approved the First National Resilience Mid-term Implementation Plan, with more than ¥20 trillion of priority projects for FY2026–FY2030.
- March 2025: Mitsui & Co. took a 50% stake in, and invested ¥18 billion in, a hyperscale data centre project in Kanagawa Prefecture.
- September 2024: DENSO announced its new Zenmyo Plant project with total investment of about ¥69 billion. Construction was planned to start in FY2025 and production in FY2028.
- August 2024: Bridgestone announced a ¥25 billion equipment upgrade at its Kitakyushu Plant, which makes tyres for mining and construction vehicles. Completion is targeted for the end of 2027.








