


Report Overview
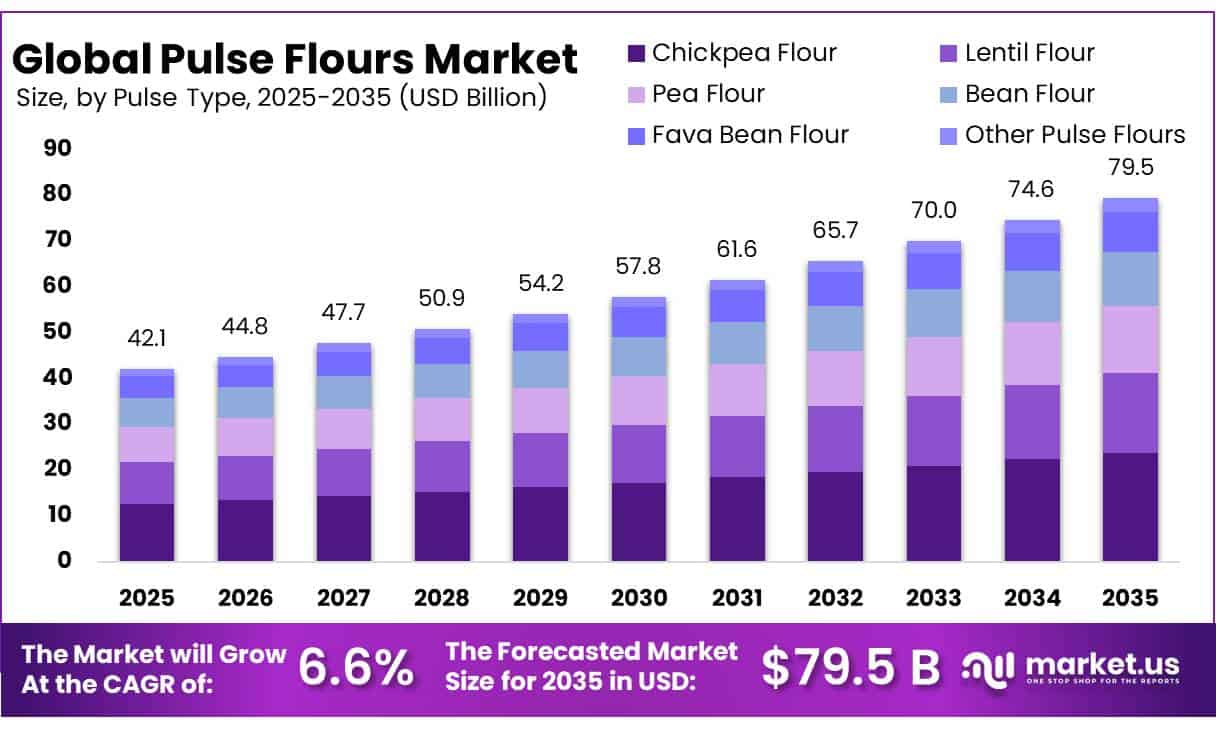
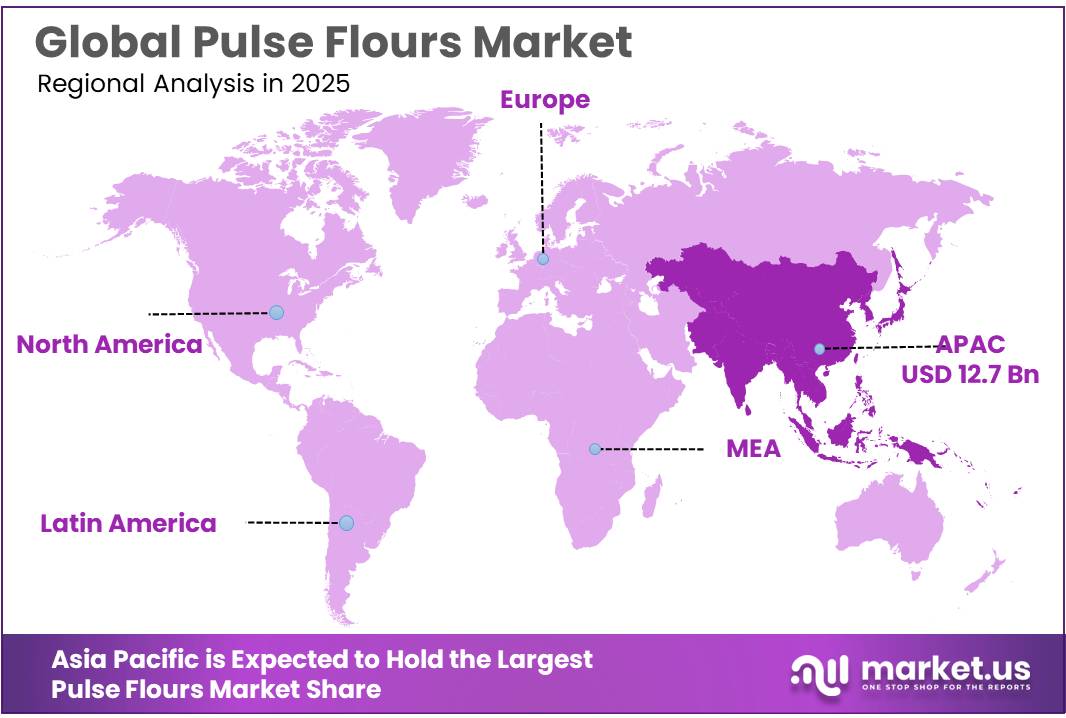
The Global Pulse Flours Market size is expected to be worth around USD 79.5 Billion by 2035, from USD 42.1 Billion in 2025, growing at a CAGR of 6.6% during the forecast period from 2026 to 2035. In 2025, Asia Pacific held a dominant market position, capturing more than a 30.00% share, holding USD 12.7 Billion revenue.
Pulse flours are gaining importance in the global food ingredients industry as manufacturers increasingly focus on plant-based nutrition, protein enrichment, dietary fibre, and clean-label food formulations. Pulse flours are produced by milling dried legumes such as peas, lentils, chickpeas, and beans into fine powders, either with their outer seed coats or after dehulling.
- The industrial scenario for pulse flours is supported by increasing agricultural production, expanding ingredient-processing capabilities, and investment in plant-protein development. According to Statistics Canada data published in February 2026, Canada produced 3.9 million tonnes of dry peas, 3.4 million tonnes of lentils, and approximately 481,589 tonnes of chickpeas in 2025.
Lentil production increased by 38.3%, while chickpea production increased by 31.3% compared with the previous year. These production levels provide an important raw-material base for milling companies and food ingredient manufacturers. Furthermore, Canadian farmers received more than USD 3 billion equivalent in Canadian-dollar pulse crop receipts during 2024, demonstrating the economic importance of the sector.
The growing availability of pulse-based raw materials is encouraging manufacturers to develop value-added ingredients through advanced milling, dehulling, air classification, and wet fractionation. Pulse Canada reports that air classification can increase protein concentration to approximately 24%–58% in pea and lentil fractions, while certain faba bean fractions can reach 31%–70% protein.
According to Pulse Canada’s application research, pulse flour can be incorporated into leavened bread at approximately 10%–15%, while certain flatbread and cracker applications can support substantially higher replacement levels. The association also reports that incorporating 30% pulse flour into biscuits and crackers can double their fibre levels. These formulation benefits are encouraging their use across bakery, snacks, pasta, and alternative protein products. Source: Pulse Canada.
Government initiatives are also supporting the wider development of plant-protein supply chains. In July 2026, the European Commission introduced its Protein Action Plan to strengthen European protein production, improve supply-chain resilience, and support sustainable agriculture.
The European Union produces approximately 67 million tonnes of plant-based protein annually from arable and fodder crops, while its livestock sector uses around 74 million tonnes of protein as animal feed each year. The initiative aims to increase the share of protein from domestically produced oilseeds and protein crops used in animal feed from 25.8% to 35% by 2035.
Key Takeaways
- Pulse Flours Market size is expected to be worth around USD 79.5 Billion by 2035, from USD 42.1 Billion in 2025, growing at a CAGR of 6.6%.
- Chickpea Flour held a dominant market position, capturing more than a 30.00% share.
- Conventional held a dominant market position, capturing more than an 82.00% share of the Pulse Flours Market.
- Dry Milling held a dominant market position, capturing more than a 72.00% share of the Pulse Flours Market.
- Bakery and Confectionery held a dominant market position, capturing more than a 25.00% share.
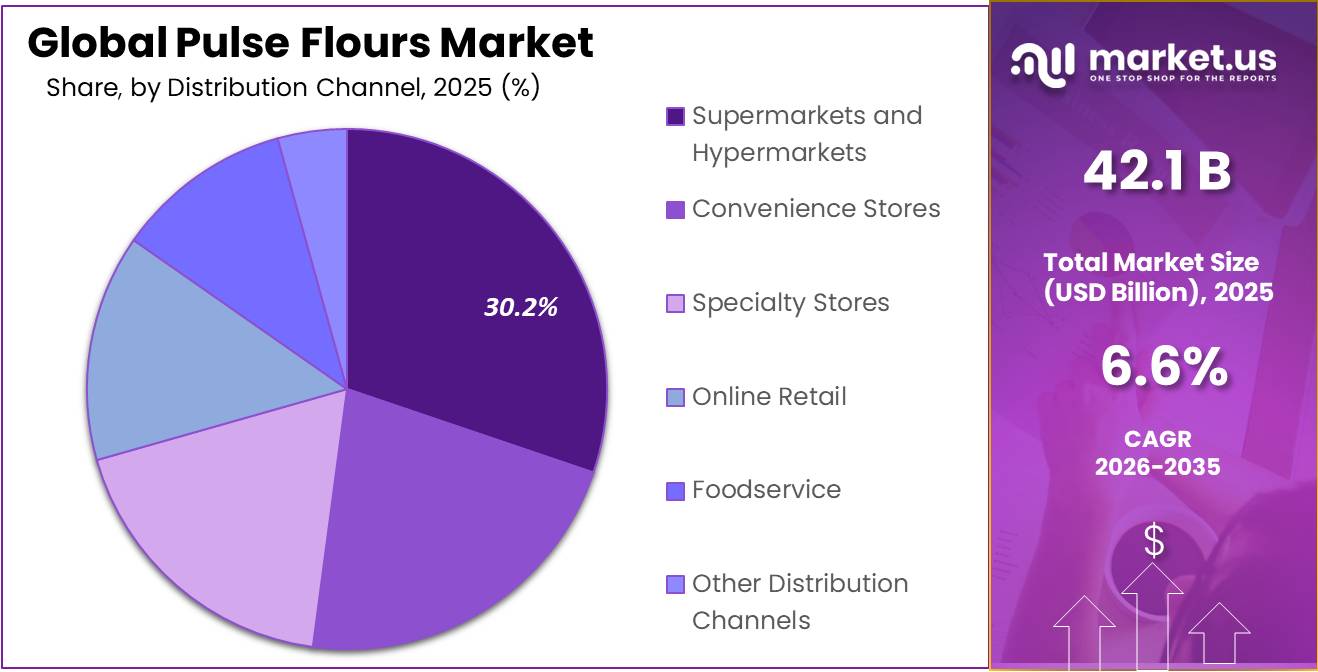
- Supermarkets and Hypermarkets held a dominant market position, capturing more than a 30.00% share.
- Asia Pacific dominated the Pulse Flours Market in 2025, accounting for 30.00% of the global market, with a reported market value of USD 12.7 billion.
By Pulse Type Analysis
Chickpea Flour maintains a strong position due to its nutritional value, gluten-free properties, and wide use in bakery and snack products.
In 2025, “Chickpea Flour” held a dominant market position, capturing more than a 30.00% share of the Pulse Flours Market by pulse type. Its position is supported by its high protein and dietary fibre content, making it a suitable ingredient for manufacturers developing nutritious and gluten-free food products. Chickpea flour is widely used in bread, biscuits, pasta, noodles, snacks, and traditional food preparations. Its ability to improve nutritional content while providing binding and thickening properties also supports its use in processed food formulations.
Lentil flour is gaining attention among food manufacturers due to its nutritional benefits and suitability for bakery products, pasta, snacks, noodles, and gluten-free food formulations. Its plant-based protein and dietary fibre content make it a useful ingredient for improving the nutritional profile of processed foods. In 2025, the availability of lentils supported ingredient processing and commercial applications.
According to the Government of Canada, western Canadian lentil production reached approximately 3.4 million tonnes in 2025, representing a 38.2% increase compared with 2024. Saskatchewan contributed 86.2% of western Canadian production, highlighting its importance as a raw-material supply region.
By Nature Analysis
Conventional pulse flours dominate due to established agricultural supply chains, wider availability, and cost-effective food processing applications.
In 2025, “Conventional” held a dominant market position, capturing more than an 82.00% share of the Pulse Flours Market by nature. Conventional pulse flours benefit from established cultivation, large-scale milling facilities, and consistent raw-material availability. Their relatively accessible pricing makes them suitable for food manufacturers producing bakery products, pasta, noodles, snacks, and other processed foods. Conventional varieties also offer flexibility in blending with wheat and other cereal flours, supporting their use across different food applications.
Organic pulse flour is attracting attention from food manufacturers seeking ingredients produced without synthetic pesticides and prohibited chemical fertilisers. Organic chickpea, lentil, and pea flours are increasingly relevant to premium bakery products, gluten-free foods, nutritional snacks, and plant-based formulations. Their appeal is supported by consumer interest in ingredient transparency, sustainable agriculture, and naturally sourced food products.
In 2025, the United States Department of Agriculture (USDA) conducted its Certified Organic Survey to collect information on organic crop acreage, production, sales, and farming practices. The survey provides an official statistical framework for assessing the development of certified organic agriculture and its supply chains. Organic pulse flour producers can benefit from expanding certified cultivation, specialised processing, and demand from premium food manufacturers.
By Processing Method Analysis
Dry milling dominates due to its simpler processing requirements, lower water consumption, and suitability for large-scale flour production.
In 2025, “Dry Milling” held a dominant market position, capturing more than a 72.00% share of the Pulse Flours Market by processing method. This method is widely preferred because it converts cleaned and dried pulses into flour through mechanical grinding without requiring extensive water-based processing. It allows manufacturers to process chickpeas, lentils, peas, and other pulses using established milling equipment. Dry milling also supports different particle sizes and flour textures, making it suitable for bakery products, snacks, pasta, and gluten-free food formulations.
Wet milling is used in pulse processing to separate and refine different components of pulses through water-based operations. The method helps manufacturers develop specialised ingredients with improved functional characteristics for bakery products, beverages, nutritional formulations, and plant-based food applications. It also supports the production of protein-rich fractions and starch-based ingredients that can be used in different food formulations.
By Application Analysis
Bakery and confectionery dominate due to the growing use of pulse flours in nutritious, gluten-free, and protein-enriched baked products.
In 2025, “Bakery and Confectionery” held a dominant market position, capturing more than a 25.00% share of the Pulse Flours Market by application. Pulse flours are increasingly used in bread, biscuits, cookies, cakes, crackers, and other bakery products to improve their protein and dietary fibre content. Chickpea, lentil, and pea flours are particularly useful because they can be blended with conventional cereal flours to improve nutritional value and product texture. Their binding and water-absorption properties also support different bakery formulations.
Snacks and savory products represent an important application area for pulse flours as manufacturers increasingly incorporate chickpea, lentil, and pea flour into chips, crackers, extruded snacks, savoury biscuits, and snack coatings. These ingredients help improve protein and dietary fibre content while providing texture and binding properties. In 2025, food processors continued to explore pulse-based formulations to diversify conventional snack products and meet demand for plant-based ingredients.
According to the U.S. Census Bureau’s 2024 Annual Integrated Economic Survey, US manufacturers in the other snack food manufacturing category recorded USD 37.42 billion in sales and shipments. This demonstrates the substantial industrial base available for ingredient suppliers targeting snack manufacturers. The growing focus on nutritional enrichment and product innovation provides further opportunities for pulse flour adoption in savoury snack applications.
By Distribution Channel Analysis
Supermarkets and hypermarkets dominate through wider product availability, organised retail networks, and easy access to packaged pulse flour products.
In 2025, “Supermarkets and Hypermarkets” held a dominant market position, capturing more than a 30.00% share of the Pulse Flours Market by distribution channel. These retail outlets provide consumers with access to different varieties of pulse flours, including chickpea, lentil, and pea flour, under multiple food and private-label brands. Their organised shelf arrangements, product comparisons, promotional offers, and established distribution networks support regular purchases.
According to the USDA Economic Research Service, grocery stores accounted for 56.2% of US food-at-home spending in 2025, while warehouse clubs and supercenters accounted for 26.4%. This highlights the importance of organised grocery retail outlets in food distribution and provides a supportive retail environment for packaged pulse flour products.
Key Market Segments
By Pulse Type
- Chickpea Flour
- Lentil Flour
- Pea Flour
- Bean Flour
- Fava Bean Flour
- Other Pulse Flours
By Nature
- Conventional
- Organic
By Processing Method
- Dry Milling
- Wet Milling
By Application
- Bakery and Confectionery
- Snacks and Savory Products
- Pasta and Noodles
- Soups and Sauces
- Meat Alternatives
- Infant Nutrition
- Other Applications
By Distribution Channel
- Supermarkets and Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Retail
- Foodservice
- Other Distribution Channels
Driver Analysis
Peptide-Based Medical Nutrition
Demand for peptide-based medical nutrition supports protein hydrolysates where patients require formulations designed for impaired digestion or absorption, while improvements in taste and concentration make these ingredients more practical for repeat use. Arla Foods Ingredients launched Lacprodan DI-3092 in November 2024 with a stated degree of hydrolysis of 16–22%, low lactose content and compatibility with direct and indirect UHT treatment; its application prototypes provide 10 g protein per 100 mL with low viscosity and reduced bitterness.
These are product-specific formulation capabilities, not proof that hydrolysates are preferable to intact proteins for every patient or a quantified market-wide shift. Nestlé’s Peptamen portfolio provides an established commercial example using hydrolysed whey as its protein source, including paediatric products intended for children aged 1–13 years with impaired gastrointestinal function; finished formula revenue is not counted as ingredient-market revenue. Under an illustrative procurement program, 100,000 patients consuming 20 g of hydrolysate-derived protein daily for 180 days require 360 tonnes of protein; at an assumed 90% protein content, ingredient demand is 400 tonnes.
This is a volume sensitivity, not a dosing recommendation or patient-population estimate. Suppliers capture value through validated specifications, sensory performance and long-term formula qualification rather than commodity protein sales alone. The +1.0 pp contribution assumes 20% of addressable revenue grows 5 percentage points faster than the underlying case, counting appropriate medical applications while excluding intact whey, beta-lactoglobulin and unrelated high-protein products.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Peptide-based medical nutrition | +1.0 pp | North America, EU, Japan | Short term (≤ 2 years) |
| Qualified infant-formula expansion | +0.8 pp | EU core; export-formula markets | Medium term (2–4 years) |
| Evidence-backed collagen adoption | +0.8 pp | North America, EU, East Asia | Short term (≤ 2 years) |
| Specialized sports formulations | +0.7 pp | US, EU, Brazil, APAC | Short term (≤ 2 years) |
| Functional aquafeed inclusion | +0.5 pp | China, Southeast Asia, Norway, Chile | Medium term (2–4 years) |
Restraint Analysis
Processing-Cost Premium
Protein hydrolysates incur additional conversion costs beyond the underlying protein feedstock because controlled enzymatic treatment can require reaction time, enzyme inactivation, fractionation, concentration and drying, with further expenditure where customers demand narrowly specified peptide fractions. A January 2026 enzyme-technology review identifies expensive enzyme preparations and downstream separation as barriers to industrial commercialization, noting that membrane separation, adsorption and chromatography can have limited throughput or selectivity; these findings do not establish one production-cost premium applicable to all hydrolysates.
Upstream conditions add pressure selectively: FAO reported September 2026 skim-milk-powder quotations 33.1% above their year-earlier level, while cheese and butter prices were substantially lower, demonstrating that a broad dairy index is not an adequate proxy for every protein feedstock. Skim milk powder is also not interchangeable with whey concentrate or collagen raw material. Under an illustrative plant model, 1,000 kg of protein solids yielding 850 kg of saleable hydrolysate produces $4.71/kg of feedstock cost when input solids cost $4/kg; an additional assumed $2/kg of processing produces $6.71/kg before overhead.
If saleable recovery falls to 750 kg with the same total batch expenditure, unit cost rises to approximately $7.60/kg, or 13.3%. These are sensitivity inputs, not commercial quotations. Suppliers must therefore align hydrolysis intensity and purification with customer specifications rather than over-process material without a recoverable premium. The −0.5 pp deduction assumes 25% of addressable revenue grows 2 percentage points more slowly because conversion economics prevent otherwise viable orders; routine process optimization without a lost sale belongs in a separate challenges analysis.
Restraint Impact Analysis
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Processing-cost premium | −0.5 pp | EU, US, China, India | Short term (≤ 2 years) |
| Bitterness-driven rejection | −0.4 pp | North America, EU, East Asia | Medium term (2–4 years) |
| Formula qualification barriers | −0.4 pp | EU core; export-formula suppliers | Medium term (2–4 years) |
| Residual allergen restrictions | −0.3 pp | US, EU, UK | Long term (≥ 4 years) |
| Intact-protein substitution | −0.3 pp | US, EU, Brazil, APAC | Short term (≤ 2 years) |
Opportunity Analysis
Characterized Plant-Peptide Platforms
Developing reproducibly characterized plant-protein hydrolysates offers an opportunity to move from generic protein procurement into ingredient platforms supported by defined composition, application evidence and customer-specific qualification. FDA’s GRAS Notice 1166 provides a concrete regulatory precedent: the agency closed the notice for a particular fava-bean protein hydrolysate on 13 November 2024 with a “no questions” letter concerning the notifier’s conclusion, covering intended uses at 2.4 g per serving across specified foods.
This is not FDA approval of every fava hydrolysate, a therapeutic authorization or validation of any claimed health benefit. The untapped element is commercialization of additional well-characterized products and genuinely new applications—not ordinary growth in plant-protein consumption already reflected in ingredient demand. An illustrative program selling 20 million annual servings at 2.4 g requires 48 tonnes of ingredient; at an assumed $40/kg, revenue is $1.92 million. If manufacturing and quality costs total an assumed $25/kg, contribution is $720,000 before research, sales, overhead and financing; a $2 million development investment would consequently require approximately 2.8 years of full-volume contribution to recover, excluding ramp-up and tax.
These are investment-screening assumptions, not published prices or margins. Suppliers should establish batch-composition comparability, permitted claims and customer formulation commitments before scaling, rather than extrapolate laboratory bioactivity into consumer benefits. The +0.35 pp upside assumes a 7% revenue exposure growing 5 percentage points faster through newly qualified peptide products, excluding generic plant isolates, pharmaceutical peptides and existing sports-hydrolysate sales merely rebranded as premium.
Opportunity Impact Analysis
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Characterized plant-peptide platforms | +0.35 pp | US, EU, Japan | Medium term (2–4 years) |
| Animal-free media ingredients | +0.30 pp | US, EU, Singapore, South Korea | Medium term (2–4 years) |
| Qualified biostimulant ingredients | +0.25 pp | EU, Brazil, India | Medium term (2–4 years) |
| Side-stream ingredient recovery | +0.25 pp | Norway, Iceland, Chile, Southeast Asia | Medium term (2–4 years) |
| Application-specific peptide fractions | +0.15 pp | EU, US, Japan | Long term (≥ 4 years) |
Challenges Analysis
Peptide-Profile Batch Consistency
An October 2026 review concludes that hydrolysates with similar degrees of hydrolysis can show markedly different technological performance because enzyme specificity, peptide distribution and amino-acid composition also matter. An April 2026 review of hydrolysates in cell culture provides a useful analytical illustration: reviewed studies detected between 64 and 33,518 peptides, averaging approximately 1,700, while measured metabolites represented roughly 14–57% of hydrolysate mass.
These figures concern particular industrial hydrolysates, not the composition of every nutritional product; importantly, the review also reports that overall batch variability was relatively low in one multisource study, preventing a blanket assumption that commercial lots are inherently inconsistent. In an illustrative 100-lot annual program, reducing lots requiring adjustment from 8% to 3% avoids five interventions; at an assumed $15,000 per intervention, the direct benefit is $75,000 before inventory and customer-support effects.
Manufacturers need feedstock segmentation, reference-batch libraries and application-relevant peptide fingerprints rather than indiscriminate testing of every detectable molecule. This is a continuing consistency challenge while qualified products remain saleable, not a claim that all variable lots must be rejected. The −0.30 pp estimate assumes 15% of revenue grows 2 percentage points more slowly because repeat characterization, blending and customer comparability work consume commercialization capacity.
Challenges Impact Analysis
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Peptide-profile batch consistency | −0.30 pp | EU, US, China, India | Medium term (2–4 years) |
| Hydrolysis scale-up control | −0.25 pp | EU, US, China, Southeast Asia | Medium term (2–4 years) |
| Membrane fractionation reliability | −0.25 pp | EU, US, Japan | Medium term (2–4 years) |
| Powder stability management | −0.25 pp | Tropical APAC, Brazil, EU exports | Long term (≥ 4 years) |
| Analytical specification alignment | −0.20 pp | EU, US, Japan; global suppliers | Medium term (2–4 years) |
Geopolitical Impact Analysis
Geopolitical Impact of Ongoing Wars on the Pulse Flours Market
The ongoing conflicts in the Middle East, Russia-Ukraine region, and surrounding shipping corridors are creating cost and supply-chain challenges for the global pulse flours market. Disruptions around the Strait of Hormuz, Red Sea, and Black Sea are affecting the movement of agricultural commodities, fuel, and fertilisers. These developments are increasing transportation costs, delivery times, and uncertainty for pulse growers, flour millers, and food ingredient manufacturers.
According to the United Nations Conference on Trade and Development (UNCTAD), shipping movements through the Strait of Hormuz declined by more than 95% following the escalation of the Middle East conflict in 2026. This disruption is increasing pressure on international trade and agricultural input costs.
The World Bank reported in October 2026 that global fertiliser prices are expected to increase by 14% in 2026, while food commodity prices are projected to rise by approximately 10%. Higher fertiliser, fuel, and freight expenses can increase pulse cultivation and processing costs, potentially raising chickpea, lentil, and pea flour prices. Prolonged conflicts may also encourage manufacturers to diversify suppliers, maintain additional inventories, and explore alternative shipping routes.
Regional Insights
Asia Pacific – Dominating Region (30.00% Share, USD 12.7 Billion)
Asia Pacific dominated the Pulse Flours Market in 2025, accounting for 30.00% of the global market, with a reported market value of USD 12.7 billion. The region benefits from established pulse cultivation, strong food-processing industries, and increasing demand for plant-based ingredients. Chickpea, lentil, and pea flours are used in bakery products, snacks, noodles, traditional food preparations, and nutritional formulations.
China also contributes to regional ingredient demand through its large food-processing industry. According to the United States Department of Agriculture (USDA), China’s dry pea domestic consumption was estimated at 690,000 tonnes in 2024/25, while chickpea consumption reached 26,000 tonnes. These applications and established food supply chains support regional demand for pulse-based ingredients.
North America represents an important growth opportunity for pulse flours, supported by established agricultural production, advanced milling facilities, and increasing interest in plant-based food ingredients. The United States and Canada have well-developed pulse supply chains that support the production of chickpea, lentil, and pea-based ingredients.
According to the USDA Economic Research Service, US chickpea net exports increased by 32%, dry pea net exports increased by 40%, and lentil net exports increased by 51% during the period through February 2025 compared with the corresponding previous-year period. This expanding pulse trade supports raw-material availability and creates opportunities for flour processors and food manufacturers.
Key Regions and Countries Insights
- North America
- US
- Canada
- Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Key Players Analysis
Synthite Industries Pvt. Ltd. strengthens its position in the natural food ingredient industry through its diversified ingredient portfolio, manufacturing infrastructure, and international distribution network. Established in 1972, the company operates 8 manufacturing facilities, serves more than 90 countries, and employs over 3,000 people. Its portfolio includes bio-ingredients, functional ingredients, and customised food solutions. These capabilities provide opportunities to serve food manufacturers seeking plant-derived ingredients and specialised food formulations.
Kalsec Inc. is a privately owned food ingredient manufacturer established in 1958, with its global headquarters in Kalamazoo, Michigan. The company focuses on natural colours, flavour extracts, antioxidants, and food protection solutions. In 2025, it opened an applications laboratory in Jakarta, Indonesia, strengthening its regional technical support. In 2024, it also opened a savoury product innovation centre at Wageningen University and new finishing and distribution centres in the United Kingdom and Singapore. These developments support its international food ingredient operations.
Plant Lipids Pvt. Ltd. is an established manufacturer of natural spice extracts, essential oils, and food ingredients. Incorporated in 1979, the company has developed manufacturing operations across multiple locations, including India, Sri Lanka, the United Kingdom, and Germany. Its facilities support extraction, blending, spray drying, and specialised ingredient processing. The company also works with more than 7,000 local farmers through its Shiggaon facility in Karnataka. Its manufacturing and ingredient-development capabilities support opportunities in specialised food formulations and natural ingredients.
Top Key Players Outlook
- Synthite Industries Pvt. Ltd.
- Kalsec Inc.
- Plant Lipids Pvt. Ltd.
- MANE Kancor Ingredients Pvt. Ltd.
- Chenguang Biotech Group Co., Ltd.
- AVT Natural Products Ltd.
- Akay Natural Ingredients Pvt. Ltd.
- Universal Oleoresins Pvt. Ltd.
- Givaudan SA
- PT Indesso Aroma
- Ozone Naturals Pvt. Ltd.
- Paprika Oleo’s India Ltd.
- Vidya Herbs Pvt. Ltd.
- Jean Gazignaire S.A.S.
- Ungerer & Company
Recent Developments
- In February 2026, Akay inaugurated its new corporate office at Ambunad, Kochi, with the participation of Oterra’s Chief Executive Officer, reflecting continued investment in infrastructure and international business relationships.
- In May 2026, MANE further expanded its functional ingredient portfolio through the acquisition of FROMATECH Ingredients B.V., a specialist in savoury flavours and functional ingredients.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 42.1 Bn |
| Forecast Revenue (2035) | USD 79.5 Bn |
| CAGR (2026-2035) | 6.6% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Pulse Type (Chickpea Flour, Lentil Flour, Pea Flour, Bean Flour, Fava Bean Flour, Other Pulse Flours), By Nature (Conventional, Organic), By Processing Method (Dry Milling, Wet Milling), By Application (Bakery and Confectionery, Snacks and Savory Products, Pasta and Noodles, Soups and Sauces, Meat Alternatives, Infant Nutrition, Other Applications), By Distribution Channel (Supermarkets and Hypermarkets, Convenience Stores, Specialty Stores, Online Retail, Foodservice, Other Distribution Channels) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | Synthite Industries Pvt. Ltd., Kalsec Inc., Plant Lipids Pvt. Ltd., MANE Kancor Ingredients Pvt. Ltd., Chenguang Biotech Group Co., Ltd., AVT Natural Products Ltd., Akay Natural Ingredients Pvt. Ltd., Universal Oleoresins Pvt. Ltd., Givaudan SA, PT Indesso Aroma, Ozone Naturals Pvt. Ltd., Paprika Oleo’s India Ltd., Vidya Herbs Pvt. Ltd., Jean Gazignaire S.A.S., Ungerer & Company |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








