


Report Overview
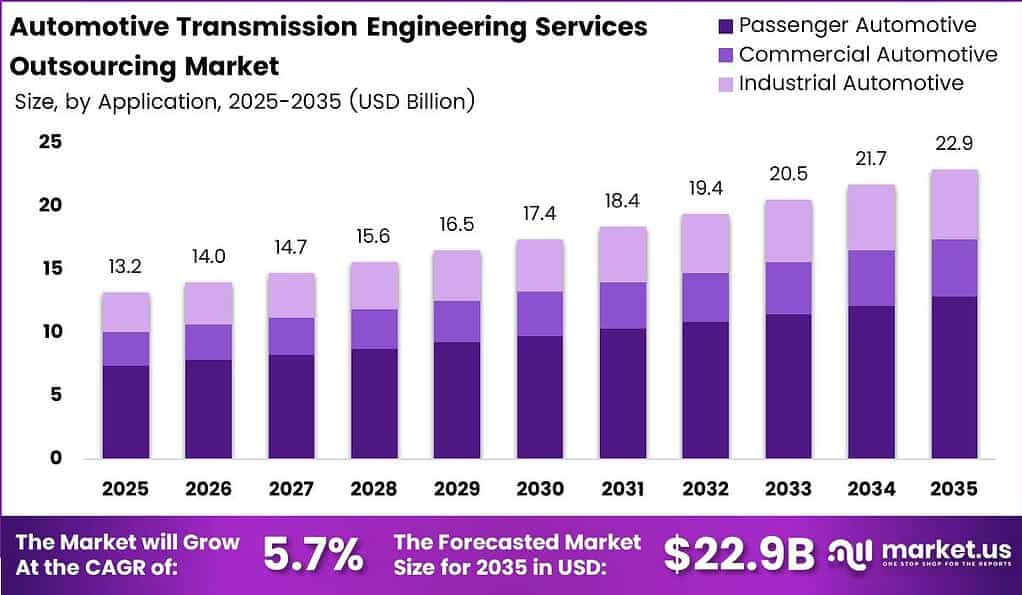
Global Automotive Transmission Engineering Services Outsourcing Market size is expected to be worth around USD 22.9 Billion by 2035 from USD 13.2 Billion in 2025, growing at a CAGR of 5.7% during the forecast period 2026 to 2035.
This market covers third-party engineering services contracted by original equipment manufacturers and Tier 1 suppliers to design, prototype, test, simulate, and integrate automotive transmission systems. Service providers support both conventional and electrified powertrain programs across passenger, commercial, and industrial vehicle segments. This reflects a structural shift in how automakers manage engineering capacity across increasingly complex multi-energy platform cycles.
Key Takeaways
- Global Automotive Transmission Engineering Services Outsourcing Market size is USD 13.2 Billion in 2025 and is projected to reach USD 22.9 Billion by 2035.
- The market is growing at a CAGR of 5.7% from 2026 to 2035.
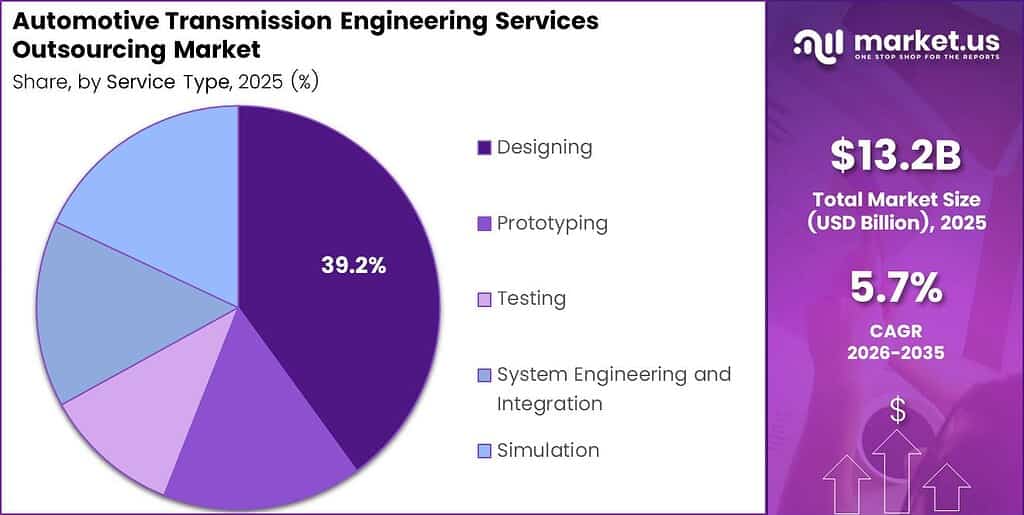
- Designing dominates the service type segment with a 39.12% market share.
- Manual Transmission dominates the transmission type segment with a 52.19% market share.
- Conventional Powertrain dominates the powertrain type segment with a 64.00% market share.
- Passenger Automotive dominates the application segment with a 55.13% market share.
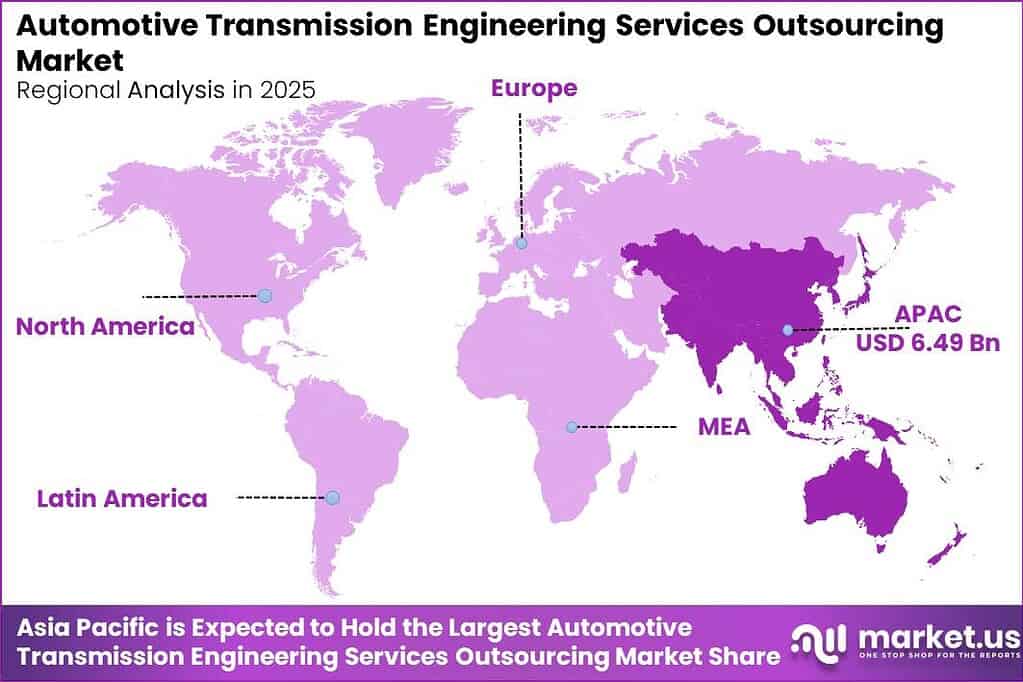
- Asia Pacific dominates the regional market with a 49.18% share, valued at USD 6.49 Billion in 2025.
- Europe is identified as the fastest-growing region during the forecast period.
According to ACEA, global car production grew 4.2% to 78.7 million units in 2025. This output expansion directly increases workload for transmission engineering service providers. OEMs scaling production require faster calibration cycles and more validation capacity than internal teams can absorb alone.
As reported by IEA, electric-car sales increased more than 20% to 21 million units in 2025, representing one in four cars sold globally. This adoption rate forces OEMs to maintain parallel engineering tracks across combustion, hybrid, and battery-electric architectures. Service providers who can operate across all three platforms hold a structural staffing advantage over single-technology specialists.
General Motors committed USD 888 million to its Tonawanda Propulsion plant in May 2025, signaling sustained OEM capital spending on powertrain infrastructure. This level of investment by a single manufacturer confirms that transmission development pipelines remain active despite EV transition pressure. Engineering service firms positioned near active OEM facilities stand to capture follow-on outsourcing contracts from these programs.
Service Type Analysis
Designing dominates with 39.12% due to front-loaded OEM engineering dependency.
In 2025, Designing held a dominant market position in the By Service Type segment of the Automotive Transmission Engineering Services Outsourcing Market, with a 39.12% share. OEMs outsource design work early in the product cycle to manage capacity constraints across simultaneous platform programs. Providers who hold deep design capability and tool compatibility with OEM systems control entry into the full program lifecycle, creating a durable competitive position before downstream services even begin.
Prototyping services capture demand between the design phase and physical validation, where engineering firms build functional transmission prototypes to verify design intent before production tooling commits. This phase is particularly time-sensitive on compressed development programs. ACEA data shows EU automotive R&D investment increased 23.2% to €72.8 billion in 2022, confirming the scale of investment that prototyping workloads must support.
Testing services represent a critical revenue stream as global regulatory requirements expand validation requirements for both conventional and electrified drivetrains. EU hybrid-electric car registrations increased 26.4% to 321,959 units in June 2024, reflecting a 29.5% market share. Each new drivetrain configuration entering production requires independent test cycles, expanding the total addressable scope for outsourced testing providers.
Simulation services occupy a growing role as OEMs adopt virtual validation to compress physical test cycles and reduce prototype costs. Hybrid-electric cars represented 34.5% and plug-in hybrids represented 9.4% of EU new-car registrations in 2025, reflecting a broad multi-powertrain mix requiring simulation-led development.
System Engineering and Integration, Simulation, and remaining service types hold the balance of market share and support program-level coordination across increasingly fragmented supplier networks. ZF announced a planned USD 500 million investment and 400 jobs for next-generation 8HP Gen4 plug-in-hybrid transmission production in February 2024. This level of component-level investment confirms that program complexity is expanding, not contracting, and creates sustained demand for outsourced system integration services.
Transmission Type Analysis
Manual Transmission dominates with 52.19% due to high installed base in cost-sensitive and commercial segments.
In 2025, Manual Transmission held a dominant market position in the By Transmission Type segment of the Automotive Transmission Engineering Services Outsourcing Market, with a 52.19% share. Manual transmissions remain the primary drivetrain in commercial vehicles, two-wheelers, and price-sensitive passenger segments across developing markets. India produced 3,157,822 passenger vehicles, three-wheelers, two-wheelers and quadricycles in August 2026, indicating active production volume in markets where manual transmissions retain structural dominance. This sustained output base keeps engineering service demand for manual transmission programs active across calibration, testing, and compliance workflows.
Automatic Transmission holds the remaining share in this segment and represents the faster-growing category as buyer preference shifts in developing markets and OEMs expand automatic-only platforms for electrified architectures. Global electric-truck sales exceeded 400,000 units and doubled to 9% of worldwide truck sales in 2025, reinforcing the commercial vehicle shift toward automated powertrains that require dedicated transmission engineering programs. Service providers building automatic transmission competency now position themselves ahead of the segment volume crossover expected within this forecast period.
Powertrain Type Analysis
Conventional Powertrain dominates with 64.00% due to active global production volume and long engineering tail.
In 2025, Conventional Powertrain held a dominant market position in the By Powertrain Type segment of the Automotive Transmission Engineering Services Outsourcing Market, with a 64.00% share. Conventional internal combustion programs continue to generate transmission engineering workloads through compliance updates, regional variant calibration, and efficiency improvements required under tightening emissions standards. The scale of active conventional powertrain programs across Asia Pacific and North America ensures that this segment remains the primary revenue base for outsourced transmission engineering services throughout the forecast period.
Hybrid Powertrain holds the remaining share in this segment and represents the most technically complex engineering category per program, given the requirement to integrate combustion-side and electric-side transmission controls within a single calibration architecture. This complexity drives outsourcing intensity per program higher than for pure conventional or pure electric platforms. Service providers with hybrid transmission expertise command pricing power in this sub-segment as OEM internal capacity for hybrid-specific calibration remains constrained.
Application Analysis
Passenger Automotive dominates with 55.13% due to highest unit volume and program diversity across OEMs.
In 2025, Passenger Automotive held a dominant market position in the By Application segment of the Automotive Transmission Engineering Services Outsourcing Market, with a 55.13% share. Passenger vehicle programs generate the broadest range of transmission engineering work, spanning design, simulation, calibration, and validation across multiple regional variants and powertrain configurations. Passenger-vehicle sales in India reached 439,309 units in August 2026 alone, reflecting the sustained production volumes that translate directly into active outsourced engineering pipelines in high-growth markets.
Commercial Automotive captures demand from truck, bus, and van programs that require transmission engineering with higher durability specifications and longer validation cycles than passenger programs. This sub-segment generates fewer programs by volume but higher engineering hours per program, supporting above-average revenue per engagement for qualified service providers. Industrial Automotive holds the remaining application share and covers off-highway, construction, and specialty vehicle transmissions with unique duty-cycle and load requirements that fall outside standard passenger or commercial validation frameworks.
Key Market Segments
By Service Type
- Designing
- Prototyping
- Testing
- System Engineering and Integration
- Simulation
By Transmission Type
- Manual Transmission
- Automatic Transmission
By Powertrain Type
- Conventional Powertrain
- Hybrid Powertrain
By Application
- Passenger Automotive
- Commercial Automotive
- Industrial Automotive
Regional Analysis
Asia Pacific Dominates the Automotive Transmission Engineering Services Outsourcing Market with a Market Share of 49.18%, Valued at USD 6.49 Billion
Asia Pacific holds 49.18% of the global market, valued at USD 6.49 Billion in 2025. Asia-Oceania produced 54,907,849 motor vehicles in 2024, giving the region an unmatched production base that sustains continuous demand for outsourced transmission engineering across all service categories. OEMs and Tier 1 suppliers operating at this scale cannot absorb peak engineering workloads internally, making third-party service providers structurally necessary rather than discretionary across the region.
Europe is the fastest-growing region in this market. The UK vehicle fleet increased 1.4% to 42,549,649 vehicles in 2025, reflecting steady fleet expansion even in a market facing electrification transition pressures. General Motors announced USD 830 million across three propulsion sites in April 2026, including USD 300 million for Romulus and USD 40 million for Toledo’s 10-speed transmission capacity, signaling continued OEM capital commitment to transmission programs in North America that drives parallel outsourcing activity. Stellantis announced a USD 13 billion US investment plan in October 2025 covering five vehicle launches and more than 5,000 jobs, confirming program pipeline depth that engineering service providers can expect to serve across North America and Europe.
Remaining regions, including Latin America and the Middle East and Africa, contribute the balance of market share. Toyota announced more than USD 50 million for seven testing and development projects at its Arizona Proving Grounds in July 2025, reinforcing that validation infrastructure investment is active across North America. Passenger-vehicle sales in India reached 439,309 units in August 2026, confirming that South Asia continues to generate strong downstream demand for transmission engineering programs linked to active vehicle production pipelines.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Market Opportunity Analysis - Underserved geographies and lower-share service segments offer entry leverage for specialized providers
Industrial Automotive holds the smallest application share in this market yet serves transmission engineering programs with the most differentiated duty-cycle requirements. Off-highway, construction, and specialty vehicle programs sit outside the standard validation frameworks used for passenger and commercial segments. Providers who build dedicated Industrial Automotive competency face less incumbent competition and can command premium pricing on programs that generalist firms decline to bid.
Simulation services represent a sub-scale segment within the By Service Type breakdown but carry the highest growth potential as OEMs compress physical development cycles. Virtual validation reduces prototype costs and accelerates homologation timelines across multi-energy platforms. By contrast, providers still anchored to physical-first validation workflows risk being excluded from programs where simulation-led development is already the OEM standard.
Hybrid Powertrain holds the smaller share within the By Powertrain Type segment but generates the highest engineering complexity per program. This complexity creates a natural barrier to entry that limits the number of qualified service providers competing for each contract. New entrants who invest in hybrid transmission calibration toolchains and cross-domain staffing position themselves for outsized share capture as hybrid programs scale across Asia Pacific and Europe through the forecast period.
Europe’s status as the fastest-growing region, combined with its regulatory-led transition to electrified architectures, creates a concentration of high-value engineering programs that the existing regional provider base may not fully absorb. This gap benefits Asia Pacific-based service firms, particularly those with established OEM relationships, who can extend their delivery capacity into European programs without building physical presence from scratch.
Technology and Innovation Landscape - AI-assisted design, digital validation tools, and expanded test infrastructure define the competitive frontier
FEV Group collaborated with Nature Architects to achieve up to 51% weight reduction in a sill reinforcement while maintaining equivalent energy absorption through AI-supported structural optimization. This method applies computational generative design to safety-critical vehicle components, replacing iterative physical prototyping with simulation-led geometry discovery. Transmission engineering providers that adopt comparable AI-assisted design workflows can offer OEMs faster design cycles with validated mass targets, a combination that commands premium contract positioning.
HORIBA expanded its Fukuchiyama Technology Center to 5,642 square metres and doubled its gas-flow calibration and liquid-vaporization testing capacities in January 2026. This infrastructure investment reflects a deliberate strategy to absorb outsourced test volume as electrified powertrain programs scale globally. Providers who invest in physical test capacity ahead of demand peaks establish utilization advantages over competitors who must subcontract during program surges.
China holds an average market share of approximately 70% across 19 of 20 strategic minerals analyzed by IEA, positioning it as the dominant upstream supplier for the rare-earth and critical materials used in electric drive units and transmission actuators. This concentration creates a materials supply risk that transmission engineering service providers must factor into program planning for electrified architectures. Providers who build supply chain risk assessment into their engineering workflows offer OEM clients a risk mitigation capability that pure technical engineering firms cannot match.
Digital-twin service platforms represent an emerging technology category directly referenced in the Opportunities data for this market, with a projected +0.30% CAGR upside contribution over a two-to-four-year execution window. These platforms allow continuous validation of transmission software updates against virtual models without requiring physical test bench time for every iteration. Providers who deploy digital-twin infrastructure today reduce per-release validation cost and create a scalable basis for the lifecycle calibration subscription model that represents the market’s highest-upside opportunity.
Drivers
Parallel OEM investment across combustion, hybrid, plug-in-hybrid, and battery-electric architectures multiplies transmission controls, thermal-management, and calibration work rather than producing a single linear technology substitution. Global electric-car sales exceeded 17 million in 2024 and reached a 20% sales share, while sales were expected to exceed 20 million and one-quarter of the market in 2025. This simultaneous program expansion forces OEMs to outsource peak engineering loads and seek an estimated 6 to 10% reduction in idle internal capacity.
In the European Union, battery-electric and hybrid-electric cars captured 17.4% and 34.5% of registrations respectively during 2025. These parallel architectures can raise transmission-related calibration maps by an estimated 15 to 25% and validation hours by 10 to 18% per multi-energy platform. This contributes approximately +0.75% to the 5.7% baseline CAGR, supporting the market case for engineering service providers who maintain cross-platform transmission competency.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Passenger powertrain proliferation | +0.75% | Global; strongest in China, Europe, and North America | Short term (≤ 2 years) |
| Efficiency compliance programs | +0.45% | Europe, North America, China, Japan, and South Korea | Short term (≤ 2 years) |
| Accelerated platform refreshes | +0.40% | Global automotive production hubs | Medium term (2–4 years) |
| Variable-cost engineering procurement | +0.30% | Europe, North America, Japan, and South Korea | Short term (≤ 2 years) |
| Automatic transmission adoption | +0.25% | India, Southeast Asia, Latin America, and Africa | Medium term (2–4 years) |
| Commercial-fleet durability demand | +0.20% | Europe, North America, India, and Latin America | Medium term (2–4 years) |
Restraints
Weak or uneven vehicle demand causes OEMs and major suppliers to freeze discretionary development packages, delay purchase orders, and retain only homologation-critical work. European Union registrations declined 1.9% during the first half of 2025 before finishing the year only 1.8% higher, illustrating the demand uncertainty that makes engineering commitments vulnerable to quarterly rephasing by finance teams.
A production-plan reduction of 3 to 5% can trigger modeled external-engineering cuts of 8 to 15%, extend contract awards by 2 to 3 quarters, and compress operating margins by roughly 150 to 300 basis points. This dynamic produces an estimated -0.55% deduction from the 5.7% baseline CAGR. Service providers without diversified OEM client portfolios face concentrated revenue risk when any single customer enters a freeze cycle.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Engineering-budget freezes | -0.55% | Europe and export-dependent production hubs | Short term (≤ 2 years) |
| OEM data firewalls | -0.35% | Europe, North America, China, Japan, and South Korea | Short term (≤ 2 years) |
| Supplier qualification lock-in | -0.30% | Global premium and safety-critical programs | Medium term (2–4 years) |
| Captive-center insourcing | -0.20% | India, Eastern Europe, Mexico, and Southeast Asia | Medium term (2–4 years) |
| Currency-linked contract erosion | -0.15% | Cross-border offshore delivery markets | Short term (≤ 2 years) |
| Fragmented procurement ownership | -0.15% | Global multi-brand automotive groups | Medium term (2–4 years) |
Challenges
A limited pool of engineers combining gears and tribology expertise with power electronics, embedded controls, functional safety, and model-based calibration creates a structural staffing constraint across the market. The United States alone is projected to require about 174,800 architecture and engineering openings annually, including approximately 17,800 mechanical-engineering openings. Transmission specialists with cross-domain credentials can command estimated compensation premiums of 12 to 20% and take 8 to 16 weeks longer to recruit than single-discipline engineers.
Projects operating with cross-domain talent gaps run at only 75 to 85% of planned staffing, creating approximately -0.45% of friction against maximum CAGR potential. The broader occupation group recorded median annual pay of USD 99,520 in 2025, raising the cost baseline for every firm competing for this talent. Service providers that invest in multi-year training academies and reusable engineering libraries can offset this drag while competitors absorb it as a margin cost.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Cross-domain engineering talent | -0.45% | Global; acute in established automotive clusters | Medium term (2–4 years) |
| Toolchain interoperability debt | -0.35% | Europe, North America, Japan, and India | Medium term (2–4 years) |
| Test-bench capacity bottlenecks | -0.30% | Global validation and homologation centers | Medium term (2–4 years) |
| Semiconductor architecture churn | -0.25% | China, Europe, North America, and East Asia | Short term (≤ 2 years) |
| Duty-cycle data scarcity | -0.20% | India, Southeast Asia, Africa, and Latin America | Medium term (2–4 years) |
| Model-correlation drift | -0.15% | Global multi-platform engineering programs | Long term (≥ 4 years) |
Opportunities
Most transmission-engineering contracts remain milestone-based and concentrated before production launch, leaving post-launch calibration, update validation, and compliance evidence weakly monetized. Software-update rules applied to existing unlimited-series European vehicle approvals from 7 July 2024, expanded to relevant new complete vehicles from 7 July 2026, and require certified software-update management systems whose assessments must be renewed at least every 3 years. This regulatory structure creates a recurring compliance obligation that service providers can convert into structured subscription engagements.
Converting one-off projects into multi-year lifecycle subscriptions could lift recurring revenue to an estimated 10 to 18% of provider sales and reduce engineering cost per validated release by 20 to 30% through reusable pipelines. Margin expansion of roughly 300 to 500 basis points and an approximately +0.70% contribution to the 5.7% baseline CAGR are achievable through this model. Providers who move first to structure compliant subscription offerings in Europe will establish contract frameworks that late movers must displace rather than simply match.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Lifecycle calibration subscriptions | +0.70% | Europe, Japan, South Korea, and other regulated markets | Medium term (2–4 years) |
| Electrified commercial axles | +0.50% | Europe, China, North America, and India | Medium term (2–4 years) |
| Circularity redesign services | +0.35% | Europe, North America, and mature aftermarket regions | Long term (≥ 4 years) |
| Digital-twin service platforms | +0.30% | Global mid-tier suppliers and specialist manufacturers | Medium term (2–4 years) |
| Off-highway electrification adjacencies | +0.25% | North America, Europe, India, and Australia | Long term (≥ 4 years) |
| Engineering-center roll-ups | +0.20% | India, Eastern Europe, Southeast Asia, and Latin America | Medium term (2–4 years) |
Key Company Insights
AVL List GmbH reported 192 Austrian patent applications during 2024 and retained first place for the 14th consecutive year. This consistent IP output signals a systematic innovation pipeline rather than cyclical R&D activity. For OEMs evaluating outsourcing partners, AVL’s patent cadence indicates proprietary methodology depth that reduces technical risk on complex multi-energy transmission programs.
FEV Group GmbH demonstrated structural innovation capability through its collaboration with Nature Architects, achieving up to 51% weight reduction in a sill reinforcement while maintaining equivalent energy absorption. This result establishes FEV’s ability to apply simulation-led design methods to safety-critical automotive structures. Buyers seeking transmission programs with mass and packaging targets that conventional design cannot meet have a validated technical case for engaging FEV’s advanced engineering teams.
As per our research, HORIBA, Ltd. commissioned its expanded Fukuchiyama Technology Center in January 2026, adding 5,642 square metres of floor area and doubling gas-flow calibration and liquid-vaporization testing capacities. This physical capacity expansion positions HORIBA to absorb increased outsourced testing volume as electrified powertrain programs scale. Tata Technologies Limited recorded FY2025 operating revenue of ₹51,685 million and operating EBITDA of ₹9,341 million, demonstrating the financial scale to support large, multi-year transmission engineering engagements across global OEM accounts.
L&T Technology Services Limited recorded Q3 FY2025 revenue of ₹26,530 million and employed 23,465 people at quarter-end, reflecting a headcount base that enables concurrent delivery across multiple programs. Ricardo plc recorded FY2023/24 revenue of £474.7 million, up 7% on a continuing basis, before WSP agreed to acquire Ricardo in June 2025 at an enterprise value of approximately £363.1 million, a transaction that reshapes the competitive supply landscape for specialist transmission engineering services.
Capgemini Engineering completed its USD 3.3 billion acquisition of WNS in October 2025, expanding its delivery capability in engineering-adjacent services. L&T Technology Services completed its acquisition of 100% of Intelliswift in January 2025 under a transaction valued at up to USD 110 million, adding digital engineering capacity to its outsourcing portfolio. Ricardo completed the sale of Ricardo Defense for total adjusted consideration of USD 90.6 million in December 2024, allowing the firm to concentrate resources on its core automotive engineering practice.
Key Players
- AVL List GmbH
- FEV Group GmbH
- Ricardo plc
- IAV GmbH
- Bertrandt AG
- EDAG Engineering GmbH
- Capgemini Engineering
- Tata Technologies Limited
- L&T Technology Services Limited
- HCL Technologies Limited
- Tech Mahindra Limited
- ALTEN Group
- HORIBA, Ltd.
- Onward Technologies Limited
- ARRK Engineering GmbH
Recent Developments
- July 1, 2026 – Tata Technologies and Tenneco announced a USD 100 million strategic mobility-transformation engagement.
- January 16, 2026 – HORIBA STEC began full-scale operation of its approximately ¥4 billion Fukuchiyama Technology Center expansion.
- January 2, 2026 – Dana completed the USD 2.7 billion sale of its Off-Highway business to Allison Transmission.
- October 27, 2025 – HARMAN announced a ₹345 crore investment to expand its Pune automotive-electronics plant by 71,505 square feet and increase capacity by more than 50%.
- September 13, 2025 – Tata Technologies agreed to acquire 100% of ES-Tec Group for €75 million.
- June 11, 2025 – WSP agreed to acquire Ricardo at an enterprise value of approximately £363.1 million.
- June 11, 2025 – Dana agreed to sell its Off-Highway business to Allison Transmission for USD 2.7 billion.
- March 7, 2025 – AVL reported 192 Austrian patent applications during 2024 and retained first place for the 14th consecutive year.
- March 6, 2024 – Stellantis announced a €5.6 billion South American investment program for 2025 to 2030 supporting more than 40 new products.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 13.2 Billion |
| Forecast Revenue (2035) | USD 22.9 Billion |
| CAGR (2026-2035) | 5.7% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Service Type (Designing, Prototyping, Testing, System Engineering and Integration, Simulation), By Transmission Type (Manual Transmission, Automatic Transmission), By Powertrain Type (Conventional Powertrain, Hybrid Powertrain), By Application (Passenger Automotive, Commercial Automotive, Industrial Automotive) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | AVL List GmbH, FEV Group GmbH, Ricardo plc, IAV GmbH, Bertrandt AG, EDAG Engineering GmbH, Capgemini Engineering, Tata Technologies Limited, L&T Technology Services Limited, HCL Technologies Limited, Tech Mahindra Limited, ALTEN Group, HORIBA, Ltd., Onward Technologies Limited, ARRK Engineering GmbH |
| Customization Scope | Customization for segments, region/country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








