


Report Overview
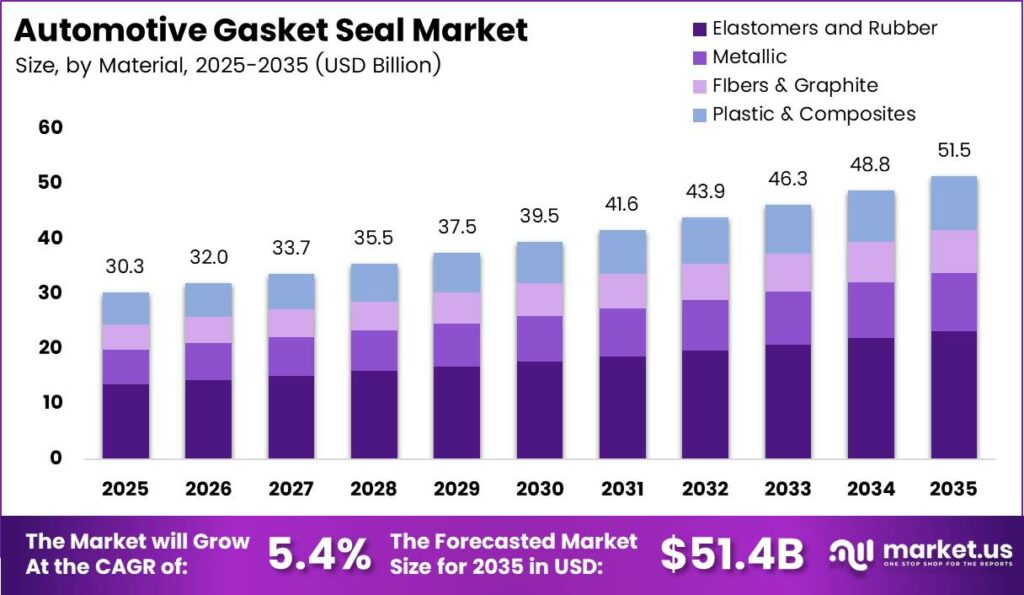
Global Automotive Gasket Seal Market size is expected to be worth around USD 51.5 Billion by 2035 from USD 32.0 Billion in 2026, growing at a CAGR of 5.4% during the forecast period 2026 to 2035. According to OICA data, global vehicle production rose from 92.7 million units in 2024 to 96.4 million units in 2025, while vehicle sales climbed from 95.3 million to 99.8 million units. Higher output directly expands OEM sealing demand.
The automotive gasket seal market covers engineered components that prevent fluid and gas leakage across vehicle systems, including engines, transmissions, EV battery enclosures, and chassis assemblies. Based on IMF data, global economic growth reached 3.2% in 2025, sustaining vehicle fleet expansion across major manufacturing economies. This market spans static and dynamic sealing applications, serving both OEM production lines and the global aftermarket replacement channel.
Key Takeaways
- The global Automotive Gasket Seal Market was valued at USD 32.0 Billion in 2026 and is forecast to reach USD 51.5 Billion by 2035.
- The market grows at a CAGR of 5.4% during the forecast period 2026 to 2035.
- By Type, Gaskets dominates with a 58.80% share in 2025.
- By Material, Elastomers and Rubber leads with a 45.00% share in 2025.
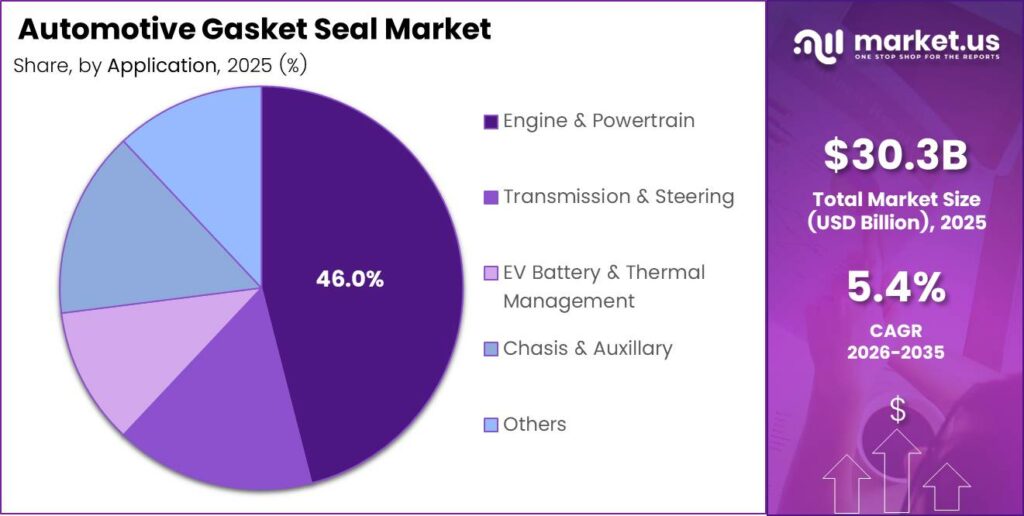
- By Application, Engine and Powertrain holds the dominant position with a 46.00% share in 2025.
- By Vehicle Type, Passenger Cars accounts for 74.00% of the market in 2025.
- By Sales Channel, OEM leads with a 65.00% share in 2025.
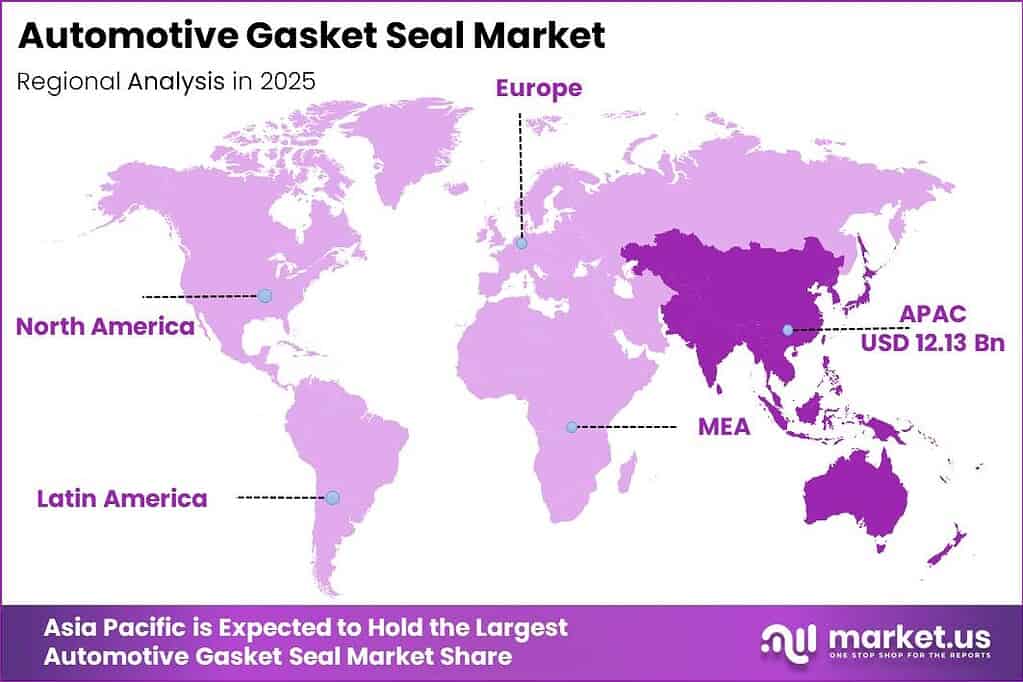
- Asia Pacific is the dominant region, holding a 40.00% share valued at USD 12.13 Billion in 2025.
- Europe is the fastest-growing regional market during the forecast period.
As per our research, world merchandise-trade volume expanded by 4.6% in 2025, reflecting a resilient cross-border supply chain that sustains raw-material flows for gasket and seal producers. This trade activity reinforces the viability of regionally distributed manufacturing strategies. Suppliers with multi-region production footprints carry a structural cost advantage over single-source competitors.
IEA data shows global electric-car sales rose by more than 20% to 21 million units in 2025, representing one-fourth of total car sales. This electrification shift restructures the sealing bill of materials per vehicle, replacing legacy ICE gasket stacks with higher-value battery enclosure and thermal management seals. Suppliers that qualify EV-grade elastomers early capture the margin uplift before programs lock sourcing. According to IEA figures, EV battery deployment reached 1.2 TWh in 2025, rising by nearly 30% from 2024 and exceeding the 2020 level by more than seven times. This deployment scale forces sealing suppliers to serve far larger thermal interface and enclosure sealing volumes than any prior product cycle required.
As reported by SIAM, India’s passenger-vehicle sales reached 4.643 million units in FY2025–26, growing by 7.9%. This positions India as one of the highest-volume growth markets for OEM sealing supply contracts outside China. On 26 November 2025, ElringKlinger launched an aftermarket plastic oil pan for OM 471 commercial-vehicle engines, delivering weight savings of up to 60% versus metal alternatives. This product signals a wider industry move toward polymer-based sealing assemblies that reduce vehicle weight and extend service life.
Type Analysis
Gaskets dominates with 58.80% due to universal fitment across all powertrain architectures.
In 2025, Gaskets held a dominant market position in the By Type segment of the Automotive Gasket Seal Market, with a 58.80% share. Gaskets serve every combustion, hybrid, and emerging EV platform through head sealing, manifold sealing, and battery enclosure perimeter applications. This cross-architecture demand prevents volume erosion even as powertrain mix shifts toward electrification. Buyers seeking a single sealing category with durable OEM volumes will find gaskets the most defensible position.
Seals cover the remainder of the By Type segment and serve high-motion applications including crankshaft, camshaft, wheel bearing, and e-motor shaft sealing. Dynamic sealing requirements grow as EV drivetrains introduce new shaft interfaces and coolant-loop connectors absent from ICE platforms. This creates a volume replacement effect that partially offsets the combustion sealing units displaced by electrification. On 15 January 2025, Trelleborg integrated Magee Plastics following its December 2024 acquisition, adding approximately SEK 230 million in 2023 sales to its sealing portfolio, signaling active consolidation in the dynamic sealing sub-segment.
Material Analysis
Elastomers and Rubber dominates with 45.00% due to chemical resistance and flexible geometry across seal types.
In 2025, Elastomers and Rubber held a dominant market position in the By Material segment of the Automotive Gasket Seal Market, with a 45.00% share. Elastomeric compounds deliver the chemical resistance, compression set recovery, and temperature flexibility demanded by both ICE and EV sealing applications. This dual-platform compatibility protects volume across the powertrain transition cycle. Suppliers with qualified fluorosilicone and FKM compound libraries carry a direct sourcing advantage as EV programs scale.
Metallic materials serve high-pressure, high-temperature applications concentrated in cylinder head, exhaust manifold, and turbocharger sealing. These applications remain structurally tied to combustion output volumes, making metallic gasket demand a function of ICE production schedules. As ICE mix declines in Europe and North America, metallic sealing revenue will compress faster than the overall market. Suppliers reliant on metallic formats must offset this attrition with EV-adjacent product extensions.
Fibers and Graphite serve exhaust and high-heat static joints where elastomers cannot meet temperature thresholds. Plastic and Composites represent the fastest-evolving format within the material mix, driven by lightweighting mandates and EV battery assembly requirements. Together these two sub-segments hold the remaining market share, with composites gaining specification wins in battery pack assembly as OEMs pursue both mass reduction and thermal management integration.
Application Analysis
Engine and Powertrain dominates with 46.00% due to the highest sealing component count per vehicle.
In 2025, Engine and Powertrain held a dominant market position in the By Application segment of the Automotive Gasket Seal Market, with a 46.00% share. This application category carries the broadest sealing stack per vehicle, spanning head gaskets, valve cover seals, oil pan gaskets, and intake manifold joints. Global trade in goods and services exceeded USD 35 trillion in 2025, growing by approximately USD 2.2 trillion or 7%, sustaining cross-border powertrain component supply chains. High component density per vehicle makes Engine and Powertrain the most volume-stable application category even as platform mix evolves.
Transmission and Steering represents the second application tier, covering gearbox, differential, and steering rack sealing across both manual and automatic platforms. This segment benefits from the lengthening average vehicle age in mature markets, which expands replacement demand for transmission seals before the vehicle is retired. By contrast, EV Battery and Thermal Management is the fastest-expanding application sub-segment, converting new safety mandates into sourcing requirements for battery perimeter, EMI shielding, and coolant-loop seals.
Chassis and Auxiliary and Others, covering suspension, braking, and accessory sealing, collectively hold the remaining application share. These segments track vehicle population growth more than new vehicle output, providing a stable base revenue stream for sealing suppliers active in the aftermarket channel. This creates a structural revenue floor that absorbs cyclical dips in OEM production schedules.
Vehicle Type Analysis
Passenger Cars dominates with 74.00% due to the highest global vehicle production and fleet volume.
In 2025, Passenger Cars held a dominant market position in the By Vehicle Type segment of the Automotive Gasket Seal Market, with a 74.00% share. IEA data shows light-duty vehicles represented more than 85% of global EV battery deployment in 2025, directly tying passenger car sealing demand to the highest-growth powertrain investment pool. SIAM data indicates India’s passenger-vehicle sales reached 4.302 million units in FY2024–25, while passenger-car sales declined from 1.549 million to 1.353 million units within that mix, showing a structural shift toward SUVs inside the passenger segment.
Within Passenger Cars, SUVs are gaining share relative to Sedans and Hatchbacks across major markets, altering the sealing content profile per vehicle as larger body-on-frame platforms carry additional chassis and thermal sealing requirements. Sedans and Hatchbacks retain high-volume relevance in emerging markets where entry-price segments still dominate retail mix. This sub-segment divergence means sealing suppliers must maintain platform-specific tooling across a wider SKU range than a homogeneous passenger mix would require.
Commercial Vehicles account for the remaining 26% of the By Vehicle Type segment, split across Light Commercial Vehicles, medium- and heavy-duty trucks and buses, and other configurations. Commercial vehicle sealing carries higher per-unit revenue than passenger sealing due to the larger displacement engines and multi-axle drivetrain complexity that expand the sealing component count. This makes commercial vehicle accounts disproportionately valuable for suppliers competing on revenue per platform.
Sales Channel Analysis
OEM dominates with 65.00% due to volume sourcing contracts tied directly to vehicle production schedules.
In 2025, OEM held a dominant market position in the By Sales Channel segment of the Automotive Gasket Seal Market, with a 65.00% share. OEM contracts deliver predictable volume tied to production scheduling, allowing sealing suppliers to optimize press-line utilization and raw-material procurement cycles. China produced 34.531 million automobiles in 2025, up 10.4%, with sales rising 9.4% to 34.4 million units, reinforcing Asia Pacific as the highest-volume OEM sealing demand pool. Suppliers with qualified positions on Chinese OEM platforms hold access to the largest single production base in the market.
The Aftermarket channel holds the remaining 35% share and operates on a fundamentally different economics model, serving vehicle owners replacing worn seals across a vehicle population that extends well beyond the active production base. As the global fleet ages in mature markets where new vehicle affordability constrains replacement rates, aftermarket sealing demand grows independently of OEM output cycles. This counter-cyclical revenue characteristic makes aftermarket exposure a strategic hedge for suppliers facing OEM production volatility.
Automotive Gasket Seal Market Segments
By Type
- Gaskets
- Seals
By Material
- Elastomers and Rubber
- Metallic
- Fibers and Graphite
- Plastic and Composites
By Application
- Engine and Powertrain
- Transmission and Steering
- EV Battery and Thermal Management
- Chassis and Auxiliary
- Others
By Vehicle Type
- Passenger Cars
- Sedans
- Hatchbacks
- SUVs
- Commercial Vehicles
- Light Commercial Vehicles (LCVs)
- Medium- and Heavy-Duty Trucks and Buses
- Others
By Sales Channel
- OEM (Original Equipment Manufacturer)
- Aftermarket
Automotive Gasket Seal Market Regional Analysis
Asia Pacific Dominates the Automotive Gasket Seal Market with a Market Share of 40.00%, Valued at USD 12.13 Billion
Asia Pacific commands the largest regional share through its concentration of the world’s highest-volume vehicle assembly operations. China’s government data confirms automobile production of 34.531 million units in 2025, up 10.4%, with China simultaneously producing 16.626 million new-energy vehicles, up 29%. This dual ICE-plus-NEV output scale makes China the single largest demand anchor for both conventional and EV-grade sealing supply. India adds incremental depth, with passenger-vehicle sales reaching 4.49 million units in CY2025, a 5% increase that sustains a growing OEM sealing demand base.
Europe is the fastest-growing regional market during the forecast period. The ACEA reports EU new-car registrations grew 1.8% in 2025, with 1,880,370 battery-electric vehicles registered, representing 17.4% of the total market. This BEV penetration rate is the highest among major regional markets and directly accelerates demand for EV-grade sealing materials across European OEM supply chains. On 17 May 2024, Trelleborg announced an investment exceeding SEK 100 million in a sealing-solutions facility of more than 5,000 square metres in Morocco, positioning North Africa as a nearshore production base to serve European OEM demand efficiently.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Drivers
Battery-electric vehicles displace the head gasket and exhaust sealing stack of combustion platforms but replace them with a higher-value sealing bill of materials covering battery-pack perimeter gaskets, IP67/IP68 enclosure seals, EMI-shielding gaskets, and coolant-loop thermal management seals. This architecture shift lifts sealing content per vehicle by an estimated 15% to 30% on a value basis. Suppliers that qualified fluorosilicone and liquid-injection-molded silicone platforms ahead of OEM sourcing cycles are capturing specification-locked, multi-year battery sealing contracts.
The conversion of commodity elastomer gaskets into engineered battery-sealing assemblies expands blended gross margins by an estimated 300 to 600 basis points for qualifying suppliers. With Chinese OEMs producing near 10 million new-energy vehicles annually, this mix shift anchors a structural +2.3% contribution to the market’s 5.4% CAGR baseline. Tightening tailpipe emission standards in the EU, North America, and India add a further +1.6% CAGR contribution by mandating tighter combustion sealing tolerances that increase gasket specification values per platform.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| EV Battery & Thermal Sealing Content Uplift | +2.3% | China, EU, North America | Short term (≤ 2 years) |
| Tightening Tailpipe Emission Standards | +1.6% | EU, North America, India | Short term (≤ 2 years) |
| Rising Aftermarket Replacement Demand | +1.2% | Global | Medium term (2–4 years) |
| Global Light-Vehicle Output Recovery | +0.9% | Asia-Pacific, Latin America | Short term (≤ 2 years) |
| Powertrain Complexity & Downsizing | +0.7% | EU, Japan, South Korea | Medium term (2–4 years) |
| Lightweight Material Substitution | +0.5% | Global | Medium term (2–4 years) |
Restraints
Electrification strands the highest-volume sealing applications in legacy supplier portfolios. A battery-electric platform eliminates an estimated 40 to 60 discrete sealing components per vehicle relative to a conventional ICE platform, removing head gaskets, manifold seals, turbocharger joints, and crankshaft seals in a single architecture decision. Suppliers with revenue 70%-plus weighted to combustion gasket sets face falling unit throughput against fixed tooling overhead, compressing capacity utilization by an estimated 500 to 800 basis points on legacy lines.
Section 232 auto-parts tariffs impose a -1.3% CAGR drag concentrated in North America by disrupting cross-border sealing supply chains and inflating landed costs for import-dependent OEM programs. Raw-material and feedstock price volatility adds a further -1.0% drag globally as elastomer and specialty chemical feedstock costs remain unpredictable. Together, ICE attrition, tariff friction, and input cost volatility pull an estimated -5.4% in combined CAGR pressure against the market’s growth trajectory.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| ICE Powertrain Sealing Attrition | -1.8% | EU, North America | Medium term (2–4 years) |
| Section 232 Auto-Parts Tariffs | -1.3% | North America | Short term (≤ 2 years) |
| Raw-Material & Feedstock Price Volatility | -1.0% | Global | Short term (≤ 2 years) |
| Elevated Interest Rates & CapEx Deferral | -0.7% | North America, EU | Short term (≤ 2 years) |
| OEM Price-Down Pressure on Tier Suppliers | -0.6% | Global | Medium term (2–4 years) |
Challenges
EV sealing applications demand elastomer chemistries including fluorosilicone, FKM, liquid silicone rubber, and thermally conductive gap fillers that must deliver dielectric strength above 15 kV/mm, thermal-runaway flame resistance, and 15-year or 240,000-km durability simultaneously. OEM PPAP and IATF 16949 qualification for a new sealing compound routinely runs 18 to 36 months before a single program launches. Accelerated-aging and dielectric testing add an estimated 8% to 12% to program development cost and stretch time-to-revenue for qualifying suppliers.
Material and tooling revalidation must restart each time cell chemistry, pack architecture, or coolant formulation changes, creating repeated qualification cycles with no revenue bridge between them. Capturing EV content upside therefore requires sustained R&D reinvestment of an estimated 4% to 7% of sealing-segment revenue into dedicated EV materials labs. Specialty elastomer supply concentration imposes an additional -0.8% CAGR drag by limiting the number of qualified raw-material sources for high-performance compounds.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| EV-Grade Material Qualification Lag | -1.1% | EU, North America, Japan | Long term (≥ 4 years) |
| Specialty Elastomer Supply Concentration | -0.8% | Global | Medium term (2–4 years) |
| Sealing & Materials Engineering Talent Deficit | -0.6% | North America, EU, India | Long term (≥ 4 years) |
| Cross-Border Logistics & Lead-Time Drag | -0.5% | Asia-Pacific to West | Medium term (2–4 years) |
| Aftermarket Counterfeit Penetration | -0.4% | India, Southeast Asia, Africa | Long term (≥ 4 years) |
Opportunities
Dedicated cell-to-cell and pack-level fire-barrier sealing remains largely unspecified across legacy EV platforms, creating a new monetization layer for suppliers that pre-qualify intumescent gaskets, ceramic-filled silicone barriers, and multi-functional seal-plus-firewall modules. This product category shifts unit economics from a commodity elastomer part toward an engineered assembly with an estimated 2x to 4x price uplift per application. Margin expansion of an estimated 400 to 700 basis points above standard sealing lines is available to suppliers that act before OEM designs freeze.
Localized manufacturing and nearshoring roll-ups offer a +1.1% CAGR upside concentrated in North America, India, and Mexico, where OEMs are actively shortening sealing supply chains to reduce tariff exposure and lead-time risk. Suppliers that execute regional capacity additions within the current 2-to-4-year window capture OEM preferred-supplier status ahead of the next platform sourcing cycle. Thermal-runaway and fire-barrier sealing systems carry the highest single opportunity value at +1.7% CAGR upside on top of the 5.4% baseline.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Thermal-Runaway & Fire-Barrier Sealing Systems | +1.7% | China, EU, North America | Medium term (2–4 years) |
| Localized Manufacturing & Nearshoring Roll-Ups | +1.1% | North America, India, Mexico | Medium term (2–4 years) |
| Sustainable & Recyclable Sealing Materials | +0.8% | EU, Japan | Long term (≥ 4 years) |
| Digital Aftermarket & e-Commerce Channels | +0.6% | India, Southeast Asia | Long term (≥ 4 years) |
| Hydrogen Fuel-Cell Sealing Adjacency | +0.5% | Japan, South Korea, EU | Long term (≥ 4 years) |
Key Company Insights
Freudenberg Sealing Technologies GmbH & Co. KG generated sales of EUR 11.7319 billion and operating profit of EUR 1.0927 billion in 2025, backed by R&D investment of EUR 579.5 million, equal to 4.9% of sales. This R&D intensity exceeds most Tier 1 sealing peers and directly funds EV-grade material qualification programs. On 25 July 2025, Freudenberg announced a double-digit-million investment to transform its Manchester facility, targeting annual production of more than 100 million gaskets for e-mobility and hydrogen applications.
Trelleborg AB, operating through Trelleborg Sealing Solutions, generated approximately SEK 34 billion in sales in 2025 across around 40 countries, providing geographic diversification that limits regional demand concentration risk. Dana Incorporated reported sales of USD 7.5 billion and adjusted EBITDA of USD 610 million in 2025, representing an 8.1% adjusted EBITDA margin, while ElringKlinger generated EUR 1.641 billion in revenue at a 5.4% adjusted EBIT margin. Parker-Hannifin achieved net sales of USD 19.85 billion in FY2025 with a 26.1% adjusted segment operating margin, the highest among disclosed peers, reflecting its diversified industrial sealing base beyond automotive.
NOK Group deployed JPY 52.399 billion in capital investment in 2025, up 15.9%, primarily expanding production capacity in Japan, China, and Southeast Asia. SKF generated net sales of SEK 91.583 billion in 2025, with its Automotive business recording Q4 2025 sales of SEK 6.031 billion versus SEK 7.217 billion one year earlier, signaling automotive segment pressure. MAHLE generated EUR 11.257 billion in sales at a 3.9% adjusted EBIT margin in 2025, while Cooper Standard reported Q4 2025 sales of USD 672.4 million, up 1.8% year over year.
Key Players
- Freudenberg Sealing Technologies GmbH & Co. KG
- Trelleborg AB — Trelleborg Sealing Solutions
- Dana Incorporated — Victor Reinz
- ElringKlinger AG
- NOK Corporation
- Parker-Hannifin Corporation
- Hutchinson S.A.
- Sumitomo Riko Company Limited
- SKF Group
- Tenneco Inc. — Federal-Mogul
- Datwyler Holding Inc.
- Cooper-Standard Holdings Inc.
- Toyoda Gosei Co., Ltd.
- MAHLE GmbH
- BRUSS Sealing Systems GmbH
Recent Developments
- 29 March 2026 – Freudenberg disclosed approximately EUR 800 million of acquisitions completed during 2025, signaling an active consolidation strategy to broaden its sealing technology portfolio ahead of accelerating EV program sourcing cycles.
- 8 May 2025 – Trelleborg completed the Aero-Plastics acquisition; the acquired company generated approximately SEK 150 million in 2024 sales, extending Trelleborg’s engineered plastics capabilities within its sealing solutions division.
- 21 January 2026 – Dana announced completion of its Off-Highway business sale at an enterprise value of USD 2.7 billion, sharpening its focus on on-highway powertrain and sealing programs with higher EV content potential.
- 6 May 2026 – Cooper Standard announced USD 127.9 million in net new business awards alongside first-quarter 2026 sales of USD 686.4 million, demonstrating continued OEM sourcing wins despite broader industry disruption.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2026) | USD 32.0 Billion |
| Forecast Revenue (2035) | USD 51.5 Billion |
| CAGR (2026-2035) | 5.4% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Type (Gaskets, Seals), By Material (Elastomers and Rubber, Metallic, Fibers and Graphite, Plastic and Composites), By Application (Engine and Powertrain, Transmission and Steering, EV Battery and Thermal Management, Chassis and Auxiliary, Others), By Vehicle Type (Passenger Cars: Sedans, Hatchbacks, SUVs; Commercial Vehicles: LCVs, Medium- and Heavy-Duty Trucks and Buses, Others), By Sales Channel (OEM, Aftermarket) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Freudenberg Sealing Technologies GmbH & Co. KG, Trelleborg AB, Dana Incorporated, ElringKlinger AG, NOK Corporation, Parker-Hannifin Corporation, Hutchinson S.A., Sumitomo Riko Company Limited, SKF Group, Tenneco Inc., Datwyler Holding Inc., Cooper-Standard Holdings Inc., Toyoda Gosei Co. Ltd., MAHLE GmbH, BRUSS Sealing Systems GmbH |
| Customization Scope | Customization for segments, region/country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








