


Market Overview
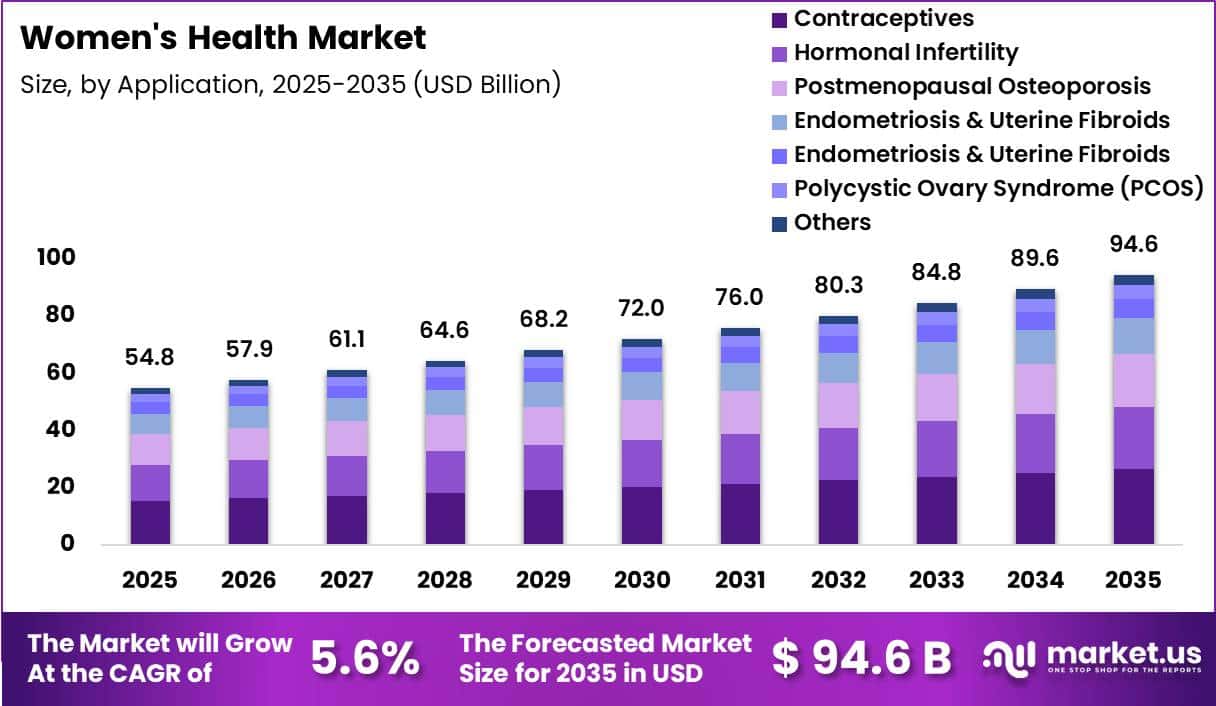
Global Women’s Health Market size is expected to be worth around US$ 94.6 Billion by 2035 from US$ 54.8 Billion in 2025, growing at a CAGR of 5.6% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 42.9% share with a revenue of US$ 23.5 Billion.
The Women’s Health Market is witnessing steady growth as healthcare systems, governments, and medical organizations increasingly focus on improving women’s health outcomes across reproductive care, maternal health, chronic disease management, diagnostics, and preventive healthcare.
Women’s health includes a wide range of services such as fertility care, contraception, pregnancy care, menopause management, gynecological disorders, breast cancer screening, and personalized treatments throughout different life stages.
Rising awareness about preventive healthcare and early diagnosis is driving demand for advanced women-centric medical solutions. According to the World Health Organization (WHO), approximately 260,000 women died in 2023 due to pregnancy and childbirth-related complications, highlighting the continued need for improved maternal healthcare access, skilled birth assistance, and innovative treatment approaches.
WHO also reported that global maternal mortality declined by around 40% between 2000 and 2023, supported by better healthcare services and improved access to essential maternal care.
Technological advancements are transforming the women’s healthcare landscape through digital health platforms, remote monitoring, AI-based diagnostics, and personalized medicine. Healthcare providers are increasingly adopting data-driven approaches to address conditions such as reproductive disorders, hormonal imbalances, and women-specific chronic diseases.
The U.S. Centers for Disease Control and Prevention (CDC) highlights the importance of research, prevention programs, education, and healthcare strategies focused on improving women’s health outcomes.
Growing government initiatives, increased healthcare investments, and rising demand for specialized treatments are expected to support the expansion of the women’s health market. The sector continues to evolve toward accessible, preventive, and patient-focused healthcare solutions worldwide.
Key Takeaways
- Market Size: Global Women’s Health Market size is expected to be worth around US$ 94.6 Billion by 2035 from US$ 54.8 Billion in 2025.
- Market Share: The market is growing at a CAGR of 5.6% during the forecast period from 2026 to 2035.
- Application: The application segment of the Women’s Health Market is led by Contraceptives, which accounted for 28.2% of the market share in 2025.
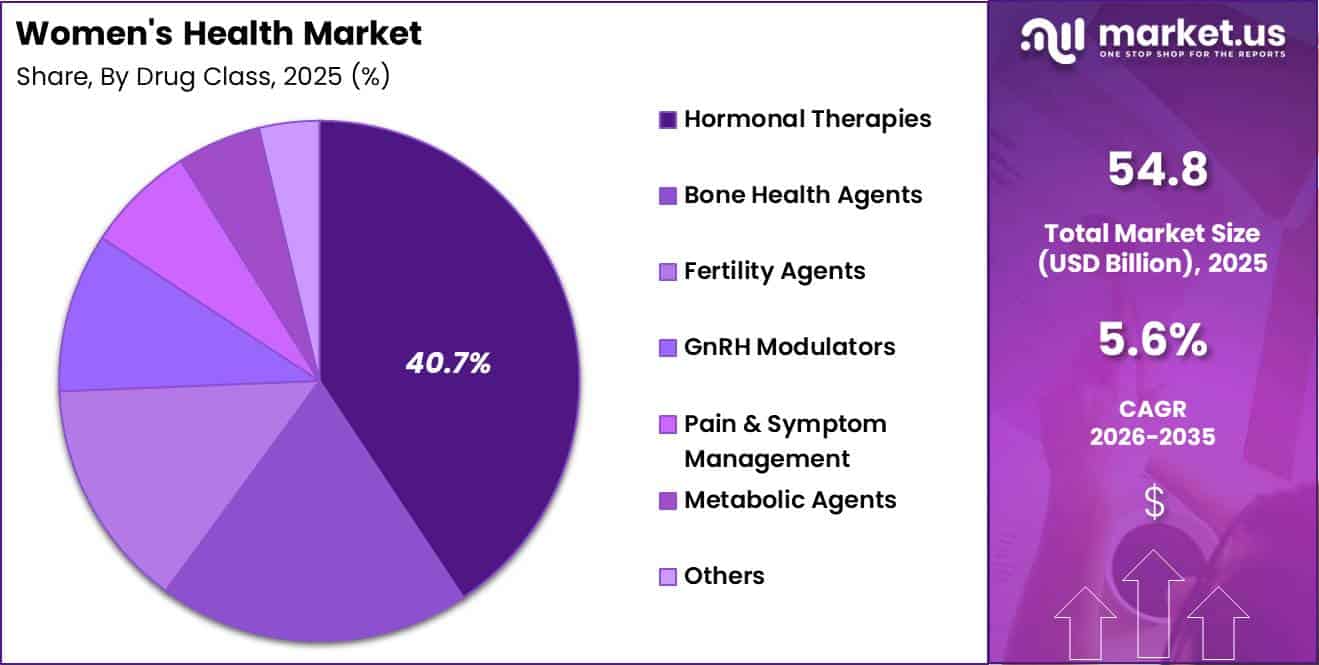
- Drug Class: The Drug Class segment of the Women’s Health Market is dominated by Hormonal Therapies, which held a 40.7% market share in 2025.
- Age Group: Age Group segment of the Women’s Health Market is led by Below 50 Years, which accounted for 58.2% of the market share in 2025.
- Distribution Channel: The Distribution Channel segment of the Women’s Health Market is dominated by Hospital Pharmacies, which held a 47.1% market share in 2025.
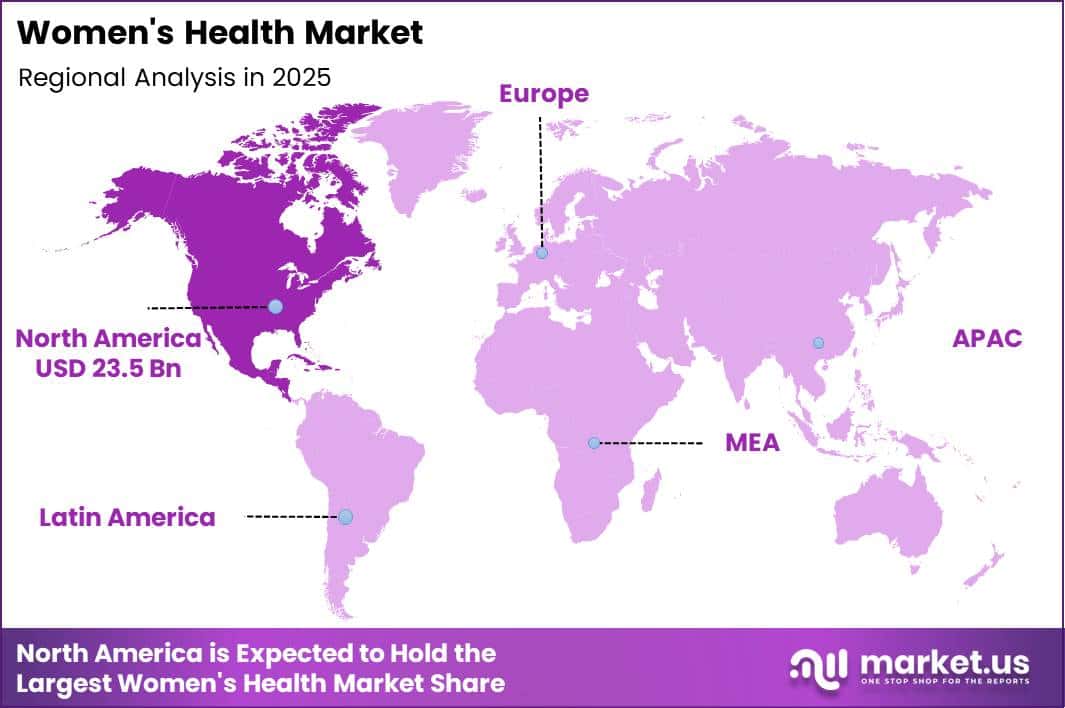
- Regional Analysis: In 2025, North America led the market, achieving over 42.9% share with a revenue of US$ 23.5 Billion.
Application Analysis
Application segment of the Women’s Health Market is led by Contraceptives.
The application segment of the Women’s Health Market is led by Contraceptives, which accounted for 28.2% of the market share in 2025. The dominance of this segment is attributed to increasing awareness regarding family planning, improved access to reproductive healthcare services, and rising demand for safe and effective birth control solutions.
Governments and healthcare organizations continue to promote contraceptive education and availability, supporting market growth. Hormonal Infertility represented 22.9% of the market, driven by increasing infertility cases, delayed pregnancies, and advancements in assisted reproductive treatments.
Postmenopausal Osteoporosis held 19.6% share due to growing concerns regarding bone health among aging women and rising adoption of preventive therapies. Endometriosis & Uterine Fibroids accounted for 13.2%, supported by improved diagnosis and treatment options for women’s reproductive disorders.
The Menopause segment contributed 7.1% as demand for symptom management therapies increased. Polycystic Ovary Syndrome (PCOS) captured 5.3% share, supported by rising awareness and healthcare screening initiatives.
Other applications contributed 3.7%, including various specialized women’s health conditions. Overall, increasing healthcare access and personalized treatment approaches are strengthening application-based growth across the market.
Drug Class Analysis
Drug Class segment of the Women’s Health Market is dominated by Hormonal Therapies.
The Drug Class segment of the Women’s Health Market is dominated by Hormonal Therapies, which held a 40.7% market share in 2025. The leading position of this segment is supported by widespread use in contraception, menopause management, hormone-related disorders, and fertility treatments. Increasing demand for targeted hormonal solutions and advancements in women-specific therapies are driving segment expansion.
Bone Health Agents accounted for 19.4% of the market, fueled by rising cases of osteoporosis among postmenopausal women and growing adoption of preventive treatments. Fertility Agents represented 14.3% due to increasing infertility rates and higher utilization of assisted reproductive technologies.
GnRH Modulators contributed 9.9%, mainly used for conditions such as endometriosis, uterine fibroids, and hormone-dependent disorders. Pain & Symptom Management drugs captured 6.8% share, supported by demand for treatments addressing menstrual disorders and chronic symptoms.
Metabolic Agents accounted for 5.2%, particularly benefiting from increased focus on PCOS-related metabolic complications. Other drug classes contributed 3.7%, including emerging therapies targeting specific women’s health conditions. Continuous pharmaceutical innovation and personalized treatment approaches are expected to enhance market growth.
Age Group Analysis
Age Group segment of the Women’s Health Market is led by Below 50 Years.
The Age Group segment of the Women’s Health Market is led by Below 50 Years, which accounted for 58.2% of the market share in 2025. The dominance of this segment is primarily driven by higher demand for reproductive health services, contraceptive solutions, fertility treatments, and management of hormonal disorders among younger women. Increasing awareness about preventive healthcare, family planning, and early diagnosis of conditions such as PCOS and endometriosis is supporting market expansion in this age category.
The 50 Years & Above segment represents a significant growth opportunity due to rising healthcare needs associated with menopause, osteoporosis, cardiovascular risks, and age-related hormonal changes. Growing life expectancy and increasing focus on healthy aging are encouraging women in this age group to seek advanced treatment options and long-term disease management solutions.
Healthcare providers are increasingly emphasizing personalized therapies and preventive screening programs across different age categories. While younger women currently generate the highest market demand, the aging female population is expected to accelerate growth in therapies related to menopause management, bone health, and chronic women’s health conditions.
Distribution Channel Analysis
Distribution Channel segment of the Women’s Health Market is dominated by Hospital Pharmacies.
The Distribution Channel segment of the Women’s Health Market is dominated by Hospital Pharmacies, which held a 47.1% market share in 2025. The strong position of hospital pharmacies is attributed to increased patient visits, availability of prescription-based women’s health medications, and direct access to healthcare professionals.
Hospitals play a crucial role in providing specialized treatments related to infertility, hormonal disorders, menopause, and reproductive health conditions, supporting higher product adoption through this channel.
Retail Pharmacies represent another important distribution channel due to their convenience, widespread availability, and accessibility for over-the-counter women’s health products and routine medications. The growth of retail pharmacies is supported by increasing healthcare awareness and demand for easily accessible treatments.
Online Pharmacies are gaining momentum as digital healthcare adoption increases, offering benefits such as home delivery, improved accessibility, and convenient medication purchasing.
Rising internet penetration and the expansion of e-pharmacy platforms are encouraging consumers to adopt online channels for women’s health products. Overall, hospitals remain the leading channel, while retail and online pharmacies are expected to experience steady growth through improved accessibility and digital healthcare integration.
Key Market Segments
By Application
- Contraceptives
- Hormonal Infertility
- Postmenopausal Osteoporosis
- Endometriosis & Uterine Fibroids
- Menopause
- Polycystic Ovary Syndrome (PCOS)
- Others
By Drug Class
- Hormonal Therapies
- Bone Health Agents
- Fertility Agents
- GnRH Modulators
- Pain & Symptom Management
- Metabolic Agents
- Others
By Age Group
- Below 50 Years
- 50 Years & Above
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
Drivers
Menopause care moves from underdiagnosed symptom management to scalable therapy pathways.
Menopause is becoming one of the clearest growth engines because it converts a historically under-served life stage into a recurring care pathway spanning symptom assessment, hormone and non-hormone therapy, sleep and mood support, bone and cardiovascular risk surveillance, and digital follow-up.
NIH notes that about 1.5 million women experience the menopause transition each year in the U.S., women typically enter menopause between ages 49 and 52 with an average age of 51, and common symptom clusters include vasomotor events, sleep disruption, mood change, vaginal symptoms, and sexual dysfunction.
Published studies in 2025 further report symptom prevalence rates around 46.3% in a large Chinese sample and broad ranges of 50% to 75% for vasomotor and genitourinary symptoms, indicating a large treatable pool rather than a narrow specialty segment.
The strategic effect is a migration from fragmented over-the-counter symptom relief to protocolized platforms with annual membership, prescription management, testing, and referral economics.
Companies that position menopause as a chronic-care workflow can raise revenue per user through layered services while also lowering churn because treatment titration, follow-up, and comorbidity surveillance create repeat touchpoints over several years.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Women-centered cardiometabolic burden expands routine care demand | +1.4% | North America core, EU, urban APAC | Short term (≤ 2 years) |
| Menopause care moves from underdiagnosed symptom management to scalable therapy pathways | +1.2% | North America core, EU, developed APAC | Medium term (2-4 years) |
| CMS/FDA digital-care alignment improves commercialization of remote women’s health management | +1.0% | U.S. core, EU spill-over, APAC digital corridors | Short term (≤ 2 years) |
| Fertility delay and one-in-six infertility burden sustain diagnostics and treatment intensity | +0.9% | North America, EU, East Asia, affluent GCC | Medium term (2-4 years) |
| Maternal safety and postpartum hemorrhage protocols upgrade obstetric care spending | +0.8% | South Asia, Africa, LATAM, U.S. hospital systems | Short term (≤ 2 years) |
| Long-acting contraception and heavy-bleeding treatment broaden lifetime value per patient | +0.7% | North America, EU, Latin America, selected APAC | Medium term (2-4 years) |
Challenge
Fragmented Care Pathways Limit Women’s Health Growth Potential.
Fragmented care pathways in women’s health manifest as multi-provider, multi-setting journeys where a single episode of care can involve more than 5 distinct touchpoints across primary care, specialist gynecology, mental health, and imaging, with average diagnostic delays of 3–7 years reported for conditions such as endometriosis and certain autoimmune disorders.
This fragmentation produces measurable friction care coordination failures increase no-show rates by 10–15%, duplicate diagnostics can add 8–12% to episode-of-care costs, and poorly orchestrated transitions between community clinics and hospital systems drive avoidable emergency visits, which, in women aged 25–44, can be 20–25% higher where integrated care models are absent.
At a market level, this erodes the conversion of awareness into treated prevalence. Screening programs may reach 60–70% of target populations, yet only 50–55% transition into guideline-concordant treatment, effectively shaving 1–2% points off realizable growth versus theoretical demand expansion. Strategic mitigation requires aggressive deployment of episode-based care pathways, shared care plans, and centralized navigation.
Health systems that invest in dedicated care coordinators, standardized referral protocols, and interoperable scheduling platforms typically reduce diagnostic latency by 20–30% and cut redundant imaging and lab work by 15–20%, which over a 3–4-year horizon translates into consistent volume growth and a reduction of friction drag toward the 0.5–0.7% range.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Fragmented care pathways | -1.4% | North America, EU, emerging APAC | Medium term (2-4 years) |
| Chronic workforce gaps | -1.6% | Global tertiary & primary care hubs | Long term (≥ 4 years) |
| Data interoperability deficit | -1.2% | US, EU, APAC digital corridors | Medium term (2-4 years) |
| Socio-cultural underdiagnosis | -1.0% | Global, high in LMICs | Long term (≥ 4 years) |
| Value-based payment complexity | -0.8% | US, OECD payers | Medium term (2-4 years) |
| Regulatory evidence bottlenecks | -0.9% | US, EU, major regulators | Long term (≥ 4 years) |
Restraints
Regulatory Complexity Increases Women’s Health Development Barriers.
The second restraint stems from regulatory complexity and the elevated burden of generating sex-specific clinical evidence for women’s health therapeutics, devices, and digital tools, a challenge that has intensified as FDA’s Office of Women’s Health and parallel EU bodies push for robust sex-difference analyses and adequate female representation across trial phases.
While these initiatives are scientifically necessary, they materially raise development costs: sponsors now routinely target ≥50–55% female enrollment in relevant indications, which can increase screening and recruitment expenditures by 10–20% versus historical mixed-sex trials, and add 6–12 months to timelines where regulatory agencies request dedicated subgroup analyses or post-marketing commitments focused on pregnancy, lactation, and menopausal cohorts.
For smaller biopharma and device companies, this converts into incremental trial budgets of USD 20–50 million for late-stage assets, lifting risk-adjusted development cost per approved women’s health product into the USD 600–800 million band and pushing internal hurdle rates up by 200–300 basis points, thereby narrowing the pipeline to indications with clear blockbuster potential while leaving many mid-prevalence gynecologic or menopausal conditions under-served.
At the same time, multi-jurisdictional compliance, coordinating FDA, EMA, PMDA, and emerging digital health frameworks, forces sponsors to run overlapping observational registries or device post-market surveillance programs, often doubling safety data-management volumes and adding 5–10% to ongoing pharmacovigilance OPEX as they scale into the US, EU, and Japan in parallel.
Strategically, this regulatory friction delays new product launches by 1–2 years in key markets, compresses the effective exclusivity window, and reduces lifetime net present value of women’s health assets by 10–15%, which in turn cools investment appetites and reallocates capital toward less complex therapeutic categories; together these dynamics justify an estimated 1.2-%-point drag on global women’s health CAGR over the medium-term horizon.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fragmented reimbursement & coverage | -1.5% | North America core, EU, select LATAM | Medium term (2–4 years) |
| Regulatory complexity & trial burden | -1.2% | US, EU, Japan, Tier-1 APAC | Medium term (2–4 years) |
| Access gaps & care delivery barriers | -1.0% | US, UK, EM urban–rural corridors | Long term (≥ 4 years) |
| Underinvestment & funding concentration | -0.8% | Global, especially EM & non-fertility segments | Long term (≥ 4 years) |
| Supply chain & affordability pressures | -0.6% | Global, with higher impact in EM | Short–Medium term (≤ 4 years) |
| Data fragmentation & sex-specific evidence gaps | -0.5% | Global, especially multi-country programs | Long term (≥ 4 years) |
Opportunity
Data-Rich Femtech Enables Clinically Integrated Women’s Care.
Most current femtech offerings focus on consumer-grade tracking of menstruation, fertility, and pregnancy with limited clinical-grade validation, resulting in a disconnect between highly engaged users and formal healthcare systems and leaving a large monetization gap in person-generated health data that could be converted into reimbursable, clinically actionable services.
Reviews of PGHD in women’s health and frameworks for femtech emphasize that apps generate rich time-series data, cycles, symptoms, mood, and activity, but lack standardized protocols for clinical ingestion, decision support, and outcome measurement, which means that obstetricians and gynecologists rarely bill or manage based on femtech data despite tens of millions of active users.
This untapped opportunity lies in building a “clinical-grade femtech stack” with validated algorithms, interoperable data formats, and regulatory-compliant workflows that plug directly into electronic health records and decision-support tools, enabling clinicians to monitor pregnancy risk scores, fertility treatment progress, and menopause symptom trends with automated alerts and reimbursable remote monitoring codes.
If 15–20% of existing femtech users are converted into hybrid clinical programs with monthly subscriptions of USD 15–25 plus payer-covered monitoring fees, platforms could add USD 5–10 billion in annual recurring revenue globally by 2035, with operating margins potentially 5–8 % points higher than traditional clinic-based care due to low marginal data and software costs.
Because current baseline market forecasts for women’s health and women’s digital health mostly assume continued consumer-driven adoption and modest clinical overlap, creating clinically integrated, data-rich femtech networks is a forward-looking strategic pivot rather than a driver and could credibly add around +2.2 % points to segment CAGR for early movers, especially in North America, the EU, and digitally maturing APAC markets over the next two years as regulatory guidance on digital health and PGHD matures.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Integrated NCD–Reproductive Care Platforms | +2.5% | North America, EU, APAC urban | Medium term (2–4 years) |
| Data-Rich Femtech for Clinical Integration | +2.2% | North America core, EU, APAC emerging | Short term (≤ 2 years) |
| Value-Based Maternal Care Ecosystems | +1.8% | North America, Latin America, Sub-Saharan Africa | Medium term (2–4 years) |
| Midlife & Menopause Performance Health | +1.6% | North America, EU, High-income APAC | Short term (≤ 2 years) |
| Employer-Backed Women’s Health Benefits Platforms | +1.4% | North America, EU, India metros | Medium term (2–4 years) |
| Low-Cost Hybrid Models for Underserved Women | +1.3% | South Asia, Sub-Saharan Africa, Latin America | Long term (≥ 4 years) |
Regional Analysis
In 2025, North America dominated the Women’s Health Market in 2025.
North America dominated the Women’s Health Market in 2025, accounting for more than 42.9% of the global market share with revenue of approximately US$ 23.5 Billion.
The region’s leadership is supported by advanced healthcare infrastructure, high awareness regarding women’s health conditions, strong adoption of innovative therapies, and increasing investments in reproductive health, menopause care, oncology, and personalized medicine.
The presence of leading pharmaceutical and biotechnology companies, including Bayer AG, Pfizer Inc., AbbVie Inc., Merck & Co., Inc., and Organon & Co., further strengthens regional market growth through continuous research, product development, and strategic collaborations.
The increasing prevalence of women-specific health concerns, such as breast cancer, osteoporosis, infertility, and hormonal disorders, has accelerated demand for advanced diagnostic solutions, therapeutics, and preventive healthcare services across the region.
Supportive healthcare policies, improved insurance coverage, and greater participation of women in clinical research are also contributing to market expansion. Additionally, the growing focus on digital health platforms, telemedicine services, and AI-enabled healthcare solutions is improving access to specialized women’s healthcare services.
The United States remains the major contributor within North America due to its high healthcare expenditure, strong pharmaceutical ecosystem, and rapid adoption of innovative medical technologies. Canada also contributes to regional growth through government-supported healthcare programs and increasing awareness initiatives focused on women’s wellness and preventive care.
Overall, North America is expected to maintain its leading position as companies continue investing in advanced therapies, personalized healthcare approaches, and integrated women’s health solutions.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The Women’s Health Market is moderately consolidated, with major pharmaceutical companies competing through advanced therapeutics, reproductive health solutions, hormonal treatments, fertility care, and disease-specific innovations.
Competitive dynamics are shaped by strong R&D capabilities, expanding product portfolios, strategic collaborations, and efforts to address unmet healthcare needs across contraception, menopause management, fertility, and women-specific diseases. Companies are increasingly focusing on personalized medicine, clinical advancements, and integrated healthcare ecosystems to strengthen their market position.
Key players are investing significantly in research and development to introduce innovative therapies and improve treatment outcomes. Bayer AG, Pfizer Inc., Amgen Inc., and AbbVie Inc. are advancing women-focused therapies through scientific innovation and portfolio expansion.
Merck & Co., Inc. and Eli Lilly and Company are strengthening their presence through research-driven healthcare solutions. Ferring Pharmaceuticals and Myovant Sciences (Pfizer) focus on reproductive health and specialized treatment areas. Organon & Co., TherapeuticsMD, Inc., Theramex Group, and Mithra Pharmaceuticals SA emphasize product innovation, partnerships, and broader access to women’s healthcare solutions.
Competitive strategies increasingly include collaborations, lifecycle management, digital healthcare integration, and ecosystem-based approaches to improve patient outcomes and expand global reach.
Top Key Players
- Bayer AG
- Pfizer Inc.
- Amgen Inc.
- AbbVie Inc.
- Merck & Co., Inc.
- Eli Lilly and Company
- Ferring Pharmaceuticals
- Myovant Sciences (Pfizer)
- Organon & Co.
- TherapeuticsMD, Inc.
- Theramex Group
- Mithra Pharmaceuticals SA
Recent Developments
- In April 2026, Organon announced a definitive agreement to be acquired by Sun Pharmaceutical Industries in an all-cash transaction valued at approximately $11.75 billion enterprise value. The acquisition strengthens Sun Pharma’s position in women’s health, biosimilars, and specialty healthcare segments while expanding global access to Organon’s portfolio.
- In March 2025, Amgen reported progress in its clinical development programs, including advancement of late-stage studies for new therapies. The company continued investment in research capabilities, reflecting broader pharmaceutical efforts to develop next-generation treatments for complex health conditions affecting women and other patient groups.
- In January 2025, AbbVie strengthened its research pipeline through strategic acquisitions and collaborations, including the acquisition of Nimble Therapeutics for approximately $200 million and a $1.64 billion partnership with Neomorph focused on advanced drug discovery platforms. These moves support AbbVie’s long-term strategy of expanding innovative therapies across multiple healthcare areas.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$54.8 Billion |
| Forecast Revenue (2035) | US$94.6 Billion |
| CAGR (2026-2035) | 5.6% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Application (Contraceptives, Hormonal Infertility, Postmenopausal Osteoporosis, Endometriosis & Uterine Fibroids, Menopause, Polycystic Ovary Syndrome (PCOS), Others), By Drug Class (Hormonal Therapies, Bone Health Agents, Fertility Agents, GnRH Modulators, Pain & Symptom Management, Metabolic Agents, Others), By Age Group (Below 50 Years, 50 Years & Above), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Bayer AG, Pfizer Inc., Amgen Inc., AbbVie Inc., Merck & Co., Inc., Eli Lilly and Company, Ferring Pharmaceuticals, Myovant Sciences (Pfizer), Organon & Co., TherapeuticsMD, Inc., Theramex Group, Mithra Pharmaceuticals SA |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








