


Market Overview
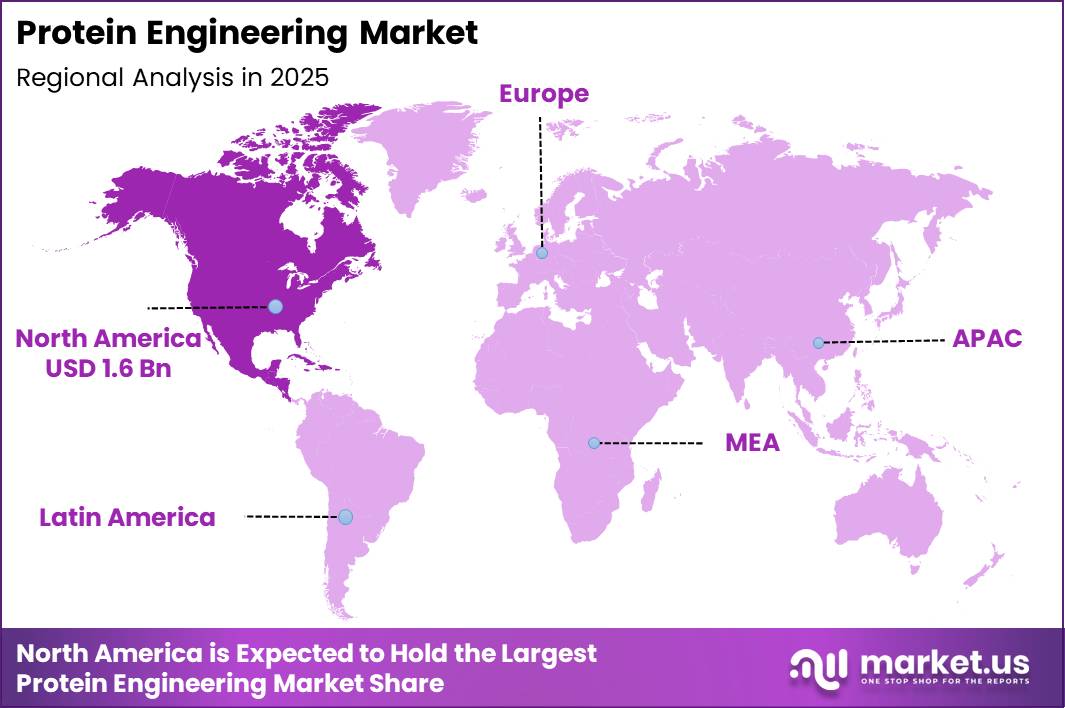
Global Protein Engineering Market size is expected to be worth around US$ 14.3 Billion by 2035 from US$ 3.3 Billion in 2025, growing at a CAGR of 15.7% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 49.3% share with a revenue of US$ 1.6 Billion.
The global protein engineering market is experiencing strong growth due to rapid advancements in biotechnology, synthetic biology, and computational approaches that enable the modification and design of proteins with improved biological properties.
Protein engineering focuses on altering amino acid sequences or creating novel protein structures to enhance stability, activity, selectivity, and therapeutic effectiveness. These technologies are increasingly being adopted across pharmaceuticals, biotechnology research, industrial enzymes, diagnostics, and vaccine development.
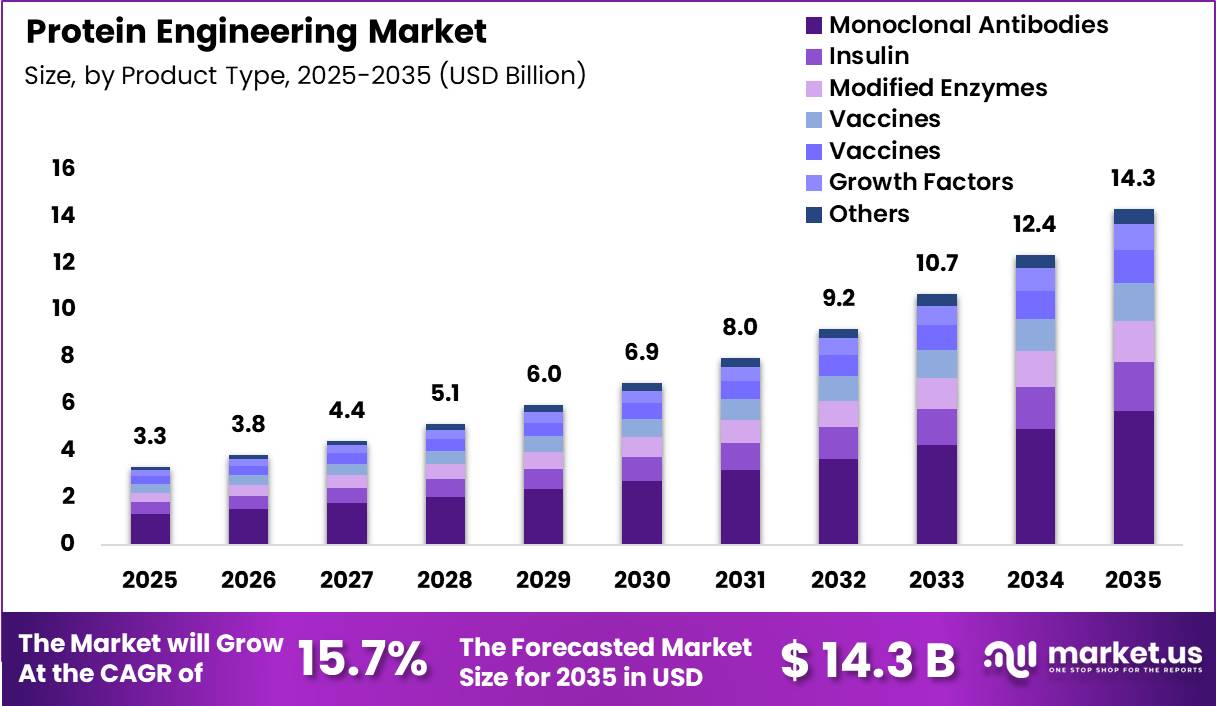
The healthcare sector represents a major area of application, as engineered proteins support the development of biologic medicines, antibody-based therapies, enzyme replacement treatments, and next-generation vaccines.
According to the National Institutes of Health (NIH), advances in protein design and molecular engineering are contributing to innovations in therapeutic discovery, including improved biologics and precision medicine approaches. The U.S. Food and Drug Administration (FDA) continues to regulate and approve biologic products, supporting the expansion of protein-based drug development pipelines.
Increasing investments in artificial intelligence (AI)-based protein structure prediction, high-throughput screening platforms, and synthetic biology tools are transforming traditional protein discovery processes. The National Science Foundation (NSF) has highlighted the importance of biotechnology research and computational methods in accelerating biological innovation.
Protein engineering is also gaining importance in industrial biotechnology, where engineered enzymes are used in applications such as sustainable manufacturing, food processing, biofuels, and environmental solutions. Growing research collaborations between academic institutions, biotechnology companies, and healthcare organizations are further accelerating technology adoption.
With rising demand for targeted therapies, advanced biologics, and sustainable biological solutions, protein engineering is expected to remain a key technology area supporting future developments in medicine, life sciences, and industrial applications.
Key Takeaways
- Market Size: The Protein Engineering Market size was US$ 3.3 Billion in 2025.The market is estimated to grow to US$ 14.3 Billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 15.7%.
- By Protein Type: Monoclonal Antibodies has the largest market share, accounting for 39.8% of total sales.
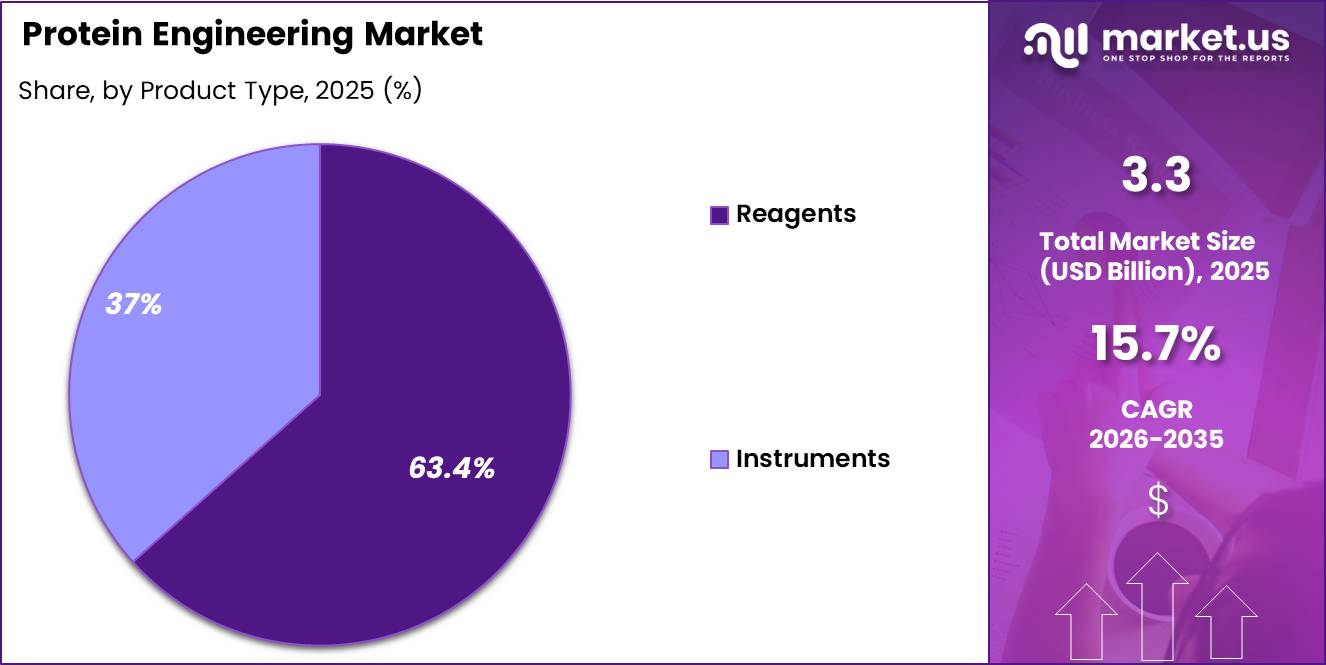
- By Product Type: Reagents the segment, accounting for 63.4% of total revenue.
- By Method: Rational Protein Design leads the segment, accounting for 41.3% of total revenue.
- By End User: Pharmaceutical and Biotechnology Companies leads the segment, accounting for 54.1% of total revenue.
- Regional: North America is the dominant regional market,accounting for 49.3% of global sales.
Protein Type Analysis
The Protein Engineering Market is segmented by protein type into Monoclonal Antibodies, Insulin, Modified Enzymes, Coagulation Factors, Vaccines, Growth Factors, and Others. Among these, Monoclonal Antibodies dominate the market with a 39.8% share in 2025, driven by their extensive application in targeted therapies, oncology treatments, autoimmune disease management, and advanced biologics development.
Continuous innovation in antibody engineering, including antibody-drug conjugates and next-generation therapeutic antibodies, is supporting strong adoption across pharmaceutical pipelines.
Insulin holds a 14.6% share, supported by rising demand for engineered insulin analogs for diabetes management and improved patient-specific treatment approaches. Modified Enzymes account for 12.3%, benefiting from applications in enzyme replacement therapies, industrial biotechnology, and metabolic disorder treatments.
Vaccines represent 11.2%, with protein engineering enabling the development of recombinant and highly targeted vaccine candidates. Coagulation Factors contribute 9.7%, supported by engineered therapies for bleeding disorders such as hemophilia.
Growth Factors hold 7.8%, driven by regenerative medicine and tissue engineering applications, while Others account for 4.6%, including emerging engineered proteins used in research and therapeutic development. Increasing demand for precision medicine and biologics continues to expand opportunities across all protein categories.
Product Type Analysis
The Protein Engineering Market is segmented by product type into Reagents and Instruments. Among these, Reagents dominate the market with a 63.4% share in 2025, owing to their essential role in protein modification, expression, purification, sequencing, and characterization processes.
Protein engineering workflows rely heavily on specialized reagents such as enzymes, buffers, expression systems, and molecular biology kits, making them a recurring requirement across academic research institutions, biotechnology companies, and pharmaceutical laboratories. The increasing adoption of advanced protein design platforms and synthetic biology techniques is further driving demand for high-quality reagents.
Instruments account for 36.6% of the market in 2025, supported by growing investments in automated protein analysis systems, high-throughput screening platforms, mass spectrometry technologies, and structural biology equipment. Advanced instrumentation enables researchers to evaluate protein structures, interactions, and functional properties with improved accuracy and efficiency.
The expansion of biologics research, drug discovery programs, and personalized medicine initiatives is increasing the need for sophisticated laboratory technologies. While reagents maintain a larger share due to their frequent usage, instruments are expected to experience steady growth as automation, artificial intelligence integration, and next-generation protein engineering platforms become more widely adopted.
Method Analysis
The Protein Engineering Market is segmented by method into Rational Protein Design, Directed Evolution, and Computational Protein Engineering approaches. Among these methods, Rational Protein Design dominates the market with a 41.3% share in 2025, supported by its ability to develop targeted protein modifications through structural analysis, molecular modeling, and biological understanding. This approach enables researchers to introduce specific changes in amino acid sequences to improve protein stability, activity, selectivity, and therapeutic performance.
Directed Evolution represents a significant segment, as it allows the generation and screening of large protein variants to identify improved characteristics without requiring complete structural knowledge. It is widely used in enzyme engineering, antibody optimization, and industrial biotechnology applications.
Computational Protein Engineering is gaining momentum due to advancements in artificial intelligence, machine learning algorithms, and predictive modeling tools that accelerate protein discovery and reduce development timelines.
These technologies enable researchers to simulate protein behavior and identify promising candidates before laboratory validation. The increasing integration of computational platforms with experimental techniques is transforming protein engineering workflows, improving efficiency, and supporting the development of advanced biologics, therapeutics, and research applications.
End User Analysis
The Protein Engineering Market is segmented by end user into Pharmaceutical and Biotechnology Companies, Academic and Research Institutes, and Other Users. Among these, Pharmaceutical and Biotechnology Companies dominate the market with a 54.1% share in 2025, driven by increasing investments in biologics development, precision medicine, and protein-based therapeutics.
These companies extensively utilize protein engineering technologies for designing monoclonal antibodies, vaccines, enzymes, and next-generation therapeutic proteins. Growing demand for innovative treatments in oncology, autoimmune disorders, metabolic diseases, and rare genetic conditions is encouraging pharmaceutical organizations to expand protein engineering capabilities.
Academic and Research Institutes represent another important segment, supported by government-funded research programs, biotechnology innovation, and increasing exploration of protein structures and biological mechanisms. These institutions contribute significantly to early-stage discoveries and technology development.
Other end users, including contract research organizations and diagnostic companies, are adopting protein engineering platforms for specialized research, assay development, and customized biological solutions.
The rising collaboration between pharmaceutical companies, universities, and biotechnology firms is accelerating innovation in engineered proteins. Increasing focus on faster drug discovery, improved therapeutic efficacy, and scalable biologics production is expected to strengthen adoption across all end-user categories.
Market Segmentations
By Protein Type
- Monoclonal Antibodies
- Insulin
- Modified Enzymes
- Coagulation Factors
- Vaccines
- Growth Factors
- Others
By Product Type
- Reagents
- Instruments
By Method
- Rational Protein Design
- De Novo Protein Design
- Direct Evolution
By End User
- Pharmaceutical and Biotechnology Companies
- Contract Research Organizations (CRO)
- Academic Institutions
- Others
Driver
Rising NCD Burden Accelerates Advanced Therapeutics Demand
Non-communicable diseases (NCDs) now account for the majority of global mortality, with analyses indicating more than 43 million NCD deaths in 2021, roughly 65% of all deaths, and projections that NCDs will kill around 52 million people annually by 2030.
This structural disease burden across cancer, cardiovascular, metabolic, and autoimmune conditions reinforces long-term demand for advanced therapeutics, many of which are biologics or protein-based drugs requiring sophisticated engineering to achieve efficacy, safety, and adherence in diverse patient populations.
For example, engineered enzymes and hormone analogues are used to improve pharmacokinetics and reduce injection frequency, while antibody formats are optimized for subcutaneous delivery, combination regimens, and targeting of challenging antigens.
In lower- and middle-income countries, pooled procurement initiatives for essential NCD drugs and diagnostics aim to leverage volume to lower prices, creating a tension between affordability and the complexity of protein therapeutics.
Over time, this encourages protein engineering solutions focused on manufacturing efficiency, including higher expression titers, simplified purification, and thermostable formulations that reduce cold-chain requirements, so that high-value biologics can be produced at lower marginal cost.
Strategically, biopharma portfolios are re-weighted toward chronic NCD indications, which translates into recurring, large-volume production runs where even 5–10% gains in yield or reductions in failure rates have meaningful impact on gross margins, reinforcing corporate willingness to invest in engineering platforms and integrated design–manufacturing capabilities.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Biologics pipeline expansion & mAbs dominance | +3.0% | North America core, EU, East Asia | Medium term (2–4 years) |
| AI-enabled protein design & high-throughput screening | +2.2% | U.S., EU innovation hubs, APAC corridors | Medium–Long term (2–6+ years) |
| CRISPR/gene editing & synthetic biology platforms | +2.0% | North America, EU, China, Japan | Long term (≥ 4 years) |
| Rising NCD burden driving advanced therapeutics | +1.8% | Global, with LMIC APAC/LatAm/MEA spill-over | Long term (≥ 4 years) |
| Industrial & food enzyme optimization demand | +1.5% | EU, APAC manufacturing belts, North America | Medium term (2–4 years) |
| Public/NIH-style R&D funding & regulatory support | +1.2% | U.S. core, EU, selected APAC | Short–Medium term (≤ 4 years) |
Challenge
Biofoundry Automation Gaps Limit Protein Engineering Scalability
Despite rapid advances in AI-enabled biofoundries, a substantial share of protein engineering activity in 2026 still runs on fragmented, semi-manual labs operating below 40% of feasible throughput, creating systemic friction that subtracts an estimated 1.1 % points from potential market growth by limiting experiment density and slowing iteration.
State-of-the-art biofoundries can execute 10,000–50,000 construct builds and tests per week across microfluidic and robotic platforms, yet in practice many academic and mid-cap industry labs function at 5–20% of that capacity, constrained by capital budgets, with automation lines typically requiring USD 5–15 million per site, integration complexity across LIMS, robotics, and analytical systems, and shortages of automation engineers and data scientists able to maintain end-to-end pipelines.
This throughput gap translates into lower hit discovery rates, such as screens of only 1,000–3,000 variants per campaign rather than 20,000+ variants, longer optimization cycles of 6–8 weeks per design iteration instead of 1–2 weeks on fully automated lines, and higher per-sample costs of USD 30–60 per assay versus USD 5–10 in high-density automated workflows, thereby delaying time-to-candidate selection by 9–12 months across pipelines.
Strategically, frontrunners are investing in centralized biofoundry networks and shared infrastructure models, consolidating experiment capacity across internal portfolios and external partnerships to drive utilization above 60–70%, while layering AI decision systems that reduce failed constructs by 20–30% and rebalance CapEx through multi-tenant usage patterns.
However, diffusion of these models into broader industry, particularly in APAC emerging hubs and smaller EU biotech clusters, will require multi-year standardization of interfaces, skill development, and financing innovations, positioning this friction firmly in the long-term mitigation horizon.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| High-complexity development cycles | -1.3% | North America, EU, Japan | Medium term (2-4 years) |
| Biofoundry & automation gaps | -1.1% | Global R&D hubs, APAC emerging | Long term (≥ 4 years) |
| Advanced talent skills crunch | -1.4% | North America core, EU, India | Long term (≥ 4 years) |
| Regulatory analytics burden | -1.0% | US, EU, Japan, UK | Medium term (2-4 years) |
| Scale-up & manufacturing variability | -1.2% | US, EU, China, India | Long term (≥ 4 years) |
| Data integration & model risk | -0.9% | Global bioinformatics hubs | Medium term (2-4 years) |
Restraints
Volatile R&D Funding Slows Protein Engineering Advancement
Volatile public R&D funding and prospective budget cuts act as a structural brake on protein engineering momentum by directly compressing the capital available for early-stage projects, multi-year platform efforts, and high-risk translational programs, particularly in the United States where NIH and related federal allocations anchor much of the academic and translational ecosystem.
Between FY2024 and FY2026, debate over cuts of up to 30–40% in some proposed federal budgets created a planning overhang that forced universities and institutes to slow hiring, freeze new core facility investments, and stretch grant-supported projects over longer timelines, effectively increasing average project duration by 12–18 months for complex protein design programs reliant on shared infrastructure.
In operational terms, this volatility translates into laboratories delaying purchases of high-throughput screening platforms, cryo-EM upgrades, or AI compute capacity, each often requiring USD 2–5 million in CapEx, leading to underutilization of next-generation protein engineering methods and forcing continued reliance on legacy assays with lower throughput and hit quality.
When NSF, NIH, and foundation calls targeting protein design and understudied proteins cluster around discrete, competitive initiatives, such as a USD 40 million AI-for-protein-design initiative spread over three years and pilot grants in the USD 50,000 range, the result is an hourglass funding profile where a handful of well-positioned centers accelerate while tier-2 and tier-3 institutions operate with annual budget gaps of 10–20% relative to what would be required to fully adopt modern computational and automated workflows.
Strategically, this produces margin compression for service-oriented protein engineering firms that rely on academic collaborations for pipeline feedstock, increases per-program burn rates by 15–25% as companies shoulder more of the discovery burden internally, and delays CapEx decisions on new design labs and GMP-adjacent facilities, particularly in North America and parts of Europe, thereby justifying a 2.0-point downward adjustment to the otherwise mid-teens CAGR in these research-intensive geographies.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatile public R&D funding and budget cuts | -2.0% | North America core, EU research hubs | Medium term (2-4 years) |
| Complex, evolving biologics and gene therapy regulation | -1.5% | North America, EU, Japan | Long term (≥ 4 years) |
| High cost and long lead times for specialized tools | -1.3% | North America, EU, APAC corridors | Medium term (2-4 years) |
| Scarcity of high-end protein design and bioinformatics talent | -1.0% | North America core, EU, select APAC | Long term (≥ 4 years) |
| Ethical and societal concerns around genetic engineering | -0.8% | North America, EU, global policy forums | Long term (≥ 4 years) |
Opportunity
AI-First Protein Platforms Transform De Novo Engineering Growth
This opportunity centers on building AI-native de novo protein design and optimization platforms that treat protein engineering as a programmable design space rather than a lab-first activity, moving revenue from project-based services into scalable software-plus-royalty models with differentiated IP compounds.
Unlike today’s baseline growth, which is largely driven by incremental improvements to therapeutic proteins and enzymes via directed evolution and rational design workflows already embedded in pharma and industrial labs, AI-first platforms apply foundation models and generative algorithms to explore billions of sequence–structure combinations ex ante, compressing design cycles from 24–36 months to 6–12 months and cutting early-stage discovery cost per candidate by 40–60%.
By 2030, realistic deployment across top-50 biopharma, large food, and consumer chemicals manufacturers could expand addressable engineering project volume by 25–30%, with platform vendors capturing monetizable upside via licensing, usage-based compute fees, such as per design call or per successful hit, and downstream royalties on commercialized molecules.
If even 10–15% of global protein engineering spend transitions onto AI-centered platforms with average revenue intensity of 5–8% of engineered product sales, this could contribute roughly USD 3–5 billion incremental TAM by 2035 and support 2 % points of CAGR upside above current forecasts.
Strategically, this is an opportunity rather than a driver because most labs still run fragmented computational workflows and bespoke scripts, while regulatory agencies are only beginning to adapt analytical guidance to complex novel structures, leaving space for first movers to define quasi-standardized validation toolchains that become the default across regions such as North America, the EU, and APAC, where digital infrastructure and regulatory sophistication can absorb such a pivot.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| AI-first de novo protein platforms | +2.0% | North America, EU, APAC | Medium term (2–4 years) |
| Industrial bio-manufacturing enzymes | +1.5% | APAC emerging, EU, LatAm | Medium term (2–4 years) |
| Chronic disease biologics & biosimilars | +1.8% | North America, EU, LMICs | Long term (≥ 4 years) |
| Sustainable food & nutrition proteins | +1.0% | EU, North America, APAC | Medium term (2–4 years) |
| Environmental remediation biocatalysts | +0.8% | APAC, LatAm, MEA | Long term (≥ 4 years) |
| Integrated CDMO & analytics platforms | +1.2% | North America core, EU | Short term (≤ 2 years) |
Regional Analysis
In 2025, North America led the market, achieving over 49.3% share with a revenue of US$ 1.6 Billion.
North America region’s leadership is supported by a well-established biotechnology ecosystem, strong investments in life sciences research, and the presence of leading biopharmaceutical companies engaged in therapeutic protein development.
Extensive funding from public agencies, advanced academic research institutions, and widespread adoption of recombinant protein technologies continue to accelerate innovation across drug discovery, vaccine development, and precision medicine applications.
Europe held the second-largest share of the market, driven by expanding biopharmaceutical manufacturing capabilities, increasing research collaborations between academia and industry, and supportive regulatory frameworks for biologics development.
Countries such as Germany, the United Kingdom, Switzerland, and France remain key contributors due to their strong biotechnology infrastructure and growing focus on biosimilar and next-generation protein therapeutics.
The Asia-Pacific region is projected to register the fastest growth during the forecast period. Rising healthcare expenditures, expanding contract research and manufacturing organizations, increasing investments in biotechnology, and favorable government initiatives are strengthening protein engineering capabilities across China, Japan, South Korea, and Singapore. The growing demand for biologics and personalized medicine further supports regional expansion.
Latin America and the Middle East & Africa represent emerging markets with steady growth potential. Improving healthcare infrastructure, rising investments in biomedical research, expanding access to advanced therapies, and increasing collaborations with global biotechnology companies are expected to gradually enhance market penetration across these regions over the coming years.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global protein engineering market is moderately consolidated, with competition shaped by a combination of established life sciences companies, biopharmaceutical manufacturers, and emerging biotechnology innovators.
The market has reached a mature stage in analytical technologies and protein production platforms, while rapid innovation continues in engineered biologics, synthetic biology, AI-assisted protein design, and precision therapeutics.
Competitive differentiation increasingly depends on the ability to integrate advanced protein discovery tools, high-throughput screening, computational modeling, and scalable manufacturing capabilities that accelerate research and clinical development.
Large multinational organizations, including Merck KGaA, Thermo Fisher Scientific Inc., GE Healthcare, Agilent Technologies Inc., Bio-Rad Laboratories Inc., Waters Corporation, Bruker Corporation, and PerkinElmer Inc., provide comprehensive research instruments, analytical platforms, bioprocessing technologies, and laboratory solutions that support the broader protein engineering ecosystem.
Biopharmaceutical leaders such as Eli Lilly and Company, Amgen Inc., and Novo Nordisk AS leverage protein engineering to strengthen biologics pipelines, optimize therapeutic proteins, and expand precision medicine strategies across multiple disease areas.
Innovation-driven biotechnology companies, including GenScript Biotech Corporation, Ingenza, Absci, and ElevateBio, focus on AI-enabled protein design, synthetic biology, custom protein development, and next-generation cell and gene engineering technologies.
Competitive strategies are centered on sustained investment in research and development, strategic collaborations with academic institutions and biotechnology partners, and continuous enhancement of protein discovery and optimization workflows.
Companies also compete by integrating automation, computational biology, biomarker research, and advanced analytical platforms into end-to-end development processes, enabling faster candidate selection, improved clinical translation, and more efficient commercialization of engineered protein products.
Top Key Players
- Merck KGaA
- GE Healthcare
- Bruker Corporation
- Bio-Rad Laboratories Inc.
- Eli Lilly and Company
- Amgen Inc.
- Novo Nordisk AS
- Ingenza
- Thermo Fisher Scientific Inc.
- Waters Corporation
- GenScript Biotech Corporation
- Agilent Technologies Inc.
- Absci
- ElevateBio
- PerkinElmer Inc.
Recent Developments
- In April 2025, Merck KGaA announced an agreement to acquire SpringWorks Therapeutics for approximately US$3.9 billion, strengthening its oncology and rare disease portfolio while expanding capabilities relevant to engineered protein therapeutics.
- In September 2025, Merck KGaA acquired JSR Life Sciences’ Chromatography business, expanding its Protein A chromatography portfolio and downstream bioprocessing solutions for monoclonal antibody manufacturing.
- In December 2025, Bruker Corporation announced multiple European orders for 1.2 GHz and high-performance NMR systems, expanding infrastructure for structural biology and biomolecular protein research.
- In June 2026, Merck KGaA announced the acquisition of Bio-Techne for approximately US$11.3 billion, significantly strengthening its life science portfolio in proteins, antibodies, cell and gene therapy, and precision research tools
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 3.3 Billion |
| Forecast Revenue (2035) | US$ 14.3 Billion |
| CAGR (2026-2035) | 15.7 % |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Protein Type (Monoclonal Antibodies, Insulin, Modified Enzymes, Coagulation Factors, Vaccines, Growth Factors, Others) By Product Type (Reagents, Instruments) By Method (Rational Protein Design, De Novo Protein Design, Direct Evolution) By End User (Pharmaceutical and Biotechnology Companies, Contract Research Organizations (CRO), Academic Institutions, Others) By Region and Companies – Industry Segment Outlook, Market Assessment, Competition Scenario, Trends and Forecast 2026-2035 |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Merck KGaA, GE Healthcare, Bruker Corporation, Bio-Rad Laboratories Inc., Eli Lilly and Company, Amgen Inc., Novo Nordisk AS, Ingenza, Thermo Fisher Scientific Inc., Waters Corporation, GenScript Biotech Corporation, Agilent Technologies Inc., Absci, ElevateBio, PerkinElmer Inc. |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








