


Market Overview
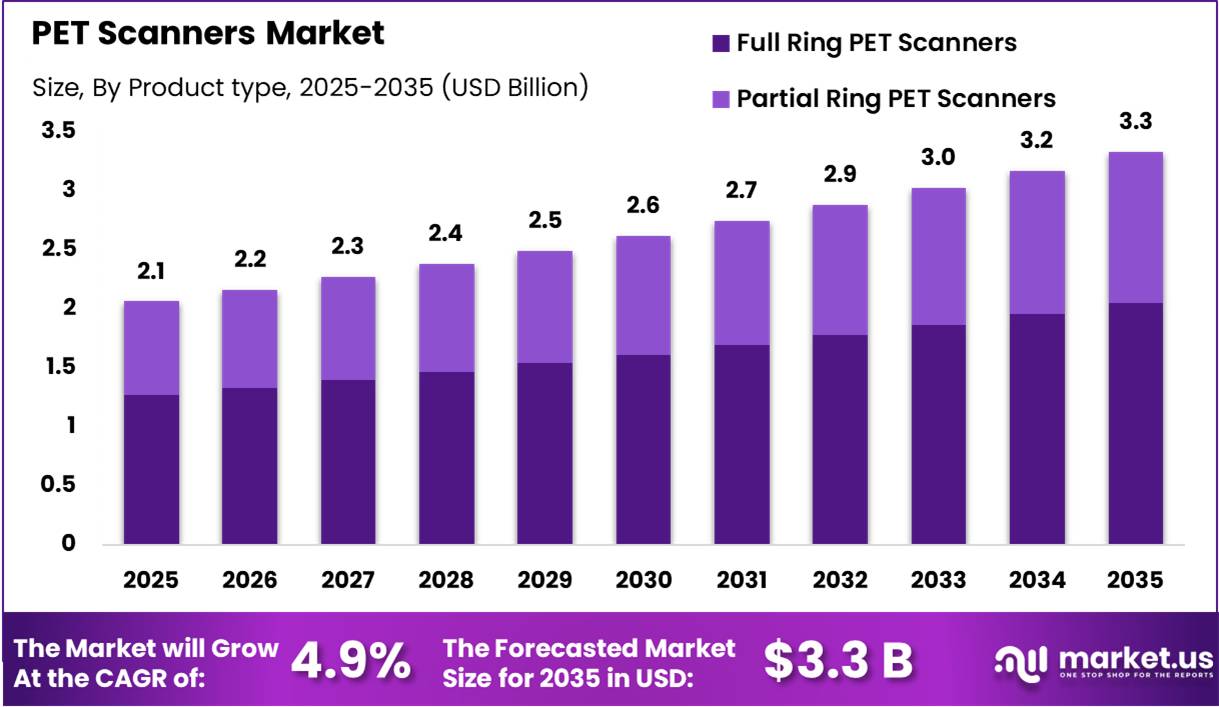
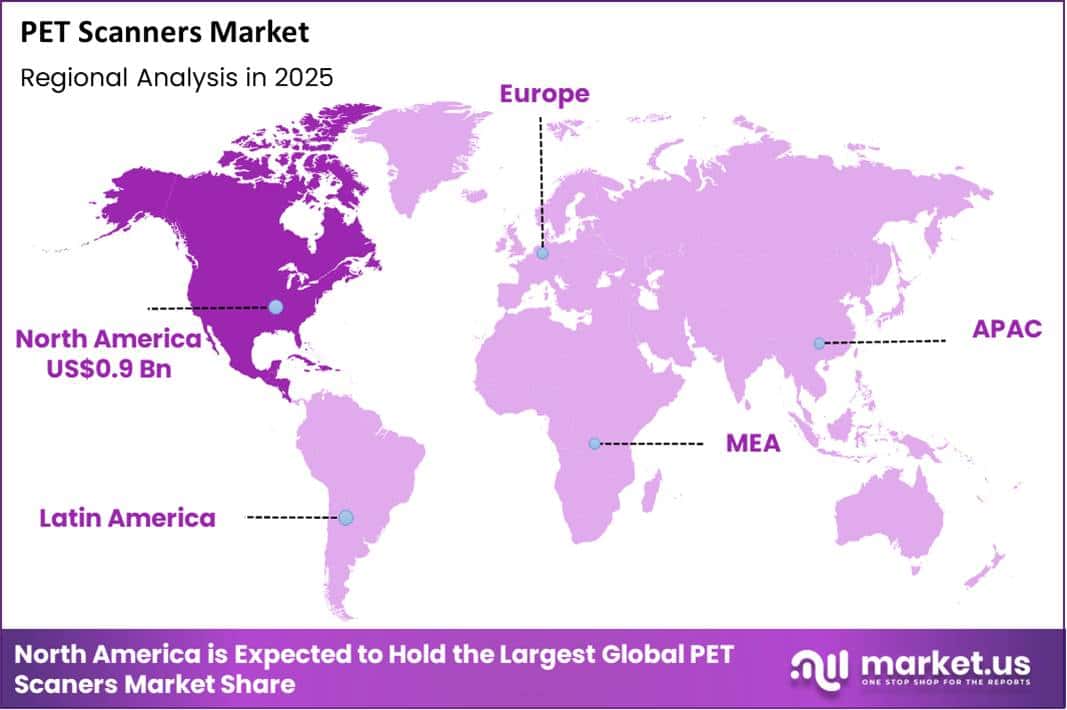
Global PET Scanners Market size is expected to be worth around US$ 3.3 Billion by 2035 from US$ 2.1 Billion in 2025, growing at a CAGR of 4.9% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 43.0% share with a revenue of US$ 0.9 Billion.
The Positron Emission Tomography (PET) Scanners Market is witnessing steady growth as healthcare systems increasingly adopt advanced molecular imaging technologies for early disease detection, diagnosis, and treatment monitoring.
PET scanners are non-invasive imaging devices that use radiotracers to visualize metabolic activity inside the body, enabling clinicians to detect abnormalities at the cellular level before structural changes become visible through conventional imaging methods. The technology is widely used in oncology, cardiology, and neurology, particularly for cancer staging, treatment response assessment, brain disorder evaluation, and cardiovascular imaging.
The rising global burden of chronic diseases is strengthening demand for PET imaging. According to the World Health Organization (WHO), cancer remains one of the leading causes of mortality worldwide, with nearly 20 million new cancer cases and approximately 9.7 million cancer-related deaths reported in 2022, increasing the need for accurate diagnostic imaging solutions. PET scanners are also increasingly integrated with computed tomography (PET/CT) and magnetic resonance imaging (PET/MRI) systems to improve anatomical localization and diagnostic precision.
Technological advancements are further shaping market development, including digital PET detectors, artificial intelligence-assisted image reconstruction, and improved radiotracer capabilities. The U.S. Food and Drug Administration (FDA) continues to regulate PET imaging systems and radiopharmaceutical products to ensure safety, performance, and clinical effectiveness.
Healthcare infrastructure expansion, growing investment in precision medicine, and increasing use of molecular imaging in personalized treatment pathways are expected to support continued adoption of PET scanners globally. North America remains a major contributor due to advanced healthcare facilities, high diagnostic imaging utilization, and strong research activity.
Key Takeaways
- Market Size: The PET Scanners Market size was US$ 2.1 Billion in 2025.The market is estimated to grow to US$ 3.3 Billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 4.9%.
- By Product Type: Full Ring PET Scanners has the largest market share, accounting for 61.6% of total sales.
- By Applications: Oncology the segment, accounting for 41.5% of total revenue.
- By Detector Type: Lutetium Oxyorthosilicate (LSO) leads the segment, accounting for 36.4% of total revenue.
- By End User: Hospitals leads the segment, accounting for 48.5% of total revenue.
- Regional: North America is the dominant regional market, accounting for 43.0% of global sales.
Product Type Analysis
The PET Scanners Market is segmented by product type into Full Ring PET Scanners and Partial Ring PET Scanners. Full Ring PET Scanners dominated the market in 2025, accounting for 61.6% of the market share, supported by their superior imaging performance, higher sensitivity, and ability to provide consistent whole-body diagnostic scans.
These systems are widely adopted in advanced hospitals and imaging centers due to their faster acquisition times, improved spatial resolution, and suitability for complex applications such as oncology staging, treatment monitoring, and neurological assessments. Continuous advancements in detector technology and integration with CT and MRI systems have further strengthened the preference for full ring configurations.
Partial Ring PET Scanners held 38.4% market share in 2025 and remain an important segment due to their lower installation costs, compact design, and suitability for facilities with moderate imaging volumes. These scanners are increasingly used in smaller hospitals, outpatient diagnostic centers, and research institutions where affordability and operational flexibility are key considerations.
Growing healthcare infrastructure expansion and demand for cost-effective molecular imaging solutions are expected to support adoption of partial ring systems, particularly in emerging healthcare markets.
Application Analysis
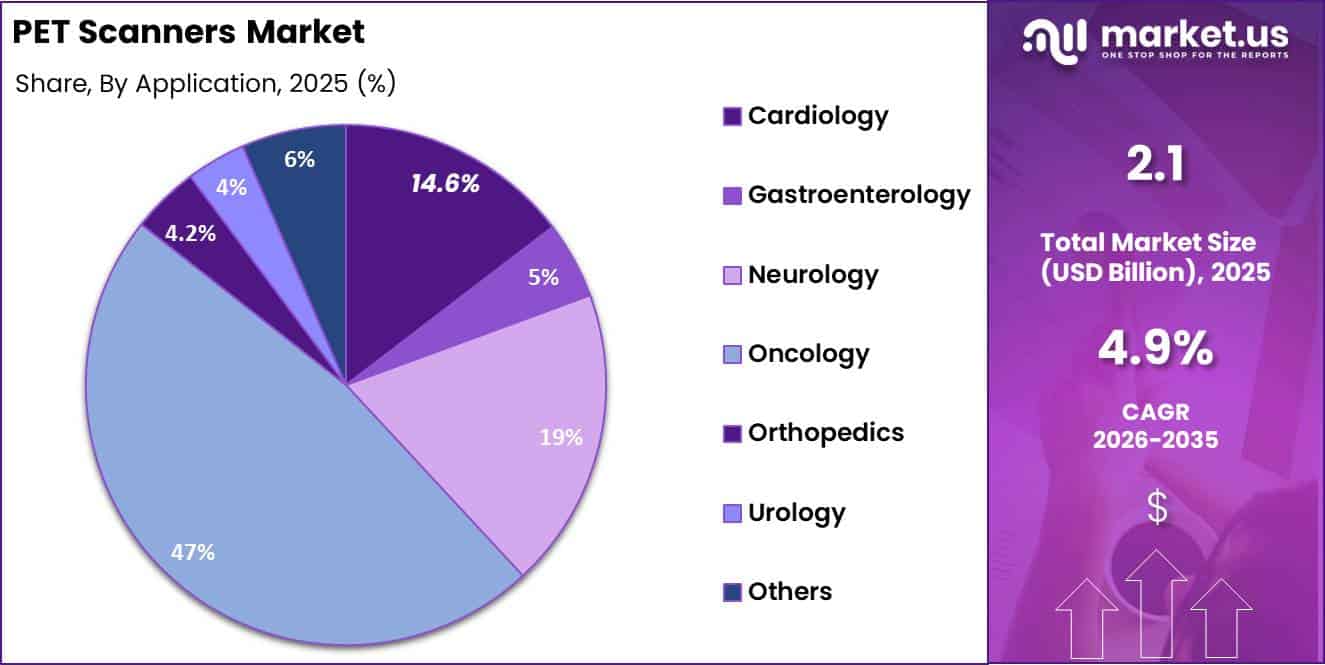
The PET Scanners Market is segmented by application into oncology, cardiology, gastroenterology, neurology, orthopedics, urology, and others. Oncology dominated the application segment in 2025, accounting for 47.5% of the market share, driven by the extensive use of PET imaging for cancer detection, staging, recurrence monitoring, and evaluation of treatment response.
The rising global burden of cancer and increasing adoption of precision oncology approaches continue to expand demand for PET-based diagnostic imaging.
Neurology represented 18.7% market share in 2025, supported by growing utilization of PET scanners for evaluating Alzheimer’s disease, dementia, epilepsy, and other neurological disorders through functional brain imaging. Cardiology accounted for 14.6% share, with PET imaging gaining importance in myocardial perfusion assessment and cardiovascular risk evaluation due to its high diagnostic accuracy.
Gastroenterology contributed 4.8% share, while orthopedics and urology accounted for 4.2% and 3.7%, respectively. These applications benefit from PET’s ability to detect metabolic changes associated with inflammation, infection, and disease progression.
Other applications held 6.5% share, including infectious disease imaging and research applications. Expanding clinical applications and improved tracer availability are expected to support broader PET scanner adoption.
Detector Type Analysis
The PET Scanners Market is segmented by detector type, including Lutetium Oxyorthosilicate (LSO) and other advanced detector technologies. Lutetium Oxyorthosilicate (LSO) dominated the detector type segment in 2025, accounting for 36.4% of the market share, owing to its excellent scintillation properties, high light output, fast decay time, and superior energy resolution.
LSO-based detectors are widely preferred in modern PET systems because they enable high-quality images with improved sensitivity and reduced scan durations.
The growing demand for precise molecular imaging, especially in oncology and neurological diagnostics, has accelerated adoption of LSO detector technology. Its compatibility with hybrid imaging platforms such as PET/CT and PET/MRI further strengthens its position in advanced diagnostic environments. Healthcare providers increasingly prioritize systems equipped with high-performance detectors to improve diagnostic confidence and workflow efficiency.
Other detector technologies continue to contribute to the market through ongoing innovations focused on improving spatial resolution, reducing radiation exposure, and enhancing image reconstruction capabilities.
Advances in silicon photomultipliers (SiPMs), digital detector designs, and time-of-flight PET technology are supporting next-generation scanner development. As imaging centers upgrade equipment and demand higher diagnostic accuracy, detector innovations are expected to remain a major factor influencing PET scanner market growth.
End User Analysis
The PET Scanners Market is segmented by end user into hospitals, diagnostic imaging centers, research institutes, and other healthcare facilities.
Hospitals dominated the end-user segment in 2025, accounting for 48.5% of the market share, due to their extensive use of PET scanners for comprehensive diagnostic services, cancer management programs, and advanced imaging procedures. Hospitals with oncology, cardiology, and neurology departments increasingly invest in PET systems to provide integrated diagnostic and treatment planning solutions.
Diagnostic imaging centers represent a significant segment as demand grows for specialized outpatient imaging services, faster diagnostic access, and advanced molecular imaging capabilities. These facilities are expanding their PET scanner installations to serve rising patient volumes and reduce pressure on hospital-based imaging departments.
Research institutes and academic centers also contribute to market growth through the use of PET scanners in drug development, clinical trials, neuroscience research, and biomarker discovery. Increasing collaboration between healthcare providers and research organizations is encouraging investment in advanced imaging technologies.
Other end users, including specialty clinics and government healthcare facilities, are adopting PET scanners to improve diagnostic accessibility. Rising healthcare expenditure, expansion of imaging infrastructure, and increasing demand for early disease detection are expected to support PET scanner adoption across diverse healthcare settings.
Market Segmentations
By Product Type
- Full Ring PET Scanners
- Partial Ring PET Scanners
By Applications
- Cardiology
- Gastroenterology
- Neurology
- Oncology
- Orthopedics
- Urology
- Others
By Detector Type
- Bismuth Germanium Oxide (BGO)
- Gadolinium Oxyorthosilicate (GSO)
- Lutetium Fine Silicate (LFS)
- Lutetium Oxyorthosilicate (LSO)
- Lutetium Yttrium Orthosilicate
By End User
- Hospitals
- Clinics
- Diagnostic Centers
- Others
Drivers
Oncology imaging load expansion from rising cancer incidence and survivorship
WHO reported about 20 million new cancer cases and 9.7 million deaths globally in 2022, with more than 53.5 million people living within five years of a diagnosis, and it expects annual new cases to exceed 35 million by 2050, representing a 77% increase from 2022 levels.
That matters for PET scanners because oncology remains the modality’s dominant use case, especially for staging, restaging, therapy response assessment, and recurrence monitoring, so a larger treated population expands both baseline scan volumes and the clinical justification for replacing older analog systems with higher-throughput digital platforms.
The demand signal is especially strong in lung, breast, colorectal, and prostate pathways, which are among the highest-incidence cancers globally and account for a large share of PET-relevant referrals in comprehensive cancer centers.
Commercially, this shifts procurement from “one-time capital purchase” logic toward multi-year capacity planning, because hospitals increasingly evaluate PET assets against scanner utilization, scheduling bottlenecks, same-day oncology workflow integration, and downstream treatment revenue capture rather than image quality alone.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Oncology imaging load expansion from rising cancer incidence and survivorship | +1.4% | North America core, EU, Japan, China, India metro clusters | Medium term |
| CMS tracer reimbursement reform improving PET procedure economics | +1.1% | U.S. hospital outpatient market, indirect spill-over to Canada and private U.S. networks | Short term |
| Digital PET and extended axial FOV upgrades lifting throughput and dose efficiency | +1.3% | U.S., Germany, France, Japan, China tier-1 hospitals, premium APAC centers | Medium term |
| Theranostics and radioligand treatment pathways increasing PET-linked patient journeys | +0.9% | U.S., EU5, Japan, Australia, GCC oncology hubs | Medium term |
| Emerging-market installation gap and radiopharmacy corridor build-out | +0.8% | India, Southeast Asia, Latin America private chains, Middle East referral hubs | Long term |
Challenge
Radiology Talent Shortages Constrain PET Market Expansion
Radiology talent shortfall is a structural bottleneck for PET utilization because imaging demand is rising faster than specialist capacity, with U.S. projections alone indicating a shortfall of roughly 17,000–42,000 radiologists, pathologists, and related specialists by the early 2030s as advanced modalities, including PET, CT, and MRI, expand.
In many oncology centers, PET volumes have increased 15–25% since the pandemic recovery period, while full-time equivalent (FTE) radiologist growth has hovered in the low single digits, creating reading backlogs of 12–48 hours for non-urgent studies and forcing prioritization of high-risk oncology cases at the expense of cardiology and neurology throughput.
This imbalance effectively caps PET scanner operational utilization at roughly 70–80% of technical capacity in high-volume hospitals and keeps smaller centers at 50–60% utilization, even when hardware uptime exceeds 95%, translating to a realistic friction drag of around 1.4 % points on potential CAGR for installed base and scan volumes in major markets.
Over time, systems attempt to mitigate this gap using teleradiology networks, AI-supported reporting, and sub-specialty stratification, but training cycles for radiologists and nuclear medicine physicians span 5–7 years beyond medical school, and pipeline expansion is constrained by residency slot caps and burnout-driven attrition.
This implies that the talent bottleneck will persist through at least one investment cycle and require structural changes in workforce planning, task shifting, protocol simplification, and automation of routine reads to sustain PET growth.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Radiology talent shortfall | -1.4% | North America, EU, high-volume APAC | Long term (≥ 4 years) |
| Radiotracer supply volatility | -1.1% | North America, EU nuclear hubs | Medium term (2-4 years) |
| Capex and uptime constraints | -0.9% | Global tertiary centers | Medium term (2-4 years) |
| Workflow, data integration gaps | -0.8% | North America core, EU, urban APAC | Short term (≤ 2 years) |
| Reimbursement and coverage lag | -1.2% | U.S. CMS, selected EU payers | Long term (≥ 4 years) |
| Regulatory, safety compliance load | -0.7% | Global, high-regulation markets | Medium term (2-4 years) |
Restraints
Elevated Interest Rates Delay PET Scanner Capital Investments
Elevated interest rates, tariff-driven equipment cost inflation, and pressure on public payer budgets are collectively dampening hospital capital expenditure appetites for large-ticket imaging equipment, with surveys of hospital executives indicating that approximately three-quarters report macro factors impacting planned capital purchases and roughly 40% actively cutting or deferring capital equipment spending.
For PET scanners, where installed-system prices, including hybrid PET/CT, shielding, site work, and radiopharmacy integration, can run into low- to mid-seven figures, a 150–250 basis point increase in effective borrowing costs materially shifts net present value calculations and extends payback periods by 1–2 years in typical oncology-led utilization scenarios.
In parallel, import tariffs on imaging components and electronics add 5–10% to hardware acquisition costs in some markets, while inflation in construction and specialized labor further pushes total room buildout and commissioning budgets up by another 5–8%, leading multi-hospital systems to prioritize lower-cost CT upgrades or software-only workflow improvements over new PET capacity.
On the margin side, higher financing costs and slower ramp-up of reimbursed volume erode expected internal rates of return, prompting boards to stretch procurement cycles from typical 18–24 months to 30–36 months and to intensify leasing and vendor-financing negotiations, thereby smoothing but lowering the annual pace of PET scanner installations.
This macro-financing drag is realistically modeled to remove around 1.8 % points from the otherwise unconstrained global CAGR between 2026 and 2030, with the impact front-loaded into the next 2–4 years while interest rates and budget uncertainty remain elevated.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Systemic radioisotope shortages | -2.0% | North America core, EU, OECD APAC | Medium term (2–4 years) |
| Elevated interest rates & CapEx deferrals | -1.8% | North America core, EU, LatAm tier-1 | Short–Medium term (≤ 4 years) |
| Fragmented reimbursement & utilization controls | -1.5% | U.S. Medicare markets, EU public payers, selected APAC | Medium–Long term (≥ 3–5 years) |
| High total cost of ownership & operational complexity | -1.2% | Global tertiary care hubs, emerging APAC corridors | Long term (≥ 4 years) |
| Regulatory and radiopharmaceutical compliance burden | -1.0% | U.S., EU, Japan, high-regulation markets | Medium term (2–4 years) |
Opportunity
Outpatient PET Micro-Centers Expand Chronic Imaging Access
Outpatient PET micro-centers represent a structural white space where PET capacity is configured in smaller, lower-capex sites embedded within endocrinology, cardio-metabolic, and community oncology networks to support longitudinal imaging for chronic disease programs, a model that remains underpenetrated because most current PET installations are concentrated in tertiary hospitals and large cancer centers with high fixed overhead and complex scheduling.
A micro-center model, built around one compact PET or PET/CT system with optimized staffing, 10–20 scan slots per day, and standardized protocols for diabetes-related cancer surveillance or heart failure imaging, can operate at 25–30% lower operating cost per scan while maintaining reimbursement levels, lifting EBITDA margins by 600–800 basis points and enabling payers and providers to deploy PET into chronic-care pathways where baseline utilization today is suppressed by access constraints and high per-episode facility costs.
If health systems in North America, Europe, and selected urban LATAM markets establish even 500–700 such micro-centers between 2028 and 2035, expanding PET volume into chronic cohorts where current imaging penetration is below 10–15%.
The additional scan throughput could add 8–10 million annual PET procedures globally, corresponding to several hundred million dollars of incremental service revenue and justifying a 1.5 % point CAGR upside to scanner demand as manufacturers design lower-footprint systems, tailored service packages, and financing models that match the economics of community-based imaging micro-hubs rather than only large hospital deployments.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Theranostic PET platform ecosystems | +2.0% | North America, EU, advanced APAC | Medium term (2–4 years) |
| Outpatient PET micro-centers for chronic care | +1.5% | North America core, EU, urban LATAM | Medium term (2–4 years) |
| Low-dose, green PET imaging for ESG-driven tenders | +1.2% | EU, UK, Canada, developed APAC | Short term (≤ 2 years) |
| AI-native PET workflow and capacity monetization | +1.8% | Global tier-1 urban markets | Medium term (2–4 years) |
| Emerging market PPP PET networks | +2.3% | APAC emerging, Middle East, Africa | Long term (≥ 4 years) |
| PET in metabolic and diabetes oncology programs | +1.4% | Global, with focus on NA/EU/China | Medium term (2–4 years) |
Regional Analysis
In 2025, North America led the market, achieving over 43.0% share with a revenue of US$ 0.9 Billion.
North America region’s leadership is supported by the strong presence of advanced healthcare infrastructure, widespread adoption of molecular imaging technologies, and high availability of hybrid imaging systems such as PET/CT and PET/MRI.
The growing burden of cancer, cardiovascular disorders, and neurological diseases has increased demand for accurate diagnostic imaging, while favorable reimbursement frameworks and investments in precision medicine continue to support PET scanner adoption across hospitals and diagnostic centers.
The presence of leading medical imaging companies and research institutions further accelerates technological advancements in detector efficiency, artificial intelligence integration, and workflow optimization.
Europe represents another significant market, driven by expanding nuclear medicine programs, increasing cancer screening initiatives, and government-supported healthcare modernization. Countries such as Germany, France, and the United Kingdom are investing in advanced diagnostic infrastructure to improve early disease detection and personalized treatment planning.
The Asia-Pacific region is expected to witness strong growth during the forecast period due to rising healthcare expenditure, improving access to advanced imaging technologies, and increasing demand for oncology diagnostics.
Emerging healthcare systems across China, Japan, South Korea, and Southeast Asia are progressively adopting PET scanners to address growing disease burdens. Meanwhile, Latin America and the Middle East & Africa are gradually expanding market opportunities through healthcare infrastructure development and increasing availability of specialized imaging services.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The PET scanners market is moderately consolidated, with competition shaped by a combination of established medical imaging companies, specialized PET technology providers, and emerging innovation-focused firms.
The market is in a mature growth phase, where competitive differentiation is increasingly driven by scanner performance improvements, hybrid imaging integration, workflow optimization, and advancements in precision diagnostics.
Companies are focusing on higher-resolution imaging, molecular imaging capabilities, artificial intelligence integration, and disease-specific tracer development to strengthen clinical adoption across oncology, neurology, and cardiology applications.
The market structure includes three primary player tiers. Large multinational imaging and healthcare companies, including Siemens, Lilly, Agfa-Gevaert Group, Neusoft Corporation, and Advanced Accelerator Applications, contribute through broad healthcare ecosystems, advanced imaging platforms, radiopharmaceutical capabilities, and global distribution networks.
Specialty technology providers such as Positron Corporation, PETsys Electronics SA, CMR Naviscan, ONCOVISION, and Segamicorp focus on dedicated PET technologies, detector innovations, and application-specific imaging solutions.
Innovation-driven companies including CellSight Technologies, RefleXion, Clarity Pharmaceuticals, Blue Earth Diagnostics Limited, and Qubiotech Health Intelligence S.L. emphasize molecular imaging, radiotracer development, AI-based analysis, and precision medicine applications.
Competitive strategies center on R&D investment, strategic collaborations with research institutions, integration of imaging workflows with clinical decision-making, and development of advanced diagnostic ecosystems.
Companies are increasingly competing through PET technology refinement, biomarker-based imaging approaches, software-driven interpretation, and partnerships that connect diagnostics with personalized treatment pathways. Differentiation is also influenced by the ability to integrate scanners, radiopharmaceuticals, and data analytics into comprehensive precision healthcare solutions.
Top Key Players
- Agfa-Gevaert Group
- CellSight Technologies
- RefleXion
- Clarity Pharmaceuticals
- PETsys Electronics SA
- Blue Earth Diagnostics Limited
- Qubiotech Health Intelligence S.L.
- Advanced Accelerator Applications
- Lilly
- Positron Corporation
- CMR Naviscan
- Neusoft Corporation
- Siemens
- Segamicorp
- ONCOVISION
Recent Developments
- In May 2025, Lilly announced the acquisition of SiteOne Therapeutics to expand its neuroscience and precision medicine pipeline, supporting future demand for advanced molecular imaging approaches.
- In August 2025, Agfa HealthCare introduced its next-generation Enterprise Imaging vision for 2025, focusing on smarter imaging workflows, clinician usability, and digital transformation across medical imaging environments.
- In October 2025, Lilly announced the acquisition of Adverum Biotechnologies to strengthen its genetic medicine capabilities; although not a PET scanner acquisition, the deal supports Lilly’s broader precision medicine and advanced diagnostic ecosystem.
- In January 2026, RefleXion received FDA clearance for the next-generation RefleXion X2 platform with SCINTIX therapy, featuring improved PET sensitivity for tumor detection and expanding biology-guided radiotherapy capabilities for primary and metastatic tumors.
- Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 2.1 Billion |
| Forecast Revenue (2035) | US$ 3.3 Billion |
| CAGR (2026-2035) | 4.9 % |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Full Ring PET Scanners, Partial Ring PET Scanners)By Applications(Cardiology, Gastroenterology, Neurology, Oncology, Orthopedics, Urology, Others) By Detector Type (Bismuth Germanium Oxide (BGO), Gadolinium Oxyorthosilicate (GSO), Lutetium Fine Silicate (LFS), Lutetium Oxyorthosilicate (LSO), Lutetium Yttrium Orthosilicate) By End User (Hospitals, Clinics, Diagnostic Centres, Others) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Agfa-Gevaert Group ,CellSight Technologies ,RefleXion ,Clarity Pharmaceuticals ,PETsys Electronics SA ,Blue Earth Diagnostics Limited ,Qubiotech Health Intelligence S.L. ,Advanced Accelerator Applications ,Lilly ,Positron Corporation ,CMR Naviscan ,Neusoft Corporation ,Siemens ,Segamicorp ,ONCOVISION |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








