


Market Overview
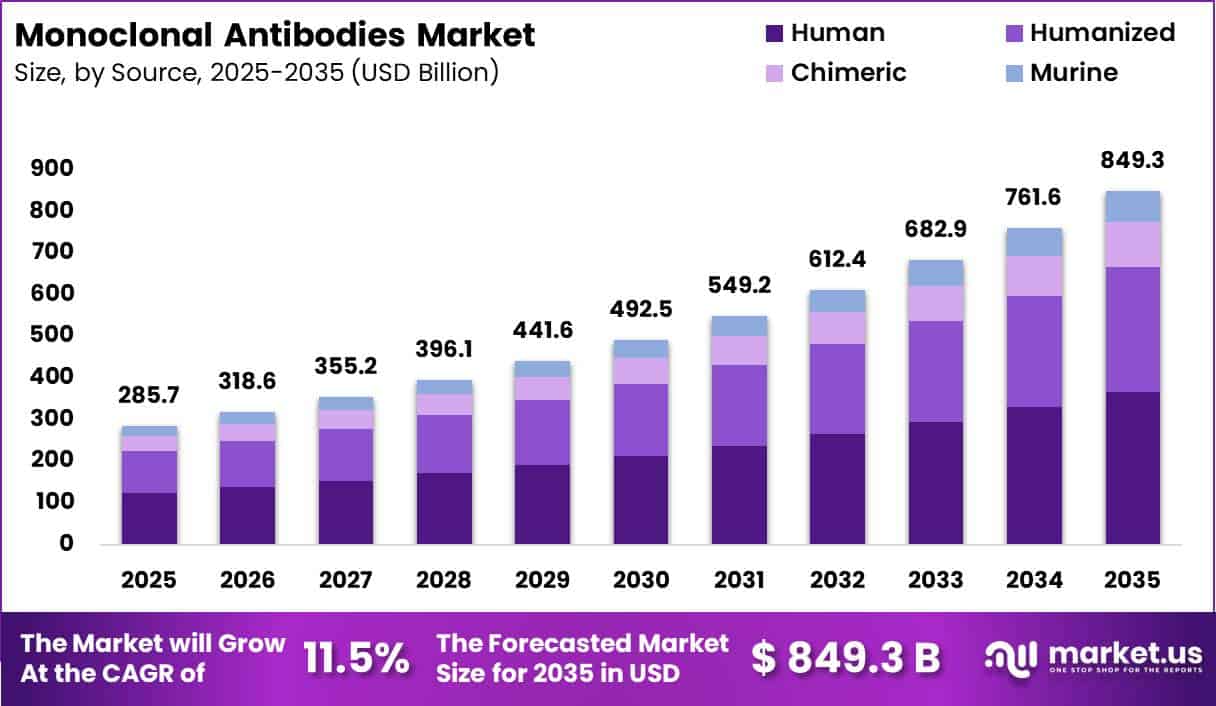
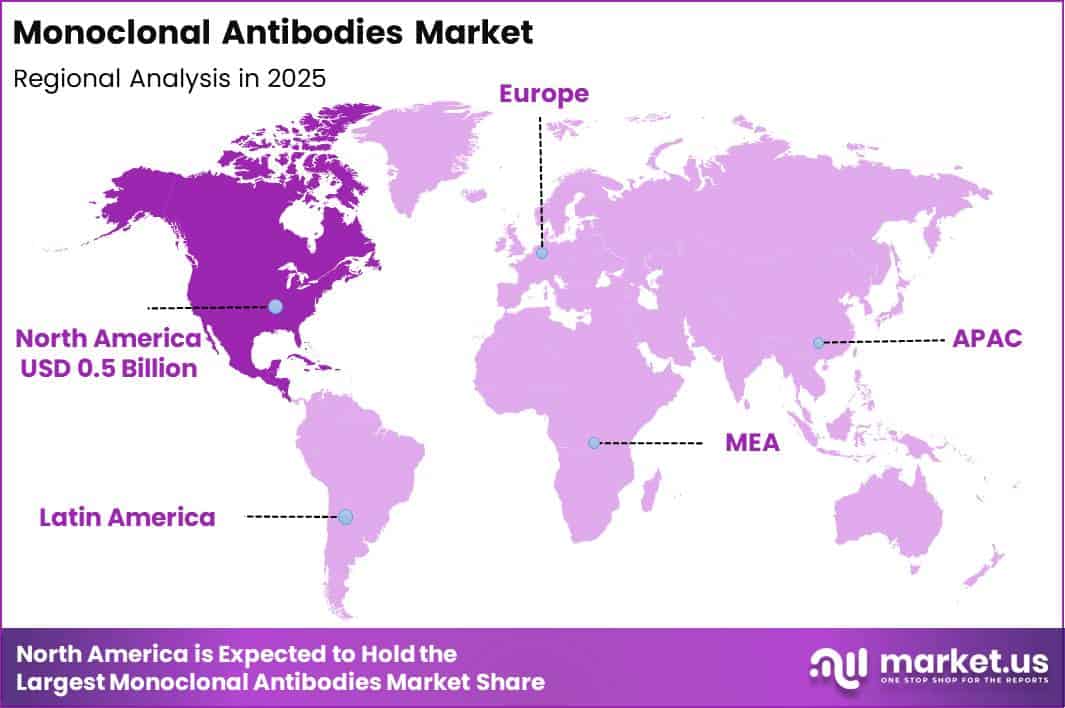
Global Monoclonal Antibodies Market size is expected to be worth around US$ 849.3 Billion by 2035 from US$ 285.7 Billion in 2025, growing at a CAGR of 11.5% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 45.6% share with a revenue of US$ 130.3 Billion.
Monoclonal antibodies (mAbs) have become one of the most transformative classes of biologic medicines, offering highly targeted treatment options for cancer, autoimmune disorders, infectious diseases, and rare conditions. Unlike conventional therapies, mAbs are engineered to bind to specific antigens, enabling greater therapeutic precision while reducing damage to healthy tissues.
The World Health Organization (WHO) recognizes monoclonal antibodies as a rapidly expanding category of biotherapeutic products and has introduced updated global guidelines to strengthen their quality, safety, efficacy, and regulatory evaluation, reflecting their growing role in modern healthcare.
The clinical pipeline for monoclonal antibodies continues to expand significantly. According to the WHO Global Observatory on Health Research and Development, 2,066 clinical trials involving monoclonal antibodies were conducted globally between 2014 and 2023, covering oncology, immune-mediated diseases, and infectious diseases.
WHO’s broader clinical trial database also shows sustained growth in monoclonal antibody research from 1999 through 2023, highlighting increasing global investment in antibody-based therapeutics.
Cancer remains the largest application area for monoclonal antibodies. The U.S. National Cancer Institute (NCI) notes that these therapies are a cornerstone of targeted cancer treatment, functioning by directly recognizing tumor-specific antigens, stimulating immune-mediated destruction of cancer cells.
Blocking tumor growth pathways, or delivering cytotoxic drugs and radioactive molecules selectively to malignant tissues. Their precision has improved treatment outcomes across multiple hematological malignancies and solid tumors.
Continuous advances in recombinant DNA technology, antibody engineering, bispecific antibodies, antibody-drug conjugates (ADCs), and Fc-modified molecules are further broadening therapeutic applications.
WHO states that next-generation monoclonal antibodies offer advantages such as improved stability, prolonged half-life, enhanced bioavailability, higher production efficiency, and the ability to target multiple disease pathways simultaneously. These technological innovations are expected to support broader clinical adoption and expand treatment options for patients worldwide.
Key Takeaways
- Market Size : Global Monoclonal Antibodies Market size is expected to be worth around US$ 849.3 Billion by 2035 from US$ 285.7 Billion in 2025.
- Market Share : The market is growing at a CAGR of 11.5% during the forecast period from 2026 to 2035.
- Indication Analysis : The oncology/cancer segment dominated the monoclonal antibodies market, accounting for 48.7% of the market share in 2025.
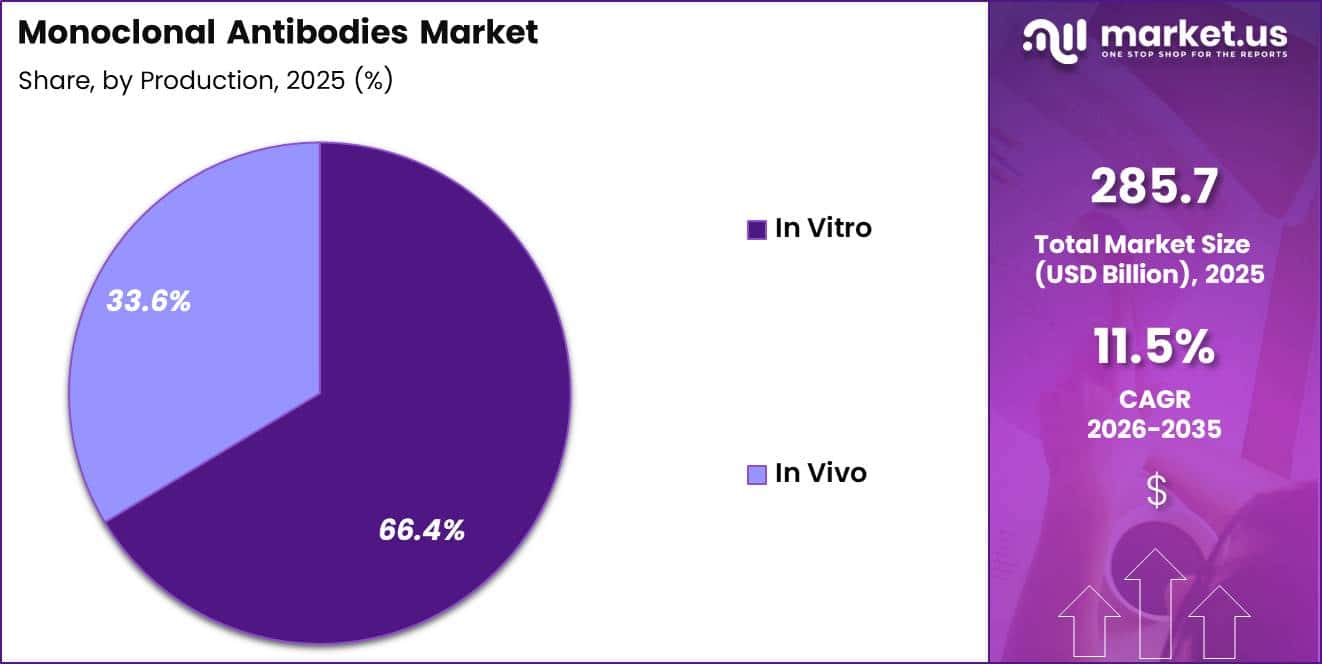
- Production Analysis : The in vitro production segment dominated the monoclonal antibodies market with 66.4% of the market share in 2025.
- End-user Analysis : Hospitals and hospital pharmacies dominated the monoclonal antibodies market, accounting for 55.3% of the market share in 2025.
- Source Analysis : The human monoclonal antibody segment dominated the market with 43.3% of the market share in 2025.
- Regional Analysis : In 2025, North America led the market, achieving over 45.6% share with a revenue of US$ 130.3 Billion.
Indication Analysis
The oncology/cancer segment dominated the monoclonal antibodies market, accounting for 48.7% of the market share in 2025. The segment’s leadership is driven by the widespread use of monoclonal antibodies as targeted therapies for solid tumors and hematological cancers, including breast cancer, lung cancer, lymphoma, and colorectal cancer.
These therapies improve treatment precision by selectively targeting cancer cells while reducing damage to healthy tissues. Continuous approvals of new antibody-based drugs, antibody-drug conjugates (ADCs), and bispecific antibodies further strengthen this segment.
According to the U.S. National Cancer Institute (NCI), monoclonal antibodies have become a major class of targeted cancer therapies and are increasingly used alone or in combination with chemotherapy and immunotherapy.
The autoimmune diseases segment held 19.3% of the market, supported by growing use in rheumatoid arthritis, psoriasis, inflammatory bowel disease, and lupus. Inflammatory and immune-mediated diseases represented 12.3%, reflecting increasing adoption for chronic inflammatory disorders.
Infectious diseases accounted for 10.4%, benefiting from expanding antibody development for viral and respiratory infections, an area highlighted in recent WHO guidance.
Neurological and other indications captured 9.3%, supported by emerging monoclonal antibody therapies for migraine, Alzheimer’s disease, and rare neurological disorders. Expanding clinical research across diverse therapeutic areas continues to broaden the market’s application base.
Production Analysis
The in vitro production segment dominated the monoclonal antibodies market with 66.4% of the market share in 2025. In vitro production has become the preferred manufacturing approach because it offers greater scalability, higher purity, improved consistency, and better compliance with regulatory quality standards.
Modern recombinant DNA technology enables monoclonal antibodies to be produced efficiently in mammalian cell culture systems such as Chinese Hamster Ovary (CHO) cells, supporting commercial-scale manufacturing.
The World Health Organization (WHO) recognizes recombinant in vitro expression systems as the current industry standard for producing monoclonal antibodies and related biologics due to their safety, quality, and manufacturing flexibility.
The in vivo segment accounted for 33.6% of the market. Although traditional hybridoma-based production in laboratory animals continues to be used for research and limited manufacturing applications, its commercial share has declined because of higher production costs, lower scalability, and ethical considerations.
Advances in cell culture technology, bioprocess optimization, and automated manufacturing continue to accelerate the transition toward in vitro production, making it the dominant approach for developing therapeutic monoclonal antibodies worldwide.
End-user Analysis
Hospitals and hospital pharmacies dominated the monoclonal antibodies market, accounting for 55.3% of the market share in 2025. This leadership is primarily attributed to the fact that most monoclonal antibody therapies require intravenous infusion or specialist supervision due to potential infusion-related reactions and the complexity of patient monitoring.
Hospitals also manage the largest number of oncology, autoimmune, and severe inflammatory disease patients, making them the primary distribution channel for these biologic medicines.
In addition, hospital pharmacies maintain specialized storage and handling infrastructure necessary for temperature-sensitive biologic products, supporting their leading market position.
Specialty centers and clinics represent the second-largest segment, benefiting from the increasing availability of outpatient infusion services for chronic diseases. Retail pharmacies are gradually expanding their role as more subcutaneous monoclonal antibody formulations become commercially available.
Online and other distribution channels continue to grow, particularly for follow-up prescriptions and home-delivery services in selected therapeutic areas. The increasing availability of self-administered biologics is expected to support gradual expansion beyond traditional hospital settings.
Source Analysis
The human monoclonal antibody segment dominated the market with 43.3% of the market share in 2025. Human antibodies are widely preferred because they closely resemble naturally occurring human antibodies, resulting in lower immunogenicity, improved safety, and better long-term treatment outcomes.
Advances in recombinant DNA technology, phage display, and transgenic animal platforms have accelerated the development of fully human monoclonal antibodies across oncology, autoimmune diseases, and infectious diseases. WHO guidelines recognize fully human antibodies as an important advancement in therapeutic biologics due to their broad clinical applicability.
The humanized segment accounted for 35.2%, supported by their extensive use in approved cancer and immune-mediated disease therapies. Chimeric antibodies represented 12.6%, continuing to play an important role in several established therapeutic products despite newer technologies.
Murine antibodies held 8.9% of the market and are primarily used in research, diagnostics, and selected therapeutic applications because of their comparatively higher immunogenicity. Ongoing innovation continues to shift product development toward fully human and humanized antibody platforms.
Market Segmentations
By Indication
- Oncology / cancer
- Autoimmune diseases
- Inflammatory / immune‑mediated
- Infectious diseases
- Neurological & other indications
By Production
- In vitro
- In vivo
By End-user
- Hospitals / hospital pharmacies
- Specialty centers / clinics
- Retail pharmacies
- Online / other channels
By Source
- Human
- Humanized
- Chimeric
- Murine
Driver
Oncology and Autoimmune Patient Pool Expansion Driving Monoclonal Antibody Growth
Cancer and chronic immune-mediated disease burden remains a fundamental volume driver for monoclonal antibodies because it expands treated prevalence, supports additional indications, and enables longer therapy duration through maintenance and combination treatment strategies. WHO reported approximately 20 million new cancer cases and 9.7 million cancer deaths in 2022, with annual new cases projected to exceed 35 million by 2050.
In the U.S., cancer projections reached approximately 2,041,910 new cases in 2025 and 2,114,850 in 2026, sustaining strong demand for antibody-based oncology therapies. Regulatory modernization is also becoming an important growth accelerator by improving development efficiency for antibody platforms.
In 2025, FDA issued draft guidance on streamlined nonclinical safety studies for monospecific antibodies and introduced initiatives supporting reduced reliance on traditional animal testing through AI-based toxicity models, organoids, organ-on-chip technologies, and other advanced evaluation approaches.
Strategically, these regulatory shifts can reduce development timelines, lower iteration costs, and improve capital efficiency for companies managing broad antibody pipelines.
Developers with platform discovery capabilities can reuse translational datasets, accelerate lifecycle extensions, and advance more candidates into clinical development per R&D dollar, strengthening portfolio flexibility and supporting long-term monoclonal antibody market expansion.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Oncology and autoimmune patient pool expansion | +2.1% | North America core, EU5, Japan, China urban tier-1/2, APAC spill-over | Medium term (2-4 years) |
| Faster regulatory throughput and non-animal development pathways | +1.6% | U.S. core, EU follow-through, global filings spill-over | Short term (≤ 2 years) |
| Biosimilar reimbursement and access expansion | +1.4% | U.S. Medicare core, EU mature biosimilar markets, LATAM tender spill-over | Short term (≤ 2 years) |
| Subcutaneous delivery and site-of-care shift | +1.3% | U.S., Western Europe, Japan, South Korea, urban China | Medium term (2-4 years) |
| Late-stage antibody pipeline depth including bispecifics | +2.0% | U.S., EU, China, Japan | Medium term (2-4 years) |
| Manufacturing digitalization and process-intensification | +1.1% | U.S., EU, Singapore, South Korea, India biologics corridors | Long term (≥ 4 years) |
Challenge
Materials Sourcing and Cost Volatility Limiting Solid State Battery Growth
Solid-state architectures rely on specialized solid electrolytes, including sulfide, oxide, and polymer-ceramic hybrid systems, along with high-nickel or lithium-rich cathodes whose supply chains are less industrially mature than mainstream liquid-electrolyte lithium-ion cathode and separator ecosystems.
This creates higher price variability, with key solid-state precursors experiencing 25–40% year-on-year volatility compared with 10–20% for conventional battery materials during 2024–2026.
For sulfide electrolytes, limited commercial-scale producers currently operate at tens to low hundreds of metric tons per year, while future gigafactory demand for mass-market EV deployment could exceed 5,000–10,000 tons annually per major region. This structural supply mismatch pushes contract prices per kilogram 15–25% above steady-state assumptions and adds approximately USD 10–20/kWh to pack-level costs.
Similarly, competition from emerging sodium-ion and improved LFP chemistries increases demand for shared processing equipment and specialty coatings, extending lead times for critical manufacturing tools by 3–6 months. As a result, procurement cycles for certain solid-state-specific components can stretch to 9–12 months, limiting capacity ramp-up speed and creating an estimated 1.1 %-point drag on potential CAGR.
Strategic mitigation requires multi-regional material sourcing with parallel supplier bases across East Asia, North America, and Europe, long-term offtake agreements with ramp-linked pricing mechanisms, and accelerated qualification of alternative electrolyte formulations to reduce dependence on high-risk materials.
Many industry participants may need to secure 5–10-year supply contracts to stabilize input costs and support predictable capital deployment as solid-state manufacturing scales.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Scale-up manufacturing yield loss | -1.6% | NA, EU, East Asia | Long term (≥ 4 years) |
| Interface stability & lifecycle proof | -1.3% | EU, Japan, Korea | Long term (≥ 4 years) |
| Materials sourcing & cost volatility | -1.1% | Global EV hubs | Medium term (2-4 years) |
| Standards, safety testing complexity | -0.9% | NA, EU regulatory hubs | Medium term (2-4 years) |
| Talent & tooling capability gap | -0.8% | Global gigafactory corridors | Long term (≥ 4 years) |
| Competing chemistries adoption drag | -0.7% | APAC, EU fleet markets | Medium term (2-4 years) |
Restraints
Cold Chain and Logistics Vulnerabilities Limiting mAb Market Expansion
Cold-chain and logistics vulnerabilities in transporting temperature-sensitive monoclonal antibodies (mAbs), especially across extended distribution networks in emerging regions, subtract an estimated 0.8 % points from global CAGR by increasing product loss, stock-outs, and end-to-end distribution costs.
Many mAbs require storage at 2–8°C with strict excursion limits. Real-world biologics logistics data indicates that 10–20% of shipments in challenging environments experience temperature deviations, with 1–3% of total distributed volume requiring quarantine or discard due to stability specification breaches.
To mitigate these risks, sponsors and distributors invest heavily in validated packaging, real-time temperature monitoring, and GDP-compliant warehousing. These measures increase logistics costs per vial by 20–40% in lower-infrastructure settings compared with core markets and raise the proportion of COGS attributed to cold-chain operations from approximately 5–7% to 10–12% in certain APAC, LATAM, and MEA corridors.
Cross-border transport lead times can extend from 3–5 days in integrated EU distribution networks to 10–15 days when customs clearance delays, limited air-freight capacity, and multi-stop routing are involved. These extended timelines amplify supply risks during extreme weather events or geopolitical disruptions.
Cold-chain failures create direct product write-offs that can reach low-single-digit %s of regional sales while also triggering batch investigations, regulatory reporting requirements, and reputational risks. As a result, some manufacturers limit direct market expansion or delay entry into regions where infrastructure reliability remains uncertain.
Strategically, requirements for redundant warehousing, increased safety inventory, and specialized third-party logistics partnerships raise working-capital intensity by 2–3 % points and restrict aggressive price reductions that could otherwise accelerate volume growth, particularly for chronic indications requiring reliable monthly or quarterly dosing.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High biologics cost and pricing controls | -2.0% | North America, EU, selected APAC | Long term (≥ 4 years) |
| Capacity and process scale-up bottlenecks | -1.5% | North America core, EU, APAC corridors | Medium term (2-4 years) |
| Complex regulatory and biosimilar pathways | -1.2% | North America, EU, Japan | Long term (≥ 4 years) |
| Cold-chain and logistics vulnerabilities | -0.8% | Emerging APAC, LATAM, MEA | Medium term (2-4 years) |
| Raw material and single-source supply risk | -0.7% | Global, with APAC sourcing concentration | Short to medium term (≤ 4 years) |
| Counterfeit and quality assurance risks | -0.6% | LATAM, MEA, parts of APAC | Long term (≥ 4 years) |
Opportunity
Population Scale mAb Prevention in High Burden Diseases Creating Growth Opportunities
The final opportunity is a strategic shift from treating advanced disease with monoclonal antibodies to deploying selected mAbs as population-scale preventive interventions, particularly in infectious diseases and high-burden chronic conditions where traditional vaccines or small-molecule approaches remain insufficient. This creates a new addressable market beyond current treatment-focused forecasts.
Recent advances in long-acting neutralizing antibodies for respiratory viruses and other pathogens demonstrate that single or infrequent doses can maintain protective antibody titers for 6–12 months, yet current utilization remains largely restricted to narrow high-risk populations in wealthier countries.
If global health agencies and governments across Africa, South Asia, and parts of Latin America co-finance preventive mAb programs targeting 50–100 million high-risk individuals annually by 2035, including immunocompromised populations and patients with major comorbidities, these initiatives could create an additional utilization layer beyond therapeutic demand.
At moderate pricing levels, population-based prevention programs could represent USD 15–25 billion in annual spending.
From an economic perspective, long-acting prophylactic mAbs have the potential to reduce downstream hospitalization and intensive care events by 30–50% in targeted populations, strengthening the case for shared-savings models and outcomes-based public procurement approaches that can sustain margins around 20–25% despite healthcare budget pressures.
Because baseline monoclonal antibody forecasts primarily assume treatment applications rather than large-scale prevention, the introduction and adoption of even 3–5 major prophylactic mAbs across high-burden regions could add approximately 1.8 % points of CAGR upside.
This growth would be driven by new patient segments, recurring long-term dosing programs, and integration into national disease-prevention strategies.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Value-based mAb contracting & risk-share models | +2.0% | North America, EU, select APAC | Medium term (2–4 years) |
| Biosimilar mAb platform & global roll-up | +2.3% | US, EU, LatAm, APAC emerging | Medium term (2–4 years) |
| Subcutaneous / long-acting mAb self-administration | +1.7% | North America core, EU, Japan | Short term (≤ 2 years) |
| Bispecific / multi-specific mAbs in mid-income markets | +1.5% | China, India, MEA, LatAm | Long term (≥ 4 years) |
| AI-optimized mAb manufacturing & modular plants | +1.3% | Global, with APAC and CEE hubs | Medium term (2–4 years) |
| Population-scale mAb prevention in high-burden diseases | +1.8% | Africa, South Asia, LatAm | Long term (≥ 4 years) |
Regional Analysis
In 2025, North America dominated the global monoclonal antibodies market, accounting for 45.6% of the total market and generating approximately US$ 130.3 billion in revenue.
The region’s leadership is supported by a well-established biopharmaceutical industry, high healthcare spending, advanced research infrastructure, and early adoption of innovative biologic therapies.
The United States remains the primary contributor due to the presence of major pharmaceutical companies, extensive clinical research activities, and a strong regulatory framework for biologics.
The U.S. Food and Drug Administration (FDA) continues to approve new monoclonal antibodies and antibody-based biologics through its Biologics License Application (BLA) pathway, supporting continuous product availability and market expansion.
Europe represents the second-largest regional market, driven by strong biologics research, favorable reimbursement policies, and widespread adoption of monoclonal antibody therapies for oncology, autoimmune diseases, and rare disorders. Countries such as Germany, France, and the United Kingdom remain key contributors due to their advanced healthcare systems and active participation in clinical research.
Meanwhile, the Asia-Pacific region is expected to witness the fastest growth during the forecast period, supported by expanding biotechnology industries, increasing healthcare investments, improving access to biologic medicines, and rising regulatory approvals in China, Japan, South Korea, and India.
A growing number of antibody therapeutics are now originating from China, reflecting the region’s rapidly expanding innovation ecosystem. Latin America and the Middle East & Africa are also experiencing steady market growth as healthcare infrastructure improves and access to advanced biologic therapies continues to expand.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global monoclonal antibodies market is driven by leading biopharmaceutical companies that continue to expand their biologics portfolios through innovation, clinical research, and advanced manufacturing capabilities.
F. Hoffmann-La Roche Ltd. maintains a leading position with a broad portfolio of monoclonal antibodies for oncology, ophthalmology, and immunology, while AbbVie Inc. is advancing numerous monoclonal antibodies, multispecific antibodies, and antibody-drug conjugates (ADCs) across immunology, oncology, neuroscience, and eye care.
Amgen Inc. continues to strengthen its biologics pipeline with monoclonal antibody therapies targeting inflammatory diseases, cancer, bone health, and rare diseases, supported by continuous investment in research and development.
AstraZeneca plc is expanding its monoclonal antibody portfolio through innovative biologics for oncology, respiratory, immunology, and rare diseases. Bristol Myers Squibb Co. (BMS) continues to develop antibody-based immunotherapies and targeted biologics for cancer and hematologic diseases, while Daiichi Sankyo Company Limited is strengthening its position through next-generation antibody-drug conjugate (ADC) platforms and global oncology collaborations.
Johnson & Johnson continues to invest in monoclonal antibody innovation across oncology, immunology, and infectious diseases, supported by its global biologics research and manufacturing network.
GlaxoSmithKline plc (GSK) is enhancing its biologics pipeline with monoclonal antibodies for respiratory diseases, infectious diseases, immunology, and cancer. Meanwhile, Bayer AG is expanding its precision medicine strategy through collaborations and targeted biologic research, particularly in oncology.
Collectively, these companies are accelerating the development of next-generation monoclonal antibodies, bispecific antibodies, and ADCs, strengthening competition and supporting continued innovation in the global monoclonal antibodies market.
Top Key Players
- AbbVie Inc.
- Amgen Inc.
- AstraZeneca plc
- Bayer AG
- Bristol Myers Squibb Co. (BMS)
- Daiichi Sankyo Company Limited
- F. Hoffmann‑La Roche Ltd.
- GlaxoSmithKline plc
- Johnson & Johnson
- Merck & Co. Inc. (MSD)
- Novartis AG
- Pfizer Inc.
- Regeneron Pharmaceuticals Inc
- Sanofi S.A.
- Takeda Pharmaceutical Company Limited
- Others
Recent Developments
- In June 2026 – AbbVie Inc. announced the acquisition of Apogee Therapeutics for US$ 10.9 billion, strengthening its immunology pipeline with zumilokibart, a long-acting antibody candidate for inflammatory diseases. The acquisition reinforces AbbVie’s leadership in antibody-based immunology therapies and expands its U.S. biologics portfolio
- In October 2025 – Roche received U.S. FDA approval for Gazyva/Gazyvaro (obinutuzumab) for adults with active lupus nephritis, marking a significant expansion of its anti-CD20 monoclonal antibody portfolio in the U.S. autoimmune disease market.
- In March 2025 – Sanofi entered a definitive agreement to acquire DR-0201 from Dren Bio with an upfront payment of US$ 600 million. The CD20-directed bispecific antibody is expected to strengthen Sanofi’s immunology pipeline and expand its antibody-based therapies for autoimmune diseases.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 285.7 Billion |
| Forecast Revenue (2035) | US$ 849.3 Billion |
| CAGR (2026-2035) | 11.5% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Indication (Oncology / cancer, Autoimmune diseases, Inflammatory / immune‑mediated, Infectious diseases, Neurological & other indications), By Production (In vitro, In vivo), By End-user (Hospitals / hospital pharmacies, Specialty centers / clinics, Retail pharmacies, Online / other channels), By Source (Human, Humanized, Chimeric, Murine) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | AbbVie Inc., Amgen Inc., AstraZeneca plc, Bayer AG, Bristol Myers Squibb Co. (BMS), Daiichi Sankyo Company Limited, F. Hoffmann‑La Roche Ltd. , GlaxoSmithKline plc , Johnson & Johnson, Merck & Co. Inc. (MSD), Novartis AG, Pfizer Inc., Regeneron Pharmaceuticals Inc, Sanofi S.A., Takeda Pharmaceutical Company Limited, Others |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |





































