


Market Overview
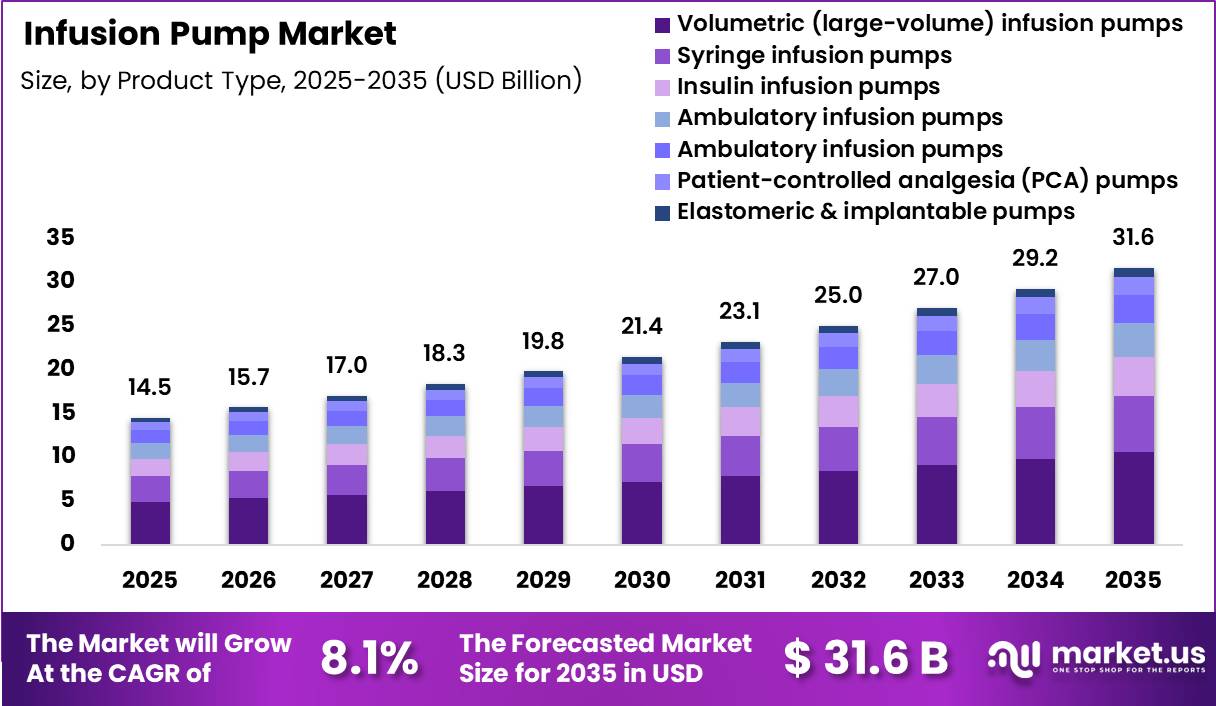
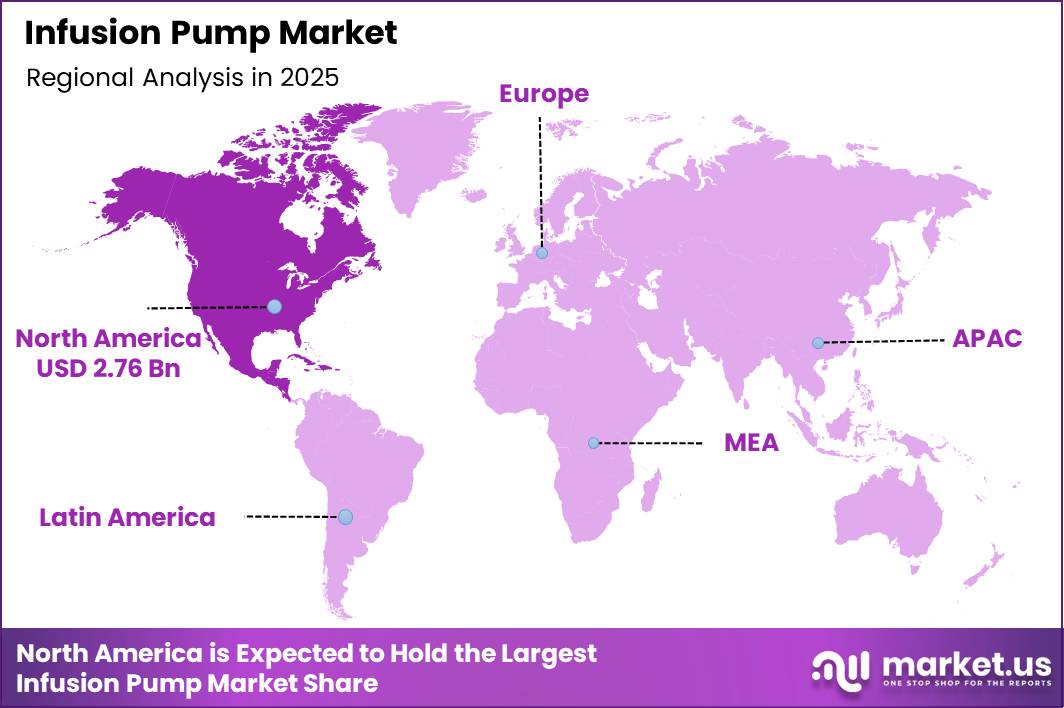
The Global Infusion Pump Market size is expected to reach around US$ 31.6 Billion by 2035, up from US$ 14.5 Billion in 2025, growing at a CAGR of 8.1% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 37.6% market share with revenue of US$ 2.76 Billion.
The Infusion Pump Market is driven by the increasing adoption of advanced medication delivery technologies in hospitals, intensive care units, emergency departments, and home healthcare settings.
Infusion pumps are medical devices designed to deliver fluids, nutrients, antibiotics, chemotherapy drugs, insulin, hormones, and pain medications into a patient’s body at accurately controlled rates. According to the U.S. Food and Drug Administration (FDA), infusion pumps enable precise delivery of very small fluid volumes and automated dosing intervals, improving the reliability of intravenous therapy compared with manual administration methods.
Growing demand for safe and efficient drug administration is encouraging healthcare facilities to adopt smart infusion pumps equipped with drug libraries, alert systems, connectivity features, and automated safety checks.
These technologies help clinicians reduce medication errors by identifying incorrect dosage settings, flow rates, and potential infusion risks. The FDA highlights that smart pump technologies can support risk reduction strategies and improve patient safety when properly implemented.
The rising burden of chronic diseases, increasing surgical procedures, expanding cancer treatments, and the growth of home-based infusion therapy are contributing to wider utilisation of infusion devices. The World Health Organisation (WHO) reports that noncommunicable diseases account for approximately 41 million deaths annually, representing about 74% of global deaths, creating continued demand for advanced treatment delivery systems.
Patient safety remains a key focus area, with regulatory agencies emphasising device quality, cybersecurity, and performance monitoring. The FDA reported approximately 56,000 adverse event reports related to infusion pumps between 2005 and 2009, leading to enhanced safety initiatives and device improvement programs.
The market is expected to benefit from innovations such as wireless connectivity, integration with electronic health records (EHRs), wearable infusion systems, and AI-enabled monitoring solutions that support personalised and safer patient care.
Key Takeaways
- Market Size: The Global Infusion Pump Market size was US$ 14.5 Billion in 2025. The market is estimated to grow to US$ 31.6 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 8.1%.
- Product Type: Volumetric (Large-Volume) Infusion Pumps has the largest market share, accounting for 33.7% of total product type revenue.
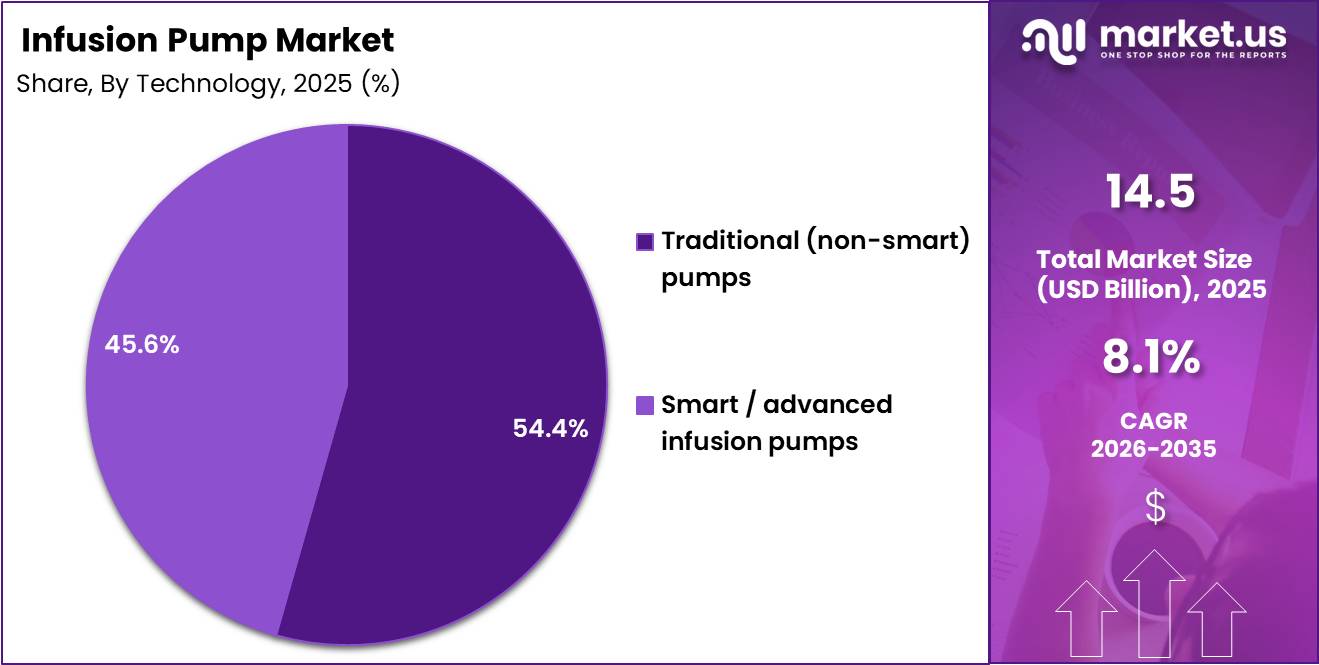
- Technology: Traditional (Non-Smart) Pumps leads the segment, accounting for 54.4% of total technology segment revenue.
- Application: Diabetes Management leads the segment, accounting for 24.8% of total application revenue.
- Regional: North America is the dominant regional market, accounting for 37.6% of global revenue, holding US$ 2.76 billion in revenue in 2025.
Product Type Analysis
The Volumetric (Large-Volume) Infusion Pumps segment dominated the Infusion Pump Market in 2025, accounting for 33.7% market share. These pumps are widely used in hospitals and critical care environments for delivering large volumes of fluids, medications, and nutritional solutions with high accuracy.
Their extensive adoption is supported by applications in intensive care units, surgical procedures, emergency care, and long-duration intravenous therapies where continuous and controlled infusion is essential.
Syringe Infusion Pumps held 20.1% market share in 2025 due to their ability to deliver precise small-volume doses, making them suitable for neonatal care, pediatric treatments, and critical medication administration. Insulin Infusion Pumps accounted for a 14.1% share, driven by increasing demand for automated insulin delivery solutions among diabetes patients requiring continuous glucose management.
Ambulatory Infusion Pumps represented 12.2% market share, supported by the rising preference for home-based infusion therapies and portable drug delivery systems. Enteral Infusion Pumps captured a 10.3% share, benefiting from growing nutritional support requirements among patients unable to consume food orally.
Patient-Controlled Analgesia (PCA) Pumps contributed a 6.3% share, mainly used for controlled pain management after surgeries and during chronic pain treatments. Elastomeric & Implantable Pumps accounted for a 3.3% share, supported by specialised applications requiring long-term medication delivery.
Technology Analysis
The Traditional (Non-Smart) Infusion Pumps segment dominated the Infusion Pump Market in 2025, accounting for 54.4% market share. These conventional infusion systems remain widely utilised across hospitals, clinics, and healthcare facilities due to their established usage, lower operational complexity, and cost advantages. Traditional pumps provide reliable fluid and medication delivery for routine intravenous therapies, including hydration, antibiotics, and basic medication administration.
However, the Smart / Advanced Infusion Pumps segment accounted for 45.6% market share in 2025 and is expected to witness strong adoption due to increasing focus on medication safety and digital healthcare integration. Smart infusion pumps incorporate advanced features such as drug libraries, dose error reduction systems, wireless connectivity, real-time monitoring, and integration with electronic health records (EHRs).
Healthcare providers are increasingly adopting smart technologies to minimise infusion-related errors and improve clinical workflow efficiency. Regulatory emphasis on infusion pump safety, cybersecurity improvements, and enhanced device performance is encouraging manufacturers to develop connected and intelligent solutions.
The growing demand for personalised treatment approaches, remote monitoring capabilities, and automated drug delivery systems is further supporting the transition from traditional pumps toward smart infusion technologies across hospitals and home healthcare settings.
Application Analysis
The Diabetes Management segment dominated the Infusion Pump Market in 2025, accounting for 24.8% market share. This leadership is attributed to the increasing prevalence of diabetes worldwide and the growing adoption of insulin infusion pumps for continuous insulin delivery. These devices help patients maintain better glucose control by providing precise insulin doses and supporting advanced diabetes management approaches.
The Chemotherapy application segment represents a significant share of the market, driven by the increasing use of infusion pumps for controlled administration of anticancer drugs. Accurate delivery of chemotherapy medications is essential to improve treatment effectiveness and reduce potential dosing risks. Analgesia applications are also expanding due to rising demand for pain management solutions, including post-operative care and chronic pain therapies using PCA pumps.
Gastroenterology applications are supported by increasing utilisation of enteral feeding pumps among patients requiring nutritional support. Pediatrics remains an important application area, as infusion pumps enable accurate delivery of small medication volumes for infants and children requiring specialised care.
Other applications, including critical care, cardiovascular treatments, antibiotic therapy, and home infusion services, continue to contribute to market growth. Increasing hospital admissions, rising chronic disease prevalence, and advancements in infusion technology are expected to further expand the use of infusion pumps across diverse medical applications.
Key Market Segments
By Product Type
- Volumetric (Large-Volume) Infusion Pumps
- Syringe Infusion Pumps
- Insulin Infusion Pumps
- Ambulatory Infusion Pumps
- Enteral Infusion Pumps
- Patient-Controlled Analgesia (PCA) Pumps
- Elastomeric & Implantable Pumps
By Technology
- Traditional (Non-Smart) Pumps
- Smart/Advanced Infusion Pumps
By Application
- Diabetes Management
- Chemotherapy
- Analgesia
- Gastroenterology
- Pediatrics
- Other Applications
Driver
Diabetes Care Digitisation and Insulin Pump Adoption
Diabetes care digitisation is a core structural growth driver for the insulin infusion pump market because the underlying patient pool continues to expand while treatment increasingly relies on connected, data-driven devices.
WHO reports that diabetes cases increased from 200 million in 1990 to 830 million in 2022, with about 14 % of adults affected globally, and more than 95 % of cases being type 2 diabetes, significantly widening the addressable population for insulin delivery technologies beyond traditional type 1 patients.
In the United States alone, the NIDDK estimates 38.4 million people had diabetes in 2021, alongside 97.6 million adults with prediabetes, creating a large pipeline of future insulin-requiring patients.
At the same time, clinical guidelines such as the ADA Standards of Care 2026 increasingly support insulin pump use in both type 1 diabetes and selected insulin-dependent type 2 populations, reinforcing gradual eligibility expansion. This shift is accelerating the adoption of digital insulin pumps that integrate continuous glucose monitoring, automated dosing algorithms, and cloud-based monitoring platforms.
As a result, the business model is evolving from one-time device sales to recurring, ecosystem-based revenue streams involving consumables, software subscriptions, and remote therapy management.
Overall, diabetes digitisation strengthens long-term demand visibility while increasing lifetime patient value through higher device utilisation, improved adherence, and tighter integration of hardware and software ecosystems.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Diabetes care digitisation and insulin pump adoption | +1.9% | North America core, EU, Japan, South Korea, urban China, GCC | Medium term (2-4 years) |
| Smart pump safety compliance and drug-library utilisation | +1.4% | North America core, EU, Australia, Gulf hospitals, large APAC private networks | Short term (≤ 2 years) |
| Home infusion and ambulatory care shift | +1.2% | U.S., Canada, Western Europe, Japan, South Korea, selected urban LATAM | Medium term (2-4 years) |
| Chronic disease and high-acuity infusion burden expansion | +1.6% | Global, with the strongest volume effect in APAC, North America, EU | Long-term (≥ 4 years) |
| Interoperability, EHR linkage, and workflow automation | +1.1% | U.S. hospital systems, EU digital hospitals, advanced APAC health systems | Medium term (2-4 years) |
| Regulatory redesign pressure and replacement cycle acceleration | +0.9% | U.S. core, EU compliance markets, mature installed bases globally | Short term (≤ 2 years) |
Challenge
Persistent Medication Error Risk in Infusion Therapy
Persistent medication error risk remains a structural constraint in the infusion pump market, even as smart pump penetration exceeds 60 to 70 % in many high-income healthcare systems.
While smart pumps with dose error reduction systems have improved safety, they have not eliminated infusion-related medication errors, which remain part of the broader burden of unsafe medication practices targeted by the WHO “Medication Without Harm” initiative. Evidence suggests smart pump adoption can reduce infusion errors by 30 to 40 %, but residual risks persist due to operational gaps.
Drug libraries are often bypassed or overridden in 5 to 15 % of cases, and up to 10 to 20 % of clinical protocols may not be fully represented, particularly in complex areas like oncology, paediatrics, and critical care. This creates ongoing safety exposure and limits aggressive standardisation.
Operationally, maintaining smart pump safety requires continuous training, structured incident reporting, and governance reviews that consume significant clinical and administrative time. Major incidents can require 50 to 100 staff hours for root cause analysis and remediation, adding to system-level workload.
As a result, hospitals tend to prioritise risk mitigation over rapid feature expansion, extending pump replacement cycles to 7 to 10 years instead of 5 to 7 years, which slows market refresh rates and contributes to an estimated 0.8 % point drag on CAGR.
Strategically, addressing this requires standardised drug libraries, better analytics on alert usage, and tighter integration with hospital medication safety systems to reduce variability and unlock faster adoption of advanced infusion platforms.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Legacy interoperability gaps | -1.2% | North America, EU, APAC tier-1 | Medium term (2–4 years) |
| Persistent medication error risk | -0.8% | Global acute & oncology centers | Long-term (≥ 4 years) |
| Cybersecurity & connectivity burden | -0.9% | North America core, EU hubs | Medium term (2–4 years) |
| Skilled clinician & biomed shortage | -1.0% | North America, EU, APAC urban | Long-term (≥ 4 years) |
| Capital & procurement cycle friction | -0.7% | Public hospitals, LMIC regions | Medium term (2–4 years) |
| Multi-vendor data standard misalignment | -0.6% | Large IDNs, EU university hospitals | Long-term (≥ 4 years) |
Restraints
Hospital CapEx Deferral and Stretched Balance Sheets in Infusion Pump Markets
Hospital and health system capital expenditure constraints are a key structural barrier to infusion pump upgrades and fleet expansion. Even though U.S. healthcare spending reached about 5.3 trillion dollars in 2024, growing at roughly 7 % annually, most of this increase is absorbed by labour costs, pharmaceuticals, and outpatient services rather than capital equipment renewal, leaving limited room for pump replacement cycles.
As a result, capital budgets for medical devices often grow only marginally, forcing hospitals, especially public and not-for-profit systems, to defer procurement decisions. Rising wage pressures, higher patient acuity, and elevated interest rates further constrain available funds.
Many institutions are therefore shifting toward leasing models, vendor-financed fleets, or managed service agreements, which extend effective infusion pump replacement cycles from 7 to 8 years to 9 to 10 years or more.
Although medical equipment financing is expanding, these arrangements increase total lifecycle costs and reduce the frequency of outright purchases. Vendors often need to offer pricing concessions or usage-based contracts, which can compress margins by 150 to 300 basis points in large deals.
Regionally, Europe and parts of Latin America face additional fiscal constraints, with limited public budgets prioritising imaging and surgical robotics over pump upgrades. This results in slower adoption of advanced connectivity features and greater reliance on refurbished systems.
Overall, these dynamics reduce replacement volumes and delay technology refresh cycles, contributing to an estimated 1.0 to 1.5 % point drag on infusion pump CAGR.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High recall and safety alert overhang | -1.8% | North America core, EU-5 | Short to medium term |
| Intensifying FDA / global software & cyber requirements | -1.5% | North America core, EU, select APAC | Medium to long term |
| Hospital CapEx deferral and stretched balance sheets | -1.4% | North America, EU, LATAM tier-1, APAC metros | Short to medium term |
| Supply chain and component cost volatility | -1.2% | Global, with APAC manufacturing corridors | Short term |
| Interoperability, EHR integration and training drag | -1.0% | North America core, EU, advanced APAC | Medium term |
| Reimbursement and operating margin pressure | -0.8% | North America, EU public systems | Medium to long term |
Opportunity
Disease-Specific Closed-Loop Infusion Ecosystems
Disease-specific closed-loop infusion ecosystems represent a shift from standalone smart pumps toward fully integrated, condition-focused therapy platforms in areas such as diabetes, oncology, and cardiovascular care.
Instead of operating as isolated devices, these systems combine infusion pumps, real-time sensors, electronic health record integration, drug libraries, and clinical decision support tools to dynamically adjust therapy and support outcome-based care models.
While current smart pumps already reduce medication errors through standardised libraries, they remain largely point solutions. The next evolution is true closed-loop operation, where physiological signals such as glucose trends in diabetes or toxicity markers in oncology directly inform infusion adjustments within clinically approved guardrails.
The scale opportunity is significant. With global diabetes prevalence rising from 7 % to 14 % of adults between 1990 and 2022 and more than 830 million people living with diabetes, alongside a large oncology treatment population, even modest penetration of 5 to 10 % of eligible patients by 2035 could generate USD 8 to 12 billion in incremental ecosystem revenue across devices, software, and services.
These systems support higher value pricing, including 15 to 25 % device premiums and recurring USD 20 to 40 per patient per month software and monitoring fees. They also enable value-based contracts by reducing adverse drug events and hospitalisations, allowing shared savings with payers.
Because global healthcare policy increasingly emphasises outcomes, adherence, and continuous monitoring rather than standalone devices, vendors that align early with disease-specific ecosystems can capture layered revenue streams.
This shift is expected to contribute roughly 2.0 % points of additional CAGR, driven primarily by software and service expansion rather than baseline infusion device demand.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Home infusion platform bundles | +2.5% | North America, EU, APAC urban LMIC | Short term (≤ 2 years) |
| Disease-specific closed-loop infusion ecosystems | +2.0% | North America core, EU, East Asia | Medium term (2-4 years) |
| AI-driven infusion fleet optimisation & RaaS | +1.8% | North America, EU, GCC, tier-1 LATAM | Medium term (2-4 years) |
| Emerging-market tiered pump portfolios | +2.2% | APAC emerging, Africa, South Asia | Long-term (≥ 4 years) |
| Interoperable data monetisation & analytics | +1.5% | North America, EU, OECD Asia | Medium term (2-4 years) |
| Oncology day-care and ambulatory infusion hubs | +2.0% | North America, EU, China, India | Short–Medium term (≤ 4 years) |
Regional Analysis
In 2025, North America led the market, achieving over 37.6% market share with revenue of US$ 2.76 billion. The North America Infusion Pump Market represents a leading region, supported by advanced healthcare infrastructure, high adoption of smart infusion technologies, and a strong focus on patient safety initiatives.
The presence of well-established hospitals, increasing demand for automated drug delivery systems, and rising prevalence of chronic diseases such as diabetes and cancer are driving infusion pump adoption across the region.
Regulatory efforts by organisations such as the U.S. Food and Drug Administration (FDA) to improve infusion pump safety, reduce medication errors, and encourage advanced device development further support market growth.
The Europe Infusion Pump Market is expanding due to increasing healthcare expenditure, growing elderly populations, and rising demand for home-based infusion therapy. Countries across the region are focusing on digital healthcare integration, connected medical devices, and improved medication management systems. The adoption of smart infusion pumps is increasing as healthcare providers prioritise clinical efficiency and patient safety.
The Asia-Pacific Infusion Pump Market is witnessing significant growth due to expanding hospital networks, increasing healthcare investments, and the rising burden of chronic diseases. Growing awareness of advanced medical devices, improving access to healthcare services, and increasing adoption of intensive care technologies are supporting market expansion in countries across the region.
The Latin America, Middle East, and Africa regions are gradually developing due to improving healthcare infrastructure, increasing government healthcare initiatives, and rising demand for reliable drug delivery systems. Investments in modern hospitals and medical technology upgrades are expected to create new opportunities for infusion pump adoption in these emerging markets.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of the Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
Suppliers in the global infusion pump market seek competitive advantage through smart pump platform development integrating dose error reduction software, drug library management systems, and electronic health record bidirectional connectivity that collectively reduce medication administration errors and nursing workflow burden in hospital critical care, oncology, and surgical settings.
Key strategic focus areas include closed-loop insulin delivery system development integrating continuous glucose monitoring with automated insulin pump dosing for diabetes management, interoperable smart pump ecosystem development enabling hospital-wide infusion therapy data analytics and remote pump management, and ambulatory and wearable infusion pump miniaturisation enabling chemotherapy, pain management, and parenteral nutrition therapy delivery outside traditional hospital inpatient environments.
Companies continue investing in FDA 510(k) and CE Mark regulatory clearance programs for next-generation smart pump platforms, hospital pharmacy integration and electronic medication administration record connectivity capability, and clinical evidence generation demonstrating medication error reduction and patient safety outcomes that support hospital value analysis committee procurement approval and premium pricing justification.
The progressive regulatory pressure from FDA safety communications and the Joint Commission mandating smart pump adoption with dose error reduction software activation across US hospital settings is creating compliance-driven institutional procurement demand for smart pump platform upgrades that accelerates technology transition from the traditional non-smart pump installed base through the forecast period to 2035.
Top Key Players
- Abbott Laboratories
- Boston Scientific Corporation
- Medtronic plc
- BIOTRONIK SE & Co. KG
- Terumo Corporation
- B. Braun Melsungen AG
- Biosensors International Group Ltd.
- MicroPort Scientific Corporation
- Meril Life Sciences Pvt. Ltd.
- Cook Medical LLC
- C. R. Bard Inc.
- Alvimedica
- Lepu Medical Technology (Beijing) Co., Ltd.
- OrbusNeich Medical Group
- STENTYS SA
- Other Key Players
Recent Developments
- In January 2026, Medtronic plc launched its next-generation closed-loop insulin delivery system integrating real-time continuous glucose monitoring with automated insulin pump dosing, securing hospital endocrinology and homecare institutional procurement agreements across North American and European diabetes management distribution networks.
- In February 2026, B. Braun Melsungen AG expanded its smart infusion pump portfolio with enhanced dose error reduction software and EHR bidirectional connectivity, securing hospital pharmacy integration approvals across leading European hospital network institutional buyers targeting medication safety improvement programs.
- In March 2026, Terumo Corporation secured a multi-year syringe and volumetric infusion pump supply agreement with a leading Asian hospital network, covering critical care and oncology department institutional procurement across its regional hospital system buyer base in Japan and Southeast Asia.
- In May 2026, Abbott Laboratories launched an enhanced ambulatory infusion pump system for outpatient chemotherapy and pain management applications, targeting oncology clinics and home care institutional buyers seeking portable infusion therapy delivery solutions enabling patient treatment outside hospital inpatient settings.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 14.5 Billion |
| Forecast Revenue (2035) | US$ 31.6 Billion |
| CAGR (2026-2035) | 8.1% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Volumetric (Large-Volume) Infusion Pumps, Syringe Infusion Pumps, Insulin Infusion Pumps, Ambulatory Infusion Pumps, Enteral Infusion Pumps, Patient-Controlled Analgesia (PCA) Pumps, Elastomeric & Implantable Pumps), By Technology (Traditional (Non-Smart) Pumps, Smart/Advanced Infusion Pumps), By Application (Diabetes Management, Chemotherapy, Analgesia, Gastroenterology, Pediatrics, Other Applications) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Abbott Laboratories, Boston Scientific Corporation, Medtronic plc, BIOTRONIK SE & Co. KG, Terumo Corporation, B. Braun Melsungen AG, Biosensors International Group Ltd., MicroPort Scientific Corporation, Meril Life Sciences Pvt. Ltd., Cook Medical LLC, C. R. Bard Inc., Alvimedica, Lepu Medical Technology (Beijing) Co., Ltd., OrbusNeich Medical Group, STENTYS SA, Other Key Players |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








