


Market Overview
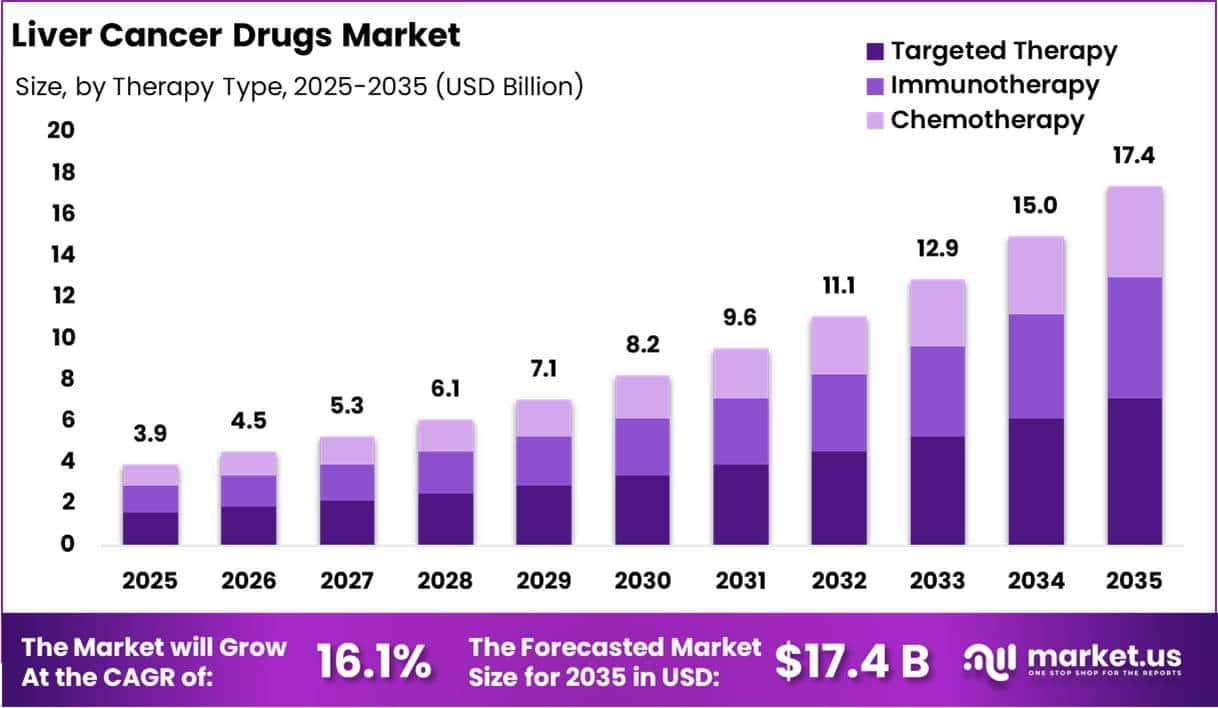
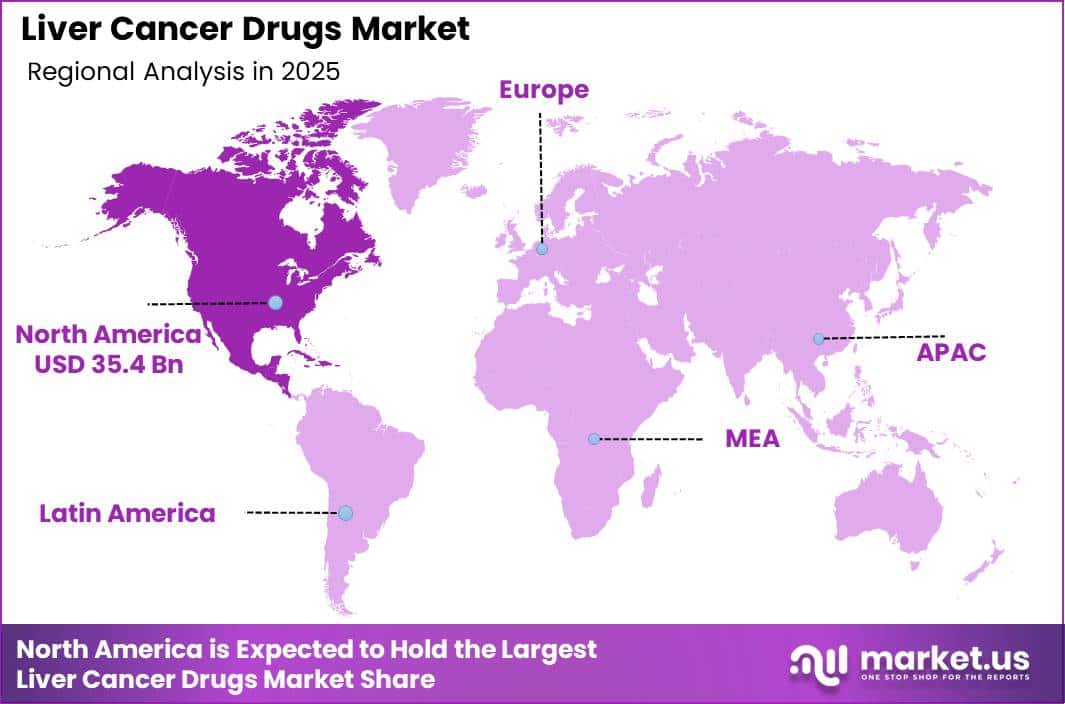
The Global Liver Cancer Drugs Market size is expected to be worth around US$ 17.4 Billion by 2035 from US$ 3.9 Billion in 2025, growing at a CAGR of 16.1% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 35.4% share with a revenue of US$ 1.38 Billion.
Liver cancer remains one of the world’s most serious cancer challenges, driving continuous advances in drug development and precision oncology. According to the World Health Organization (WHO), liver cancer is among the leading causes of cancer-related deaths globally, with hundreds of thousands of new cases diagnosed every year.
The increasing prevalence of chronic liver diseases, particularly hepatitis B, hepatitis C, non-alcoholic fatty liver disease (NAFLD), obesity, and alcohol-related liver damage, continues to expand the number of patients requiring systemic therapies.
Healthcare agencies are encouraging earlier diagnosis and broader access to treatment. The U.S. National Cancer Institute (NCI) notes that hepatocellular carcinoma (HCC) accounts for approximately 90% of primary liver cancer cases, making it the primary target for new therapeutic innovations.
Recent years have seen significant progress in targeted therapies, immune checkpoint inhibitors, and combination treatment regimens that improve survival outcomes for eligible patients.
Regulatory support is accelerating innovation across the sector. The U.S. Food and Drug Administration (FDA) has approved multiple targeted and immunotherapy-based medicines for advanced liver cancer, while ongoing clinical trials continue to evaluate novel combinations and next-generation biologics.
According to ClinicalTrials.gov, hundreds of liver cancer-related clinical studies are active worldwide, highlighting sustained investment in research and development.
Growing adoption of biomarker-guided treatment, expanding oncology infrastructure, and increasing awareness of liver disease screening are expected to strengthen demand for advanced liver cancer drugs. Continued collaboration among pharmaceutical companies, research institutions, and healthcare providers is supporting the development of more effective and personalized therapies, improving treatment options for patients with advanced liver malignancies.
Key Takeaways
- Market Size: Liver Cancer Drugs Market size was US$ 3.9 billion in 2025. The market is estimated to grow to US$ 17.4 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 16.1%.
- By Therapy Type: Targeted Therapy has the largest market share, accounting for 41.0% of total sales.
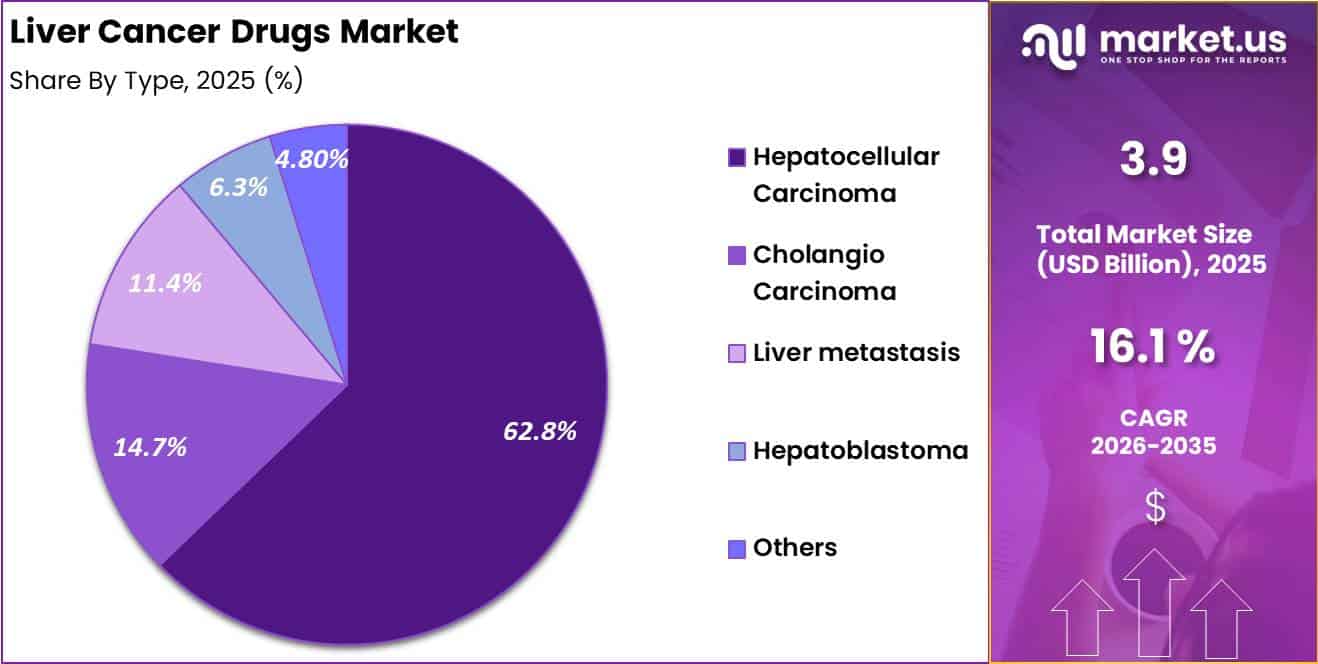
- By Type Method: Hepatocellular Carcinoma, accounting for 62.8% of total revenue.
- By Route of Administration: Oral leads the segment, accounting for 56.1% of total revenue.
- By Medication Type: Branded leads the segment, accounting for 67.4% of total revenue.
- Regional: North America is the dominant regional market,accounting for 37.1% of global sales.
Therapy Analysis
The targeted therapy segment dominated the liver cancer drugs market in 2025, accounting for 41.0% of the total market share. This leadership is driven by the growing adoption of molecularly targeted medicines that inhibit specific signaling pathways involved in tumor growth and angiogenesis.
Targeted therapies have become a preferred treatment option for patients with advanced hepatocellular carcinoma due to their ability to improve progression-free survival while offering a more favorable safety profile than conventional chemotherapy.
Continuous advancements in biomarker-based treatment selection, combination regimens, and next-generation kinase inhibitors have further strengthened segment growth. Increasing regulatory approvals and expanding clinical evidence supporting targeted drugs are also encouraging physicians to adopt these therapies as standard treatment.
Immunotherapy represented 33.6% of the market in 2025, supported by rising use of immune checkpoint inhibitors and combination immunotherapy regimens that enhance anti-tumor immune responses. Growing clinical success has increased their use in first-line and second-line treatment settings.
Meanwhile, chemotherapy accounted for 25.4% of the market. Although its market share has declined with the emergence of targeted and immune-based treatments, chemotherapy continues to play an important role in patients who are ineligible for newer therapies, particularly in resource-limited healthcare settings and as part of combination treatment strategies.
Type Analysis
The hepatocellular carcinoma (HCC) segment held the largest share of the liver cancer drugs market in 2025, capturing 62.8% of total revenue. HCC dominates because it represents the majority of primary liver cancer cases worldwide and is strongly associated with chronic hepatitis B, hepatitis C, alcohol-related liver disease, and metabolic dysfunction-associated steatotic liver disease.
Increasing disease prevalence, earlier diagnosis through surveillance programs, and the availability of multiple targeted therapies and immunotherapies have significantly expanded treatment options for HCC patients. Ongoing clinical trials evaluating novel drug combinations continue to support strong market growth within this segment.
The cholangiocarcinoma segment accounted for 14.7% of the market, driven by increasing recognition of bile duct cancers and the introduction of precision medicines targeting specific genetic alterations. Liver metastasis represented 11.4%, supported by the growing use of systemic therapies for metastatic cancers originating from colorectal, breast, and lung malignancies.
Hepatoblastoma, primarily affecting pediatric patients, contributed 6.3%, benefiting from advances in pediatric oncology treatment protocols. The others category accounted for 4.8%, covering rare liver malignancies and less common tumor subtypes requiring specialized therapeutic approaches.
Route of Administration Analysis
The oral segment dominated the liver cancer drugs market in 2025, accounting for 56.1% of total market revenue. Oral therapies have gained widespread acceptance because they provide greater convenience, improved patient adherence, and reduced dependence on hospital-based administration.
Many leading targeted therapies used for advanced liver cancer are available as oral formulations, allowing patients to continue long-term treatment from home while maintaining quality of life.
The increasing availability of oral kinase inhibitors and personalized treatment approaches has further accelerated demand. Healthcare providers also favor oral medications due to simplified dosing schedules, fewer infusion-related complications, and lower administration costs compared to injectable therapies.
The remaining market consisted primarily of injectable and intravenous formulations, including immunotherapies, monoclonal antibodies, and selected chemotherapy agents administered in hospitals or specialty infusion centers.
These therapies remain essential for patients requiring intensive treatment, combination regimens, or advanced disease management. Growing adoption of immune checkpoint inhibitors delivered intravenously continues to support this segment despite the overall dominance of oral medications.
Increasing investment in innovative drug delivery systems, improved infusion protocols, and expanded access to oncology treatment centers are expected to sustain demand for injectable therapies while oral formulations continue leading the market throughout the forecast period.
Medication Type Analysis
The branded segment led the liver cancer drugs market in 2025, accounting for 67.4% of the overall market share. The dominance of branded medicines reflects the availability of innovative targeted therapies, immunotherapies, and recently approved oncology drugs protected by intellectual property rights.
Physicians often prefer branded products because of their established clinical efficacy, extensive safety data, and strong regulatory support. Continuous investments in research and development, coupled with ongoing clinical trials evaluating combination therapies and expanded treatment indications, have strengthened the market position of branded liver cancer medications.
Premium pricing and the introduction of breakthrough therapies further contribute to the segment’s substantial revenue generation. The generic segment accounted for the remaining market share, supported by the expiration of patents for selected chemotherapy drugs and increased efforts to improve treatment affordability.
Generic medicines are particularly important in emerging economies where healthcare budgets are constrained and access to innovative therapies remains limited. Governments and healthcare systems continue promoting generic adoption to reduce treatment costs while expanding access to cancer care.
Although generic competition is increasing gradually, branded therapies are expected to maintain market leadership during the forecast period due to their continued innovation, superior clinical outcomes, and expanding use in personalized medicine strategies.
End Use Analysis
The hospitals segment dominated the liver cancer drugs market in 2025, holding 51.0% of total market revenue. Hospitals remain the primary treatment setting because liver cancer management requires multidisciplinary care involving oncologists, hepatologists, surgeons, radiologists, and specialized nursing teams.
Advanced therapies such as immunotherapy infusions, combination treatments, imaging-guided procedures, and comprehensive patient monitoring are predominantly delivered in hospital environments. The increasing number of specialized oncology centers, improved diagnostic capabilities, and expanding access to advanced cancer treatment services have further strengthened hospital demand.
Hospitals also participate actively in clinical trials evaluating next-generation liver cancer therapies, supporting early adoption of innovative medicines.
Specialty cancer clinics represented another significant end-use segment, benefiting from increasing demand for outpatient oncology services, personalized treatment planning, and long-term patient follow-up. These facilities provide convenient access to targeted therapies, supportive care, and routine monitoring while reducing hospitalization requirements.
Other healthcare settings, including ambulatory infusion centers and academic research institutions, also contribute to market growth by expanding treatment availability and supporting clinical research. Rising investments in oncology infrastructure, integrated cancer care networks, and patient-centered treatment models are expected to reinforce the leading position of hospitals throughout the forecast period.
Market Segmentations
By Therapy
- Targeted Therapy
- Immunotherapy
- Chemotherapy
By Type
- Hepatocellular Carcinoma
- Cholangio Carcinoma
- Hepatoblastoma
- Liver metastasis
- Others
By Route of Administration
- Oral
- Injectable
By Medication Type
- Generic
- Branded
- By End Use
- Hospitals
- Specialty cancer centers
- Research and academic centers
Driver
First-Line Immunotherapy Expansion Transforms HCC Treatment Growth
The strongest near-term commercial driver is the widening first-line immunotherapy menu in unresectable or metastatic hepatocellular carcinoma, because each additional approved regimen increases physician willingness to initiate systemic therapy earlier, expands biomarker-light prescribing, and raises the average revenue opportunity per treated patient.
In April 2025, the FDA approved nivolumab plus ipilimumab in the first line for unresectable or metastatic HCC, with median overall survival of 23.7 months versus 20.6 months for lenvatinib or sorafenib and an overall response rate of 36.1% versus 13.2%, creating a clinically visible efficacy signal large enough to shift tumor-board preference toward immuno-oncology combinations in eligible patients.
This matters structurally because liver cancer drug spend is no longer driven mainly by lower-intensity tyrosine kinase inhibitor monotherapy; it is increasingly driven by combination regimens, infusion-center economics, adverse-event management, and longer treatment duration in responders, all of which lift value per patient episode.
The practical market effect is highest in the U.S., EU5, Japan, and South Korea, where reimbursement pathways, multidisciplinary HCC clinics, and infusion infrastructure are already mature enough to absorb rapid standard-of-care transitions.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| First-line immunotherapy expansion in unresectable or metastatic HCC | +2.4% | North America core, EU, Japan, South Korea, urban China | Short term (≤ 2 years) |
| High viral hepatitis burden sustaining treatable HCC flow | +1.9% | APAC core, China, Southeast Asia, Sub-Saharan Africa, MENA spill-over | Medium term (2-4 years) |
| Broader diagnosis-to-treatment conversion through guideline-led staging and earlier referral | +1.5% | North America, EU, Japan, tertiary APAC corridors | Short term (≤ 2 years) |
| Metabolic liver disease and diabetes-linked HCC expansion | +1.7% | North America core, GCC, EU, urban Latin America, developed APAC | Medium term (2-4 years) |
| Medicare and payer redesign improving oral oncology affordability | +1.1% | U.S. core, selective OECD spill-over | Short term (≤ 2 years) |
| Second-line and sequencing complexity increasing therapy intensity per patient | +1.3% | North America, EU, Japan, South Korea, China top centers | Medium term (2-4 years) |
Challenge
Complex Etiology and Late Diagnosis Limit Liver Cancer Drug Growth
Liver cancer drugs operate against a structurally complex disease backdrop where heterogeneous etiologies, including chronic hepatitis B and C, alcohol-related cirrhosis, and rapidly rising metabolic liver disease such as nonalcoholic steatohepatitis (NASH), create multiple biological subtypes with divergent progression patterns and drug response profiles, driving persistent treatment inefficiency and late-stage presentation.
Globally, liver cancer accounted for roughly 7–8% of cancer deaths in 2024, with more than 700,000 deaths annually and a projected >55% increase in new cases and deaths by 2040 if current incidence trends persist, meaning that a growing share of the eligible drug-treated population arrives with Barcelona stage C–D disease, portal hypertension, or Child–Pugh B/C hepatic function, which significantly narrows the therapeutic index for systemic drugs and immunotherapy combinations.
In high-burden regions such as East Asia and parts of Sub-Saharan Africa, screening coverage remains patchy, often below 30–40% of high-risk populations, so drug developers must design regimens that can deliver incremental survival benefits of 3–6 months in cohorts with median baseline overall survival frequently under 12 months, reducing apparent effect sizes in trials and compressing commercial differentiation despite material R&D investments.
This persistent late-diagnosis skew also forces companies to maintain broader product portfolios spanning tyrosine kinase inhibitors, PD-1/PD-L1 antibodies, and loco-regional adjuncts rather than converging on a small number of high-volume first-line agents, increasing fixed cost overhead in manufacturing, pharmacovigilance, and real-world evidence generation.
As a result, global market CAGR is realistically dragged by roughly 1.4 % points versus a scenario with earlier-stage detection and more homogeneous disease biology, and mitigation requires long-horizon investments into population-level hepatitis vaccination, NASH management, and structured surveillance programs that typically unfold over 5–10 years, beyond a single product cycle.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Complex etiology & late diagnosis | -1.4% | Asia-Pacific, Sub-Saharan Africa, Latin America | Long term (≥ 4 years) |
| Trial design & recruitment complexity | -1.2% | North America core, EU oncology hubs, East Asia | Medium term (2-4 years) |
| Biomarker & stratification gaps | -1.0% | Global tertiary centers, high-SDI regions | Long term (≥ 4 years) |
| Manufacturing & cold-chain constraints | -0.9% | Emerging markets, rural care corridors | Medium term (2-4 years) |
| Pricing, access & reimbursement friction | -1.3% | North America, EU, Middle East & Africa | Long term (≥ 4 years) |
| Multimodal delivery & toxicity management | -0.8% | Global comprehensive cancer centers | Medium term (2-4 years) |
Restraints
Fragmented Reimbursement Limits Liver Cancer Drug Market Expansion
Uneven reimbursement architectures and insurance coverage gaps for liver cancer drugs create a multi-speed demand profile where high-income, well-insured segments gain early access to novel immunotherapies and targeted agents, while large pools of patients in Latin America, MENA, and parts of Asia rely on out-of-pocket payments that can exceed 1–3 times median annual household income for a full course of systemic therapy, resulting in under-treatment rates exceeding 30–40% of clinically eligible advanced HCC cases.
In the United States, while Medicare and commercial plans increasingly cover checkpoint inhibitors and locoregional innovations, coinsurance rates of 20–30% on high-cost biologics translate into patient liabilities of USD 10,000–30,000 per year, which, coupled with complex prior authorization processes and specialty pharmacy limitations, slow real-world uptake relative to approved indications and produce 15–20% abandonment rates for newly prescribed regimens in some cohorts.
Across emerging markets, the absence of robust pooled procurement, limited inclusion of newer HCC drugs on national formularies, and delayed health technology assessments can stretch time-to-reimbursement decisions to 18–36 months post-approval, effectively truncating the high-growth window during which drugs typically capture 50–60% of their potential peak share in eligible populations.
Strategically, this fragmented access picture constrains revenue scalability, forces companies to maintain dual pricing strategies with discounts of 40–60% in constrained markets, increases patient assistance program OpEx by an estimated 5–10% of sales in select geographies, and collectively knocks around 1.9 % points off the baseline market CAGR that would be achievable under more harmonized reimbursement conditions.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Aggressive oncology price controls & tendering | -2.2% | China, EU-5, emerging Asia | Long term (≥ 4 years) |
| Fragmented reimbursement & access inequality | -1.9% | US, Latin America, MENA, Southeast Asia | Medium term (2-4 years) |
| High clinical failure rates in HCC pipeline | -1.6% | Global | Long term (≥ 4 years) |
| Complex multi-modal care delivery & capacity gaps | -1.4% | APAC corridors, Sub-Saharan Africa, rural EU/US | Medium term (2-4 years) |
| Regulatory friction for advanced modalities | -1.2% | US, EU, Japan, China | Short–medium term (≤ 4 years) |
| Systemic late diagnosis & screening deficits | -1.1% | Global, especially Asia-Pacific & Africa | Long term (≥ 4 years) |
Opportunity
Subtype-Specific Precision Drugs Expand Liver Cancer Treatment Opportunities
The liver cancer drugs market remains heavily concentrated on hepatocellular carcinoma (HCC), which represents approximately 80–90% of primary liver cancers. Consequently, intrahepatic cholangiocarcinoma (ICC) and other rare subtypes remain comparatively underserved, despite having distinct molecular drivers and geographic incidence patterns.
Approximately 123,000 ICC cases were estimated globally in 2018, with the disease burden expected to increase alongside overall liver cancer incidence. South-Eastern Asia, Eastern Asia, parts of Europe, and Latin America are expected to account for a substantial share of future cases, potentially exceeding 150,000–200,000 annually by 2035.
A precision-drug strategy focused on subtype-specific portfolios, including FGFR2, IDH, and other pathway inhibitors, could expand the addressable ICC population.
When supported by biomarker-based diagnostics and subtype-segmented clinical development, treatment penetration of 25–40% could be achieved, with annual drug spending of USD 25,000–40,000 per patient. This could generate approximately USD 1.5–3.0 billion in incremental revenue and add nearly 1.8 percentage points to market CAGR.
However, this represents an opportunity rather than an established market driver. Dedicated registrational programs, companion diagnostics, payer education, targeted M&A, and co-development partnerships will be required to commercialize these smaller, higher-value patient segments through 2035.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| NASH-linked liver cancer prevention therapies | +2.5% | North America, EU, East Asia | Medium term (2–4 years) |
| Early-stage HCC adjuvant / neoadjuvant regimens | +2.2% | East Asia, North Africa, US | Short–Medium term (≤ 4 years) |
| Subtype-specific precision drugs (ICC vs HCC) | +1.8% | East Asia, EU, Latin America | Medium–Long term (≥ 3 years) |
| Low-cost combo regimens for LMICs | +2.0% | South-East Asia, India, Africa | Short term (≤ 2 years) |
| Real-world data-driven reimbursement and outcomes contracts | +1.5% | US, EU, Japan | Medium term (2–4 years) |
| Digital adherence and remote toxicity management add-ons | +1.2% | Global urban markets | Short term (≤ 2 years) |
Regional Analysis
In 2025, North America led the market, achieving over 35.4% share with a revenue of US$1.38 billion
North America region’s leadership is supported by a high prevalence of liver cancer associated with chronic hepatitis B and C infections, alcohol-related liver disease, and the growing burden of metabolic dysfunction-associated steatotic liver disease (MASLD). Strong healthcare infrastructure, widespread access to advanced diagnostic imaging, and early screening programs enable timely diagnosis and treatment, supporting higher adoption of innovative liver cancer therapies.
The presence of major pharmaceutical and biotechnology companies, along with continuous investments in oncology research, further strengthens the regional market. North America has been at the forefront of introducing targeted therapies and immune checkpoint inhibitors for hepatocellular carcinoma, supported by favorable regulatory pathways and extensive clinical trial activity.
High healthcare spending, broad insurance coverage for cancer treatments, and rapid incorporation of newly approved medicines into clinical practice also contribute to market expansion.
The United States remains the primary revenue contributor due to its advanced oncology care network, while Canada continues to expand access to precision medicine and multidisciplinary cancer management. Collaboration among academic institutions, cancer research centers, and pharmaceutical companies accelerates the development of next-generation therapeutics.
As the demand for personalized treatment approaches and combination therapies continues to increase, North America is expected to maintain its leading position in the liver cancer drugs market throughout the forecast period.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The Liver Cancer Drugs Market is moderately consolidated, with a mix of global pharmaceutical leaders and specialized oncology companies competing through advanced research, targeted therapies, and immuno-oncology innovations. Competition is driven by continuous investments in clinical development, regulatory approvals, and combination treatment strategies designed to improve patient survival and treatment outcomes.
Companies are increasingly emphasizing precision medicine, biomarker-guided therapies, and collaborative research programs to strengthen their market positions while expanding access across developed and emerging healthcare markets.
Bristol-Myers Squibb Company, Johnson & Johnson, Servier Pharmaceuticals, LLC, Bayer AG, AstraZeneca plc, Eisai Co., Ltd., Exelixis, Inc., F. Hoffmann-La Roche Ltd, Glenmark Pharmaceuticals Ltd., Amgen Inc., Merck & Co., Inc., Regeneron Pharmaceuticals, Inc., Sanofi S.A., AbbVie Inc., and Taiho Pharmaceutical Co., Ltd. are actively investing in robust R&D pipelines focused on novel targeted therapies, immunotherapies, and combination regimens for hepatocellular carcinoma and other liver cancers.
Strategic partnerships with biotechnology firms, academic institutions, and clinical research organizations help accelerate drug discovery and global clinical trials while supporting regulatory submissions across multiple regions.
Product innovation remains a primary competitive strategy, with companies pursuing next-generation checkpoint inhibitors, kinase inhibitors, antibody-based therapies, and personalized treatment approaches. Workflow integration is improving through digital clinical trial platforms, real-world evidence generation, and coordinated patient support programs that enhance treatment management.
Ecosystem-based competition is becoming increasingly important as companies collaborate with diagnostic developers, healthcare providers, and research networks to advance companion diagnostics, optimize therapeutic decision-making, and expand comprehensive oncology care, strengthening long-term competitiveness in the evolving liver cancer treatment landscape.
Top Key Players
- Bristol-Myers Squibb Company
- Johnson & Johnson
- Servier Pharmaceuticals, LLC
- Bayer AG
- AstraZeneca plc
- Eisai Co., Ltd.
- Exelixis, Inc.
- F. Hoffmann-La Roche Ltd
- Glenmark Pharmaceuticals Ltd.
- Amgen Inc.
- Merck & Co., Inc.
- Regeneron Pharmaceuticals, Inc.
- Sanofi S.A.
- AbbVie Inc.
- Taiho Pharmaceutical Co., Ltd.
Recent Developments
- In March 2025, Bristol-Myers Squibb Company received European Commission approval for Opdivo (nivolumab) plus Yervoy (ipilimumab) as a first-line treatment for adults with unresectable or advanced hepatocellular carcinoma (HCC), expanding treatment options for liver cancer patients.
- In April 2025, Bristol-Myers Squibb Company announced that the U.S. FDA approved Opdivo plus Yervoy as a first-line therapy for unresectable or metastatic hepatocellular carcinoma based on the Phase III CheckMate-9DW trial.
- In March 2026, Servier Pharmaceuticals, LLC announced an agreement to acquire Day One Biopharmaceuticals for approximately US$2.5 billion, expanding its oncology portfolio and pipeline for rare cancers.
- In June 2026, Johnson & Johnson announced the acquisition of Firefly Bio, Inc. for approximately US$1 billion, strengthening its oncology pipeline with a novel degrader antibody conjugate platform for difficult-to-treat solid tumors.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 3.9 Billion |
| Forecast Revenue (2035) | US$ 17.4 Billion |
| CAGR (2026-2035) | 16.1% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Therapy (Targeted Therapy, Immunotherapy, Chemotherapy) By Type (Hepatocellular Carcinoma,Cholangio Carcinoma, Hepatoblastoma, Liver metastasis, Others) By Route of Administration (Oral,Injectable) By Medication Type (Generic,Branded) By End Use (Hospitals, Specialty cancer centers , Research and academic centers) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Bristol-Myers Squibb Company ,Johnson & Johnson ,Servier Pharmaceuticals, LLC ,Bayer AG ,AstraZeneca plc ,Eisai Co., Ltd. ,Exelixis, Inc. ,F. Hoffmann-La Roche Ltd ,Glenmark Pharmaceuticals Ltd. ,Amgen Inc. ,Merck & Co., Inc. ,Regeneron Pharmaceuticals, Inc. ,Sanofi S.A. ,AbbVie Inc. ,Taiho Pharmaceutical Co., Ltd. |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








