


Key Findings at a Glance
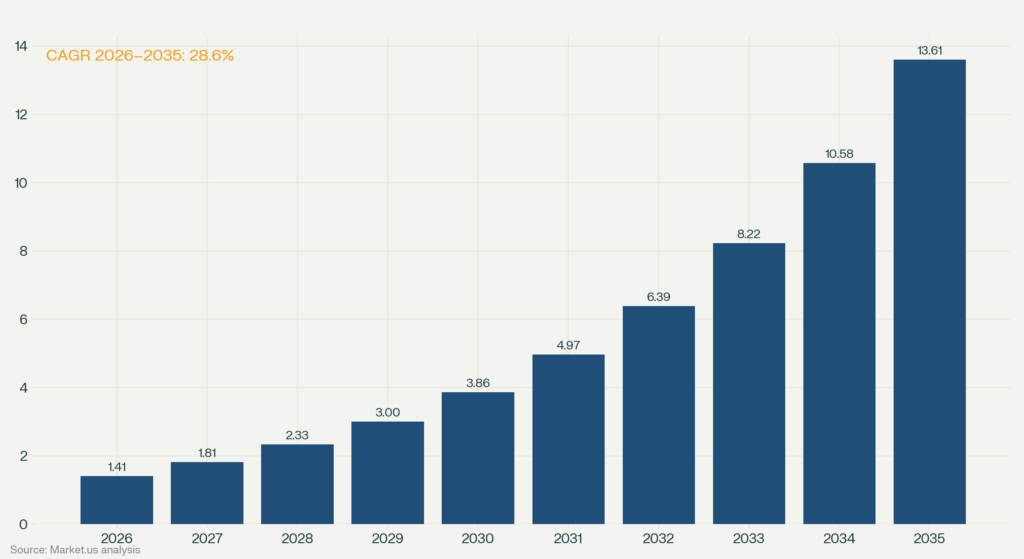
- Japan’s predictive maintenance market is estimated at USD 1.41 Billion in 2026 and is projected to reach USD 13.61 Billion by 2035, a CAGR of 28.6%.
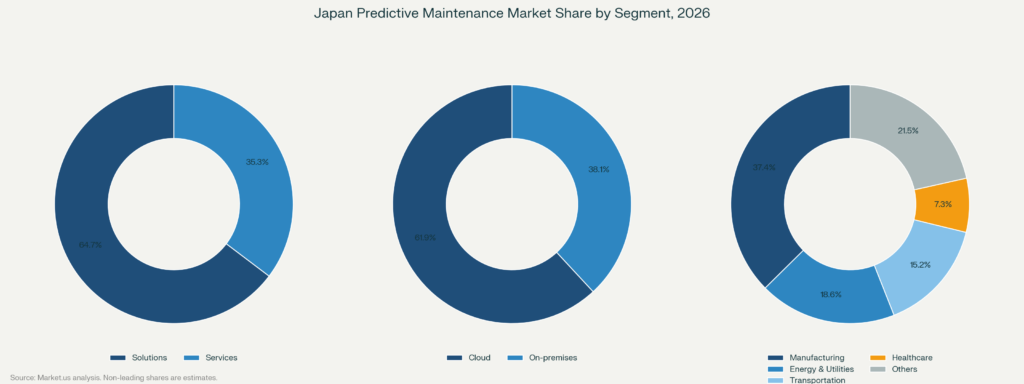
- Solutions (64.7%), Cloud (61.9%) and Manufacturing (37.4%) are the largest segments in 2026.
- Energy and Utilities is the fastest-growing end user, at a 33.0% CAGR, and its share is expected to rise from 18.6% to about 25% by 2035.
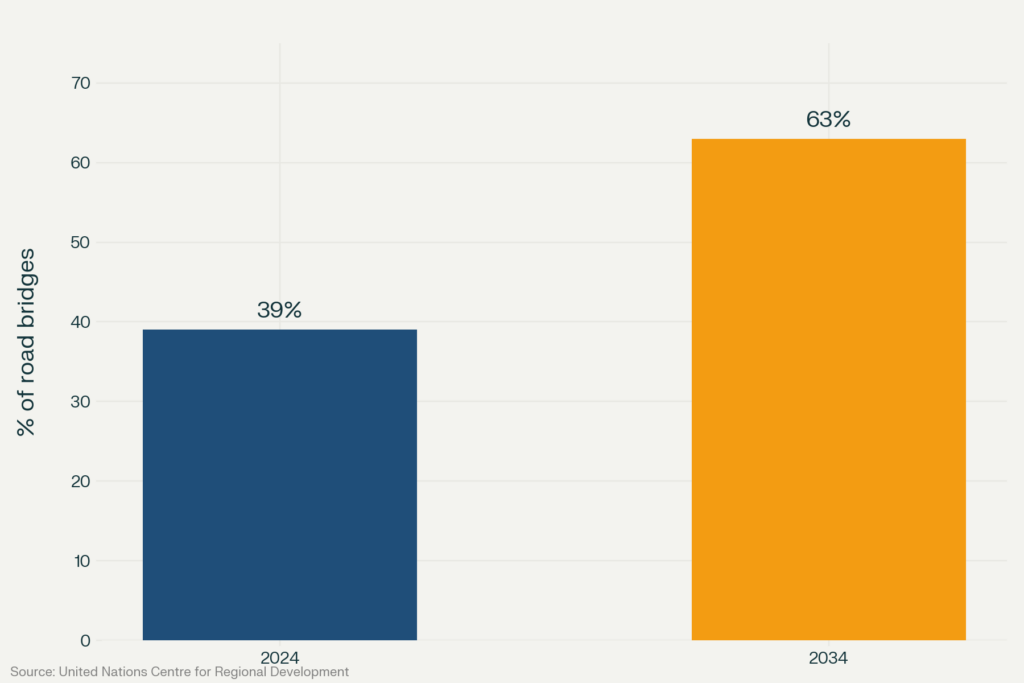
- 39% of Japan’s road bridges were more than 50 years old in 2024. That share is set to reach 63% by 2034.
- Kyushu-Okinawa (33.5% CAGR) and Tohoku (33.0% CAGR) are the fastest-growing regions, driven by new semiconductor plants.
Market Overview
The Japan Predictive Maintenance Market is estimated at USD 1.41 Billion in 2026 and is projected to reach USD 13.61 Billion by 2035, growing at a CAGR of 28.6% over the forecast period.
Manufacturing is the foundation of this market. According to the Statistics Bureau of Japan, manufacturing makes up about 20% of Japan’s nominal GDP. It runs many expensive machines, where downtime is costly and output must stay high. An unexpected breakdown doesn’t just stop production. It can also put export deadlines and long-standing supplier relationships at risk.
The forecast rests on three trends:
- Japan’s ageing industrial base needs equipment health monitoring (condition monitoring) on a large scale.
- A shrinking maintenance workforce makes manual inspection more and more expensive.
- Connected sensors in factories, railways and utilities produce the data that predictive models need.
All three trends get stronger at the same time over the forecast period. This makes the 28.6% CAGR mainly a story of buyer demand, not of technology looking for a market.
The market covers software platforms, hardware sensors and professional services used to predict when industrial equipment will fail. Enterprise resource planning (ERP) software and general factory automation are outside its scope. Predictive maintenance forecasts when equipment will fail. Prescriptive maintenance also recommends what to do about it. The line between the two is blurring, but this report counts prescriptive systems only when they run on the same platform as predictive diagnostics.
In June 2026, Hitachi and Intel announced a strategic collaboration that includes using physical AI for predictive diagnostics and maintenance optimisation in semiconductor manufacturing. Physical AI combines real-world sensor data with digital simulation, rather than relying on software models alone. Vendors without similar partnerships may lose ground as buyers expect more accurate predictions.
Analyst insight: “This market is still small next to the companies that sell into it. At about ¥220.6 billion in 2026, Japan’s whole predictive maintenance market is only about 5% of Hitachi’s Lumada digital business alone, which earned ¥4,146.0 billion in the year to March 2026. That gap shows predictive maintenance is still an early-stage niche inside much larger digital and industrial portfolios. That is why a high growth rate from a small base is realistic. It is also why the large conglomerates, not start-ups, are best placed to capture the growth.”
— Research Team Market.us
Market Definition
This report measures annual spending on predictive maintenance in Japan. It includes:
- Solutions: Software platforms for collecting data, detecting anomalies and forecasting failures, plus related sensors and edge devices sold as part of predictive maintenance programmes.
- Services: Consulting, system integration, sensor installation, model training, and managed monitoring services.
The market covers manufacturing, energy and utilities, transportation, healthcare and other end users, deployed in the cloud or on-premises. It excludes general ERP software, general factory automation hardware, and maintenance labour that is not linked to predictive systems.
Key Takeaways
- The market is valued at USD 1.41 Billion in 2026 and is expected to reach USD 13.61 Billion by 2035, at a CAGR of 28.6%.
- By Component: Solutions led with a 64.7% share in 2026.
- By Deployment: Cloud led with a 61.9% share in 2026.
- By End User: Manufacturing led with a 37.4% share in 2026.
- By Region: Kanto led with a 35.8% share in 2026.
- Fastest-growing categories: Services (31.5% CAGR), Cloud (30.0%), Energy and Utilities (33.0%), and Kyushu-Okinawa (33.5%).
- Top key players: TDK Corporation, Sony AI, Toshiba Digital Solutions Corporation, Hitachi Vantara, NEC Corporation, Mitsubishi Electric Corporation, Fujitsu Limited, Omron Corporation, Yokogawa Electric Corporation and NTT Data.
Key Market Statistics
| Indicator | Value | Source |
|---|---|---|
| Manufacturing share of nominal GDP | About 20% | Statistics Bureau of Japan |
| Tokyo share of national GDP (2022) | 20.2% | Cabinet Office prefectural accounts |
| Road bridges over 50 years old | 39% (2024) → 63% (2034) | United Nations Centre for Regional Development |
| Infrastructure maintenance and renewal spending | ¥2.6–2.7 trillion a year by FY2038 | MLIT |
| Japan data centre electricity demand growth to 2030 | +15 TWh (+80%) | IEA |
| Japan merchandise exports (2025) | US$708.5 billion | WTO |
| Cumulative government R&D support for Rapidus | ¥2.354 trillion | METI |
| JASM (TSMC) Kumamoto total investment | Over US$20 billion | TSMC |
| Kioxia–Sandisk planned investment in Japan (to 2032) | Over ¥5 trillion | Kioxia, Sandisk |
| Hitachi FY2025 revenue (year to March 2026) | ¥10,586.7 billion (+8%) | Hitachi |
| Average exchange rate, 2026 | ¥156.44 per USD | Market exchange rate data |
Research Methodology
How the Market Size Was Built
| Component (2026) | Basis | Value (¥ billion) | Value (USD Mn) |
|---|---|---|---|
| Solutions | Software, platform and sensor revenue from predictive maintenance programmes (vendor-level estimate) | 142.7 | 912.3 |
| Services | Consulting, integration, installation and managed monitoring revenue (vendor-level estimate) | 77.9 | 497.7 |
| Total | 220.6 | 1,410.0 |
USD values use the 2026 average exchange rate of ¥156.44 per USD.
Forecast Approach
The 28.6% USD CAGR for 2026–2035 combines two drivers:
- Growth in yen (about 25.8% a year): Adoption is rising from a low base. The drivers are ageing assets, workforce shortages, semiconductor and data centre investment, and growing use of cloud and AI-based platforms.
- Yen recovery (about 2.2% a year): The forecast assumes the yen gradually strengthens from ¥156 per USD in 2026. At a constant exchange rate, the CAGR would be about 25.8%.
Segment and regional CAGRs are set above or below the national rate based on investment pipelines and adoption trends. They are balanced so that each segment adds up to the national forecast.
Data and Validation
- Top-down: Data on industrial activity, infrastructure age, energy demand and investment came from the Statistics Bureau, MLIT, METI, the IEA and the WTO. It was used to size demand by end user and region.
- Bottom-up: Vendor results and announced projects were used to check the totals and segment trends.
- Modelled figures: Non-leading segment shares, regional shares other than Kanto, and all 2035 values and CAGRs are Market.us estimates. They are labelled as estimates throughout.
- Primary and expert validation: For this 2026 edition, findings were checked against first-hand statements from market participants published between February 2024 and September 2026. Analysts reviewed Hitachi’s results for the fiscal year ended 31 March 2026, including Lumada business performance and guidance. Analysts also reviewed 10 developments announced between February 2024 and September 2026, involving TSMC, NEC, Rapidus, METI, Hitachi, Intel, TDK, Mitsubishi Electric, Kioxia, Sandisk, Fujitsu and Schneider Electric. These were used to validate technology, investment and regional growth trends. Assumptions were checked against METI’s Rapidus funding decision (April 2026), MLIT’s infrastructure maintenance cost estimates, IEA electricity demand projections and WTO trade data.
How this report was produced: Market.us analysts collected and checked data from government statistics, international agencies and company filings. AI tools assisted with drafting and formatting. All figures, analysis and conclusions were reviewed and approved by Market.us Research Team before publication.
| Segment | Category | 2026 Share | 2026 Value (USD Mn) | 2035 Value (USD Mn) | CAGR 2026–2035 |
|---|---|---|---|---|---|
| Component | Solutions | 64.7% | 912.3 | 7,757.7 | 26.85% |
| Component | Services | 35.3% | 497.7 | 5,852.3 | 31.50% |
| Deployment | Cloud | 61.9% | 872.8 | 9,255.5 | 30.00% |
| Deployment | On-premises | 38.1% | 537.2 | 4,354.5 | 26.18% |
| End User | Manufacturing | 37.4% | 527.4 | 4,264.3 | 26.14% |
| End User | Energy and Utilities | 18.6% | 262.3 | 3,415.0 | 33.00% |
| End User | Transportation | 15.2% | 214.3 | 2,195.3 | 29.50% |
| End User | Healthcare | 7.3% | 102.9 | 1,129.9 | 30.50% |
| End User | Others | 21.5% | 303.1 | 2,605.5 | 27.00% |
Note: Leading shares come from the Market.us model. Other shares, all 2035 values and all CAGRs are Market.us estimates.
Component Analysis
Solutions led the Component segment with a 64.7% share in 2026, worth USD 912.3 Million.
Software platforms for collecting data, detecting anomalies and forecasting failures take the largest share. Buyers see them as the core of any predictive maintenance programme. According to the Japan Automobile Manufacturers Association, automotive shipments reached ¥71.6 trillion, 19.2% of all manufacturing shipments. At that scale of production, protecting high-speed lines from breakdowns is worth far more than a software subscription. Predictive maintenance platforms are now often a purchasing requirement for tier-one automotive suppliers, not an optional upgrade.
Services are the fastest-growing component, at an estimated 31.5% CAGR. Mid-sized manufacturers and utilities often lack in-house data scientists. Managed services that bundle sensor installation, model training and continuous monitoring are growing quickly. Vendors offering outcome-based contracts, where fees depend on measured reductions in downtime rather than the number of software licences, are winning deals that traditional licence-based platforms cannot.
Deployment Analysis
Cloud led the Deployment segment with a 61.9% share in 2026, worth USD 872.8 Million.
Cloud deployment leads because it removes the upfront hardware and software cost that once slowed adoption among Japan’s mid-sized manufacturers. Cloud platforms train models across several plants at once, update automatically and add computing power when diagnostic workloads peak. Together, these give cloud platforms a lower total cost than on-premises systems. Connecting factory sensors to cloud analytics through the industrial internet of things (IIoT) is now a standard design for new projects. Cloud is also the faster-growing deployment type, at an estimated 30.0% CAGR.
On-premises deployment remains common in regulated industries. It is also used in facilities whose operational technology (OT) networks, the systems that control machines, cannot connect to the public cloud without breaking cybersecurity rules. Hybrid systems are becoming the preferred option for large manufacturers that need to keep on-site control. In these systems, devices at the edge of the network handle time-critical predictions on site, while cloud platforms store historical data and retrain models.
End User Analysis
Manufacturing accounted for 37.4% of End User demand in 2026, worth USD 527.4 Million, the highest of any category.
Japan’s manufacturing sector has many expensive machines, tough uptime targets and direct financial exposure when breakdowns disrupt export contracts. Spending focuses on press lines, CNC machining centres and conveyor systems, where failures are immediately costly.
Energy and Utilities is the fastest-growing end user, at an estimated 33.0% CAGR. Utilities face regulatory pressure to extend asset life and reduce power cuts without hiring many more maintenance staff. Data centre growth adds to this. The IEA expects Japan’s data centre electricity demand to rise by about 15 TWh, or 80%, by 2030.
Transportation operators use predictive maintenance on trains, signalling equipment and trackside assets. Healthcare is an emerging user, monitoring imaging systems and air-conditioning equipment in hospitals, where failures can affect patient safety. Predictive maintenance is spreading across all these sectors, moving from a manufacturing tool to a standard practice across industries.
Analyst insight: “The market’s centre of gravity is shifting away from factories. Manufacturing leads today with 37.4% of demand, but by 2035 we expect its share to fall to about 31%. Over the same period, Energy and Utilities should rise from 18.6% to about 25%. The reason is simple: Japan’s power grid, data centres and public infrastructure are ageing faster than utilities can hire maintenance staff, and the IEA expects Japan’s data centre electricity demand to rise 80% by 2030. Vendors that build energy and utility expertise now will capture the fastest-growing part of the market.”
— Research Team Market.us
Key Market Segments
By Component
- Solutions
- Services (fastest growing)
By Deployment
- Cloud (fastest growing)
- On-premises
By End User
- Manufacturing
- Energy and Utilities (fastest growing)
- Transportation
- Healthcare
- Others
Regional Analysis
| Region | 2026 Share | 2026 Value (USD Mn) | 2035 Value (USD Mn) | CAGR 2026–2035 |
|---|---|---|---|---|
| Kanto | 35.8% | 504.9 | 4,139.6 | 26.34% |
| Central/Chubu | 18.9% | 266.5 | 2,636.3 | 29.00% |
| Kansai/Kinki | 17.0% | 239.7 | 2,210.8 | 28.00% |
| Kyushu-Okinawa | 10.3% | 145.2 | 1,956.1 | 33.50% |
| Chugoku | 6.3% | 88.8 | 736.8 | 26.50% |
| Tohoku | 6.1% | 86.0 | 1,120.0 | 33.00% |
| Hokkaido | 3.2% | 45.1 | 549.0 | 32.00% |
| Shikoku | 2.4% | 33.8 | 261.4 | 25.50% |
| Total | 100% | 1,410.0 | 13,610.0 | 28.60% |
Note: Shares other than Kanto’s, and all CAGRs, are Market.us estimates.
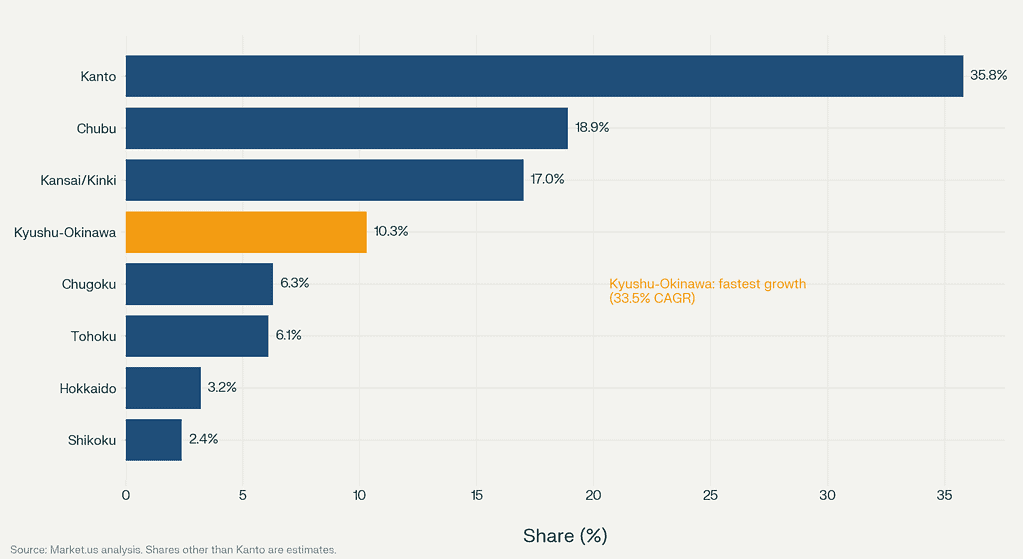
Kanto Region
Kanto led with a 35.8% share in 2026, worth USD 504.9 Million.
Tokyo alone accounted for 20.2% of Japan’s GDP in 2022, according to the Cabinet Office’s prefectural accounts. Kanto has the most corporate headquarters, advanced manufacturing clusters and connected industrial facilities in Japan. Buyers here have the purchasing authority and budgets to roll out enterprise platforms across many sites, which makes Kanto the largest region by a wide margin.
Central/Chubu Region
Chubu is the second-largest region, with an estimated 18.9% share. According to Aichi Prefecture’s industrial statistics, Aichi has recorded Japan’s highest annual value of manufactured goods shipments every year since 1977. The region’s dense automotive supply chain, centred on Toyota, creates demand for predictive maintenance at every supplier tier. Tier-two and tier-three suppliers now face requirements from car makers to provide equipment reliability data. This is pulling smaller manufacturers into monitoring programmes they had previously put off.
Kansai/Kinki Region
Kansai produces about 16% of Japan’s GDP, according to the EU-Japan Centre, supported by heavy industry in Osaka and Hyogo and precision machinery in Kyoto. Chemical plants, electronics makers and port operators here run continuous processes where unplanned stoppages are expensive to restart. This makes Kansai a strong market for condition monitoring in process industries.
Kyushu-Okinawa Region
Kyushu-Okinawa is the fastest-growing region, at an estimated 33.5% CAGR. According to TSMC, total investment in Japan Advanced Semiconductor Manufacturing (JASM) in Kumamoto exceeds US$20 billion, with monthly capacity of more than 100,000 12-inch wafers. Chip plants have some of the strictest uptime requirements of any industry. Kyushu’s fast build-out of chip capacity creates large, immediate demand for systems that monitor cleanroom equipment, lithography machines and ultra-pure water systems.
Tohoku Region
Tohoku is the second-fastest-growing region, at an estimated 33.0% CAGR. Kioxia plans to build a third chip plant (Fab3) at its Kitakami site in Iwate Prefecture. The plant has a total budget of ¥1.8 trillion, including more than ¥1 trillion for initial construction, and output is planned for fiscal 2029. Together with existing automotive and food processing plants in Miyagi and Iwate, this is drawing predictive maintenance vendors into a previously underserved region. New plant construction lets vendors build monitoring in from the start, rather than retrofitting old equipment.
Chugoku Region
Chugoku has steel production, shipbuilding and chemical manufacturing in Hiroshima and Yamaguchi. These industries use equipment with long replacement cycles, which makes the cost-benefit case for predictive maintenance especially strong. Buyers here usually prefer to retrofit existing equipment rather than build new systems. This creates demand for sensor integration services that work with older machines without built-in connectivity.
Hokkaido Region
Cumulative Japanese government R&D support for Rapidus reached ¥2.354 trillion after a ¥631.5 billion top-up in April 2026, according to METI. The government has also invested ¥250 billion in Rapidus shares. Rapidus plans to make 2nm chips in Chitose, which positions Hokkaido as an emerging high-tech manufacturing cluster. Its predictive maintenance needs will match semiconductor-level precision. This gives monitoring vendors a long-term reason to build early relationships with Rapidus’s suppliers.
Shikoku Region
Shikoku’s industry centres on petrochemicals and paper, with continuous processes and ageing plants. Adoption lags the larger regions, partly because smaller operators have few in-house technical staff to run monitoring platforms. Subscription-based managed services address this gap directly, and vendors offering turnkey services are starting to target Shikoku’s underserved industrial base.
Analyst insight: “Japan’s semiconductor build-out is reshaping the regional map. JASM in Kumamoto (over US$20 billion, about ¥3.1 trillion), Rapidus in Hokkaido (¥2.354 trillion in government R&D support) and Kioxia’s new Kitakami plant (¥1.8 trillion) add up to over ¥7 trillion of chip investment outside the traditional industrial centres. Kyushu-Okinawa, Tohoku and Hokkaido together hold only 19.6% of the market in 2026, but we expect their combined share to rise to about 26.6% by 2035. Chip plants need monitoring from day one, so vendors that set up local teams early will win long-term contracts.”
— Research Team Market.us
Macroeconomic Impact
According to the WTO, Japan’s merchandise exports reached US$708.5 billion in 2025. The United States took 18.6%, China 17.0% and the EU 9.1%. Japan’s tariff exposure is limited: its simple average most-favoured-nation (MFN) tariff is 3.8%, and its trade-weighted average is 2.6%. Any trade friction with the US or China pushes exporters to protect margins by cutting costs, which strengthens the business case for predictive maintenance.
The WTO expects world trade to slow in 2026 after stronger-than-expected growth in 2025, which was driven largely by trade in AI-related products. Slower exports cut revenue for Japanese manufacturers, while their fixed asset costs stay the same. Companies under margin pressure respond by extending the life of their equipment and avoiding unplanned downtime instead of buying new capacity. Both responses speed up predictive maintenance adoption as a way to manage costs.
Market Dynamics
Driver: Ageing Infrastructure and Industry 4.0 Expand Condition-Based Maintenance
According to the United Nations Centre for Regional Development, 39% of Japan’s road bridges were more than 50 years old in 2024, and this is set to reach 63% by 2034. Infrastructure this old cannot be maintained affordably by waiting for things to break. Factory equipment, trains and utility assets across Japan are ageing in the same way. This is driving a broad shift towards monitoring-based maintenance.
Japan’s energy sector faces similar pressure. The IEA expects Japan’s data centre electricity demand to rise by about 15 TWh, or 80%, by 2030. Globally, it expects data centre electricity use to rise from 415 TWh in 2024 to about 945 TWh by 2030, roughly 15% a year. Data centre operators running at this energy intensity cannot afford cooling or power failures, so predictive monitoring of mechanical and electrical equipment becomes a financial necessity. Factory automation investments already under way across Japan provide the sensor networks that predictive models depend on.
Restraint: Mixed Legacy Equipment and Cybersecurity Risks Slow Adoption
United Nations Centre for Regional Development research shows that preventive maintenance limits the 30-year rise in road maintenance costs to about 30%. Corrective maintenance, which fixes things only after they break, raises costs by about 140% over the same period. The difference is well understood, yet many Japanese operators still rely on corrective maintenance because their equipment lacks the sensors and network connections that predictive models need. With older and newer machines mixed together, a prediction is only as accurate as the weakest data source.
Cybersecurity adds to the problem. Japanese factory control networks (operational technology, or OT) were designed to be isolated, not connected. Linking them to cloud platforms creates new points of attack that factory security teams are not yet staffed to manage. When cybersecurity reviews flag unresolved risks in connecting OT with corporate IT systems, enterprise contracts can be delayed by six to eighteen months at conservative industrial companies.
Opportunity: Retrofits of Existing Assets and Subscription Services for Mid-Sized Manufacturers
According to MLIT, Japan’s infrastructure maintenance and renewal spending is projected to rise from ¥1.9 trillion in FY2018 to ¥2.6–2.7 trillion in FY2038, totalling ¥71.6–76.1 trillion over 30 years. Public asset owners on this spending path cannot afford to replace everything that breaks. Fitting predictive maintenance to existing bridges, tunnels and railways (brownfield retrofits) extends their life without the cost of full replacement.
Analyst insight: “The economics of predictive maintenance are clearest in public infrastructure. United Nations research shows preventive maintenance limits the 30-year rise in road maintenance costs to about 30%, against roughly 140% if operators wait for things to break. That is a difference of almost five times. With MLIT expecting ¥71.6–76.1 trillion of maintenance and renewal spending over 30 years, even small efficiency gains are worth trillions of yen. This is why we expect brownfield retrofits to be the biggest near-term opportunity, especially for vendors whose sensors work with older equipment.”
— Research Team Market.us
Subscription-based managed services close the skills gap that stops mid-sized manufacturers from adopting predictive maintenance on their own. Smaller producers cannot hire the data scientists, machine learning engineers and sensor specialists that an in-house programme needs. Vendors that bundle hardware, model development and outcome reports into a fixed monthly fee turn a large upfront purchase into a predictable running cost. This opens up a group of buyers that enterprise platform vendors have largely ignored.
Porter’s Five Forces
| Force | Level | Explanation |
|---|---|---|
| Threat of new entrants | Moderate, rising barriers | Established vendors build up years of customer data, which new entrants can’t match for model accuracy |
| Supplier power | Moderate | Sensor hardware is becoming a commodity, but AI chip suppliers and cloud providers hold strong leverage |
| Buyer power | High | Large manufacturers run competitive tenders and demand proof-of-concept results before signing multi-year contracts |
| Threat of substitutes | Moderate | Scheduled preventive maintenance and manual inspection remain credible alternatives for smaller operators |
| Competitive rivalry | High | Japanese conglomerates and global software vendors compete for the same enterprise accounts, which squeezes margins and pushes competition towards service quality, accuracy and integration |
AI and Gen AI Impact
According to the IEA, data centres used about 1.5% of global electricity in 2024, and this share is set to approach 3% by 2030. The computing infrastructure that trains and runs AI models is itself within predictive maintenance’s addressable market. AI data centres need the same equipment monitoring as traditional industrial assets. This creates a self-reinforcing loop: AI adoption both uses predictive maintenance services and improves them.
Generative AI is changing how predictive maintenance diagnoses problems. Technicians can now ask about alerts and asset histories in plain language, without writing database queries. Digital twins are virtual models of physical equipment. Combined with generative AI, they simulate failure scenarios that train predictive models faster than historical failure data alone. Early adopters that build generative AI into maintenance workflows shorten the time from spotting a problem to fixing it. Vendors without AI-native systems cannot close this gap through software updates alone.
Market Trends
Platforms Combine Prediction and Prescription
Japan’s predictive maintenance platforms are moving beyond simple failure alerts. Vendors are adding prescriptive features that turn a failure prediction into a specific repair instruction, a parts order and a technician schedule. Machine vision adds visual defect detection to sensor-based monitoring, so platforms can cover more types of assets without extra hardware. Buyers choosing platforms in 2026 increasingly treat prescriptive features as standard rather than premium, which leaves less time for alert-only vendors to keep their enterprise customers.
Physical AI and Semiconductor-Grade Monitoring
Hitachi and Intel’s June 2026 collaboration shows a shift towards physical AI. Hitachi collects high-precision data from its semiconductor metrology and etching systems on its ExTOPE platform, and uses physical AI to predict equipment failures and optimise maintenance. As Japan builds new chip plants in Kyushu, Hokkaido and Tohoku, this kind of semiconductor-grade monitoring is likely to set the standard for other high-precision industries.
Market Competition Overview
The market is moderately concentrated among large enterprise vendors, where Japanese conglomerates compete directly with global industrial software companies.
- Hitachi: Revenue from its Lumada digital business reached ¥4,146.0 billion in the year to March 2026, 40% of group revenue. This gives Hitachi Vantara a large base for industrial data services.
- Mitsubishi Electric: The company states a target of ¥200 billion in energy solutions revenue by FY2031. In August 2026, it agreed to acquire PCI Energy Solutions for a base price of US$1.4 billion, which signals a push to bundle predictive monitoring into wider energy management platforms.
- Siemens: According to its FY2025 annual report, Siemens added €2.4 billion to intangible assets and property, plant and equipment, reflecting continued investment in the software and hardware behind its industrial analytics.
In October 2025, NEC agreed to acquire CSG Systems International for about US$2.89 billion, which expands its software services and data management capabilities.
The mid-sized and small manufacturer segments remain fragmented, with dozens of specialist vendors competing on price and ease of integration. Concentration at the top is increasing, as large vendors buy niche analytics companies to fill capability gaps faster than their own R&D can.
Company Profiles
Hitachi Vantara (Hitachi, Ltd.)
Hitachi Vantara places predictive maintenance within a wider industrial data platform that connects factory sensor data to corporate IT systems. Hitachi’s consolidated revenue reached ¥10,586.7 billion in the year to March 2026, up 8%, and net income rose 30.3% to ¥802.3 billion. Its Lumada digital business earned ¥4,146.0 billion, 40% of revenue. In June 2026, Hitachi and Intel announced a collaboration covering physical AI, edge AI and factory automation, including predictive diagnostics for semiconductor manufacturing equipment. Hitachi’s scale lets it train AI models on its own industrial equipment base, a data advantage that pure software competitors cannot easily copy through partnerships.
Siemens AG
Siemens competes through its Xcelerator platform, which combines predictive analytics, digital simulation and industrial automation management in one environment. According to its FY2025 annual report, its taxonomy-aligned operating expenditure, weighted towards R&D, reached €2.7 billion. (“Taxonomy-aligned” refers to spending that qualifies as sustainable under EU rules.) This R&D supports Siemens’ strength in physics-based simulation models, which perform better than data-only approaches for equipment with little failure history. Japan matters strategically for Siemens, because its relationships with automotive and electronics manufacturers provide a base for expanding predictive services across supplier networks.
Key Players
- TDK Corporation
- Sony AI
- Toshiba Digital Solutions Corporation
- Hitachi Vantara
- NEC Corporation
- Mitsubishi Electric Corporation
- Fujitsu Limited
- Omron Corporation
- Yokogawa Electric Corporation
- NTT Data
- Panasonic Corporation
- Microsoft Corporation
- IBM Corporation
- Siemens AG
- SAP SE
- General Electric
- Rockwell Automation
- Schneider Electric SE
- PTC Inc.
- ABB Ltd.
Pricing Analysis
Japan’s predictive maintenance market uses three main pricing models:
- Enterprise software licences: Upfront fees range from tens of millions to hundreds of millions of yen. Annual maintenance and support adds 15–20% of the licence value.
- Subscription-based managed services: Priced per monitored asset or per plant, these are gaining share because they turn a large upfront cost into a predictable running cost.
- Hardware-bundled offerings: Sensor costs are built into multi-year service agreements. This lowers the apparent entry price while securing long-term recurring revenue.
Price competition is fiercest in the mid-market managed services segment, where Japanese and global vendors compete for manufacturers that cannot accept enterprise contract terms. Enterprise leaders compete on model accuracy and integration rather than price, and protect margins by proving measurable reductions in downtime. Challengers in both segments use outcome-based pricing, where fees scale with verified savings, to win customers from incumbents.
Supply Chain and Value Chain Analysis
The value chain runs from sensor and chip makers, through platform and analytics vendors, system integrators and service providers, to equipment owners. Most value is created at the platform and analytics layer, where data becomes predictions, and at the managed services layer, where predictions become maintenance actions. Sensor hardware is becoming a commodity, while AI chip and cloud computing providers hold concentrated power over platform costs.
The main bottleneck is integration with older equipment. Many machines in Japanese factories lack built-in sensors or network connections, so retrofitting them needs specialist integration work. A second bottleneck is the shortage of data scientists and OT security specialists. Vendors that standardise retrofit kits and offer managed security services reduce both problems.
Regulatory Landscape
Several rules shape the market:
- Infrastructure inspections: MLIT requires regular inspections of bridges and tunnels. This creates a strong policy case for monitoring-based maintenance of public infrastructure, and MLIT’s long-term maintenance cost estimates encourage owners to move from corrective to preventive maintenance.
- Cybersecurity: Cybersecurity guidelines for factory control systems, promoted by METI, increasingly shape how predictive platforms connect OT networks to the cloud. Utilities and other critical infrastructure operators face stricter security requirements, which favours vendors with proven OT security credentials.
- Data protection: Japan’s data protection rules apply where maintenance data includes personal information, for example technician records.
- Semiconductor subsidies: Government support for chip plants, including Rapidus and JASM, indirectly drives demand for advanced monitoring systems in new facilities.
Investment and White Space Analysis
Investment is concentrated in three areas:
- Monitoring for new chip plants in Kyushu, Hokkaido and Tohoku.
- AI-based platforms, including physical AI and generative AI diagnostics.
- Acquisitions that expand vendors’ energy and software capabilities, such as Mitsubishi Electric–PCI Energy Solutions and NEC–CSG.
The biggest white space is managed predictive maintenance for mid-sized manufacturers and regional utilities. Few vendors offer affordable, turnkey services that work with older equipment and include OT security. Brownfield retrofits for public infrastructure are a second major opportunity. They are backed by MLIT’s long-term spending plans and by the growing number of ageing bridges, tunnels and railways.
Analyst View
- The market is small compared with its vendors’ digital businesses, so strong growth from a low base is realistic.
- Energy and Utilities (33.0% CAGR) will gain share from manufacturing as grid, data centre and infrastructure ageing speeds up.
- Semiconductor investment of over ¥7 trillion is shifting growth towards Kyushu-Okinawa, Tohoku and Hokkaido.
- Managed services (31.5% CAGR) will grow fastest, because mid-sized buyers lack in-house skills.
- Integrating older equipment and OT cybersecurity remain the main barriers. Vendors that solve both will lead.
Recent Developments
- September 2026: Fujitsu announced global sales of its 2nm FUJITSU-MONAKA CPU from November 2026, aimed at high-performance computing and AI inference workloads.
- September 2026: Schneider Electric planned a €1.2 billion bid for Shelly, to widen its range of smart energy monitoring and control devices.
- 27 August 2026: Kioxia and Sandisk announced plans to invest over ¥5 trillion (more than US$31 billion) in Japan through 2032, including a new ¥1.8 trillion Fab3 at the Kitakami Plant in Iwate Prefecture, with output planned for fiscal 2029.
- August 2026: Mitsubishi Electric agreed to acquire all of PCI Energy Solutions for a base price of US$1.4 billion, expanding its energy management and industrial services portfolio in North America.
- June 2026: TDK agreed to acquire Fabric8Labs for up to US$400 million, adding electrochemical additive manufacturing (a type of 3D printing) to its sensor and component technology roadmap.
- 5 June 2026: Hitachi and Intel announced a strategic collaboration covering physical AI, edge AI and factory automation. It includes predictive diagnostics and maintenance optimisation for semiconductor manufacturing equipment.
- April 2026: METI approved an additional ¥631.5 billion (US$3.96 billion) for Rapidus R&D, bringing cumulative government R&D support to ¥2.354 trillion.
- 27 February 2026: Rapidus completed a ¥267.6 billion (US$1.7 billion) funding round from the Japanese government and private companies, supporting chip production scale-up in Chitose.
- October 2025: NEC agreed to acquire CSG Systems International for about US$2.89 billion, expanding its software services and data management capabilities.
- February 2024: TSMC, Sony Semiconductor Solutions, DENSO and Toyota announced a second JASM fab in Kumamoto, taking total investment above US$20 billion.
Report Scope
| Report Characteristics | Details |
|---|---|
| Market Value (2026) | USD 1.41 Billion |
| Forecast Revenue (2035) | USD 13.61 Billion |
| CAGR (2026 to 2035) | 28.6% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020 to 2024 |
| Forecast Period | 2026 to 2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Component (Solutions, Services), By Deployment (Cloud, On-premises), By End User (Manufacturing, Energy and Utilities, Transportation, Healthcare, Others) |
| Regions Covered | Kanto, Central/Chubu, Kansai/Kinki, Kyushu-Okinawa, Chugoku, Tohoku, Hokkaido, Shikoku |
| Competitive Landscape | TDK Corporation, Sony AI, Toshiba Digital Solutions Corporation, Hitachi Vantara, NEC Corporation, Mitsubishi Electric Corporation, Fujitsu Limited, Omron Corporation, Yokogawa Electric Corporation, NTT Data, Panasonic Corporation, Microsoft Corporation, IBM Corporation, Siemens AG, SAP SE, General Electric, Rockwell Automation, Schneider Electric SE, PTC Inc., ABB Ltd. |
| Customization Scope | Customization for segments and region or country level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | Three license options: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited Users and Printable PDF) |








