


Market Overview
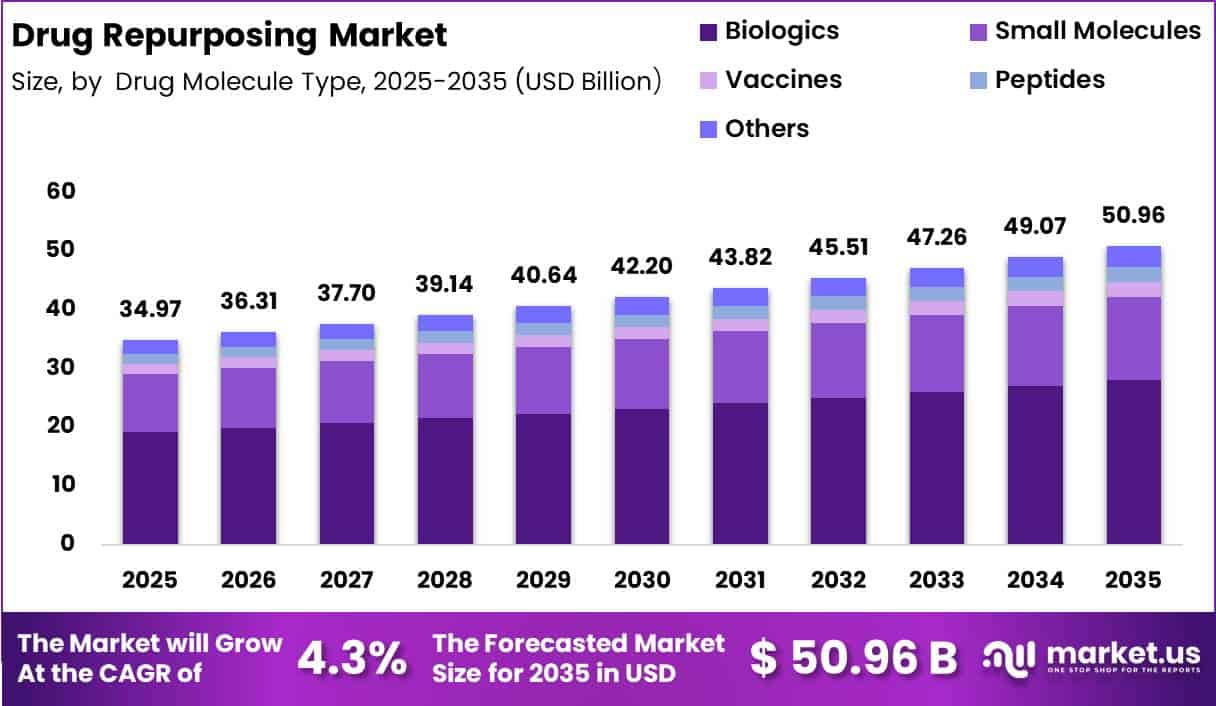
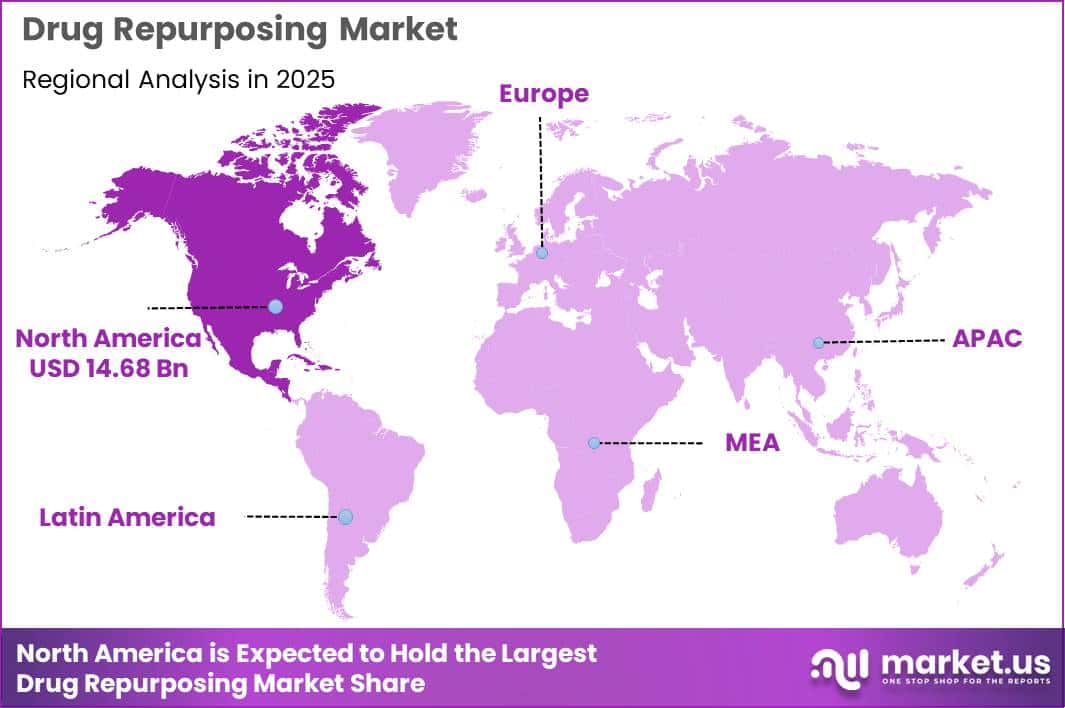
The Global Drug Repurposing Market size is expected to be worth around US$ 50.96 Billion by 2035 from US$ 34.97 Billion in 2025, growing at a CAGR of 4.3% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 42.00% share with a revenue of US$ 14.68 Billion.
Drug repurposing, also known as drug repositioning, involves identifying new therapeutic uses for existing approved or investigational medicines. This strategy significantly reduces development time, costs, and safety risks because the drugs already have established clinical data. The approach has become increasingly important in oncology, rare diseases, infectious diseases, and neurological disorders, where rapid treatment development is essential.
The U.S. Food and Drug Administration (FDA) continues to encourage drug repurposing initiatives for unmet medical needs and has expanded efforts to gather stakeholder input for accelerating approvals of new indications for existing drugs.
Growing investments in artificial intelligence, genomic research, and real-world evidence are further improving the identification of promising repurposing candidates. Public health organizations and research agencies are also supporting collaborative programs to accelerate the development of treatments for neglected and rare diseases.
According to the World Health Organization (WHO), an estimated 1.495 billion people required interventions for neglected tropical diseases in 2023, highlighting the ongoing need for faster and more affordable therapeutic solutions.
As healthcare systems seek cost-effective innovations and faster patient access to therapies, drug repurposing is expected to remain a strategic component of global pharmaceutical research and development over the coming decade.
Key Takeaways
- Market Size: Drug Repurposing Market size was US$34.97 billion in 2025. The market is estimated to grow to US$50.96 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 4.3%.
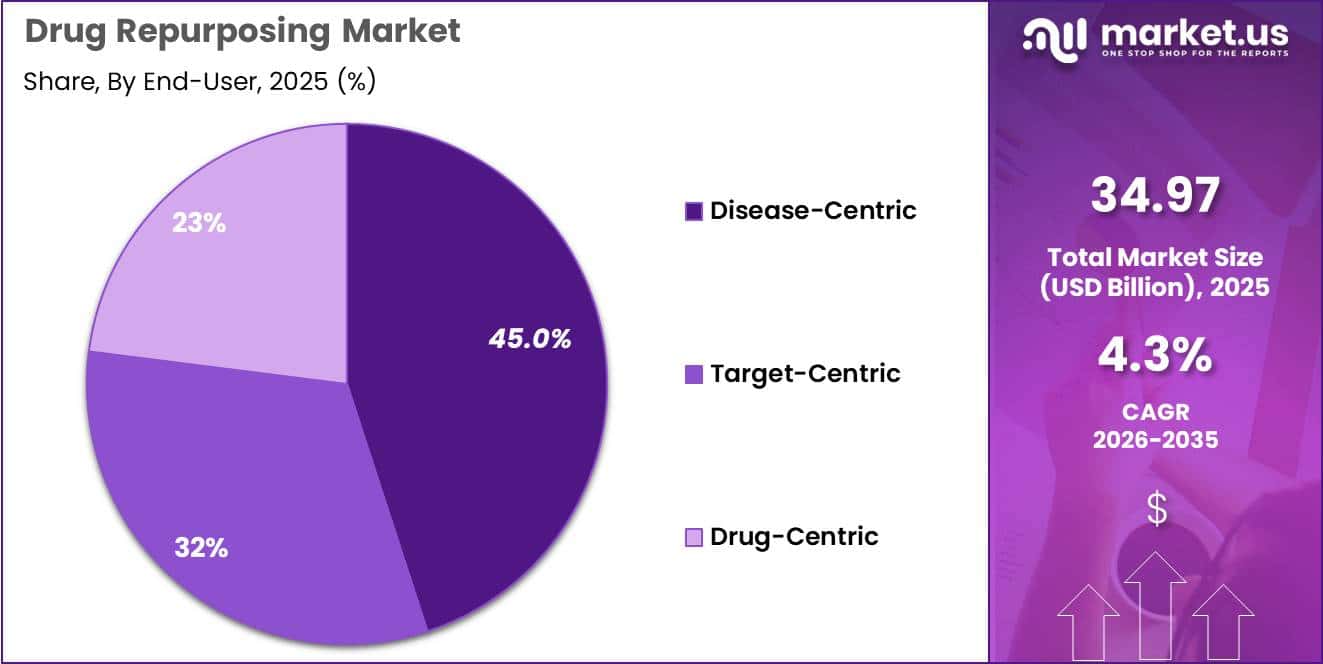
- By Type of Approach: Disease-Centric has the largest market share, accounting for 45.00% of total sales.
- By Drug Molecule Type: Biologics, accounting for 55.00% of total revenue.
- By Therapeutic Area: Oncology leads the segment, accounting for 35% of total revenue.
- By End User: Pharmaceutical & Biotechnology Companies lead the segment, accounting for 48.00% of total revenue.
- Regional: North America is the dominant regional market, accounting for 42.00% of global sales.
Type of Approach Analysis
The Disease-Centric segment dominated the Drug Repurposing Market in 2025, accounting for 45% of the total market share. This approach focuses on identifying existing drugs that can treat a specific disease by analyzing clinical needs, disease biology, and patient outcomes. The growing burden of chronic diseases, rare disorders, and infectious diseases has encouraged researchers to prioritize disease-focused drug repurposing because it reduces development time and lowers clinical risk.
Governments, academic institutions, and pharmaceutical companies increasingly support disease-centric programs to accelerate access to effective therapies. The availability of electronic health records, genomic databases, and real-world evidence further strengthens this approach by helping researchers identify new therapeutic opportunities for approved drugs.
The Target-Centric segment held 32% of the market in 2025. This method identifies biological targets such as proteins, genes, or signaling pathways and evaluates existing drugs that interact with them. Advances in genomics, proteomics, and artificial intelligence have improved target identification and expanded opportunities for precision medicine.
The Drug-Centric segment represented 23% of the market. This strategy begins with an existing drug and explores additional therapeutic indications by analyzing its pharmacological properties, safety profile, and mechanism of action, making it a practical option for extending product lifecycles.
Drug Molecule Type Analysis
The Biologics segment dominated the Drug Repurposing Market in 2025, capturing 55% of the total market share. Biologics have gained significant attention because of their high specificity, established clinical safety data, and effectiveness in treating complex diseases such as cancer, autoimmune disorders, and inflammatory conditions.
Pharmaceutical companies are increasingly evaluating approved monoclonal antibodies, recombinant proteins, and other biologic therapies for new disease indications. The rapid growth of biotechnology research, combined with advances in molecular diagnostics and personalized medicine, has further supported biologic drug repurposing. Strong investment in biologics manufacturing and regulatory incentives also contribute to the segment’s leadership.
The Small Molecules segment accounted for 28% of the market in 2025. Small molecules remain widely used due to their well-understood pharmacology, cost-effective production, oral availability, and extensive history of regulatory approval, making them attractive candidates for rapid repurposing.
The Vaccines segment held 5% of the market as researchers investigated approved vaccines for broader immune-modulating applications beyond their original indications.
The Peptides segment also represented 5%, supported by increasing interest in targeted therapies with favorable safety profiles.
The Others segment contributed 7%, including gene-based therapies, nucleic acid products, and emerging biologic modalities undergoing evaluation for new therapeutic uses.
Therapeutic Area Analysis
The Oncology segment dominated the Drug Repurposing Market in 2025, accounting for 35% of the total market share. Rising global cancer incidence, high treatment costs, and the urgent demand for effective therapies have made oncology the leading application for drug repurposing.
Researchers increasingly evaluate approved drugs with known safety profiles for new anticancer indications, reducing development timelines and clinical risks. Advances in precision medicine, biomarker identification, artificial intelligence, and genomic research have accelerated the discovery of repurposed oncology treatments. Collaboration among pharmaceutical companies, academic institutions, and cancer research organizations continues to strengthen this segment.
The Neurology segment remained a significant contributor as researchers explored repurposed therapies for Alzheimer’s disease, Parkinson’s disease, epilepsy, and multiple sclerosis, where unmet medical needs remain substantial.
The Infectious Diseases segment experienced steady growth due to continued efforts to identify existing drugs that can rapidly address emerging viral and bacterial infections while reducing development costs.
The Cardiovascular Diseases segment benefited from ongoing research aimed at expanding indications for approved cardiovascular medicines to improve long-term patient outcomes.
The Rare Diseases segment gained momentum because repurposing offers a practical and cost-efficient strategy for treating conditions with limited commercial incentives for new drug development.
Other therapeutic areas, including autoimmune, metabolic, and respiratory disorders, also contributed to overall market expansion through continued clinical research and regulatory support.
End User Analysis
The Pharmaceutical & Biotechnology Companies segment dominated the Drug Repurposing Market in 2025, holding 48% of the total market share. These organizations lead drug repurposing activities by leveraging extensive drug libraries, advanced research capabilities, clinical development expertise, and regulatory experience. Growing investments in artificial intelligence, computational biology, and real-world evidence analytics have enabled companies to identify new therapeutic indications more efficiently.
Repurposing also allows pharmaceutical and biotechnology firms to maximize the value of existing drug portfolios, reduce research costs, shorten development timelines, and improve commercial returns. Strategic collaborations with academic institutions, contract research organizations, and healthcare providers further strengthen innovation and accelerate market growth.
Academic and research institutes represent another important end-user segment, contributing significantly through translational research, disease biology studies, and early-stage discovery supported by government and public funding.
Contract Research Organizations (CROs) continue to expand their role by providing specialized preclinical, clinical, regulatory, and data analysis services that help sponsors accelerate repurposing programs.
Hospitals and healthcare institutions also support market growth by participating in clinical trials, generating real-world evidence, and evaluating repurposed therapies in routine clinical practice.
Government agencies and non-profit organizations further contribute through funding initiatives, public health research programs, and collaborations focused on addressing unmet medical needs across diverse disease areas.
Market Segmentations
By Type of Approach
- Disease-Centric
- Target-Centric
- Drug-Centric
By Drug Molecule Type
- Biologics
- Small Molecules
- Vaccines
- Peptides
- Others
By Therapeutic Area
- Oncology
- Neurology & CNS Disorders
- Infectious Diseases
- Cardiovascular Diseases
- Others
By End User
- Pharmaceutical & Biotechnology Companies
- Contract Research Organizations (CROs)
- Academic & Research Institutes
- Hospitals & Clinics
- Healthcare Providers
Driver
Chronic Disease Burden Expanding Fast Screening Candidate Pools
Demand-side pressure is expanding the repurposing opportunity set faster than novel-drug pipelines can economically respond. WHO reports that the number of people living with diabetes rose from 200 million in 1990 to 830 million in 2022, while 14% of adults aged 18 years and older were living with diabetes in 2022; separately, the IDF estimates 589 million adults aged 20–79 were living with diabetes in 2024 and projects 853 million by 2050.
For drug repurposing, this matters less as a single-diabetes story and more as proof that chronic metabolic and age-linked diseases are producing broad, large, and persistent pools of patients in which already-characterized molecules can be repositioned faster than greenfield assets can be discovered, de-risked, and launched.
Commercially, rising chronic-disease prevalence changes portfolio construction. Sponsors are more willing to revisit shelved compounds, generic actives, adjunct therapies, and mechanism-adjacent molecules when patient numbers are high enough to support indication segmentation, biomarker-guided positioning, or combination use cases with lower development spend than de novo programs.
The result is improved expected value per candidate larger addressable populations support lower per-program revenue thresholds for viability, while existing safety knowledge can compress early-stage failure risk, especially in metabolic, inflammatory, and neurodegenerative categories that FDA itself has already identified as repurposing priorities.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| FDA-backed label expansion and evidence-based repurposing pathways | +2.2% | North America core, EU follow-through, APAC reference markets | Short term (≤ 2 years) |
| Chronic disease burden widening fast-screening candidate pools | +1.8% | North America core, EU, APAC, Latin America spill-over, Middle East | Medium term (2-4 years) |
| NIH/NCATS open translational infrastructure lowering discovery cost | +1.6% | U.S. core, EU academic hubs, APAC research clusters | Short term (≤ 2 years) |
| AI plus real-world evidence improving hit prioritization economics | +1.5% | North America core, EU, APAC digital-health corridors | Medium term (2-4 years) |
| Reimbursement and drug-pricing pressure favoring lower-risk lifecycle extension | +1.3% | U.S. core, EU payer-led markets, Japan | Medium term (2-4 years) |
| Rare disease and unmet-need prioritization raising approval attractiveness | +1.9% | U.S. and EU core, selected APAC orphan markets | Long term (≥ 4 years) |
Challenge
Weak IP Protection and Incentive Misalignment Limiting Repurposing Growth
Weak intellectual property protection and misaligned economic incentives for repurposed drugs subtract an estimated 1.3 % points from the market’s growth potential by discouraging high-risk, data-intensive repurposing programs in off-patent molecules and diminishing sponsor appetite for narrow indications with modest revenue ceilings.
Many repurposing candidates sit in a “genericized” space where composition-of-matter patents have expired, leaving sponsors reliant on method-of-use, data exclusivity, or regulatory incentives that often provide only 5–10 years of partial protection, compared with 12–15 years for new molecular entities, compressing the window for capital recovery and dampening ROI.
This IP asymmetry pushes portfolio allocation toward indications with high prevalence and pricing power, such as oncology and immunology, leaving under-served rare disease and infectious-disease repurposing opportunities underfunded even though real-world evidence suggests potentially meaningful signal detection.
At an operational level, weak exclusivity translates into slower investment in confirmatory phase III trials. Internal modelling by many sponsors assumes a 10–20% lower probability of commercial exclusivity than in novel drug programs, causing expected NPV to fall by 25–40% and reducing the number of active repurposing assets in mid-to-late development by low double-digit percentages compared with a stronger IP environment.
In response, firms are pursuing layered protection strategies, including method-of-use patents combined with formulation or delivery technology protection, more aggressive orphan-drug designation pathways, and structured public-private arrangements in which public funders absorb 20–30% of development risk for socially valuable indications while corporate partners retain defined revenue-sharing rights.
These approaches aim to lift portfolio-level investment in repurposing by high single-digit percentages and gradually lessen the CAGR drag over a 10-year horizon.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Fragmented regulatory pathways | -1.6% | US, EU, UK, Japan | Long term (≥ 4 years) |
| Weak IP & incentive alignment | -1.3% | US, EU, emerging Asia | Long term (≥ 4 years) |
| Real-world data quality limits | -1.2% | US, EU, APAC corridors | Medium term (2-4 years) |
| Clinical trial design complexity | -1.0% | US, EU, global oncology hubs | Medium term (2-4 years) |
| Talent and infrastructure gap | -0.9% | Emerging markets, mid-tier pharma | Long term (≥ 4 years) |
| Cross-stakeholder coordination friction | -0.8% | Global, multi-center collaborations | Medium term (2-4 years) |
Restraints
Data Access and Knowledge Sharing Barriers Limiting Repurposing Efficiency
Data access and knowledge-sharing barriers between originator companies, regulators, and independent researchers impede discovery of viable repurposing hypotheses and slow translation from signal identification to clinical validation, because much of the richest pharmacovigilance, mechanistic, and failed trial data is siloed behind corporate firewalls and regulatory confidentiality frameworks.
In principle, large volumes of safety and efficacy data from abandoned assets could be re-mined to reveal new indications, combination opportunities, or biomarker-defined subgroups, yet originator firms face legal, competitive, and reputational disincentives to opening detailed datasets, and existing initiatives that share a limited set of compounds or anonymized data often encompass only dozens of molecules relative to thousands of potentially repurposable candidates.
At an operational level, the absence of safe-harbor frameworks for multi-sponsor data pooling and the cost of curating decades of trial data into AI-ready formats mean that only a handful of large collaborations or public-private partnerships emerge. Many academic teams must rely on fragmented published literature rather than complete clinical datasets, reducing the predictive power of in-silico screening and forcing redundant early-stage investigations.
This friction adds 18–36 months to the average discovery-to-Phase II timeline, raises early-stage failure rates, and confines many promising signals to the “grey literature” of internal reports and regulatory archives. Cumulatively, the resulting under-utilization of available knowledge trims growth by roughly 0.8 % points in knowledge-intensive regions such as the US and EU, where the volume of latent data is greatest but cross-institutional sharing constraints remain acute.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fragmented regulatory pathways & labeling rigidity | -2.0% | US, EU, UK, advanced Asia | Medium term (2-4 years) |
| Weak IP/exclusivity economics for generics | -1.5% | US, EU, generics-heavy EMs | Long term (≥ 4 years) |
| High trial cost vs. low price ceilings | -1.8% | US, EU, Japan | Medium term (2-4 years) |
| Data access and knowledge-sharing barriers | -0.8% | US, EU | Medium term (2-4 years) |
| Payer HTA skepticism on off-patent repositioning | -1.2% | EU, UK, Canada, select APAC | Long term (≥ 4 years) |
| Operational and supply chain misalignment for new indications | -0.7% | Global, esp. EM hospital networks | Short to medium term (≤ 4 years) |
Opportunity
AI Led Rare Disease and Pediatric Indication Mining Opportunities
The opportunity lies in constructing AI-native pipelines that deliberately target rare diseases and pediatric indications, areas explicitly highlighted in recent pharmacoequity and repurposing policy discussions, but largely absent from current baseline forecasts due to limited sponsor interest and fragmented data.
These platforms can use multimodal models integrating omics, clinical registries, imaging, and claims data to identify 200–300 high-probability drug-disease matches out of thousands of approved molecules by 2030.
Baseline AI-enabled repurposing growth already assumes broad use in common indications, yet rare and pediatric populations remain under-tapped because of small market sizes and complex trial feasibility. The upside here depends on specialized algorithms tuned for ultra-small cohort signal detection, synthetic control arm design, and trial simulation, which can reduce time-to-hypothesis from 3–5 years to 12–18 months and lower early-stage failure rates by 20–30% compared with conventional repurposing programs.
With global rare disease prevalence affecting an estimated 300–400 million people and pediatric segments accounting for 20–25% of life-course disease burden, realistic monetization of even 5–10% of this unmet need via repurposed therapies priced at 30–40% below novel orphan drugs could generate an incremental TAM of USD 10–15 billion by 2035, alongside 5–10 % point lower acquisition costs per responder due to prespecified genetic and phenotypic targeting.
The projected 1.9 % point CAGR upside reflects not the generic spread of AI itself, which is already a driver, but the creation of dedicated rare and pediatric repurposing platforms, new reimbursement codes, and specialized registries that reposition these populations as a portfolio with predictable returns rather than isolated, charity-driven projects.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Equity-focused generic repurposing consortia | +2.2% | US, EU, selective APAC | Medium term (2-4 years) |
| AI-led rare disease and pediatric indication mining | +1.9% | US, EU, Japan, UK | Medium term (2-4 years) |
| Value-based contracting for repurposed chronic therapies | +1.6% | US, EU core | Short term (≤ 2 years) |
| Network-medicine repurposing for neurodegeneration | +1.4% | US, EU, East Asia | Long term (≥ 4 years) |
| Nanotechnology-enabled reformulations for metabolic and oncology care | +1.3% | US, EU, China, India | Long term (≥ 4 years) |
| Real-world data platforms for off-label use and label expansion | +1.5% | US, EU, multi-region | Short–medium term (≤ 4 years) |
Regional Analysis
In 2025, North America led the market, achieving over 42.00% share with a revenue of US$14.68 billion.
In 2025, the North America region’s leadership is supported by a well-established pharmaceutical and biotechnology ecosystem, substantial investments in biomedical research, and a strong regulatory framework that encourages the development of innovative therapies. Drug repurposing has gained momentum as companies seek faster and more cost-effective alternatives to traditional drug discovery, helping reduce development timelines and clinical risks.
The United States remains the primary contributor to regional growth due to the presence of leading pharmaceutical manufacturers, advanced research institutions, and extensive collaboration between academia, government agencies, and private organizations.
Federal support for rare disease research, oncology, infectious diseases, and neurological disorders has further accelerated the identification of new therapeutic uses for approved medicines. The widespread adoption of artificial intelligence, machine learning, and bioinformatics platforms is also improving target identification and drug screening, making repurposing strategies more efficient.
Canada complements regional expansion through increasing investments in life sciences research, precision medicine initiatives, and collaborative clinical trials. Growing healthcare expenditure, a rising burden of chronic diseases, and strong intellectual property protection continue to create favorable conditions for market growth.
Additionally, the increasing number of strategic partnerships, licensing agreements, and public-private collaborations across North America is expected to sustain the region’s leadership in the global Drug Repurposing Market throughout the forecast period.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global Drug Repurposing Market is moderately fragmented, with a combination of established pharmaceutical companies and specialized artificial intelligence (AI)-driven biotechnology firms competing to accelerate drug discovery and reduce development timelines.
Market participants focus on expanding existing drug portfolios by identifying new therapeutic indications for approved or investigational molecules, enabling faster commercialization with lower clinical risks. Innovation is centered on advanced computational biology, machine learning, genomics, and real-world evidence to improve target identification and optimize clinical success rates.
Large pharmaceutical companies leverage extensive research capabilities and regulatory expertise, while emerging technology-focused firms strengthen the competitive landscape through AI-powered drug discovery platforms and precision medicine approaches.
Leading companies operating in the market include Pfizer Inc., Novartis AG, Johnson & Johnson (Janssen), Roche (Genentech), Eli Lilly and Company, Recursion Pharmaceuticals, BenevolentAI, Atomwise Inc., Excelra (GVK BIO), Lantern Pharma Inc., Paradigm Biopharmaceuticals, BioXcel Therapeutics, SOM Biotech, Fios Genomics, and HLK Pharmacin.
These companies emphasize continuous investment in research and development to identify novel therapeutic applications for existing compounds across oncology, neurology, infectious diseases, and rare disorders. Strategic collaborations between pharmaceutical companies, AI developers, academic institutions, and contract research organizations enhance data sharing and accelerate clinical validation.
Product innovation increasingly integrates artificial intelligence, bioinformatics, and multi-omics datasets into drug discovery workflows, improving prediction accuracy and reducing development costs. Competition is also evolving toward ecosystem-based models, where technology providers, data analytics specialists, and pharmaceutical manufacturers collaborate to create end-to-end drug repurposing platforms that support faster decision-making, regulatory compliance, and commercialization.
Top Key Players
- Pfizer Inc.
- Novartis AG
- Johnson & Johnson (Janssen)
- Roche (Genentech)
- Eli Lilly and Company
- Recursion Pharmaceuticals
- BenevolentAI
- Atomwise Inc.
- Excelra (GVK BIO)
- Lantern Pharma Inc.
- Paradigm Biopharmaceuticals
- BioXcel Therapeutics
- SOM Biotech
- Fios Genomics
- HLK Pharmacin
Recent Developments
- BioXcel Therapeutics (May 2026): FDA accepted BioXcel’s supplemental application for IGALMI at-home use in agitation associated with bipolar disorders or schizophrenia, assigning a November 14, 2026 PDUFA action date.
- Recursion Pharmaceuticals (August 2026): Recursion announced IND clearance for REC-7735, a mutant-selective PI3Kα H1047R inhibitor, with Phase 1/2 initiation planned during second-half 2026, advancing its AI-designed oncology pipeline.
- SOM Biotech (November 2025): SOM3355 received a positive EMA orphan-designation opinion and FDA alignment on its proposed Phase 3 program for Huntington’s disease, supporting planned late-stage development of the repurposed oral therapy.
- Paradigm Biopharmaceuticals (October 2025): Paradigm commenced patient dosing in its global Phase 3 osteoarthritis trial for Zilosul, progressing clinical validation of its repurposed pentosan polysulfate sodium candidate for knee osteoarthritis.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 34.97 Billion |
| Forecast Revenue (2035) | US$ 50.96 Billion |
| CAGR (2026-2035) | 4.3% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Type of Approach(Disease-Centric, Target-Centric, Drug-Centric) By Drug Molecule Type (Biologics, Small Molecules,Vaccines,Peptides, Others) By Therapeutic Area (Oncology ,Neurology & CNS Disorders ,Infectious Diseases ,Cardiovascular Diseases ,Others) By End User (Pharmaceutical & Biotechnology Companies, Contract Research Organizations (CROs) ,Academic & Research Institutes ,Hospitals & Clinics ,Healthcare Providers) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Pfizer Inc., Novartis AG , Johnson & Johnson (Janssen) , Roche (Genentech) , Eli Lilly and Company, Recursion Pharmaceuticals,BenevolentAI,Atomwise Inc. ,Excelra (GVK BIO) ,Lantern Pharma Inc. ,Paradigm Biopharmaceuticals ,BioXcel Therapeutics ,SOM Biotech ,Fios Genomics ,HLK Pharmacin |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








