


Market Overview
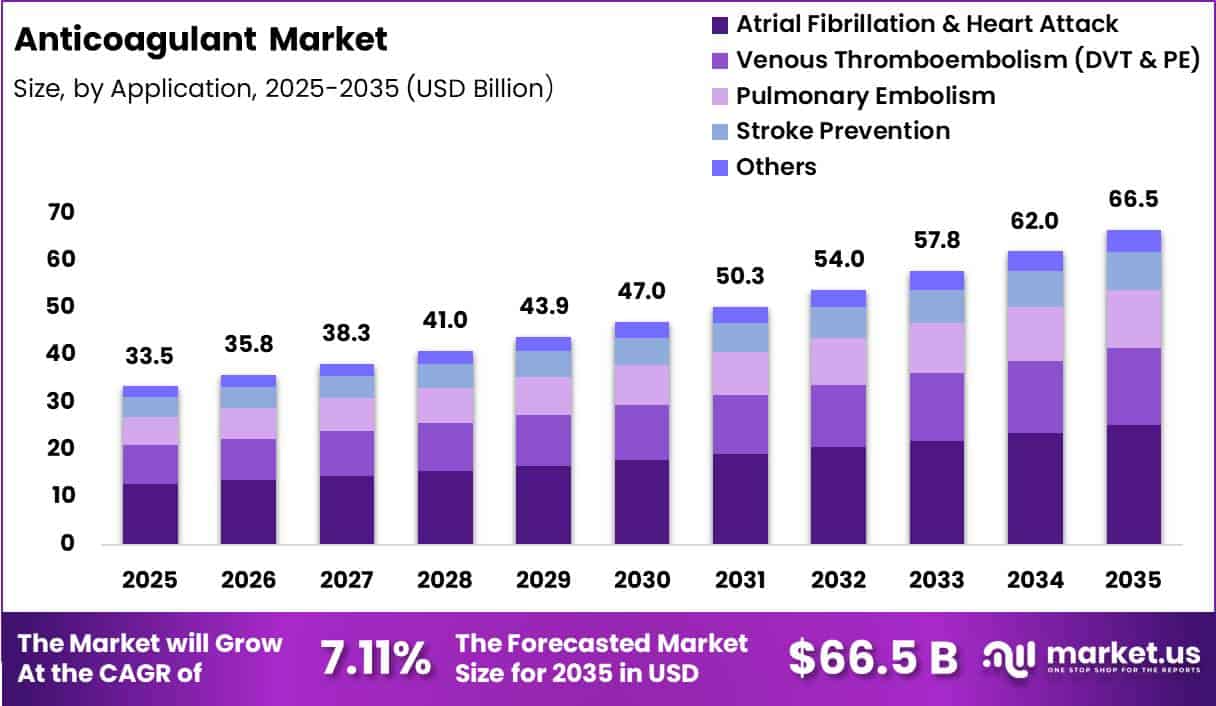
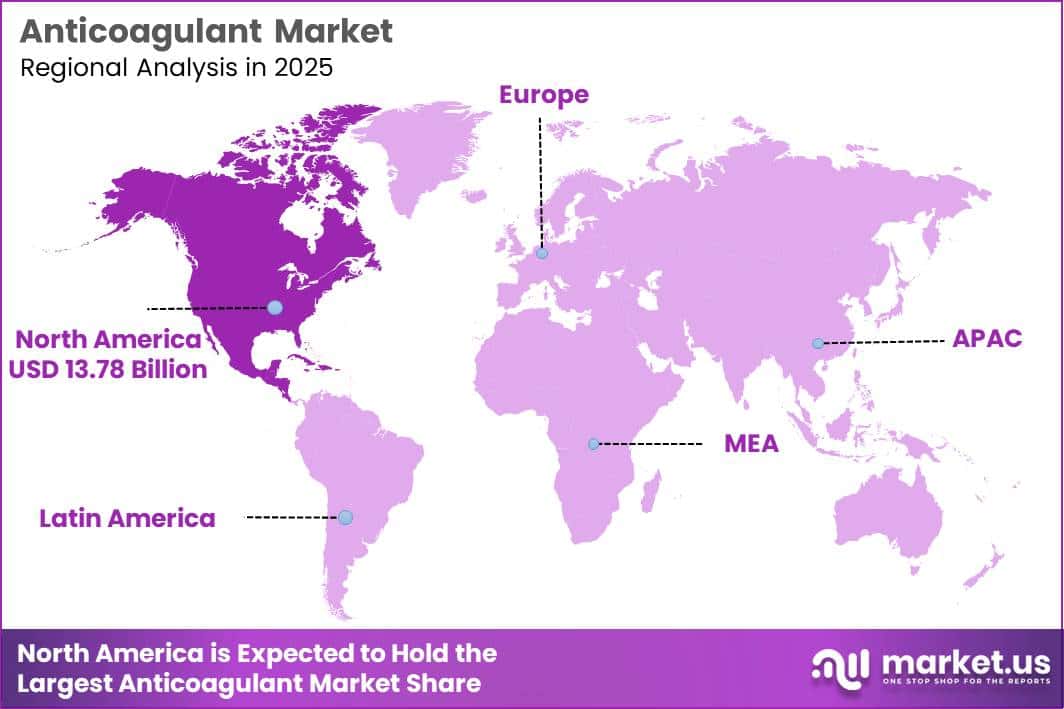
Global Anticoagulant Market size is expected to be worth around US$ 66.48 Billion by 2035 from US$ 33.46 Billion in 2025, growing at a CAGR of 7.11% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 41.20% share with a revenue of US$ 13.78 Billion.
The global anticoagulant market is witnessing sustained growth as healthcare systems prioritize the prevention and treatment of thromboembolic disorders, including deep vein thrombosis (DVT), pulmonary embolism (PE), atrial fibrillation, and stroke.
Rising cardiovascular disease prevalence, expanding elderly populations, and increasing awareness of early diagnosis are driving demand for effective anticoagulation therapies worldwide. According to the World Health Organization (WHO), cardiovascular diseases remain the leading cause of death globally, accounting for approximately 17.9 million deaths each year, highlighting the growing need for therapies that reduce clot-related complications.
The increasing burden of venous thromboembolism is another key factor supporting market expansion. The U.S. Centers for Disease Control and Prevention (CDC) estimates that up to 900,000 people in the United States experience venous thromboembolism annually, resulting in 60,000 to 100,000 deaths every year.
The CDC also notes that as many as 70% of healthcare-associated VTE cases are preventable through appropriate preventive measures, including anticoagulant medications, although fewer than half of eligible hospitalized patients receive these interventions.
Clinical practice has increasingly shifted toward direct oral anticoagulants (DOACs), including factor Xa inhibitors and direct thrombin inhibitors, because of their favorable safety profile, fewer monitoring requirements, and lower risk of intracranial hemorrhage compared with traditional vitamin K antagonists.
The U.S. National Heart, Lung, and Blood Institute (NHLBI) recommends anticoagulants as a cornerstone therapy for preventing stroke in patients with atrial fibrillation and for treating venous thromboembolism, reinforcing their essential role in modern cardiovascular care.
Key Takeaways
- Market Size : Global Anticoagulant Market size is expected to be worth around US$ 66.48 Billion by 2035 from US$ 33.46 Billion in 2025.
- Market Share : The market is growing at a CAGR of 7.11% during the forecast period from 2026 to 2035.
- Drug Class Analysis : The Novel Oral Anticoagulants (NOACs) segment dominated the anticoagulant market in 2025, accounting for 41.20% of the total market share.
- Route of Administration Analysis : The Oral segment held the largest share of the anticoagulant market in 2025, capturing 57.40% of total revenue.
- Application Analysis : The Atrial Fibrillation & Heart Attack segment accounted for the largest share of the anticoagulant market in 2025, representing 38.10% of total revenue.
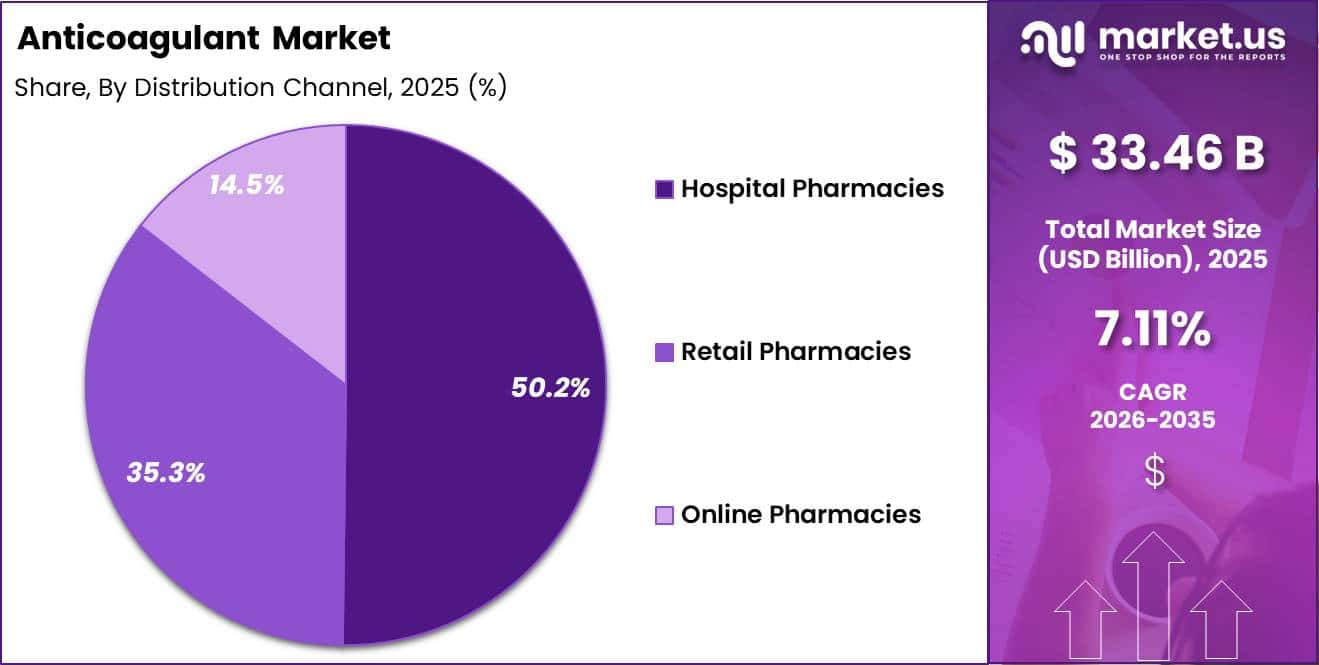
- Distribution Channel Analysis : The Hospital Pharmacies segment dominated the anticoagulant market in 2025, accounting for 50.20% of total revenue
- End User Analysis : The Hospitals segment led the anticoagulant market in 2025, capturing 53.10% of the total market share.
- Regional Analysis : In 2025, North America led the market, achieving over 41.20% share with a revenue of US$ 13.78 Billion.
Drug Class Analysis
The Novel Oral Anticoagulants (NOACs) segment dominated the anticoagulant market in 2025, accounting for 41.20% of the total market share. This leadership is supported by the growing clinical preference for NOACs because they provide predictable anticoagulation, rapid onset of action, fixed dosing, and significantly reduce the need for routine coagulation monitoring compared with traditional therapies.
Major NOACs, including factor Xa inhibitors and direct thrombin inhibitors, are widely recommended for non-valvular atrial fibrillation and venous thromboembolism management in current clinical guidelines.
Heparin & Low Molecular Weight Heparin (LMWH) continue to play a critical role in hospitals for acute thrombotic events, perioperative anticoagulation, and thromboprophylaxis, owing to their rapid anticoagulant effect and established clinical use.
Vitamin K Antagonists (VKA) remain essential for patients with mechanical heart valves and selected valvular heart diseases where NOACs are not recommended, despite requiring regular INR monitoring. Direct Thrombin Inhibitors maintain importance in specialized indications, including patients with heparin-induced thrombocytopenia and those requiring alternative anticoagulation strategies.
The Others segment includes emerging anticoagulants and specialized agents that address specific clinical conditions and are expected to benefit from continued pharmaceutical innovation and expanding therapeutic applications.
Route of Administration Analysis
The Oral segment held the largest share of the anticoagulant market in 2025, capturing 57.40% of total revenue. Oral anticoagulants have become the preferred treatment option because they offer convenient administration, improved patient adherence, and suitability for long-term management of chronic cardiovascular disorders.
The increasing use of direct oral anticoagulants has further strengthened this segment, as these therapies are recommended for eligible patients with atrial fibrillation and venous thromboembolism while requiring less frequent laboratory monitoring than vitamin K antagonists. Oral formulations also support outpatient treatment, reducing hospitalization and improving treatment continuity.
The Injectable / Parenteral segment remains indispensable in emergency care, inpatient treatment, perioperative management, and critically ill patients requiring immediate anticoagulant action. Heparin and LMWH continue to be widely administered by injection for thromboprophylaxis following surgery, acute coronary syndromes, and hospitalized patients at high thrombotic risk.
The Others segment comprises specialized delivery approaches and investigational formulations designed for unique patient populations. Continued innovation in anticoagulant therapies, combined with improved patient education and guideline-directed treatment, is expected to sustain growth across all administration routes while oral medications maintain market leadership.
Application Analysis
The Atrial Fibrillation & Heart Attack segment accounted for the largest share of the anticoagulant market in 2025, representing 38.10% of total revenue. Rising prevalence of atrial fibrillation and cardiovascular disease has significantly increased the use of anticoagulants to reduce the risk of stroke, systemic embolism, and recurrent cardiac complications.
Clinical guidelines recommend anticoagulation for eligible patients with non-valvular atrial fibrillation, driving widespread adoption of NOACs and other anticoagulant therapies.
Venous Thromboembolism (DVT & PE) represents another major application, supported by increasing awareness, improved diagnosis, and guideline-based treatment using both injectable and oral anticoagulants. The Pulmonary Embolism segment continues to expand as prompt anticoagulant therapy remains the standard of care following diagnosis.
Stroke Prevention remains a key therapeutic area, particularly among patients with atrial fibrillation and recurrent thromboembolic risk. The Others category includes anticoagulant use in orthopedic surgery, inherited thrombophilia, cancer-associated thrombosis, and additional cardiovascular conditions.
Growing disease burden, aging populations, and continuous improvements in anticoagulant safety and efficacy continue to strengthen demand across all application segments.
Distribution Channel Analysis
The Hospital Pharmacies segment dominated the anticoagulant market in 2025, accounting for 50.20% of total revenue. Hospital pharmacies remain the primary dispensing channel because anticoagulant therapy is frequently initiated during hospitalization for cardiovascular emergencies, surgical procedures, venous thromboembolism, and acute coronary syndromes.
Injectable anticoagulants such as unfractionated heparin and LMWH require clinical supervision, making hospital pharmacies central to treatment delivery and medication management. Hospitals also provide anticoagulation monitoring, dose adjustments, and multidisciplinary care for complex patients.
Retail Pharmacies continue to support long-term therapy by dispensing oral anticoagulants prescribed for chronic management of atrial fibrillation, stroke prevention, and venous thromboembolism. Increasing prescription refills, pharmacist counseling, and medication adherence programs have strengthened this segment.
Online Pharmacies are experiencing gradual growth as digital healthcare services, electronic prescriptions, and home delivery improve medication accessibility, particularly for patients receiving lifelong anticoagulant therapy.
Expanding telehealth adoption and greater emphasis on outpatient disease management are expected to support all distribution channels, although hospital pharmacies are expected to retain their leading position because of the complexity of anticoagulant initiation and monitoring.
End User Analysis
The Hospitals segment led the anticoagulant market in 2025, capturing 53.10% of the total market share. Hospitals remain the largest end users because they manage acute thrombotic emergencies, cardiovascular surgeries, stroke care, trauma cases, and complex anticoagulation therapies requiring continuous monitoring and specialist oversight.
The growing number of cardiac interventions, orthopedic surgeries, and hospitalized patients requiring thromboprophylaxis continues to drive anticoagulant utilization within hospital settings. Advanced diagnostic infrastructure and multidisciplinary cardiovascular care further reinforce hospital leadership.
Specialty Clinics play an important role in managing patients with cardiology, hematology, and vascular disorders who require long-term anticoagulation and routine follow-up. Ambulatory Care Centers continue to expand with the increasing number of minimally invasive procedures and same-day surgeries that require perioperative anticoagulant management.
Homecare Settings are witnessing steady growth as oral anticoagulants enable safe long-term treatment outside hospitals, supported by telemedicine, patient education, and improved medication adherence.
Continued advancements in anticoagulant therapy, remote monitoring, and patient-centered care models are expected to drive demand across all end-user segments while hospitals maintain their dominant position.
Market Segmentations
By Drug Class
- Novel Oral Anticoagulants (NOACs)
- Heparin & Low Molecular Weight Heparin (LMWH)
- Vitamin K Antagonists (VKA)
- Direct Thrombin Inhibitors
- Others
By Route of Administration
- Oral
- Injectable / Parenteral
- Others
By Application
- Atrial Fibrillation & Heart Attack
- Venous Thromboembolism (DVT & PE)
- Pulmonary Embolism
- Stroke Prevention
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By End User
- Hospitals
- Specialty Clinics
- Ambulatory Care Centers
- Homecare Settings
Drivers
Hospital-linked VTE prevention and post-discharge protocols
VTE prophylaxis is a high-conviction utilization driver because it is embedded in hospital quality workflows rather than discretionary retail demand.
CDC estimates up to 900,000 people in the U.S. are affected by VTE each year, 60,000–100,000 die annually, more than one-third of diagnosed cases are linked to recent hospitalization, VTE is a leading cause of preventable hospital death, and as many as 70% of healthcare-associated VTEs are preventable, yet fewer than half of hospital patients receive preventive measures.
That gap creates a measurable commercial runway across inpatient prophylaxis, discharge continuation, orthopedic pathways, oncology wards, and digitally monitored care transitions; each protocol upgrade raises treated-patient capture without requiring a new epidemiology shock.
The business-model effect is important: procurement shifts from single-product prescribing toward pathway contracts spanning inpatient injectables, discharge oral therapy, and clinical decision support, which increases account-level selling power in the U.S., EU5, and large APAC tertiary centers.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Aging AFib stroke-prevention pool expansion | +2.2% | North America core, EU, Japan, urban China | Medium term |
| Hospital-linked VTE prevention and post-discharge protocols | +1.8% | US, EU5, Japan, tertiary-care APAC | Short term |
| Medicare price negotiation improving branded DOAC access | +1.4% | US core, limited spill-over to reference-price markets | Short term |
| DOAC guideline entrenchment over warfarin monitoring burden | +1.9% | North America, EU, South Korea, Australia, Gulf | Medium term |
| Cancer-, CKD-, and multi-morbidity-associated anticoagulation demand | +1.3% | US, EU, China, high-acuity oncology corridors | Medium term |
| Reversal-agent availability and bleeding-management confidence | +0.9% | US core, advanced hospital systems in EU and APAC | Long term |
Challenges
Limited Thrombosis Specialist Capacity Restricts Anticoagulant Adoption
Finally, systemic constraints in thrombosis-specialist capacity and uneven diffusion of expertise create a pervasive execution bottleneck that is estimated to subtract roughly 0.5–0.9 percentage points from attainable CAGR by slowing adoption of optimized anticoagulation strategies and advanced therapies.
Many countries face growing thrombotic disease burdens due to aging populations and increasing cardiovascular risk factors, but the number of hematologists, thrombosis specialists, and specialized anticoagulation clinic staff has not scaled proportionately, producing high patient-to-specialist ratios and long wait times, particularly outside major academic centers.
This capacity gap pushes much of anticoagulation management to general practitioners and hospitalists who must juggle multiple comorbidities often without ready access to genetics, advanced coagulation testing, or sophisticated decision-support, leading to conservative prescribing, reluctance to use higher-intensity regimens, or inertia in switching from VKAs to DOACs or future FXI-targeted agents even when clinically indicated.
In inpatient settings, multidisciplinary VTE teams and dedicated anticoagulation services have demonstrated significant reductions in hospital-acquired VTE and improved thromboprophylaxis utilization, but establishing and staffing such services require upfront investments in personnel, training, and IT integration that many hospitals, especially in resource-constrained systems, have been slow to prioritize.
Moreover, advanced techniques such as AI-driven dosing algorithms, pharmacogenomic-guided warfarin initiation, or complex post-VTE chronic management protocols demand competencies not yet widely embedded in frontline practice, further widening the gap between what is clinically possible and what is routinely delivered.
Over a long-term horizon, scaling specialist capacity will depend on expanding fellowship programs, integrating thrombosis management into broader cardiovascular and internal medicine training, and wider deployment of centralized virtual anticoagulation services that can support multiple hospitals and clinics; until then, limited specialist availability will continue to constrain the speed and depth of anticoagulant adoption, especially for novel and more complex therapies.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Complex bleeding–clot risk balancing | -1.4% | North America, EU, East Asia | Long term (≥ 4 years) |
| Heterogeneous reimbursement & access | -1.2% | North America, EU periphery, LATAM, MEA | Long term (≥ 4 years) |
| Monitoring & adherence workflow gaps | -1.0% | North America, EU, APAC corridors | Medium term (2–4 years) |
| Fragmented care & VTE under-diagnosis | -0.9% | Global, especially LMICs | Long term (≥ 4 years) |
| Regulatory drag on novel agents | -0.8% | U.S., EU regulatory hubs, Japan | Medium term (2–4 years) |
| Limited thrombosis-specialist capacity | -0.7% | North America, EU, Emerging Asia | Long term (≥ 4 years) |
Restraints
Manufacturing and API Supply Risks Constrain Anticoagulant Market Growth
Manufacturing constraints and active pharmaceutical ingredient (API) supply risks introduce recurrent friction into anticoagulant value chains, amplifying lead times, elevating operating costs, and periodically disrupting product availability across both mature and emerging regions, with particular vulnerability in APAC-centric supply corridors feeding global demand.
The high concentration of critical APIs and intermediate synthesis steps in a limited number of facilities across China, India, and select EU countries means that localized disruptions, be they regulatory compliance crackdowns, energy price spikes, or logistics bottlenecks, can translate into 15–25% swings in monthly output capacity, with downstream hospital and retail inventories experiencing stockouts or rationing episodes lasting 4–8 weeks in worst-case scenarios.
Post-pandemic regulatory tightening on GMP inspections has also increased the frequency of temporary plant shutdowns, raising quality assurance compliance costs by 5–10% of COGS and pushing manufacturers to hold higher safety stock, thereby tying up additional working capital and eroding operating margins by 150–250 basis points in already competitive segments.
Strategically, firms must invest in dual-sourcing, geographic diversification of manufacturing, and in some cases on-shore selective production, which in turn implies incremental CapEx outlays in the tens to hundreds of millions of dollars per site over a 3–5-year horizon, collectively adding complexity and cost that compresses profitability and slows expansion into price-sensitive markets.
These dynamics are reasonably modeled as contributing about a 0.8-percentage-point downward adjustment to the global CAGR as supply-chain resilience efforts consume capital that would otherwise be directed into commercial scaling.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Intensified safety scrutiny on reversal and high-risk agents | -1.4% | North America core, EU, Japan | Short–Medium term |
| Cost-containment and reimbursement tightening | -1.6% | North America, EU, select LATAM, Asia advanced | Medium–Long term |
| Generic erosion and patent cliffs | -1.2% | North America, EU, Emerging APAC | Medium term |
| Manufacturing and API supply risk | -0.8% | Global, APAC corridors, EU | Short–Medium term |
| Slow adoption in low-income health systems | -0.9% | Sub-Saharan Africa, South Asia, parts of LATAM | Long term |
| Competitive shifts toward non-pharmacologic and alternative modalities | -0.7% | North America, EU, high-income APAC | Medium–Long term |
Opportunity
Expansion into Under-Treated AF and VTE Patient Populations
This opportunity focuses on systematically capturing the sizeable portion of atrial fibrillation (AF) and venous thromboembolism (VTE) patients who remain sub-optimally anticoagulated despite guideline recommendations, thereby creating upside above the baseline growth that already reflects current prescribing trends.
Epidemiological data indicate annual VTE incidence of roughly 1–2 cases per 1,000 person-years in Europe and the USA, translating into hundreds of thousands of events annually, with lifetime VTE risk approaching about 8% and approximately 1.2 million total VTE cases per year in the USA alone.
At the same time, multiple studies have documented oral anticoagulant treatment rates well below 70% of high-risk AF patients and wide variability across centers, with some cohorts showing anticoagulation levels under 60%, implying a persistent under-treatment gap of 10–20 percentage points or more across major markets.
If innovators design targeted outreach programs, simplified dosing regimens, differentiated formulations, for example, low-bleeding-risk DOACs for frail elderly patients, and payer-aligned risk scoring tools that bring treated proportions closer to 80–85% in AF and high-risk VTE prevention segments, this could unlock incremental treated populations equivalent to 15–25% above current volumes in North America and Europe and 20–30% in rapidly urbanizing APAC hubs.
Assuming average annual drug spend per patient of USD 1,000–1,500 in high-income markets and USD 300–600 in upper-middle-income economies, tapping even half of the under-treated cohort could add USD 5–8 billion in incremental revenue globally by 2035, with operating margins lifted by 200–300 basis points due to scale efficiencies and relatively low incremental acquisition cost when using embedded care pathways and digital outreach rather than full-brand promotional campaigns.
Because baseline forecasts already assume continued guideline-driven DOAC uptake, only deliberate campaigns to move treatment penetration meaningfully above current benchmarks constitute true upside, supporting a plausible additional CAGR of around +2.0 percentage points over the next decade as underserved risk pools are systematically converted.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Expansion into under-treated AF & VTE cohorts | +2.0% | North America, EU, APAC urban | Medium term (2–4 years) |
| Integrated chronic CVD & diabetes care platforms | +1.8% | North America core, EU, China | Medium term (2–4 years) |
| Low-cost DOACs & differentiated access models | +1.5% | APAC emerging, Latin America, Africa | Long term (≥ 4 years) |
| AI-guided anticoagulation optimization & adherence | +1.2% | North America, EU, advanced APAC | Short–Medium term (≤ 3 years) |
| Peri-procedural & hospital-to-home transition bundles | +1.0% | North America, EU, GCC, East Asia | Short term (≤ 2 years) |
| Real-world evidence monetization & risk-sharing contracts | +0.8% | North America, EU, Japan | Medium–Long term (3–5+ years) |
Regional Analysis
In 2025, North America led the market, achieving over 41.20% share with a revenue of US$ 13.78 Billion. North America maintained its leadership in the global anticoagulant market due to the region’s significant burden of thromboembolic and cardiovascular diseases, widespread clinical adoption of advanced anticoagulant therapies, and strong healthcare infrastructure.
According to the U.S. Centers for Disease Control and Prevention (CDC), atrial fibrillation is the most common treated cardiac arrhythmia, and an estimated 12.1 million people in the United States are projected to be living with the condition by 2050.
Because atrial fibrillation increases the risk of ischemic stroke by approximately fivefold, long-term anticoagulant therapy remains a cornerstone of disease management.
The region also benefits from early disease diagnosis, well-established clinical guidelines, broad access to direct oral anticoagulants (DOACs), and continuous regulatory approvals for innovative therapies.
Healthcare providers increasingly favor DOACs over conventional vitamin K antagonists because they require less routine monitoring and offer improved convenience for patients. In addition, high healthcare spending, comprehensive insurance coverage, and growing awareness of stroke prevention continue to support market demand.
Canada further contributes to regional growth through expanding cardiovascular care programs and increasing adoption of evidence-based anticoagulation strategies. Europe represents the second-largest regional market, supported by aging demographics and universal healthcare systems that encourage timely diagnosis and treatment of thromboembolic disorders.
Meanwhile, Asia-Pacific is anticipated to record the fastest growth during the forecast period due to improving healthcare infrastructure, rising cardiovascular disease incidence, expanding access to modern medicines, and increasing government initiatives focused on chronic disease management and stroke prevention.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global Anticoagulant Market is characterized by the presence of established pharmaceutical companies that compete through product innovation, clinical research, regulatory approvals, and geographic expansion.
Bristol-Myers Squibb Company and Pfizer Inc. hold a strong position through their global collaboration for Eliquis (apixaban), which is approved for reducing the risk of stroke in patients with non-valvular atrial fibrillation and for the treatment and prevention of deep vein thrombosis (DVT) and pulmonary embolism (PE).
Bayer AG and Johnson & Johnson (Janssen) continue to maintain a significant presence with Xarelto (rivaroxaban), while Boehringer Ingelheim GmbH offers Pradaxa (dabigatran), one of the first direct oral thrombin inhibitors introduced for stroke prevention and venous thromboembolism management.
Daiichi Sankyo Company strengthens its portfolio with LIXIANA/Savaysa (edoxaban), and Sanofi S.A. remains a key supplier of injectable anticoagulants through Lovenox (enoxaparin) for thrombosis prevention and treatment. AstraZeneca plc continues to expand its cardiovascular portfolio through ongoing research and strategic collaborations focused on cardiovascular disease management.
Collectively, these companies emphasize clinical trials, label expansions, regulatory compliance, and partnerships with healthcare providers to improve patient outcomes and strengthen their global market positions.
Top Key Players
- Bristol-Myers Squibb Company
- Bayer AG
- Johnson & Johnson (Janssen)
- Boehringer Ingelheim GmbH
- Pfizer Inc.
- Daiichi Sankyo Company
- Sanofi S.A.
- AstraZeneca plc
- GlaxoSmithKline plc
- Aspen Pharmacare Holdings
- LEO Pharma A/S
- Portola Pharmaceuticals (Alexion)
Recent Developments
- In April, 2025 – LEO Pharma A/S LEO Pharma expanded the commercial reach and digital footprint of its low-molecular-weight heparin, Innohep, across Canadian thrombosis clinics to secure the regional supply chain and address rising local patient demand.
- In January, 2026 – Bristol-Myers Squibb Company & Pfizer Inc. During their corporate briefings, BMS and Pfizer initiated a defensive direct-to-patient strategy in the United States to offset an anticipated 10% to 15% revenue decline in Europe as Eliquis loses patent exclusivity.
- In April, 2026 – Johnson & Johnson (Janssen) In its first-quarter financial report, Johnson & Johnson confirmed a strategic reallocation of pharmaceutical investments toward its next-generation thrombosis pipeline to counteract ongoing generic market erosion of Xarelto in the United States.
- In May, 2026 – Bayer AG Bayer announced that the U.S. FDA granted Priority Review for its New Drug Application for asundexian, accelerating the regulatory timeline from 10 months to 6 months to expedite the drug’s launch in the North American stroke prevention market.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 33.46 Billion |
| Forecast Revenue (2035) | US$ 66.48 Billion |
| CAGR (2026-2035) | 7.11% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Drug Class (Novel Oral Anticoagulants (NOACs), Heparin & Low Molecular Weight Heparin (LMWH), Vitamin K Antagonists (VKA), Direct Thrombin Inhibitors, Others), By Route of Administration (Oral, Injectable / Parenteral, Others), By Application (Atrial Fibrillation & Heart Attack, Venous Thromboembolism (DVT & PE), Pulmonary Embolism, Stroke Prevention, Others), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), By End User (Hospitals, Specialty Clinics, Ambulatory Care Centers, Homecare Settings) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Bristol-Myers Squibb Company, Bayer AG, Johnson & Johnson (Janssen), Boehringer Ingelheim GmbH, Pfizer Inc., Daiichi Sankyo Company, Sanofi S.A., AstraZeneca plc, GlaxoSmithKline plc, Aspen Pharmacare Holdings, LEO Pharma A/S, Portola Pharmaceuticals (Alexion) |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








