


Market Overview
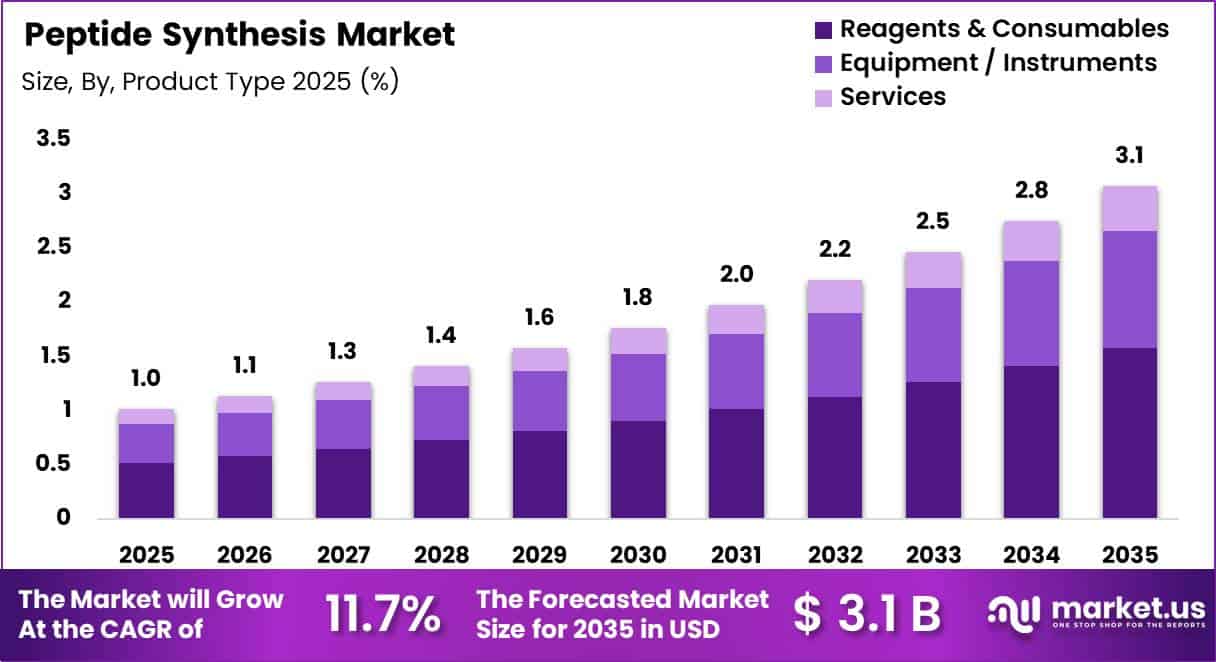
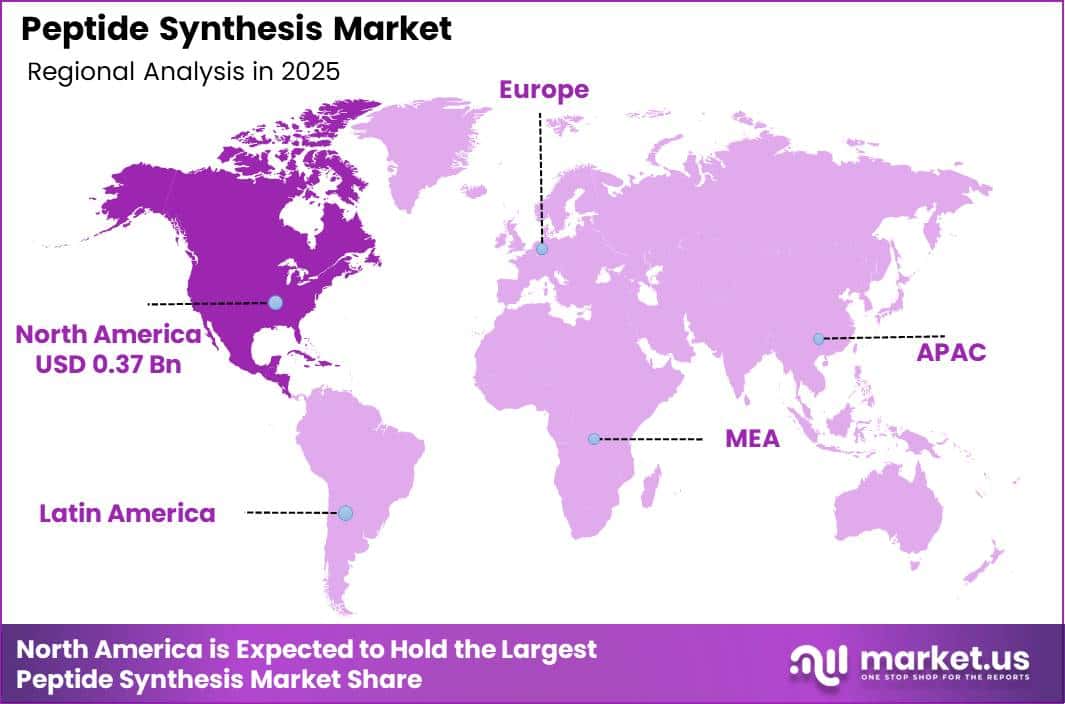
Global Peptide Synthesis Market size is expected to be worth around US$ 3.07 Billion by 2035 from US$ 1.02 Billion in 2025, growing at a CAGR of 11.7% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 37% share with a revenue of US$0.37 billion.
Peptide synthesis is a fundamental process used to produce short chains of amino acids that serve as therapeutic agents, research tools, diagnostic reagents, and vaccine components.
Advances in solid-phase peptide synthesis (SPPS), automated synthesizers, and purification technologies have significantly improved peptide yield, purity, and scalability, supporting growing applications across pharmaceuticals, biotechnology, and academic research.
Peptides are increasingly recognized for their high target specificity, favorable safety profiles, and ability to address diseases that are difficult to treat using conventional small-molecule drugs.
According to the U.S. Food and Drug Administration (FDA), more than 100 peptide-based drugs have been approved globally for treating conditions such as diabetes, cancer, osteoporosis, cardiovascular diseases, and metabolic disorders, with numerous additional candidates progressing through clinical development.
Meanwhile, ClinicalTrials.gov, maintained by the U.S. National Library of Medicine, lists thousands of active and completed clinical studies involving peptide therapeutics, reflecting sustained research and commercialization efforts. The World Health Organization (WHO) also recognizes peptide-based medicines as important components of treatment strategies for several chronic and infectious diseases.
Growing investment in precision medicine, oncology research, and next-generation biologics is driving demand for high-quality peptide synthesis services and reagents. Improvements in green chemistry, automated manufacturing platforms, and high-throughput synthesis technologies are helping reduce production time while improving reproducibility and product quality.
Furthermore, increasing collaborations between pharmaceutical companies, biotechnology firms, and research institutions are accelerating innovation in custom peptide production, peptide libraries, and complex therapeutic peptide development, reinforcing the strategic importance of peptide synthesis across modern drug discovery, diagnostics, and translational biomedical research.
Key Takeaways
- Market Size: Peptide Synthesis Market size was US$ 1.02 billion in 2025. The market is estimated to grow to US$ 3.07 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 11.7%.
- By Technology / Synthesis Method: Chemical Synthesis has the largest market share, accounting for 85.00% of total sales.
- By Type of API: Generic Peptides, accounting for 88% of total revenue.
- By Product: Reagents & Consumables leads the segment, accounting for 51.23% of total revenue.
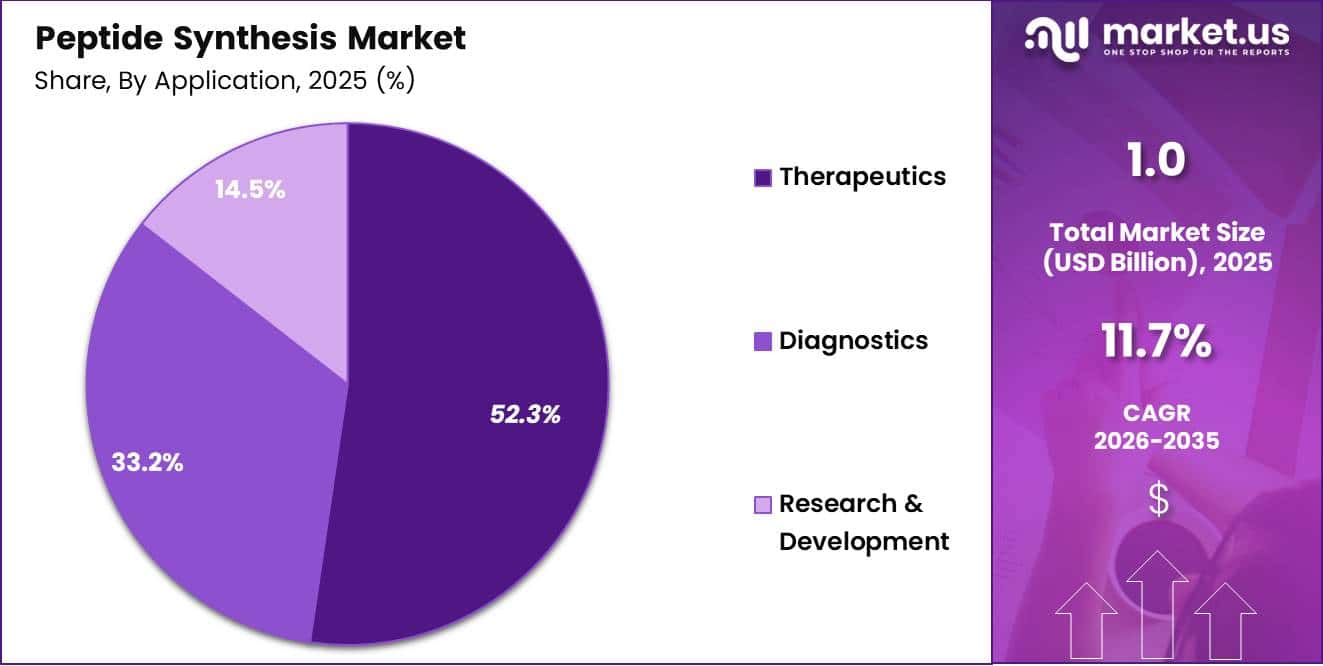
- By Application: Therapeutics (the largest segment) leads the segment, accounting for 52.31% of total revenue.
- By End User: Pharmaceutical & Biotechnology Companies lead the segment, accounting for 45% of total revenue.
- Regional: North America is the dominant regional market, accounting for 37% of global sales
Technology/Synthesis Method Segmentation Analysis
The technology/synthesis method segment of the peptide synthesis market is primarily led by chemical synthesis, which accounted for 85% of the market share in 2025. This dominance is attributed to its ability to produce peptides with high purity, precise sequence control, and scalability suitable for both research and commercial manufacturing.
Solid-phase peptide synthesis (SPPS), the most widely adopted chemical approach, enables rapid assembly of complex peptide chains while supporting automation and high-throughput production. Pharmaceutical manufacturers favor chemical synthesis because it accommodates a broad range of peptide lengths and modifications required for therapeutic development.
Continuous improvements in coupling reagents, protecting groups, and automated synthesizers have further enhanced production efficiency and reduced manufacturing time, reinforcing the segment’s market leadership.
The biological/recombinant method, representing 15% of the market in 2025, continues to gain traction for producing larger and more structurally complex peptides that are difficult to manufacture through chemical routes.
Recombinant technologies offer cost advantages for selected peptide products at large production volumes while supporting sustainable manufacturing practices. Growing advances in microbial expression systems, genetic engineering, and bioprocess optimization are expanding the applicability of recombinant peptide production.
Although this segment remains smaller than chemical synthesis, increasing demand for innovative peptide therapeutics is expected to support its steady growth over the forecast period.
Type of API Segmentation Analysis
Based on type of API, the peptide synthesis market is dominated by generic peptides, which captured 88% of the market share in 2025. The widespread adoption of generic peptide APIs is driven by the expiration of patents for several established peptide drugs and the increasing demand for cost-effective treatment alternatives.
Generic peptides provide healthcare providers with affordable therapeutic options while maintaining equivalent quality, safety, and efficacy standards required by regulatory authorities. Their extensive use in managing chronic diseases such as diabetes, hormonal disorders, and metabolic conditions has significantly contributed to market expansion.
Additionally, growing manufacturing capabilities, standardized production technologies, and expanding regulatory pathways for generic peptide approvals continue to strengthen this segment’s leadership.
The innovative and proprietary peptide API segment, accounting for the remaining market share, is witnessing steady development due to rising investments in novel drug discovery and precision medicine.
Pharmaceutical companies are focusing on next-generation peptide therapeutics with improved stability, enhanced bioavailability, and targeted delivery mechanisms. Increasing research into multifunctional peptides for oncology, rare diseases, and autoimmune disorders is creating new commercial opportunities.
Although innovative peptide APIs currently represent a smaller portion of the market, their strong clinical pipeline and expanding research collaborations are expected to drive long-term growth alongside continued advancements in peptide engineering technologies.
Product Segmentation Analysis
By product, the peptide synthesis market is led by reagents & consumables, which accounted for 51.23% of the market share in 2025. This leadership is supported by the recurring demand for amino acids, coupling reagents, resins, solvents, protecting groups, and purification materials used throughout peptide manufacturing workflows.
Since these consumables are required for every synthesis cycle, research project, and commercial production batch, they generate consistent purchasing activity across pharmaceutical companies, biotechnology firms, and academic laboratories.
The increasing volume of peptide research, expanding clinical pipelines, and growing commercialization of peptide therapeutics continue to fuel demand for high-quality reagents. Furthermore, continuous innovation in synthesis chemicals that improve reaction efficiency, purity, and yield has strengthened the dominance of this segment.
The equipment and instruments segment also represents an important component of the market, supported by increasing adoption of automated peptide synthesizers, purification systems, and analytical instruments.
Pharmaceutical manufacturers are investing in advanced automation technologies to improve production consistency, reduce labor requirements, and accelerate drug development timelines. Modern synthesis platforms capable of high-throughput processing and digital workflow integration are enhancing manufacturing efficiency.
As peptide-based drug development expands globally, demand for sophisticated synthesis equipment is expected to rise steadily, complementing the sustained growth of the reagents and consumables segment.
Application Segmentation Analysis
Based on application, the peptide synthesis market is dominated by therapeutics, which held 52.31% of the market share in 2025. The segment’s leadership is driven by the expanding clinical adoption of peptide-based medicines for treating metabolic disorders, cancer, cardiovascular diseases, infectious diseases, and endocrine conditions.
Peptide therapeutics offer high target specificity, favorable safety profiles, and reduced systemic toxicity compared with many conventional drugs, making them increasingly attractive for modern drug development.
Growing regulatory approvals of peptide medicines, combined with strong investment in clinical research and innovative drug pipelines, continue to accelerate demand for high-quality peptide synthesis. Advances in formulation technologies and delivery systems have also improved the clinical effectiveness and commercial viability of peptide-based therapies.
The research and diagnostic applications segment continues to expand as peptides become essential tools in biomarker discovery, vaccine development, molecular biology, and laboratory investigations.
Academic institutions, contract research organizations, and biotechnology companies increasingly utilize synthetic peptides for assay development, antibody production, and disease mechanism studies.
Rising investments in life science research, precision medicine, and personalized healthcare are further supporting demand across research applications. While therapeutics remain the dominant revenue contributor, expanding scientific research activities are expected to strengthen the overall growth of the peptide synthesis market during the forecast period.
End User Segmentation Analysis
Based on end user, pharmaceutical & biotechnology companies dominated the peptide synthesis market, accounting for 45% of the market share in 2025. Their leadership is driven by extensive investments in peptide drug discovery, clinical development, and commercial manufacturing.
These organizations utilize advanced peptide synthesis technologies to develop innovative therapeutics targeting chronic diseases, rare disorders, metabolic conditions, and oncology.
Increasing research and development expenditures, expanding biologics pipelines, and the growing number of peptide-based drug candidates have significantly increased demand for high-quality synthesis services and manufacturing capabilities.
Strategic collaborations with contract development and manufacturing organizations (CDMOs), along with the adoption of automated synthesis platforms, have further strengthened the position of pharmaceutical and biotechnology companies within the market.
Other important end users include academic & research institutes, contract research organizations (CROs), and contract manufacturing organizations (CMOs/CDMOs), which collectively contribute to market growth through basic research, preclinical studies, process development, and large-scale production.
Universities and research centers continue to advance peptide science through innovation in synthesis methods and therapeutic applications. Meanwhile, outsourcing trends are increasing demand for specialized CRO and CDMO services that offer technical expertise, regulatory compliance, and scalable manufacturing solutions.
Together, these end users are supporting continuous technological advancement and expanding the global peptide synthesis ecosystem.
Market Segmentations
By Technology / Synthesis Method
- Chemical Synthesis
- Solid-Phase Peptide Synthesis (SPPS)
- Fmoc (Fluorenylmethyloxycarbonyl) Strategy
- Boc (t-Butyloxycarbonyl) Strategy
- Liquid-Phase Peptide Synthesis (LPPS)
- Hybrid Phase Synthesis (SPPS + LPPS combined)
- Biological / Recombinant Method
- Enzymatic Synthesis
- Cell-Free / In Vitro Synthesis
- Recombinant DNA Technology
By Type of API
- Generic Peptides
- Branded / Innovator Peptides
By Product
- Reagents & Consumables
- Equipment / Instruments
- Services
By Application
- Therapeutics (largest segment)
- Oncology
- Metabolic Disorders (Diabetes, Obesity — GLP-1 agonists)
- Cardiovascular Diseases
- Infectious Diseases
- CNS Disorders
- Diagnostics
- Research & Development
By End User
- Pharmaceutical & Biotechnology Companies
- Contract Development & Manufacturing Organizations (CDMOs)
- Contract Research Organizations (CROs)
- Academic & Research Institutes
Driver
Rapid Expansion of Therapeutic Peptide Pipeline and TIDES Approvals Driving Growth
The most powerful structural driver is the expansion of the global peptide and oligonucleotide (TIDES) pipeline, which systematically translates into higher synthesis volumes, more complex sequences, and broader adoption of custom and catalog peptide offerings.
As of the mid-2020s, more than 80 peptide drugs have gained global regulatory approval, and 200–650 peptide-based candidates are in clinical development depending on the definition used, spanning oncology, autoimmune, metabolic, cardiovascular, and infectious disease indications. This expansion inherently requires robust upstream peptide synthesis capacity.
In the US, CDER approved 50 novel drugs in 2024 and 46 in 2025, with specialist TIDES analyses indicating that multiple peptide or peptide-containing entities were included among these approvals in each year. This confirms that peptides are no longer a niche therapeutic category but an increasingly recurring component of annual drug approval pipelines.
The growing pipeline is driving sponsors to secure multi-year access to GMP-grade peptides, reference standards, and process development batches, pushing both captive and outsourced synthesis capacity expansion at double-digit volume rates, even where revenue growth remains in the mid-single-digit to high-single-digit range due to pricing pressure.
Strategically, this driver accelerates the transition from ad hoc, project-based synthesis toward portfolio-level capacity planning, with pharmaceutical companies developing multi-asset peptide platforms and CDMOs restructuring operations around repeat clinical and commercial supply contracts.
This structural shift is capable of lifting baseline peptide synthesis market CAGR by around 2.2 % points over 2026–2030, keeping peptide synthesis growth above broader pharmaceutical R&D expansion trends.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid expansion of therapeutic peptide pipeline and TIDES approvals | +2.2% | North America core, EU, Japan, selective APAC hubs | Medium term (2–4 years) |
| Scale-up of solid-phase and hybrid peptide synthesis technologies | +1.9% | North America, EU, China, India, South Korea | Long term (≥ 4 years) |
| Shift of pharma/biotech outsourcing to specialized peptide CDMOs | +1.7% | North America, EU, APAC corridors, LatAm spill-over | Medium term (2–4 years) |
| Regulatory support and streamlined pathways for complex peptides | +1.4% | US, EU-5, Japan, China | Medium term (2–4 years) |
| Growth in metabolic, oncology and infectious disease peptide therapeutics | +1.8% | Global, with demand concentration in US, EU, China | Long term (≥ 4 years) |
| Cost optimization through automation, miniaturization and greener chemistries | +1.5% | Global, with manufacturing clusters in US, EU, China, India | Short to medium term (≤ 4 years) |
Challenge
Complex Multi Step GMP Compliance Limiting Peptide Synthesis Growth
Peptide synthesis operates at a regulatory intersection where FDA, EMA, and ICH guidelines demand granular control of impurities, elemental contaminants, nitrosamines, and sequence variants across 15–40 step synthetic routes, creating significantly higher CMC and documentation burdens compared with typical small-molecule APIs.
For a 30-mer therapeutic peptide, sponsors frequently manage specifications for 20–40 individual process-related impurities, maintain total impurity limits at 1.0–1.5%, and implement multi-stage purification involving up to 3–4 chromatographic passes. These requirements add 20–30% to batch cycle time and increase cost of goods by 10–20% compared with products requiring less stringent impurity control.
Validation and stability programs typically require 3–6 validated analytical methods, including HPLC, LC-MS, peptide mapping, residual solvent analysis, and elemental testing, along with 12–24 month stability studies across multiple temperature and humidity conditions.
Extensive comparability packages are also required in line with evolving FDA and EMA expectations for synthetic peptides modeled on biological reference products.These requirements create ongoing operational friction through additional QA/QC resources, extended technology-transfer timelines of 6–9 months, and higher risks of regulatory queries. Collectively, these factors create an estimated 1.1 %-point drag on market CAGR as projects progress more slowly through development and regulatory filing stages.
Corporate responses include establishing centralized peptide CMC centers of excellence, digitalizing batch records and impurity-trending systems, adopting platform analytical methods across multiple peptide programs to reduce validation duplication, and embedding regulatory specialists into process-development teams to reduce iteration cycles by 10–20% over the long term.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Capacity-constrained CDMO network | -1.4% | North America, EU, APAC hubs | Medium term (2–4 years) |
| Complex multi-step GMP compliance | -1.1% | US, EU, Japan, Korea | Long term (≥ 4 years) |
| High-complexity obesity peptide pipelines | -0.9% | US, EU, global trial clusters | Medium term (2–4 years) |
| Fragmented amino acid supply chain | -0.8% | APAC corridors, EU importers | Medium term (2–4 years) |
| Advanced analytics and QC bottlenecks | -0.7% | Global regulatory hubs | Long term (≥ 4 years) |
| Chronic peptide talent shortfall | -0.6% | US, EU, India, China | Long term (≥ 4 years) |
Restraints
Limited GMP Capable Peptide Capacity Restricting Market Expansion
Despite robust demand from metabolic disease, oncology, and vaccine applications, GMP-capable peptide synthesis capacity remains geographically concentrated and significantly constrained.
A limited pool of CDMOs can reliably deliver multi-kilogram GMP lots of complex peptides under stringent regulatory expectations, leading to chronic slot scarcity and extended project lead times.
Many established facilities operate at 75–90% utilization on critical solid-phase synthesis lines, resulting in contractual lead times of 9–15 months for new projects and 6–9 months for scale-up campaigns.
Therapeutic peptide batch sizes often remain in the 0.5–5 kg per run range due to reactor limitations and resin handling constraints, restricting manufacturing efficiency and limiting economies of scale.
Building additional GMP peptide capacity, including large-scale reactors of 300–1,000 L, advanced purification systems, and validated cleanroom infrastructure, typically requires USD 30–80 million in capital investment per site and qualification timelines of 24–36 months. These requirements make sponsors cautious about aggressive capacity expansion amid macroeconomic uncertainty and structurally higher interest rates compared with the 2010s.
As a result, some pipeline programs experience sequencing delays, with 10–20% of planned peptide-based trials being rephased or slowed due to manufacturing slot constraints, particularly in North America and Europe.
while emerging APAC corridors continue to face shortages of GMP-qualified partners. These supply-side limitations create an estimated 1.2 %-point drag on global peptide synthesis CAGR through 2026–2030 by restricting the pace at which demand can be converted into commercial-scale output.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High-cost protected reagents & resins | -1.6% | North America core, EU, Japan, South Korea | Medium term (2–4 years) |
| Regulatory stringency on peptide impurities | -1.4% | US, EU, UK, Japan | Long term (≥ 4 years) |
| Limited GMP-capable peptide capacity | -1.2% | North America, EU, select APAC corridors | Medium term (2–4 years) |
| Supply chain fragility in amino acid & solvent inputs | -1.0% | Global, with higher exposure in APAC and EU | Short to medium term (≤ 3 years) |
| Skilled workforce and automation gap | -0.9% | Global, pronounced in emerging APAC & LATAM | Long term (≥ 4 years) |
Opportunity
High Throughput Custom Research Peptides Creating New Growth Opportunities
While current growth drivers already account for routine custom peptide orders for academia and pharmaceutical R&D, they do not fully capture the potential step-change in high-throughput and ultra-custom peptide demand linked to emerging research models such as large-scale screening libraries, peptide microarrays, and peptide conjugates for diagnostics and targeted delivery.
This opportunity focuses on industrializing small-batch, high-mix production through flexible and automated platforms capable of synthesizing thousands of distinct sequences per month, with order sizes often ranging from milligrams to grams, where turnaround time and sequence complexity remain key demand constraints.
By developing digital ordering portals, standardized catalog libraries exceeding 50,000–100,000 sequences, and AI-assisted sequence optimization engines, suppliers can access an underpenetrated market in translational research and early-stage discovery that could reach 1.5–2.0 times current academic and research peptide spending by 2030.
Operational improvements, including reducing average lead times from 3–4 weeks to 5–7 days and lowering per-sequence quality-control costs by 20–25% through integrated LC-MS analysis and automated documentation, could increase throughput per production line by 2–3 times while maintaining gross margins in the 45–55% range through premium pricing for complex modifications such as PEGylation, cyclization, and labeling.
With life sciences R&D investment expanding across North America, Europe, China, and India, and peptide applications extending into infectious diseases, oncology, autoimmune disorders, diagnostics, and targeted delivery, scaling bespoke research peptide capacity and digital ordering infrastructure could generate approximately 2 % points of CAGR upside beyond baseline growth.
The opportunity is expected to accelerate over a 2–4-year execution window as demand for high-complexity screening tools continues to expand.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| GLP-1 & metabolic peptide scale-out | +3.0% | North America, EU, East Asia | Short term (≤ 2 years) |
| Peptide CDMO & synthesizer platformization | +2.5% | North America core, EU, APAC emerging | Medium term (2-4 years) |
| High-throughput custom research peptides | +2.0% | North America, EU, China, India | Medium term (2-4 years) |
| Smart, green peptide synthesis technologies | +1.8% | EU, North America, Japan, South Korea | Long term (≥ 4 years) |
| Peptide-enabled precision nutrition & diabetes care | +2.2% | North America, EU, Gulf, APAC urban | Medium term (2-4 years) |
| Regionalized peptide manufacturing clusters | +2.7% | APAC (India, China, ASEAN), LATAM, MENA | Long term (≥ 4 years) |
Regional Analysis
In 2025, North America led the market, achieving over 37% share with a revenue of US$0.37 billion.
In 2025, North America region’s leadership is supported by a strong biopharmaceutical ecosystem, advanced research infrastructure, and significant investments in peptide-based drug discovery and development.
The United States remains the primary contributor, driven by the presence of major pharmaceutical companies, contract development and manufacturing organizations (CDMOs), and leading academic research institutions.
Increasing demand for peptide therapeutics in oncology, metabolic disorders, and rare diseases continues to accelerate peptide synthesis activities across the region. Government funding for biomedical research, coupled with favorable regulatory pathways for innovative therapeutics, further strengthens market growth.
Europe represents the second-largest regional market, supported by a well-established pharmaceutical manufacturing base, extensive clinical research programs, and increasing adoption of peptide-based medicines. Countries such as Germany, Switzerland, the United Kingdom, and France continue to invest in advanced synthesis technologies and GMP-compliant production facilities.
The Asia-Pacific region is expected to register the fastest growth during the forecast period, fueled by expanding pharmaceutical manufacturing capabilities, lower production costs, and rising investments in biotechnology across China, India, Japan, and South Korea. Growing outsourcing of peptide manufacturing and increasing research collaborations are also boosting regional demand.
Latin America and the Middle East & Africa hold comparatively smaller market shares but are experiencing gradual growth due to improving healthcare infrastructure, expanding pharmaceutical industries, and increasing awareness of peptide-based therapies.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global peptide synthesis market is moderately consolidated, with a mix of established multinational manufacturers and specialized peptide synthesis providers competing across research, clinical, and commercial production.
Competition is driven by technological innovation, manufacturing scalability, quality compliance, and the ability to support increasingly complex peptide therapeutics. Companies are investing heavily in advanced synthesis platforms, automation, and high-purity manufacturing capabilities to meet growing demand from pharmaceutical, biotechnology, and academic research organizations.
The market also reflects increasing collaboration across the drug development ecosystem, where integrated services from peptide design through GMP manufacturing have become a key differentiator.
Leading participants include Bachem Holding AG, Thermo Fisher Scientific Inc., Merck KGaA (MilliporeSigma), PolyPeptide Group, GenScript Biotech Corporation, Lonza Group AG, Ajinomoto Bio-Pharma Services, AmbioPharm Inc., CEM Corporation, Aapptec LLC (AAPPTEC), Biotage AB, AnaSpec Inc., Corden Pharma International, Asymchem Laboratories, and Creative Peptides.
These companies are strengthening their competitive positions through continuous R&D focused on improving synthesis efficiency, peptide purity, and production yields while expanding capabilities for complex and long-chain peptides.
Strategic partnerships with pharmaceutical and biotechnology companies enable accelerated drug development and broader manufacturing capacity. Product innovation includes automated synthesizers, advanced resins, novel coupling chemistries, and integrated purification technologies that improve workflow efficiency.
Many players are also pursuing workflow integration by combining peptide discovery, analytical characterization, scale-up, and GMP manufacturing within unified service platforms. This ecosystem-based competitive approach enhances customer retention, shortens development timelines, and supports the expanding pipeline of peptide-based therapeutics across diverse clinical applications.
Top Key Players
- Bachem Holding AG
- Thermo Fisher Scientific Inc.
- Merck KGaA (MilliporeSigma)
- PolyPeptide Group
- GenScript Biotech Corporation
- Lonza Group AG
- Ajinomoto Bio-Pharma Services
- AmbioPharm Inc.
- CEM Corporation
- Aapptec LLC (AAPPTEC)
- Biotage AB
- AnaSpec Inc.
- Corden Pharma International
- Asymchem Laboratories
- Creative Peptides
Recent Developments
- In February 2025, Bachem Holding AG announced major investments to expand peptide manufacturing capacity, including new large-scale SPPS reactors, expanded production infrastructure in Switzerland and the U.S., and plans for a new peptide manufacturing site in Sisseln to address growing peptide API demand.
- In September 2025, Thermo Fisher Scientific Inc. completed the acquisition of Sanofi’s sterile manufacturing facility in Ridgefield, New Jersey, expanding its CDMO manufacturing capacity and strengthening pharmaceutical production services for global biopharma customers.
- In May 2026, Corden Pharma International announced the acquisition of AmbioPharm Inc., significantly expanding its global peptide API development and manufacturing capabilities while increasing U.S.-based peptide production capacity.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 1.02 Billion |
| Forecast Revenue (2035) | US$ 3.07 Billion |
| CAGR (2026-2035) | 11.7% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Technology / Synthesis Method(Chemical Synthesis, Biological / Recombinant Method) By Type of API(Generic Peptides, Branded / Innovator Peptides) By Product(Reagents & Consumables, Equipment / Instruments, Services)By Application (Therapeutics, Diagnostics, Research & Development) By End User(Pharmaceutical & Biotechnology Companies, Contract Development & Manufacturing Organizations (CDMOs), Contract Research Organizations (CROs), Academic & Research Institutes) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Bachem Holding AG ,Thermo Fisher Scientific Inc. ,Merck KGaA (MilliporeSigma) ,PolyPeptide Group ,GenScript Biotech Corporation ,Lonza Group AG ,Ajinomoto Bio-Pharma Services ,AmbioPharm Inc. ,CEM Corporation, Aapptec LLC (AAPPTEC) ,Biotage AB ,AnaSpec Inc. ,Corden Pharma International ,Asymchem Laboratories, Creative Peptides |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








