


Report Overview
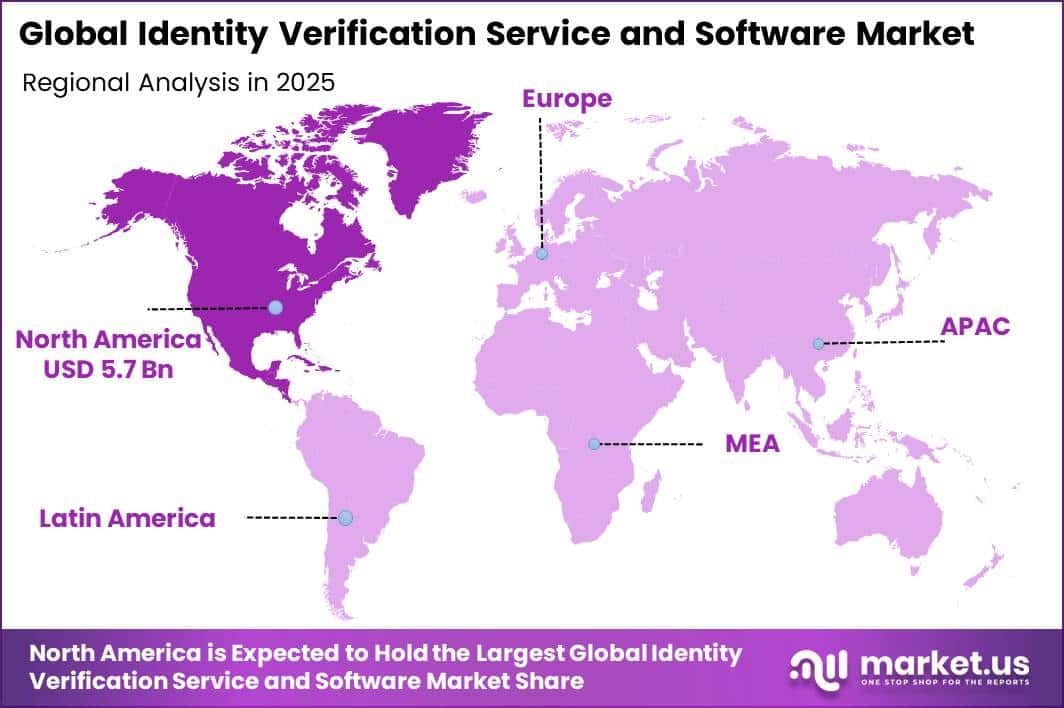
In 2025, the Global Identity Verification Service and Software Market was valued at USD 14.7 billion. The market is projected to grow at a CAGR of 15.1% during 2026–2035, reaching approximately USD 60.0 billion by 2035. North America dominated the global market in 2025, accounting for more than 38.7% of the total market share and generating approximately USD 5.7 billion in revenue.
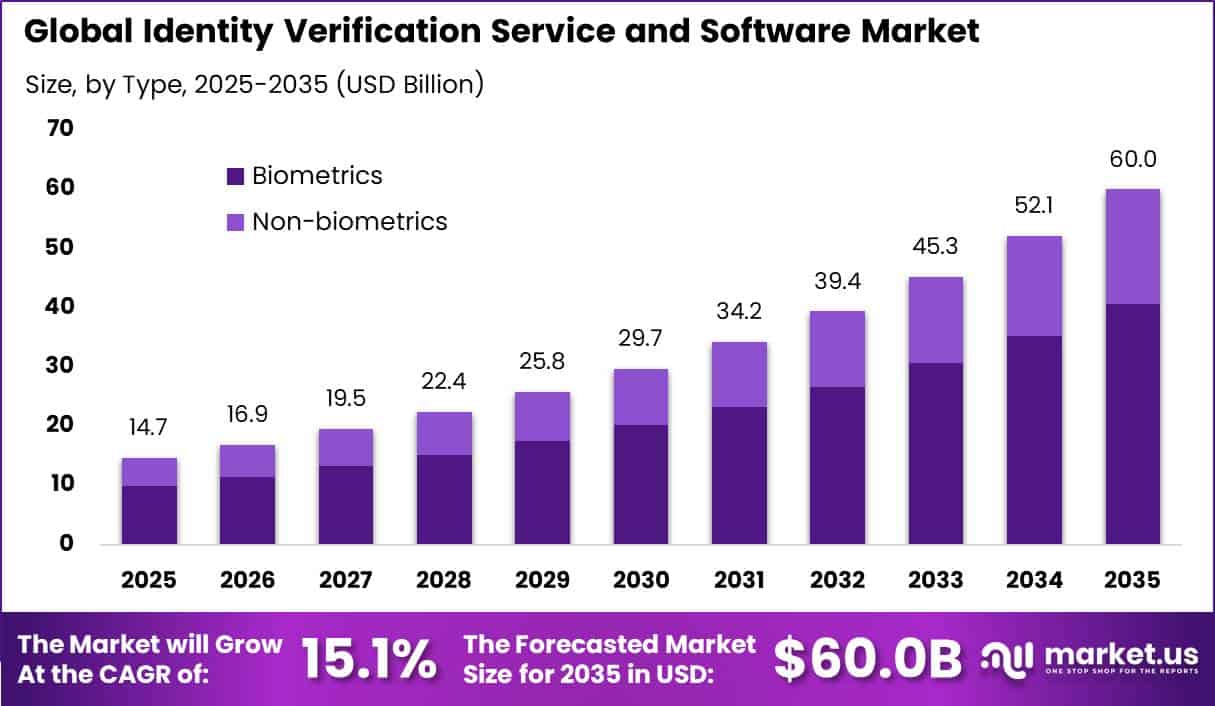
Market growth is supported by the increasing need for banks, telecom companies, insurers, digital platforms, and government agencies to verify users before opening accounts, processing payments, providing services, or allowing access to sensitive information.
In the United States, the FTC received more than 6.5 million consumer reports in 2024, including over 1.1 million identity-theft reports. Consumers reported fraud losses exceeding USD 12.5 billion, representing a 25% increase from the previous year, while credit-card-related identity theft reached 449,032 reports.
The FBI recorded 859,532 suspected internet-crime complaints in 2024, with reported losses reaching USD 16.6 billion, up 33% from 2023. In addition, the 2025 NIST Digital Identity Guidelines strengthened recommendations related to fraud prevention and identity proofing, further encouraging organizations to invest in secure and automated identity verification solutions.
Key Takeaway
- The Identity Verification Service and Software Market was valued at USD 14.7 billion in 2025 and is projected to reach USD 60.0 billion by 2035 at a 15.1% CAGR.
- The biometrics segment dominated with a 67.8% share, driven by strong demand for secure identity authentication.
- The software segment dominated with a 73.2% share, supported by growing adoption of automated verification platforms.
- The on-premises segment dominated with a 60.7% share, supported by greater control over sensitive identity data.
- Large enterprises dominated with a 65.4% share, driven by high transaction volumes and stronger compliance needs.
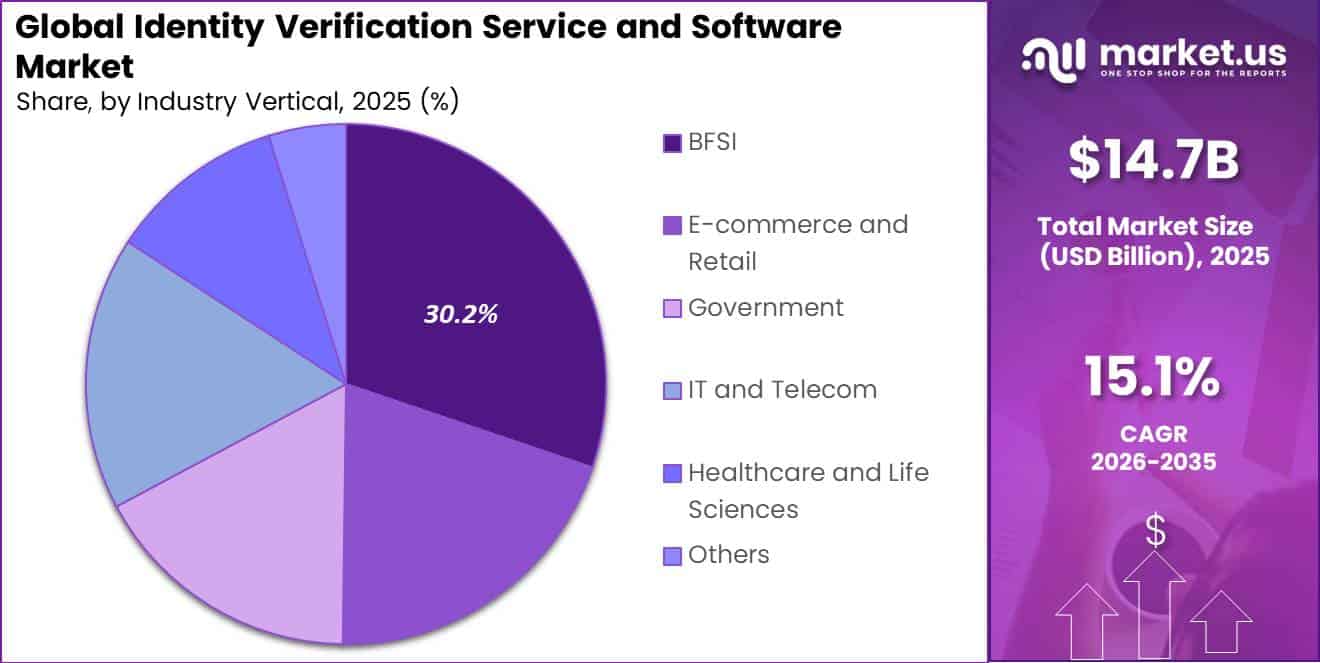
- The BFSI segment dominated with a 30.2% share, supported by strict KYC, AML, and fraud-prevention requirements.
- North America led the market in 2025 with a 38.7% share, generating around USD 5.7 billion in revenue.
By Type
Biometrics held a dominant position in the Identity Verification Service and Software Market, accounting for a 67.8% share. The segment leads because biometric verification uses physical characteristics such as facial features, fingerprints, iris patterns, and voice to confirm a person’s identity. These traits are more difficult to copy, share, or misuse compared with passwords and basic identity documents.
Biometric solutions are increasingly used for digital account opening, employee access, government benefits, travel services, and online public services. According to the World Bank, more than 90% of countries use digital data within their identity systems, while at least two-thirds provide some form of digital verification or authentication for in-person transactions.
Demand also remains strong due to gaps in global identity access. The World Bank’s 2025 ID4D data indicates that around 800 million people still lack official identification, while approximately 2.8 billion people do not have access to a government-recognized digital identity for secure online transactions. Moreover, national identification is required for bank-account opening in 65 of 73 countries reviewed by the World Bank.
By Component
Software held a dominant position in the Identity Verification Service and Software Market, accounting for a 73.2% share. The segment leads because identity verification software can manage the complete verification process in real time, including data capture, document validation, biometric matching, risk assessment, audit recording, and integration with banking, telecom, insurance, and government platforms.
According to the World Bank, 64% of adults worldwide made or received a digital payment in 2021, while the share reached 95% in high-income economies. This growing use of digital financial services increases the need for fast and automated identity checks that can handle large transaction volumes without requiring the same level of manual staff.
The United Nations reported that 189 countries, representing 98% of assessed UN Member States, provided at least one online government service in 2024. The global average number of online services also increased from 16 in 2022 to 18 in 2024. Software platforms support these services by verifying users, reducing duplicate accounts, improving fraud controls, and maintaining compliance records, strengthening the segment’s leading market position.
By Deployment
On-premises deployment held a dominant position in the Identity Verification Service and Software Market, accounting for a 60.7% share. The segment leads because banks, government agencies, healthcare organizations, and large enterprises often prefer to keep sensitive identity information within their own IT infrastructure.
Biometric records, identity documents, customer data, and verification logs can be stored in internal data centers, giving organizations greater control over security, access, data retention, and system updates. The U.S. banking system included 3,912 commercial banks in 2024, representing a large base of regulated institutions that manage confidential customer information and often depend on complex legacy systems.
By Organization Size
Large enterprises held a dominant position in the Identity Verification Service and Software Market, accounting for a 65.4% share. The segment leads because large organizations manage high transaction volumes, broad customer networks, and greater financial risks linked to fraudulent or duplicate identities. According to UNCTAD, business e-commerce sales across 43 economies reached nearly USD 27 trillion in 2022, compared with USD 17 trillion in 2016.
Their larger technology budgets also allow identity platforms to be integrated with identity-theft reports, customer applications, employee systems, compliance tools, and fraud-management platforms. According to the World Federation of Exchanges, 52,756 domestic and foreign companies were listed across member exchanges in March 2025, with a combined market capitalization of USD 123.7 trillion.
By Industry Vertical
BFSI held a dominant position in the Identity Verification Service and Software Market, accounting for a 30.2% share. The segment leads because banks, insurers, payment companies, and other financial institutions must verify customers before opening accounts, transferring funds, issuing credit, or processing insurance claims.
Demand is also supported by the large volume of money moving through the global financial system. According to the World Bank, worldwide remittance flows reached around USD 905 billion in 2024, including approximately USD 685 billion received by low- and middle-income countries.
Key Market Segments
By Type
- Biometrics
- Non-biometrics
By Component
- Software
- Service
By Deployment
- On-premises
- Cloud
By Organization Size
- SMEs
- Large Enterprises
By Industry Vertical
- BFSI
- E-commerce and Retail
- Government
- IT and Telecom
- Healthcare and Life Sciences
- Others
Geopolitical Impact Analysis
Geopolitical disruption is affecting the Identity Verification Service and Software Market mainly through the hardware, data infrastructure, and electronic components required for biometric verification, document scanning, secure storage, and edge processing. Cameras, fingerprint scanners, servers, networking equipment, and mobile verification terminals depend heavily on global semiconductor and electronics supply chains.
UN Trade and Development reported that by mid-2024, vessel tonnage passing through the Suez Canal had fallen by 70%, while tonnage arriving in the Gulf of Aden declined by 76% due to Red Sea disruption. Shipping rerouting contributed 148 percentage points to a cumulative 120% increase in the China Containerized Freight Index between October 2023 and June 2024.
Trade tensions are adding further sourcing and pricing pressure. The WTO projected global merchandise trade volume to decline by 0.2% in 2025 under policy conditions prevailing in April 2025, while stronger tariff measures and uncertainty could have resulted in a 1.5% contraction. The IEA also reports that China processes more than half of global lithium, cobalt, graphite, and rare-earth supplies, increasing supply concentration risks for electronic components.
Vendors are therefore expanding inventories, qualifying alternative suppliers, and regionalizing production. Energy costs remain another concern, although the World Bank projected its energy-price index to decline by 17% in 2025, while continuing geopolitical tensions could still create price volatility.
Regional Analysis
North America held a dominant position in the Identity Verification Service and Software Market in 2025, capturing a 38.7% share and generating around USD 5.7 billion in revenue. The region benefits from high digital transaction volumes across banking, insurance, retail, healthcare, telecom, and government services. According to the U.S. Census Bureau, U.S. retail e-commerce sales reached USD 326.7 billion in the first quarter of 2026.
Growing online purchases, digital account registrations, loan applications, insurance claims, and wallet transactions are increasing the need for secure identity checks and fraud prevention. Large enterprises are also investing in biometrics, document verification, risk scoring, and compliance software. In Canada, the government provides more than 270 online services and continues to develop digital credentials and single-sign-on systems.
Asia Pacific is expected to be the fastest-growing regional market, supported by rapid growth in digital payments, mobile banking, e-commerce, and public digital services. World Bank Global Findex data shows that 89% of adults in China held an account in 2021, while 82% used an account for digital merchant payments.
Across the rest of East Asia and the Pacific, 59% of adults had an account and 23% made digital merchant payments. Around 54% of these digital-payment users adopted such services for the first time after the pandemic began, increasing demand for remote identity verification, biometric matching, document checks, and fraud screening.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Drivers
| Driver | (~) % CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Risk-based digital identity standards | +2.4% | North America and Europe | Short term (2 years or less) |
| Digital-payment onboarding volumes | +1.9% | Global | Short term (2 years or less) |
| Biometric authentication adoption | +1.6% | North America, Europe and Asia Pacific | Medium term (2 to 4 years) |
| Public-service digitization | +1.3% | Europe, Asia Pacific and Middle East | Medium term (2 to 4 years) |
| Enterprise fraud-control integration | +1.1% | Global | Short term (2 years or less) |
Risk-based digital identity standards
NIST finalized SP 800-63-4 in July 2025, replacing the 2020 edition and strengthening controls for remote identity proofing, phishing resistance, enrollment attacks, mobile driver’s licenses, and verifiable credentials.
The EU Digital Identity Regulation became effective in May 2024 and requires every Member State to provide at least 1 interoperable digital wallet by the end of 2026. The European Commission also adopted 7 additional trust-service regulations in July 2025.
These standards are shifting spending from one-time document checks toward recurring identity platforms covering proofing, authentication, fraud analytics, audit trails, and credential management. Better standardization can reduce integration risk and support higher enterprise adoption, creating an estimated +2.4% CAGR contribution above the 15.1% baseline CAGR.
Restraints
| Restraint | (~) % CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Biometric privacy restrictions | -2.1% | Europe and North America | Short term (2 years or less) |
| Data-localization mandates | -1.5% | Asia Pacific, Middle East and Europe | Medium term (2 to 4 years) |
| Public-procurement budget limits | -1.1% | Emerging markets | Short term (2 years or less) |
| Legacy-system replacement costs | -0.9% | Global | Medium term (2 to 4 years) |
| Cross-border data-transfer limits | -0.8% | Europe and Asia Pacific | Short term (2 years or less) |
Biometric privacy restrictions
Biometric verification can face sales barriers because facial templates, fingerprints, and voiceprints are sensitive personal data that require strict legal controls and limited retention. The EU AI Act entered into force on 1 August 2024, with bans on certain AI practices applying from 2 February 2025. The European Data Protection Board also continues to apply GDPR requirements across 27 EU Member States.
NIST’s 2025 identity guidelines further increase testing and assurance requirements for proofing errors, presentation attacks, and enrollment fraud. These compliance pressures can delay biometric deployments or push customers toward lower-assurance methods, creating an estimated -2.1% CAGR drag against the 15.1% baseline CAGR.
Challenges
| Challenge | (~) % CAGR | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Deepfake attack escalation | -1.8% | Global | Medium term (2 to 4 years) |
| Document coverage fragmentation | -1.3% | Global | Long term (4 years or more) |
| Identity-data quality gaps | -1.1% | Emerging markets | Long term (4 years or more) |
| Skilled security talent shortage | -0.9% | Global | Medium term (2 to 4 years) |
| Model-bias validation burden | -0.7% | North America and Europe | Medium term (2 to 4 years) |
Deepfake attack escalation
Identity verification providers must continuously improve fraud models, liveness detection, testing, and human-review processes to respond to changing attack methods. These additional operating and R&D costs can limit margin improvement and create an estimated -1.8% CAGR friction drag on maximum market growth.
Opportunities
| Opportunity | (~) % CAGR | Geographic Relevance | Execution Window |
|---|---|---|---|
| Reusable digital credential networks | +2.2% | Europe, North America and Asia Pacific | Medium term (2 to 4 years) |
| SME compliance automation | +1.6% | Global | Medium term (2 to 4 years) |
| Age-assurance service expansion | +1.3% | Europe, North America and Australia | Short term (2 years or less) |
| Workforce identity orchestration | +1.1% | North America and Europe | Medium term (2 to 4 years) |
| Embedded identity API monetization | +0.9% | Global | Long term (4 years or more) |
Reusable digital credential networks
Reusable credential networks remain a strong opportunity rather than a current growth driver because cross-sector acceptance and enterprise integration are still developing. The EU Digital Identity Framework requires Member States to provide at least 1 digital identity wallet by the end of 2026, while these wallets can link national identities with driving licences, qualifications, and bank-account information.
A mature reusable-credential model could reduce repeated identity checks by allowing users to share verified attributes with consent. This could lower verification costs by around 30% to 50% after initial enrollment and create recurring revenue from credential issuance, verification, orchestration, and audit services. If providers build strong issuer partnerships and interoperable wallet networks, this opportunity could add around +2.2% CAGR upside above the 15.1% baseline CAGR.
Key Players Analysis
Tier-1 companies in the Identity Verification Service and Software Market include large data, credit, and risk-information providers with strong enterprise relationships and compliance capabilities. RELX, through LexisNexis Risk Solutions, reported GBP 3.2 billion in 2024 Risk revenue, representing 35% of RELX’s GBP 9.4 billion group revenue.
Experian generated USD 5.4 billion in FY2025 B2B revenue, including USD 3.8 billion from data products and USD 1.5 billion from decisioning. The company also invested USD 1.2 billion in acquisitions and USD 651 million in capital expenditure. TransUnion reported USD 4.1 billion in 2024 revenue.
Together, these Tier-1 players are estimated to represent around 25–35% of addressable identity, fraud, and decisioning spending within the listed peer group, although audited market-share data is not publicly available.
Tier-2 players such as GBG/IDology, Mitek, Jumio, Onfido, Trulioo, Veriff, AuthenticID, Pindrop, ComplyCube, and Intellicheck compete through biometric verification, document authentication, liveness detection, and SaaS-based onboarding. GBG reported GBP 282.7 million in FY2025 revenue, with Identity contributing GBP 159.0 million, or 56%.
Mitek generated USD 179.7 million, including USD 105.6 million in recurring revenue, up 17%, while R&D spending reached USD 35.3 million, or about 19.6% of revenue. Intellicheck reported USD 22.4 million in SaaS revenue, equal to 99% of USD 22.7 million total revenue, while R&D spending rose 38% to USD 5.3 million.
Top Key Players in the Market
- Onfido Limited
- Idology Inc. (GB Group PLC)
- Intellicheck Inc.
- Jumio Corporation
- Trulioo Information Services Inc.
- Mitek Systems Inc.
- Veriff
- IBM Corporation
- AuthenticID
- Experian PLC
- TransUnion
- LexisNexis Risk Solutions Inc. (RELX Group PLC)
- Pindrop
- ComplyCube
- Nuance Communications Inc.
Recent Developments
- In 2025, GBG acquired DataTools, an Australian and New Zealand address-validation and data-quality provider, for AUD 16.0 million, equivalent to about GBP 7.9 million. DataTools generated AUD 5.0 million in revenue during the 12 months ended June 2025, with more than 90% recurring revenue from over 700 customers.
- In 2026, Jumio expanded its digital identity capabilities through an integration with Trinsic, allowing customers to verify mobile driver’s licenses, electronic IDs, EUDI credentials, and other reusable digital credentials across more than 60 countries and territories. Jumio reported that its wider platform had processed more than 1 billion transactions across over 200 countries and territories, strengthening its position in large-scale digital identity verification.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 14.7 Billion |
| Forecast Revenue (2035) | USD 60.0 Billion |
| CAGR (2026-2035) | 15.1% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Type (Biometrics, Non-biometrics); By Component (Software, Service); By Deployment (On-premises, Cloud); By Organization Size (SMEs, Large Enterprises); By Industry Vertical (BFSI, E-commerce and Retail, Government, IT and Telecom, Healthcare and Life Sciences, Others) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | Onfido Limited, Idology Inc. (GB Group PLC), Intellicheck Inc., Jumio Corporation, Trulioo Information Services Inc., Mitek Systems Inc., Veriff, IBM Corporation, AuthenticID, Experian PLC, TransUnion, LexisNexis Risk Solutions Inc. (RELX Group PLC), Pindrop, ComplyCube, Nuance Communications Inc. |
| Customization Scope | We will provide customization for segments and region/country levels. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited Users and Printable PDF) |









