


Market Overview
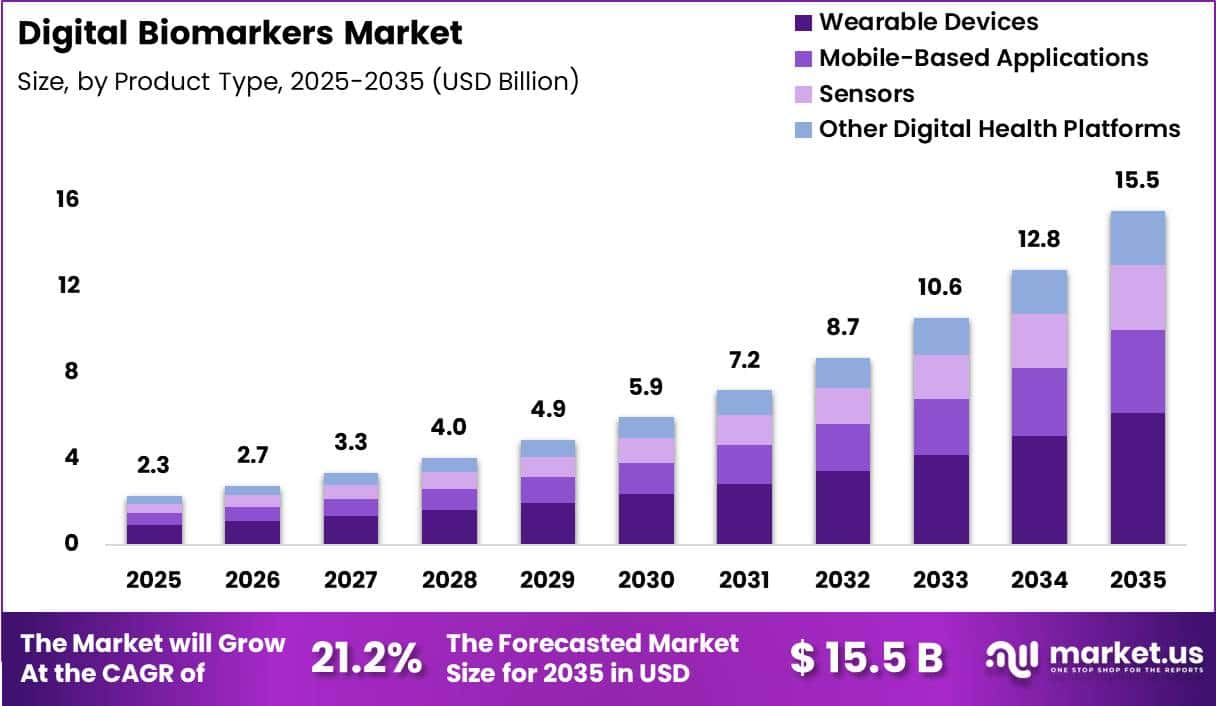
Global Digital Biomarkers Market size is expected to be worth around US$ 15.53 Billion by 2035 from US$ 2.27 Billion in 2025, growing at a CAGR of 21.22% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 45.50% share with a revenue of US$ 1.03 Billion.
Digital biomarkers are becoming a critical part of modern healthcare as clinicians and researchers increasingly rely on continuous, real-world patient data collected through wearable devices, smartphones, biosensors, and connected medical technologies.
Unlike traditional biomarkers that are measured during hospital visits, digital biomarkers enable continuous monitoring of physiological and behavioral changes, supporting earlier disease detection, personalized treatment decisions, and improved long-term patient management.
The U.S. Food and Drug Administration (FDA) recognizes Digital Health Technologies (DHTs) as an important component of healthcare innovation, highlighting their ability to capture health data remotely and support clinical decision-making, medical product development, and decentralized clinical trials.
The growing burden of chronic diseases is strengthening demand for digital biomarkers worldwide. According to the World Health Organization (WHO), noncommunicable diseases account for approximately 43 million deaths annually, representing about 75% of all non-pandemic deaths globally, creating a strong need for continuous patient monitoring outside conventional healthcare settings.
At the same time, the National Institutes of Health (NIH) reports that next-generation wearable sensors can generate more than 250,000 physiological measurements per person each day, demonstrating the enormous volume of real-time health data that can be transformed into clinically meaningful digital biomarkers.
Furthermore, the FDA continues to expand support for sensor-based digital health technologies, including wearable devices such as smartwatches, smart rings, patches, and continuous monitoring systems, while the NIH has launched dedicated funding initiatives to accelerate the development and validation of digital health technology-derived biomarkers for remote monitoring and clinical endpoint assessment.
These initiatives are expected to improve disease management, enhance patient engagement, and accelerate precision medicine across neurology, cardiology, oncology, metabolic disorders, and mental health applications.
Key Takeaways
- Market Size : Digital Biomarkers Market size is expected to be worth around US$ 15.53 Billion by 2035 from US$ 2.27 Billion in 2025.
- Market Share : The market is growing at a CAGR of 21.22% during the forecast period from 2026 to 2035.
- Product Type Analysis : In 2025, Wearable Devices dominated the Digital Biomarkers market, accounting for 39.60% of the global market share.
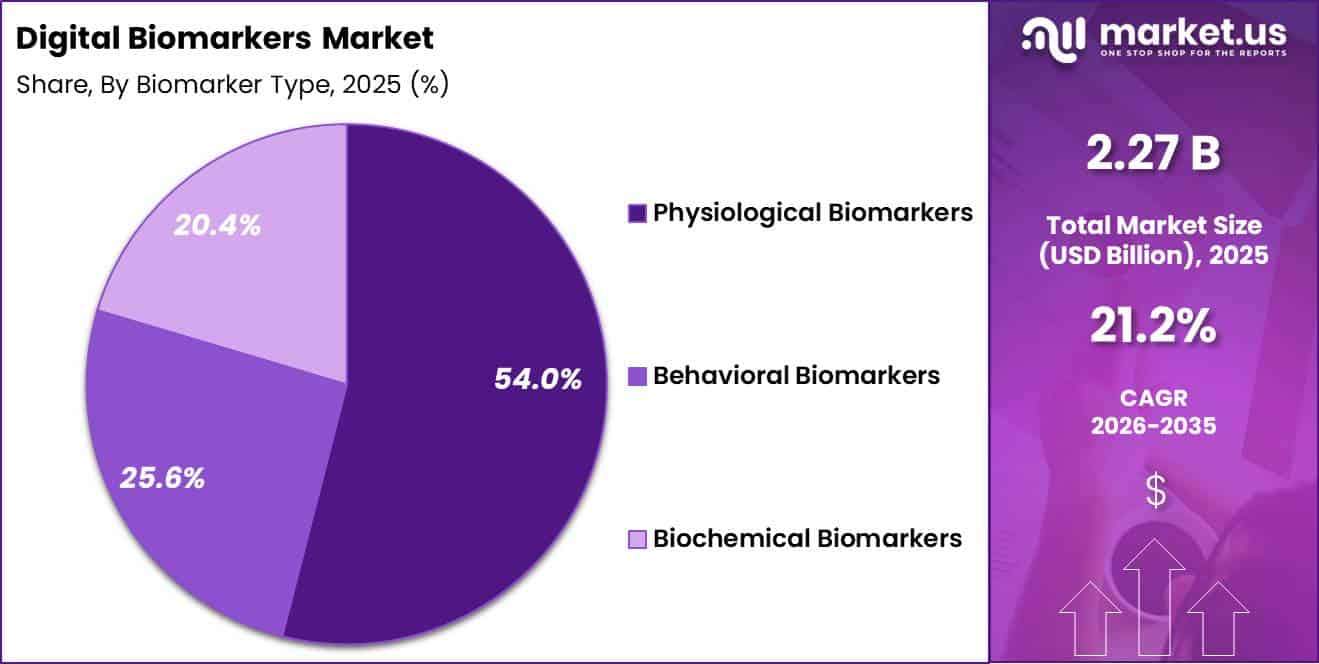
- Biomarker Type Analysis : In 2025, Physiological Biomarkers held the largest share of the Digital Biomarkers market, accounting for 54.00% of global revenue.
- Clinical Practice Analysis : In 2025, Diagnostic Digital Biomarkers accounted for the largest share of the Digital Biomarkers market, representing 52.30% of total revenue
- End User Analysis : In 2025, Pharmaceutical & Biotech Companies dominated the Digital Biomarkers market with 46.80% of the global market share.
- Therapeutic Area Analysis : In 2025, Cardiovascular & Metabolic Disorders held the largest share of the Digital Biomarkers market, accounting for 31.40% of global revenue.
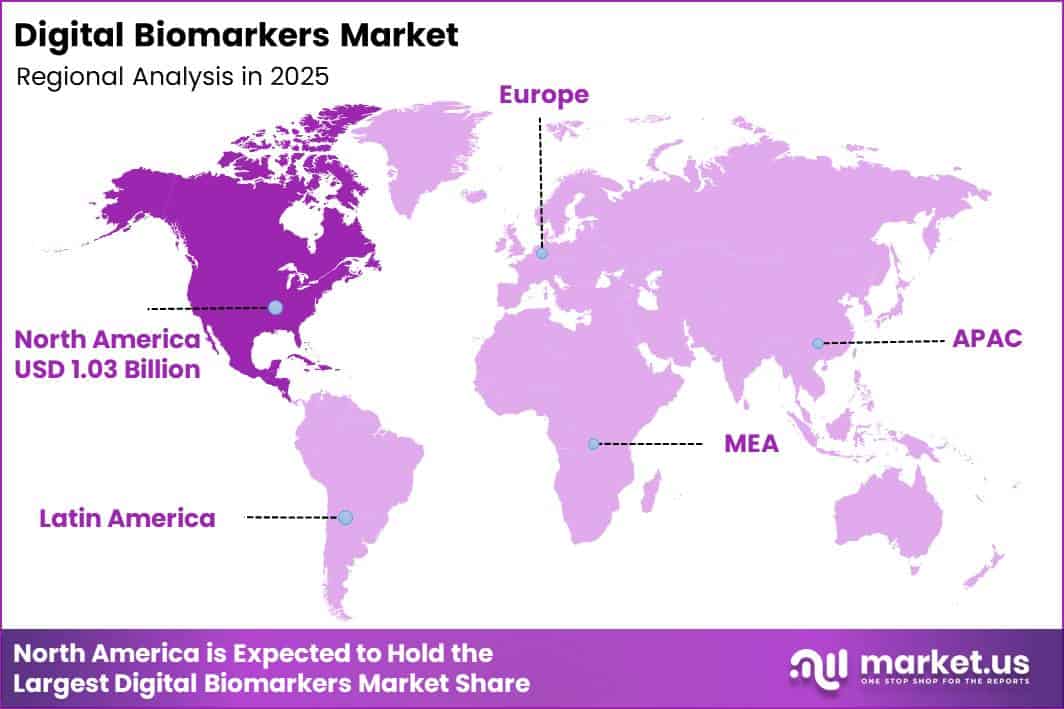
- Regional Analysis : In 2025, North America led the market, achieving over 45.50% share with a revenue of US$ 1.03 Billion.
Product Type Analysis
In 2025, Wearable Devices dominated the Digital Biomarkers market, accounting for 39.60% of the global market share. Their leadership is driven by the increasing use of smartwatches, fitness bands, smart rings, wearable ECG monitors, and continuous glucose monitoring systems that collect real-time physiological and behavioral data.
These devices enable continuous monitoring of heart rate, sleep, physical activity, oxygen saturation, and other health parameters, making them valuable tools for disease detection, remote patient monitoring, and decentralized clinical trials.
The U.S. FDA has recognized wearable sensor-based digital health technologies as an important component of modern healthcare, with an expanding list of authorized wearable medical devices for home-based monitoring.
Mobile-Based Applications represent another important segment, as smartphone applications capture health information through embedded sensors, patient-reported outcomes, and digital assessments. Their ease of use and widespread smartphone adoption support large-scale health data collection.
Sensors continue to gain importance through advanced biosensors capable of monitoring physiological signals with greater accuracy across clinical and consumer settings.
Meanwhile, Other Digital Health Platforms, including cloud-based analytics, artificial intelligence platforms, connected medical devices, and telehealth ecosystems, play a vital role by integrating data from multiple digital sources.
Together, these technologies improve clinical decision-making, enable personalized medicine, and accelerate the development of validated digital biomarkers across therapeutic areas.
Biomarker Type Analysis
In 2025, Physiological Biomarkers held the largest share of the Digital Biomarkers market, accounting for 54.00% of global revenue. The segment dominates because physiological measurements such as heart rate, respiratory rate, blood pressure, electrocardiogram (ECG), blood oxygen saturation, glucose levels, body temperature, and sleep patterns can be continuously collected through wearable devices and connected sensors.
These objective measurements support early disease detection, treatment monitoring, and chronic disease management while improving the accuracy of clinical research. The FDA recognizes physiological characteristics as an important category of biomarkers and continues supporting digital health technologies capable of collecting such information remotely.
Behavioral Biomarkers are experiencing rapid growth as smartphones and wearable devices monitor activity levels, mobility, gait, speech, cognitive performance, sleep behavior, and digital interactions that can indicate neurological or mental health conditions.
These biomarkers are increasingly used in psychiatric and neurodegenerative disease research. Biochemical Biomarkers are also expanding through connected biosensors and continuous monitoring technologies, particularly in diabetes management and metabolic disorders.
The integration of physiological, behavioral, and biochemical information through artificial intelligence enables more comprehensive patient assessment and personalized healthcare. Growing adoption of multimodal digital health platforms is expected to strengthen all biomarker categories while supporting remote monitoring, decentralized clinical trials, and precision medicine initiatives.
Clinical Practice Analysis
In 2025, Diagnostic Digital Biomarkers accounted for the largest share of the Digital Biomarkers market, representing 52.30% of total revenue. Their dominance is supported by the increasing use of wearable devices, smartphone applications, and connected sensors that help identify disease-related physiological and behavioral changes before symptoms become severe.
These digital biomarkers assist clinicians in detecting cardiovascular disorders, neurological diseases, metabolic conditions, and respiratory illnesses while supporting faster and more objective clinical assessments. Regulatory agencies, including the FDA, continue encouraging the use of digital health technologies for diagnosis and medical product development.
Monitoring Biomarkers form another significant segment by enabling continuous tracking of patient health during treatment. They support long-term disease management, medication adherence, and early detection of clinical deterioration through remote monitoring.
Predictive Biomarkers are gaining adoption because artificial intelligence can analyze longitudinal digital health data to identify individuals at higher risk of disease progression or adverse events before clinical symptoms appear.
Prognostic Biomarkers also continue expanding as healthcare providers increasingly use digital data to estimate disease outcomes, recovery patterns, and treatment effectiveness. Together, these clinical practice segments are improving personalized medicine, decentralized clinical research, and value-based healthcare by providing continuous, objective, and real-world patient information beyond traditional hospital settings.
End User Analysis
In 2025, Pharmaceutical & Biotech Companies dominated the Digital Biomarkers market with 46.80% of the global market share. The segment leads because pharmaceutical companies increasingly incorporate digital biomarkers into clinical trials, drug development, patient stratification, and treatment monitoring.
Wearable devices, mobile applications, and connected sensors provide continuous real-world evidence that improves endpoint measurement and supports decentralized clinical trials. Regulatory guidance from the FDA continues to encourage the use of digital health technologies for remote data acquisition during clinical investigations, accelerating industry adoption.
Healthcare Providers represent another major end-user group, utilizing digital biomarkers for remote patient monitoring, chronic disease management, and personalized treatment planning. Hospitals and clinics increasingly integrate wearable data into electronic health records to improve patient outcomes and reduce unnecessary hospital visits.
Payers and Insurers are gradually adopting digital biomarkers to support preventive healthcare, population health management, and value-based reimbursement programs through continuous patient monitoring. Research Organizations also play a vital role by validating digital biomarkers and conducting clinical studies that establish their reliability across therapeutic areas.
Increasing collaboration among healthcare providers, pharmaceutical companies, technology firms, and academic institutions continues to expand the adoption of digital biomarkers worldwide while strengthening evidence-based healthcare and precision medicine initiatives.
Therapeutic Area Analysis
In 2025, Cardiovascular & Metabolic Disorders held the largest share of the Digital Biomarkers market, accounting for 31.40% of global revenue. The segment’s leadership is driven by the widespread availability of wearable devices capable of continuously monitoring heart rate, ECG, blood pressure, physical activity, glucose levels, and other physiological indicators.
These technologies support early detection of cardiovascular abnormalities, diabetes management, and long-term monitoring of chronic conditions while reducing dependence on frequent hospital visits. The FDA continues to recognize wearable sensor-based technologies as important tools for remote patient monitoring and chronic disease management.
Neurological Disorders represent another rapidly expanding segment, where digital biomarkers help monitor cognitive decline, Parkinson’s disease, Alzheimer’s disease, epilepsy, and multiple sclerosis using movement, speech, and behavioral data.
Respiratory Disorders increasingly utilize connected monitoring systems to assess breathing patterns and oxygen saturation. Psychiatric Disorders benefit from digital biomarkers derived from activity, sleep, voice, and smartphone usage to evaluate depression, anxiety, and other mental health conditions.
Sleep & Movement Disorders rely heavily on wearable sensors that objectively measure sleep quality, circadian rhythms, and mobility, while Musculoskeletal Disorders use digital monitoring to evaluate rehabilitation progress, physical function, and treatment outcomes.
The growing integration of artificial intelligence with digital health technologies is expected to expand biomarker applications across all major therapeutic areas.
Market Segmentations
By Product Type
- Wearable Devices
- Mobile-Based Applications
- Sensors
- Other Digital Health Platforms
By Biomarker Type
- Physiological Biomarkers
- Behavioral Biomarkers
- Biochemical Biomarkers
By Clinical Practice
- Diagnostic Digital Biomarkers
- Monitoring Biomarkers
- Predictive Biomarkers
- Prognostic Biomarkers
By End User
- Pharmaceutical & Biotech Companies
- Healthcare Providers
- Payers / Insurers
- Research Organizations
By Therapeutic Area
- Cardiovascular & Metabolic Disorders
- Neurological Disorders
- Respiratory Disorders
- Psychiatric Disorders
- Sleep & Movement Disorders
- Musculoskeletal Disorders
Drivers
FDA and NIH validation push for trial-grade digital endpoints
The FDA’s Digital Health Center of Excellence and the April 2026 launch of the TEMPO pilot show a more active regulatory posture toward scaling digital health devices while maintaining evidence and safety requirements, which is important because digital biomarkers gain far higher commercial value once they move from wellness tracking to regulated clinical decision support or trial-grade endpoint use.
In parallel, NIH’s 2024–2026 funding program specifically targeted digital health technology-derived biomarkers and outcome assessments for remote monitoring, requiring proposals to demonstrate use across three or more diseases or conditions and to define how these tools can serve as primary or secondary endpoints in interventional trials.
That standardization push improves sponsor confidence, lowers validation redundancy, and supports premium pricing for vendors that can document reproducibility, context-of-use specificity, and endpoint sensitivity; Nature’s 2026 perspective also cites analysis showing Phase III trials using digital biomarkers were on average 4–5 months shorter, creating a direct economic incentive for adoption in CRO and pharma workflows
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Reimbursement expansion for remote physiologic data workflows | +2.4% | North America core, EU follow-on, APAC private-care spillover | Short term (≤ 2 years) |
| FDA and NIH validation push for trial-grade digital endpoints | +2.1% | North America core, EU research hubs, Japan/Korea innovation clusters | Medium term (2-4 years) |
| Diabetes and cardiometabolic burden raising continuous monitoring demand | +1.9% | North America core, EU, China, India, GCC urban systems | Short term (≤ 2 years) |
| Pharma decentralization and site-light trial design adoption | +1.7% | U.S., Western Europe, Singapore, Australia | Medium term (2-4 years) |
| AI analytics shifting biomarkers from raw signals to actionable risk stratification | +1.5% | U.S., EU, China selective, APAC tertiary-care corridors | Medium term (2-4 years) |
| Cybersecurity and medical-device compliance hardening vendor selection | +1.0% | U.S. core, EU regulated markets, Japan | Long term (≥ 4 years) |
Challenges
Chronic Disease Prevalence Drives Digital Health Monitoring Growth
The chronic disease and aging profile in 2026 materially raises the ceiling for digital biomarkers growth by structurally expanding the addressable patient pool and intensifying payer pressure for continuous, outcomes-based monitoring.
In the US alone, the CDC estimates roughly 38–40 million people with diabetes or prediabetes under active surveillance, with 4–6 annual lab or clinic touchpoints per patient, translating into more than 160–240 million discrete data events per year that can be partially digitized and transformed into remote biomarkers for glucose, activity, sleep and cardiovascular risk.
Across cardiovascular disease, NIH and WHO data show more than 500 million people worldwide living with heart-related conditions, and hospital readmission rates above 15–20% in high‑income health systems for heart failure, driving demand for continuous remote markers such as step count, heart rate variability and arrhythmia episodes captured via wearables and patches.
With more than 10–15% of populations in North America, Europe and Japan already above age 65, CMS and other payers continue shifting toward value-based models that reward reductions in 30‑day readmissions and emergency visits, creating direct economic incentives often $3,000–$10,000 avoided cost per prevented hospitalization for adopting validated digital biomarkers in chronic care bundles.
Structurally, this driver pushes the baseline CAGR upward by around 2.3 % points by increasing longitudinal data volumes, supporting risk‑stratification algorithms, and making digital biomarkers core to risk-based contracts rather than optional add‑ons, while also steering business models toward subscription monitoring and per‑member‑per‑month analytics rather than one‑off device sales.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Chronic disease burden & aging | +2.3% | North America, EU, East Asia | Long term (≥ 4 years) |
| Wearables, smartphones & IoT penetration | +2.0% | Global urban corridors | Medium term (2-4 years) |
| Regulatory engagement on digital health | +1.7% | US, EU, select Asia-Pacific | Medium term (2-4 years) |
| Remote monitoring & virtual care scaling | +2.1% | North America core, EU, advanced APAC | Long term (≥ 4 years) |
| Pharma demand for trial efficiency | +1.9% | US, EU, Japan, Korea | Medium term (2-4 years) |
| AI / ML analytics maturation | +2.2% | Global innovation hubs | Long term (≥ 4 years) |
Restraints
Cross-Border Data Restrictions Increase Digital Biomarkers Compliance Costs
Data privacy, consent, and cross‑border transfer constraints create structural friction for digital biomarker business models, particularly those reliant on multi‑country real‑world data streams and cloud‑based analytics, and are estimated to suppress growth by roughly 1.8 % points relative to an unconstrained data‑sharing scenario.
Regulations such as GDPR in the EU, state‑level privacy laws in the US, and emerging data‑localization rules in APAC demand granular consent management, strict purpose limitation, and often in‑region data storage, forcing vendors to build parallel infrastructures and legal workflows that can add 10–15% to operating expenditure per market and lengthen deployment cycles by 6–12 months.
Continuous sensor‑based capture of location, behaviour, and physiological signals, often at minute‑level frequency, amplifies cybersecurity liabilities and breach impact, driving up insurance premiums and necessitating investments in encryption, zero‑trust architectures, and audit trails that can push per‑patient data management costs from low single‑digit dollars to the mid‑teens annually in highly regulated regions.
Strategically, these frictions limit the ability to pool cross‑regional datasets at scale, weakening algorithm generalizability, forcing developers to maintain 3–5 separate model variants for different regions, and slowing the creation of robust longitudinal evidence required for payer negotiations, thereby compressing margins and delaying the realization of global, platform‑level economies of scale beyond 2030.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fragmented regulatory validation pathways | -2.0% | North America, EU, Japan, UK | Medium term (2–4 years) |
| Data privacy, consent, and cross-border transfer frictions | -1.8% | EU, North America, APAC data hubs | Long term (≥ 4 years) |
| Limited clinical validation and evidentiary standards | -1.5% | Global | Medium term (2–4 years) |
| Interoperability and EHR integration bottlenecks | -1.2% | North America, EU, select APAC | Long term (≥ 4 years) |
| Reimbursement, HTA, and payer adoption lag | -1.7% | North America, EU, advanced LATAM | Long term (≥ 4 years) |
| Sensor, device, and cybersecurity compliance overheads | -0.8% | Global | Short–medium term (≤ 4 years) |
Opportunity
Digital Endpoint Adoption Unlocks High-Growth Clinical Trial Opportunities
This opportunity centers on building validated digital biomarkers as primary and secondary endpoints for cardiometabolic drug and device trials, moving beyond today’s limited pilots into systematic adoption across phase II–IV programs.
Regulators such as the FDA and EMA have issued frameworks for digital health technologies and endpoint qualification, but only a small fraction of cardiometabolic trials currently deploy fully qualified digital biomarkers, implying that less than 10–15% of the potential trial TAM is being monetized via endpoint licensing, analytics subscriptions, and data services.
If vendors capture even 25–30% of new cardiometabolic trials globally and monetize endpoints at USD 0.5–1.0 million per program, this could unlock USD 1.5–2.5 billion incremental annual revenue by 2035 on top of baseline remote monitoring and device-linked sales.
Margins are attractive: software and data layers often deliver gross margins above 70%, compared with 40–50% for hardware-heavy offerings, driving a 5–10 % point margin uplift at portfolio level.
Because the baseline forecast mainly assumes use of digital measures as exploratory endpoints or post-hoc analyses, a shift toward fit‑for‑purpose, qualified cardiometabolic digital endpoints leveraging continuous data from wearables and sensors for hypertension, heart failure, and diabetes would push overall market CAGR upward by around 2.0 % points between 2026 and 2035 through higher per‑trial ASPs, stickier sponsor relationships, and faster regulatory acceptance cycles.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Integrated cardiometabolic digital endpoints in clinical trials | +2.0% | North America, EU, Japan | Medium term (2–4 years) |
| Payer-backed chronic disease remote monitoring bundles | +1.5% | North America core, EU, select APAC | Short–Medium term (≤ 3 years) |
| Consumer-centric mental health & cognition biomarkers | +1.3% | North America, EU, urban APAC | Medium–Long term (3–6 years) |
| Cross-condition multimodal biomarker platforms | +1.0% | Global biopharma hubs (NA, EU, China) | Medium term (2–4 years) |
| Real-world evidence (RWE) data commercialization ecosystems | +1.0% | North America, EU | Medium–Long term (3–6 years) |
| Low-cost, regulatory-grade biomarkers for emerging markets | +0.8% | APAC emerging, LATAM, Middle East, Africa | Long term (≥ 4 years) |
Regional Analysis
In 2025, North America led the global digital biomarkers market, accounting for over 45.50% of the total market and generating US$ 1.03 billion in revenue. The region’s dominance is supported by a mature digital healthcare ecosystem, high adoption of wearable medical devices, strong clinical research capabilities, and favorable regulatory frameworks.
The U.S. Food and Drug Administration (FDA) continues to promote the integration of Digital Health Technologies (DHTs) into clinical trials and healthcare delivery, supporting the use of remote monitoring tools, sensor-based devices, and digital endpoints for medical product development and patient care. Europe represents the second-largest regional market, driven by government-backed digital health strategies and increasing investment in connected healthcare infrastructure.
The World Health Organization (WHO) Europe is supporting countries through its Regional Digital Health Action Plan 2023–2030, which encourages the adoption of interoperable health systems, artificial intelligence, telemedicine, and digital monitoring technologies. These initiatives are accelerating the use of digital biomarkers in chronic disease management, personalized medicine, and population health programs across the region.
The Asia-Pacific region is expected to witness the fastest growth during the forecast period due to expanding healthcare digitization, rising smartphone and wearable device penetration, and increasing investments in digital healthcare infrastructure.
Countries such as China, Japan, South Korea, India, and Singapore are strengthening digital health programs to improve healthcare accessibility and remote patient monitoring. The World Health Organization continues to support digital transformation across the region through initiatives focused on health data interoperability, digital innovation, and equitable access to digital healthcare services.
Meanwhile, Latin America and the Middle East & Africa are gradually expanding their digital health capabilities through government modernization initiatives, improved internet connectivity, and growing adoption of telehealth services.
Although these regions currently account for a smaller market share, increasing investments in digital health infrastructure, mobile health applications, and remote monitoring solutions are expected to create new opportunities for digital biomarker adoption in the coming years.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The Digital Biomarkers market is characterized by collaborations between technology companies, pharmaceutical manufacturers, and healthcare organizations that are developing digital tools for continuous health monitoring and clinical research.
Leading companies are investing in wearable technologies, digital health platforms, artificial intelligence, and remote patient monitoring to generate clinically meaningful digital biomarkers that improve disease detection, treatment monitoring, and decentralized clinical trials.
Regulatory support from the U.S. Food and Drug Administration (FDA) for Digital Health Technologies has further encouraged innovation and adoption across the healthcare ecosystem.
Apple Inc. continues to expand digital health capabilities through Apple Health and ResearchKit, enabling researchers to collect real-world health data from iPhone and Apple Watch users for medical studies. Alphabet’s Verily Life Sciences offers its Numetric Digital Biomarkers platform, combining wearable devices, machine learning, and cloud analytics to develop validated digital measures for clinical research.
Koninklijke Philips N.V. strengthens its position with connected patient monitoring and remote care technologies that support continuous health data collection. Biogen Inc. is advancing digital biomarkers in neurological research, particularly for neurodegenerative diseases.
Roche Holding AG integrates digital solutions into diagnostics and personalized healthcare through Roche Digital to improve patient management. AstraZeneca plc incorporates digital technologies into clinical development and remote patient monitoring to enhance research efficiency and treatment outcomes.
Garmin Ltd. contributes through advanced wearable devices capable of continuously tracking physiological metrics that support digital biomarker development and real-world health monitoring.
Top Key Players
- Apple Inc. (Apple Health / Research Kit)
- Alphabet / Google (Verily Life Sciences)
- Koninklijke Philips N.V.
- Biogen Inc.
- Roche Holding AG (Roche Digital)
- AstraZeneca plc
- Garmin Ltd.
- Withings S.A.
- Evidation Health Inc.
- Seer Bio
- Mindstrong Health
- Elekta AB (Analytic Oncology)
Recent Developments
- In May 2026, Roche Holding AG entered into a definitive agreement to acquire PathAI for US$750 million upfront, with up to US$300 million in milestone payments, strengthening its AI-powered digital pathology and biomarker discovery capabilities for diagnostics and pharmaceutical research.
- In March 2025, AstraZeneca plc expanded its strategic collaboration with Tempus AI to use multimodal clinical data and artificial intelligence for biomarker discovery, patient stratification, and precision oncology research, strengthening AI-enabled clinical development.
- In January 2025, Withings S.A. unveiled Omnia, an AI-powered connected health platform that integrates data from smart scales, wearables, blood pressure monitors, and sleep devices to deliver continuous health insights and support the future development of digital biomarkers for preventive care.
- In January 2025, Verily Life Sciences (Alphabet Inc.) expanded its Lightpath platform by integrating AI-driven evidence generation and real-world data capabilities to improve decentralized clinical trials and digital biomarker development for life sciences partners.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 2.27 Billion |
| Forecast Revenue (2035) | US$ 15.53 Billion |
| CAGR (2026-2035) | 21.22% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Wearable Devices, Mobile-Based Applications, Sensors, Other Digital Health Platforms), By Biomarker Type (Physiological Biomarkers, Behavioral Biomarkers, Biochemical Biomarkers), By Clinical Practice (Diagnostic Digital Biomarkers, Monitoring Biomarkers, Predictive Biomarkers, Prognostic Biomarkers), By End User (Pharmaceutical & Biotech Companies, Healthcare Providers, Payers / Insurers, Research Organizations), By Therapeutic Area (Cardiovascular & Metabolic Disorders, Neurological Disorders, Respiratory Disorders, Psychiatric Disorders, Sleep & Movement Disorders, Musculoskeletal Disorders) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Apple Inc. (Apple Health / Research Kit), Alphabet / Google (Verily Life Sciences), Koninklijke Philips N.V., Biogen Inc., Roche Holding AG (Roche Digital), AstraZeneca plc, Garmin Ltd., Withings S.A., Evidation Health Inc., Seer Bio, Mindstrong Health, Elekta AB (Analytic Oncology) |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








