


Market Overview
Global Dental Care Drugs Market size is expected to be worth around US$ 27.5 Billion by 2035 from US$ 13.5 Billion in 2025, growing at a CAGR of 7.4% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 37.50% share with a revenue of US$ 5.06 Billion.
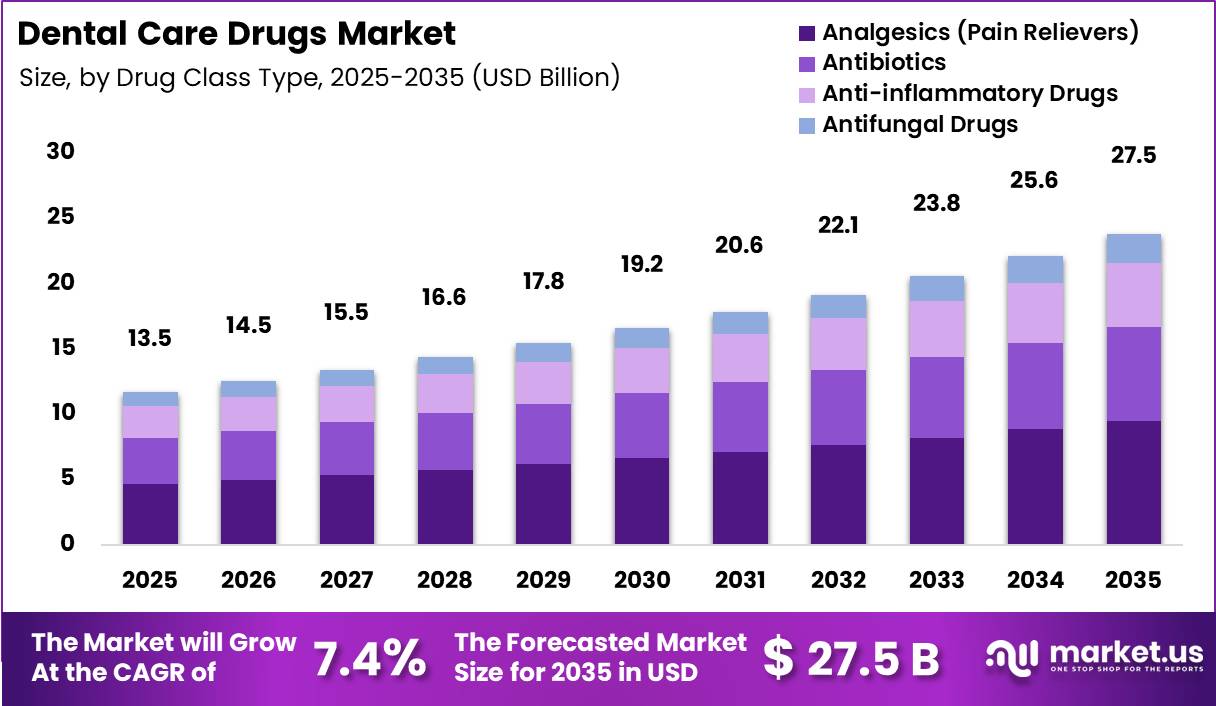
The Dental Care Drugs Market is a vital segment of the global healthcare industry, supporting the prevention and treatment of oral diseases such as dental caries, periodontal disease, oral infections, and post-procedural inflammation.
According to the World Health Organization, oral diseases affect nearly 3.5 billion people worldwide, with untreated dental caries alone impacting around 2.5 billion individuals, highlighting sustained pharmaceutical demand for analgesics, antibiotics, fluoride-based agents, antiseptics, and anti-inflammatory drugs used in dental care .
Rising prevalence of oral conditions is a key market driver. Severe periodontal disease affects approximately 1 billion people globally, while oral cancers contribute to over 380,000 new cases annually, increasing the need for adjunctive drug therapies in dental oncology and post-surgical care.
Governments and public health systems are strengthening oral healthcare access through preventive programs, early screening initiatives, and integration of dental services into primary healthcare frameworks, further supporting demand for essential dental medications.
In India and other emerging economies, oral diseases account for a significant healthcare burden due to high sugar consumption, tobacco use, and limited preventive care access. This has led to increased utilization of affordable generic dental drugs in both public and private healthcare systems. Additionally, fluoride-based formulations and antimicrobial mouth rinses are widely used in community oral health programs.
The market is also influenced by growing awareness of preventive dentistry, rising dental clinic visits, and expanding insurance coverage for oral treatments. However, challenges such as high out-of-pocket expenditure and uneven access to dental care persist, especially in rural regions.
Overall, the Dental Care Drugs Market continues to expand steadily, driven by global disease burden and increasing focus on preventive oral healthcare.
Key Takeaways
- Market Size: Global Dental Care Drugs Market size is expected to be worth around US$ 27.5 Billion by 2035 from US$ 13.5 Billion in 2025.
- Market Share: The market is growing at a CAGR of 7.4% during the forecast period from 2026 to 2035.
- Drug Class Analysis: Analgesics (Pain Relievers) dominate the segment with a 52.8% market share in 2025.
- Application Analysis: Dental Pain Management dominates the segment with a 41.00% market share
- Dosage Form Analysis: Tablets & Capsules lead the segment with a 46.00% market share in 2025
- Distribution Channel Analysis: Hospital Pharmacies dominate the segment with a 38.00% market share
- Regional Analysis: In 2025, North America led the market, achieving over 37.50% share with a revenue of US$ 5.06 Billion.
Drug Class Analysis
The Drug Class segmentation of the Dental Care Drugs Market is primarily driven by strong demand for effective pain relief and infection control in oral healthcare procedures. Analgesics (Pain Relievers) dominate the segment with a 52.8% market share in 2025, reflecting their widespread use in managing acute dental pain, post-procedural discomfort, and chronic oral conditions.
Antibiotics account for 26.00% share, playing a critical role in preventing and treating bacterial infections associated with periodontal disease, tooth extractions, and oral surgeries. Anti-inflammatory drugs hold 18.00% share, supported by their importance in reducing swelling, inflammation, and post-treatment complications in dental procedures.
Local anesthetics represent 13.50% share, widely used during invasive dental procedures to ensure patient comfort and enable painless treatment delivery. Antifungal drugs, with an 8.00% share, are utilized for managing oral fungal infections such as candidiasis, particularly in immunocompromised patients.
Overall, the segment reflects a balanced demand across symptom management, infection control, and procedural support, with analgesics leading due to high prevalence of dental pain cases globally and increasing access to dental care services.
Application Analysis
The Application segmentation of the Dental Care Drugs Market is strongly influenced by the rising burden of oral diseases and increasing dental procedure volumes worldwide. Dental Pain Management dominates the segment with a 41.00% market share in 2025, driven by the high incidence of tooth decay, post-treatment pain, and sensitivity-related conditions.
Periodontal Disease Treatment accounts for 27.00% share, supported by the growing prevalence of gum diseases linked to poor oral hygiene, smoking, and diabetes. Post-Surgical Care represents 18.00% share, reflecting the need for medications that support healing, reduce inflammation, and prevent infection following dental surgeries such as extractions and implant placements.
Oral Infections contribute 14.00% share, covering bacterial, viral, and fungal infections affecting the oral cavity, including abscesses and stomatitis. The increasing adoption of advanced dental procedures and rising awareness regarding oral health are further driving pharmaceutical demand across these applications.
Overall, pain management remains the largest application area due to immediate treatment needs, while periodontal and post-surgical segments continue to expand with growing preventive and restorative dental care adoption globally.
Dosage Form Analysis
The Dosage Form segmentation in the Dental Care Drugs Market is primarily dominated by oral solid formulations due to their convenience, affordability, and high patient compliance.
Tablets & Capsules lead the segment with a 46.00% market share in 2025, widely used for analgesics, antibiotics, and anti-inflammatory drugs prescribed for dental pain and infection management.
Their popularity is attributed to ease of administration, precise dosing, and longer shelf stability compared to liquid forms. Liquid formulations, including syrups and suspensions, are also commonly used, especially for pediatric and geriatric patients who may have difficulty swallowing solid dosage forms.
Topical formulations such as gels, mouth rinses, and sprays are increasingly utilized for localized treatment of oral infections, gum inflammation, and post-procedural care, offering rapid relief at the site of action.
Injectable forms are primarily used in clinical or hospital settings for severe infections or surgical dental procedures requiring immediate therapeutic effects.
Overall, the dominance of tablets and capsules reflects strong outpatient prescription trends, while topical and liquid forms continue to grow with expanding home-based oral care and pediatric dental treatment needs.
Distribution Channel Analysis
The Distribution Channel segmentation of the Dental Care Drugs Market is led by hospital-based dispensing systems due to the high volume of dental procedures performed in clinical environments.
Hospital Pharmacies dominate the segment with a 38.00% market share in 2025, as they directly supply medications for post-surgical care, infection control, and pain management following dental treatments.
Retail pharmacies also represent a significant channel, benefiting from easy accessibility, walk-in prescriptions, and rising self-medication trends for mild dental pain and oral care products.
Dental clinics contribute notably to distribution, as many practitioners dispense medications directly after procedures, ensuring immediate patient compliance and treatment continuity.
Online pharmacies are emerging as a growing channel, driven by increasing digital healthcare adoption, home delivery convenience, and competitive pricing, particularly for over-the-counter dental care drugs.
Overall, hospital pharmacies remain the dominant channel due to their integration with treatment procedures, while retail and online channels are expanding rapidly with growing consumer awareness and accessibility improvements in oral healthcare services across urban and semi-urban regions.
Market Segmentations
Drug Class Analgesics (Pain Relievers)
- Antibiotics
- Anti-inflammatory Drugs
- Antifungal Drugs
- Local Anesthetics
Application
- Dental Pain Management
- Periodontal Disease Treatment
- Post-Surgical Care
- Oral Infections
Dosage Form Tablets & Capsules
- Oral Gels & Ointments
- Mouth Rinses
- Injectables
Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
End User
- Hospitals & Dental Clinics
- Homecare Settings
- Academic & Research Institutes
Opportunity
Preventive school and fluoride programs represent a significant opportunity for oral healthcare expansion as governments increasingly prioritize preventive care over treatment-focused approaches.
The WHO Oral Health Action Plan 2030 sets targets for 50% of countries to implement national fluoride delivery programs, 50% to adopt measures reducing free-sugar consumption, and 80% to provide oral-health services through primary healthcare systems.
These goals create opportunities for large-scale deployment of fluoride-based and anti-caries preparations through schools, maternal-child health services, and community health programs.
Many countries have not yet fully implemented these initiatives, leaving substantial room for future expansion. Public-sector procurement can support recurring distribution of preventive oral-care products with broad population reach.
School-based and community programs are particularly effective for improving access among children and underserved rural populations. The opportunity is especially relevant across India, Southeast Asia, Africa, Latin America, and the Middle East, where preventive oral-health infrastructure continues to develop.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Primary-care oral drug inclusion | +2.4% | APAC emerging, Africa, LATAM, public EU systems | Medium term (2-4 years) |
| Opioid-sparing dental pain platforms | +2.1% | North America core, EU, ANZ, advanced APAC | Short term (≤ 2 years) |
| Geriatric xerostomia therapeutics | +1.8% | Japan, EU, North America, Korea | Medium term (2-4 years) |
| Adjunctive periodontal drug kits | +1.7% | North America, EU, urban APAC, GCC | Short term (≤ 2 years) |
| Oncology and mucositis crossover | +1.5% | North America, EU, Japan, tertiary-care APAC | Long term (≥ 4 years) |
| Preventive school and fluoride programs | +1.9% | India, SEA, Africa, LATAM, Middle East | Long term (≥ 4 years) |
Drivers
Primary-care oral service expansion is becoming an important driver for the dental pharmaceuticals market by increasing access to oral healthcare beyond traditional dental clinics.
The WHO Oral Health Action Plan 2030 targets 80% of countries providing accessible oral-health services through primary healthcare facilities and expanding access to essential oral-health services.
This shift integrates oral healthcare into routine medical care, allowing earlier identification and management of dental conditions. Primary-care settings can support preventive treatments, pain management, fluoride-based interventions, and referral-linked prescribing. The approach is particularly important in regions where dentist availability remains limited and access to specialized dental care is uneven.
Broader integration into primary healthcare creates additional touchpoints for patient engagement and treatment initiation. It also strengthens institutional procurement and distribution of oral-health products through public-health systems.
As a result, primary-care expansion is expected to improve access to preventive and early-stage oral-health interventions across diverse populations.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| WHO oral-health policy push | +2.5% | APAC, Africa, LATAM, public EU systems | Long term (≥ 4 years) |
| High untreated disease burden | +2.2% | Global, strongest in emerging and aging markets | Short term (≤ 2 years) |
| Essential medicines inclusion | +1.9% | APAC emerging, Africa, LATAM, GCC | Medium term (2-4 years) |
| Non-opioid dental pain shift | +1.8% | North America core, EU, ANZ, advanced APAC | Short term (≤ 2 years) |
| Aging population oral morbidity | +1.6% | Japan, EU, North America, Korea | Long term (≥ 4 years) |
| Primary-care oral service expansion | +1.7% | Public health systems globally | Medium term (2-4 years) |
Challeneges
Public formulary conversion gaps remain a significant challenge for the dental pharmaceuticals market because policy commitments are often implemented more slowly than expected at the healthcare-system level.
The WHO Oral Health Action Plan 2030 targets 50% of countries including dental preparations from the WHO Model Lists of Essential Medicines in national medicine lists, while also aiming for 80% entitlement to essential oral-health services and 80% accessibility of oral-health services through primary-care facilities.
Although these targets provide a clear policy direction, many countries still need to update formularies, revise procurement frameworks, and standardize product specifications.
Healthcare providers also require training on approved dental medicines and reimbursement pathways. These administrative processes can take multiple budget and procurement cycles before translating into routine medicine use.
As a result, manufacturers often face irregular tender schedules, limited demand visibility, and uneven market activation across regions. This can complicate inventory planning and slow the conversion of policy goals into consistent pharmaceutical procurement.
| Challenge | Geographic Relevance | Mitigation Horizon |
|---|---|---|
| Public formulary conversion gap | APAC emerging, Africa, LATAM, public EU systems | Medium term (2-4 years) |
| Oral care access inequality | North America, LATAM, Africa, South Asia | Long term (≥ 4 years) |
| Prevention-to-prescription disconnect | Global public health systems | Medium term (2-4 years) |
| Dental-medical channel fragmentation | North America, EU, urban APAC | Medium term (2-4 years) |
| Post-surgical pain protocol transition | North America core, EU, ANZ | Short term (≤ 2 years) |
| Workforce and task-mix bottlenecks | Global, strongest in underserved regions | Long term (≥ 4 years) |
Restraints
Low-value generic saturation is a significant restraint in the dental pharmaceuticals market because many products belong to mature categories such as antibiotics, antifungals, topical antiseptics, and pain-relief medications with limited differentiation.
The WHO essential dental preparations framework includes standardized formulations such as fluoride toothpaste containing 1,000–1,500 ppm fluoride, fluoride mouthrinse containing 230–900 ppm fluoride, and fluoride varnish containing 22,500 ppm fluoride.
While these standards improve access to oral healthcare, they also increase product interchangeability across manufacturers. As a result, purchasing decisions are often driven by price rather than brand preference or product innovation.
Generic alternatives can be substituted easily, particularly in pharmacy, institutional, and public procurement channels. This creates ongoing pricing pressure and reduces opportunities for premium positioning.
Manufacturers also face weaker incentives for product extensions and differentiation strategies. Consequently, market volume may expand, but profitability remains constrained by commodity-like competition and procurement-led purchasing behavior.
| Restraint | Geographic Relevance | Impact Timeline |
|---|---|---|
| Low-value generic saturation | Global, strongest in mature pharmacy markets | Medium term (2-4 years) |
| Essential-list price compression | APAC emerging, Africa, LATAM, public EU systems | Long term (≥ 4 years) |
| Uneven treatment access | North America, LATAM, Africa, South Asia | Long term (≥ 4 years) |
| Prevention-heavy public spending | Public health systems globally | Medium term (2-4 years) |
| Dental reimbursement fragmentation | North America, EU, private urban APAC | Medium term (2-4 years) |
| Opioid-alternative uptake drag | North America core, EU, ANZ | Short term (≤ 2 years) |
Regional Analysis
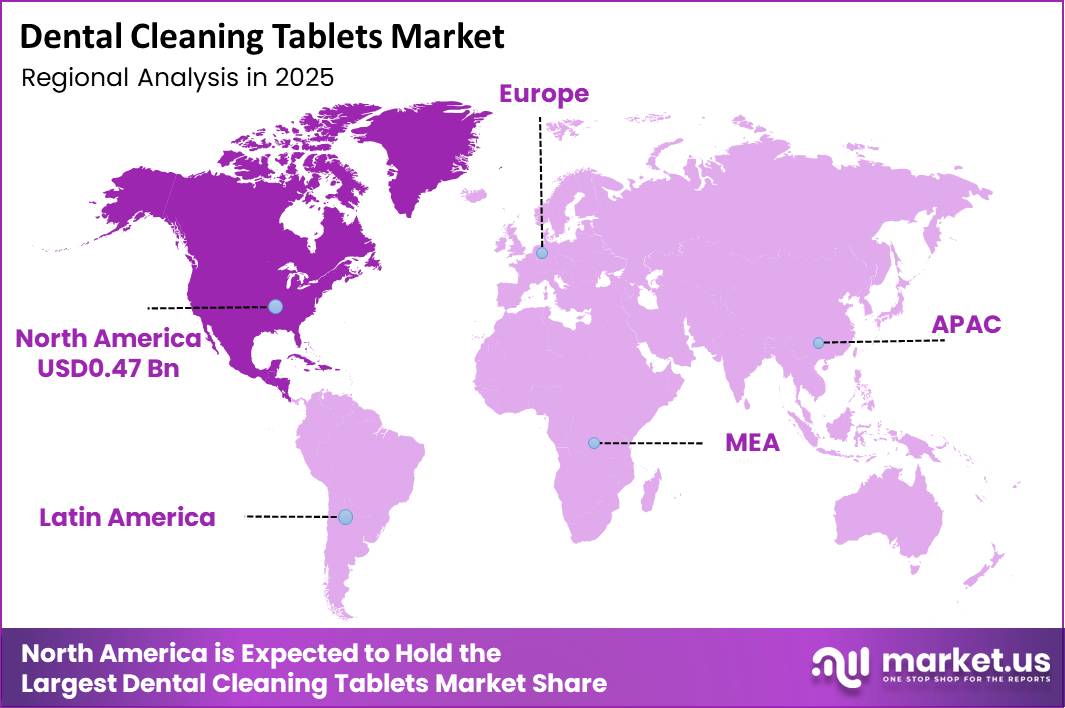
The Dental Care Drugs Market demonstrates clear regional differentiation driven by healthcare infrastructure, disease prevalence, and access to dental services. In 2025, North America led the global market, capturing over 37.50% share and generating approximately US$ 5.06 billion in revenue.
This dominance is supported by high dental care awareness, strong insurance coverage for dental treatments, widespread adoption of prescription-based analgesics and antibiotics, and a high incidence of dental caries and periodontal disorders across the U.S. and Canada.
Europe followed as the second-largest regional market, driven by aging populations, well-established public healthcare systems, and routine dental check-up practices. Countries such as Germany, the UK, and France show consistent demand for anti-inflammatory and antimicrobial dental drugs due to strong preventive care frameworks.
The Asia-Pacific region represents the fastest-growing market, fueled by large patient populations, rising disposable incomes, and expanding access to dental services in China, India, and Southeast Asia. Improving oral health awareness and increasing government-supported dental programs are accelerating drug adoption.
Meanwhile, Latin America and Middle East and Africa account for smaller but steadily growing shares, supported by urbanization, gradual healthcare infrastructure improvements, and rising untreated dental disease burdens. Collectively, these regions offer long-term growth potential as access to essential dental medications continues to expand.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
A leading player in the dental and oral care drugs market typically operates across both prescription and over-the-counter segments, positioning itself as an integrated provider of preventive and therapeutic solutions.
Such a player benefits from a diversified product portfolio that includes analgesics, antibiotics, anti-inflammatory drugs, local anesthetics, and medicated oral care products addressing cavities, periodontal disease, and post-procedural pain.
Strong in-house research and development capabilities enable continuous formulation improvement, clinical validation, and compliance with evolving regulatory standards.
Brand trust and long-term relationships with dental professionals are critical competitive strengths. A key player often supports its portfolio through clinical education programs, evidence-based marketing, and collaborations with dental associations, reinforcing credibility among practitioners.
In the OTC segment, extensive retail and pharmacy distribution networks, combined with direct-to-consumer advertising, help drive high product visibility and repeat purchases. Manufacturing scale and supply chain resilience further enhance competitiveness, ensuring consistent availability across developed and emerging markets.
Many leading players also pursue geographic expansion through localized manufacturing and region-specific product adaptations to meet varying regulatory and pricing requirements. Additionally, digital engagement, including patient education platforms and professional portals, is increasingly used to strengthen market presence.
Overall, a key player’s success is defined by its ability to balance innovation, affordability, regulatory compliance, and strong stakeholder relationships, enabling sustainable growth in a market driven by rising oral disease prevalence and preventive care awareness.
Top Key Players
- Pfizer Inc
- GlaxoSmithKline (GSK)
- Johnson & Johnson
- Sanofi
- Bayer AG
- Sun Pharmaceutical Industries
- Dr. Reddy’s Laboratories
- Cipla Ltd.
- Abbott Laboratories
- Colgate-Palmolive (OTC oral care drugs)
- Haleon
- 3M Health Care
- Prestige Consumer Healthcare
- Perrigo Company plc
- Septodont
Recent Developments
- In November 2025, Pfizer completed its acquisition of Metsera in a deal valued up to $10 billion, strengthening its metabolic disease pipeline.
- In September 2025, Johnson & Johnson received U.S. FDA approval for INLEXZO, a targeted intravesical drug-delivery system demonstrating high localized drug efficacy (82% tumor clearance in trials), reflecting advancement in controlled drug delivery technologies applicable to localized therapeutic areas including oral cavity drug delivery research.”
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 13.5 Bn |
| Forecast Revenue (2035) | US$ 27.5 Bn |
| CAGR (2026-2035) | 7.4% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Drug Class Analgesics (Pain Relievers)(Antibiotics, Anti-inflammatory Drugs, Antifungal Drugs, Local Anesthetics) By Application (Dental Pain Management, Periodontal Disease Treatment, Post-Surgical Care, Oral Infections)By Dosage Form Tablets & Capsules(Oral Gels & Ointments, Mouth Rinses, Injectables ) By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies) By End User (Hospitals & Dental Clinics, Homecare Settings, Academic & Research Institutes) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Pfizer Inc., GlaxoSmithKline (GSK),Johnson & Johnson, Sanofi, Bayer AG, Sun Pharmaceutical Industries, Dr. Reddy’s Laboratories, Cipla Ltd., Abbott Laboratories, Colgate-Palmolive (OTC oral care drugs), Haleon,3M Health Care, Prestige Consumer Healthcare, Perrigo Company plc, Septodont |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








