


Market Overview
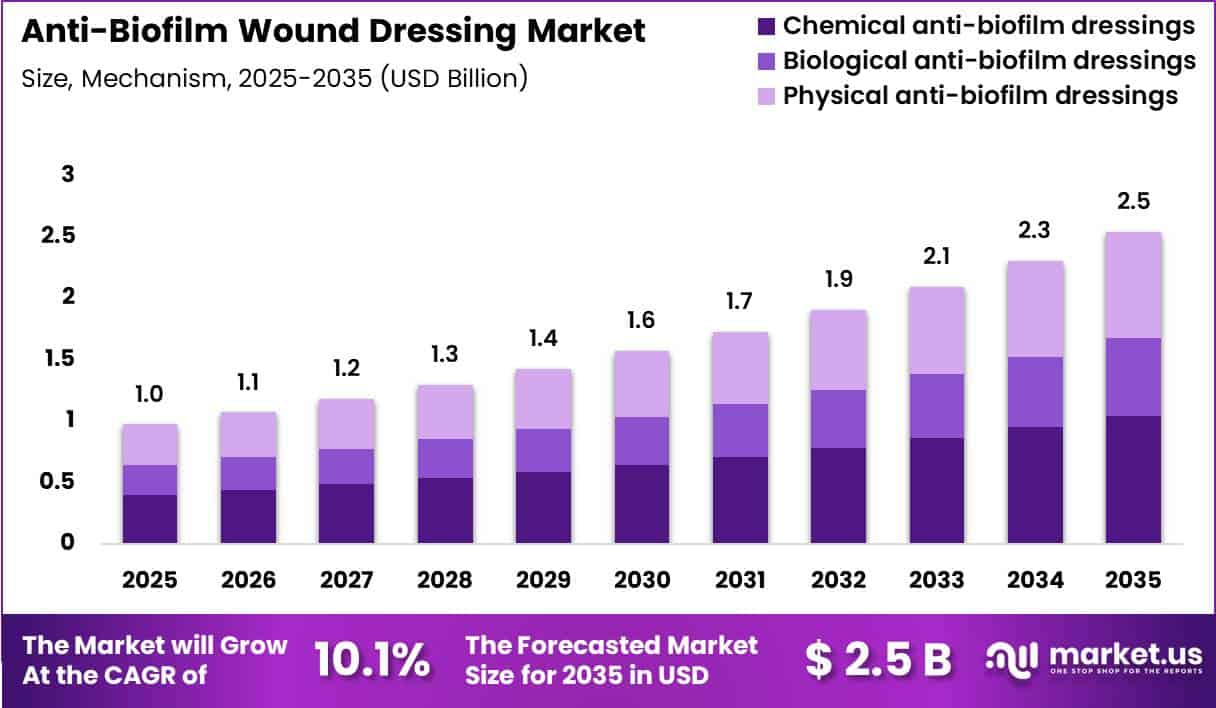
Global Anti-Biofilm Wound Dressing Market size is expected to be worth around US$ 2.5 Billion by 2035 from US$ 1.0 Billion in 2025, growing at a CAGR of 10.1% during the forecast period from 2026 to 2035. In 2025,North America led the market, achieving over 38.4% share with a revenue of US$ 0.4 Billion.
The Anti-Biofilm Wound Dressing Market is gaining importance as healthcare systems focus on advanced wound management solutions that address persistent infections and delayed healing. Biofilms are structured communities of microorganisms surrounded by a protective extracellular matrix, making them difficult to eliminate through conventional antimicrobial treatments.
These microbial formations are increasingly recognized as a major challenge in chronic wound care, particularly in diabetic foot ulcers, pressure ulcers, venous leg ulcers, and non-healing surgical wounds.
The rising burden of chronic wounds is creating demand for next-generation dressings designed to disrupt biofilm formation, reduce microbial load, and support faster tissue regeneration.
Research supported by the U.S. National Institutes of Health highlights that more than 6.5 million people in the United States suffer from chronic wounds, with approximately 30% of patients failing to heal using existing interventions. Studies also indicate that biofilms are present in a significant proportion of chronic wounds, contributing to treatment resistance and prolonged healing timelines.
Anti-biofilm wound dressings incorporate technologies such as silver-based materials, iodine, polyhexanide, nitric oxide-releasing systems, bacterial cellulose, and advanced hydrogel platforms. These solutions work by disrupting microbial communities, penetrating biofilm structures, and maintaining a favorable wound environment.
Research has demonstrated that antiseptic-loaded bacterial cellulose dressings can show strong biofilm-control activity against wound-associated pathogens.
Increasing diabetic wound cases, growing awareness of infection prevention, rising healthcare expenditure, and innovation in antimicrobial biomaterials are expected to accelerate adoption of anti-biofilm wound dressing technologies globally.
Key Takeaways
- Market Size: Global Anti-Biofilm Wound Dressing Market size is expected to be worth around US$ 2.5 Billion by 2035 from US$ 1.0 Billion in 2025.
- Market Share: The market is growing at a CAGR of 10.1% during the forecast period from 2026 to 2035.
- Mechanism: Chemical anti-biofilm dressings dominated the market in 2025, accounting for 41.2% market share.
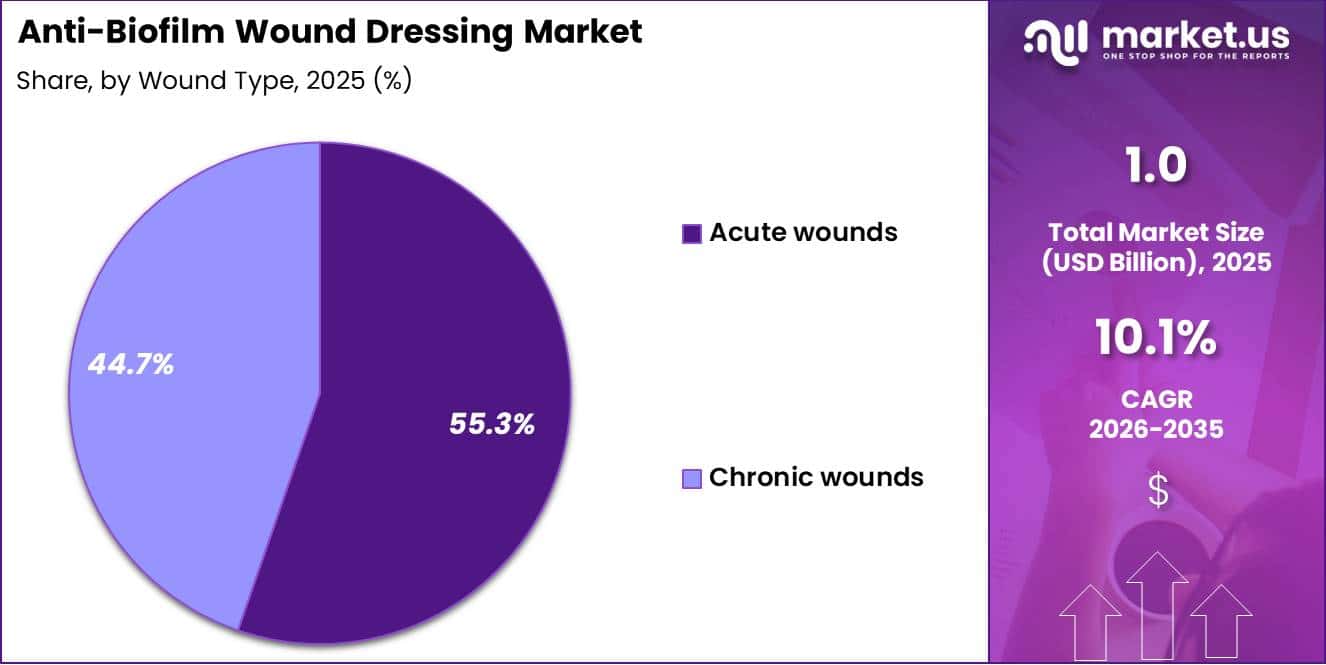
- Wound Type: Acute wounds dominated the market in 2025, accounting for 55.4% market share.
- Product Type: Silver-based dressings dominated the market in 2025 with a 24.5% market share.
- Distribution Channel: Hospitals dominated the market in 2025, accounting for 40.3% market share.
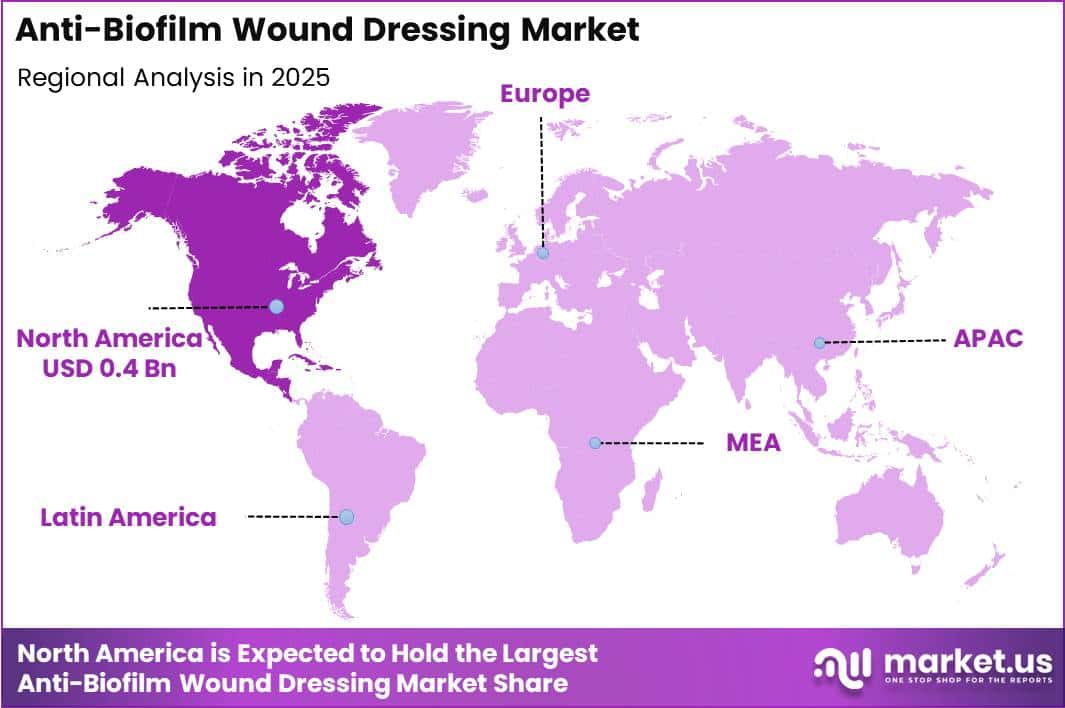
- Regional Analysis: In 2025,North America led the market, achieving over 38.4% share with a revenue of US$ 0.4 Billion.
Mechanism Analysis
Chemical anti-biofilm dressings dominated the market in 2025.
Based on mechanism, the Anti-Biofilm Wound Dressing Market is segmented into chemical anti-biofilm dressings, biological anti-biofilm dressings, and physical anti-biofilm dressings.
Chemical anti-biofilm dressings dominated the market in 2025, accounting for 41.2% market share, driven by their widespread clinical adoption, antimicrobial effectiveness, and ability to disrupt bacterial biofilm formation through active agents such as silver, iodine, and other antimicrobial compounds. These dressings are increasingly preferred for infected and high-risk wounds due to their proven ability to reduce microbial burden and support healing.
Physical anti-biofilm dressings represented 34.1% market share in 2025, supported by growing demand for non-pharmacological approaches that remove or prevent biofilm accumulation through moisture management, mechanical disruption, and wound environment optimization.
Biological anti-biofilm dressings accounted for 24.7% share and are projected to be the fastest-growing segment, fueled by advancements in biomaterials, natural antimicrobial compounds, and regenerative wound care technologies.
Increasing research into enzyme-based solutions, peptides, and biologically derived materials is enhancing their potential for advanced wound management. Overall, innovation across all mechanisms is improving treatment outcomes, reducing infection risks, and addressing the growing burden of chronic and complex wounds globally.
Wound Type Analysis
Acute wounds dominated the market in 2025.
Based on wound type, the Anti-Biofilm Wound Dressing Market is classified into acute wounds and chronic wounds. Acute wounds dominated the market in 2025, accounting for 55.4% market share, primarily due to the high volume of surgical wounds, trauma injuries, burns, and accidental wounds requiring effective infection prevention and rapid healing solutions.
The increasing number of surgical procedures worldwide and the need to minimize surgical site infections are driving the adoption of anti-biofilm dressings in acute wound management.
Chronic wounds accounted for 44.6% market share in 2025 and represent the fastest-growing segment, supported by the rising prevalence of diabetes, pressure ulcers, venous leg ulcers, and other long-term wound conditions.
Chronic wounds often develop persistent biofilms that delay healing and increase treatment complexity, creating strong demand for advanced dressings capable of disrupting microbial communities and promoting tissue repair. Growing healthcare awareness, improved wound care protocols, and increased adoption of specialized wound management products are further accelerating segment growth.
The rising elderly population and increasing incidence of lifestyle-related diseases are expected to strengthen demand for anti-biofilm solutions in chronic wound care applications.
Product Type Analysis
Silver-based dressings dominated the market in 2025.
Based on product type, the Anti-Biofilm Wound Dressing Market includes silver-based dressings, hydrogel dressings, alginate dressings, iodine-based dressings, foam dressings, PHMB-based dressings, honey-based dressings, and others.
Silver-based dressings dominated the market in 2025 with a 24.5% market share, attributed to their strong antimicrobial properties, broad-spectrum activity, and extensive clinical usage in infected wounds, burns, and surgical wound management. Silver-based products remain highly preferred due to their ability to control bacterial growth and reduce biofilm formation.
Hydrogel and alginate dressings are gaining adoption due to their moisture-balancing capabilities and suitability for wounds requiring advanced healing environments. Iodine-based dressings continue to witness demand because of their effective antimicrobial action against a wide range of pathogens.
Foam dressings are increasingly used for moderate-to-high exudating wounds due to their absorption capacity and patient comfort benefits. PHMB-based dressings are expanding as healthcare providers seek alternatives with sustained antimicrobial protection and lower resistance concerns.
Honey-based dressings are also gaining attention due to their natural antibacterial properties and wound-healing benefits. Continuous product innovation, improved material technologies, and increasing preference for advanced wound care solutions are expected to support market expansion across all product categories.
End Use Analysis
Hospitals dominated the market in 2025.
Based on end use, the Anti-Biofilm Wound Dressing Market is segmented into hospitals, ambulatory surgical centers, wound care centers, home healthcare, and others. Hospitals dominated the market in 2025, accounting for 40.3% market share, driven by the high volume of surgical procedures, trauma cases, and management of complex infected wounds requiring advanced wound care products.
Hospitals remain the primary users of anti-biofilm dressings due to the availability of specialized wound care teams and advanced infection management facilities.
Ambulatory surgical centers are witnessing increasing adoption as minimally invasive procedures and outpatient surgeries continue to expand globally. Wound care centers play an important role in treating chronic and difficult-to-heal wounds, supporting demand for specialized anti-biofilm technologies.
Home healthcare is the fastest-growing segment, supported by the rising preference for home-based treatment, increasing elderly populations, and the need for cost-effective long-term wound management solutions.
Improved patient education, remote monitoring capabilities, and availability of easy-to-use advanced dressings are accelerating adoption in home care settings. Other end users, including rehabilitation facilities and long-term care centers, are also contributing to market growth as healthcare systems focus on reducing hospitalization costs and improving patient outcomes.
Key Market Segments
By Mechanism
- Chemical anti-biofilm dressings
- Biological anti-biofilm dressings
- Physical anti-biofilm dressings
By Wound Type
- Acute wounds
- Chronic wounds
By Product Type
- Silver-based dressings
- Hydrogel dressings
- Alginate dressings
- Iodine-based dressings
- Foam dressings
- PHMB-based dressings
- Honey-based dressings
- Others
By End Use
- Hospitals
- Ambulatory surgical centers
- Wound care centers
- Home healthcare
- Others
Drivers
Clinical evidence and guideline evolution validating anti-biofilm technologies.
Another critical driver is the gradual accumulation of clinical and pre-clinical evidence confirming the efficacy of anti-biofilm technologies, such as cadexomer iodine combinations, surfactant-based dressings, and electroceutical devices, which in turn influences clinical guidelines and routine practice.
Academic reviews have highlighted that many traditional antimicrobials and standard dressings do not effectively eradicate biofilms, whereas newer formulations and surfactant-based antimicrobial dressings have demonstrated significant biofilm disruption and complete microbial death in experimental models.
Wireless electroceutical wound dressings, for example, have shown the ability to inhibit biofilms of pathogens like Pseudomonas aeruginosa by interfering with quorum-sensing pathways and resistance mechanisms, with porcine models demonstrating prevention and treatment of mixed biofilms and improved wound healing parameters.
Evidence-based reviews of antibiofilm agents for wound care catalogue the modes of action and clinical significance of currently available antibiofilm products, highlighting that surfactants, antiseptics, and advanced dressings can be integrated into treatment algorithms for chronic wounds.
Over time, such evidence feeds into practice guidelines developed by wound care associations and specialist societies, which are beginning to emphasize biofilm management and recommend combinations of debridement and topical biocides, as well as consideration of antibiofilm dressings in recalcitrant wounds.
For industry, the pivot from early-stage research to guideline-supported interventions is strategically important: once anti-biofilm dressings are referenced in clinical pathways, they gain a quasi-standard-of-care status in defined indications, helping vendors secure formulary listings, scale volumes, and shift commercial messaging from “promising innovation” to “guideline-aligned therapy.”
Given that guideline updates and broad clinician education typically unfold over 2–4 years, this driver supports medium-term acceleration in utilization and underpins an estimated +1.8 % point enhancement of overall market CAGR during the 2026–2030 window.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising chronic & diabetic wound burden boosting anti-biofilm adoption | +3.0% | North America core, EU, APAC corridors | Long term (≥ 4 years) |
| Ageing population & comorbidity load increasing advanced wound care spend | +2.2% | North America core, EU, East Asia | Long term (≥ 4 years) |
| Hospital infection-control and AMR stewardship policies favouring anti-biofilm dressings | +2.0% | North America core, EU, selective LATAM & APAC | Medium term (2-4 years) |
| Clinical evidence and guideline evolution validating anti-biofilm technologies | +1.8% | North America core, EU, APAC corridors | Medium term (2-4 years) |
| Technological innovation in electroceutical, surfactant, nanotech and combination dressings | +2.5% | North America core, EU, APAC innovation hubs | Long term (≥ 4 years) |
| Expansion of outpatient, home-care and value-based reimbursement models | +1.5% | North America core, EU, developed APAC | Short–Medium term (≤ 4 years) |
Challenge
Limited Clinical Evidence Slows Anti-Biofilm Dressing Adoption.
Limited high-quality clinical evidence specifically isolating anti-biofilm effects in wound dressings exerts a persistent friction drag on adoption, as systematic reviews up to 2024 highlight that existing studies often have small sample sizes, heterogeneous endpoints, and inconsistent definitions of “biofilm clearance,” leaving payers and hospital formulary committees unconvinced about incremental value versus standard advanced wound care.
Meta-analyses report biofilm prevalence in chronic wounds around 68–78%, yet relatively few randomized trials explicitly quantify biofilm load reduction in vivo with standardized imaging or histologic techniques, and many studies still rely on surrogate measures such as time to granulation or infection recurrence.
This evidence deficit manifests operationally as slower formulary approvals, often adding 12–18 months of evaluation cycles, lower protocol penetration, and conservative procurement policies that cap anti-biofilm dressing usage to 10–15% of eligible cases despite prevalence figures implying that 50–70% of chronic wounds may benefit from targeted biofilm control.
Strategically, manufacturers must invest in multicenter trials enrolling 300–600 patients across diabetic foot ulcers, venous leg ulcers, and pressure injuries, integrating quantifiable biofilm diagnostics, such as imaging-guided debridement or blotting techniques, and health-economic endpoints , while hospital systems need to embed these evidence streams into clinical governance dashboards to accelerate guideline updates over a 2–4-year horizon.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Limited clinical evidence | -1.4% | North America, EU, APAC hospitals | Medium term (2–4 years) |
| Complex reimbursement pathways | -1.1% | North America core, EU payers | Long term (≥ 4 years) |
| Biofilm diagnostics capacity gap | -1.0% | EU, APAC, Latin America | Medium term (2–4 years) |
| Specialist workforce shortfall | -0.9% | Global urban–rural mix | Long term (≥ 4 years) |
| Manufacturing scale-up complexity | -1.2% | North America, EU, APAC corridors | Medium term (2–4 years) |
| Antimicrobial stewardship pressure | -1.0% | Global tertiary care hubs | Long term (≥ 4 years) |
Restraints
Stricter FDA Reclassification Raises Antimicrobial Dressing Barriers.
A second restraint stems from the FDA’s proposed reclassification of many pre-amendment antimicrobial wound dressings and liquid wound washes into higher-risk device categories , particularly targeting products that contain antimicrobials with medium or low antimicrobial resistance concern and that historically entered the market without robust, prospective biofilm-disruption data.
Under draft rules issued since late 2023, manufacturers with legacy antiseptic or antimicrobial dressings are facing new requirements for biocompatibility, AMR risk characterization, standardized bench and animal models for biofilm disruption, and in some cases human clinical evidence that moves the cost of a full regulatory dossier from low six figures into the upper six or low seven figures per SKU over 24–36 months.
For small and mid-sized innovators focused specifically on anti-biofilm mechanisms, these rules create a step-change in pre-market and post-market surveillance costs: per-product testing cycles that previously took 6–9 months and USD 0.3–0.5 million can stretch to 18–24 months and USD 1–2 million when additional AMR, leachables, and long-term exposure data are required, with ongoing annual compliance adding a further 3–5% of sales in regulatory overhead.
Commercially, this raises the internal hurdle rate for new launches; a company planning to introduce three new anti-biofilm lines and line extensions across silver, polyhexanide, and biofilm-disruptive surfactant technologies between 2026 and 2029 may rationalize its pipeline to one or two “global” platforms, slowing SKU diversification and narrowing the range of indications that can be addressed.
In parallel, distributors and group purchasing organizations serving large US hospital systems increasingly require proof of FDA alignment with new classifications as a condition of maintaining contracts, so any delay in reclassification or special controls compliance can result in 12–24 months of formulary access risk in a market where 60–70% of advanced chronic wound episodes are routed through hospital-affiliated outpatient departments and home health agencies.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| CMS skin-substitute reimbursement compression | -2.2% | North America core | Medium term (2-4 years) |
| Stricter FDA antimicrobial dressing reclassification | -1.9% | North America core, EU | Medium term (2-4 years) |
| Evidence threshold for biofilm-specific claims | -1.4% | North America core, EU, UK | Short–Medium term (≤ 4 years) |
| Hospital budget pressure and DRG constraints | -1.6% | North America core, EU, APAC Tier-1 | Short term (≤ 2 years) |
| High manufacturing and QA cost intensity | -1.3% | EU, North America core, Japan | Long term (≥ 4 years) |
| Antimicrobial resistance (AMR) stewardship pressure | -1.1% | EU, North America core, OECD APAC | Long term (≥ 4 years) |
Opportunity
Integrated Surgical Infection Protocols Expand Anti-Biofilm Dressing Adoption.
Integrated surgical infection-prevention protocols involving anti-biofilm dressings present a white-space expansion from chronic wound care into the perioperative segment, where the burden of surgical site infections (SSIs) continues to drive substantial mortality, readmissions, and cost but where biofilm-specific dressings have not yet been systematically embedded into standardized bundles.
Current SSI management often combines systemic antimicrobials and conventional dressings presented within broad infection-prevention guidelines, but emerging evidence on biofilm behavior and the role of surface colonization in complex infections creates an opening for protocolized use of anti-biofilm dressings in high-risk procedures, such as orthopedic implants, vascular surgery, and diabetic limb salvage, where biofilm formation can lead to re-operations and hardware failure.
If vendors partner with hospital quality committees to define high-risk surgical cohorts and implement pathways that use biofilm-active dressings alongside optimized debridement and wound bed preparation techniques, they could demonstrate 10–20% relative reductions in SSIs or re-operations in target procedures, translating into hospital savings on the order of USD 2,000–5,000 per prevented event while adding only USD 80–150 per case in product cost.
Penetration of such bundles into even 8–12% of eligible surgeries in North America, the EU, and GCC markets over a 2–4-year window would materially expand TAM into a new segment and, through higher per-procedure dressing usage and premium positioning tied to quality metrics, could contribute roughly 1.7 % points of upside to the market CAGR beyond the baseline trajectory anchored in chronic wound demand alone.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| AI-driven biofilm diagnostics integration | +2.0% | North America, EU, APAC urban | Medium term (2–4 years) |
| Value-based chronic wound bundles | +1.8% | North America, EU, select LATAM | Medium term (2–4 years) |
| Diabetic foot ulcer (DFU) community care penetration | +2.2% | APAC emerging, MEA, Latin America | Long term (≥ 4 years) |
| Next-gen multifunctional dressings (biofilm + regeneration) | +2.5% | Global high-income and upper-middle income | Long term (≥ 4 years) |
| Home-care subscription and DTC channels | +1.5% | North America, EU, APAC | Short term (≤ 2 years) |
| Integrated surgical infection-prevention protocols | +1.7% | North America core, EU, GCC | Medium term (2–4 years) |
Regional Analysis
In 2025, North America dominated the Anti-Biofilm Wound Dressing Market.
North America dominated the Anti-Biofilm Wound Dressing Market in 2025, accounting for over 38.4% of the global market share, with revenue reaching approximately US$ 0.4 Billion. The region’s leadership is attributed to the increasing prevalence of chronic wounds, diabetic foot ulcers, pressure ulcers, and surgical site infections, which have created strong demand for advanced wound care solutions.
The presence of well-established healthcare infrastructure, higher adoption of innovative wound management technologies, and favorable reimbursement frameworks have further supported market growth.
The United States represents the major contributor within North America due to the rising burden of diabetes-related complications and the growing focus on reducing healthcare-associated infections. Hospitals, specialty wound care centers, and long-term care facilities are increasingly adopting anti-biofilm dressings that help disrupt microbial communities, control infection risks, and improve healing outcomes.
Additionally, continuous investments in research and development by leading wound care manufacturers are accelerating product innovation, including antimicrobial materials, advanced hydrogel formulations, and biofilm-targeting technologies.
The region is also witnessing increased collaboration between healthcare providers and medical device companies to improve wound care protocols and enhance patient outcomes. Growing awareness among clinicians regarding biofilm management, along with advancements in personalized wound treatment approaches, is expected to strengthen demand further.
With ongoing technological advancements, expanding chronic wound management programs, and increasing healthcare expenditure, North America is projected to maintain its leading position in the Anti-Biofilm Wound Dressing Market during the forecast period.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The Anti-Biofilm Wound Dressing Market is moderately consolidated, with leading global wound care companies competing through advanced biomaterial technologies, antimicrobial solutions, and integrated wound management platforms.
The competitive landscape is driven by continuous R&D investments, clinical validation of anti-biofilm technologies, and the development of next-generation dressings designed to improve healing outcomes in chronic and complex wounds.
Companies are focusing on combining antimicrobial efficacy, moisture balance, and patient comfort while strengthening partnerships with healthcare providers and research organizations to expand adoption.
Mölnlycke Health Care, Smith+Nephew, and 3M Company emphasize product innovation through advanced wound dressings, infection management solutions, and evidence-based wound care approaches. ConvaTec Group, Coloplast, and Johnson & Johnson focus on expanding wound care portfolios through research collaborations and integrated care solutions. B. Braun Melsungen AG, Medline Industries, and Hartmann Group strengthen market positions through broad healthcare ecosystems and hospital partnerships.
Integra LifeSciences, Paul Hartmann AG, Acelity, Urgo Medical, Lohmann & Rauscher, and DermaRite Industries compete through specialized dressing technologies, workflow integration, and customized wound management solutions. Strategic partnerships, product development, and ecosystem-based competition remain key factors shaping market growth.
Top Key Players
- Mölnlycke Health Care
- Smith+Nephew
- 3M Company
- ConvaTec Group
- Coloplast
- Johnson & Johnson
- B. Braun Melsungen AG
- Medline Industries
- Hartmann Group
- Integra LifeSciences
- Paul Hartmann AG
- Acelity
- Urgo Medical
- Lohmann & Rauscher
- DermaRite Industries
Recent Developments
- In November 2025, Mölnlycke Health Care, Mölnlycke Health Care strengthened its long-term wound care manufacturing strategy by beginning operations at its first wound care manufacturing site in China. The investment supports localized production capacity and improves supply chain flexibility for advanced wound care solutions, including antimicrobial and infection-management dressings.
- In September 2025, ConvaTec expanded its advanced wound care portfolio after receiving regulatory approval for ConvaMatrix™ in the UK and Europe. The development strengthened the company’s position in regenerative wound management and demonstrated continued investment in next-generation wound healing technologies.
- In May 2026, Smith+Nephew introduced new wound care innovations, including ALLEVYN™ COMPLETE CARE Dressing and RENASYS™ EDGE tNPWT System, focusing on improving chronic wound treatment efficiency and reducing clinical workload. The products were prepared for showcase at EWMA 2026 as part of the company’s continued investment in wound management technologies.,
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 1.0 Billion |
| Forecast Revenue (2035) | US$ 2.5 Billion |
| CAGR (2026-2035) | 10.1% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Mechanism (Chemical anti-biofilm dressings, Biological anti-biofilm dressings, Physical anti-biofilm dressings), By Wound Type (Acute wounds, Chronic wounds), By Product Type (Silver-based dressings, Hydrogel dressings, Alginate dressings, Iodine-based dressings, Foam dressings, PHMB-based dressings, Honey-based dressings, Others), By End Use (Hospitals, Ambulatory surgical centers, Wound care centers, Home healthcare, Others) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Mölnlycke Health Care, Smith+Nephew, 3M Company, ConvaTec Group, Coloplast, Johnson & Johnson, B. Braun Melsungen AG, Medline Industries, Hartmann Group, Integra LifeSciences, Paul Hartmann AG, Acelity, Urgo Medical, Lohmann & Rauscher, DermaRite Industries |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








