


Market Overview
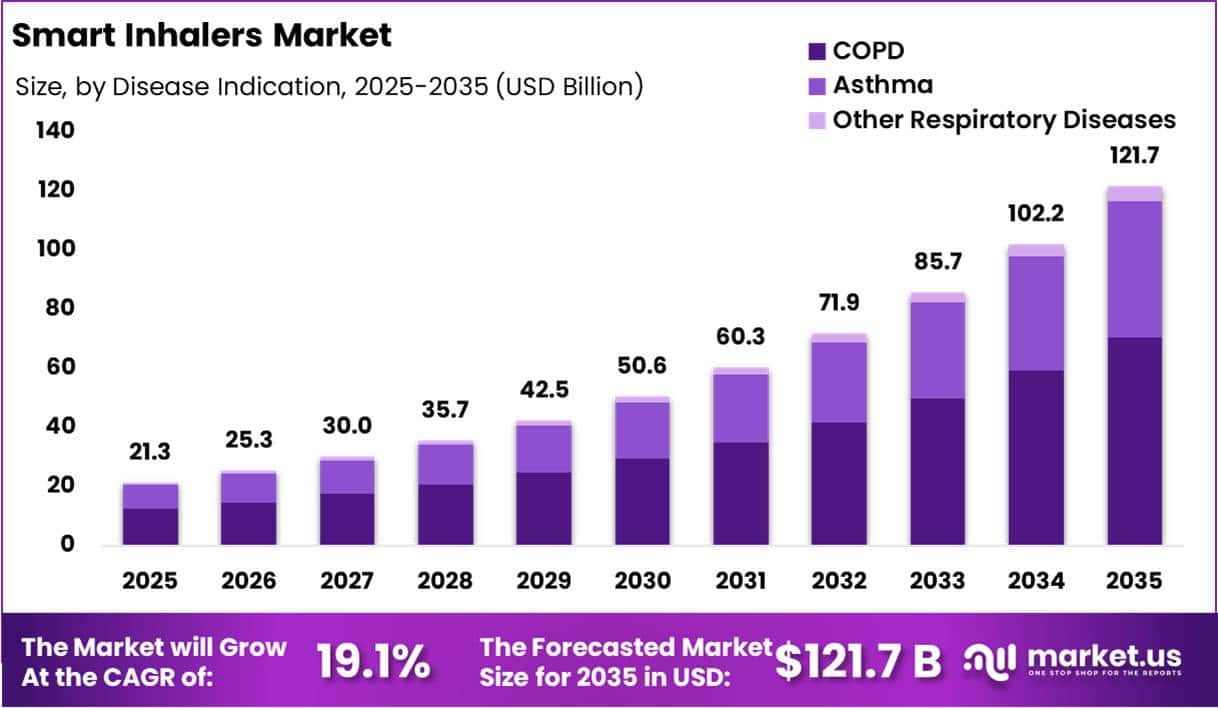
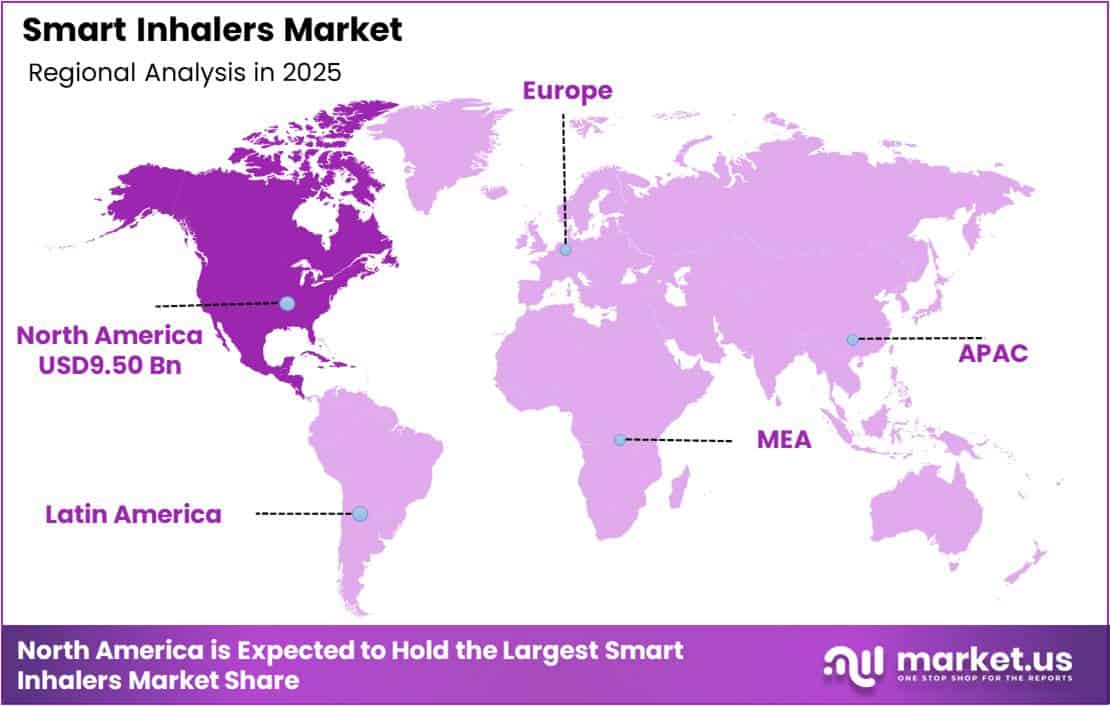
The Global Smart Inhalers Market size is expected to be worth around US$121.7 Billion by 2035 from US$21.3 Billion in 2025, growing at a CAGR of 19.1% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 44.60% share with a revenue of US$ 9.50 Billion.
The global smart inhalers market is expanding rapidly as healthcare systems increasingly adopt digital technologies to improve the management of chronic respiratory diseases such as asthma and chronic obstructive pulmonary disease (COPD).
Smart inhalers combine conventional inhaler devices with sensors and connected software that record medication usage, remind patients to take prescribed doses, and enable healthcare professionals to monitor adherence remotely.
According to the World Health Organization (WHO), asthma affected an estimated 262 million people worldwide and caused approximately 455,000 deaths in 2019, highlighting the continued need for better disease management.
Meanwhile, the U.S. Centers for Disease Control and Prevention (CDC) estimates that about 24.9 million people in the United States live with asthma, including millions of children, reinforcing demand for digital respiratory care solutions. Growing adoption of telehealth, remote patient monitoring, and connected medical devices is supporting the integration of smart inhalers into routine clinical practice.
Regulatory agencies such as the U.S. Food and Drug Administration (FDA) continue to advance oversight of digital health technologies, encouraging innovation while ensuring patient safety.
Healthcare providers are increasingly using inhaler adherence data to personalize treatment plans and reduce preventable exacerbations and hospitalizations. Advances in Bluetooth connectivity, mobile health applications, cloud-based analytics, and artificial intelligence are further improving patient engagement and medication compliance.
Rising healthcare spending, expanding digital health infrastructure, and increasing awareness of respiratory disease management are expected to support continued adoption of smart inhaler technologies across hospitals, clinics, and home-care settings, contributing to improved long-term patient outcomes and more efficient respiratory care delivery.
Key Takeaways
- Market Size:Smart Inhalers Market size was US$ 21.3 billion in 2025.The market is estimated to grow to US$ 121.7 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 19.1%.
- By Product Type:Smart Metered Dose Inhalers (MDIs) has the largest market share, accounting for 64.20% of total sales.
- By Disease Indication Method:COPD, accounting for 58.00% of total revenue.
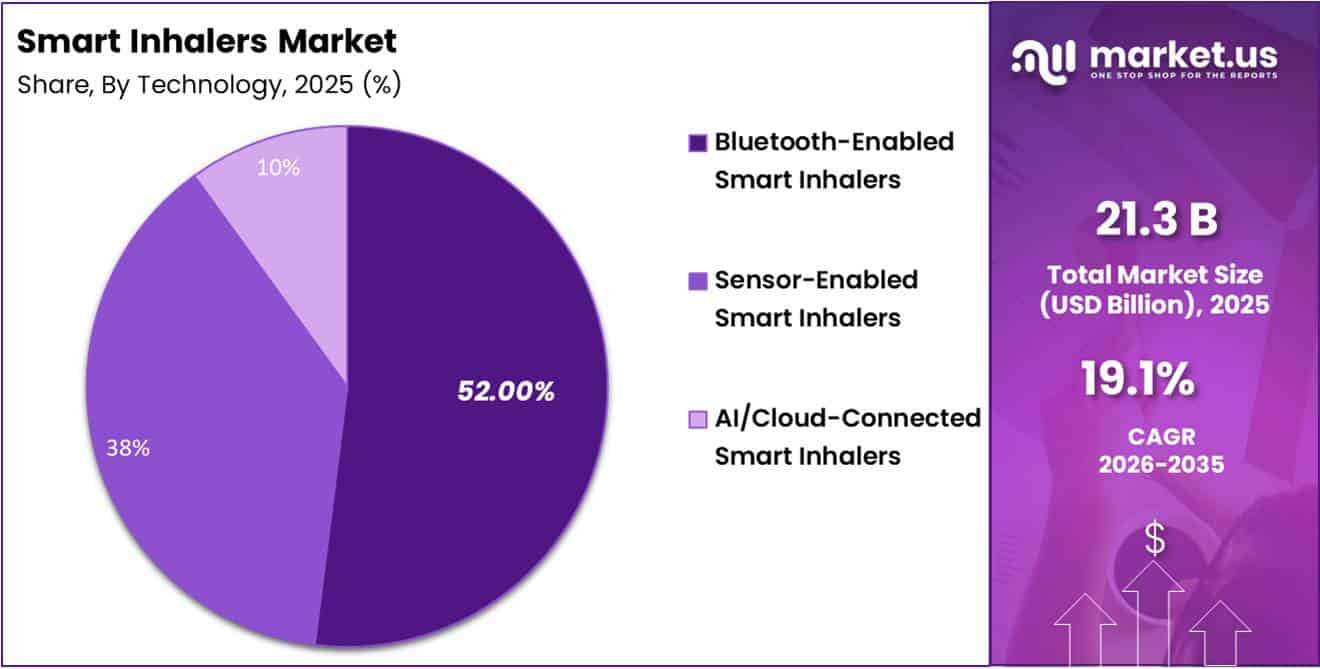
- By Technology:Bluetooth-Enabled Smart Inhalers leads the segment, accounting for 52.00% of total revenue.
- By End User:Hospitals & Clinics leads the segment, accounting for 48.00% of total revenue.
- By Distribution Channel:Hospital Pharmacies leads the segment, accounting for 46.00% of total revenue.
- Regional: North America is the dominant regional market,accounting for 44.60% of global sales.
Product Type Analysis
In 2025, Smart Metered Dose Inhalers (MDIs) dominated the smart inhalers market, accounting for 64.20% of the total market share. Their leadership is supported by widespread clinical adoption, ease of use, and compatibility with digital monitoring technologies.
Smart MDIs combine traditional inhaler delivery with built-in sensors that record medication usage, helping patients and healthcare providers monitor adherence and inhalation patterns. These devices are particularly beneficial for individuals requiring regular maintenance therapy, as they provide reminders, usage reports, and real-time data that improve disease management.
Growing adoption of connected healthcare solutions and increasing awareness of medication compliance further strengthen demand for smart MDIs. Meanwhile, Smart Dry Powder Inhalers (DPIs) represented 35.80% of the market in 2025.
Smart DPIs are gaining traction due to their breath-actuated design, eliminating the need for hand-breath coordination and making them suitable for many patients. Integration of digital sensors and mobile applications allows users to track inhalation technique and treatment progress.
Increasing development of advanced dry powder formulations, combined with rising demand for portable and environmentally friendly inhalers, is expected to support continued growth of this segment over the coming years.
Disease Indication Analysis
In 2025, Chronic Obstructive Pulmonary Disease (COPD) emerged as the leading disease indication segment, capturing 58.00% of the smart inhalers market. The dominance of COPD is driven by the increasing global burden of chronic respiratory diseases, particularly among aging populations and individuals with a history of smoking or long-term exposure to air pollution.
Patients with COPD often require long-term inhalation therapy, making smart inhalers valuable for improving medication adherence, monitoring treatment routines, and reducing hospital admissions through early intervention.
Healthcare providers increasingly recommend connected inhalers to support personalized disease management and remote patient monitoring. Asthma accounted for 38.00% of the market in 2025, supported by rising asthma prevalence across children and adults, along with growing awareness of preventive treatment strategies.
Smart inhalers help asthma patients maintain regular medication schedules and monitor symptom control effectively. The Other Respiratory Diseases segment represented 4.00% of the market, including conditions such as bronchiectasis and other chronic lung disorders.
Although comparatively smaller, this segment is expected to benefit from expanding digital respiratory care and increasing use of connected therapeutic devices.
Technology Analysis
In 2025, Bluetooth-Enabled Smart Inhalers held the largest share of the smart inhalers market, accounting for 52.00% of total revenue. Their widespread adoption is driven by seamless connectivity with smartphones and healthcare applications, enabling patients to receive medication reminders, monitor inhaler usage, and share treatment data with healthcare professionals.
Bluetooth technology offers a cost-effective and user-friendly solution for remote disease management, making it the preferred choice among healthcare providers and patients.
Increasing demand for connected healthcare devices and digital monitoring tools further supports this segment’s growth. Sensor-Enabled Smart Inhalers captured 38.00% of the market in 2025. These devices utilize embedded sensors to record inhalation events, detect usage patterns, and evaluate inhaler technique without requiring continuous wireless communication.
They are increasingly adopted in clinical settings to improve treatment adherence and optimize patient outcomes. The AI/Cloud-Connected Smart Inhalers segment represented 10.00% of the market.
Although still developing, these advanced devices leverage artificial intelligence and cloud platforms to generate predictive insights, support personalized treatment plans, and enable continuous remote monitoring. Growing investment in digital health infrastructure is expected to accelerate adoption of AI-enabled inhaler technologies.
End User Analysis
In 2025, Hospitals & Clinics dominated the smart inhalers market, accounting for 48.00% of the total market share. Their leadership is attributed to the high volume of respiratory disease diagnosis and treatment conducted in hospital settings, where healthcare professionals increasingly utilize connected inhalers to monitor medication adherence and improve clinical outcomes.
Hospitals also benefit from integrated digital health systems that enable physicians to access inhaler usage data and make informed treatment decisions.
The growing adoption of remote patient monitoring programs further supports demand within this segment. Beyond hospitals and clinics, home care settings are gaining importance as patients seek convenient long-term disease management through connected devices. Smart inhalers allow patients to monitor therapy from home while sharing data with healthcare providers, reducing unnecessary hospital visits.
Specialty respiratory care centers also contribute significantly by providing personalized treatment for chronic respiratory conditions. Additionally, ambulatory care centers and other healthcare facilities are expanding the use of smart inhalers to enhance outpatient respiratory care.
Increasing focus on patient-centered healthcare, digital therapeutics, and continuous disease monitoring is expected to strengthen adoption across all end-user segments during the forecast period.
Distribution Channel Analysis
In 2025, Hospital Pharmacies led the smart inhalers market, capturing 46.00% of the total market share. Their dominance is supported by the growing number of respiratory disease patients receiving prescriptions directly through hospitals and specialty healthcare centers.
Hospital pharmacies ensure immediate availability of advanced smart inhalers while providing professional guidance on device usage, medication adherence, and digital monitoring features. Integration with hospital treatment programs and electronic health records further enhances their importance in respiratory care.
Retail pharmacies also represent a significant distribution channel, benefiting from widespread accessibility and increasing consumer demand for convenient prescription fulfillment.
Pharmacists play a vital role in educating patients about proper inhaler techniques and connected health applications. Online pharmacies and e-commerce platforms are experiencing rapid growth as patients increasingly prefer home delivery services and digital healthcare solutions.
Rising internet penetration and expanding telemedicine services are accelerating this trend. Additionally, other distribution channels, including specialty pharmacies and direct healthcare provider supply programs, continue to support market expansion by improving access to innovative respiratory care devices. Growing digital healthcare adoption is expected to strengthen all distribution channels in the coming years.
Market Segmentations
Product Type
- Smart Metered Dose Inhalers (MDIs)
- Smart Dry Powder Inhalers (DPIs)
Disease Indication
- COPDAsthma
- Other Respiratory Diseases
Technology
- Bluetooth-Enabled Smart Inhalers
- Sensor-Enabled Smart Inhalers
- AI/Cloud-Connected Smart Inhalers
End User
- Hospitals & Clinics
- Homecare Settings
- Ambulatory Care Centers & Others
Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
Driver
Asthma COPD burden pushing controller adherence tools
The first structural growth driver is the sheer size and persistence of the treatable respiratory population, because smart inhalers monetize not only device sales but also medication persistence, refill continuity, and preventable exacerbation reduction.
WHO reports that asthma affected an estimated 363 million people in 2023 and caused 442,000 deaths, while under diagnosis and under treatment remain material, especially outside high income systems; this creates a very large installed base where even low single digit digital conversion translates into meaningful unit demand for sensor enabled inhalers, clip on devices, and software subscriptions.
From a market mechanics standpoint, adherence support matters because smart inhalers target a chronic use category with recurring dosing behavior rather than one time episodic treatment, so value capture scales through repeat prescriptions, app linked reminders, and clinician dashboards that can reduce therapy drop off in maintenance regimens.
NICE’s evidence review found high quality evidence for adherence outcomes in asthma and cited one cost consequence analysis showing a smart inhaler generated 12 % better adherence and 0.14 fewer exacerbations per patient, even though the device added £83 per patient, which is commercially relevant because preventing one urgent care or hospital episode can offset hardware and software costs in risk bearing systems.
This driver therefore lifts CAGR primarily through higher attach rates to existing inhaler volumes rather than through new disease creation, with strongest monetization in North America and Europe where controller therapy penetration, smartphone access, and digital disease management infrastructure are already established.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Asthma/COPD burden pushing controller adherence tools | +2.4% | North America core, EU, Japan, urban China, India metro | Medium term |
| FDA/device clearance widening compatible inhaler base | +1.9% | US core, Canada follow-through, selected EU spill-over | Short term |
| Guideline and evidence support for adherence monitoring | +1.6% | UK, EU, North America, Australia | Medium term |
| Remote monitoring for exacerbation prediction and care management | +1.7% | US integrated delivery networks, UK NHS pilots, Western Europe | Medium term |
| Access and reimbursement pressure for inhaled medicines digitization | +1.3% | EU, UK, Gulf, upper-middle-income APAC, selective LATAM | Medium term |
| Pediatric and high-risk population targeting through primary care pathways | +1.1% | UK core, North America, Australia, urban APAC | Short term |
Challenge
Respiratory Supply Chain Coupling
Smart inhaler growth is also constrained by its dependence on the broader respiratory drug delivery supply chain, because digital adoption often rides on existing pMDI ecosystems whose component availability, fill finish schedules, propellant transitions, accessory compatibility, and packaging flows are governed by pharmaceutical manufacturing realities rather than digital health timelines
That coupling creates about 0.9 % points of growth drag by introducing launch slippage when a sensor qualified inhaler SKU changes, when propellant related redesign priorities absorb engineering bandwidth, or when respiratory medicine continuity takes precedence over connected feature expansion.
The risk is structurally meaningful given the scale of conventional MDI propellant use in the US alone, estimated by EPA at roughly 1,595 metric tons in 2025, which underscores how large and operationally entrenched the legacy inhaler base remains relative to the still smaller connected overlay.
To navigate this, smart inhaler vendors need dual sourcing for electronics and plastics, compatibility roadmaps aligned with pharmaceutical lifecycle management, and region specific inventory buffers of roughly 8 to 12 weeks for high volume SKUs so respiratory drug supply volatility does not cascade directly into digital deployment volatility.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Device-Evidence Validation Gap | -1.4% | North America core, UK pilots, EU evidence markets | Medium term (2-4 years) |
| Inhaler Platform Fragmentation | -1.2% | EU regulatory hubs, US provider networks, APAC private systems | Medium term (2-4 years) |
| Cybersecurity Compliance Load | -1.0% | US FDA market, EU connected-care systems, developed APAC | Short term (≤ 2 years) |
| Respiratory Supply Chain Coupling | -0.9% | North America, EU, Japan, import-dependent APAC | Medium term (2-4 years) |
| Digital Adherence Workflow Fatigue | -1.1% | UK/Nordics pilots, US health systems, urban Asia | Short term (≤ 2 years) |
| Specialist Talent Bottlenecks | -0.8% | US innovation clusters, EU medtech centers, Israel/Singapore hubs | Long term (≥ 4 years) |
Restraints
Reimbursement gaps
The largest structural restraint remains weak and uneven reimbursement because smart inhalers usually add a sensor, app layer, cloud dashboard, and support workflow on top of standard inhaled therapy, yet many payer systems still reimburse the drug while only partially recognizing the digital companion, which compresses the economic case at scale.
This is especially relevant because asthma affected an estimated 363 million people in 2023, creating a large theoretical addressable pool, but NICE’s May 2026 position on asthma digital tools still centers on conditional NHS use during evidence generation rather than broad mature reimbursement, signaling that budget holders continue to demand harder utilization and outcome proof before routine funding.
In practical terms, this means suppliers often face 9 to 18 month evidence building cycles, health system selling costs that can absorb 12% to 18% of annual contract value, and renewal risk where digital fees are reviewed separately from pharmaceutical budgets, leading providers to delay deployment, limit rollouts to high risk cohorts, or negotiate outcome linked pricing that can cut realized gross margin by 300 to 600 basis points versus plan.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Reimbursement gaps | -2.1% | North America core, EU, Japan | Medium term |
| Regulatory burden | -1.9% | US, EU, UK | Short term |
| Cybersecurity compliance | -1.6% | US core, EU, developed APAC | Short term |
| Device cost inflation | -1.8% | EU, North America, APAC import markets | Medium term |
| Patient onboarding friction | -1.4% | Global mass market | Medium term |
| MDR and launch delays | -1.5% | EU core | Short term |
Opportunity
Severe asthma biologics companion
This is an untapped adjacency because biologic-treated severe asthma patients are a high-value subset whose therapy economics are dominated today by drug spend, while inhaler companies have not fully positioned smart inhalers as companion tools that optimize step-up/step-down decisions, rescue-use mapping, and ICS-formoterol adherence around biologic initiation rather than simply tracking generic inhaler use.
Given GINA’s continued emphasis on access to anti-inflammatory inhalers and reassessment of adherence and technique before escalating therapy, a smart inhaler plus biologic companion model could help identify non-responders earlier, reduce inappropriate biologic starts by an estimated 8–12%.
Improve persistence in controller therapy by 12–18%, and create a premium enterprise value proposition to specialty clinics and pharma partners worth perhaps 400–700 incremental annual platform revenue per severe patient cohort, translating into roughly +1.6 % points of market CAGR upside where severe asthma pathways and specialty reimbursement are most developed.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| RTM reimbursement scaling | +2.4% | North America core, select EU | Short term (≤ 2 years) |
| Pediatric caregiver platform | +1.9% | North America, EU, urban APAC | Medium term (2-4 years) |
| Severe asthma biologics companion | +1.6% | US, EU5, Japan, GCC | Medium term (2-4 years) |
| LMIC retrofit attachables | +2.8% | India, SEA, LATAM, Africa | Medium term (2-4 years) |
| Pharma data-licensing model | +1.7% | US, EU, Japan | Short term (≤ 2 years) |
| Roll-up of niche sensor assets | +1.3% | US, EU, Israel, APAC medtech hubs | Long term (≥ 4 years) |
Regional Analysis
In 2025, North America held a dominant market position, capturing more than a 44.60% share and holds US$ 9.50 Billion market value for the year. The region’s leadership reflects its healthcare infrastructure, awareness of respiratory diseases, and use of connected medical devices.
The United States is a contributor, supported by a large population living with asthma. The CDC reported that 8.4% of the US population, or about 27.8 million people, had current asthma in 2023.
This creates demand for tools that help patients follow treatment plans and track inhaler use. Smart inhalers can record medication use and share information with mobile apps or healthcare teams. These features support better monitoring and timely care.
Canada contributes through its established healthcare system and interest in digital health solutions. Wider use of remote care, improved connectivity, and focus on medication adherence are expected to support regional growth. However, device costs, data privacy, and reimbursement gaps may limit adoption.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The smart inhalers market is moderately consolidated, with established pharmaceutical manufacturers competing alongside specialized digital health companies that develop connected inhaler technologies and patient monitoring platforms.
Competition is driven by continuous innovation in sensor-enabled inhalers, mobile health applications, cloud-based analytics, and adherence monitoring solutions that improve disease management for asthma and chronic obstructive pulmonary disease (COPD).
Companies are increasingly investing in digital therapeutics, artificial intelligence-enabled insights, and remote patient monitoring capabilities to strengthen their competitive positions while meeting the growing demand for personalized respiratory care.
Leading participants include Adherium Limited, Propeller Health, Teva Pharmaceutical Industries Ltd., AptarGroup Inc., AstraZeneca PLC, Novartis AG, GSK plc, H&T Presspart Manufacturing Ltd., Amiko Digital Health Ltd., FindAir, Pneuma Respiratory Inc., AireHealth Inc., Cognita Labs LLC, 3M Health Care, and Boehringer Ingelheim GmbH.
These companies prioritize research and development to enhance inhaler connectivity, improve dose-tracking accuracy, and deliver real-time patient insights through digital platforms.
Strategic partnerships between pharmaceutical companies, medical device manufacturers, software developers, and healthcare providers are accelerating the commercialization of integrated respiratory care solutions.
Product innovation remains centered on Bluetooth-enabled inhalers, digital sensors, predictive analytics, and user-friendly mobile applications that encourage medication adherence. In addition, companies are focusing on workflow integration by connecting smart inhalers with electronic health records, telehealth platforms, and hospital information systems.
Ecosystem-based competition is becoming increasingly important, as organizations build comprehensive digital respiratory care networks that combine inhaler devices, data analytics, patient engagement tools, and clinical decision support to improve treatment outcomes and long-term disease management.
Top Key Players
- Adherium Limited
- Propeller Health
- Teva Pharmaceutical Industries Ltd.
- AptarGroup Inc.
- AstraZeneca PLC
- Novartis AG
- GSK plc
- H&T Presspart Manufacturing Ltd.
- Amiko Digital Health Ltd.
- FindAir
- Pneuma Respiratory Inc.
- AireHealth Inc.
- Cognita Labs LLC
- 3M Health Care
- Boehringer Ingelheim GmbH
Recent Developments
- In April 2025, AptarGroup Inc. announced the launch of a clinical study to validate its SmartTrack™ platform for inhaled medicines, aiming to support FDA regulatory pathways and accelerate approval of generic inhaled drug products through advanced computational modeling.
- In October 2025, AptarGroup Inc. announced that the U.S. FDA granted 510(k) clearance for HeroTracker® Sense, a Bluetooth-enabled connected add-on device that transforms conventional metered-dose inhalers into smart inhalers for asthma and COPD management.
- In May 2026, Amiko Digital Health Ltd. presented new clinical evidence at the Respiratory Drug Delivery 2026 conference showing that 73% of patients improved their inhaler technique using its Respiro connected inhaler platform across multiple inhaler types.
- In May 2026, Adherium Limited announced that multiple clinical studies featuring its Hailie® Smartinhaler® technology would be presented at the American Thoracic Society (ATS) 2026 conference, reinforcing the technology’s role in improving medication adherence, inhaler technique, and healthcare outcomes.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 21.3 Billion |
| Forecast Revenue (2035) | US$ 121.7 Billion |
| CAGR (2026-2035) | 19.1% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Smart Metered Dose Inhalers (MDIs), Smart Dry Powder Inhalers (DPIs))By Disease Indication(COPD, Asthma, Other Respiratory Diseases) By Technology (Bluetooth-Enabled Smart Inhalers, Sensor-Enabled Smart Inhalers,AI/Cloud-Connected Smart Inhalers) By End User (Hospitals & Clinics, Homecare Settings, Ambulatory Care Centers & Others) By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Adherium Limited, Propeller Health, Teva Pharmaceutical Industries Ltd., AptarGroup Inc., AstraZeneca PLC, Novartis AG, GSK plc, H&T Presspart Manufacturing Ltd., Amiko Digital Health Ltd., FindAir, Pneuma Respiratory Inc., AireHealth Inc., Cognita Labs LLC, 3M Health Care, Boehringer Ingelheim GmbH |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








