


Market Overview
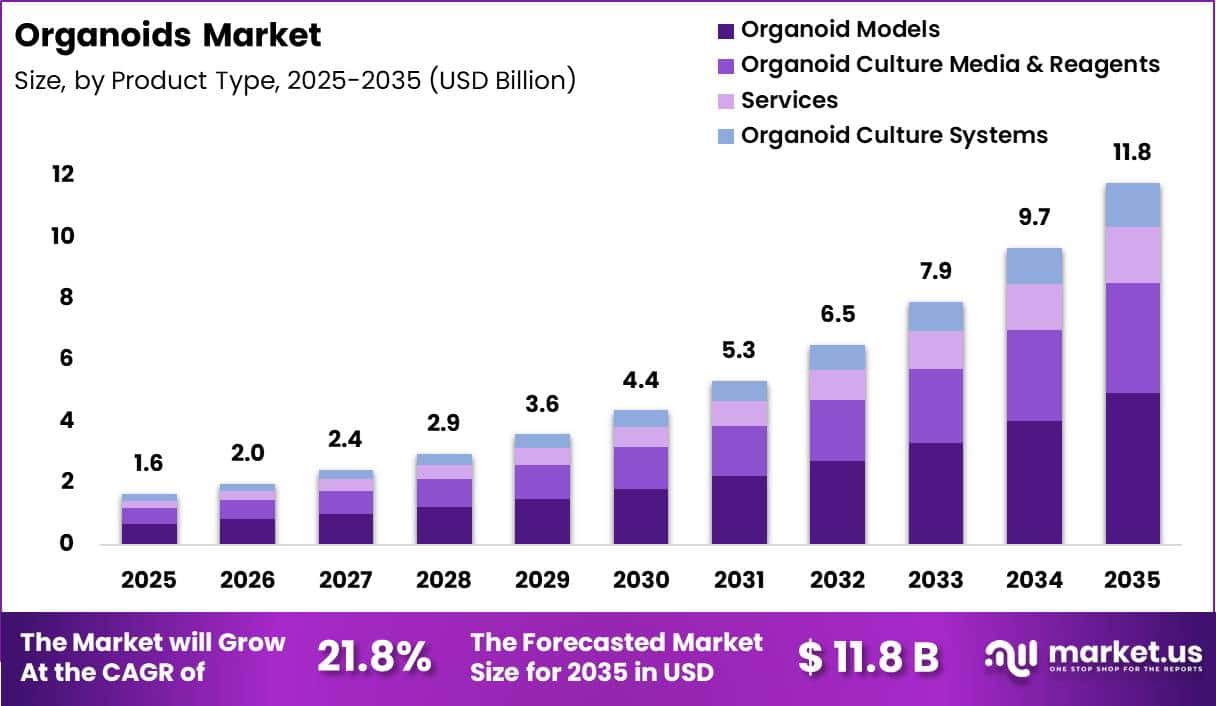
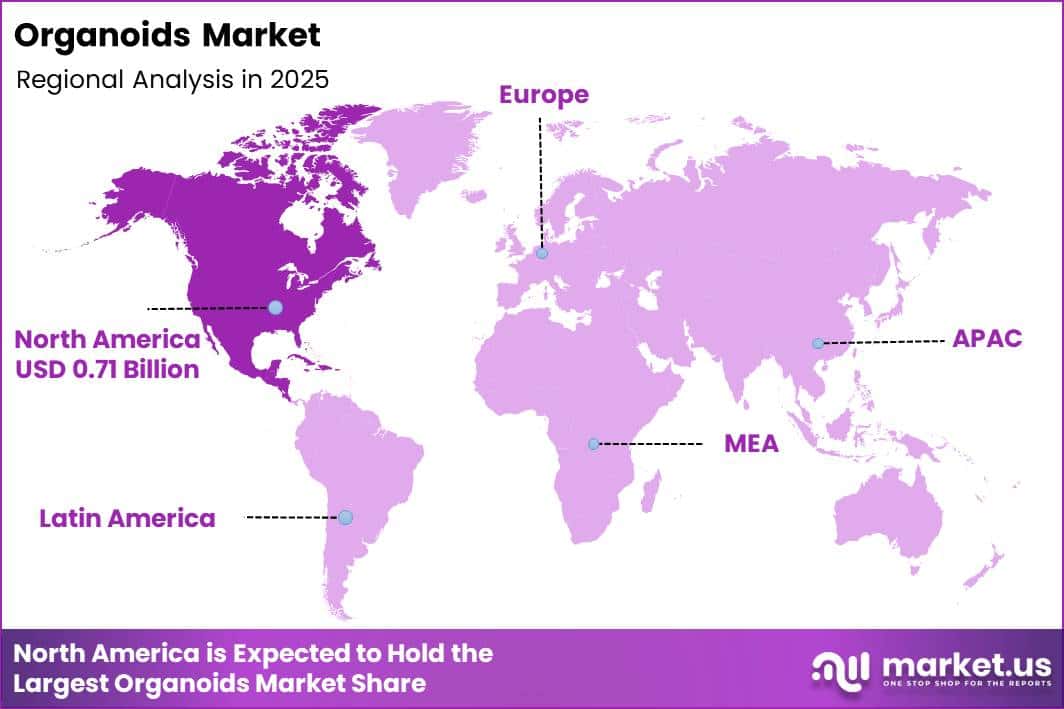
Global Organoids Market size is expected to be worth around US$ 11.8 Billion by 2035 from US$ 1.6 Billion in 2025, growing at a CAGR of 21.8% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 43.2% share with a revenue of US$ 0.71 Billion.
The global organoids market is gaining strong momentum as biomedical researchers and pharmaceutical companies increasingly adopt three-dimensional (3D) human tissue models for disease research, drug discovery, toxicology testing, and precision medicine.
Organoids are miniature laboratory-grown structures derived from stem cells that closely replicate the architecture and biological functions of human organs, making them more predictive than conventional two-dimensional cell cultures.
According to the U.S. National Cancer Institute (NCI), organoids preserve many of the molecular and genetic characteristics of the original tissue, enabling researchers to study cancer biology, evaluate treatment responses, and support personalized therapeutic strategies. Government agencies are actively supporting the advancement of organoid technologies.
In September 2025, the U.S. National Institutes of Health (NIH) launched the Standardized Organoid Modeling (SOM) Center, investing US$ 87 million during its first three years to establish standardized organoid protocols and reduce reliance on animal testing.
The center integrates artificial intelligence, robotics, imaging, and human cell resources to improve reproducibility and accelerate biomedical innovation. Organoids are increasingly being applied across oncology, infectious diseases, neuroscience, gastrointestinal disorders, and regenerative medicine.
NIH researchers recently developed vascularized lung and intestinal organoids capable of generating specialized blood vessels, representing a major scientific breakthrough that enhances the physiological relevance of these models for drug evaluation and developmental biology studies. Such advances are expected to improve preclinical testing accuracy while supporting more efficient therapeutic development.
Growing investment in stem cell research, precision medicine, genome editing, and advanced laboratory technologies continues to strengthen the adoption of organoid platforms worldwide.
Their expanding use in disease modeling, biomarker discovery, toxicity assessment, and personalized medicine positions organoids as one of the most promising technologies transforming modern biomedical research and next-generation drug development.
Key Takeaways
- Market Size : Global Organoids Market size is expected to be worth around US$ 11.8 Billion by 2035 from US$ 1.6 Billion in 2025.
- Market Share : The market is growing at a CAGR of 21.8% during the forecast period from 2026 to 2035.
- Product Type Analysis : The Organoid Models segment accounted for 41.8% of the organoids market in 2025, driven by their growing adoption as physiologically relevant alternatives to conventional two-dimensional cell cultures.
- Source Analysis : Patient-Derived Organoids (PDOs) held the largest market share of 36.8% in 2025, reflecting their increasing importance in precision medicine and translational oncology.
- Organ Type Analysis : The Intestine segment dominated the organoids market with 18.5% of the market share in 2025, reflecting its maturity as one of the earliest and most extensively validated organoid models.
- Application Analysis : The Drug Discovery & Development segment led the organoids market with 31.7% of the market share in 2025.
- End User Analysis : Pharmaceutical & Biotechnology Companies accounted for 38.5% of the organoids market in 2025.
- Regional Analysis : In 2025, North America led the market, achieving over 43.2% share with a revenue of US$ 0.71 Billion.
Product Type Analysis
The Organoid Models segment accounted for 41.8% of the organoids market in 2025, driven by their growing adoption as physiologically relevant alternatives to conventional two-dimensional cell cultures.
Pharmaceutical companies, biotechnology firms, and academic researchers increasingly use organoid models because they closely reproduce the structural and functional characteristics of human organs, making them valuable for disease modeling, drug screening, and precision medicine.
Official resources from STEMCELL Technologies highlight the expanding use of intestinal, cerebral, hepatic, and other organoid systems across multiple biomedical research areas.
Recent advancements in standardized organoid culture protocols have further improved reproducibility and experimental consistency. The Organoid Culture Media & Reagents segment represented 30.6% of the market, supported by continuous demand for specialized growth media, extracellular matrices, cytokines, and differentiation reagents that maintain organoid viability and function.
Services accounted for 15.4%, benefiting from increasing outsourcing of organoid development, assay design, and preclinical testing by pharmaceutical companies. The Organoid Culture Systems segment held 12.2%, supported by growing adoption of automated culture platforms, microfluidic systems, and bioreactors that improve scalability, workflow efficiency, and reproducible organoid production for research and drug development.
Source Analysis
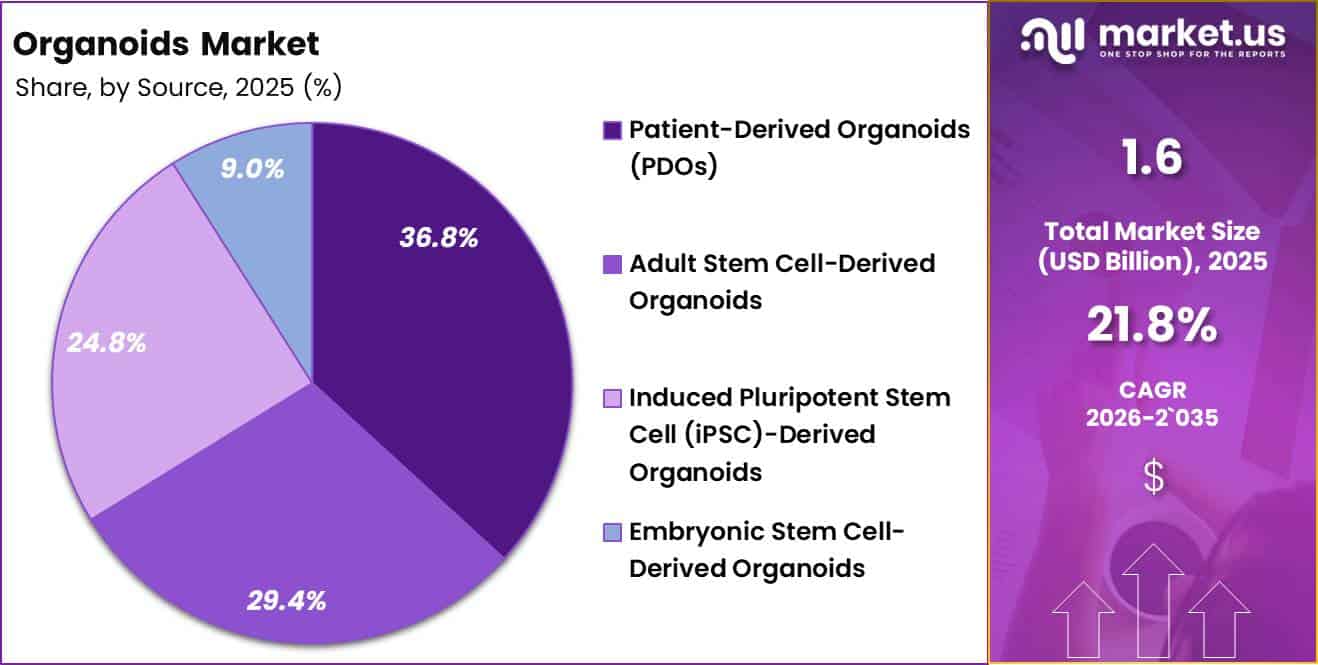
Patient-Derived Organoids (PDOs) held the largest market share of 36.8% in 2025, reflecting their increasing importance in precision medicine and translational oncology. PDOs retain the genetic and molecular characteristics of the original patient tissue, allowing researchers to evaluate drug responses and disease progression with greater clinical relevance.
The National Institutes of Health recognizes patient-derived organoids as an important component of next-generation human-based research models that improve disease investigation while reducing dependence on animal studies.
Adult Stem Cell-Derived Organoids captured 29.4% of the market due to their proven ability to generate stable organ-specific models for intestinal, liver, stomach, and kidney research. Their well-established culture methods continue to support regenerative medicine and toxicity studies.
Induced Pluripotent Stem Cell (iPSC)-Derived Organoids represented 24.8%, supported by their ability to model neurological, cardiovascular, and inherited disorders while enabling patient-specific research.
Embryonic Stem Cell-Derived Organoids accounted for 8.9% of the market, primarily serving developmental biology and early organ formation studies, although ethical considerations and evolving regulatory priorities continue to encourage broader adoption of adult stem cell and iPSC-based organoid platforms.
Organ Type Analysis
The Intestine segment dominated the organoids market with 18.5% of the market share in 2025, reflecting its maturity as one of the earliest and most extensively validated organoid models.
Intestinal organoids are widely used to investigate gastrointestinal diseases, inflammatory bowel disorders, host-microbiome interactions, nutrient absorption, and drug metabolism.
Official information from STEMCELL Technologies highlights their broad use in epithelial biology, stem cell research, toxicity evaluation, and regenerative medicine. The Liver segment remains an important area for hepatotoxicity assessment, metabolic disease research, and liver regeneration studies.
Brain organoids continue to gain significant attention for investigating neurodevelopmental disorders and neurodegenerative diseases, while Lung organoids are increasingly used for respiratory disease and infectious disease research. Kidney, Pancreas, and Stomach organoids support studies involving diabetes, digestive disorders, and renal diseases.
Heart organoids contribute to cardiovascular disease modeling and cardiotoxicity testing, whereas Breast, Prostate, and Skin organoids are increasingly adopted for cancer biology and personalized oncology research.
The Others segment includes retina, bladder, ovary, and additional tissue-specific organoids that continue expanding biomedical research applications.
Application Analysis
The Drug Discovery & Development segment led the organoids market with 31.7% of the market share in 2025. Growing reliance on human-relevant biological models has encouraged pharmaceutical and biotechnology companies to integrate organoids into target identification, efficacy evaluation, and preclinical drug screening workflows.
According to the National Institutes of Health, organoids improve disease modeling while reducing dependence on traditional animal models, supporting more predictive research outcomes. Toxicology Testing continues to expand as organoids provide more physiologically relevant platforms for evaluating drug safety and organ-specific toxicity.
Personalized Medicine has become another major application through the use of patient-derived organoids for individualized treatment selection, particularly in oncology.
Disease Modeling remains a core application by enabling researchers to investigate disease progression under controlled laboratory conditions. Regenerative Medicine and Stem Cell Research benefit from organoids that mimic tissue development and regeneration.
Cancer Research continues to drive strong adoption through tumor organoid biobanks and precision oncology studies, while Infectious Disease Research and Genetic Disorder Research increasingly rely on organoids to study pathogen-host interactions and inherited diseases using clinically relevant human tissue models.
End User Analysis
Pharmaceutical & Biotechnology Companies accounted for 38.5% of the organoids market in 2025, reflecting increasing investment in advanced human-relevant research platforms that improve drug development efficiency and translational success.
Companies are incorporating organoid technologies into oncology, regenerative medicine, rare disease, and precision medicine programs to enhance preclinical decision-making. The NIH’s establishment of the Standardized Organoid Modeling (SOM) Center further demonstrates the growing importance of standardized organoid technologies for industry adoption.
Contract Research Organizations (CROs) continue to strengthen their market presence by providing organoid-based screening, toxicity testing, and customized research services for pharmaceutical developers.
Academic & Research Institutes remain significant contributors through fundamental biological research, disease mechanism studies, and technology innovation supported by government funding. Hospitals & Clinical Research Centers increasingly utilize patient-derived organoids to support personalized treatment strategies and translational medicine.
Regenerative Medicine Centers are expanding the use of organoids to investigate tissue repair, stem cell therapies, and organ regeneration. The Others segment includes government laboratories, biotechnology incubators, and specialized diagnostic organizations that continue advancing organoid technology development and commercialization.
Market Segmentations
Product Type
- Organoid Models
- Organoid Culture Media & Reagents
- Organoid Culture Systems
- Services
Source
- Adult Stem Cell-Derived Organoids
- Induced Pluripotent Stem Cell (iPSC)-Derived Organoids
- Embryonic Stem Cell-Derived Organoids
- Patient-Derived Organoids (PDOs)
Organ Type
- Intestine
- Liver
- Brain
- Lung
- Kidney
- Pancreas
- Stomach
- Heart
- Breast
- Prostate
- Skin
- Others
Application
- Drug Discovery & Development
- Toxicology Testing
- Personalized Medicine
- Disease Modeling
- Regenerative Medicine
- Stem Cell Research
- Cancer Research
- Infectious Disease Research
- Genetic Disorder Research
- Others
End User
- Pharmaceutical & Biotechnology Companies
- Contract Research Organizations (CROs)
- Academic & Research Institutes
- Hospitals & Clinical Research Centers
- Regenerative Medicine Centers
- Others
Driver
Regulatory Pivot from Animal Models to Organoid Based Testing
The most powerful structural driver for the organoids market through 2026–2030 is the regulatory pivot away from traditional animal models toward advanced human relevant systems, with organoids positioned as a central replacement technology.
Three dimensional human cell culture systems encompassing spheroids and organoids are increasingly recognized in drug discovery as better recapitulating in vivo human tissue architecture, gradients, and cell cell interactions than 2D monolayers, which translates into higher predictive value for efficacy and toxicity screens.
In parallel, multiple regulatory and policy signals are converging: the NIH has publicized a strategic goal to reduce reliance on animal testing and is investing in standardized organoid platforms, including plans to channel Standardized Organoid Modeling Center that will supply validated liver, lung, heart, and intestinal organoids and share protocols and data openly.
Strategically, this driver alters the unit economics of preclinical testing by shifting spend from large animal facilities where housing, breeding, and compliance costs can dominate to modular organoid platforms that scale with consumables and medium volumes once capital is invested in bioreactors and imaging systems, per assay costs can fall as organoid production is standardized and batch to batch variability decreases.
For organoid vendors and technology platforms, this pivot supports recurring revenue models tied to catalogued organoid lines, maintenance media, and quality controlled batches sold on subscription or multi year supply agreements to pharma and CROs, thereby lifting baseline CAGR by an estimated 2.8 % points above a purely research driven trajectory.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Regulatory pivot from animal models to organoid-based testing | +2.8% | North America core, EU, APAC corridors | Medium term (2–4 years) |
| Oncology and rare disease drug discovery adoption | +2.4% | North America core, EU, APAC corridors | Medium term (2–4 years) |
| Public and NIH-led organoid funding programs | +1.9% | North America core, EU | Short–Medium term (≤ 4 years) |
| Advances in 3D cell culture and screening automation | +1.7% | North America core, EU, APAC corridors | Medium–Long term (≥ 3 years) |
| Movement toward personalized and precision medicine | +1.5% | North America core, EU, APAC corridors | Long term (≥ 4 years) |
| Early regulatory and payer recognition of organoid data | +1.2% | North America core, EU | Medium–Long term (≥ 3 years) |
Challenge
Limited Clinical Validation Slows Organoid Market Adoption
Limited clinical validation of organoid derived predictions relative to patient outcomes remains a structural challenge because, despite compelling case studies in oncology and cystic fibrosis, only a modest subset of indications, likely fewer than 50 out of thousands of disease entities, have been rigorously evaluated in prospective or retrospective cohorts linking ex vivo organoid responses to clinical endpoints such as progression free survival or biomarker change.
The FDA Modernization Act 2.0 and related guidance permit organoids and other new approach methodologies to substitute for some animal tests, but this legal flexibility does not automatically equate to payer or clinician confidence; sponsors still need datasets of hundreds of patients per indication to demonstrate that organoid based drug sensitivity or toxicity predictions achieve sensitivity and specificity metrics above 80–85%, alongside acceptable false negative rates for safety events.
Generating such datasets is capital and time intensive: each translational program may require 3–5 years, coordination among multiple academic medical centers, and data sharing infrastructure that respects privacy regulations while allowing cross site analytics.
Consequently, many pharma decision makers cap organoid spend at a small %, often below 5–10%, of their overall preclinical budget until validation signals accumulate, resulting in a stepwise adoption curve rather than the unconstrained S curve implied by technology capabilities alone.
Market participants can reduce this drag by forming consortia that pool de identified organoid and clinical outcome data across institutions, targeting at least 3–5 high value therapeutic areas where they can achieve statistically powered validation within a 4–6 year horizon, which in turn could unlock more aggressive internal replacement of animal models and recover approximately 1–1.5 % points of CAGR currently suppressed by risk averse budgeting and governance.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Non-standardized protocols | -1.8% | North America, EU, East Asia hubs | Medium term (2-4 years) |
| High-complexity production | -1.5% | US, EU, Japan, South Korea | Long term (≥ 4 years) |
| Limited clinical validation | -1.2% | Global oncology & rare disease centers | Long term (≥ 4 years) |
| Regulatory uncertainty NAMs | -1.0% | US, EU, UK, Asia-Pacific regulators | Medium term (2-4 years) |
| Talent and infrastructure gap | -0.9% | Emerging Asia, Latin America, EEMEA | Long term (≥ 4 years) |
| Data integration & IP silos | -0.8% | Pharma R&D clusters worldwide | Medium term (2-4 years) |
Restraints
Regulatory Uncertainty Slows Organoid Commercialization and Adoption
Regulatory uncertainty and ethics oversight burden exert a nuanced restraint: while frameworks like the FDA Modernization Act and associated roadmaps explicitly open the door for organoids and other non animal methodologies, they simultaneously introduce new validation, documentation and governance requirements that slow commercial scaling.
Sponsors must now generate extensive comparability data to justify replacing animal studies, often requiring parallel runs of organoid and traditional models over at least 2–3 compound programs, adding USD 3–7 million of incremental cost spread over 24–36 months before regulators fully accept the new approach for broader indications.
In addition, ethics committees and institutional review boards have begun to scrutinize specific organoid lines, particularly those derived from human embryonic or fetal tissue, or brain organoids with advanced functional properties, leading to approval cycles that can extend from 4–6 weeks to 10–20 weeks and imposing ongoing monitoring obligations that consume 5–10% of project management bandwidth.
On the industry side, sponsors face a moving target of guidance updates and pilot program criteria, which raises perceived regulatory risk and results in conservative adoption curves many large pharmas allocate only 5–10% of their non animal methods budgets to organoids, preferring lower regret investments in simpler in vitro assays and computational modeling until organoid specific regulatory precedents accumulate.
Strategically, the combination of heavier ethics oversight workflows, extended approval timelines and the need for multi arm validation programs erodes near term ROI and pushes several pipelines to treat organoids as complementary, not primary, decision tools, which collectively trims around 1.7 % points from the market’s CAGR over the medium term until clearer regulatory playbooks, standardized validation templates and global alignment reduce friction.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High cost of advanced organoid inputs | -2.3% | North America core, EU, APAC research hubs | Medium term (2-4 years) |
| Limited scalable bioprocessing and reproducibility | -1.9% | North America core, EU, East Asia | Long term (≥ 4 years) |
| Regulatory uncertainty and ethics oversight burden | -1.7% | North America core, EU, selected APAC corridors | Medium term (2-4 years) |
| Shortage of specialized skills and infrastructure | -1.5% | Emerging APAC, LATAM, MEA urban clusters | Long term (≥ 4 years) |
| Fragmented IP and data-sharing frameworks | -1.2% | North America core, EU, Japan | Medium term (2-4 years) |
| Logistical and cold-chain constraints for live organoids | -1.0% | Global, with emphasis on cross-border trade lanes | Short term (≤ 2 years) |
Opportunity
Regenerative Micro-Grafts Expand Organoids Beyond Research Applications
This opportunity focuses on moving organoids beyond in vitro models into regulated regenerative micro graft products and cell therapy adjuncts, an area where proof of concept studies exist but where commercialization is still nascent and not reflected in mainstream forecasts that treat organoids principally as research tools.
As organoid protocols for liver, gut, retina, and brain continue to mature, and as standardization initiatives such as NIH’s SOM Center drive reproducibility and quality control, organoid derived micro grafts could realistically become adjuncts to cell therapies or surgical interventions, for example, patches seeded with liver organoids to support regeneration post resection, or intestinal organoid grafts to treat localized mucosal damage.
If such products achieve regulatory clearance in key markets by the early 2030s and capture only 1–2% of eligible procedure volumes in high value indications, the resulting TAM could exceed USD 1.0–1.5 billion annually by 2035, with gross margins in the 60–70% range.
While timelines are longer due to regulatory and manufacturing scale up, this shift from service/assay revenue into reimbursed therapeutic products has the potential to add approximately 2.2 % points of CAGR upside for the organoids sector, particularly across North America, Europe, and emerging APAC markets where regenerative medicine and advanced therapies are strategic national priorities.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Standardized organoid CRO platforms | +2.0% | North America, EU, Japan | Short term (≤ 2 years) |
| NAM-aligned regulatory toxicology suites | +1.5% | North America core, EU | Medium term (2-4 years) |
| Clinical-trial-in-a-dish personalization services | +1.8% | North America, EU, APAC tier-1 | Medium term (2-4 years) |
| Regenerative micro-grafts and cell therapy adjuncts | +2.2% | North America, EU, APAC emerging | Long term (≥ 4 years) |
| AI-automated organoid manufacturing & cloud labs | +1.3% | North America, EU, APAC | Medium term (2-4 years) |
| Emerging-market organoid access programs | +0.8% | APAC emerging, LATAM, MENA | Long term (≥ 4 years) |
Regional Analysis
North America accounted for the largest share of the global organoids market in 2025, representing 43.2% of total revenue. The region’s leadership is supported by a strong biotechnology ecosystem, advanced stem cell research, well-established pharmaceutical and biotechnology industries, and favorable regulatory initiatives.
In April 2025, the U.S. Food and Drug Administration (FDA) announced a roadmap to reduce animal testing in drug development by encouraging the use of New Approach Methodologies (NAMs), including human organoids, organ-on-chip platforms, and AI-based computational models.
The FDA also began encouraging the inclusion of NAM-based evidence in investigational new drug (IND) applications, reinforcing the adoption of organoid technologies in preclinical research and drug safety evaluation.
Europe remains the second-largest regional market, driven by substantial investments in regenerative medicine, stem cell science, and collaborative research initiatives supported by leading universities and biomedical institutes.
Countries such as Germany, the Netherlands, France, and the United Kingdom continue to expand organoid applications in oncology, gastrointestinal diseases, and neurological disorders.
Meanwhile, Asia-Pacific is emerging as the fastest-growing region due to increasing government support for biotechnology, expanding pharmaceutical R&D activities, and rising investments in precision medicine.
Scientific studies also indicate that China has become one of the world’s leading hubs for organoid-based clinical research, reflecting its rapidly expanding role in translational medicine and advanced therapeutic development.
Latin America and the Middle East & Africa currently account for a smaller market share but are steadily advancing through improved biomedical research infrastructure, international research collaborations, and growing public investment in life sciences, creating long-term opportunities for organoid technology adoption.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global organoids market is characterized by continuous innovation, with leading companies focusing on patient-derived organoids, stem cell technologies, disease modeling, and advanced drug discovery platforms.
Hubrecht Organoid Technology (HUB) remains one of the pioneers in the field, providing patented organoid technology, licensing programs, and living biobanks that support pharmaceutical research and precision medicine. Following its acquisition by Merck KGaA’s Life Science business in 2024, HUB has expanded the commercialization of its organoid platform globally.
Companies such as MIMETAS, Organovo, STEMCELL Technologies, DefiniGEN, Crown Bioscience, InSphero, QGel, and Horizon Discovery are strengthening competition by developing advanced 3D cell culture systems, organ-on-chip technologies, patient-derived organoid models, stem cell differentiation platforms, and high-throughput drug screening solutions.
Crown Bioscience has expanded its oncology research portfolio with proprietary patient-derived organoid models developed using licensed HUB technology, while Organovo continues to advance 3D human tissue platforms for inflammatory bowel disease and other therapeutic areas.
Strategic collaborations with pharmaceutical companies, research institutes, and academic centers remain a common growth strategy across the market. Companies are increasingly investing in automation, artificial intelligence-enabled image analysis, biobanking, and personalized medicine applications to improve predictive drug testing and reduce dependence on animal models.
These technological advancements, combined with expanding research partnerships and commercialization efforts, are expected to intensify competition and support long-term growth in the global organoids market.
Top Key Players
- Hubrecht Organoid Technology (HUB)
- MIMETAS
- Organovo
- STEMCELL Technologies
- DefiniGEN
- Crown Bioscience
- InSphero
- QGel
- Horizon Discovery
- Prometheus Life Technologies
- Organogenesis Inc.
- Cellesce
- HemoShear Therapeutics
- Emulate Inc.
- Takara Bio
- Other Key Players
Recent Developments
- July, 2026 – Crown Bioscience (Global) joined the Critical Path Institute (C-Path) NAMs Developer Coalition to support the adoption of New Approach Methodologies (NAMs), including organoid-based models, in drug development. The initiative is intended to improve translational research while reducing reliance on animal testing through broader industry collaboration.
- April, 2026 – Crown Bioscience (Global/Europe–U.S.) entered into a strategic partnership with Turbine to combine AI-driven drug response prediction with patient-derived organoid validation. The collaboration aims to accelerate precision oncology by improving preclinical drug candidate selection and biomarker discovery using clinically relevant organoid models.
- January, 2025 – STEMCELL Technologies (Canada) launched IntestiCult™ Plus Intestinal Organoid Culture Medium, a next-generation organoid culture medium that enables simultaneous expansion and differentiation of intestinal organoids. The new product improves organoid maturity, reproducibility, and workflow efficiency, supporting researchers in gastrointestinal disease modeling, regenerative medicine, and drug discovery.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 1.6 Billion |
| Forecast Revenue (2035) | US$ 11.8 Billion |
| CAGR (2026-2035) | 21.8% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | Product Type (Organoid Models, Organoid Culture Media & Reagents, Services, Organoid Culture Systems), Source (Patient-Derived Organoids (PDOs), Adult Stem Cell-Derived Organoids, Induced Pluripotent Stem Cell (iPSC)-Derived Organoids, Embryonic Stem Cell-Derived Organoids), Organ Type (Intestine, Liver, Brain, Lung, Kidney, Pancreas, Stomach, Heart, Breast, Prostate, Skin, Others), Application (Drug Discovery & Development, Toxicology Testing, Personalized Medicine, Disease Modeling, Regenerative Medicine, Stem Cell Research, Cancer Research, Infectious Disease Research, Genetic Disorder Research, Others), End User (Pharmaceutical & Biotechnology Companies, Contract Research Organizations (CROs), Academic & Research Institutes, Hospitals & Clinical Research Centers, Regenerative Medicine Centers, Others) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Hubrecht Organoid Technology (HUB), MIMETAS, Organovo, STEMCELL Technologies, DefiniGEN, Crown Bioscience, InSphero, QGel, Horizon Discovery, Prometheus Life Technologies, Organogenesis Inc., Cellesce, HemoShear Therapeutics, Emulate Inc., Takara Bio, Other Key Players |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








