


Market Overview
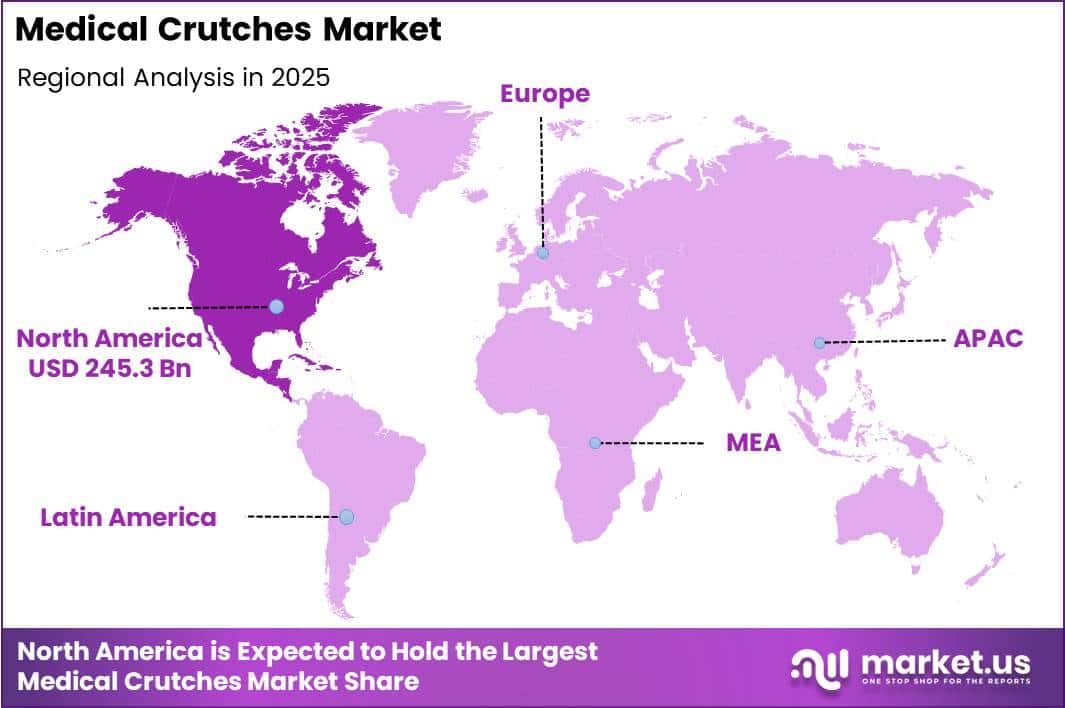
Global Medical Crutches Market size is expected to be worth around US$ 1,256.2 Billion by 2035 from US$ 685.1 Billion in 2025, growing at a CAGR of 6.3% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 35.8% share with a revenue of US$ 245.3 Billion.
Medical crutches are essential mobility-assistance devices designed to help individuals with temporary or permanent lower-limb impairments maintain balance, reduce weight-bearing on injured limbs, and regain independence during rehabilitation. These devices are widely used following fractures, ligament injuries, orthopedic surgeries such as hip and knee replacements, sports-related trauma, and neurological conditions affecting mobility.
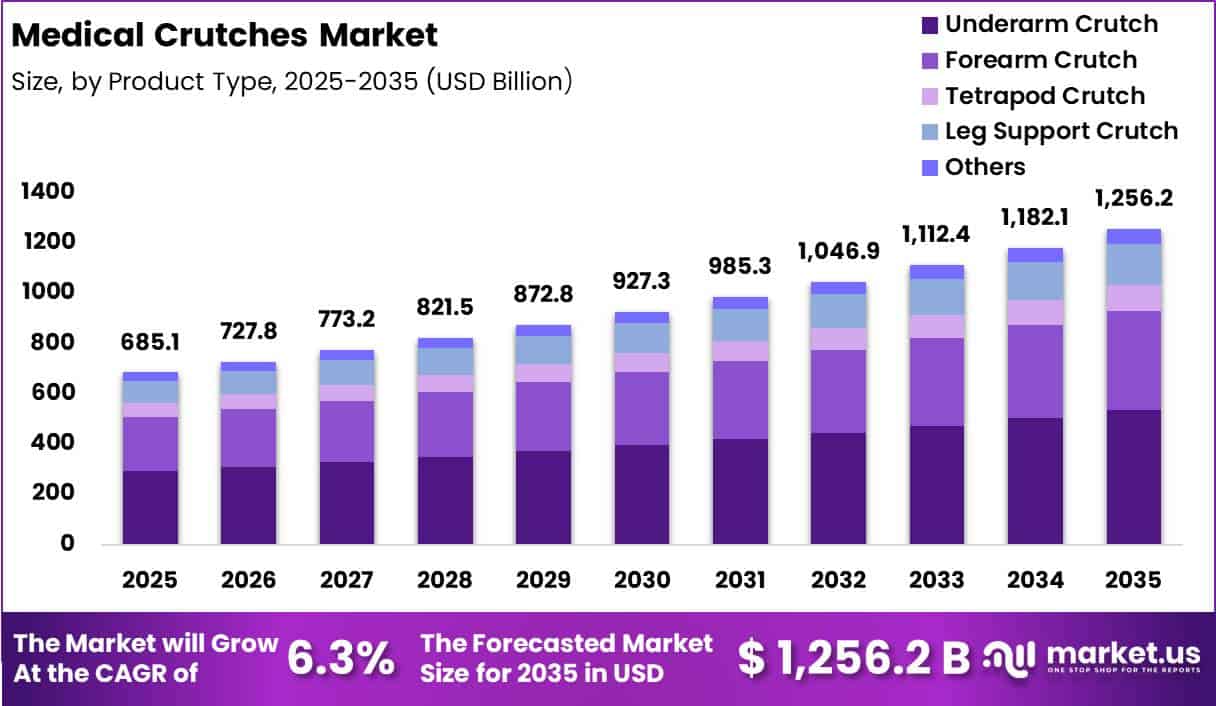
According to the World Health Organization (WHO), approximately 1.3 billion people, or about 16% of the global population, live with significant disabilities, many of whom require assistive products such as crutches, walkers, or wheelchairs to improve daily functioning and quality of life.
Furthermore, the WHO and UNICEF estimate that more than 2.5 billion people worldwide need one or more assistive products, with demand expected to rise to over 3.5 billion by 2050 due to population aging and the growing burden of chronic diseases. The U.S. Centers for Disease Control and Prevention (CDC) also reports that 1 in 4 U.S. adults lives with a disability, with mobility disability being one of the most common categories.
Increasing incidences of road traffic injuries, musculoskeletal disorders, osteoporosis-related fractures, and sports injuries continue to drive the need for reliable mobility aids. Advances in lightweight aluminum and carbon-fiber materials, ergonomic forearm supports, adjustable-height mechanisms, and anti-slip ferrules are improving patient comfort and safety while supporting faster rehabilitation outcomes.
Growing government initiatives promoting access to assistive technologies and expanding orthopedic care infrastructure are further strengthening adoption of medical crutches across hospitals, rehabilitation centers, and home-care settings worldwide.
Key Takeaways
- Market Size: The Medical Crutches Market size was US$ 685.1 Billion in 2025.The market is estimated to grow to US$ 1,256.2 Billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 6.3%.
- By Product Type: Underarm Crutch has the largest market share, accounting for 42.6% of total sales.
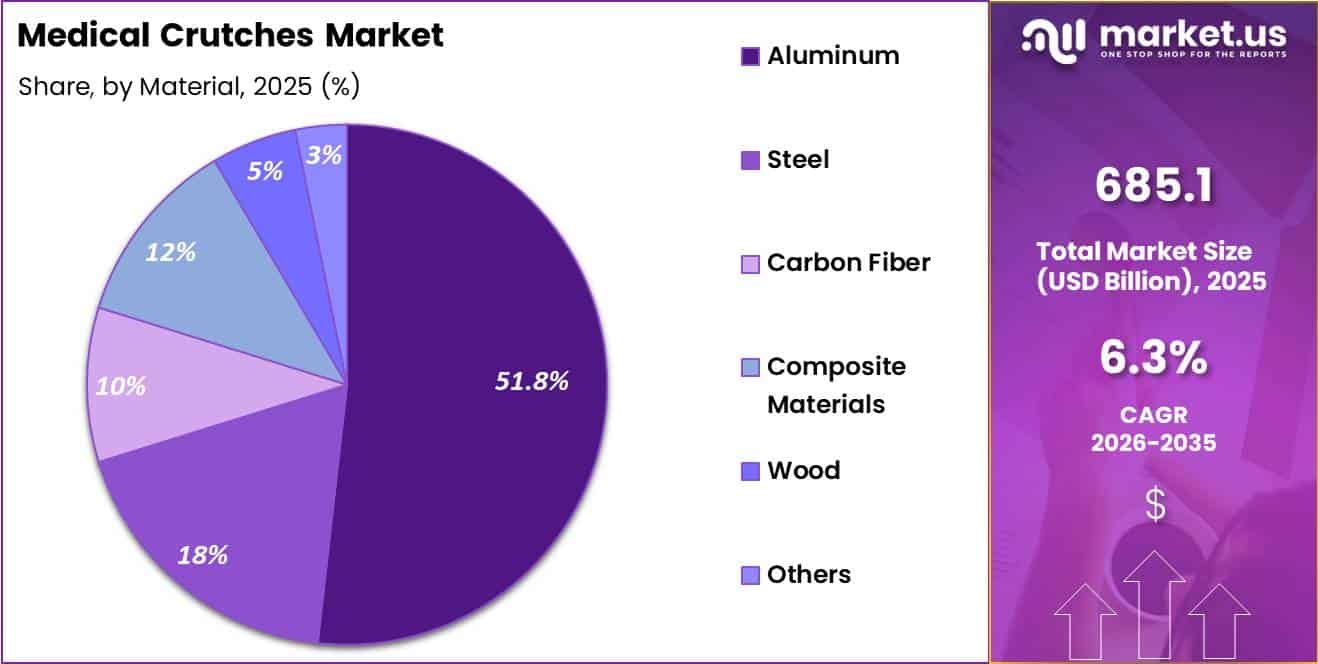
- By Material: Aluminum dominate the segment, accounting for 51.8% of total revenue.
- By Age Group: Adult leads the segment, accounting for 61.7% of total revenue.
- By Application: Orthopedic Injuries leads the segment, accounting for 28.7% of total revenue.
- By End User: Hospitals leads the segment, accounting for 34.7% of total revenue.
- Regional: North America is the dominant regional market, accounting for 43.3% of global sales.
Product Type Analysis
The Underarm Crutch segment dominated the Medical Crutches Market, accounting for 42.6% of the market share in 2025. Underarm crutches remain the preferred mobility aid for patients recovering from fractures, sprains, ligament injuries, and lower-limb surgeries due to their affordability, wide availability, and ease of use.
Hospitals and emergency departments frequently prescribe these crutches for short-term rehabilitation, making them the most commonly utilized product type. Their standardized design and suitability for temporary weight-bearing support further strengthen market demand.
The Forearm Crutch segment captured 31.4% of the market, supported by increasing use among individuals requiring long-term mobility assistance because of neurological disorders, musculoskeletal conditions, or chronic disabilities.
Leg Support Crutches represented 12.8% of the market, gaining attention for enabling hands-free mobility during recovery from foot and ankle injuries while maintaining greater patient independence. Tetrapod Crutches, accounting for 8.3%, are primarily used by elderly individuals and patients with balance impairments who require enhanced stability.
The Others category held 4.9% of the market and includes specialized crutches designed for bariatric patients, sports rehabilitation, and customized orthopedic applications. Continuous ergonomic improvements and lightweight designs are supporting product innovation across all segments.
Material Analysis
The Aluminum segment led the Medical Crutches Market with a 51.8% share in 2025. Aluminum remains the preferred material because it combines lightweight construction, corrosion resistance, durability, and cost-effectiveness.
Adjustable aluminum crutches are widely adopted across hospitals, rehabilitation centers, and home healthcare settings due to their ease of handling and ability to accommodate different patient heights. Manufacturers also favor aluminum for its strength-to-weight ratio and efficient large-scale production.
The Steel segment accounted for 18.4% of the market, benefiting from its superior load-bearing capacity and durability, particularly for bariatric patients and heavy-duty clinical applications. Composite Materials represented 11.7%, reflecting growing demand for products that balance strength with reduced weight while improving user comfort.
Carbon Fiber captured 9.6% of the market and is increasingly utilized in premium mobility devices because of its exceptional strength, lightweight properties, and enhanced shock absorption, particularly among active users and athletes.
Wood held 5.3% of the market, supported mainly by traditional healthcare settings and low-cost applications in selected regions. The Others category contributed 3.2%, including advanced polymer blends and specialty materials developed to improve ergonomics, durability, and patient comfort while reducing overall device weight.
Age Group Analysis
The Adult segment dominated the Medical Crutches Market, accounting for 61.7% of the market share in 2025. Adults represent the largest patient population requiring mobility assistance due to sports injuries, workplace accidents, orthopedic surgeries, trauma cases, and temporary fractures.
The increasing number of knee and hip replacement procedures, combined with rising participation in physical activities, continues to generate substantial demand for crutches designed for adult users. Manufacturers offer a wide variety of adjustable and ergonomic models tailored to this age group, further supporting segment leadership.
The Geriatric segment held 25.6% of the market, driven by the growing elderly population, higher prevalence of osteoporosis, arthritis, balance disorders, and age-related mobility limitations. Older adults increasingly require mobility support following falls, joint replacement surgeries, and rehabilitation programs, contributing to sustained demand for comfortable and stable crutches.
The Pediatric segment accounted for 12.7% of the market, supported by the treatment of congenital orthopedic conditions, fractures, sports-related injuries, and post-operative rehabilitation among children. Pediatric crutches are specifically designed with lightweight materials, colorful finishes, and adjustable sizing to improve usability and comfort.
Ongoing advancements in ergonomic design and customized mobility solutions continue to enhance product adoption across all age groups.
Application Analysis
The Orthopedic Injuries segment dominated the Medical Crutches Market, capturing 28.4% of the market share in 2025. Orthopedic injuries, including fractures, ligament tears, sprains, dislocations, and post-traumatic conditions, represent the largest indication for crutch use worldwide.
Crutches play a critical role in reducing weight-bearing during recovery, promoting proper healing, and supporting rehabilitation after lower-limb injuries. Increasing sports participation, road traffic accidents, occupational injuries, and orthopedic surgical procedures continue to drive demand within this segment.
Other important applications include post-operative rehabilitation following hip, knee, ankle, and foot surgeries, where temporary mobility assistance is essential during recovery. Neurological disorders such as cerebral palsy, multiple sclerosis, and stroke also contribute significantly to market demand by requiring long-term ambulatory support.
Chronic musculoskeletal disorders, including arthritis and degenerative joint diseases, further expand the use of medical crutches among patients experiencing reduced mobility. Additionally, mobility assistance for elderly individuals with balance impairment and disability management remains an important application area.
Growing emphasis on early rehabilitation, outpatient orthopedic care, and home-based recovery programs is encouraging broader adoption of lightweight, ergonomic, and adjustable crutches across diverse clinical applications, supporting continued market growth.
End User Analysis
The Hospitals segment dominated the Medical Crutches Market, accounting for 34.7% of the market share in 2025. Hospitals remain the primary point of care for patients recovering from fractures, orthopedic surgeries, trauma, and emergency injuries, making them the largest purchasers of medical crutches.
Healthcare providers typically prescribe and fit crutches before patient discharge, ensuring proper sizing, training, and safe mobility during recovery. The increasing number of orthopedic procedures and trauma admissions continues to strengthen hospital demand.
Rehabilitation centers represent another significant end-user segment, where crutches are extensively utilized during structured physical therapy and post-surgical recovery programs. Ambulatory surgical centers also contribute to market expansion as more orthopedic procedures shift toward outpatient settings requiring short-term mobility support.
Home healthcare has emerged as a rapidly growing end-user category, driven by increasing preference for home-based rehabilitation, aging populations, and improved access to portable mobility aids. Retail pharmacies, medical equipment suppliers, and online distribution channels further support patient access to crutches for both temporary and long-term use.
Rising investments in rehabilitation services, expanding outpatient orthopedic care, and growing awareness regarding early mobility after injury continue to diversify end-user demand and reinforce sustained growth across the medical crutches market.
Market Segmentations
By Product Type
- Underarm Crutch
- Forearm Crutch
- Tetrapod Crutch
- Leg Support Crutch
- Others
By Material
- Aluminum
- Steel
- Carbon Fiber
- Composite Materials
- Wood
- Others
By Age Group
- Pediatric
- Adult
- Geriatric
By Application
- Orthopedic Injuries
- Fracture Management
- Post-Surgical Recovery
- Sports Injuries
- Neurological Disorders
- Mobility Assistance for Chronic Conditions
- Others
By End User
- Hospitals
- Orthopedic Clinics
- Rehabilitation Centers
- Ambulatory Surgical Centers (ASCs)
- Homecare Settings
- Others
Driver
Aging Related Falls and Fracture Driven Rehabilitation Demand for Crutch Utilization
Falls among older adults are a major structural driver of fracture related care and short cycle mobility support demand, directly translating demographic aging into repeat utilization of crutches and related rehabilitation devices.
According to the CDC, falls can lead to serious injuries such as fractures of the wrist, arm, ankle, and hip, while NIH data indicates that more than one in four adults aged 65 and older experiences a fall each year. WHO similarly identifies falls as a leading cause of injury related disability and loss of independence in older populations.
Clinically, these events frequently trigger post acute mobility impairment, where patients require immediate assistive devices during recovery. This creates recurring demand not only for standard axillary crutches, but also for replacement units, bariatric variants, and bundled discharge mobility kits used in hospital to home transitions.
In many cases, crutches serve as the first line mobility aid before progression to walkers or wheelchairs, extending their utilization across recovery phases. From a market perspective, this is a highly stable and non discretionary demand driver, particularly in regions with aging demographics such as North America, Europe, and Japan.
Higher fall incidence rates, combined with structured rehabilitation pathways and better access to orthopedic care, reinforce consistent device utilization.
Overall, the sustained rise in older adult falls and fracture incidence is estimated to contribute approximately 1.4% points of CAGR uplift in crutch and mobility aid markets, supported by predictable clinical recurrence and strong post acute care integration.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Aging-falls fracture rehabilitation demand | +1.4% | North America core, EU, Japan, urban APAC spill-over | Short term |
| Osteoarthritis and post-arthroplasty mobility support | +1.1% | U.S., Canada, Western Europe, Australia, advanced APAC | Medium term |
| Medicare/DME reimbursement and clinical prescribing stability | +0.9% | U.S. core, selective reimbursement-led spill-over in other developed markets | Short term |
| Ergonomic shift toward lower-exertion forearm and hybrid crutch designs | +0.8% | EU core, North America, rehab-focused APAC metros | Medium term |
| Home-care and outpatient recovery pathway expansion | +0.7% | U.S., UK, EU, higher-income APAC | Medium term |
| Aluminum and steel tariff-driven sourcing reset and premiumization | +0.5% | U.S. core, Mexico/Canada supply chain, export-dependent Asia | Short term |
Challenges
Supply Chain Variability in Mid Low End Crutch Markets
Supply chain variability in mid low end crutch segments reflects persistent instability in availability, quality, and delivery timelines, particularly in price sensitive emerging markets and public procurement systems.
These markets rely heavily on imported or semi localized manufacturing from a limited set of producing countries such as China, Thailand, Germany, Taiwan, and the United States, creating structural dependence on external supply cycles.
In practice, procurement lead times for basic mobility aids can fluctuate significantly, ranging from 4 weeks to 12 to 16 weeks, depending on shipping conditions, tender cycles, and customs clearance variability.
This inconsistency disrupts steady availability in public health programs and rural distribution networks, where demand is often episodic but urgent. Quality variability is another key constraint. Low end crutch models can exhibit 5 to 10 % rejection rates due to issues such as weld inconsistency, grip durability, or tip wear, while early life failure rates in some segments reach 3 to 5 % within the first year.
These quality issues reduce clinician confidence and encourage substitution toward higher cost, higher durability alternatives, indirectly suppressing mass market volume growth. Inventory inefficiencies further compound the problem.
Public procurement systems often alternate between shortages and oversupply due to delayed shipments, increasing inventory carrying costs by an estimated 5 to 7 % and reducing procurement efficiency.
Overall, these dynamics create a structural drag of approximately 0.9 % points on CAGR, as manufacturers must maintain higher safety stocks, manage fragmented supplier bases, and navigate inconsistent tender outcomes. Longer term stabilization depends on localization of components, stronger supplier qualification systems, and improved procurement standardization across public health networks.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Fragmented rehab pathways | -1.3% | North America, EU, urban APAC | Medium term (2-4 years) |
| Low device personalization | -1.0% | Global, especially aging hubs | Long term (≥ 4 years) |
| Training & usage adherence gap | -1.5% | North America, EU, emerging Asia | Medium term (2-4 years) |
| Supply chain variability mid–low end | -0.9% | APAC manufacturing, LATAM, Africa | Medium term (2-4 years) |
| Reimbursement & policy complexity | -1.7% | U.S., EU mixed-payer systems | Long term (≥ 4 years) |
| Clinical data & outcomes under-quantified | -0.8% | Global, research-led systems | Long term (≥ 4 years) |
Restraints
Raw Material and Logistics Cost Inflation in Crutch Manufacturing
Raw material and logistics cost inflation is a persistent structural restraint, reducing achievable CAGR by an estimated 1.3 % points through margin compression and constrained pricing flexibility in highly price sensitive mobility aid markets.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stricter device regulation & compliance load | -1.6% | EU core, US, China | Medium term (2-4 years) |
| Hospital & public procurement budget pressure | -1.4% | North America, EU, selected LATAM | Short–Medium term (≤ 4 years) |
| Raw material & logistics cost inflation | -1.3% | Global, especially import-dependent APAC & Africa | Short term (≤ 2 years) |
| Fragmented last-mile distribution & low reimbursement | -1.1% | India, wider APAC, Africa corridors | Long term (≥ 4 years) |
| Slow innovation & limited clinical differentiation | -0.9% | Global, more visible in mature OECD markets | Medium–Long term (≥ 3 years) |
| Demographic & prevention shifts moderating incident demand | -0.7% | Global, especially high-income OECD | Long term (≥ 4 years) |
Crutch manufacturing depends heavily on aluminium or steel tubing, polymer grips and tips, fasteners, and basic composite reinforcements, all of which have experienced sustained price volatility since 2021. Global aluminium prices, for example, Diabetes and Obesity Driven Expansion of Mobility Aid Utilization Through Integrated Chronic Care Programs
Integrating crutches and mobility aids into structured diabetes and obesity management programs represents a forward looking demand expansion opportunity, as current usage is still largely tied to acute orthopedic injury and age related degeneration rather than metabolic disease driven functional impairment.
Global diabetes prevalence has risen sharply from approximately 200 million in 1990 to over 830 million in 2022, with a disproportionate burden in low and middle income countries. A significant share of these patients develop complications such as peripheral neuropathy, foot ulcers, musculoskeletal decline, and obesity related joint stress, all of which contribute to reduced mobility and higher fall risk. However, mobility aids are not yet systematically integrated into chronic disease care pathways.
If structured care models in North America, Latin America, and selected EMEA emerging markets formally incorporated time limited crutch use for moderate to severe mobility impairment, and if even 3 to 5 percent of adults with diabetes received mobility support kits, this could translate into millions of incremental device deployments by 2035.
Each integrated episode could generate approximately USD 80 to 150 in crutch hardware revenue, plus an additional USD 50 to 100 in services, including physiotherapy, tele rehabilitation, and mobility coaching. This shifts crutches from episodic orthopedic devices into chronic disease management tools embedded within broader care budgets.
Given the scale of global diabetes related healthcare spending, this integration could drive a 5 to 8 percent uplift in demand across targeted regions, contributing approximately 1.5 percentage points of global CAGR upside versus baseline scenarios that assume purely injury driven utilization.
have shown quarterly swings of 15 to 25 percent, while plastics and resin inputs have also faced intermittent supply driven spikes. Because metals and polymers account for roughly 35 to 45 percent of ex factory cost, even a modest 10 percent increase in input prices can raise total unit manufacturing cost by 3 to 5 percent, which is difficult to pass through in tender driven or reimbursement constrained procurement systems.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stricter device regulation & compliance load | -1.6% | EU core, US, China | Medium term (2-4 years) |
| Hospital & public procurement budget pressure | -1.4% | North America, EU, selected LATAM | Short–Medium term (≤ 4 years) |
| Raw material & logistics cost inflation | -1.3% | Global, especially import-dependent APAC & Africa | Short term (≤ 2 years) |
| Fragmented last-mile distribution & low reimbursement | -1.1% | India, wider APAC, Africa corridors | Long term (≥ 4 years) |
| Slow innovation & limited clinical differentiation | -0.9% | Global, more visible in mature OECD markets | Medium–Long term (≥ 3 years) |
| Demographic & prevention shifts moderating incident demand | -0.7% | Global, especially high-income OECD | Long term (≥ 4 years) |
Opportunity
Diabetes and Obesity Driven Expansion of Mobility Aid Utilization Through Integrated Chronic Care Programs
Integrating crutches and mobility aids into structured diabetes and obesity management programs represents a forward looking demand expansion opportunity, as current usage is still largely tied to acute orthopedic injury and age related degeneration rather than metabolic disease driven functional impairment. Global diabetes prevalence has risen sharply from approximately 200 million in 1990 to over 830 million in 2022, with a disproportionate burden in low and middle income countries.
A significant share of these patients develop complications such as peripheral neuropathy, foot ulcers, musculoskeletal decline, and obesity related joint stress, all of which contribute to reduced mobility and higher fall risk. However, mobility aids are not yet systematically integrated into chronic disease care pathways.
If structured care models in North America, Latin America, and selected EMEA emerging markets formally incorporated time limited crutch use for moderate to severe mobility impairment, and if even 3 to 5 percent of adults with diabetes received mobility support kits, this could translate into millions of incremental device deployments by 2035.
Each integrated episode could generate approximately USD 80 to 150 in crutch hardware revenue, plus an additional USD 50 to 100 in services, including physiotherapy, tele rehabilitation, and mobility coaching. This shifts crutches from episodic orthopedic devices into chronic disease management tools embedded within broader care budgets.
Given the scale of global diabetes related healthcare spending, this integration could drive a 5 to 8 percent uplift in demand across targeted regions, contributing approximately 1.5 percentage points of global CAGR upside versus baseline scenarios that assume purely injury driven utilization.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Smart connected crutches ecosystems | +2.0% | North America, EU, urban APAC | Medium term (2-4 years) |
| Diabetes & obesity-focused mobility programs | +1.5% | North America, Latin America, EMEA LMICs | Short term (≤ 2 years) |
| Subscription-based home recovery bundles | +1.8% | North America core, EU, developed APAC | Medium term (2-4 years) |
| Low-cost crutch access in LMICs | +1.2% | Sub-Saharan Africa, South & SE Asia | Long term (≥ 4 years) |
| Post-acute care & insurer-integrated models | +2.3% | US, EU-5, Japan, Middle East | Medium term (2-4 years) |
| Robotics-assisted hybrid crutch platforms | +1.0% | North America, EU, high-income APAC | Long term (≥ 4 years) |
Regional Analysis
In 2025, North America led the market, achieving over 35.8% share with a revenue of US$ 245.3 Billion.
In 2025, North America region’s leadership is driven by a high prevalence of orthopedic disorders, sports-related injuries, and an expanding elderly population requiring mobility assistance following fractures, joint replacements, and age-related musculoskeletal conditions.
Strong healthcare infrastructure, favorable reimbursement policies, and widespread availability of advanced rehabilitation services further support market growth. Continuous product innovation, including lightweight aluminum and carbon-fiber crutches with ergonomic designs, has also strengthened adoption across hospitals, rehabilitation centers, and homecare settings.
Europe represented the second-largest regional market, supported by an aging demographic, rising incidence of osteoporosis, and well-established public healthcare systems that promote access to mobility aids. Increasing investments in rehabilitation programs and orthopedic care continue to stimulate demand across the region.
Meanwhile, the Asia-Pacific market is projected to witness the fastest growth during the forecast period, driven by expanding healthcare infrastructure, improving access to medical devices, growing awareness of rehabilitation services, and a large patient population in countries such as China, Japan, and South Korea.
Rising healthcare expenditure and increasing road accident cases further contribute to regional expansion. Latin America and the Middle East & Africa are also experiencing gradual market growth, supported by improving healthcare accessibility, expanding distribution networks, and government initiatives aimed at enhancing orthopedic and post-operative care, although these regions continue to face challenges related to affordability and uneven healthcare infrastructure.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The Medical Crutches Market is moderately fragmented, with competition shaped by a mix of global medical device manufacturers, rehabilitation specialists, and regional mobility solution providers. The market has reached a relatively mature stage in developed economies, while emerging regions continue to create expansion opportunities through improving healthcare infrastructure and rising demand for mobility assistance.
Competitive differentiation increasingly depends on ergonomic product design, lightweight materials, patient comfort, and compliance with evolving clinical rehabilitation standards. Manufacturers are also investing in advanced aluminum alloys, carbon-fiber components, adjustable support systems, and user-centric innovations that enhance mobility, durability, and long-term patient outcomes.
The competitive landscape can be categorized into three strategic tiers. Large multinational healthcare suppliers, including Cardinal Health, Medline Industries, Drive DeVilbiss Healthcare, and Invacare Corporation, leverage extensive distribution networks, diversified product portfolios, and established relationships with hospitals and rehabilitation centers.
Specialized mobility companies such as Sunrise Medical, Össur, Nova Medical Products, Karma Medical Products, and Amigo Mobility International focus on rehabilitation expertise, ergonomic engineering, and premium mobility solutions.
Innovation-oriented and niche manufacturers, including Millennial Medical, Ergoactives, Breg Inc., Performance Health, Vive Health, and GPC Medical Ltd., strengthen competition through specialized product development, targeted clinical applications, digital sales channels, and expanding presence in outpatient and homecare settings.
Competitive strategies emphasize continuous product innovation, investments in lightweight and adjustable crutch technologies, collaborations with rehabilitation providers, and portfolio expansion through new product launches.
Companies also compete by improving supply chain efficiency, strengthening regional distribution partnerships, integrating patient-centered design into product development, and expanding their presence across hospital, orthopedic, rehabilitation, and home healthcare ecosystems to sustain long-term market positioning.
Top Key Players
- Cardinal Health
- Medline Industries
- Sunrise Medical
- Invacare Corporation
- Drive DeVilbiss Healthcare
- Amigo Mobility International
- Nova Medical Products
- Össur
- Ergoactives
- Millennial Medical
- Karma Medical Products
- Breg Inc.
- Performance Health
- Vive Health
- GPC Medical Ltd.
Recent Developments
- In August 2025, Cardinal Health announced the acquisition of Solaris Health, a leading urology management services organization (MSO), further expanding its specialty physician services business.
- In November 2025, Cardinal Health completed the acquisition of Solaris Health, integrating more than 750 providers into its specialty care platform.
- In June 2025, Medline Industries unveiled Mpower™, an AI-enabled cloud-based digital supply chain control tower, with commercial release planned for early 2026, enhancing healthcare logistics and inventory management.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 685.1 Billion |
| Forecast Revenue (2035) | US$ 1,256.2 Billion |
| CAGR (2026-2035) | 6.3 % |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Underarm Crutch ,Forearm Crutch ,Tetrapod Crutch ,Leg Support Crutch ,Others) By Material (Aluminum, Steel ,Carbon Fiber ,Composite Materials ,Wood ,Others)By Age Group (Pediatric ,Adult ,Geriatric) By Application (Orthopedic Injuries ,Fracture Management ,Post-Surgical Recovery ,Sports Injuries ,Neurological Disorders ,Mobility Assistance for Chronic Conditions ,Others) By End User (Hospitals ,Orthopedic Clinics ,Rehabilitation Centers ,Ambulatory Surgical Centers (ASCs) ,Homecare Settings ,Others) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Cardinal Health ,Medline Industries ,Sunrise Medical ,Invacare Corporation ,Drive DeVilbiss Healthcare ,Amigo Mobility International ,Nova Medical Products ,Össur ,Ergoactives ,Millennial Medical ,Karma Medical Products ,Breg Inc., Performance Health ,Vive Health ,GPC Medical Ltd. |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








