


Report Overview
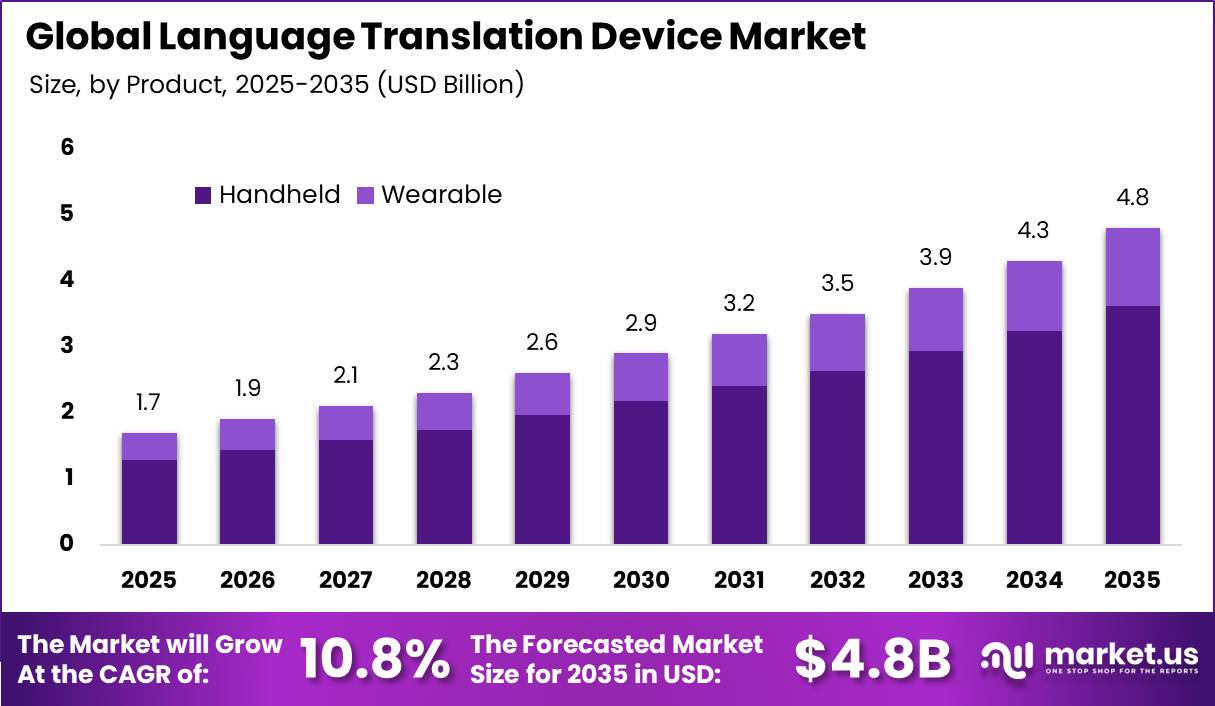
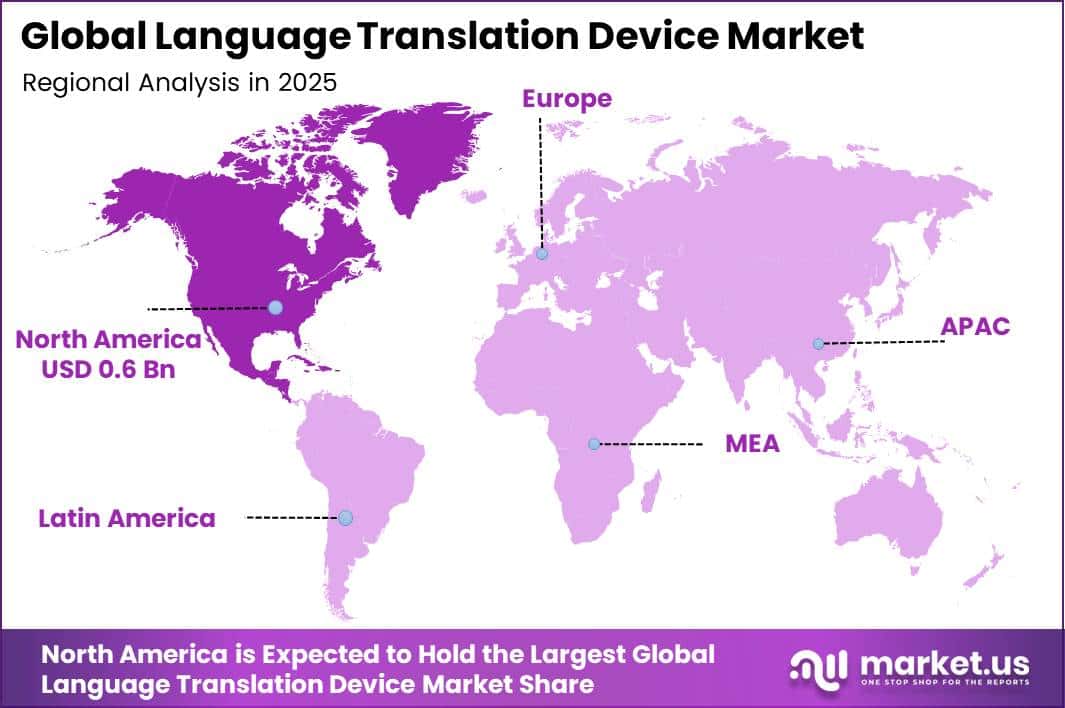
In 2025, the Global Language Translation Device Market was valued at USD 1.7 billion. The market is projected to grow at a CAGR of 10.8% during 2026–2035, reaching approximately USD 4.8 billion by 2035. North America dominated the global market in 2025, accounting for more than 35.3% of the total market share and generating approximately USD 0.6 billion in revenue.
Market growth is strongly supported by rising international travel, migration, education, and cross-border business activities. International tourist arrivals reached approximately 1.5 billion in 2025, around 60 million higher than in 2024. Europe alone welcomed about 793 million international visitors, while global tourism export revenues reached a record USD 2.2 trillion.
This increasing movement of travelers is creating strong demand for handheld, wearable, and app-based translation solutions that support real-time communication. In addition, the global stock of international migrants reached 302.1 million in 2023, while refugees and asylum seekers accounted for another 50.3 million people, supporting steady demand for language assistance across workplaces, healthcare facilities, schools, and public services.
Strong international business activity, tourism, immigration, and multilingual workplaces continue to support regional adoption. The United States remains a major destination for international migrants, increasing the need for real-time translation across healthcare, education, business, travel, and government services.
Key Takeaway
- The Language Translation Device Market was valued at USD 1.7 billion in 2025 and is projected to reach USD 4.8 billion by 2035 at a 10.8% CAGR.
- Handheld translators dominated the product segment with more than 75.4% share.
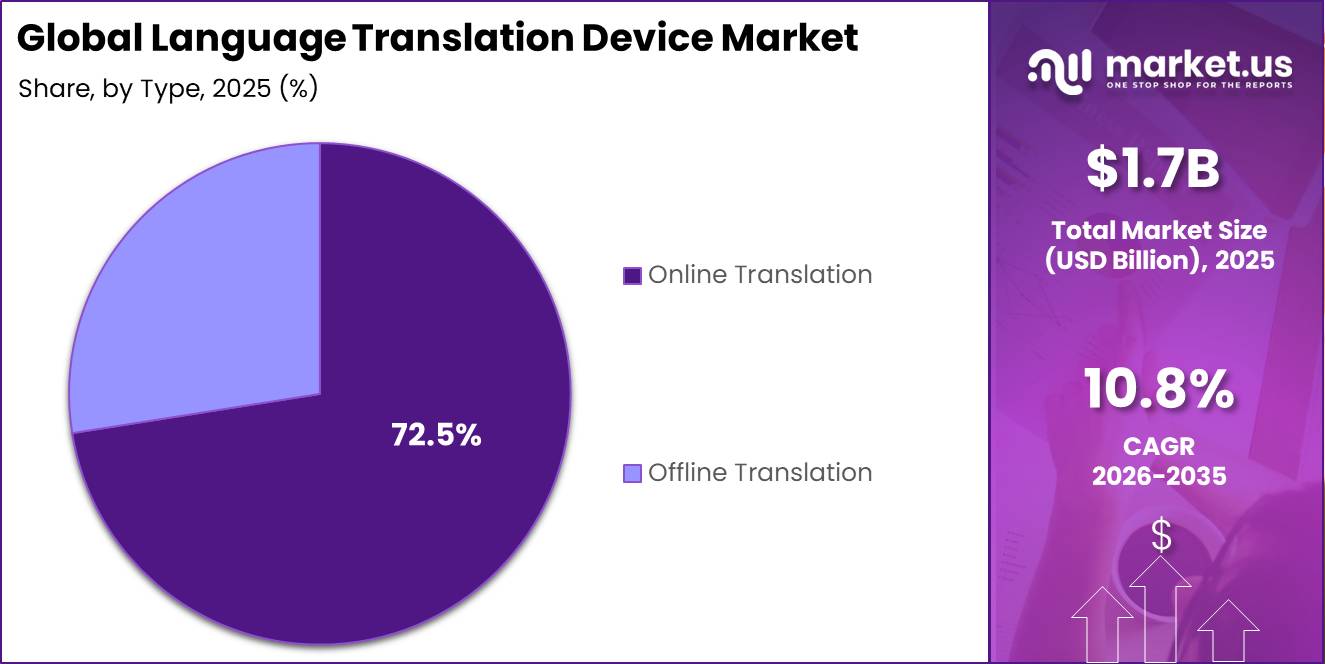
- Online translation led the type segment with more than 72.5% share, supported by rising global internet connectivity.
- Commercial applications held more than 63.1% share, driven by growing international trade and investment.
- Online platforms accounted for more than 68.8% of distribution channel share amid rising global e-commerce.
- North America led the market with more than 35.3% share, generating approximately USD 0.6 billion in revenue.
By Product
In 2025, Handheld Translators held a dominant position in the Language Translation Device Market, capturing more than 75.4% share. Their strong adoption is supported by the rapid growth of international passenger travel and the need for quick, real-time communication while people are on the move. Global passenger traffic reached approximately 9.8 billion trips in 2025, representing 3.7% year-on-year growth.
At the same time, international air passenger demand, measured in revenue passenger kilometers, increased by 7.1%, while December passenger load factors reached a record 83.6%. These high travel volumes create frequent language barriers at airports, hotels, customs counters, restaurants, taxis, and tourist destinations.
By Type
In 2025, Online Translation held a dominant position in the Language Translation Device Market, capturing more than 72.5% share. The segment benefits from the rapid expansion of global internet and mobile connectivity. Around 6 billion people were using the internet in 2025, up from 5.8 billion in 2024. The world also recorded approximately 9.2 billion mobile-cellular subscriptions and 99 mobile broadband subscriptions per 100 people.
This large connected population supports the use of cloud-based translation devices that access updated language models, vocabulary, and contextual information in real time. Online translation solutions can provide broader language coverage and regular software improvements without requiring users to store large language databases directly on their devices.
By Application
In 2025, the Commercial application segment held a dominant position in the Language Translation Device Market, capturing more than 63.1% share. Strong growth in international trade and cross-border investment is increasing the need for accurate multilingual communication across businesses. Global merchandise exports reached approximately USD 26.3 trillion in 2025, increasing by 7.2% year-on-year.
At the same time, global foreign direct investment reached around USD 1.6 trillion, with reported growth ranging from 6% to 14%, depending on the measurement approach. These large international business flows create regular demand for translation devices during contract discussions, supplier meetings, factory audits, trade exhibitions, customer support, and business negotiations.
By Distribution Channel
In 2025, Online Platforms held a dominant position in the Language Translation Device Market, capturing more than 68.8% share. The segment benefits from the rapid expansion of global e-commerce and digital purchasing channels. Global business e-commerce sales reached approximately USD 28 trillion in 2024 across 45 economies, which together represented around three-quarters of global GDP and exports.
At the same time, digitally deliverable services trade reached nearly USD 2.6 trillion, recording average annual growth of 12.3%. These strong digital commerce trends make online platforms an effective distribution channel for specialized translation devices, particularly for customers located far from physical electronics stores.
Key Market Segments
By Product
- Handheld
- Wearable
By Type
- Online Translation
- Offline Translation
By Application
- Consumer
- Commercial
By Distribution Channel
- Online Platforms
- Retail Stores
Geopolitical Impact Analysis
Rising U.S.-China trade tensions are increasing cost pressure across the Language Translation Device Market supply chain. Combined U.S. tariffs on certain Chinese-origin semiconductors can reach 87.5%, including a 12.5% base tariff, 50% Section 301 tariff, and 25% Section 232 tariff. General electronics can face tariffs of around 37.5%, raising procurement costs for processors, voice-recognition chips, and other electronic components used in handheld and wearable translators.
China’s export licensing rules introduced in April 2025 cover 7 heavy rare earth elements, including dysprosium, terbium, and yttrium. Exports of these materials have reportedly remained around 50% below pre-restriction levels, creating supply pressure for magnets used in speakers, microphones, and haptic components.
A further set of controls covering 5 additional elements, along with the 0.1% rule for certain foreign-made products containing Chinese-origin materials, has been suspended until November 10, 2026, leaving manufacturers exposed to future supply-chain uncertainty.
Despite these trade pressures, global merchandise trade volume increased by 4.6% in 2025. However, longer shipping routes and geopolitical disruptions continue to increase transportation costs and delivery times for electronics moving between Asian production centers and Western markets.
Regional Analysis
North America held a dominant position in the global Language Translation Device Market, capturing more than 35.3% share and generating approximately USD 0.6 billion in revenue. The region benefits from strong multinational business activity, international travel, and a large immigrant population, creating regular demand for translation devices across healthcare, education, government services, and corporate environments.
Asia Pacific is expected to be the fastest-growing region, supported by increasing tourism, digital connectivity, and international student mobility. International tourist arrivals in the region reached approximately 331 million in 2025, increasing 6% year-on-year, while North-East Asia recorded growth of 13%. Southeast Asia attracted around 144 million international visitors in 2025, representing a 13.4% increase and moving above its 2019 tourism level.
Digital adoption is also strengthening demand, with internet penetration across Asia Pacific expanding at an average annual rate of 10.7% since 2005, compared with the global rate of 8%. The region also accounts for nearly one-third of the world’s 7.3 million internationally mobile students, further supporting demand for real-time translation devices in education and everyday communication.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Drivers
| Driver | (~) % CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Multilingual service digitization | +2.2% | North America, Europe, Asia Pacific | Short term (2 years or less) |
| Enterprise cross-border workflows | +1.7% | Global | Short term (2 years or less) |
| Edge AI hardware adoption | +1.5% | East Asia, North America | Medium term (2 to 4 years) |
| Public-sector language access | +1.1% | North America, Western Europe | Medium term (2 to 4 years) |
| Travel retail device demand | +0.8% | Asia Pacific, Europe, Middle East | Short term (2 years or less) |
Multilingual service digitization
Multilingual service digitization is a strong growth driver for the Language Translation Device Market, as translation tools are increasingly used in healthcare, education, customer service, and public administration. In the U.S., 22% of people aged 5+speak a language other than English at home, while Census Bureau data covers more than 500 languages and language groups. Google also added 110 languages to Translate in 2024, increasing its total coverage to 243 languages.
Government language-access and digital-service requirements are further encouraging institutions to adopt real-time translation solutions. This shift is supporting recurring revenue from device-linked software, centralized fleet management, and enterprise licenses rather than only one-time hardware sales. Growing institutional procurement can also reduce customer acquisition costs for suppliers. Overall, multilingual service digitization could contribute an estimated +2.2% upside to the market’s baseline CAGR.
Restraints
| Restraint | (~) % CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| AI compliance cost burden | -1.8% | European Union, global exporters | Short term (2 years or less) |
| Consumer substitute pressure | -1.4% | Global | Short term (2 years or less) |
| Hardware import tariff exposure | -1.1% | North America, Europe | Medium term (2 to 4 years) |
| Low-cost device commoditization | -0.9% | Asia Pacific, Latin America | Short term (2 years or less) |
| Restricted procurement budgets | -0.7% | Public-sector buyers globally | Medium term (2 to 4 years) |
AI compliance cost burden
AI compliance is becoming a major restraint for the Language Translation Device Market, particularly for smaller manufacturers. The EU AI Act entered into force on 1 August 2024, while rules on prohibited AI practices and AI literacy became applicable on 2 February 2025. Requirements for general-purpose AI models followed on 2 August 2025, increasing documentation, risk-management, copyright, and supplier-monitoring obligations for cloud-connected translation solutions.
Compliance costs are higher for vendors that depend on third-party AI models and lack dedicated regulatory teams. EU governance and penalty provisions also became applicable from 2 August 2025, while certain existing general-purpose AI models have until 2 August 2027 to achieve compliance. Additional legal reviews, testing, localization, and regulatory support can increase operating costs and delay product launches. These pressures could create an estimated -1.8% drag on the market’s achievable CAGR.
Challenges
| Challenge | (~) % CAGR | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Rare-language accuracy gap | -1.6% | Global, emerging markets | Long term (4 years or more) |
| Component supply concentration | -1.2% | East Asia, North America, Europe | Medium term (2 to 4 years) |
| Cloud latency variability | -1.0% | Rural and lower-income markets | Medium term (2 to 4 years) |
| Speech data governance | -0.8% | Europe, North America, Asia Pacific | Long term (4 years or more) |
| Battery runtime trade-offs | -0.6% | Global | Medium term (2 to 4 years) |
Rare-language accuracy gap
Rare-language accuracy remains a major challenge for the Language Translation Device Market because reliable real-time translation requires large datasets covering speech, text, dialects, accents, and code-switching. Google added 110 languages in 2024, but more than 7,000 languages are spoken worldwide. The U.S. Census Bureau alone recognizes more than 500 languages and language groups, showing the complexity of providing consistent translation quality across different communities.
Limited digital access also slows improvement in low-resource languages. Around 2.2 billion people remained offline in 2025, reducing the amount of real-world language data available for cloud-based model training and feedback. Vendors therefore need long-term investment in local datasets, human evaluation, on-device learning, and offline translation capabilities.
Opportunities
| Opportunity | (~) % CAGR | Geographic Relevance | Execution Window |
|---|---|---|---|
| Regulated-sector device fleets | +2.0% | North America, Europe, Japan | Medium term (2 to 4 years) |
| Offline-first emerging markets | +1.6% | South Asia, Africa, Latin America | Long term (4 years or more) |
| Interpreter marketplace bundling | +1.3% | Global urban markets | Medium term (2 to 4 years) |
| Travel ecosystem partnerships | +1.0% | Asia Pacific, Europe, Middle East | Short term (2 years or less) |
| Accessibility procurement programs | +0.9% | North America, Western Europe | Medium term (2 to 4 years) |
Regulated-sector device fleets
Regulated sectors offer a strong untapped opportunity for language translation devices, as hospitals, courts, emergency services, and public agencies still rely heavily on individual purchases instead of centrally managed fleets. In the U.S., 22% of people aged 5+speak a language other than English at home, while the Census Bureau tracks more than 500 language categories, showing the need for flexible multilingual solutions.
Healthcare also provides a large institutional opportunity, with the World Health Organization representing 194 Member States. Managed device fleets could generate recurring software, security, and maintenance revenue instead of one-time hardware sales. Such models may improve gross margins by around 8%–15% and lower per-device support costs by nearly 20% through remote provisioning and centralized management.
Key Players Analysis
The Language Translation Device Market has a clear two-tier competitive structure. Tier-1 companies such as Google LLC and iFLYTEK compete through large AI platforms, strong R&D capabilities, and advanced translation technologies. In FY2025, iFLYTEK generated revenue of RMB 27.1 billion, increasing 16.1% year-on-year.
The company invested RMB 5.3 billion in R&D, equal to 19.79% of revenue, supporting upgrades to its Spark large model, speech recognition, and translation technologies. Its open-platform business generated RMB 6.09 billion, rising 17.72% year-on-year, and provides voice and translation APIs to third-party device manufacturers.
Tier-2 companies, including Cheetah Mobile, Pocketalk, Timekettle, Vasco Electronics, Langogo, Waverly Labs, and ECTACO, mainly compete through specialized hardware, wearable designs, and online distribution. In FY2025, Cheetah Mobile’s total revenue increased 42.6% to RMB 1,150.4 million, or approximately USD 164.5 million.
Its AI and Others segment grew 84.7% to RMB 535.2 million, representing 46.5% of total revenue compared with 35.9% in 2024. The segment also recorded a quarterly operating profit of RMB 3.9 million in Q3 2025, its first in 6 years, highlighting its shift toward AI-based services.
Top Key Players in the Market
- Google LLC
- iFLYTEK Co., Ltd.
- Pocketalk
- Vasco Electronics
- Langogo
- Cheetah Mobile Inc.
- Timekettle
- Waverly Labs
- ECTACO, Inc.
Recent Developments
- In 2025, Timekettle introduced its W4 AI Interpreter Earbuds at IFA in September and later showcased the product at GITEX Global in Dubai in October. Following the addition of Bengali, its translation coverage expanded to 43 languages and 96 accents, strengthening the product’s reach across international travel and cross-border communication applications.
- In 2025, iFLYTEK held synchronized product events in Shanghai and Dubai, introducing its third-generation AI simultaneous interpretation technology and new iFLYTRANS Headsets while upgrading the Dual-Screen Translator 2.0. The headsets support real-time interpretation across 60 languages, include more than 100,000 professional terms, and reduce Chinese-English first-sentence translation latency to around 2 seconds.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 1.7 Billion |
| Forecast Revenue (2035) | USD 4.8 Billion |
| CAGR (2026-2035) | 10.8% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product (Handheld, Wearable); By Type (Online Translation, Offline Translation); By Application (Consumer, Commercial); By Distribution Channel (Online Platforms, Retail Stores) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | Google LLC, iFLYTEK Co., Ltd., Pocketalk, Vasco Electronics, Langogo, Cheetah Mobile Inc., Timekettle, Waverly Labs, ECTACO, Inc. |
| Customization Scope | We will provide customization for segments and region/country levels. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited Users and Printable PDF) |









