


Key Findings at a Glance
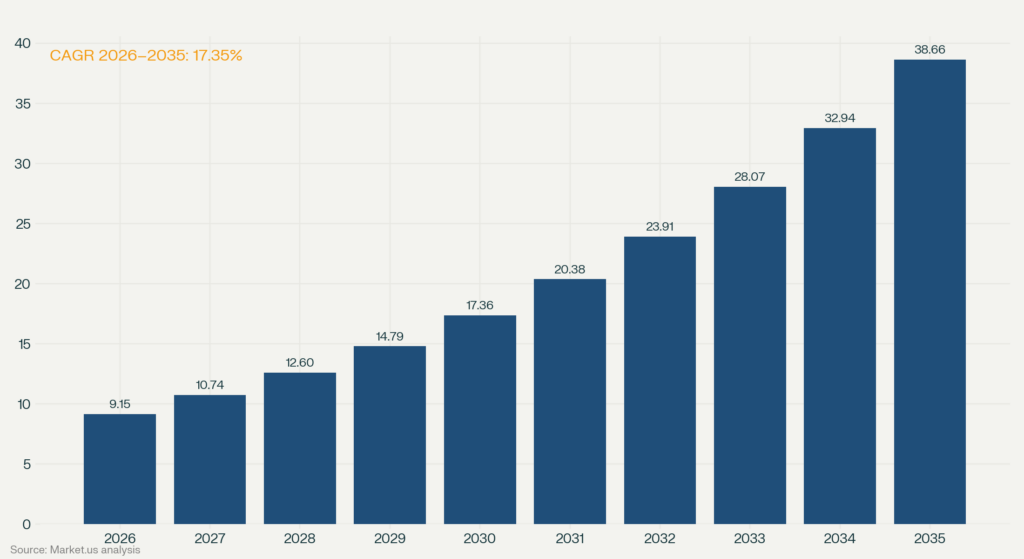
- Japan’s logistics automation market is estimated at USD 9.15 Billion in 2026 and is projected to reach USD 38.66 Billion by 2035, a CAGR of 17.35%.
- Japan’s logistics system equipment sales hit a record ¥657.0 billion in FY2024, up 3.8% (JILS).
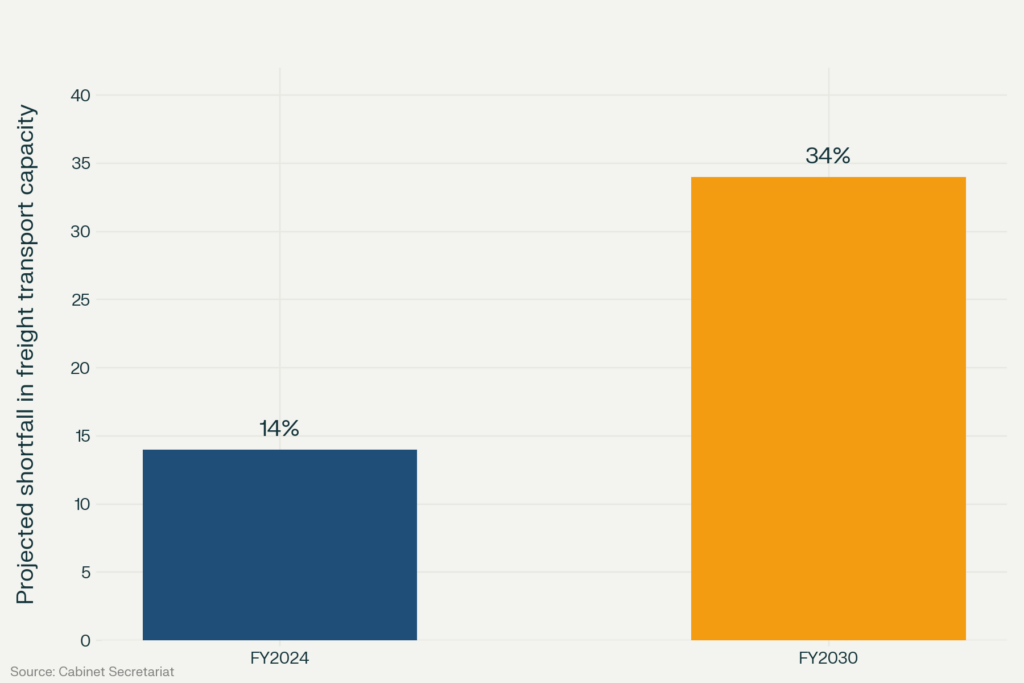
- Without action, Japan faces a freight transport capacity shortfall of about 14% in FY2024, rising to 34% by FY2030 (Cabinet Secretariat).
- From April 2026, large shippers handling 90,000 tonnes or more a year must appoint a Chief Logistics Officer (CLO) and submit efficiency plans.
- Software (21.5% CAGR), Transportation Management (20.5%), SMEs (20.4%) and Kyushu-Okinawa (21.0%) are the fastest-growing segments.
Market Overview
The Japan Logistics Automation Market is estimated at USD 9.15 Billion in 2026 and is projected to reach USD 38.66 Billion by 2035, growing at a CAGR of 17.35% over the forecast period.
Japan’s logistics automation sector is built on a strong robotics manufacturing base. According to the International Federation of Robotics (IFR), Japan had about 450,500 industrial robots in operation in 2024, up 3%, and installed 44,500 new units. That made Japan the world’s second-largest market for robot installations. This supplier base now supports wider warehouse automation.
Japanese industry body JILS reports that logistics system equipment sales reached a record ¥657.0 billion in FY2024, up 3.8%. This was the third year in a row above ¥600 billion. The 17.35% forecast CAGR reflects a long-term change in demand rather than a short-term upswing. Labour shortages, trucking limits and e-commerce growth are forcing warehouse operators to invest at scale. Logistics automation has moved from an optional upgrade to an operational necessity.
UNCTAD reports that global trade grew about 7.5% in 2025 to a record US$35 trillion. As a major exporter, Japan sees higher global trade feed directly into higher volumes in its domestic warehouses and distribution networks.
The market covers automated hardware, warehouse software and related services. Neighbouring sectors such as cold-chain distribution, port automation and transport between facilities connect closely to its growth.
Analyst insight: “There’s a clear gap between the forecast and recent hardware growth. JILS data shows logistics system equipment sales grew only 3.8% in FY2024. Our forecast needs hardware to grow about 15.6% a year. Regulation is the main reason we expect that acceleration. From April 2026, more than 3,000 large shippers must appoint a Chief Logistics Officer and submit efficiency plans to the government. At the same time, the projected freight capacity shortfall widens from 14% to 34% by FY2030. Automation stops being a budget choice and becomes a compliance and continuity requirement. Watch the JILS FY2025 and FY2026 figures as the first test of this forecast.”
— Research Team, Market.us
Market Definition
This report measures annual spending on logistics automation in Japan. It includes:
- Hardware: Mobile robots (automated guided vehicles, AGVs, and autonomous mobile robots, AMRs), automated storage and retrieval systems (AS/RS), sorting systems, palletising and de-palletising systems, conveyors, automatic identification and data collection (AIDC) equipment such as barcode and RFID systems, and order-picking systems.
- Software: Warehouse management systems (WMS), warehouse execution systems (WES) and transport management software.
- Services: Installation, integration, value-added services and maintenance.
The market excludes manual forklifts, general factory robots not used for logistics, and logistics labour costs.
Key Takeaways
- The market is valued at USD 9.15 Billion in 2026 and is expected to reach USD 38.66 Billion by 2035, at a CAGR of 17.35%.
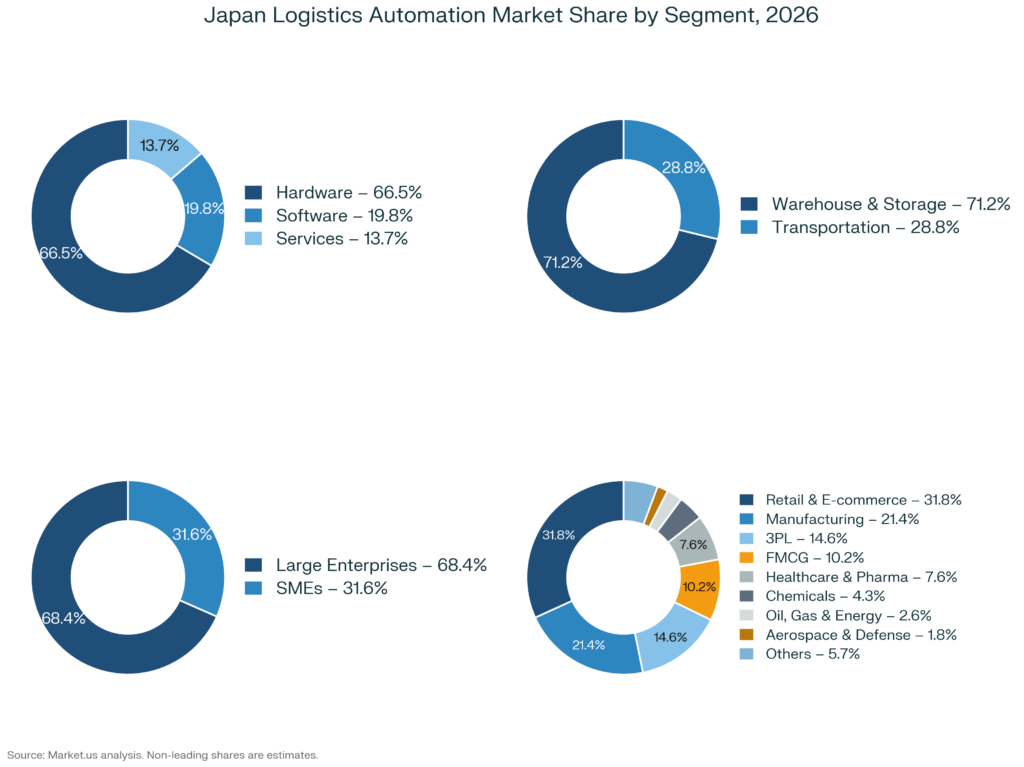
- By Component: Hardware led with a 66.5% share in 2026, and Software is the fastest-growing component.
- By Function: Warehouse and Storage Management led with a 71.2% share in 2026, and Transportation Management is the fastest-growing function.
- By Enterprise Size: Large Enterprises led with a 68.4% share in 2026.
- By Industry Vertical: Retail and E-commerce led with a 31.8% share in 2026.
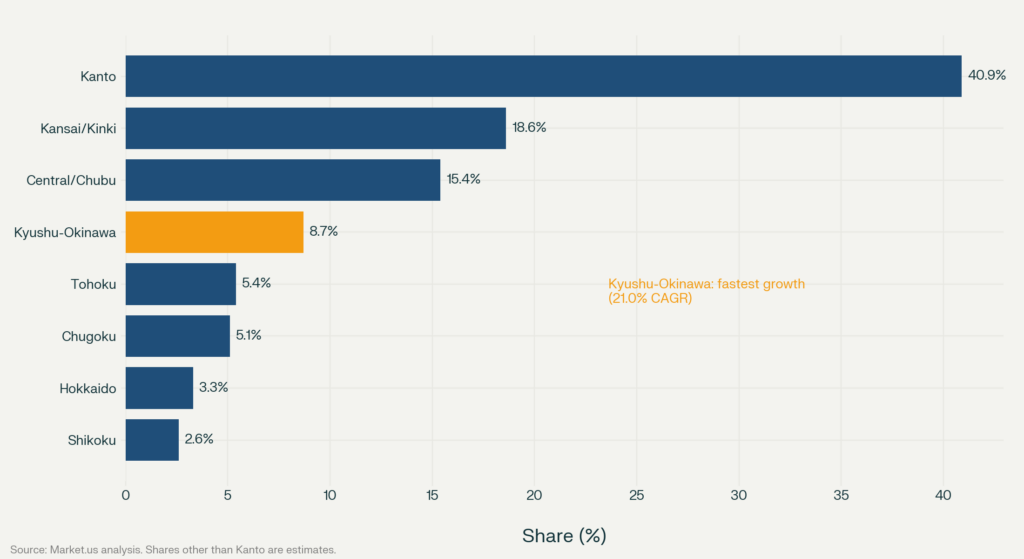
- By Region: Kanto led with a 40.9% share in 2026.
- Top 5 key players: Daifuku Co., Ltd., Murata Machinery, Ltd., Toyota Automated Logistics, Mitsubishi Logisnext Co., Ltd., and FANUC Corporation.
Key Market Statistics
| Indicator | Value | Source |
|---|---|---|
| Logistics system equipment sales, FY2024 | ¥657.0 billion (+3.8%, record) | JILS / JIMH |
| Logistics system equipment sales, FY2023 | ¥633.0 billion | JILS / JIMH |
| Number of equipment sales, FY2024 | 133,532 (+12.8%) | JILS / JIMH |
| Industrial robots in operation, 2024 | About 450,500 (+3%) | IFR |
| New industrial robot installations, 2024 | 44,500 (2nd in the world) | IFR |
| Projected freight capacity shortfall, FY2024 | About 14% (without action) | Cabinet Secretariat |
| Projected freight capacity shortfall, FY2030 | About 34% (without action) | Cabinet Secretariat |
| Trucking share of domestic freight | About 90% | JAL Cargo |
| Truck driver overtime cap (from April 2024) | 960 hours a year | Ministry of Health, Labour and Welfare |
| CLO rule threshold (from April 2026) | Shippers handling 90,000+ tonnes a year | MLIT |
| Global trade, 2025 | US$35 trillion (+7.5%) | UNCTAD |
| Average exchange rate, 2026 | ¥156.44 per USD | Market exchange rate data |
Research Methodology
How the Market Size Was Built
| Component (2026) | Basis | Value (¥ billion) | Value (USD Mn) |
|---|---|---|---|
| Logistics system equipment | JILS FY2024 sales of ¥657.0 billion, grown to 2026 at about 4% a year | 710.6 | 4,542.4 |
| AIDC, logistics robots and automated forklifts | Products not fully covered by JILS (est.) | 241.3 | 1,542.4 |
| Hardware subtotal | 951.9 | 6,084.8 | |
| Software (WMS, WES, transport management) | Vendor revenue estimates | 283.4 | 1,811.7 |
| Services (integration, maintenance, value-added) | Vendor revenue estimates | 196.1 | 1,253.5 |
| Total | 1,431.4 | 9,150.0 |
USD values use the 2026 average exchange rate of ¥156.44 per USD.
Forecast Approach
The 17.35% USD CAGR for 2026–2035 combines two drivers:
- Growth in yen (about 14.8% a year): Labour shortages, the April 2024 truck driver overtime cap, the April 2026 CLO and efficiency-plan requirements, e-commerce growth, and the move to software and subscription models.
- Yen recovery (about 2.2% a year): The forecast assumes the yen gradually strengthens from ¥156 per USD in 2026. At a constant exchange rate, the CAGR would be about 14.8%.
Segment and regional CAGRs are set above or below the national rate. They are balanced so that each segment adds up to the national forecast.
Data and Validation
- Top-down: JILS equipment sales, IFR robot data, Cabinet Secretariat freight projections and UNCTAD trade data were used to size the market.
- Bottom-up: Vendor results and announced projects were used to check the totals and segment trends.
- Modelled figures: Non-leading segment shares, regional shares other than Kanto, and all 2035 values and CAGRs are Market.us estimates. They are labelled as estimates throughout.
- Primary and expert validation: For this 2026 edition, findings were checked against first-hand statements from market participants published between April 2025 and April 2026. Analysts reviewed Daifuku’s results for the fiscal year ended 31 December 2025, including its orders by destination and its guidance. Analysts also reviewed 9 developments announced between April 2025 and April 2026, involving Yaskawa Electric, Mitsubishi Heavy Industries, Japan Industrial Partners, OMRON, Isuzu, Hino, Mitsubishi Fuso, UD Trucks, Daifuku and FANUC. These were used to validate technology, ownership and transport automation trends. Market assumptions were checked against the JILS FY2024 logistics system equipment statistics (published 4 September 2025), Cabinet Secretariat freight capacity projections, and the revised Physical Distribution Efficiency Act, fully in force from 1 April 2026.
How this report was produced: Market.us analysts collected and checked data from industry associations, government sources and company filings. AI tools assisted with drafting and formatting. All figures, analysis and conclusions were reviewed and approved by Research Team before publication.
| Segment | Category | 2026 Share | 2026 Value (USD Mn) | 2035 Value (USD Mn) | CAGR 2026–2035 |
|---|---|---|---|---|---|
| Component | Hardware | 66.5% | 6,084.8 | 22,386.5 | 15.57% |
| Component | Software | 19.8% | 1,811.7 | 10,453.8 | 21.50% |
| Component | Services | 13.7% | 1,253.5 | 5,819.7 | 18.60% |
| Function | Warehouse and Storage Management | 71.2% | 6,514.8 | 24,544.5 | 15.88% |
| Function | Transportation Management | 28.8% | 2,635.2 | 14,115.5 | 20.50% |
| Enterprise Size | Large Enterprises | 68.4% | 6,258.6 | 23,287.4 | 15.72% |
| Enterprise Size | SMEs | 31.6% | 2,891.4 | 15,372.6 | 20.40% |
| Industry Vertical | Retail and E-commerce | 31.8% | 2,909.8 | 12,616.5 | 17.70% |
| Industry Vertical | Manufacturing | 21.4% | 1,958.1 | 6,996.9 | 15.20% |
| Industry Vertical | 3PL | 14.6% | 1,335.9 | 6,790.2 | 19.80% |
| Industry Vertical | FMCG | 10.2% | 933.3 | 3,954.0 | 17.40% |
| Industry Vertical | Healthcare and Pharmaceuticals | 7.6% | 695.4 | 3,752.8 | 20.60% |
| Industry Vertical | Chemicals | 4.3% | 393.4 | 1,362.6 | 14.80% |
| Industry Vertical | Oil, Gas and Energy | 2.6% | 237.9 | 743.6 | 13.50% |
| Industry Vertical | Aerospace and Defense | 1.8% | 164.7 | 535.6 | 14.00% |
| Industry Vertical | Others | 5.7% | 521.5 | 1,907.8 | 15.50% |
Note: Leading Component and Function shares come from the Market.us model. Other shares, all 2035 values and all CAGRs are Market.us estimates.
Component Analysis
Hardware accounted for 66.5% of component demand in 2026, worth USD 6,084.8 Million, the highest of any category.
Hardware leads because transforming a warehouse in Japan requires heavy investment in equipment. AS/RS, conveyor networks and palletising systems form the physical backbone of high-volume fulfilment centres.
Japan’s deep robot base supports this. According to the IFR, the automotive sector installed 11,881 industrial robots in 2023, 26% of national installations. The electrical and electronics industry installed 14,692, and the metal and machinery sector 7,854. Mobile robots are the fastest-growing type of hardware, as operators prefer flexibility over fixed conveyor layouts.
Software is the fastest-growing component, at an estimated 21.5% CAGR. WMS and WES platforms add intelligence to existing hardware. Vendors that sell hardware first and add software upgrades later increase customer lifetime value and make it harder for customers to switch.
Function Analysis
Warehouse and Storage Management led the function segment with a 71.2% share in 2026, worth USD 6,514.8 Million.
Warehouse and storage management leads because Japan has invested first in automating fixed sites. Multi-level AS/RS, robotic picking cells and automated sorting all fall in this function and take most of the investment. Retail and e-commerce operators handling many different products (high-SKU operations) have the clearest return on investment.
Transportation Management is the fastest-growing function, at an estimated 20.5% CAGR, driven by Japan’s trucking capacity crisis. Carriers and third-party logistics (3PL) providers are using route-optimisation software and autonomous transport to move more goods with fewer drivers.
Autonomous trucks are getting closer to commercial use. In October 2025, Isuzu, Hino, Mitsubishi Fuso and UD Trucks began joint Level 4 autonomous truck tests on a 210 km section of the Shin-Tomei Expressway, aiming for driverless heavy trucks from 2026. The line between warehouse and transport is blurring, as integrated platforms link inventory visibility to last-mile dispatch in one system.
Enterprise Size Analysis
Large Enterprises led the enterprise size segment with a 68.4% share in 2026, worth USD 6,258.6 Million.
Large enterprises have the capital, IT systems and buying power to commit to automation across many sites. Japan’s major retailers, 3PL operators and manufacturers have moved beyond pilots to full rollouts across their distribution networks. The business case is strongest where labour costs are highest and volumes are most consistent. The revised Physical Distribution Efficiency Act adds pressure, as large shippers must now appoint a CLO and submit medium- to long-term efficiency plans.
SMEs are the fastest-growing segment, at an estimated 20.4% CAGR. Robotics-as-a-Service (RaaS) models, where customers rent robots for a monthly fee, are the main way to lower entry barriers, because they remove the need for large upfront investment. Vendors that turn SME pilots into long-term subscriptions will capture a segment that large players have mostly overlooked.
Industry Vertical Analysis
Retail and E-commerce led the industry vertical segment with a 31.8% share in 2026, worth USD 2,909.8 Million.
Retail and e-commerce operators face the sharpest combination of volume growth and labour shortage in Japan. Same-day and next-day delivery promises require warehouse speeds that manual picking cannot sustain. Automation in this vertical is driven by competitive need, not optional efficiency gains.
Healthcare and Pharmaceuticals is the fastest-growing vertical, at an estimated 20.6% CAGR. It needs precision and traceability, which favours software-integrated picking systems. 3PL providers (19.8% CAGR) multiply adoption across industries by deploying automation for many clients in shared warehouses. FMCG focuses on speed and volume in both ambient and temperature-controlled environments. Manufacturing, chemicals, energy and aerospace have more specialised, slower-growing needs.
Key Market Segments
By Component
- Hardware
- Mobile Robots (AGV, AMR)
- Automated Storage and Retrieval Systems (AS/RS)
- Automated Sorting Systems
- De-palletizing/Palletizing Systems
- Conveyor Systems
- Automatic Identification and Data Collection (AIDC)
- Order Picking
- Software (fastest growing)
- Warehouse Management Systems (WMS)
- Warehouse Execution Systems (WES)
- Services
- Value-Added Services
- Maintenance
By Function
- Warehouse and Storage Management
- Transportation Management (fastest growing)
By Enterprise Size
- Large Enterprises
- SMEs (fastest growing)
By Industry Vertical
- Retail and E-commerce
- Manufacturing
- Healthcare and Pharmaceuticals (fastest growing)
- Fast-Moving Consumer Goods (FMCG)
- 3PL
- Aerospace and Defense
- Oil, Gas and Energy
- Chemicals
- Others
Regional Analysis
| Region | 2026 Share | 2026 Value (USD Mn) | 2035 Value (USD Mn) | CAGR 2026–2035 |
|---|---|---|---|---|
| Kanto | 40.9% | 3,742.4 | 14,824.7 | 16.53% |
| Kansai/Kinki | 18.6% | 1,701.9 | 7,901.3 | 18.60% |
| Central/Chubu | 15.4% | 1,409.1 | 5,700.7 | 16.80% |
| Kyushu-Okinawa | 8.7% | 796.0 | 4,426.0 | 21.00% |
| Tohoku | 5.4% | 494.1 | 2,125.6 | 17.60% |
| Chugoku | 5.1% | 466.7 | 1,774.7 | 16.00% |
| Hokkaido | 3.3% | 301.9 | 1,095.9 | 15.40% |
| Shikoku | 2.6% | 237.9 | 811.1 | 14.60% |
| Total | 100% | 9,150.0 | 38,660.0 | 17.35% |
Note: Shares other than Kanto’s, and all CAGRs, are Market.us estimates.
Kanto Region
Kanto led with a 40.9% share in 2026, worth USD 3,742.4 Million.
Kanto has Japan’s largest concentration of distribution hubs, ports and e-commerce fulfilment centres in and around Greater Tokyo. According to Savills, Greater Tokyo was expected to add more than 1.4 million square metres of logistics floor space in the first half of 2025 alone. New warehouse space on this scale creates immediate demand for automated racking, sorting and picking systems from the day a facility opens. Japanese importers are also holding more inventory domestically to make supply chains more resilient, which adds to Kanto’s warehouse demand.
Kansai/Kinki Region
Greater Osaka anchors Kansai and is seeing Japan’s largest logistics property expansion outside Tokyo. According to Savills, Greater Osaka was expected to add a record 1.7 million square metres of logistics floor space in 2025, with nearly 900,000 square metres completed in the first half alone. New supply at this pace, without matching growth in available workers, makes automation a requirement for new facilities. Kansai is expected to grow at an estimated 18.6% CAGR.
Central/Chubu Region
Chubu’s demand comes mainly from car manufacturing. Toyota’s production network creates high-volume, precision-dependent logistics flows inside and between plants. AGVs and AS/RS in Chubu serve both factory floors and nearby distribution centres. The region’s industrial base provides reliable demand even when consumer e-commerce slows.
Kyushu-Okinawa Region
Kyushu-Okinawa is the fastest-growing region, at an estimated 21.0% CAGR. Manufacturing growth, semiconductor investment and better expressway links are pulling distribution infrastructure south. Regional 3PL providers face the same driver shortages as those in Kanto but have less existing automation. This creates an opportunity to build automated warehouse and transport operations from scratch.
Tohoku Region
Tohoku’s demand is shaped by post-disaster rebuilding and the slow growth of e-commerce fulfilment in its smaller cities. Cold-chain automation is especially relevant, given the region’s role in food processing and farm produce distribution. Operators serving Tohoku’s spread-out population face last-mile costs that favour automated sorting and routing.
Chugoku Region
Chugoku is a logistics corridor between Kansai and Kyushu, with distribution centres serving national networks. Automation here is driven mainly by 3PL providers streamlining hub operations rather than by retail demand. Improving efficiency, not volume growth, is the main reason to invest.
Hokkaido Region
Hokkaido’s adoption is limited by distance, low population density and an economy based on farming and fishing. Cold-chain handling and food-processing automation are the most relevant categories. National operators invest selectively, focusing on consolidation hubs rather than spreading automation widely.
Shikoku Region
Shikoku is the smallest of Japan’s eight regional markets, reflecting its limited industrial base and population. Bridges to Honshu have improved supply chain links, creating modest demand for sorting and transport management automation. Growth will stay below the national average unless industrial investment changes significantly.
Macroeconomic Impact
Japan’s logistics automation market faces a weak yen, high energy import costs and tighter fiscal policy. According to Savills, logistics property transactions in the first half of 2025 were 42% lower than a year earlier. Rising financing costs are slowing property deals, even as demand for warehouse space ready for automation grows. Operators are prioritising efficiency-driven automation over building new facilities.
Global shipping adds a second layer of pressure. UNCTAD data shows global maritime trade grew just 2.2% in 2024, with only 0.5% growth projected for 2025, well below the ten-year average. Ships taking longer routes to avoid disruptions pushed global shipping ton-miles up 5.9% in 2024, which raised costs for Japanese importers. UNCTAD expects maritime trade to recover to about 2% a year from 2026 to 2030, which would support steady volumes through Japan’s distribution network.
Market Dynamics
Driver: Labour Shortages and Trucking Limits Force Automation at Scale
Japan’s logistics workforce is shrinking. The Cabinet Secretariat projected a freight transport capacity shortfall of about 14% in fiscal 2024 without countermeasures, rising to about 34% by fiscal 2030. Trucks carry about 90% of Japan’s freight, according to JAL Cargo, so any loss of trucking capacity affects the whole national supply chain. Automation is the only option large enough to make up for the shrinking workforce.
Since April 2024, truck drivers’ overtime has been capped at 960 hours a year, which limits how much each driver can carry. Japan already had 435,299 industrial robots in operation in 2023, according to the IFR, so it has the supplier base and engineering skills to deploy automation quickly. Digital logistics platforms that combine dispatch, route optimisation and autonomous vehicle coordination are becoming a priority for carriers of all sizes.
Restraint: High Costs and Old Warehouses Slow SME Adoption
High upfront costs create a gap between large enterprises and smaller operators. Japan installed 46,106 industrial robots in 2023, down 9%, according to the IFR. This shows that yearly purchasing swings when financing gets tighter, even when long-term demand is strong. According to Mitsui Global Strategic Studies Institute, Japan risked losing about 400 million tonnes of trucking capacity, around 14% of the total, by 2025 without corrective action. Smaller operators still didn’t invest in proportion to that risk, because payback periods are too long without access to structured financing.
Older urban warehouses add complexity that standard automation products can’t easily handle. When WMS, enterprise resource planning (ERP) and transport management systems run on incompatible platforms, integration takes longer and projects become riskier. Vendors that can’t offer modular systems suited to existing (brownfield) sites lose deals to more flexible competitors, even when their core technology is better.
Opportunity: RaaS and Cold-Chain Automation Open New Markets
Mitsui estimates that 940 million tonnes of trucking capacity, matching the 34% shortfall, could be at risk by 2030. Last-mile automation addresses the bottleneck at the final delivery stage. This includes autonomous transport between facilities and robotic sorting at regional hubs.
RaaS changes the market by turning large upfront investments into monthly operating costs. Cold-chain automation is a distinct growth area. Food distribution, pharmaceutical logistics and convenience store restocking all have temperature requirements that make manual work costly and error-prone. Vendors entering these niches with purpose-built systems face less competition than in standard warehouses.
Porter’s Five Forces
| Force | Level | Explanation |
|---|---|---|
| Threat of new entrants | Low to moderate | High capital needs, long sales cycles and the need to work with existing Japanese warehouse systems protect incumbents such as Daifuku and Murata Machinery. Well-funded foreign entrants can still compete on software and AI |
| Supplier power | Moderate | Japan has a deep domestic supply chain for chips, servo motors and sensors |
| Buyer power | Rising | Large clients combine purchasing and demand integrated hardware, WMS and transport management rather than single products |
| Threat of substitutes | Low | Manual labour at scale is no longer realistic, though simpler conveyors and AIDC compete at the low end |
| Competitive rivalry | High | The top five to eight players compete hard on technology. Price pressure is stronger in software and services than in complex hardware, where switching costs are high |
AI and Gen AI Impact
AI is changing Japan’s logistics automation most visibly at the warehouse orchestration layer. AI-powered WES platforms assign tasks across AMR fleets, picking robots and human workers in real time, which raises output without adding equipment. Japanese vendors such as FANUC and Omron have built machine-vision AI into robot arms that can handle irregular items that older rule-based systems couldn’t. Operators still using fixed conveyors and manual picking face rising labour cost disadvantages every year.
Generative AI is entering through demand forecasting, inventory placement and maintenance scheduling. Predictive maintenance models trained on sensor data from AS/RS and conveyors reduce unplanned downtime. This matters in 24-hour “dark warehouses” (fully automated warehouses that run with almost no staff), where one system failure can stop all operations. Companies that delay AI adoption also risk losing the software engineers that next-generation logistics vendors are competing to hire.
Market Trends
Dark Warehouses and Integrated Autonomous Systems
Dark warehouses, which combine AS/RS, AMR fleets and robotic picking for 24-hour operation with almost no staff, are moving from showcase projects to commercial targets. UNCTAD reports that global goods trade grew about 7% in 2025, adding roughly US$1.8 trillion, while services trade grew about 8%. Rising trade is loading Japan’s distribution network faster than manual-plus-conveyor setups can handle. Platforms that combine AS/RS control, AMR fleet management and WES orchestration make dark warehouses possible, and vendors offering this full stack are winning the highest-value contracts.
Regulation Turns Logistics into a Boardroom Issue
The revised Physical Distribution Efficiency Act took full effect on 1 April 2026. Shippers handling 90,000 tonnes or more a year must appoint a CLO from senior management, submit medium- to long-term efficiency plans and report every year. Companies that don’t comply can be named publicly and fined up to ¥1 million. Logistics automation is moving from an operations budget line to a board-level strategy.
Ownership Changes Reshape the Supplier Base
Japan’s material handling sector is consolidating. Japan Industrial Partners completed its tender offer for Mitsubishi Logisnext in February 2026, taking Japan’s forklift and logistics equipment maker private and separating it from Mitsubishi Heavy Industries. Private ownership gives suppliers more freedom to invest in automation and to pursue mergers and acquisitions.
Market Competition Overview
The market is moderately concentrated at the top. A few Japanese groups hold large shares thanks to deep integration skills and decades of installed customers. Daifuku and Murata Machinery lead through complete system delivery covering AS/RS, conveyors and WMS, which makes switching costly for customers. Japan was the world’s second-largest market for industrial robots in 2024, with 44,500 installations, according to the IFR. Automotive robot stock reached 132,766 units in 2023, up 3%, which shows how deeply incumbent vendors are embedded in related industrial markets.
According to company filings, FANUC reported net sales of ¥857.8 billion in fiscal 2025, up 7.6%. Foreign players including KION Group, Swisslog and Dematic compete mainly through software platforms and RaaS rather than hardware scale. They target enterprise clients frustrated by the complexity of integrating Japan-specific systems. Challengers will gain share mainly in software-led deals, where integration risk is lower and buying decisions are faster.
Analyst insight: “Japan’s market leader is less dominant at home than many assume. Daifuku had sales of ¥660.7 billion in 2025, but only ¥182.0 billion, 27.5%, came from Japan. That is about 19% of Japan’s estimated ¥951.9 billion hardware market in 2026. Most of Daifuku’s growth comes from overseas semiconductor, cleanroom and airport projects. This leaves real room in Japan’s domestic market for Murata Machinery, Toyota’s logistics businesses, Okamura and newer players such as Rapyuta Robotics and Mujin, especially in SME and software-led deals.”
— Research Team, Market.us
Competitive Benchmarking
| Company | Key Metric | Value | Growth | Data As Of |
|---|---|---|---|---|
| Daifuku | Net sales | ¥660.7 billion | +2.6% | FY ended 31 Dec 2025 |
| Daifuku | Operating income | ¥100.8 billion (15.3% margin) | +24.4% | FY ended 31 Dec 2025 |
| Daifuku | Japan sales | ¥182.0 billion (27.5% of total) | — | FY ended 31 Dec 2025 |
| FANUC | Net sales | ¥857.8 billion | +7.6% | Fiscal 2025 |
| OMRON | Consolidated net sales | ¥801.8 billion | — | FY ended Mar 2025 |
| Yaskawa Electric | Consolidated revenue | ¥537.7 billion | — | FY ended Feb 2025 |
Company Profiles
Daifuku Co., Ltd.
Daifuku is Japan’s largest logistics automation systems integrator. Its advantage is complete project delivery, from engineering design through AS/RS installation and conveyor integration to lifetime maintenance contracts. In the fiscal year ended 31 December 2025, net sales reached a record ¥660.7 billion, up 2.6%, and operating income rose 24.4% to ¥100.8 billion. Growth came from intralogistics and cleanroom systems. Orders reached ¥672.6 billion, up 3.0%. Its work across automotive, semiconductor and e-commerce customers spreads revenue across industry cycles. Its installed base in Kanto and Chubu provides recurring service revenue that hardware-only competitors cannot easily match.
Mitsubishi Logisnext Co., Ltd.
Mitsubishi Logisnext makes forklifts, automated guided forklifts and logistics systems. In February 2026, Japan Industrial Partners completed a tender offer to take the company private, and Mitsubishi Heavy Industries is exiting its stake. Before the deal, MHI’s Logistics, Thermal & Drive Systems segment, which included Logisnext, recorded fiscal 2024 orders of ¥1,330.5 billion and revenue of ¥1,307.1 billion. As a private company, Logisnext has more freedom to invest in automated forklifts and integrated warehouse systems.
OMRON and Yaskawa Electric
OMRON reported consolidated net sales of ¥801.8 billion for the year ended March 2025. Its industrial automation and robotics businesses supply the sensing and control layers of warehouse systems. Yaskawa Electric reported consolidated revenue of ¥537.7 billion for the year ended February 2025. Its motion control and robotics platforms are used in sorting, palletising and picking systems across Japan’s major distribution centres.
Key Players
- Daifuku Co., Ltd.
- Murata Machinery, Ltd.
- Toyota Automated Logistics
- Mitsubishi Logisnext Co., Ltd.
- Rapyuta Robotics Co., Ltd.
- Hacobu Inc.
- FANUC Corporation
- Yaskawa Electric Corporation
- Kawasaki Heavy Industries, Ltd.
- Denso Corporation
- Mujin, Inc.
- Omron Corporation
- Okamura Corporation
- Hitachi, Ltd.
- Toyota Industries Corporation
- Toshiba Corporation
- Honeywell International Inc.
- KION Group AG
- Swisslog
- Dematic
Pricing Analysis
Pricing depends on system complexity, how much integration is needed and contract length:
- AS/RS installations: Large projects carry the highest prices, and multi-year maintenance contracts add well beyond the hardware cost.
- WMS and WES software: Pricing is moving from one-time perpetual licences to annual subscriptions. This lowers upfront revenue for vendors but makes revenue more predictable and keeps customers longer.
- Mobile robots: Prices face moderate downward pressure as more Japanese and Chinese makers enter the AMR market.
- Precision robotic picking systems: Prices stay high because of the machine-vision AI built into them.
RaaS adds a third pricing tier, below outright purchase and traditional leasing. Monthly per-robot fees shift maintenance risk to the vendor and give operators costs that rise and fall with volumes. Vendors that price RaaS competitively for SMEs and protect margins with service bundles are building subscription revenue that one-off hardware contracts can’t match.
Supply Chain and Value Chain Analysis
The supply chain begins with makers of servo motors, sensors, semiconductors and structural steel, who supply robot and system builders. Japanese suppliers such as Yaskawa, Omron and Denso hold the highest-value positions, making the motion control and sensing parts that determine system performance. System integrators, led by Daifuku and Murata Machinery, add value through engineering design, software integration and project management, turning components into working systems. End users in retail, e-commerce and manufacturing receive not just hardware but ongoing WMS licences, maintenance and upgrades.
The biggest bottleneck is connecting automation hardware to companies’ IT systems. Operators running SAP or older WMS platforms often face six– to eighteen-month integration projects before new systems reach full output. Vendors that reduce this risk with ready-made connectors, standard APIs and dedicated integration teams turn this pain point into a reason to charge premium prices.
Regulatory Landscape
Japan’s rules for logistics automation combine labour law, industrial safety standards and government digital policy:
- Truck driver overtime cap: Since April 2024, truck drivers’ overtime has been capped at 960 hours a year. This created an immediate compliance need and sped up automation purchases across carriers.
- Revised Physical Distribution Efficiency Act: Fully in force since 1 April 2026, it requires shippers handling 90,000 tonnes or more a year to appoint a CLO, submit medium- to long-term efficiency plans and report every year. For fiscal 2026 only, the deadline to submit plans has been extended to the end of October. Companies that don’t comply risk being named publicly and fined up to ¥1 million.
- Logistics digitalisation (DX) guidelines: MLIT has published guidelines that encourage digital dispatch, automated sorting and autonomous transport as part of national freight reform.
- Safety certification: AMRs and autonomous vehicles working alongside people must meet ISO 3691-4 and related Japanese Industrial Standards (JIS). This adds pre-deployment testing but protects operators from liability.
Government subsidy programmes under the Green Innovation Fund and Society 5.0 policy direct money towards smart manufacturing and logistics automation. Operators whose projects qualify can access subsidised financing that shortens payback periods. Foreign vendors must meet Japanese product certification rules, which differ from CE or UL standards. This raises entry costs and favours established distributors over companies entering directly.
Investment and White Space Analysis
Investment is concentrated in three areas:
- Large AS/RS installations for e-commerce fulfilment.
- AMR fleets for warehouses handling many different products.
- WMS and WES software integration.
Kanto and Kansai take most of the investment because of their dense logistics infrastructure. Kyushu-Okinawa’s fast growth shows southern Japan becoming a credible second-tier destination for 3PL providers looking for cheaper land and better transport links.
There are two main white spaces: SME warehouse automation and automated cold-chain systems. SMEs run most of Japan’s warehouses but account for a minority of automation spending. RaaS providers offering right-sized AMR fleets and subscription WMS can win lasting revenue from this underserved group. Cold-chain automation for pharmaceutical, food and convenience store distribution is the highest-margin white space. Multi-temperature environments are complex to engineer, so few vendors qualify, and prices stay high.
Analyst View
- Regulation is now the main catalyst. The April 2024 overtime cap and the April 2026 CLO rule turn automation from an option into a requirement.
- The forecast needs hardware growth to accelerate from 3.8% (FY2024, JILS) to about 15.6% a year, so JILS data for FY2025 and FY2026 will be the key test.
- Software (21.5% CAGR) and Transportation Management (20.5% CAGR) will grow fastest as warehouses and trucks are linked on one platform.
- SMEs (20.4% CAGR) are the biggest untapped group, and RaaS is the way to reach them.
- Kyushu-Okinawa (21.0% CAGR) offers the strongest regional growth, supported by semiconductor investment and new logistics hubs.
Recent Developments
- April 2026: FANUC reported fiscal 2025 net sales of ¥857.8 billion, up 7.6%, reflecting demand for its CNC systems and industrial robots in factory and warehouse automation.
- 1 April 2026: The revised Physical Distribution Efficiency Act took full effect. Shippers handling 90,000 tonnes or more a year must now appoint a CLO and submit efficiency plans.
- 18 February 2026: Japan Industrial Partners completed its tender offer for Mitsubishi Logisnext, taking the company private. Mitsubishi Heavy Industries is exiting its stake.
- 12 February 2026: Daifuku reported record net sales of ¥660.7 billion (+2.6%) and operating income of ¥100.8 billion (+24.4%) for the year ended December 2025.
- 21 October 2025: Isuzu, Hino, Mitsubishi Fuso and UD Trucks began joint Level 4 autonomous truck tests on a 210 km section of the Shin-Tomei Expressway, aiming for driverless heavy trucks from 2026.
- October 2025: OMRON reported consolidated net sales of ¥801.8 billion for the year ended March 2025 across its industrial automation and control businesses.
- 30 September 2025: Mitsubishi Logisnext announced support for Japan Industrial Partners’ planned tender offer to acquire all its shares and take it private.
- May 2025: Mitsubishi Heavy Industries reported fiscal 2024 orders of ¥1,330.5 billion and revenue of ¥1,307.1 billion for its Logistics, Thermal & Drive Systems segment.
- April 2025: Yaskawa Electric reported consolidated revenue of ¥537.7 billion for the year ended February 2025, with motion control and robotics as core revenue sources.
Report Scope
| Report Characteristics | Details |
|---|---|
| Market Value (2026) | USD 9.15 Billion |
| Forecast Revenue (2035) | USD 38.66 Billion |
| CAGR (2026 to 2035) | 17.35% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020 to 2024 |
| Forecast Period | 2026 to 2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Component (Hardware, Software, Services), By Function (Warehouse and Storage Management, Transportation Management), By Enterprise Size (Large Enterprises, SMEs), By Industry Vertical (Retail and E-commerce, Manufacturing, Healthcare and Pharmaceuticals, FMCG, 3PL, Aerospace and Defense, Oil Gas and Energy, Chemicals, Others) |
| Regions Covered | Kanto, Kansai/Kinki, Central/Chubu, Kyushu-Okinawa, Tohoku, Chugoku, Hokkaido, Shikoku |
| Competitive Landscape | Daifuku Co. Ltd., Murata Machinery Ltd., Toyota Automated Logistics, Mitsubishi Logisnext Co. Ltd., Rapyuta Robotics Co. Ltd., Hacobu Inc., FANUC Corporation, Yaskawa Electric Corporation, Kawasaki Heavy Industries Ltd., Denso Corporation, Mujin Inc., Omron Corporation, Okamura Corporation, Hitachi Ltd., Toyota Industries Corporation, Toshiba Corporation, Honeywell International Inc., KION Group AG, Swisslog, Dematic |
| Customization Scope | Customization for segments and region or country level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | Three license options: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited Users and Printable PDF) |








