


Market Overview
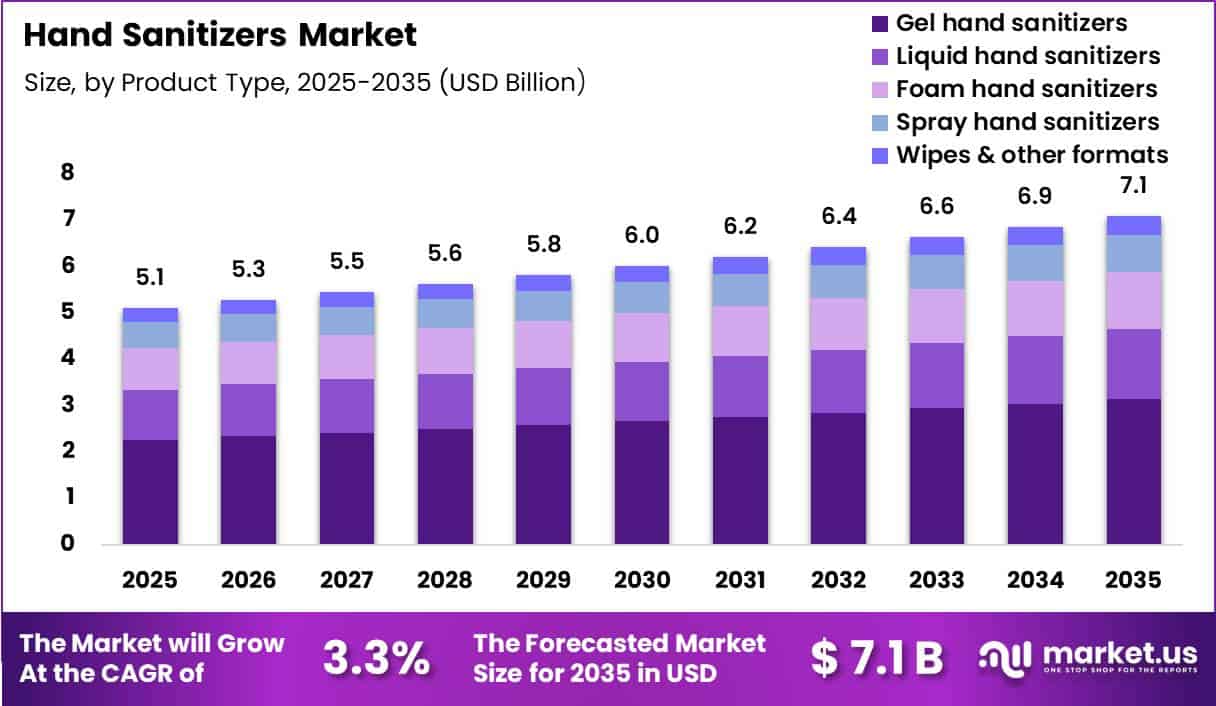
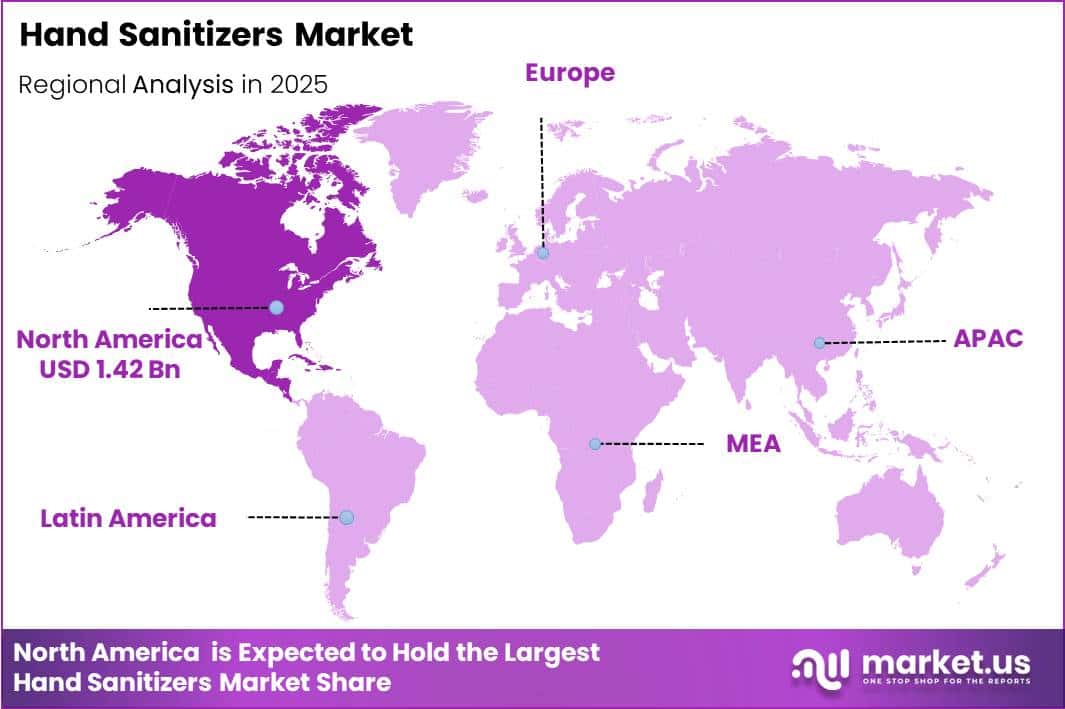
The Global Hand Sanitizers Market size is expected to be worth around US$ 7.1 Billion by 2035 from US$ 5.1 Billion in 2025, growing at a CAGR of 3.3% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 27.7% market share with revenue of US$ 1.42 Billion.
The global Hand Sanitizers Market is witnessing sustained growth driven by increasing awareness of hand hygiene, infection prevention practices, and the expanding use of sanitizing products across healthcare, commercial, and household environments. Hand sanitizers have become an essential hygiene solution, particularly in hospitals, clinics, schools, workplaces, transportation facilities, and public spaces where quick and convenient hand disinfection is required.
According to the Centres for Disease Control and Prevention (CDC), alcohol-based hand sanitizers containing at least 60% alcohol can help reduce the spread of germs when soap and water are not available. The CDC also highlights that sanitizers with 60–95% alcohol concentration are more effective against a broad range of microbes compared with lower-alcohol or non-alcohol formulations.
The healthcare sector remains a major application area, as hand hygiene is a critical component of infection control programs. The World Health Organisation (WHO) recommends alcohol-based hand rub formulations containing ethanol or isopropyl alcohol along with supporting ingredients such as glycerol and hydrogen peroxide for effective hand hygiene practices.
Rising healthcare-associated infection prevention initiatives, increased adoption of automatic sanitizer dispensers, and growing consumer preference for portable hygiene products are supporting market expansion. Regulatory agencies, including the U.S. Food and Drug Administration (FDA), classify hand sanitizers as over-the-counter drug products and regulate their active ingredients and manufacturing standards.
Future growth opportunities are expected from innovations in skin-friendly formulations, alcohol-based gels, foam sanitizers, sustainable packaging, and smart dispensing technologies across healthcare and public infrastructure sectors.
Key Takeaways
- Market Size: The Global Hand Sanitizers Market size was US$ 5.1 billion in 2025. The market is estimated to grow to US$ 7.1 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 3.3%.
- Product Type: Gel Hand Sanitizers has the largest market share, accounting for 44.3% of total product type revenue.
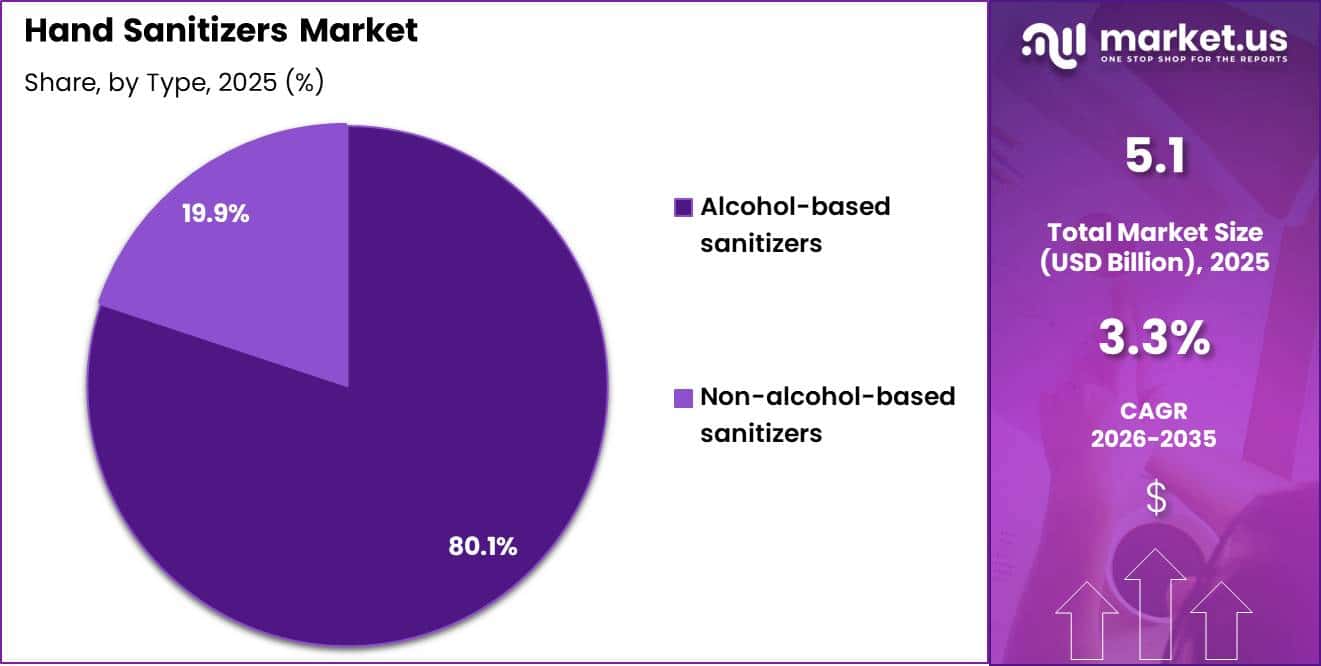
- Formulation: Alcohol-Based Sanitizers dominates the segment, accounting for 80.1% of total formulation revenue.
- Distribution Channel: Hypermarkets & Supermarkets leads the segment, accounting for 38.9% of total distribution channel revenue.
- End User: Households/Individual Use leads the segment, accounting for 40.1% of total end-user revenue.
- Regional: North America is the dominant regional market, accounting for 27.7% of global revenue, holding US$ 1.42 billion in revenue in 2025.
Product Type Analysis
The Gel Hand Sanitizers segment dominated the Hand Sanitizers Market in 2025, accounting for 44.3% market share, supported by their convenience, portability, quick absorption, and widespread consumer acceptance.
Gel formulations are extensively used in households, healthcare facilities, workplaces, and public areas due to their easy application and effective microbial reduction properties. Their availability in multiple sizes, including pocket-sized bottles and large institutional packs, further supports demand growth.
The Liquid Hand Sanitizers segment captured 21.2% market share in 2025, driven by increasing adoption in hospitals, offices, educational institutions, and commercial facilities where bulk dispensing systems are commonly used. Liquid formats are preferred for high-volume applications because of their efficient dispensing and cost-effectiveness.
Foam Hand Sanitizers accounted for 17.5% market share, gaining popularity due to their lightweight texture, reduced dripping, and improved user experience, particularly in healthcare and workplace environments. Spray Hand Sanitizers represented a 11.1% share, supported by their suitability for quick application on hands and frequently touched surfaces.
Meanwhile, Wipes & Other Formats contributed 5.9% market share, with demand increasing for travel-friendly and on-the-go hygiene solutions. Growing awareness of infection prevention continues to encourage innovation across all product formats.
Type Analysis
The Alcohol-Based Sanitizers segment dominated the Hand Sanitizers Market in 2025, representing 80.1% market share, due to their proven effectiveness against a wide range of microorganisms and strong recommendation by global healthcare organisations.
Alcohol-based formulations containing ethanol or isopropyl alcohol are widely adopted in hospitals, clinics, workplaces, and households because of their rapid antimicrobial action and convenient usage.
According to the Centres for Disease Control and Prevention (CDC), alcohol-based hand sanitizers containing at least 60% alcohol are recommended when soap and water are unavailable. These products are extensively utilised in healthcare infection-control protocols and public hygiene initiatives.
The Non-Alcohol-Based Sanitizers segment accounted for 19.9% market share in 2025, supported by demand from consumers seeking alternative formulations, including products containing ingredients such as benzalkonium chloride and other antimicrobial agents.
These sanitizers are gaining attention in applications where alcohol-free options are preferred, including sensitive skin care and certain institutional environments. Increasing product innovation, regulatory focus on ingredient safety, and rising hygiene awareness are encouraging manufacturers to develop advanced formulations with improved skin compatibility and longer-lasting protection.
Distribution Channel Analysis
The Hypermarkets & Supermarkets segment dominated the Hand Sanitizers Market in 2025, accounting for 38.9% market share, driven by strong consumer accessibility, wide product availability, promotional activities, and bulk purchasing options. These retail channels allow consumers to compare multiple brands, product formats, and package sizes, making them a preferred purchasing destination for household hygiene products.
Pharmacies & Drugstores represent a significant distribution channel due to their importance in healthcare-related purchases. Consumers often prefer pharmacies for trusted hygiene products, especially during seasonal outbreaks and increased infection-control requirements.
Convenience & Departmental Stores continue to support market expansion by providing easy access to sanitizers in high-traffic locations such as shopping areas, transportation hubs, and residential communities. The Online / E-commerce segment is witnessing increased adoption due to digital shopping growth, doorstep delivery, subscription-based purchases, and availability of diverse product options.
Other channels, including institutional suppliers, direct sales, and healthcare procurement networks, contribute to market growth by supplying bulk quantities to hospitals, offices, schools, and public organisations. The expansion of multi-channel retail strategies is expected to strengthen product availability globally.
End-User Analysis
The Households / Individual Use segment dominated the Hand Sanitizers Market in 2025, accounting for 40.1% market share, supported by increased awareness of personal hygiene, infection prevention practices, and everyday use in homes, travel, and outdoor activities. Consumers increasingly prefer portable sanitizing solutions for convenient protection against germs in daily environments.
The Healthcare Facilities segment remains a major contributor due to the critical role of hand hygiene in preventing healthcare-associated infections. Hospitals, clinics, and diagnostic centres require continuous supplies of sanitizers for healthcare workers, patients, and visitors.
The Food Service & Restaurants segment is expanding as businesses adopt strict hygiene protocols to improve food safety and customer confidence. Educational institutions are also increasing sanitizer adoption to maintain healthier environments for students and staff.
Offices and Hospitality sectors are incorporating hand sanitizing stations as part of workplace safety and guest experience initiatives. Public spaces such as airports, transportation facilities, shopping centers, and government buildings continue to represent important end-user areas due to high visitor traffic.
Growing global emphasis on hygiene compliance and infection prevention is expected to support demand across residential, commercial, and institutional applications.
Key Market Segments
By Product Type
- Gel Hand Sanitizers
- Liquid Hand Sanitizers
- Foam Hand Sanitizers
- Spray Hand Sanitizers
- Wipes & Other Formats
By Formulation
- Alcohol-Based Sanitizers
- Non-Alcohol-Based Sanitizers
By Distribution Channel
- Hypermarkets & Supermarkets
- Pharmacies & Drugstores
- Convenience & Departmental Stores
- Online/E-Commerce
- Other Channels
By End User
- Households/Individual Use
- Healthcare Facilities
- Food Service & Restaurants
- Education
- Offices, Hospitality & Public Spaces
Driver
Regulatory Consolidation and Quality Screening Shift in Hand Sanitizers
Regulatory consolidation in the hand sanitizer market is increasingly reshaping competition, with compliance now acting as a primary determinant of market participation. FDA guidance in 2026 reinforces adherence to the OTC topical antiseptic monograph and current Good Manufacturing Practice (cGMP) requirements.
Shifting the industry from opportunistic production toward structured, quality-controlled manufacturing. This tightening is reinforced by ongoing FDA safety warnings and enforcement actions following past contamination events, including methanol-related recalls.
As a result, distributors, retailers, and institutional buyers have raised compliance expectations, requiring validated supply chains, ingredient traceability, and consistent batch testing before onboarding suppliers.
The outcome is gradual consolidation toward larger, compliant manufacturers that can reliably manage ethanol or isopropyl alcohol sourcing while maintaining full documentation and testing protocols. Smaller producers face increasing pressure from higher compliance costs, slower regulatory clearance, and elevated delisting risk, which limits their ability to compete on price alone.
Rather than significantly expanding overall unit demand, this shift improves market structure and revenue quality. It supports more stable pricing, reduces low-quality supply fluctuations, and strengthens brand preference across both consumer and institutional channels.
Private label portfolios are also becoming more selective, favouring audited and certified suppliers. Overall, regulatory consolidation does not primarily drive volume growth but enhances market discipline, leading to improved realised revenue stability and quality-adjusted CAGR through stronger compliance barriers and reduced fragmentation.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Healthcare IPC compliance procurement | +2.2% | North America core, EU core, APAC developed healthcare hubs | Short term (≤ 2 years) |
| Regulatory consolidation and quality-screening shift | +1.6% | US core, EU regulated markets, APAC export corridors | Medium term (2–4 years) |
| Everyday mobility and public-contact hygiene use | +1.3% | North America, EU urban corridors, APAC metro corridors, Middle East travel hubs | Short term (≤ 2 years) |
| Skin-friendly premium formulations improving repeat purchase | +1.1% | North America premium retail, EU pharmacy channels, Japan/South Korea urban markets | Medium term (2–4 years) |
| Institutional replenishment across eldercare, clinics, and schools | +1.8% | US core, Canada, EU public systems, selective APAC public institutions | Short term (≤ 2 years) |
| WHO-led hand-hygiene normalisation in emerging systems | +0.9% | South Asia, Southeast Asia, Africa, and Latin America spill-over | Long-term (≥ 4 years) |
Challenges
Quality Compliance Volatility in Hand Sanitizers
Quality compliance volatility in the hand sanitizer market arises from uneven manufacturing standards across a highly fragmented supplier base, particularly among small and mid-sized producers that expanded rapidly during the pandemic.
This scale-up period introduced inconsistencies in alcohol concentration, denaturant usage, and contaminant control, despite regulatory expectations from the FDA and WHO that products maintain roughly 60 to 95 % alcohol content with strict excipient and impurity limits.
Regulatory inspections and batch testing can periodically remove 3 to 7 % of annual volume from premium or institutional channels, while triggering short-term demand shifts toward established, compliant brands.
However, the larger structural issue is the ongoing compliance burden: leading manufacturers typically allocate 3 to 5 % of revenues to quality systems, validation testing, and documentation, compared with much lower requirements in less regulated personal care categories.
This cost differential, estimated at roughly 2 to 4 cents per 100 mL unit, compresses margins for mid-tier producers and discourages sustained investment in branding or process innovation.
As a result, category fragmentation increases and overall demand growth becomes less efficient, contributing to an estimated 1.2 % point drag on CAGR versus a fully standardised market environment.
To manage this volatility, manufacturers are strengthening multi-layered quality systems, including incoming alcohol purity testing, GMP audits of contract sites, and lot-level microbial efficacy validation aligned with WHO protocols. Increasing reliance on digital traceability and serialisation is also becoming essential to prevent large-scale recalls and maintain retailer and institutional trust in an increasingly compliance-sensitive market.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Quality compliance volatility | -1.2% | North America, EU, selected APAC | Medium term (2-4 years) |
| Raw material cost instability | -1.0% | Global production hubs | Medium term (2-4 years) |
| Formulation safety perception gaps | -0.9% | Global consumer markets | Long-term (≥ 4 years) |
| Distribution and last-mile fragmentation | -0.8% | Emerging APAC, Africa, LATAM | Long-term (≥ 4 years) |
| Hand hygiene behavior fatigue | -1.4% | Global, stronger in developed | Long-term (≥ 4 years) |
| Antimicrobial resistance and efficacy scrutiny | -0.7% | Hospital & clinical clusters worldwide | Short–Medium term (≤ 4 years) |
Restraints
Ethanol and IPA Feedstock Volatility in Hand Sanitizers
Volatility in ethanol and isopropyl alcohol IPA feedstock markets is a key structural pressure point for the hand sanitizer industry, directly affecting cost stability and margin predictability. Alcohol typically accounts for 50 to 70 % of total raw material costs in sanitizer formulations, meaning even moderate swings in input prices have an outsized impact on unit economics.
Historical disruptions, particularly during the COVID-19 period, demonstrated that ethanol and IPA prices can fluctuate by 30 to 60 % within a single year, driven by shifts in fuel demand, agricultural output for bioethanol, refinery outages, and logistics constraints.
Because WHO recommended formulations require high alcohol concentrations, typically 60 to 95 %, depending on product type, manufacturers have limited ability to reformulate without compromising efficacy or regulatory compliance.
This rigidity is compounded in APAC and emerging markets, where reliance on imported pharmaceutical-grade alcohol exposes producers to additional risks from currency depreciation, freight volatility, and port congestion. In some instances, landed costs can increase by 20 to 30 % during supply chain stress periods, further compressing margins.
To manage this volatility, companies often extend supply contracts, diversify sourcing, and build higher inventory buffers. However, these strategies increase working capital requirements and storage costs while limiting pricing agility in a category where retail prices are highly competitive and often contractually fixed in institutional tenders.
Overall, the mismatch between volatile upstream feedstock costs and relatively rigid downstream pricing structures creates persistent margin pressure. This dynamic is estimated to reduce long-term category growth potential by approximately 0.9 % points of CAGR, as smaller and mid-tier producers delay expansion and lose competitiveness against vertically integrated suppliers with upstream alcohol access.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Post-COVID demand normalization | -1.5% | North America core, EU, mature APAC | Medium term (2-4 years) |
| Stricter alcohol & OTC regulations | -1.2% | North America core, EU, selective LATAM | Medium term (2-4 years) |
| Ethanol & IPA feedstock volatility | -0.9% | North America core, EU, APAC corridors | Short–Medium term (≤ 4 years) |
| Quality, claims & litigation risk | -0.8% | North America core, EU | Medium term (2-4 years) |
| Packaging & logistics cost pressure | -0.6% | Global, with higher impact in emerging markets | Short term (≤ 2 years) |
Opportunity
IoT-enabled hand hygiene systems and compliance bundling opportunity
A major future opportunity in the hand sanitizer market is the shift from standalone consumables to integrated, data-driven hand hygiene systems.
In healthcare and other high risk environments, infection control guidelines already emphasise not just availability of alcohol based rubs, but also consistent compliance with hand hygiene protocols across staff workflows. However, most current systems still rely on passive dispensers and untracked consumable use.
The emerging white space is the integration of sanitizers into IoT-enabled dispensers paired with compliance analytics platforms. These systems can track usage frequency, monitor workflow adherence, and generate real-time alerts to improve compliance with WHO and CDC hand hygiene standards.
When combined with AI-driven dashboards, hospitals, long-term care facilities, and food service operators can identify behavioural gaps and reduce healthcare-associated infection HAI risk measurably.
If adoption reaches just 10 to 15 % of institutional settings globally by 2035, particularly in North America, Europe, and Gulf markets, it could meaningfully reshape revenue models. Instead of one-time consumable sales, companies could capture recurring SaaS style income layered with sanitizer consumption contracts, increasing account-level revenue by 8 to 12 % and improving EBITDA margins by 5 to 7 % points.
This shift would also support stronger compliance reporting and ESG-linked procurement requirements, which are becoming increasingly important in regulated healthcare and corporate environments.
Overall, integrated hygiene systems could add approximately 1.8 % points of incremental CAGR, driven by higher retention, recurring software revenue, and improved institutional adherence outcomes.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Hospital-grade clinical formulations | +2.5% | North America, EU, APAC urban | Medium term (2-4 years) |
| Integrated hand hygiene IoT & bundling | +1.8% | North America core, EU, GCC | Medium term (2-4 years) |
| Skin-health and dermatology-led sanitizers | +1.6% | North America, EU, East Asia | Short term (≤ 2 years) |
| Emerging-market micro-pack & refill ecosystems | +2.2% | APAC emerging, Africa, LatAm | Long term (≥ 4 years) |
| Industrial and B2B workflow-specific solutions | +1.4% | Global industrial hubs | Medium term (2-4 years) |
| Subscription and enterprise hygiene-as-a-service | +1.3% | Global corporates, healthcare chains | Medium term (2-4 years) |
Regional Analysis
In 2025, North America led the market, achieving over 27.7% market share with revenue of US$ 1.42 billion. The Hand Sanitizers Market demonstrates strong growth across regions due to rising awareness of hygiene practices, infection prevention initiatives, and increased adoption across healthcare, commercial, and household applications.
North America represents a significant market, supported by strong healthcare infrastructure, strict infection-control standards, and widespread consumer adoption of alcohol-based sanitizers. The presence of regulatory frameworks from organisations such as the U.S. Centres for Disease Control and Prevention (CDC) and the U.S. Food and Drug Administration (FDA) continues to encourage safe and effective hand hygiene practices in healthcare and public environments.
Europe is witnessing steady market expansion due to increased focus on healthcare-associated infection prevention, workplace hygiene regulations, and demand for sustainable hygiene products. Hospitals, schools, and public institutions across European countries continue to integrate hand sanitizing solutions as part of broader health and safety programs.
Asia-Pacific is expected to experience significant growth driven by increasing healthcare expenditure, expanding urban populations, rising awareness of personal hygiene, and growing adoption of sanitization products in commercial spaces. Countries across the region are witnessing higher demand from households, hospitals, educational institutions, and hospitality sectors.
Latin America, the Middle East & Africa are also contributing to market development through improving healthcare facilities, government-led hygiene awareness programs, and increased availability of personal care products. Expanding retail networks, e-commerce penetration, and demand for convenient hygiene solutions are further supporting regional growth across emerging markets.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global hand sanitizers market is highly competitive, with major players focusing on product innovation, brand expansion, distribution network development, and institutional partnerships.
GOJO Industries Inc., through its PURELL brand, has maintained a strong position across healthcare, workplace, and retail channels; following its acquisition by The Clorox Company in April 2026, its market reach is expected to benefit from broader distribution capabilities.
Reckitt Benckiser Group plc, Procter & Gamble, and Unilever plc leverage strong consumer brands and extensive retail networks, while Vi-Jon Laboratories Inc. competes through its Germ-X portfolio and North American presence. Henkel AG & Co. KGaA, Ecolab Inc., 3M Company, Best Sanitizers Inc., and Kutol Products Company Inc. maintain significant positions in professional and institutional hygiene applications.
Himalaya Wellness Company, ITC Limited, Dabur Ltd., Colgate-Palmolive Company, and Johnson & Johnson/Kenvue strengthen competition through personal-care expertise and regional distribution. Other Key Players contribute through specialized formulations, private-label manufacturing, and niche product offerings.
Top Key Players
- GOJO Industries Inc.
- Reckitt Benckiser Group plc
- Procter & Gamble
- Unilever plc
- Vi-Jon Laboratories Inc.
- Henkel AG & Co. KGaA
- Himalaya Wellness Company
- Best Sanitizers Inc.
- Kutol Products Company Inc.
- 3M Company
- Ecolab Inc.
- Johnson & Johnson/Kenvue
- Colgate-Palmolive Company
- ITC Limited
- Dabur Ltd.
- Other Key Players
Recent Developments
- In January 2026, GOJO Industries launched an enhanced moisturising PURELL Advanced Hand Sanitizer formulation with improved skin conditioning technology targeting healthcare facility and food service institutional buyers seeking clinical efficacy combined with reduced skin irritation for high-frequency use applications.
- In February 2026, Reckitt Benckiser expanded its Dettol hand sanitizer portfolio with a new natural ingredient-based alcohol gel range across Asian and Middle Eastern retail and pharmacy distribution channels, targeting health-conscious consumer demographics seeking natural formulation alternatives to conventional synthetic alcohol sanitizers.
- In March 2026, Ecolab Inc. secured a multi-year hand hygiene program supply agreement with a leading North American hospital health system network covering dispensing system installation and sanitizer product supply across its institutional healthcare facility network, targeting hand hygiene compliance improvement programs.
- In May 2026, Unilever plc launched a refillable hand sanitizer dispenser system under its Lifebuoy brand across European retail and institutional channels, targeting sustainability-conscious consumers and corporate buyers seeking reduced single-use plastic packaging consumption through refillable dispensing infrastructure programs.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 5.1 Billion |
| Forecast Revenue (2035) | US$ 7.1 Billion |
| CAGR (2026-2035) | 3.3% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Gel Hand Sanitizers, Liquid Hand Sanitizers, Foam Hand Sanitizers, Spray Hand Sanitizers, Wipes & Other Formats), By Formulation (Alcohol-Based Sanitizers, Non-Alcohol-Based Sanitizers), By Distribution Channel (Hypermarkets & Supermarkets, Pharmacies & Drugstores, Convenience & Departmental Stores, Online/E-Commerce, Other Channels), By End User (Households/Individual Use, Healthcare Facilities, Food Service & Restaurants, Education, Offices/Hospitality/Public Spaces) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | GOJO Industries Inc., Reckitt Benckiser Group plc, Procter & Gamble, Unilever plc, Vi-Jon Laboratories Inc., Henkel AG & Co. KGaA, Himalaya Wellness Company, Best Sanitizers Inc., Kutol Products Company Inc., 3M Company, Ecolab Inc., Johnson & Johnson/Kenvue, Colgate-Palmolive Company, ITC Limited, Dabur Ltd., Other Key Players |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








