


Report Overview
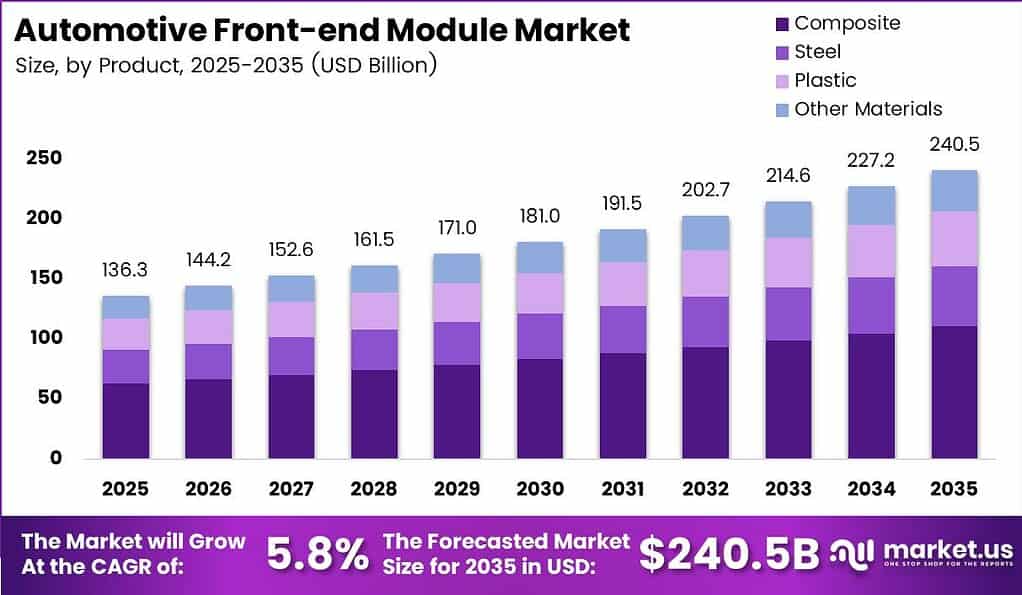
Global Automotive Front-End Module Market size is expected to be worth around USD 240.5 Billion by 2035 from USD 136.3 Billion in 2025, growing at a CAGR of 5.8% during the forecast period 2026 to 2035.
The automotive front-end module market covers pre-assembled structural and functional units mounted at the front of a vehicle. These modules integrate radiators, headlights, front grilles, condensers, and related components into a single deliverable unit. Suppliers build and test the module off-line, then deliver it sequentially to the vehicle assembly line. This structure reduces OEM assembly complexity and consolidates supplier accountability.
Key Takeaways
- The global Automotive Front-End Module Market was valued at USD 136.3 Billion in 2025 and is projected to reach USD 240.5 Billion by 2035 at a CAGR of 5.8%.
- By Product, the Composite segment dominates with a 44.23% share in 2025.
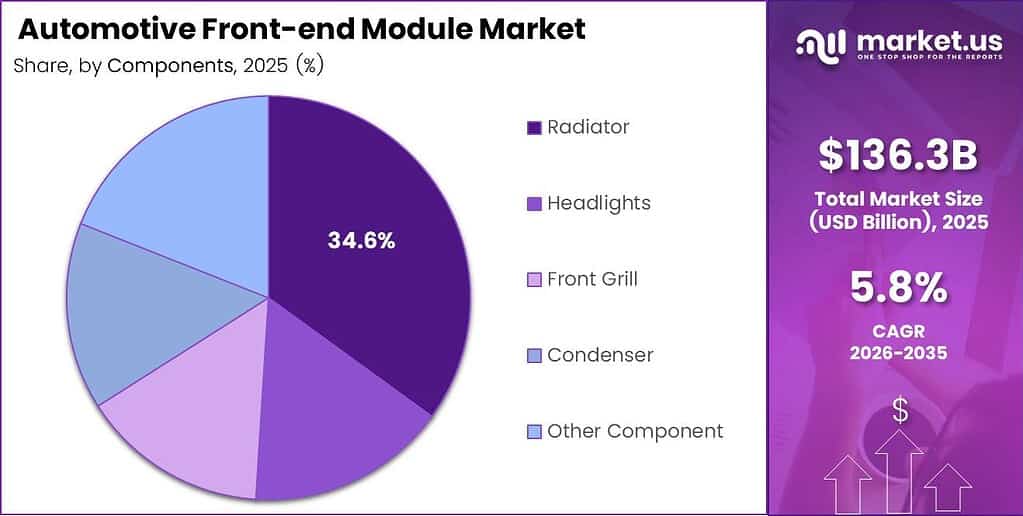
- By Components, the Radiator segment holds the largest share at 34.67%.
- By Vehicle Type, Passenger Cars hold a dominant share of 63.21% and are the fastest-growing sub-segment.
- By End Use, the OEM segment leads with an 84.34% share, while the Aftermarket segment is the fastest-growing.
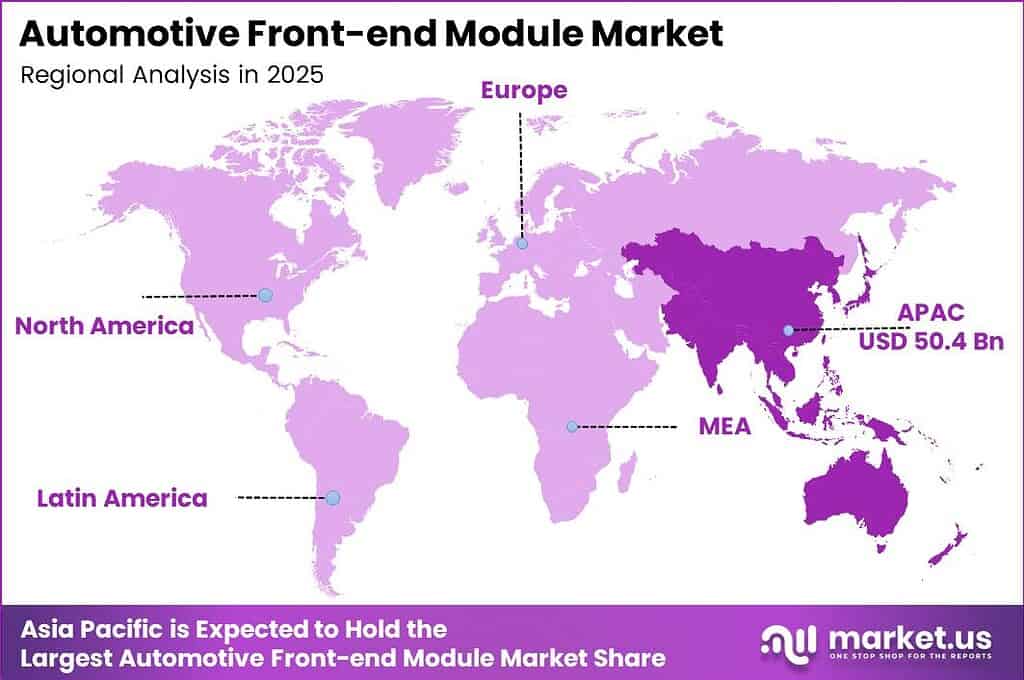
- Asia-Pacific dominates the regional landscape with a 37.33% share, valued at USD 50.4 Billion, and is the fastest-growing region.
According to OICA data, global vehicle production reached 96.4 million units in 2025, up 3.9%. This volume expansion directly widens the addressable unit base for front-end module suppliers. Every additional vehicle produced represents one more module demand cycle, and OEMs increasingly outsource this assembly to reduce line complexity.
As reported by the IEA, global electric-car sales exceeded 20 million units in 2025, increasing 20% and representing 25% of new-car sales. This scale forces front-end module architectures to incorporate battery-cooling circuits and active airflow controls. Suppliers that qualify thermal-mechatronic assemblies for EV platforms earn higher content per vehicle than conventional module programs.
Data from ACEA shows global new-car registrations reached 77.6 million units in 2025, up 3.5%. Global vehicle sales hit 99.8 million units in 2025, up 4.7%. This gap between registrations and sales confirms active inventory draw-down, which signals continued production pressure on module suppliers across all powertrain types.
EU requirements mandate at least 85% reuse and recycling and 95% reuse and recovery by average end-of-life vehicle weight. This regulatory floor pushes OEMs and module suppliers toward recyclable composite and steel construction. In November 2025, Toyota announced a USD 912 million investment across five U.S. plants supporting hybrid-vehicle production, demonstrating how OEM capital commitments are shaping module content demand. Suez Canal transits decreased 42% from their peak and Shanghai-to-Europe container spot freight rates increased 256% during the Red Sea disruption, pressuring cross-border input costs for front-end module supply chains.
Product Analysis
Composite dominates with 44.23% due to its superior weight-to-strength performance ratio.
In 2025, Composite held a dominant market position in the By Product segment of the Automotive Front-End Module Market, with a 44.23% share. The global composites market totaled 13.5 million tonnes in 2024, confirming broad raw material availability. Composite modules reduce vehicle mass without sacrificing structural performance, which lowers fuel consumption and extends EV range. This weight benefit gives composite-intensive suppliers a specification advantage on energy-regulated platforms.
Steel is the fastest-growing material sub-segment in this market. Advanced high-strength steel can reduce vehicle weight by 25% to 39% compared with conventional steel. This performance range narrows the gap with composite alternatives at lower tooling cost. Tier-1 suppliers that position high-strength steel as a cost-competitive lightweight option can penetrate budget-sensitive OEM platforms where composite processing costs remain prohibitive.
Plastic and Other Materials hold the remaining share in the By Product segment. Plastic retains relevance in non-structural cladding and closeout panel applications where cost priority exceeds structural requirement. Other Materials cover specialty alloys and hybrid constructions used in niche platform programs. These sub-segments serve cost-sensitive and performance-specific tiers without displacing composite or steel in volume applications.
Components Analysis
Radiator dominates with 34.67% due to its mandatory thermal management role across all powertrains.
In 2025, Radiator held a dominant market position in the By Components segment of the Automotive Front-End Module Market, with a 34.67% share. A 2025 recall covered 291,664 Ram ProMaster vehicles due to inadequate protection for a 400-watt fan circuit, per NHTSA data. This event confirms that thermal management integrity carries direct regulatory and warranty exposure. Suppliers that invest in validated cooling-circuit designs build a defensible quality premium with OEM procurement teams.
Headlights are a critical safety and regulatory component within the front-end module assembly. IIHS data found that vehicles with good headlight ratings recorded 19% fewer nighttime single-vehicle crashes and 23% fewer nighttime pedestrian crashes than vehicles with poor-rated headlights. These statistics tie lighting performance directly to insurance liability and safety ratings. In March 2024, Koito commenced operations at its Gujarat lighting plant following an approximately ¥3.7 billion investment, with annual capacity for 500,000 headlamps.
Front Grille, Condenser, and Other Components hold the remaining share in the By Components segment. Front grille integration now extends beyond aesthetics into active aerodynamic management for fuel economy compliance. Condenser units gain content value on EV platforms that require heat-pump conditioning systems. Other Components cover sensor brackets, crash beams, and closeout panels that vary by platform architecture.
Vehicle Analysis
Passenger Cars dominate with 63.21% due to global volume output and electrification platform investment.
In 2025, Passenger Cars held a dominant market position in the By Vehicle segment of the Automotive Front-End Module Market, with a 63.21% share. Passenger Cars are also the fastest-growing sub-segment, supported by expanding OEM investment. In March 2025, Hyundai Motor Group announced a USD 21 billion U.S. investment program for 2025 to 2028, including USD 9 billion to establish annual production capacity of 1.2 million vehicles. This capital commitment confirms that passenger-car platform spending drives sustained module volume.
Commercial Vehicles represent the remaining share in the By Vehicle segment. Approximately 16.7 million commercial vehicles are manufactured worldwide annually, including 3,079,810 units in Europe, per ACEA figures. Commercial vehicle platforms typically carry higher module content value per unit than passenger cars. This content premium makes commercial vehicle programs strategically attractive for suppliers willing to develop platform-specific thermal and structural configurations.
End Use Analysis
OEM dominates with 84.34% due to captive volume from direct vehicle assembly contracts.
In 2025, OEM held a dominant market position in the By End Use segment of the Automotive Front-End Module Market, with an 84.34% share. In October 2025, Stellantis announced a USD 13 billion U.S. investment supporting five new vehicles, more than 5,000 jobs, and a 50% production increase. OEM-scale production commitments at this level generate predictable, platform-locked module demand. Suppliers with validated OEM program positions benefit from multi-year volume visibility that reduces payback risk on tooling investment.
The Aftermarket segment is the fastest-growing End Use sub-segment. Global EV battery deployment reached 1.2 TWh in 2025, increasing almost 30% from 2024, per IEA data. As the EV fleet expands, replacement demand for thermally integrated front-end components will grow with vehicle aging cycles. World merchandise-trade volume increased 4.6% in 2025 and is projected to increase 1.9% in 2026, per WTO data, supporting aftermarket parts distribution logistics across all regions.
Key Market Segments
By Product
- Composite
- Steel
- Plastic
- Other Materials
By Components
- Radiator
- Headlights
- Front Grill
- Condenser
- Other Components
By Vehicle
- Passenger Cars
- Commercial Vehicles
By End Use
- OEM
- Aftermarket
Regional Analysis
Asia-Pacific Dominates the Automotive Front-End Module Market with a Market Share of 37.33%, Valued at USD 50.4 Billion
Asia-Pacific is the dominant and fastest-growing region in this market. OICA data shows Asia-Pacific vehicle production reached approximately 59.2 million units in 2025, increasing 7.6% and accounting for more than 61% of global output. This production concentration drives module demand directly. Suppliers operating in Asia-Pacific benefit from co-located OEM relationships, shorter just-in-sequence lead times, and expanding EV platform investment across China, India, and Southeast Asia.
India is an emerging growth center within Asia-Pacific. SIAM data shows Indian passenger-vehicle sales reached 4.3 million units in FY2024 to 25, increasing 2%. In October 2025, HARMAN announced a ₹345 crore investment to expand its Pune plant by more than 50% and create 300 jobs by 2027. In March 2026, Valeo broke ground on a USD 225 million, 337,000-square-foot Texas facility expected to create up to 500 jobs, signaling North American localization driven by tariff pressure.
European new-car registrations reached 16,317,613 units in 2025, increasing 1.4%, per ACEA data. The EU passenger-car fleet reached 256 million vehicles in 2024, increasing 1.4%. North American passenger-car production declined 0.9% to 11.2 million units in 2025. Latin American electric-car sales increased 75% year over year in the first quarter of 2026. African vehicle sales increased 22% from 1.05 million units in 2024 to 1.29 million units in 2025, per OICA figures, identifying Africa as a nascent but high-velocity volume market.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Drivers
Electric-car sales exceeded 17 million units in 2024, growing more than 25%, and surpassed 20 million units in 2025 with approximately 20% annual growth. This volume forces front-end architectures to integrate battery-cooling circuits, heat exchangers, active airflow controls, and revised crash-load paths. A validated thermal-mechatronic assembly can carry approximately 5 to 10% more content per vehicle than a conventional module, shifting the commercial model toward higher-value, platform-specific subassemblies and multi-year engineering programs.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Electrified Front-End Redesign | +0.7% | Global; strongest in China, Europe and North America | Short term (≤ 2 years) |
| Mandatory ADAS Integration | +0.5% | Europe, North America, Japan and South Korea | Short term (≤ 2 years) |
| Global Vehicle Output Recovery | +0.4% | Global; Asia-led | Short term (≤ 2 years) |
| Lightweight Multi-Material Adoption | +0.3% | Europe, China, North America and Japan | Medium term (2–4 years) |
| Modular Assembly Outsourcing | +0.2% | Global automotive manufacturing hubs | Medium term (2–4 years) |
| Asian Production Localization | +0.2% | India, China and Southeast Asia | Medium term (2–4 years) |
Restraints
A 25% tariff imposed on specified imported automobiles and automobile parts in 2025 created an immediate landed-cost barrier for cross-border electrical, structural, and thermal inputs used in front-end modules. For a module with 20 to 40% dutiable imported content, gross mechanical exposure equals approximately 5 to 10% of module value before relief. Temporary offsets were set at 3.75% of eligible U.S.-assembled vehicle value through April 30, 2026 and 2.5% through April 30, 2027, compressing supplier margins by roughly 150 to 300 basis points where contracts prevent rapid pass-through.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| United States Auto-Parts Tariffs | -0.7% | North America and export-oriented supply bases | Short term (≤ 2 years) |
| European Output Contraction | -0.5% | European Union and adjacent supplier clusters | Short term (≤ 2 years) |
| OEM Price-Down Lock-In | -0.4% | Global | Short term (≤ 2 years) |
| Platform Tooling Barriers | -0.3% | Global; strongest for smaller suppliers | Medium term (2–4 years) |
| Model-Specific Aftermarket Limits | -0.2% | Global replacement channels | Long term (≥ 4 years) |
| High-Cost Capital Environment | -0.2% | Europe and emerging manufacturing markets | Short term (≤ 2 years) |
Challenges
Global car production reached approximately 75.5 million units in 2024 while electric-car sales exceeded 17 million units, forcing suppliers to support internal-combustion, hybrid, and battery-electric platforms simultaneously. Each architecture requires different cooling packs, air-management systems, reinforcement geometries, and sensor mounting points. This complexity can increase active module variants by an estimated 10 to 20%, extend changeovers and validation cycles by roughly 8 to 12 weeks, and generate a modeled 1 to 3 percentage-point loss in equipment effectiveness during launches.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Mixed-Powertrain Variant Proliferation | -0.5% | Global | Medium term (2–4 years) |
| Just-in-Sequence Logistics Fragility | -0.3% | Europe, North America and Asia | Short term (≤ 2 years) |
| Sensor Calibration Yield Loss | -0.3% | Europe, North America, China and Japan | Medium term (2–4 years) |
| Multi-Material Joining Complexity | -0.2% | Global advanced-manufacturing clusters | Medium term (2–4 years) |
| Cybersecurity Validation Workload | -0.1% | Europe, Japan and UNECE-aligned markets | Long term (≥ 4 years) |
| Regional Supplier Qualification Delays | -0.1% | North America, Europe and emerging Asia | Medium term (2–4 years) |
Opportunities
Global electric medium- and heavy-duty truck sales exceeded 90,000 units in 2024, with more than 80% concentrated in China, and electric trucks reached approximately 9% of worldwide truck sales in 2025. Suppliers that adapt front-end modules for high-capacity cooling, battery conditioning, power-electronics heat rejection, and active aerodynamic control could raise content per commercial vehicle by an estimated 15 to 25% and reduce customer assembly operations by approximately 10 to 15%. Capturing this application could add approximately +0.5% above the 5.8% baseline CAGR and expand gross margins by a modeled 3 to 5 percentage points.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Electric Commercial-Vehicle Thermal Modules | +0.5% | China initially; Europe, North America and India subsequently | Medium term (2–4 years) |
| Active-Aerodynamics Product Upgrades | +0.4% | Europe, China, North America and Japan | Medium term (2–4 years) |
| Repairable Modular Aftermarket Systems | +0.3% | Europe and mature insurance markets | Long term (≥ 4 years) |
| Predictive-Diagnostics Service Layer | +0.2% | Connected-vehicle markets globally | Long term (≥ 4 years) |
| Front-End Supplier Roll-Ups | +0.2% | Europe, India and Southeast Asia | Medium term (2–4 years) |
| Cross-Platform Module Licensing | +0.1% | Emerging vehicle manufacturers globally | Long term (≥ 4 years) |
Key Company Insights
Magna International generated USD 42 billion in sales and USD 1.9 billion in free cash flow in 2025. This financial scale gives Magna the capital to absorb platform-specific tooling costs that smaller suppliers cannot sustain. In September 2025, Magna announced assembly of two XPENG electric-vehicle models in Graz, demonstrating that its contract manufacturing capability extends its positioning beyond components into full-vehicle programs.
FORVIA generated €26.2 billion in sales and a 5.6% operating margin in 2025. This margin performance at that revenue scale reflects disciplined program management across a complex multi-segment portfolio. In April 2024, OPmobility inaugurated a Texas plant with annual assembly capacity of 2.5 million modules, signaling that North American localization is now a competitive baseline requirement rather than a differentiator for leading suppliers.
Key Players
- HBPO GmbH
- Magna International Inc.
- Forvia SE
- OPMOBILITY SE (Plastic Omnium)
- Hyundai Mobis Co., Ltd.
- DENSO Corporation
- Valeo SA
- Marelli Holdings Co., Ltd.
- Samvardhana Motherson Group
- SL Corporation
- Flex-N-Gate Corporation
- Aisin Corporation
- Benteler Automotive
- Yinlun Co., Ltd.
Recent Developments
- 18 February 2026 – Valeo announced an investment exceeding €200 million in India and targeted approximately €700 million in Indian sales by 2028.
- 4 February 2026 – Aisin announced a ¥32 billion investment to expand its Haryana plant and construct an 86,000-square-metre plant in Maharashtra.
- 9 January 2026 – Sinopec Capital agreed to invest RMB 300 million, approximately €40 million, in FORVIA Hydrogen Solutions China.
- 22 December 2025 – Motherson entered exclusive negotiations to acquire 100% of Nexans Autoelectric’s wiring-harness business at an enterprise value of €207 million.
- 9 September 2024 – DENSO announced an approximately ¥69 billion investment in a 56,000-square-metre plant for electrification and ADAS control units.
- 24 April 2024 – Hyundai Mobis announced a KRW 170 billion investment in a Spanish plant with annual capacity for 360,000 battery systems.
- 30 July 2026 – Maruti Suzuki commenced production at Hansalpur Plant D after an estimated ₹39 billion investment, adding 250,000 units of annual capacity.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 136.3 Billion |
| Forecast Revenue (2035) | USD 240.5 Billion |
| CAGR (2026-2035) | 5.8% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Product (Composite, Steel, Plastic, Other Materials), By Components (Radiator, Headlights, Front Grill, Condenser, Other Components), By Vehicle (Passenger Cars, Commercial Vehicles), By End Use (OEM, Aftermarket) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | HBPO GmbH, Magna International Inc., Forvia SE, OPMOBILITY SE (Plastic Omnium), Hyundai Mobis Co., Ltd., DENSO Corporation, Valeo SA, Marelli Holdings Co., Ltd., Samvardhana Motherson Group, SL Corporation, Flex-N-Gate Corporation, Aisin Corporation, Benteler Automotive, Yinlun Co., Ltd. |
| Customization Scope | Customization for segments, region/country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








