


Report Overview
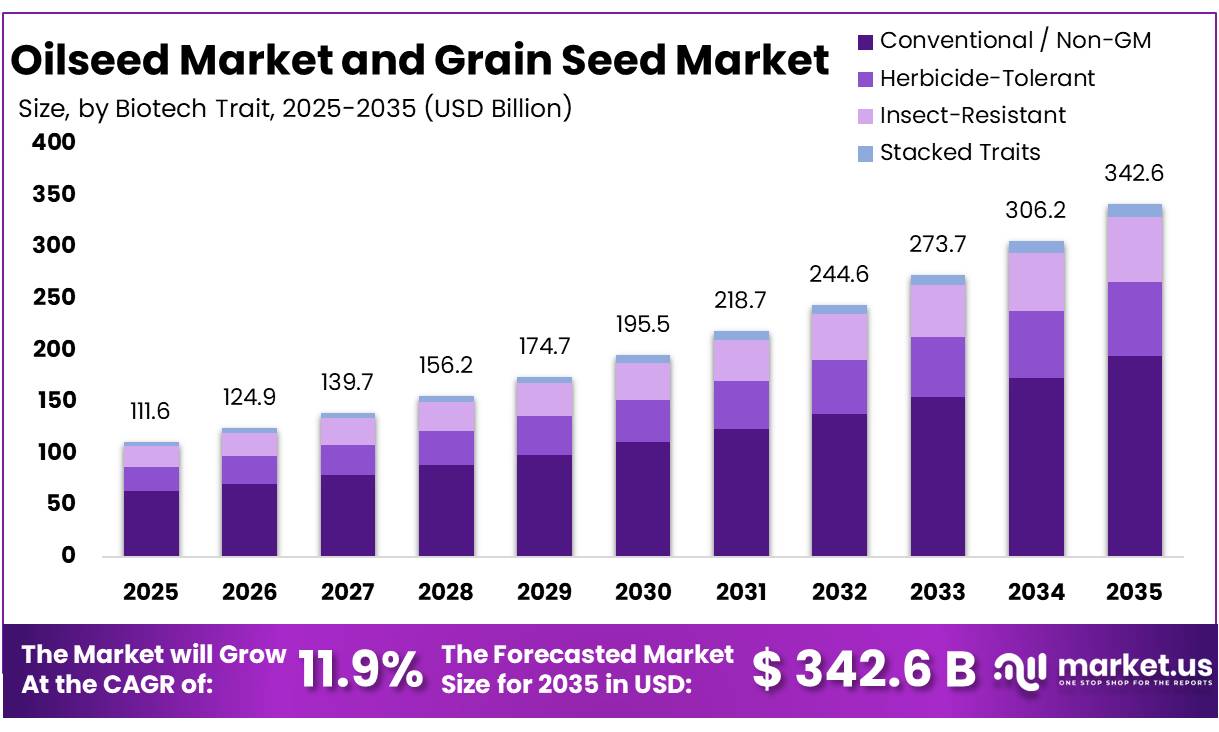
The Global Oilseed Market and Grain Seed Market size is expected to be worth around USD 342.6 Billion by 2035, from USD 111.6 Billion in 2025, growing at a CAGR of 11.9% during the forecast period from 2026 to 2035. In 2025, North America held a dominant market position, capturing more than a 34.70% share, holding USD 38.7 Billion revenue.
The oilseed and grain seed industries play an important role in global agriculture, food security, animal nutrition, and industrial processing. Oilseeds such as soybeans, rapeseed, sunflower seeds, and cottonseed supply vegetable oils and protein-rich meals used in food manufacturing, livestock feed, and biofuel production. Grain seeds, including wheat, corn, barley, and rice, support food production and animal feed supply chains.
The United States Department of Agriculture (USDA) tracks global production, consumption, trade, and inventories for major oilseeds and grains through its monthly commodity reports. These data help producers, processors, traders, and governments assess supply conditions and changing market demand.
- According to the USDA Economic Research Service, the United States accounted for 26% of global soybean exports in the 2023/24 marketing year, highlighting the importance of international trade in the oilseed supply chain. Brazil and other major agricultural producers also influence global availability and prices.
Oilseed processing companies convert harvested crops into crude and refined oils, oilseed meals, and other industrial ingredients. Grain seed producers, meanwhile, supply conventional and improved varieties designed to support yield, crop quality, and adaptation to different growing conditions.
- Global grain production also provides a major foundation for the agricultural economy. The Food and Agriculture Organization of the United Nations (FAO) estimated 2025 global cereal production at 3,043 million tonnes, representing a 6.1% increase compared with 2024. This high production level demonstrates the importance of efficient seed supply, improved farming practices, and reliable agricultural distribution networks.
The major driving factors include population growth, changing dietary preferences, livestock feed requirements, and demand for renewable energy. Improved seed varieties are also supporting agricultural productivity through better yield potential, pest resistance, disease tolerance, and adaptation to local climates. According to the USDA Economic Research Service, the seven largest seed companies invested more than USD 6.5 billion in crop improvement research and development in 2021, compared with less than USD 2 billion in 1990.
Key Takeaways
- Oilseed Market and Grain Seed Market size is expected to be worth around USD 342.6 Billion by 2035, from USD 111.6 Billion in 2025, growing at a CAGR of 11.9%.
- Oilseeds lead the market with a 43.50% share in 2025, supported by their widespread use in edible oil production, animal feed, and food processing.
- Hybrids dominate the market with a 51.50% share.
- Conventional / Non-GM seeds lead the market with a 56.70% share in 2025.
- Animal Feed / Oilseed Meals leads with a 31.00% market share in 2025.
- North America held a dominant market position, capturing 34.70% of the market, valued at USD 38.7 billion.
By Product Type Analysis
Oilseed Market and Grain Seed Market By Crop / Product Type of Oilseeds
Oilseeds lead the market with a 43.50% share in 2025, supported by their widespread use in edible oil production, animal feed, and food processing. Oilseed crops provide both vegetable oils and protein-rich meals, making them important to agricultural supply chains. Demand is also supported by the use of soybean and other oilseed products in industrial applications and renewable fuel production. Government agricultural statistics from the United States Department of Agriculture help track production, consumption, and trade across major oilseed crops.
Soybean remains a key oilseed crop in 2025, supported by its use in vegetable oil, protein meal, animal feed, and food processing. According to the USDA, soybean production in the United States reached approximately 4.26 billion bushels in 2025, with an average yield of 53.0 bushels per acre. Soybeans also accounted for about 90% of U.S. oilseed production, demonstrating their importance to the domestic oilseed industry. Demand from food manufacturers, livestock feed producers, and oil processors supports soybean cultivation and trade.
By Breeding Technology Analysis
Oilseed Market and Grain Seed Market By Breeding Technology of Hybrids
Hybrids dominate the market with a 51.50% share in 2025, supported by their potential to deliver improved yields, more uniform crop growth, and better resistance to selected pests and diseases. Hybrid seeds are developed by crossing selected parent plants to combine desirable traits. Their use in suitable oilseed and grain crops helps farmers improve crop performance and maintain consistent production. Demand is also supported by ongoing plant-breeding research and the need for seed varieties that perform under different growing conditions.
Open-Pollinated Varieties (OPVs) remain relevant for farmers seeking seeds that can retain their characteristics when properly selected and saved across generations. These varieties support local seed adaptation and can offer farmers greater flexibility in seed management. In 2025, the United States Department of Agriculture reported that 94% of planted corn acres used biotech varieties. This figure reflects biotechnology adoption, not OPV usage, and should not be treated as an OPV market share.
By Biotech Trait Analysis
Oilseed Market and Grain Seed Market By Biotech Trait of Conventional / Non-GM
Conventional / Non-GM seeds lead the market with a 56.70% share in 2025, supported by demand from farmers and food producers seeking crops grown without genetic modification. These seeds remain important in agricultural supply chains serving conventional food products and buyers with non-GM sourcing requirements. Their adoption is also influenced by local farming practices, seed availability, and market preferences. Conventional varieties provide an established option for oilseed and grain production, while demand for traceable agricultural products helps maintain their relevance across food and feed applications.
Genetically Modified (GM) / Herbicide-Tolerant seeds support crop production by helping farmers control weeds more effectively and manage field operations. In 2025, the United States Department of Agriculture reported that 96% of soybean acreage used herbicide-tolerant seed varieties, while 94% of corn acreage used biotech varieties. These figures show strong adoption of relevant seed technologies in major crops, although they do not represent the global market share of GM or herbicide-tolerant seeds.
By Application Analysis
Oilseed Market and Grain Seed Market By Application of Animal Feed / Oilseed Meals
Animal Feed / Oilseed Meals leads with a 31.00% market share in 2025, supported by its importance as a protein source in livestock and poultry diets. Oilseed meals are produced during oil extraction from crops such as soybeans and rapeseed, providing a valuable feed ingredient for animal production. Demand is linked to the need for reliable protein supplies, growth in livestock farming, and the production of meat, milk, and eggs.
Oil Processing remains a major application of oilseeds, driven by demand for edible oils, food ingredients, and industrial feedstocks. In 2025, the United States processed 75.2 million tons of soybeans to produce crude oil, an increase of 7% from 2024. Crude soybean oil production reached 29.5 billion pounds, also rising 7% year over year. These figures highlight the scale of oilseed processing and its role in supplying food manufacturers and other industries.
Key Market Segments
By Product Type
- Oilseeds
- Soybean
- Sunflower
- Canola (rapeseed)
- Others
- Grain / Cereal Seeds
- Corn (maize)
- Wheat
- Rice
- Others
By Breeding Technology
- Hybrids
- Open-Pollinated Varieties (OPVs)
- Conventional Seeds
By Biotech Trait
- Genetically Modified (GM) / Herbicide-Tolerant
- Genetically Modified (GM) / Insect-Resistant
- Genetically Modified (GM) / Stacked Traits
- Conventional / Non-GM
By Application
- Oil Processing (Edible Oils & Biofuels)
- Animal Feed / Oilseed Meals
- Human Food Products
- Sowing / Seed Multiplication
Driver Analysis
Biofuel Oil Demand
Biofuel policy is raising the commercial value of soybean, rapeseed, sunflower, canola, palm, and other oilseed genetics because vegetable oil is increasingly purchased not only by food processors but also by renewable-diesel, biodiesel, and sustainable-aviation-fuel value chains that reward predictable oil volume, fatty-acid profile, harvestability, and regional feedstock availability.
Approximately 18% of global vegetable-oil supply is already used for biomass-based diesel, compared with 52% used directly in food and food preparation, and the OECD–FAO outlook identifies the United States, European Union, Indonesia, and Brazil as the four largest biomass-based-diesel markets; Indonesia’s vegetable-oil use for biodiesel is projected to reach 12.6 million tonnes by 2034.
In the United States, soybean oil use for biofuel is forecast at 17.8 billion pounds in 2026/27, up 3.0 billion pounds from 2025/26, with soybean oil accounting for about 40% of feedstocks used in biomass-based diesel during 2026; this makes seed traits that protect oil yield, reduce harvest loss, improve stress tolerance, or enable double-cropping financially more valuable to growers and crushers. The business-model impact is a shift from selling seed solely on yield per hectare toward capturing value through trait premiums, acreage contracts, identity-preserved supply programs, and seed-plus-advisory packages tied to crusher and fuel-refinery demand.
While global biofuel-driven vegetable-oil growth is expected to moderate to about 0.7% annually over the next decade after the prior decade’s much faster expansion, its effect on seed mix remains material because it influences profitability and crop switching at the farm level. This driver adds an estimated +1.7 percentage points to combined oilseed and grain seed CAGR through 2028–2030, led by the United States, Brazil, Indonesia, and the EU.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Biofuel oil demand | +1.7 pp | U.S., Brazil, Indonesia, EU | Medium term (2–4 years) |
| Yield-led cereal expansion | +1.5 pp | India, China, Africa, LatAm | Long term (≥ 4 years) |
| Climate-resilient varieties | +1.4 pp | North America, EU, India, Africa | Medium term (2–4 years) |
| Genomic breeding reform | +1.2 pp | EU, UK, Japan, Australia | Long term (≥ 4 years) |
| High input-cost economics | +1.1 pp | Global; India, Brazil, Africa | Short term (≤ 2 years) |
| Seed traceability digitization | +0.8 pp | India, China, EU, North America | Medium term (2–4 years) |
Restraint Analysis
Farm-Saved Seed Dependence
FAO notes that in some countries well over 70% of seed even for major crops—remains within informal systems, while a six-country African dataset covering 9,660 observations and 40 crops found that farmers sourced 90.2% of seed from informal channels and 50.9% from local markets; only 9.8% came from sources considered formal, including agro-dealers, government, NGOs, or contract growers.
For oilseeds and self-pollinated grains such as soybean, wheat, rice, pulses, and groundnut, growers can retain seed for one to three seasons, avoiding a cash outlay that may equal USD 20–100/ha, whereas hybrid maize, sunflower, rapeseed, and some sorghum varieties retain stronger replacement economics because segregating progeny dilute hybrid vigor.
The commercial impact is lower annual replacement rates, weaker royalty capture, smaller dealer inventory turns, and limited farmer data visibility; a seed company selling into a region with a 25% certified-seed replacement rate needs roughly four times the grower base required in a 100% replacement market to generate equivalent seasonal volume.
Formalization is constrained by limited rural credit, weak local multiplication capacity, uncertain varietal availability, and farmer preference for locally adapted seed, meaning the remedy requires multi-year investment in affordable small packs, community seed producers, trusted demonstration plots, and quality-declared seed systems rather than simple price discounts. This structural leakage subtracts an estimated -1.3 percentage points from 2026–2031 CAGR across Africa, South Asia, Latin America, and Central Asia.
Restraint Impact Analysis
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Farm-Saved Seed Dependence | -1.3 pp | Africa, South Asia, LatAm, Central Asia | Long term (≥ 4 years) |
| Fertilizer-Driven Cash Squeeze | -1.0 pp | India, Africa, MENA, Latin America | Short term (≤ 2 years) |
| Counterfeit Seed Leakage | -0.9 pp | Africa, India, Southeast Asia, LatAm | Medium term (2–4 years) |
| Regulatory Approval Delays | -0.7 pp | EU, China, India, Brazil | Long term (≥ 4 years) |
| Seed Multiplication Bottlenecks | -0.6 pp | Global hybrid-seed regions | Medium term (2–4 years) |
| Climate-Driven Crop Failures | -0.5 pp | Africa, South Asia, LatAm, Australia | Short term (≤ 2 years) |
Opportunity Analysis
Seed-as-a-Service Bundles
The unexploited opportunity is to move from seasonal seed-unit sales into Seed-as-a-Service contracts that combine seed, seed treatment, agronomic prescriptions, weather advisory, crop-establishment support, input finance, and output-market linkage under a per-hectare or harvest-linked payment model; this is a strategic monetization pivot rather than a current driver because most suppliers still recognize revenue when seed is dispatched to distributors.
A bundled program priced at an analyst-modeled USD 45–120/ha for hybrid maize, sunflower, canola, rice, soybean, or wheat could raise supplier revenue per managed hectare by 20–50% versus seed-only sales, improve renewal rates from an estimated 45–60% in dealer-led channels to 70–85% where agronomic outcomes are documented, and lower customer-acquisition cost by 15–30% through cooperative, aggregator, and lender partnerships.
The economics are strengthened by high input-price volatility: global fertilizer prices were projected to increase 31% in 2026, with urea prices expected to rise 60%, making seed choices that improve nutrient response and crop establishment more valuable to growers.
Suppliers can finance adoption through deferred payment at harvest, but must cap exposure using credit scoring, parametric weather cover, and crop-offtake agreements; an initial 10,000-ha program could require USD 0.5–1.2 million of seasonal working capital yet generate multi-year data and cross-sell economics. India, Brazil, the United States, and EU grain belts are the highest-priority markets because digital advisory and formal input distribution already exist; if service bundles reach 10–15% of commercial acres by 2031, the model estimates +1.6 percentage points of incremental CAGR upside.
Opportunity Impact Analysis
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Seed-as-a-Service bundles | +1.6 pp | India, Brazil, U.S., EU | Short term (≤ 2 years) |
| Climate-resilience data platforms | +1.4 pp | Africa, India, LatAm, Australia | Medium term (2–4 years) |
| NGT trait licensing | +1.3 pp | EU, UK, Japan, Australia | Long term (≥ 4 years) |
| Oilseed biofuel contracting | +1.1 pp | U.S., Brazil, Indonesia, EU | Medium term (2–4 years) |
| Regional seed-platform roll-ups | +0.9 pp | India, Africa, Brazil, Southeast Asia | Medium term (2–4 years) |
| Traceable seed marketplaces | +0.8 pp | India, China, Africa, LatAm | Short term (≤ 2 years) |
Challenges Analysis
Parent-Line Multiplication Volatility
A hybrid maize, sunflower, canola, sorghum, or rice multiplication field may produce only 1–3 tonnes/ha of saleable seed versus 4–10 tonnes/ha in a commercial grain field, so a 20–35% reduction in pollination success, germination, or genetic-purity pass rate can remove enough inventory to disrupt 1–2 planting seasons rather than merely reduce margin.
Heat, rainfall during anthesis, drought, disease, male-female flowering mismatch, labor unavailability, or a failed parental seed increase can turn a planned 10,000-tonne production program into 6,500–8,000 tonnes of certifiable product, forcing emergency imports, dealer allocation, substitution with lower-performing legacy varieties, or lost sales; maintaining 15–25% safety stock limits stockouts but raises working-capital requirements and exposure to 12-month viability loss.
The pressure is rising because cereal output is projected to depend primarily on yield gains—global cereal yields are expected to increase 0.9% annually to reach approximately 4.2 tonnes/ha by 2034—which expands portfolio complexity as suppliers maintain more localized stress-tolerant hybrids rather than fewer broad-acre varieties.
Mitigation requires geographically diversified multiplication, predictive flowering models, irrigation back-up, male-line redundancy, digital field monitoring, contracted labor pools, and 18–24 months of forward parent-stock planning, yet biological dependence on weather and synchrony makes this a long-horizon challenge with an estimated -0.8-percentage-point CAGR friction drag across global hybrid-seed markets.
Challenges Impact Analysis
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Parent-Line Multiplication Volatility | -0.8 pp | Global hybrid-seed regions | Long term (≥ 4 years) |
| Climate-Localized Trial Gaps | -0.7 pp | Africa, India, LatAm, Australia | Long term (≥ 4 years) |
| Phytosanitary Trade Friction | -0.7 pp | APAC, EU, Americas, Africa | Medium term (2–4 years) |
| Breeding-Talent Scarcity | -0.6 pp | North America, EU, India, China | Long term (≥ 4 years) |
| Counterfeit-Channel Intelligence Gaps | -0.6 pp | Africa, South Asia, Southeast Asia, LatAm | Medium term (2–4 years) |
| Trait-Data Interoperability | -0.5 pp | North America, EU, Brazil, China | Medium term (2–4 years) |
Geopolitical Impact Analysis
Geopolitical Impact of Ongoing Wars on the Oilseed Market and Grain Seed Market
Ongoing conflicts, particularly the Russia–Ukraine war and instability affecting Black Sea shipping routes, continue to create uncertainty for global oilseed and grain supply chains. Disruptions to ports, higher insurance premiums, changing trade routes, and increased fuel and fertilizer costs can raise production and transportation expenses. Ukraine is an important supplier of sunflower oil, corn, and other agricultural commodities, so interruptions to its exports can tighten global supplies and encourage buyers to seek alternatives from Brazil, the United States, and other producing countries.
The impact is reflected in current market data. The Food and Agriculture Organization of the United Nations (FAO) reported in October 2026 that global cereal trade for the 2026/27 season was forecast at 505.8 million tonnes, down 3.5% from the previous season, with constrained Black Sea shipping routes contributing to lower export expectations.
Higher freight and fertilizer costs may also affect seed production, farm profitability, and planting decisions. For oilseed and grain seed suppliers, the conflict creates opportunities to expand production in alternative regions, diversify sourcing, and improve storage capacity. However, prolonged disruption could keep commodity prices volatile and make seed, feed, and vegetable oil supplies less predictable.
Regional Insights
Dominating Region: North America
In 2025, North America held a dominant market position, capturing 34.70% of the market, valued at USD 38.7 billion. The region benefits from large-scale farming, advanced seed technology, established agricultural supply chains, and strong demand for oilseeds and grain crops. The United States is a major contributor, with soybeans accounting for approximately 90% of its oilseed production, according to the United States Department of Agriculture (USDA).
In 2025, U.S. soybean production reached 4.26 billion bushels, while corn production reached a record 17.0 billion bushels. These figures demonstrate the region’s strong production base and support demand for improved seeds, crop traits, and seed treatment solutions.
Asia-Pacific presents significant growth opportunities, supported by rising demand for food, vegetable oils, animal feed, and higher-yielding crop varieties. Expanding agricultural mechanization and investment in hybrid seeds and crop improvement are also encouraging seed adoption. The USDA projected global soybean production at 420.87 million metric tonnes for the 2025/26 marketing year, highlighting the scale of international oilseed supply and trade.
In Asia-Pacific, demand from food processors and livestock producers supports interest in soybean, corn, and other grain seeds. Climate-resilient varieties, improved seed quality, and stronger distribution networks offer further opportunities for seed companies. However, weather variability, input costs, and changing trade policies can affect regional growth.
Key Regions and Countries Insights
- North America
- US
- Canada
- Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Key Players Analysis
Bayer AG strengthens its position in the oilseed and grain seed industry through its Crop Science division, which develops seeds and crop protection products. In 2025, Bayer’s Crop Science sales reached €21.622 billion, with currency- and portfolio-adjusted growth of 1.1%. Corn seed and trait products were key growth drivers, helping offset regulatory and competitive pressures. The company continues to focus on seed innovation, crop productivity, and improved agricultural solutions for farmers.
Corteva Agriscience is a major supplier of hybrid seeds, soybean seeds, and crop traits for agricultural producers. In 2025, its Seed segment generated USD 9.898 billion in net sales, compared with USD 9.545 billion in 2024. North America contributed USD 6.271 billion, making it the company’s largest seed sales region. Its Pioneer and Brevant brands support corn, soybean, and other crop production. Corteva focuses on seed development, crop performance, and technologies that help farmers manage weeds and improve productivity.
Syngenta Group serves the oilseed and grain seed market through its field crop and vegetable seed businesses. In 2025, its Seeds division recorded USD 4.8 billion in sales, representing a 2% increase from the previous year. Field crop performance benefited from stronger sales in Brazil, where sales increased 17%, while Latin America grew 10%. The company also introduced 2 new corn hybrids and 6 soybean varieties in Brazil, strengthening its seed portfolio and supporting farmers seeking productive crop varieties.
Top Key Players Outlook
- Bayer AG
- Corteva Agriscience
- Syngenta Group
- BASF SE
- Groupe Limagrain
- KWS SAAT SE & Co. KGaA
- DLF Seeds A/S
- Advanta Seeds
- RAGT Semences
- LongPing High-Tech
- Gansu Dunhuang Seed Group Co., Ltd.
- Mahyco Private Limited
- Land O’Lakes, Inc. – WinField United
- Nuziveedu Seeds Limited
- Rallis India Limited
Recent Developments
- In May 2026, Groupe Limagrain European Investment Bank granted Limagrain a €300 million loan to support seed innovation and sustainable agriculture. In July 2026, Limagrain and Qi Biodesign signed a worldwide licensing agreement for genome-editing technologies to accelerate the development of next-generation crop varieties.
- In April 2026, BASF announced a €40 million investment to modernize and expand its seed-processing facilities in Nunhem, Netherlands, with completion expected by the end of 2028.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 111.6 Bn |
| Forecast Revenue (2035) | USD 342.6 Bn |
| CAGR (2026-2035) | 11.9% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Oilseeds, Grain / Cereal Seeds), By Breeding Technology (Hybrids, Open-Pollinated Varieties (OPVs), Conventional Seeds), By Biotech Trait (Genetically Modified (GM) / Herbicide-Tolerant, Genetically Modified (GM) / Insect-Resistant, Genetically Modified (GM) / Stacked Traits, Conventional / Non-GM), By Application (Oil Processing (Edible Oils & Biofuels), Animal Feed / Oilseed Meals, Human Food Products, Sowing / Seed Multiplication) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | Bayer AG, Corteva Agriscience, Syngenta Group, BASF SE, Groupe Limagrain, KWS SAAT SE & Co. KGaA, DLF Seeds A/S, Advanta Seeds, RAGT Semences, LongPing High-Tech, Gansu Dunhuang Seed Group Co., Ltd., Mahyco Private Limited, Land O’Lakes, Inc. – WinField United, Nuziveedu Seeds Limited, Rallis India Limited |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








