


Market Overview
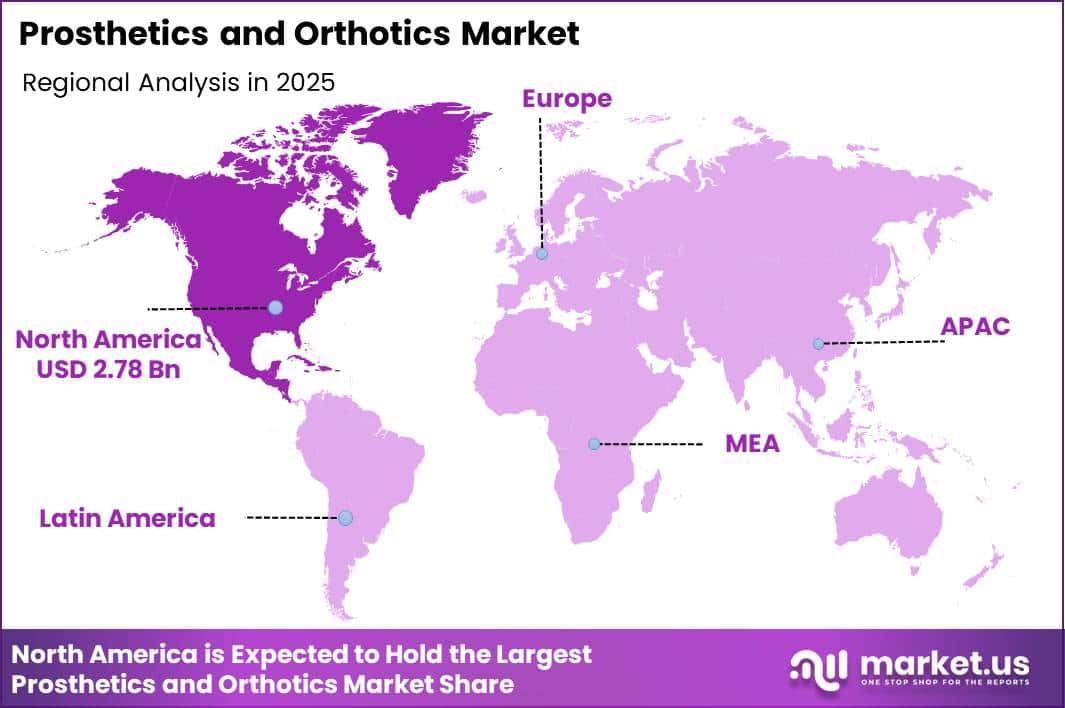
The Global Prosthetics and Orthotics Market size is expected to be worth around US$ 11.4 Billion by 2035 from US$ 7.1 Billion in 2025, growing at a CAGR of 4.8% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 39.1% share with a revenue of US$ 2.78 Billion.
The global prosthetics and orthotics market is witnessing steady growth as healthcare systems increasingly prioritize rehabilitation, mobility restoration, and long-term disability care. Prosthetic devices replace missing limbs, while orthotic devices support or correct weakened muscles and joints, helping people regain independence and improve their quality of life.
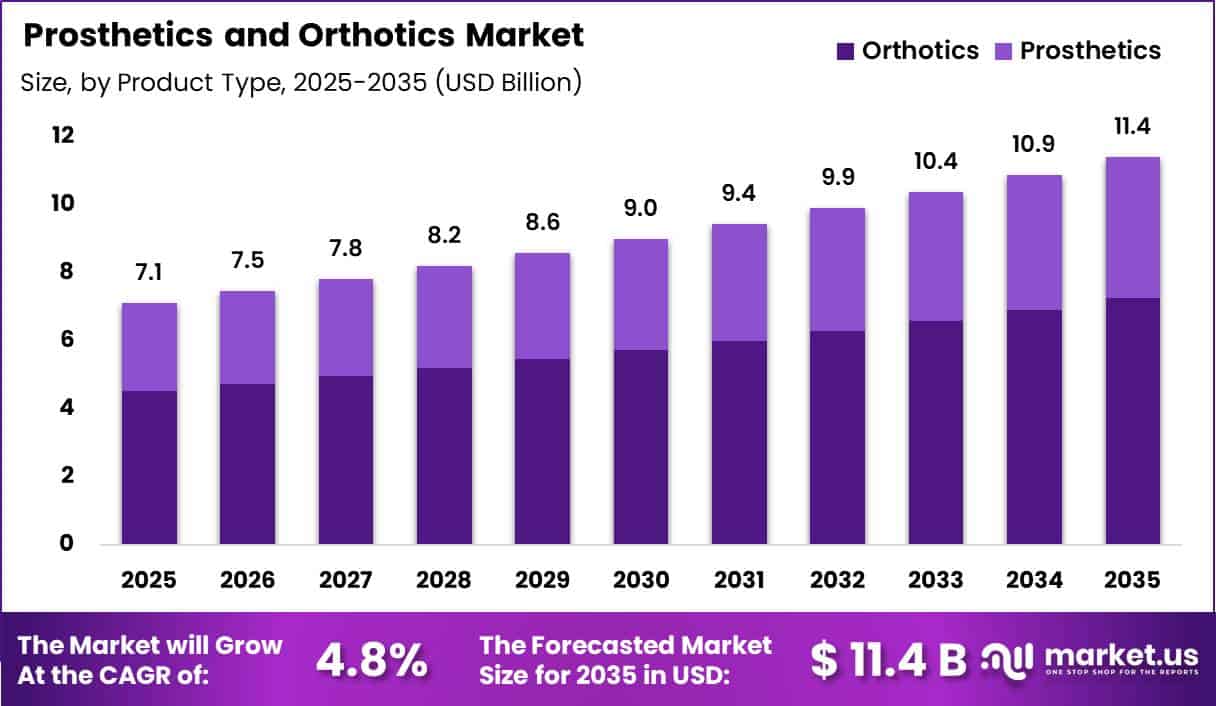
Rising cases of diabetes, trauma injuries, vascular diseases, congenital limb conditions, and an aging population are driving the need for advanced prosthetic and orthotic solutions worldwide. Governments and healthcare organizations are also strengthening rehabilitation services and improving access to assistive technologies, creating favorable conditions for market expansion.
According to the World Health Organization (WHO), approximately 2.4 billion people globally could benefit from rehabilitation services, while more than 2.5 billion people currently need at least one assistive product, including prosthetic limbs and orthotic devices. This demand is expected to increase to 3.5 billion people by 2050 due to population aging and the growing burden of chronic diseases.
WHO also estimates that only 1 in 10 people who require assistive products currently have adequate access, highlighting a significant unmet need for prosthetic and orthotic services.
Additionally, WHO standards indicate that around 0.5% of the global population, equivalent to 35–40 million people, may require prosthetic and orthotic services, with orthotic care needed by two to four times more people than prosthetic care.
Continuous innovation in lightweight materials, digital scanning, 3D printing, and microprocessor-controlled devices is further enhancing patient outcomes and supporting long-term market growth.
Key Takeaways
- Market Size: The Global Prosthetics and Orthotics Market size was US$ 7.1 billion in 2025. The market is estimated to grow to US$ 11.4 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 4.8%.
- Product Type: Orthotics has the largest market share, accounting for 63.5% of total sales.
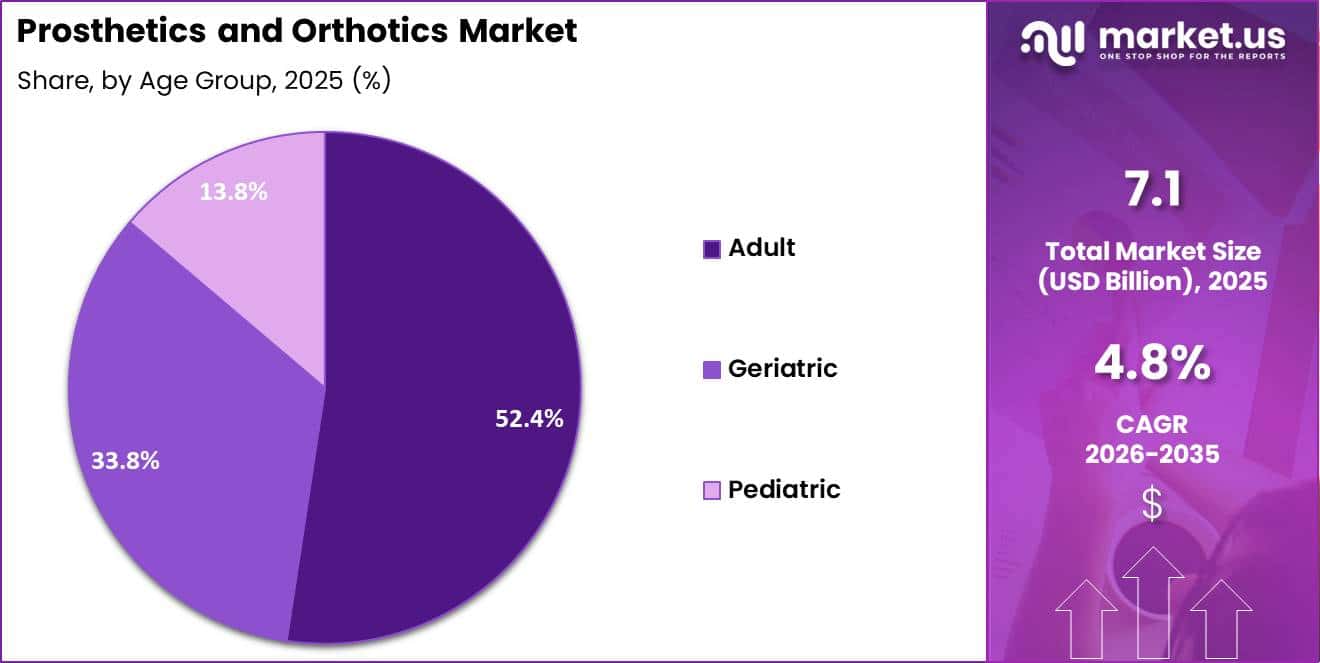
- Age Group: Adults dominate the segment, accounting for 52.4% of total revenue.
- Application: Osteoarthritis leads the segment, accounting for 19.1% of total revenue.
- End User: Prosthetic & Orthotic Clinics dominate the segment, accounting for 37.2% of total revenue.
- Regional: North America is the dominant regional market, accounting for 39.1% of global sales.
Product Type Analysis
The Orthotics segment dominated the global prosthetics and orthotics market in 2025, accounting for 63.5% of the total market share. The segment’s leadership is driven by the rising prevalence of musculoskeletal disorders, osteoarthritis, diabetic foot complications, scoliosis, and sports-related injuries that require external support devices rather than limb replacement.
Orthotic products, including spinal braces, ankle-foot orthoses, knee braces, and customized insoles, are increasingly prescribed to improve mobility, reduce pain, and prevent further joint damage.
Growing awareness of early intervention, advancements in lightweight composite materials, and wider availability of customized 3D-printed orthotic devices further support market expansion. The increasing aging population also contributes significantly, as elderly individuals frequently require orthotic support for chronic orthopedic conditions.
Meanwhile, the Prosthetics segment held 36.5% of the market in 2025. Demand for upper-limb and lower-limb prosthetic devices continues to increase due to traumatic injuries, diabetes-related amputations, vascular diseases, and congenital limb deficiencies.
Technological innovations such as microprocessor-controlled knees, myoelectric prosthetic limbs, AI-assisted movement systems, and advanced sensor integration are improving patient mobility, comfort, and functionality, making prosthetic solutions more effective and widely accepted across healthcare systems.
Age Group Analysis
The Adult segment accounted for the largest share of the global prosthetics and orthotics market in 2025, representing 52.4% of total revenue. Adults experience a high incidence of traumatic injuries, workplace accidents, sports injuries, obesity-related orthopedic disorders, diabetes complications, and degenerative joint diseases that require prosthetic or orthotic interventions.
Rising employment participation and active lifestyles also increase demand for mobility-restoring devices that enable individuals to maintain productivity and independence.
Technological improvements, better reimbursement policies, and greater access to rehabilitation services continue to strengthen adoption among working-age populations.
The Geriatric segment represented 33.8% of the market in 2025. Growing life expectancy and the increasing prevalence of osteoporosis, osteoarthritis, peripheral vascular disease, and balance disorders are driving demand for supportive orthotic devices and lower-limb prosthetics among elderly patients.
Meanwhile, the Pediatric segment captured 13.8% of the market. Children with congenital limb deficiencies, cerebral palsy, scoliosis, and neuromuscular disorders require specialized prosthetic and orthotic devices designed to accommodate continuous physical growth.
Advances in pediatric customization, lightweight materials, and adjustable designs are improving comfort, mobility, and long-term treatment outcomes.
Application Analysis
The Osteoarthritis segment dominated the global Prosthetics and Orthotics Market in 2025, accounting for 19.1% of the market share. The increasing prevalence of osteoarthritis, particularly among aging populations and individuals with obesity, has significantly increased demand for orthopedic braces, knee supports, ankle-foot orthoses, and customized mobility devices.
These products help reduce pain, improve joint stability, and delay the need for surgical procedures, making them an essential component of conservative disease management.
Growing awareness of rehabilitation therapies and the expansion of orthopedic care services further strengthen this segment. Trauma & Accident Rehabilitation represents another important application, supported by rising road traffic injuries and workplace accidents worldwide. Diabetes-Related Limb Loss continues to expand due to increasing diabetes prevalence and associated complications requiring lower-limb prostheses.
Other significant applications include Vascular Diseases, Congenital Limb Deficiencies, Cerebral Palsy, Stroke Rehabilitation, Sports Injuries, Spinal Disorders, and Neuromuscular Disorders, each contributing to steady market demand through specialized rehabilitation needs.
The Others category includes rare orthopedic and neurological conditions requiring customized prosthetic and orthotic solutions. Continuous innovation in digital fitting technologies and patient-specific device manufacturing is improving treatment outcomes across all application segments.
End User Analysis
The Prosthetic & Orthotic Clinics segment dominated the global prosthetics and orthotics market in 2025, accounting for 37.2% of total market revenue. These specialized clinics provide comprehensive patient assessment, device customization, fitting, alignment, maintenance, and rehabilitation services in one setting.
Their ability to deliver personalized care using advanced digital scanning, gait analysis, and 3D-printing technologies has strengthened patient outcomes and satisfaction.
Increasing referrals from orthopedic surgeons, rehabilitation specialists, and primary care physicians further support the growth of dedicated prosthetic and orthotic clinics worldwide. Hospitals represent another major end-user segment, particularly for post-surgical rehabilitation, trauma care, and complex orthopedic treatments requiring multidisciplinary management.
Rehabilitation Centers continue to witness strong demand due to structured physical therapy programs that improve patient mobility and recovery. Ambulatory Surgical Centers (ASCs) are increasingly adopting prosthetic and orthotic services as outpatient orthopedic procedures expand. Long-Term Care Facilities utilize supportive devices to enhance mobility among elderly residents with chronic musculoskeletal conditions.
Military & Veterans Healthcare Facilities remain important users due to rehabilitation needs associated with combat-related injuries and limb loss. The Others segment includes community healthcare providers, specialty medical centers, and academic institutions supporting prosthetic and orthotic care.
Key Market Segments
By Product Type
- Prosthetics
- Upper Limb Prosthetics
- Transradial
- Transhumeral
- Shoulder Disarticulation
- Partial Hand
- Lower Limb Prosthetics
- Transtibial
- Transfemoral
- Knee Disarticulation
- Hip Disarticulation
- Partial Foot
- Prosthetic Liners
- Prosthetic Sockets
- Prosthetic Joints
- Prosthetic Components & Accessories
- Upper Limb Prosthetics
- Orthotics
- Spinal Orthotics
- Cervical Orthoses
- TLSO
- LSO
- Lower Limb Orthotics
- Foot Orthoses
- Ankle-Foot Orthoses (AFO)
- Knee-Ankle-Foot Orthoses (KAFO)
- Knee Orthoses
- Hip Orthoses
- Upper Limb Orthotics
- Wrist
- Elbow
- Shoulder
- Hand Orthoses
- Cranial Orthotics
- Pediatric Orthotics
- Spinal Orthotics
By Age Group
- Pediatric
- Adult
- Geriatric
By Application
- Trauma & Accident Rehabilitation
- Diabetes-Related Limb Loss
- Vascular Diseases
- Congenital Limb Deficiencies
- Osteoarthritis
- Cerebral Palsy
- Stroke Rehabilitation
- Sports Injuries
- Spinal Disorders
- Neuromuscular Disorders
- Others
By End User
- Hospitals
- Prosthetic & Orthotic Clinics
- Rehabilitation Centers
- Ambulatory Surgical Centers (ASCs)
- Long-Term Care Facilities
- Military & Veterans Healthcare Facilities
- Others
Driver
Diabetes Linked Amputation Load Driving Prosthetics and Orthotics Demand
Diabetes is a major volume driver because it expands the addressable population requiring both prosthetic limbs after lower-extremity amputation and orthotic interventions for gait instability, pressure offloading, and musculoskeletal compensation.
WHO reports that global diabetes cases increased from 200 million in 1990 to 830 million in 2022, with faster prevalence growth occurring in low- and middle-income countries.
CDC reporting shows US diabetes prevalence reached 13.5% during 2021–2023, representing approximately 40.1 million people living with diabetes in 2023, while NIDDK notes that around 200,000 amputations occur annually in the US, including approximately 130,000 among people with diabetes.
For the prosthetics and orthotics industry, this expands demand beyond episodic device purchases into recurring clinical pathways, including post-amputation prosthetic fitting, liner and socket replacement, contralateral limb protection, neuropathy-related bracing, and rehabilitation monitoring.
The commercial implication is that diabetes creates a high-value, long-duration patient pathway rather than a single-device opportunity. Even if only a small % of the global diabetic population progresses to advanced prosthetic or orthotic needs, these patients typically require multiple clinical interactions annually, periodic refitting as residual limb volume changes, and ongoing demand for ancillary components such as sleeves, feet, knees, braces, and maintenance services.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Diabetes-linked amputation load | +1.4% | North America core, GCC, India, China, Latin America urban centers | Short term |
| Ageing mobility impairment demand | +1.1% | EU, Japan, South Korea, North America, China coastal provinces | Medium term |
| Reimbursement and fee schedule uplift | +0.9% | US core, Western Europe selective, Australia | Short term |
| Digital scanning and 3D printed fabrication | +1.0% | North America, EU, China, India private networks | Medium term |
| Rehab-integrated outcomes care models | +0.8% | US, EU, Japan, tertiary hospital clusters in APAC | Medium term |
| Assistive access and disability policy expansion | +0.7% | LMIC public systems, Africa pilots, South Asia, ASEAN | Long term |
Challenge
Fragmented Workforce Regulation Limiting Orthotic and Prosthetic Market Growth
Fragmented regulation of the orthotist/prosthetist workforce creates systemic friction by limiting cross-border recognition, complicating quality assurance, and slowing service expansion even as clinical demand continues to rise.
A global workforce review found that only about 15% of countries have formal national-level regulation for orthotist/prosthetists, and only a smaller subset maintain all core regulatory standards, meaning that many practitioners operate in environments with limited or absent oversight.
Such fragmentation creates an estimated 0.8-point drag on potential CAGR by increasing payer and policymaker caution, delaying reimbursement inclusion for advanced orthotic and prosthetic devices, and creating service bottlenecks when cross-regional recruitment is required. Licensing and credential-recognition processes can extend hiring timelines by 6–12 months for multinational providers attempting to scale clinical networks.
Over a 2–4-year mitigation horizon, strategic responses involve collaboration between professional bodies and governments to establish national registers, define protected professional titles, standardize continuing education requirements, and align training frameworks with international education standards. These measures can improve practitioner availability and support progress toward recommended workforce density levels.
For companies, fragmented regulation requires localized market-entry strategies, investment in practitioner training programs, structured clinical evidence generation, and adaptable post-market surveillance systems.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Chronic access gap | -1.3% | LMICs, emerging APAC, Africa | Long term (≥ 4 years) |
| Fragmented workforce regulation | -0.8% | Global, esp. LMICs | Medium term (2-4 years) |
| Skilled clinician shortage | -1.0% | UK, North America, Australasia | Long term (≥ 4 years) |
| Reimbursement complexity | -0.9% | US, EU, mixed-coverage markets | Medium term (2-4 years) |
| Data and outcomes deficit | -0.7% | Global clinical systems | Long term (≥ 4 years) |
| Standards adoption gap | -0.6% | LMICs, decentralized systems | Medium term (2-4 years) |
Restraints
CMS Prior Authorization Expansion Increasing Orthotic Reimbursement Friction
CMS expanded prior authorization requirements for additional DMEPOS orthotic codes effective April 13, 2026, adding five orthotic HCPCS codes to the nationwide prior authorization list. This increases documentation requirements before device delivery and raises the likelihood of claim friction, rejection, and resubmission cycles.
For providers, this typically converts same-week fulfilment models into multi-step approval workflows that can add 7–21 days to cash conversion, increase administrative workload by roughly 1.0–2.5 FTE equivalents per mid-sized clinic, and require higher working-capital buffers for inventory management and patient-specific fabrication.
The restraint is most pronounced in the U.S., where Medicare policy often influences commercial payer behavior, resulting in lower throughput, slower revenue recognition, and an estimated 0.8 %-point near-term CAGR drag.
The market also faces persistent payment friction due to CMS coverage definitions, Medicare Part B processing requirements, and payer documentation standards requiring precise clinical justification.
2026 billing guidance reflects tighter authorization criteria, expanded audits, and increased scrutiny of proof-of-delivery records, serial-number traceability, and fabrication documentation.
In practice, even approved claims may remain in accounts receivable for 45–90 days, with denial rates increasing when clinical notes are incomplete or device coding does not align with payer requirements. This directly pressures small and mid-sized orthotics and prosthetics practices operating with limited billing resources and narrow EBITDA margins.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| CMS prior auth expansion | -0.8% | U.S. core | Short term (≤ 2 years) |
| Reimbursement lag | -0.7% | North America, parts of the EU | Short term (≤ 2 years) |
| Skilled workforce gap | -0.9% | U.S., UK, EU urban centers | Medium term (2-4 years) |
| Input cost inflation | -0.6% | Global, APAC manufacturing | Medium term (2-4 years) |
| Customization lead times | -0.5% | North America, EU, APAC | Short term (≤ 2 years) |
| Regulatory fragmentation | -0.4% | Cross-border markets | Long-term (≥ 4 years) |
Opportunity
Integrated Geriatric Mobility Ecosystems Creating New Growth Opportunities
Integrated geriatric mobility ecosystems shift the prosthetics and orthotics value proposition from standalone devices toward holistic mobility solutions for older adults, leveraging the steadily rising number of households with mobility limitations in aging societies through 2035.
Instead of treating orthotics for spinal, lower limb, or balance-related conditions as isolated prescriptions, this approach bundles devices with home-based rehabilitation, fall-prevention systems, and digital monitoring platforms targeted at millions of households where mobility limitations and self-care challenges are increasingly expected to coexist, particularly across North America, Europe, Japan, and China.
If 10–20% of mobility-impaired older households are converted into multi-product and multi-service contracts with annual per-household spending 2–3 times current single-device outlays, manufacturers and care networks can increase average revenue per mobility patient by 50–100%.
Incremental service margins could exceed 40% because ecosystem components, including education, remote check-ins, and basic digital tools, can be delivered at relatively low cost once scaled.
As mobility limitations among adults aged 80 and above continue to rise, this ecosystem model could add approximately 1.6 % points of CAGR upside compared with baseline expectations by transforming geriatric mobility from an episodic device-replacement market into a managed, subscription-like care category.
The opportunity is particularly strong in healthcare systems focused on reducing fall-related hospitalizations, improving independence, and lowering long-term care costs.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Value-based limb salvage & post-amputation care bundles | +2.0% | North America, EU, select APAC | Medium term (2-4 years) |
| AI-driven personalized fit & remote adjustment platforms | +1.8% | North America core, EU, urban APAC | Short term (≤ 2 years) |
| Low-cost modular prosthetics & orthotics for emerging markets | +2.5% | APAC emerging, Africa, LATAM | Long-term (≥ 4 years) |
| Integrated geriatric mobility ecosystems | +1.6% | North America, EU, Japan, China | Medium term (2-4 years) |
| Diabetes-focused preventative orthotic pathways | +2.2% | North America, EU, Middle East, India | Medium term (2-4 years) |
| Digital twin–enabled R&D and mass customization | +1.5% | Global leading manufacturers | Long-term (≥ 4 years) |
Regional Analysis
In 2025, North America led the market, achieving over 39.1% market share with revenue of US$ 2.78 billion. The region benefits from a well-established healthcare infrastructure, high healthcare spending, favorable reimbursement policies, and widespread adoption of advanced prosthetic and orthotic technologies.
The United States leads regional demand due to the growing prevalence of diabetes, peripheral vascular disease, traumatic injuries, and an expanding elderly population requiring mobility assistance.
Strong investments in rehabilitation services, digital prosthetic manufacturing, microprocessor-controlled devices, and 3D printing technologies further support market growth.
Europe represents the second-largest regional market, driven by rising cases of musculoskeletal disorders, osteoarthritis, and an aging population.
Government-funded healthcare systems and increasing access to rehabilitation programs across countries such as Germany, France, the United Kingdom, and Italy continue to strengthen the adoption of customized orthotic and prosthetic solutions. Continuous innovation and supportive regulatory frameworks also contribute to regional expansion.
Asia Pacific is projected to register the fastest growth during the forecast period. Rapid improvements in healthcare infrastructure, increasing awareness of rehabilitation services, expanding healthcare expenditure, and a growing diabetic population are fueling demand in countries including China, Japan, India, South Korea, and Australia.
Government initiatives to improve accessibility to assistive technologies and rehabilitation services are creating new growth opportunities.
Latin America, the Middle East, and Africa are experiencing steady market development due to improving healthcare access, rising investments in rehabilitation centers, increasing trauma cases, and greater availability of prosthetic and orthotic services through public health programs and international healthcare initiatives.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
Competitive advantage in the global prosthetics and orthotics market is driven by comprehensive product portfolios covering prosthetic and orthotic solutions across upper limb, lower limb, spinal, and pediatric applications, supported by established relationships with prosthetic and orthotic clinics, hospitals, and rehabilitation centers.
Leading manufacturers are also strengthening their market positions through continued investment in advanced materials, microprocessor-controlled joint technologies, and digital scanning and fabrication capabilities, which contribute to improved patient outcomes, enhanced functionality, and greater fitting precision.
ey strategic priorities include the expansion of microprocessor-controlled knee and ankle prosthetic systems to address the increasing demand for functional mobility solutions among adult and geriatric patients, alongside the development of 3D printing and CAD/CAM-based orthotic fabrication technologies that can reduce production timelines and improve customization and fit accuracy.
In addition, manufacturers are increasingly expanding distribution and institutional partnerships with rehabilitation centers, military and veterans healthcare facilities, and other specialized care providers to address diverse clinical requirements associated with trauma, diabetes-related complications, neurological disorders, and other conditions requiring prosthetic and orthotic intervention.
Top Key Players
- Ottobock Healthcare
- Össur
- Hanger Inc.
- Blatchford Group
- Fillauer Companies
- Nakamura Brace
- Proteor
- College Park Industries
- WillowWood
- Steeper Group
- Endolite
- DJO Global
- Becker Orthopedic
- Aspen Medical Products
- Thuasne
- Other Key Players
Recent Developments
- In January 2026, Ottobock Healthcare launched an expanded microprocessor-controlled transfemoral prosthetic knee system with enhanced gait adaptation algorithms, targeting prosthetic and orthotic clinics and rehabilitation centers seeking improved functional mobility outcomes for above-knee amputee patients.
- In February 2026, Össur introduced a new 3D-printed transtibial prosthetic socket fabrication service integrating digital scanning and CAD/CAM manufacturing, targeting prosthetic clinic institutional buyers seeking reduced patient fitting timelines and improved custom socket comfort outcomes.
- In March 2026, Hanger Inc. expanded its pediatric orthotics service capabilities with new AFO and KAFO fabrication technologies, targeting pediatric rehabilitation center and hospital institutional buyers seeking improved orthotic solutions for children with cerebral palsy and neuromuscular disorder indications.
- In April 2026, DJO Global secured a multi-year supply agreement with a leading Asian hospital and rehabilitation center network covering its spinal orthotic and lower limb orthotic product portfolio, expanding its institutional presence across osteoarthritis and stroke rehabilitation patient management programs in the region.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 7.1 Billion |
| Forecast Revenue (2035) | US$ 11.4 Billion |
| CAGR (2026-2035) | 4.8% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Prosthetics, Orthotics), By Age Group (Pediatric, Adult, Geriatric), By Application (Trauma & Accident Rehabilitation, Diabetes-Related Limb Loss, Vascular Diseases, Congenital Limb Deficiencies, Osteoarthritis, Cerebral Palsy, Stroke Rehabilitation, Sports Injuries, Spinal Disorders, Neuromuscular Disorders, Others), By End User (Hospitals, Prosthetic & Orthotic Clinics, Rehabilitation Centers, Ambulatory Surgical Centers (ASCs), Long-Term Care Facilities, Military & Veterans Healthcare Facilities, Others) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Ottobock Healthcare, Össur, Hanger Inc., Blatchford Group, Fillauer Companies, Nakamura Brace, Proteor, College Park Industries, WillowWood, Steeper Group, Endolite, DJO Global, Becker Orthopedic, Aspen Medical Products, Thuasne, Other Key Players |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








