


Market Overview
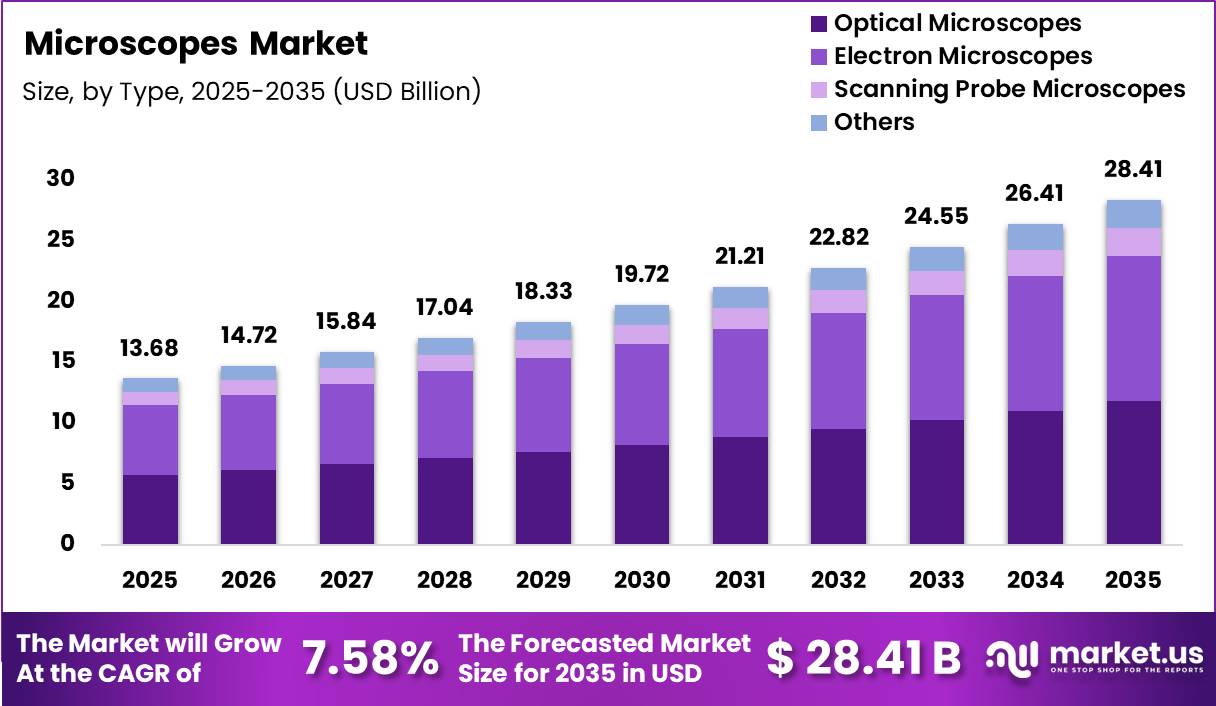
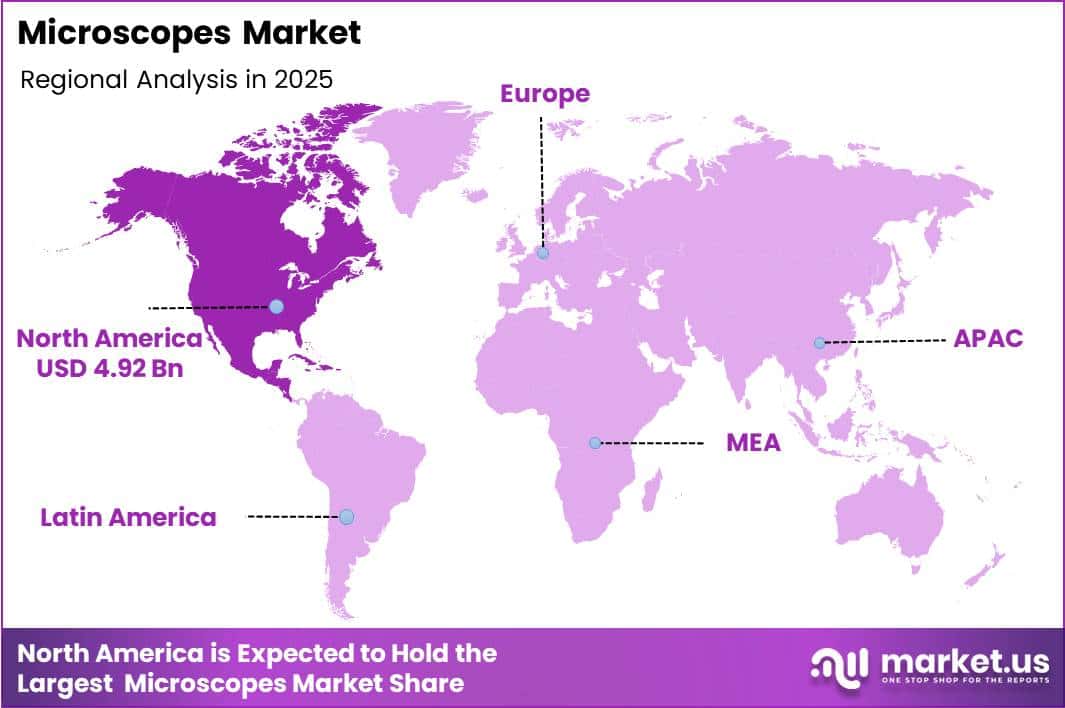
The Global Microscopes Market size is expected to be worth around US$ 28.41 Billion by 2035 from US$ 13.68 Billion in 2025, growing at a CAGR of 7.58% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 36.02% share with a revenue of US$ 4.92 Billion.
The global microscopes market is experiencing sustained growth, driven by expanding investments in biomedical research, semiconductor manufacturing, advanced materials science, and clinical diagnostics. Microscopes remain indispensable tools across life sciences, pathology laboratories, academic research institutions, pharmaceutical development, and industrial quality assurance.
Continuous technological advances, including digital imaging, artificial intelligence-assisted image analysis, automated workflows, and super-resolution microscopy, are improving analytical precision while enabling faster and more reproducible research outcomes.
Government agencies and trusted healthcare organizations continue to support microscopy-based research through funding initiatives and scientific infrastructure development. The U.S. National Institutes of Health (NIH) has increased investments in advanced imaging technologies to accelerate biomedical discoveries, while the National Institute of Standards and Technology (NIST) promotes precision measurement and imaging standards that strengthen microscopy applications across research and manufacturing.
Similarly, the U.S. Food and Drug Administration (FDA) relies on microscopic analysis in pharmaceutical quality assessment, pathology, and medical device evaluation, reinforcing the technology’s importance in regulatory science. The World Health Organization (WHO) also recognizes microscopy as an essential diagnostic tool for infectious diseases such as tuberculosis and malaria, particularly in resource-limited healthcare settings.
The market is also benefiting from rising global research expenditure, increased adoption of electron and confocal microscopes, and growing demand for high-resolution imaging in nanotechnology and cell biology. Expanding biotechnology and pharmaceutical R&D activities, coupled with the rapid development of personalized medicine and regenerative therapies, continue to increase demand for sophisticated microscopy systems.
Furthermore, improvements in digital connectivity, cloud-based image management, and automated laboratory platforms are enhancing workflow efficiency, enabling laboratories to generate high-quality imaging data for research, clinical diagnostics, and industrial inspection.
Key Takeaways
- Market Size: Microscopes Market size was US$ 13.68 billion in 2025. The market is estimated to grow to US$ 28.41 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 7.58%.
- By Type: Optical Microscopes have the largest market share, accounting for 41.78% of total sales.
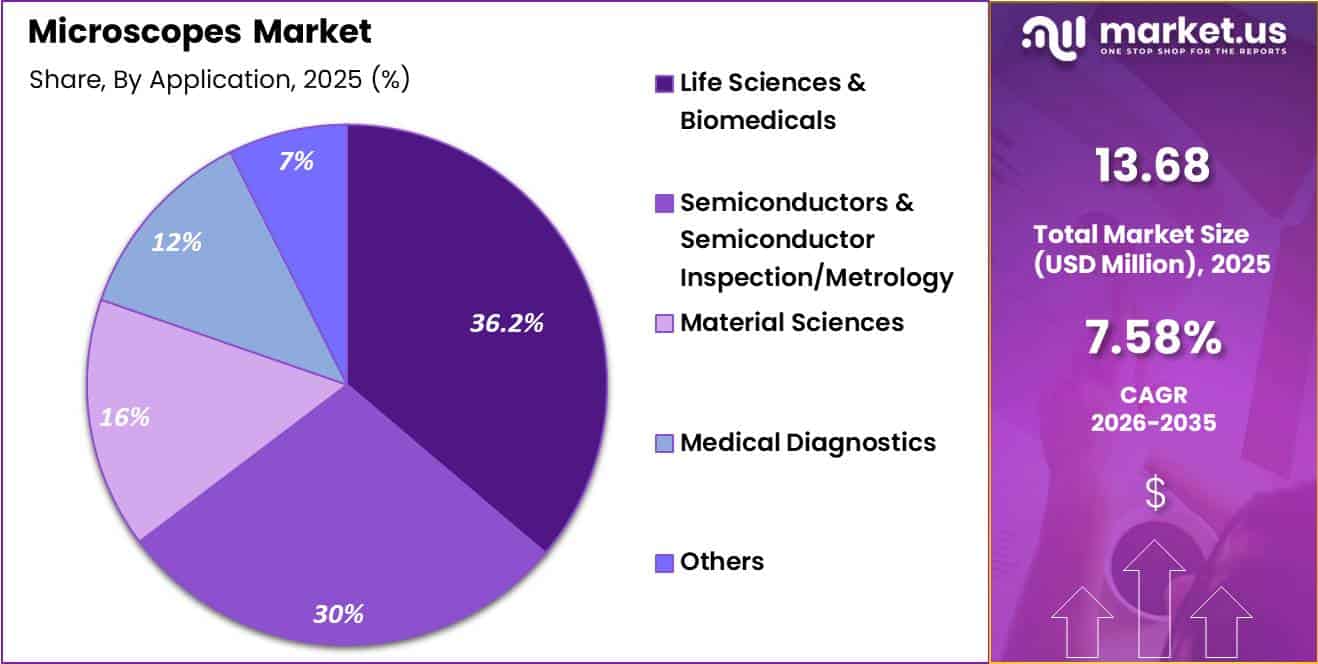
- By Application: Life Sciences & Biomedicals, accounting for 36.20% of total revenue.
- By End User: Hospitals & Diagnostic Centers leads the segment, accounting for 42.05% of total revenue.
- Regional: In 2025, North America led the market, achieving over 36.02% share with a revenue of US$ 4.92 Billion.
Type Segment Analysis
The type segment of the microscopes market is driven by continuous advancements in imaging technology, expanding research activities, and increasing demand for precision diagnostics across healthcare, industrial, and academic applications.
In 2025, Optical Microscopes dominated the market, accounting for 41.78% of the total market share. Their leadership is attributed to affordability, ease of operation, rapid sample preparation, and widespread adoption in clinical laboratories, educational institutions, and biological research.
Optical microscopes remain indispensable for routine pathology, microbiology, and life science studies, where real-time visualization of living specimens is essential. Improvements in digital imaging, fluorescence microscopy, and automated analysis have further strengthened their market position.
Electron Microscopes represented 41.97% of the market and continue to gain traction due to their exceptional magnification and nanometer-scale resolution, making them critical for semiconductor inspection, materials science, nanotechnology, and advanced biomedical research.
Despite their higher cost and infrastructure requirements, investments from research institutes and manufacturing industries support sustained demand. Scanning Probe Microscopes accounted for 8.12% of the market, benefiting from expanding applications in nanoscience, molecular biology, and surface characterization.
The Others category, also holding 8.12%, includes specialized microscopy technologies such as acoustic, confocal, and digital microscopes, which address niche research and industrial inspection requirements. Ongoing innovation across all microscopy technologies continues to enhance analytical capabilities and broaden application areas worldwide.
Application Segment Analysis
The application segment of the microscopes market reflects the technology’s growing importance across healthcare, scientific research, industrial manufacturing, and educational activities. In 2025, Life Sciences & Biomedicals dominated the market, accounting for 36.20% of the total market share.
The segment’s leadership is supported by rising investments in biomedical research, pharmaceutical development, cell biology, pathology, microbiology, and genomics. Microscopes are fundamental tools for disease diagnosis, drug discovery, tissue analysis, and clinical research, while advancements in fluorescence, confocal, and digital imaging technologies continue to improve research accuracy and laboratory productivity.
Increasing demand for personalized medicine and molecular diagnostics further strengthens adoption within life science laboratories. The Material Sciences segment also represents a significant share, supported by expanding nanotechnology research, metallurgy, semiconductor manufacturing, and advanced materials characterization.
High-resolution microscopy enables researchers to evaluate structural integrity, surface morphology, and material composition with exceptional precision. Industrial Inspection applications continue to expand as manufacturers increasingly rely on microscopy for quality assurance, defect detection, electronics inspection, and precision engineering.
Meanwhile, the Education and Academic Research segment maintains steady growth as universities and research institutions invest in advanced laboratory infrastructure to support scientific training and innovation. Collectively, these diverse applications ensure sustained demand for microscopes across both established and emerging research and industrial environments.
End User Segment Analysis
The end user segment of the microscopes market is influenced by increasing healthcare expenditure, expanding scientific research, and growing industrial quality control requirements. In 2025, Hospitals & Diagnostic Centers dominated the market, accounting for 42.05% of the total market share. Their leadership is driven by the extensive use of microscopes in pathology, microbiology, hematology, cytology, and infectious disease diagnostics.
Rising demand for accurate laboratory testing, cancer screening, and precision diagnostics has encouraged hospitals to adopt advanced digital and automated microscopy systems that improve workflow efficiency and diagnostic accuracy.
Continuous modernization of clinical laboratories further supports segment growth. Academic & Research Institutes represent another major end-user category, benefiting from increasing government funding, university research initiatives, and expanding life science and nanotechnology programs.
These institutions utilize a broad range of optical, electron, and scanning probe microscopes for fundamental and applied research. The Pharmaceutical & Biotechnology Companies segment is also experiencing robust growth as microscopy plays a vital role in drug discovery, cell analysis, biologics development, and quality assurance during pharmaceutical manufacturing.
Industrial Manufacturers, including semiconductor, electronics, automotive, and materials companies, increasingly rely on advanced microscopy for defect analysis, failure investigation, and product quality inspection. The broad adoption of microscopy across healthcare, research, and manufacturing sectors continues to strengthen overall market expansion.
Market Segmentations
By Type
- Optical Microscopes
- Fluorescence Microscopes
- Confocal Scanning Microscopes
- Stereo / Stereomicroscopes
- Other Optical Microscopes
- Electron Microscopes
- Scanning Electron Microscopes (SEM)
- Transmission Electron Microscopes (TEM)
- Others
- Scanning Probe Microscopes
- Atomic Force Microscopes (AFM)
- Scanning Tunneling Microscopes (STM)
- Others
- X-Ray Microscopes
- Infrared Microscopes
- Digital / Automated Microscopes
By Application
- Life Sciences & Biomedicals
- Semiconductors & Semiconductor Inspection/Metrology
- Material Sciences
- Medical Diagnostics
- Others
By End User
- Hospitals & Diagnostic Centers
- Academic & Research Institutes
- Industries & Manufacturing
- Forensic Laboratories
- Pharmaceutical & Biotechnology Companies
- Others
Driver
Surgical and Clinical Microscopy Adoption Driving Market Expansion
Surgical microscopes and clinical diagnostic microscopes are benefiting from the expansion of complex procedures in neurosurgery, ophthalmology, ENT, and spine, alongside broader global efforts to improve access to diagnostic services where approximately 70% of healthcare decisions depend on test results yet only a low-single-digit share of health budgets currently goes to diagnostics.
Surgical microscopes alone are projected to grow from mid-single-billion-dollar levels in the mid-2020s to more than USD 3 billion by the early 2030s, reflecting near-10% CAGR for this segment and implying faster growth than general microscopes driven by operating room modernization and increasing case complexity.
At the same time, clinical laboratories in both high-income and low-resource settings rely on optical microscopes for pathology, hematology, and infectious disease testing. WHO’s diagnostics resolution WHA76.5 and the subsequent Diagnostics Taskforce explicitly prioritize strengthening national laboratory systems, workforce training, and access to essential diagnostic technologies, including microscopy, which supports a structural increase in installed base requirements across primary and secondary care.
Vendors are responding with ergonomic, digitally integrated surgical microscopes that combine visualization, recording, and navigation capabilities, shifting business models from one-time hardware sales toward bundled service, training, and software upgrades.
Clinical microscopes are also seeing rising demand for robust, low-maintenance designs suitable for decentralized laboratories. Taken together, these factors support above-average growth in surgical and clinical segments versus the broader market and can add around 1.2 % points to global microscopes CAGR over 2026–2030, especially in regions investing heavily in surgical infrastructure and diagnostic capacity.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Semiconductor & electronics inspection expansion | +2.0% | North America core, EU, APAC corridors | Medium term (2–4 years) |
| Life sciences, pharma-biotech R&D intensity | +1.5% | North America core, EU, APAC corridors | Long term (≥ 4 years) |
| Surgical and clinical microscopy adoption | +1.2% | North America core, EU, APAC corridors, South America spill-over | Medium term (2–4 years) |
| Electron and advanced microscopy modalities | +1.8% | North America core, EU, APAC corridors | Long term (≥ 4 years) |
| Digital & AI-supported microscopy | +2.3% | EU, APAC corridors, South America spill-over | Medium term (2–4 years) |
| Global diagnostics capacity & primary care labs | +1.0% | APAC corridors, South America spill-over, Africa emerging | Long term (≥ 4 years) |
Challenge
High Precision Component Bottlenecks Limiting Microscope Supply Growth
High-precision components, including objective lenses with nanometer-grade tolerances, vibration-isolated stages, high-speed CMOS/CCD sensors, and vacuum equipment for electron microscopes, represent a chronic bottleneck in the microscopes supply chain by extending lead times and creating uneven regional availability without fully freezing shipments.
Global optics manufacturing is concentrated in a limited number of EU and Japanese clusters, while advanced sensor fabrication is anchored in a few APAC semiconductor facilities. Disruptions in these hubs, combined with cross-border logistics friction, can stretch component lead times from a design baseline of 6–8 weeks to 16–20 weeks, forcing OEMs to hold 10–15% additional buffer inventory or delay deliveries, effectively reducing annual ship-ready capacity by an estimated 5–10% versus unconstrained demand.
In industrial and biomedical segments, microscopes are often bundled into larger capital projects, so a 3–4 month delay on a single optical module can cascade into 6–9 month project extensions, depressing recognized revenue per year while keeping order books nominally healthy.
Modeling these delays relative to demand growth yields roughly a 1.4 % point friction drag on achievable CAGR. Strategic mitigation requires dual-sourcing optics and sensors, localized assembly near APAC fabrication corridors, and higher investment in component standardization to increase interchangeability.
However, re-tooling precision supply chains and qualifying alternative vendors typically requires 2–4 years of engineering validation and regulatory documentation, placing this challenge in the medium-term horizon.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Fragmented procurement standards | -1.2% | North America, EU, Asia hospitals | Medium term (2–4 years) |
| Skilled microscopy talent gap | -1.0% | Global research hubs | Long term (≥ 4 years) |
| High-precision component bottlenecks | -1.4% | EU optics clusters, APAC fabs | Medium term (2–4 years) |
| Digital pathology integration friction | -0.9% | North America, EU, high-income APAC | Medium term (2–4 years) |
| Biosafety and compliance overhead | -0.8% | Clinical and BSL labs worldwide | Long term (≥ 4 years) |
| Lifecycle service and uptime risk | -0.7% | Emerging markets, secondary cities | Medium term (2–4 years) |
Restraints
Critical Components and Optics Supply Chain Bottlenecks Limiting Growth
The microscopes value chain is highly sensitive to bottlenecks in precision optics, high-NA objective lenses, specialty glass, lasers, detectors, and motion control systems. The post-2023 environment of intermittent logistics disruptions, energy-price volatility, and critical material constraints has translated into structurally longer lead times and higher input costs across APAC and European corridors.
Root-cause bottlenecks include concentration of high-precision glass and objective manufacturing in a small number of Japanese and European suppliers, dependence on specific rare-earth doped materials and advanced coatings that compete with semiconductor and battery industries, and limited redundancy for key CMOS and PMT sensor lines.
These factors leave OEMs exposed when even one facility faces operational disruptions. Lead times for complex objectives and laser modules that were typically 8–10 weeks have stretched to 16–20 weeks for many configurations since 2024, while freight costs for temperature-controlled optical shipments have at times risen 25–35% compared with pre-2020 baselines.
Combined, these delays can extend full system delivery timelines for high-end microscopes from 3–4 months to 6–8 months, directly impacting annual installation volumes. Strategically, manufacturers are increasing safety stock by 15–25% for critical components and pursuing dual-sourcing strategies where possible, tying up more capital in inventory and extending cash conversion cycles.
Distributors in APAC and select emerging markets report that 20–30% of tenders require schedule renegotiation due to late deliveries. These frictions cumulatively translate into an estimated 0.9 %-point drag on global microscopes CAGR from 2026, as some demand is deferred into later periods and a portion of budget-constrained laboratory procurement is lost when delivery timelines exceed purchasing windows.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Tightening medical device regulation & compliance costs | -1.2% | EU, North America core, India | Medium term (2–4 years) |
| Public and academic CapEx cyclicality for advanced microscopes | -1.0% | North America core, EU, APAC research hubs | Medium term (2–4 years) |
| Critical components & optics supply chain bottlenecks | -0.9% | APAC corridors, EU, select Emerging Markets | Short to medium term (≤ 4 years) |
| Procurement and tendering complexity in healthcare systems | -0.8% | EU, UK, India, public health systems globally | Medium to long term (≥ 3 years) |
| Shortage of skilled microscopy operators and technicians | -0.7% | Asia Pacific, Latin America, MEA, secondary cities | Long term (≥ 4 years) |
| Pricing pressure from budget constraints and commoditization | -0.8% | Global, strongest in public and mid-tier private segments | Short to medium term (≤ 4 years) |
Opportunity
Sustainable Low Energy Microscopes for Green Laboratory Adoption
The increasing emphasis on sustainable laboratory operations, including energy-efficient equipment and lower lifecycle environmental impact, is not yet a core purchasing driver for microscopes. However, by 2030, regulatory and institutional “green lab” programs in Europe, North America, and leading APAC research hubs are expected to make energy and sustainability metrics a formal criterion in equipment tenders.
Current microscope designs often rely on high-intensity light sources and power-intensive ancillary systems, contributing to laboratory energy loads. In contrast, new microscopes leveraging LED illumination, optimized standby modes, and energy monitoring can reduce per-device power consumption by 30–50%.
When combined with eco-certified materials and take-back programs, these solutions can lower lifecycle emissions by 20–30% per unit. As more institutions implement accreditation and grant-linked sustainability frameworks, vendors able to demonstrate 10–20% annual laboratory energy savings across fleets of 50–100 microscopes may secure preferential procurement, supporting premium pricing of 5–10% while maintaining similar or improved margins through standardized efficient designs.
This could translate into USD 0.5–1.0 billion in incremental global revenue and stronger win rates in high-value tenders by 2035. Because current microscope procurement rarely specifies precise sustainability KPIs and green performance labels are still emerging, this remains an untapped white space.
Positioning sustainability-optimized microscopes as a distinct product category linked to institutional net-zero goals can add an estimated 1.0 % point to market CAGR by accelerating replacement cycles and converting compliance-driven budgets that would otherwise continue supporting legacy systems.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| AI-native digital pathology microscopes-as-a-service | +2.5% | North America, EU, APAC tier-1 | Medium term (2-4 years) |
| Point-of-care microscopy for chronic disease & community labs | +1.8% | APAC emerging, Latin America, Africa | Medium term (2-4 years) |
| Data monetization & image analytics platforms | +2.2% | North America, EU, Global research hubs | Long term (≥ 4 years) |
| Sustainable, low-energy microscopes for green labs | +1.0% | EU, UK, North America, advanced APAC | Short term (≤ 2 years) |
| Industrial in-line smart microscopy for advanced manufacturing | +1.7% | APAC manufacturing, North America, EU | Medium term (2-4 years) |
| Tele-microscopy & remote diagnostics networks | +1.5% | Global, especially LMIC health systems | Long term (≥ 4 years) |
Regional Analysis
In 2025, North America led the market, achieving over 36.02% share with a revenue of US$4.92 billion.
North America region’s leadership is supported by its well-established life sciences ecosystem, extensive investments in biomedical research, and widespread adoption of advanced imaging technologies across academic institutions, pharmaceutical companies, and clinical laboratories.
The United States remains the primary contributor, driven by strong funding for research through government agencies, expanding biotechnology activities, and continuous innovation in microscopy for disease diagnosis, drug discovery, and materials science.
The presence of leading microscope manufacturers and imaging technology developers further strengthens regional competitiveness through ongoing product development and strategic collaborations.
Canada also contributes significantly through increasing investments in healthcare infrastructure, university-based research, and nanotechnology initiatives, while Mexico is witnessing the gradual adoption of advanced microscopy systems supported by industrial manufacturing growth and improvements in diagnostic capabilities.
Across North America, demand is further reinforced by rising applications in semiconductor inspection, forensic science, environmental monitoring, and industrial quality assurance. The integration of artificial intelligence, digital imaging, and automated analysis into microscopy platforms is improving workflow efficiency and expanding adoption among research laboratories.
Additionally, favorable government support for scientific innovation, robust public-private research partnerships, and increasing precision medicine initiatives are expected to sustain North America’s leadership position throughout the forecast period, making the region a major hub for technological advancements and high-value microscope applications.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global microscopes market is moderately consolidated, with a mix of established multinational manufacturers and specialized microscopy technology providers competing across optical, electron, digital, and scanning probe microscopy segments.
Competition is driven by continuous technological innovation, precision imaging capabilities, software integration, automation, and expanding applications in life sciences, materials science, semiconductors, and industrial quality control.
Companies are increasingly investing in advanced imaging platforms, AI-enabled analysis, digital workflows, and high-resolution visualization technologies to strengthen their competitive positioning. Strategic partnerships with research institutions, universities, healthcare organizations, and semiconductor manufacturers are also supporting product development and expanding market reach.
Leading participants include Carl Zeiss AG, Leica Microsystems (Danaher Corp.), Olympus Corporation (Evident), Nikon Corporation, Thermo Fisher Scientific Inc., JEOL Ltd., Bruker Corporation, Hitachi High-Tech Corporation, Keyence Corporation, Oxford Instruments plc, Park Systems Corp., Motic (Xiamen Motic Group), Meiji Techno Co., Ltd., Topcon Corporation, and Labomed Inc.
These companies prioritize substantial R&D investments to improve imaging resolution, automation, digital connectivity, and user-friendly analytical software. Product innovation increasingly focuses on AI-assisted image processing, cloud-enabled data management, multimodal imaging, and workflow integration that enhances laboratory efficiency and reproducibility.
Ecosystem-based competition is becoming more prominent as manufacturers combine hardware, software, imaging analytics, and service offerings into comprehensive microscopy platforms.
Additionally, collaborations with academic institutions, biotechnology companies, and industrial manufacturers accelerate technology validation and application development, enabling vendors to address evolving customer requirements while maintaining long-term competitive advantages in the global microscopy market.
Top Key Players
- Carl Zeiss AG
- Leica Microsystems (Danaher Corp.)
- Olympus Corporation (Evident)
- Nikon Corporation
- Thermo Fisher Scientific Inc.
- JEOL Ltd.
- Bruker Corporation
- Hitachi High-Tech Corporation
- Keyence Corporation
- Oxford Instruments plc
- Park Systems Corp.
- Motic (Xiamen Motic Group)
- Meiji Techno Co., Ltd.
- Topcon Corporation
- Labomed Inc.
Recent Developments
- In July 2025, Carl Zeiss AG acquired Pi Imaging Technology SA, a Swiss developer of single-photon avalanche diode (SPAD) image sensor technology, to strengthen next-generation fluorescence microscopy and advanced imaging capabilities.
- In November 2025, Carl Zeiss AG (through ZEISS Ventures) participated in a CHF 6.3 million funding round for arcoris bio to accelerate digital pathology and spatial multiomics technologies that complement advanced microscopy applications.
- In March 2026, Leica Microsystems (Danaher Corp.) launched the Viventis SCAPE Light Sheet Microscope, enabling high-speed 3D volumetric imaging with standard sample carriers for live-cell and developmental biology research.
- In April 2026, Leica Microsystems (Danaher Corp.) introduced the Launch Early Access Program (LEAP) for its ATTOAuriga spatial biology reagent platform, expanding integrated microscopy workflows for multiplex spatial biology research.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 13.68 Bn |
| Forecast Revenue (2035) | US$ 28.41 Bn |
| CAGR (2026-2035) | 7.58% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Type (optical Microscopes(Fluorescence Microscopes, Confocal Scanning Microscopes, Stereo / Stereomicroscopes, Other Optical Microscopes), Electron Microscopes (Scanning Electron Microscopes (SEM) , Transmission Electron Microscopes (TEM) , Others), Scanning Probe Microscopes(Atomic Force Microscopes (AFM), Scanning Tunneling Microscopes (STM)) Others(X-Ray Microscopes, Infrared Microscopes, Digital / Automated Microscopes)) By Application (Life Sciences & Biomedicals, Semiconductors & Semiconductor Inspection/Metrology, Material Sciences, Medical Diagnostics, Others) By End User (Hospitals & Diagnostic Centers, Academic & Research Institutes, Industries & Manufacturing, Forensic Laboratories, Pharmaceutical & Biotechnology Companies, Others) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Carl Zeiss AG ,Leica Microsystems (Danaher Corp.) ,Olympus Corporation (Evident) ,Nikon Corporation ,Thermo Fisher Scientific Inc. ,JEOL Ltd. ,Bruker Corporation ,Hitachi High-Tech Corporation ,Keyence Corporation Oxford Instruments plc ,Park Systems Corp. ,Motic (Xiamen Motic Group) ,Meiji Techno Co., Ltd. ,Topcon Corporation ,Labomed Inc. |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








