


Report Overview
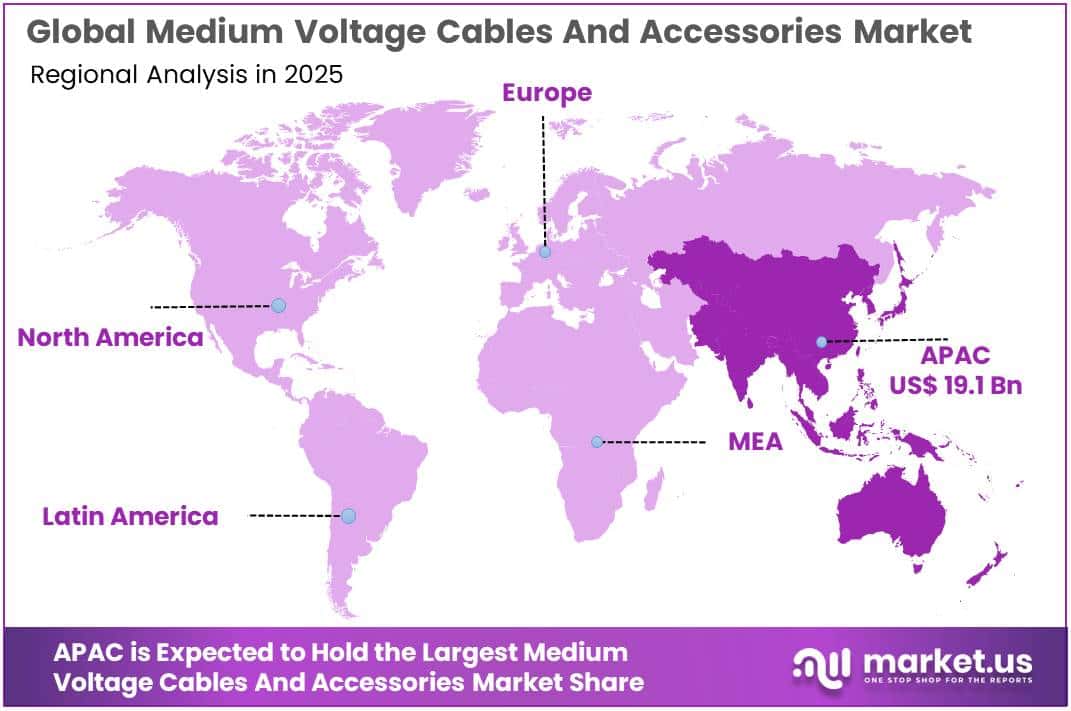
The Global Medium Voltage Cables And Accessories Market size is expected to be worth around USD 102.2 Billion by 2035, from USD 55.3 Billion in 2025, growing at a CAGR of 6.3% during the forecast period from 2026 to 2035. In 2025, Asia-Pacific held a dominant market position, capturing more than a 34.67% share, holding USD 19.1 Billion revenue.
The medium voltage cables and accessories industry plays an important role in electricity transmission and distribution networks by ensuring the safe and reliable transfer of power from substations to industrial facilities, commercial buildings, renewable energy installations, and infrastructure projects.
Medium voltage cables generally operate across voltage levels of approximately 1 kV to 36 kV, depending on application and technical standards. These cables are manufactured using copper or aluminium conductors, insulation materials such as cross-linked polyethylene (XLPE), and protective outer sheaths.
The industrial scenario is increasingly influenced by electricity network modernisation, renewable energy integration, industrial electrification, and urban infrastructure development. According to the International Energy Agency (IEA), global electricity demand has grown at approximately twice the rate of overall energy demand over the past decade.
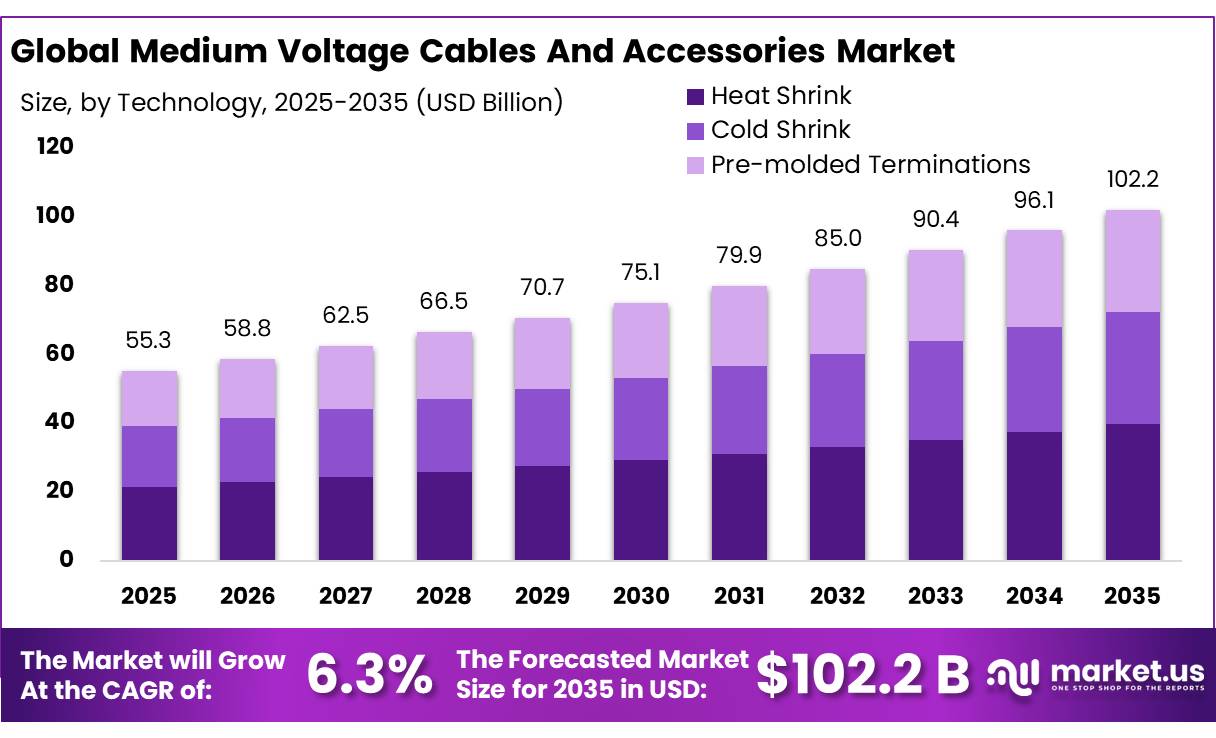
The agency also indicates that meeting electricity demand growth through 2035 will require grid capacity to increase by at least 30%, equivalent to adding or replacing approximately 25 million kilometres of electricity lines. These developments are creating opportunities for medium voltage cable manufacturers, particularly in distribution networks, substations, industrial power systems, and renewable energy connections.
One of the major driving factors is increasing investment in electricity distribution infrastructure. According to the European Commission, approximately 40% of European electricity distribution grids are more than 40 years old, creating a strong requirement for replacement and modernisation. The Commission estimates that approximately €584 billion in investment will be necessary for European electricity grids during the current decade.
Another important growth driver is the expansion of renewable energy and industrial electrification. Solar power plants, wind farms, battery storage facilities, electric vehicle charging infrastructure, and data centres require reliable medium voltage connections to distribute electricity efficiently. In the United States, the Energy Information Administration reported that utility distribution infrastructure capital investment reached USD 50.9 billion in 2023, representing an increase of 160% compared with 2003.
Material availability and manufacturing costs remain important industry considerations. Copper and aluminium prices directly influence cable production expenses, while insulation quality, fire resistance, moisture protection, and electrical performance influence product selection. The IEA reported in its 2025 energy investment assessment that cable prices had nearly doubled since 2018, highlighting the impact of material costs and increasing infrastructure demand.
Key Takeaways
- Medium Voltage Cables And Accessories Market size is expected to be worth around USD 102.2 Billion by 2035, from USD 55.3 Billion in 2025, growing at a CAGR of 6.3%.
- Cables held a dominant market position, capturing more than a 58.78% share.
- Heat Shrink held a dominant market position, capturing more than a 34.23% share.
- Overhead held a dominant market position, capturing more than a 43.67% share.
- Residential held a dominant market position, capturing more than a 45.67% share.
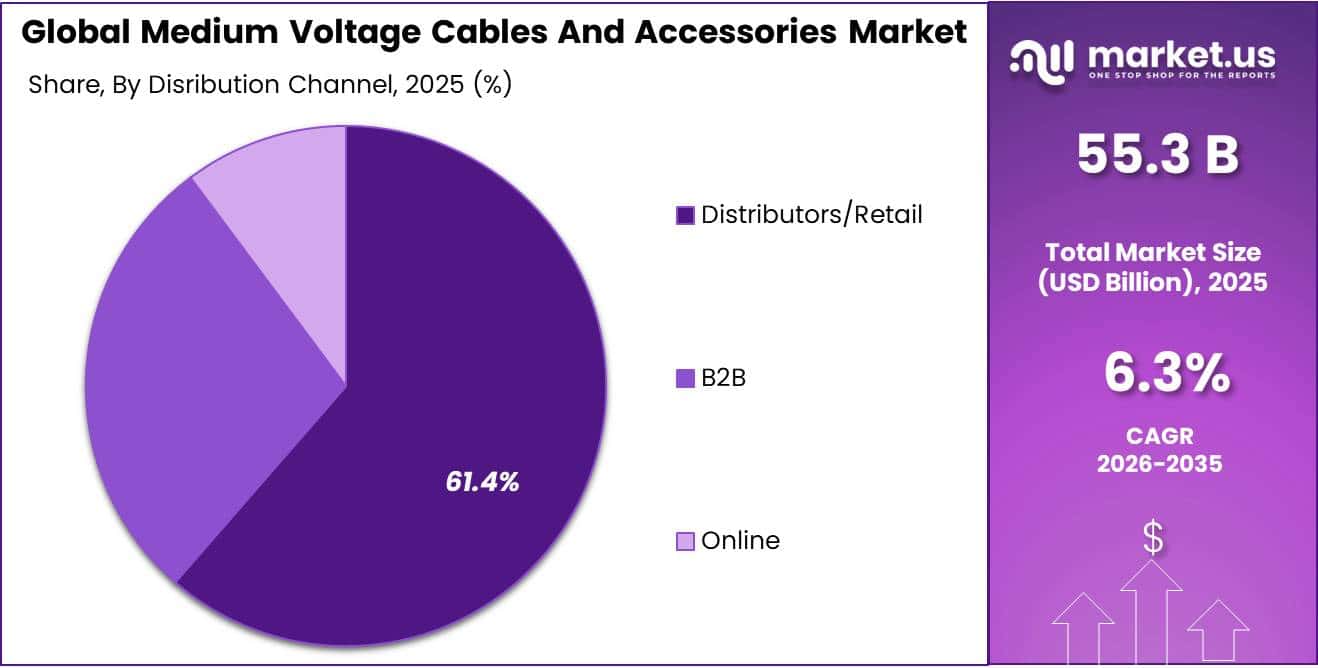
- Distributors/Retail held a dominant market position, capturing more than a 61.45% share.
- Asia-Pacific held a dominant position in the Medium Voltage Cables and Accessories Market in 2025, accounting for 34.67% of the global market, valued at USD 19.1 billion.
By Product Analysis
Cables dominate the market due to their essential role in electricity distribution, industrial power supply, and grid connectivity.
In 2025, “Cables” held a dominant market position, capturing more than a 58.78% share. Their leading position is supported by their widespread use in power distribution networks, manufacturing facilities, commercial infrastructure, and renewable energy projects. Medium voltage cables provide reliable electricity transmission between substations and end-user installations. Increasing investment in grid modernisation, underground power distribution, and industrial electrification continues to support demand.
The 5–11 kV segment serves applications requiring dependable medium voltage power distribution, particularly in industrial plants, manufacturing units, commercial complexes, and distribution substations. These cables are commonly used to connect transformers, switchgear, motors, and electrical distribution equipment. In 2025, demand was supported by the need for reliable electricity supply, replacement of ageing distribution infrastructure, and expansion of industrial facilities.
According to the International Energy Agency (IEA), global grid capacity needs to increase by at least 30% by 2035, requiring approximately 25 million kilometres of electricity lines to be added or replaced. This infrastructure requirement provides a favourable growth environment for 5–11 kV cables used in distribution networks.
By Technology Analysis
Heat Shrink dominates the market due to its reliable insulation, strong sealing performance, and cost-effective installation.
In 2025, “Heat Shrink” held a dominant market position, capturing more than a 34.23% share. Its leading position is supported by its widespread use in medium voltage cable joints, terminations, and insulation protection applications. Heat shrink accessories provide electrical insulation, moisture resistance, and mechanical protection, making them suitable for industrial facilities, utility networks, and underground power distribution systems. Their established installation methods and compatibility with different cable designs continue to support adoption.
Cold Shrink technology is increasingly used in medium voltage cable joints and terminations because it allows installation without external heating equipment. Its pre-expanded design contracts around the cable when the supporting core is removed, providing consistent insulation and sealing. In 2025, its adoption was supported by utility maintenance activities, underground cable installations, and industrial power distribution requirements.
The US Department of Energy’s Grid Deployment Office reported that the Grid Resilience and Innovation Partnerships (GRIP) programme provides USD 10.5 billion in funding to strengthen and modernise electricity grids, supporting the wider infrastructure environment for advanced cable accessories.
By Installation Analysis
Overhead installation dominates the market due to its lower installation costs, easier maintenance, and suitability for widespread electricity distribution networks.
In 2025, “Overhead” held a dominant market position, capturing more than a 43.67% share. Its leading position is supported by its extensive use in utility distribution networks, industrial power connections, and rural electrification projects. Overhead medium voltage cables are preferred in areas where underground installation involves higher construction costs or complex site conditions. Their accessibility also makes inspection, maintenance, and fault identification easier for utility operators.
Underground medium voltage cables are increasingly used in urban infrastructure, commercial developments, industrial facilities, and locations where overhead networks face space or environmental limitations. These installations protect electrical connections from wind, storms, falling trees, and other external disturbances. In 2025, demand was supported by urban development, grid modernisation, and the growing requirement for reliable electricity distribution. Underground systems also help improve the appearance of developed areas by reducing the need for visible overhead power lines.
Government supporting statistic: According to the European Commission, approximately 40% of Europe’s electricity distribution grids are more than 40 years old, highlighting the need for infrastructure replacement and modernisation. The European Commission estimates that approximately €584 billion of investment will be required for European electricity grids during the current decade. These investments provide opportunities for underground cable installations and associated accessories.
By End User Analysis
Residential dominates the market due to rising electricity demand, housing development, and the expansion of reliable power distribution networks.
In 2025, “Residential” held a dominant market position, capturing more than a 45.67% share. Its leading position is supported by the growing requirement for dependable electricity connections across residential buildings, housing complexes, and urban infrastructure projects. Medium voltage cables play an important role in connecting distribution substations and transformers that supply electricity to residential areas. Increasing housing development, power network expansion, and replacement of ageing electrical infrastructure continue to support demand.
Industrial end users require medium voltage cables and accessories to supply electricity to manufacturing plants, processing facilities, warehouses, mining operations, and other energy-intensive installations. In 2025, demand was supported by industrial expansion and the increasing use of automated production equipment, which requires stable and continuous electricity supply.
Government supporting statistic: According to the International Energy Agency (IEA), global electricity demand is expected to grow at an average annual rate of approximately 3.5% through 2027. Rising electricity consumption across industrial and commercial activities is increasing the requirement for stronger distribution infrastructure and dependable medium voltage cable systems.
By Disribution Channel Analysis
Distributors/Retail dominates the market due to its wide product availability, established supply networks, and direct access to end users.
In 2025, “Distributors/Retail” held a dominant market position, capturing more than a 61.45% share. Its leading position is supported by the important role of distributors and electrical retailers in supplying medium voltage cables, joints, terminations, connectors, and related accessories to utility contractors, industrial buyers, and electrical installation companies. These channels provide access to different cable specifications, established product brands, and technical support.
The B2B distribution channel serves electricity utilities, infrastructure developers, construction companies, industrial manufacturers, and renewable energy project operators. In 2025, this channel benefited from large-scale electricity distribution projects and the increasing need for customised cable solutions. Direct business transactions allow buyers to obtain products according to specific voltage requirements, technical standards, installation conditions, and project schedules.
Government supporting statistic: According to the International Energy Agency (IEA), global electricity demand is projected to increase by approximately 3.5% annually through 2027. This rising demand is encouraging utilities and industrial customers to strengthen electricity distribution infrastructure, supporting procurement opportunities through direct B2B supply agreements.
Key Market Segments
By Product
- Cables
- 5-11 KV
- >11-22 KV
- >22-35 KV
- Accessories Fastest Growing
- Cable joints and Splice
- Connectors
- Separable
- Terminations
- Others
By Technology
- Heat Shrink
- Cold Shrink
- Pre-molded Terminations
By Installation
- Overhead
- Underground
- Submarine
By End User
- Residential
- Industrial
- Commercial
By Disribution Channel
- B2B
- Distributors/Retail
- Online
Driver Analysis
Aging-Grid Replacement
Replacement of mature distribution assets is the largest modeled driver because it creates recurring procurement demand that is less dependent on new generation commissioning than greenfield projects. The European Commission reports that 40% of EU distribution grids are more than 40 years old and identifies €584 billion of required electricity-grid investment; neither figure represents an MV-cable-only opportunity.
The European Grids Package, presented on 10 December 2025, includes proposals to revise infrastructure rules and accelerate permitting, but proposed measures should not be treated as already-delivered procurement. Globally, the IEA estimates that annual grid investment needs to rise roughly 50% from about $400 billion to meet electricity-demand requirements through 2030, supporting a broader replacement-and-reinforcement cycle.
The strategic value pool therefore includes joints and terminations as well as cable length: replacing a constrained feeder can require new interfaces with retained substations and existing circuits. Qualification continuity, delivery reliability and installation support become differentiators, although utility rate approvals, civil works and commissioning capacity can postpone revenue recognition.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Aging-grid replacement | +1.2 pp | EU, UK, US, Canada | Medium term (2–4 years) |
| Renewable collection networks | +1.0 pp | China, India, EU, US, Brazil | Short term (≤ 2 years) |
| Distribution-network expansion | +0.8 pp | India core; Southeast Asia | Medium term (2–4 years) |
| AI and data-centre power | +0.6 pp | US, China, Ireland, Germany, UK | Short term (≤ 2 years) |
| EV charging reinforcement | +0.5 pp | China, EU, UK, US | Medium term (2–4 years) |
| Resilience and undergrounding | +0.4 pp | US, Canada, EU, UK | Long term (≥ 4 years) |
Restraint Analysis
Metal-Cost Volatility
Conductor-price volatility restrains real market growth when procurement budgets, working-capital facilities and contractual escalation mechanisms fail to adjust as quickly as input costs. The World Bank’s October 2026 outlook projects annual average copper prices of approximately $13,200 per metric ton, about 33% above 2025, and aluminium prices of $3,250 per metric ton, approximately 24% higher; these are commodity forecasts, not cable-price increases or realized full-year outcomes.
If the original selling price is 100 and manufacturing cost is 85, that shock raises cost to 93.5; without repricing, gross margin falls from 15% to 6.5%, an 8.5-percentage-point contraction. These are scenario calculations rather than observed industry averages, but they illustrate why fixed-price tenders can destroy conversion margins even when order books expand. Suppliers consequently face pressure to shorten quotation validity, require deposits and introduce metal-indexed pricing, while customers may reduce purchased lengths, postpone reinforcement or reconsider conductor specifications.
Importantly, successful price pass-through can increase nominal cable revenue without increasing physical demand; this report therefore models only the real-growth effect. The −0.5 pp deduction assumes 25% of addressable revenue experiences growth 2 percentage points below the driver-inclusive case, with the penalty allocated to affordability and working-capital constraints rather than commodity inflation itself.
Restraint Impact Analysis
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Metal-cost volatility | −0.5 pp | Global; import-dependent APAC, EU | Short term (≤ 2 years) |
| Connection and permit delays | −0.5 pp | US, EU, UK, India | Medium term (2–4 years) |
| Equipment delivery mismatch | −0.4 pp | North America, EU, India | Short term (≤ 2 years) |
| Utility financing constraints | −0.4 pp | Sub-Saharan Africa, South Asia | Medium term (2–4 years) |
| Skilled-labour shortages | −0.3 pp | US, Canada, EU, UK | Medium term (2–4 years) |
| Undergrounding cost premium | −0.2 pp | US, Canada, EU, UK | Long term (≥ 4 years) |
Opportunity Analysis
Smart Retrofit Accessories
Technical feasibility is already demonstrated: TE Connectivity and CNIguard announced a March 2025 partnership combining retrofit grid sensing, underground monitoring and analytics, with IP68-rated hardware and an ISO 27001-certified digital architecture; TE separately identifies thermal sensing, partial-discharge detection and insulation-health monitoring at MV cable interfaces within 5–35 kV distribution systems.
The uncaptured opportunity is therefore broader deployment and interoperable packaging for customers that have not yet adopted monitored accessories—not the invention of smart accessories themselves. An illustrative supplier offer could add $500 of factory-integrated sensing and interface functionality to a $2,000 passive-accessory package, representing a 25% product uplift; if the incremental manufacturing and support provision is $300, the additional $200 contribution equals 40% of the uplift, before sales costs, warranty losses and platform integration.
These figures are modeled commercial targets rather than observed selling prices. Go-to-market should prioritize utilities and industrial campuses where customers can demonstrate an economic case for earlier fault detection, with pilot acceptance based on signal quality, false alarms, installation compatibility and cybersecurity rather than unverified outage-reduction claims.
The +0.35 pp opportunity corresponds to 2.1 additional 2031 product-revenue index points, approximately 1.7% above baseline revenue; only incremental sales of integrated accessories are counted, while standalone sensors, analytics subscriptions and merely shifting purchases between suppliers are excluded.
Opportunity Impact Analysis
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Smart retrofit accessories | +0.35 pp | US, Canada, EU, UK | Short term (≤ 2 years) |
| Circular low-carbon products | +0.30 pp | EU, UK; North America | Short term (≤ 2 years) |
| Modular MV connection kits | +0.25 pp | US, EU, India, Southeast Asia | Medium term (2–4 years) |
| Shore-power packages | +0.20 pp | EU ports; UK, US expansion | Short term (≤ 2 years) |
| Geothermal MV systems | +0.15 pp | US core; selected global projects | Long term (≥ 4 years) |
Challenges Analysis
Accessory Interface Reliability
TE Connectivity’s energy catalogue attributes more than 50% of MV accessory failures to installation errors and cites an average replacement cost of approximately $10,000 for a single MV joint; these are supplier-published reference figures, not an independently established global failure distribution or a 2026 cost benchmark.
Product selection itself requires detailed configuration control: one TE separable-connector family spans conductor cross-sections of 25–1,000 mm², while an individual listed variant specifies a much narrower insulation-diameter range of 21.2–34.6 mm, demonstrating why conductor area alone cannot establish accessory compatibility. In a modeled program installing 10,000 joints, reducing a 0.5% early-rework incidence to 0.2% avoids 30 interventions; at an assumed $10,000 per intervention, the direct benefit is $300,000 before outage losses, penalties or reputational effects.
Neither defect rate is presented as an observed industry average. The strategic response is to standardize dimensional verification, serialized installation records, approved tooling and targeted post-installation testing, while allocating responsibility clearly across cable manufacturers, accessory suppliers and contractors.
This differs from a labour-availability restraint: sufficient crews may exist, yet installation quality can remain inconsistent across them. The −0.30 pp friction estimate assumes 15% of addressable revenue grows 2 percentage points more slowly because recurring rework, warranty resolution and customer requalification absorb resources that could otherwise support expansion.
Challenges Impact Analysis
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Accessory interface reliability | −0.30 pp | US, Canada, EU, India | Medium term (2–4 years) |
| Qualification and configuration complexity | −0.25 pp | EU, UK, US, export APAC | Medium term (2–4 years) |
| Thermal rating uncertainty | −0.20 pp | Southern EU, India, Gulf, US | Long term (≥ 4 years) |
| Circular feedstock quality control | −0.20 pp | EU, UK, North America | Medium term (2–4 years) |
| Lifecycle moisture risk management | −0.20 pp | Coastal APAC, EU, US | Long term (≥ 4 years) |
| Connected accessory cybersecurity | −0.10 pp | EU, UK, US, Canada | Medium term (2–4 years) |
Geopolitical Impact Analysis
Geopolitical Impact of Recent Wars on the Medium Voltage Cables and Accessories Market
Ongoing geopolitical conflicts, particularly the Russia-Ukraine war and tensions in the Middle East, are creating uncertainty across the medium voltage cables and accessories industry. Damage to electricity infrastructure in conflict-affected regions is increasing the need for replacement cables, distribution equipment, cable joints, and termination accessories.
At the same time, disruptions to international trade routes, energy supplies, and industrial supply chains are affecting the availability and cost of copper, aluminium, and insulation materials. These conditions are creating pressure on cable manufacturers through higher procurement expenses, longer delivery schedules, and increased transportation costs.
The scale of infrastructure damage is creating significant replacement and reconstruction opportunities. According to the World Bank’s February 2026 assessment, Ukraine’s total recovery and reconstruction requirements reached nearly USD 588 billion, while energy-sector recovery needs accounted for nearly USD 91 billion. The assessment also reported a 21% increase in damaged or destroyed energy assets since the previous assessment. This creates potential demand for medium voltage cables, underground distribution systems, protective insulation, and cable accessories.
Regional Insights
Dominating Region: Asia-Pacific
Asia-Pacific held a dominant position in the Medium Voltage Cables and Accessories Market in 2025, accounting for 34.67% of the global market, valued at USD 19.1 billion. The region’s leadership is supported by expanding electricity distribution networks, rapid urban development, industrial growth, and increasing investment in renewable energy infrastructure. China, Japan, South Korea, and Australia are important contributors to regional demand.
Growing requirements for reliable power supply across manufacturing facilities, commercial buildings, residential developments, and utility networks are supporting the adoption of medium voltage cables and accessories. The expansion of underground distribution systems, replacement of ageing electrical infrastructure, and development of modern substations are also strengthening regional market performance.
Key Regions and Countries Insights
- North America
- US
- Canada
- Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Key Players Analysis
Prysmian Group maintains a strong position in the cable industry through its extensive portfolio of power distribution, transmission, and electrification solutions. In 2025, the company reported total revenue of approximately €19.65 billion, with adjusted EBITDA of €2.398 billion. Its Power Grid division generated €3.811 billion in sales, supported by demand for grid infrastructure and medium and high voltage cable solutions. The company continues to strengthen its manufacturing capabilities and develop advanced cable technologies.
Nexans strengthens its market presence through medium voltage power cables, electrical distribution systems, and cable accessories designed for utility, industrial, and infrastructure applications. In 2025, the company recorded standard sales of €6.098 billion, while adjusted EBITDA reached €728 million, representing a 27.3% year-on-year increase. Its organic sales growth reached 8.3%, reflecting strong demand across its electrification businesses. The company also acquired RCT Cables in Spain in 2025, supporting its cable business expansion and regional market presence.
ABB participates in the medium voltage cables and accessories industry through its electrification portfolio, which includes medium voltage electrical components, switchgear, circuit breakers, and power distribution technologies. In 2025, its Electrification business area generated approximately USD 17.4 billion in revenue and employed around 53,400 people. The company serves residential, commercial, industrial, utility, renewable energy, and infrastructure customers through its global distribution network. Its continued investment in manufacturing capacity and electrical distribution technologies supports its position in the wider medium voltage infrastructure ecosystem.
Top Key Players Outlook
- Prysmian Group
- Nexans
- ABB
- Siemens
- Sumitomo Electric Industries
- NKT
- LS Cable and System
- Southwire
- Dubai Cable Company
- Furukawa Electric
- Other Key Players
Recent Developments
- In May 2026, Sumitomo Electric announced its Mid-term Management Plan 2028, targeting JPY 6 trillion in annual sales and JPY 600 billion in operating profit by FY2028, supported by cumulative investments of JPY 1 trillion during FY2026–FY2028.
- In May 2026, NKT launched the JCSI-35, an IEEE-qualified medium voltage cold-shrink splice for 15 kV, 28 kV, and 35 kV applications, targeting electricity utilities and distributors in North America.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 55.3 Bn |
| Forecast Revenue (2035) | USD 102.2 Bn |
| CAGR (2026-2035) | 6.3% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product (Cables, 5-11 KV, >11-22 KV, >22-35 KV, Accessories Fastest Growing, Cable joints and Splice, Connectors, Separable, Terminations, Others), By Technology (Heat Shrink, Cold Shrink, Pre-molded Terminations), By Installation ( Overhead, Underground, Submarine), By End User (Residential, Industrial, Commercial), By Disribution Channel (B2B, Distributors/Retail, Online) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | Prysmian Group, Nexans, ABB, Siemens, Sumitomo Electric Industries, NKT, LS Cable and System, Southwire, Dubai Cable Company, Furukawa Electric, Other Key Players |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








