


Market Overview
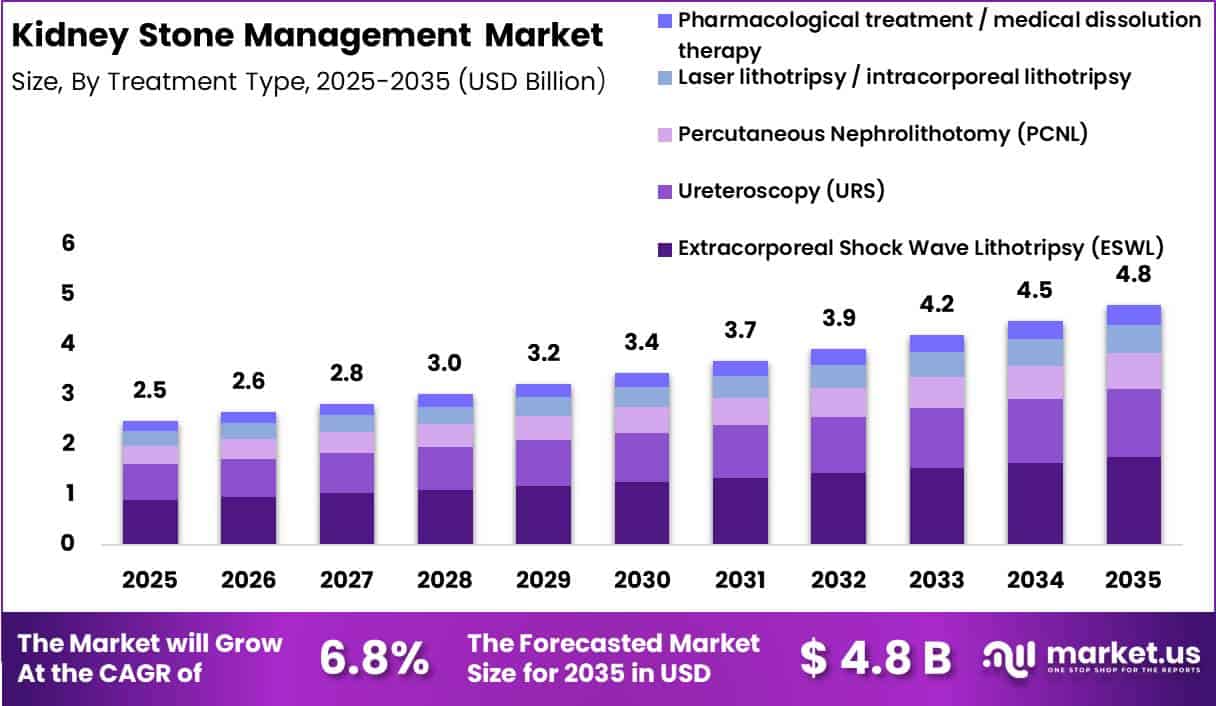
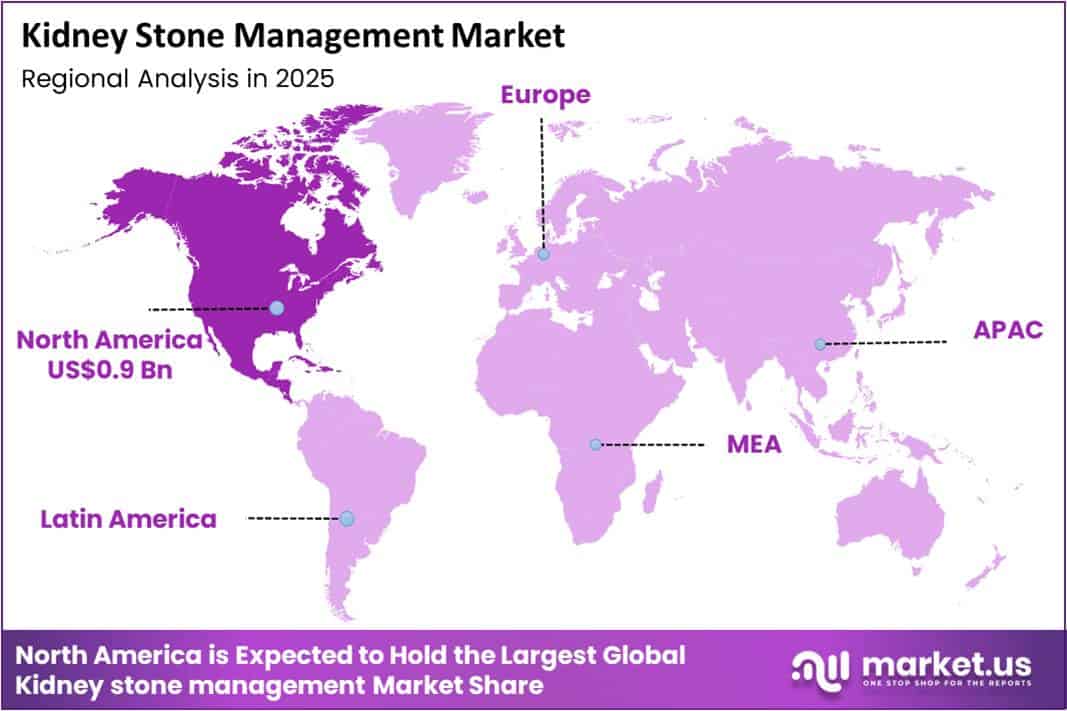
The Global Kidney Stone Management Market size is expected to be worth around US$ 4.8 Billion by 2035 from US$ 2.5 Billion in 2025, growing at a CAGR of 6.8% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 37.1% share with a revenue of US$ 0.9 Billion.
The Kidney Stone Management Market is experiencing steady growth as the global burden of kidney stone disease continues to rise due to unhealthy dietary habits, obesity, diabetes, dehydration, and aging populations. Kidney stones affect millions of people worldwide, creating significant demand for accurate diagnosis and minimally invasive treatment options.
According to the National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK), about 11% of men and 6% of women in the United States experience kidney stones at least once in their lifetime, while recurrence rates can reach 50% within 5 to 10 years without preventive measures. The increasing recurrence of the disease has strengthened the need for long-term monitoring and effective management strategies.
Kidney stone management includes diagnostic imaging, medical therapy, extracorporeal shock wave lithotripsy (ESWL), ureteroscopy, percutaneous nephrolithotomy (PCNL), laser lithotripsy, and preventive care. Healthcare providers are increasingly adopting minimally invasive technologies that reduce hospital stays, improve patient recovery, and enhance treatment precision.
The National Kidney Foundation recommends adequate hydration, dietary modifications, and timely medical intervention to reduce recurrence, emphasizing prevention alongside treatment. Advances in laser systems, digital ureteroscopes, and flexible endoscopic devices have further improved procedural success and patient outcomes.
The market is also supported by increasing healthcare expenditure, expanding access to urology services, and growing awareness of kidney health. According to the U.S. Centers for Disease Control and Prevention (CDC), approximately 37 million U.S. adults are living with chronic kidney disease, highlighting the importance of comprehensive kidney care and early diagnosis.
These healthcare trends continue to drive innovation and investment in kidney stone management solutions, supporting sustained market expansion over the coming decade.
Key Takeaways
- Market Size: Kidney Stone Management Market size was US$ 2.5 billion in 2025.The market is estimated to grow to US$ 4.8 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 6.8%.
- By Treatment Type: Extracorporeal Shock Wave Lithotripsy (ESWL) has the largest market share, accounting for 36.4% of total sales.
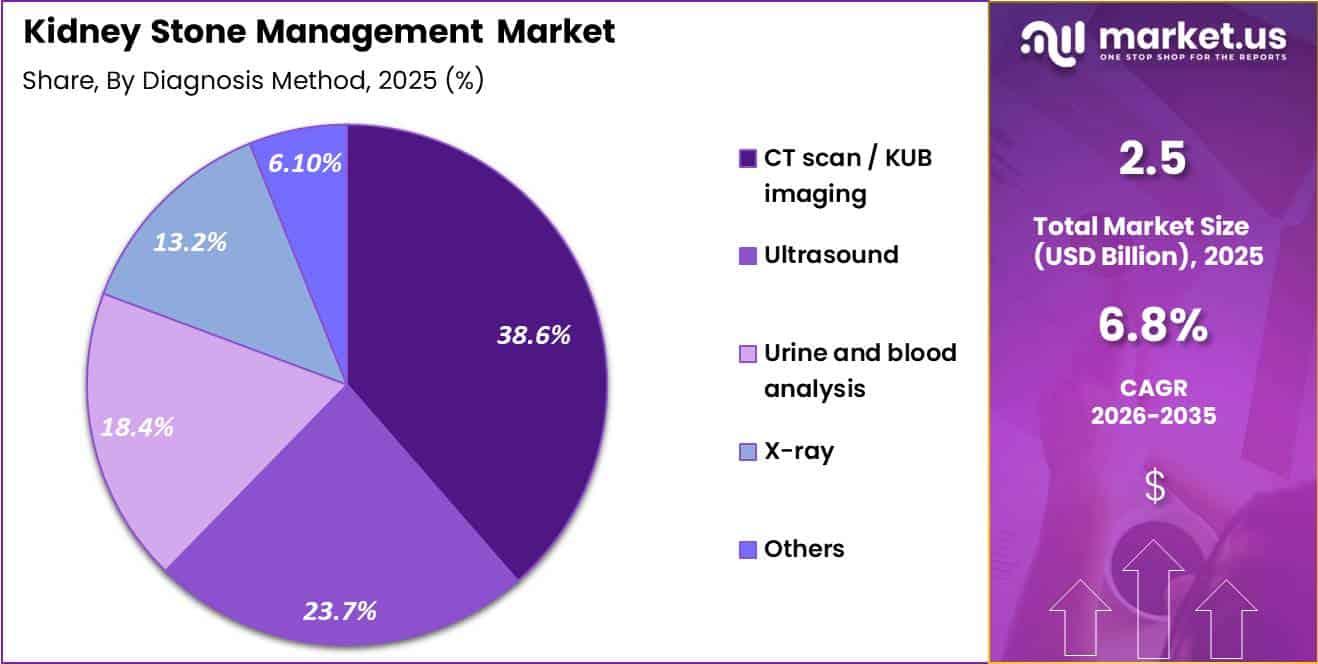
- By Diagnosis Method: CT scan / KUB imaging, accounting for 38.6% of total revenue.
- By End User: Hospitals lead the segment, accounting for 61.2% of total revenue.
- Regional: North America is the dominant regional market, accounting for 37.1% of global sales
Treatment Type Analysis
The Extracorporeal Shock Wave Lithotripsy (ESWL) segment dominated the Kidney Stone Management Market in 2025, accounting for 36.4% of the total market share. ESWL remains the preferred treatment because it is a non-invasive procedure that uses shock waves to fragment kidney stones into smaller pieces, allowing them to pass naturally through the urinary tract.
Its shorter recovery period, reduced hospital stay, and broad suitability for small- to medium-sized stones have supported widespread adoption. The increasing preference for minimally invasive treatments among patients and healthcare providers continues to strengthen demand for ESWL. Advancements in lithotripter technology have also improved treatment precision and patient outcomes, further reinforcing its leading position.
Ureteroscopy (URS) represented 28.7% of the market due to its high success rates in treating ureteral and renal stones, particularly with flexible endoscopic systems. Percutaneous Nephrolithotomy (PCNL) captured 14.8%, mainly used for large or complex kidney stones that require direct surgical access.
Laser lithotripsy/intracorporeal lithotripsy accounted for 11.8%, supported by improvements in laser technologies that enable effective stone fragmentation with minimal tissue damage. Pharmacological treatment or medical dissolution therapy held 8.3%, primarily used for selected stone types and early-stage management to reduce the need for surgical intervention.
Diagnosis Method Analysis
The CT scan / KUB imaging segment led the Kidney Stone Management Market in 2025, capturing 38.6% of the total market share. CT imaging remains the gold standard for kidney stone diagnosis because it provides highly accurate visualization of stone size, location, density, and potential urinary tract obstruction.
The growing availability of low-dose CT protocols has further encouraged its adoption by reducing radiation exposure while maintaining diagnostic accuracy. Early diagnosis has become increasingly important for preventing complications, supporting continued demand for advanced imaging techniques.
Ultrasound accounted for 23.7% of the market, driven by its radiation-free nature and widespread use among pregnant women, children, and patients requiring repeated examinations. Urine and blood analysis represented 18.4%, as laboratory testing helps identify infection, metabolic abnormalities, and stone-forming risk factors while guiding long-term prevention strategies.
X-ray held 13.2% of the market because it remains a cost-effective option for monitoring radiopaque kidney stones and evaluating treatment progress in selected patients. The Others segment captured 6.1%, including specialized diagnostic approaches such as MRI, intravenous urography, and emerging imaging technologies used in complex clinical cases where additional anatomical assessment is required.
End User Analysis
The Hospitals segment dominated the Kidney Stone Management Market in 2025, accounting for 61.2% of the total market share. Hospitals remain the primary treatment setting because they provide comprehensive diagnostic imaging, emergency care, advanced surgical facilities, and multidisciplinary teams capable of managing both routine and complex kidney stone cases.
The availability of specialized urology departments, modern lithotripsy systems, laser equipment, and intensive postoperative care has strengthened hospital preference among patients and physicians. Rising admissions for severe kidney stone complications, including urinary obstruction and infection, have further supported hospital-based treatment volumes.
In addition, hospitals are more likely to adopt advanced minimally invasive technologies such as ureteroscopy, percutaneous nephrolithotomy, and robotic-assisted procedures, improving treatment outcomes and patient safety. Growing investments in healthcare infrastructure and increasing access to specialized urological services continue to reinforce this segment’s leadership.
Ambulatory surgical centers are also experiencing steady growth due to shorter procedure times, lower treatment costs, and faster patient discharge for uncomplicated stone cases. Specialty urology clinics contribute to market expansion by offering outpatient consultations, follow-up care, preventive management, and metabolic evaluations aimed at reducing stone recurrence.
The increasing focus on patient-centered care and minimally invasive interventions is expected to support growth across all end-user settings during the forecast period.
Market Segmentations
By Treatment Type
- Extracorporeal Shock Wave Lithotripsy (ESWL)
- Percutaneous Nephrolithotomy (PCNL)
- Ureteroscopy (URS)
- Pharmacological treatment / medical dissolution therapy
- Laser lithotripsy / intracorporeal lithotripsy
By Diagnosis Method
- CT scan / KUB imaging
- Urine and blood analysis
- Ultrasound
- X-ray
- Others
By End User
- Ambulatory Surgical Centers
- Hospitals
- Specialty clinics
- Others
Driver
Rising kidney stone prevalence & recurrence in high-risk populations
Global data indicate that kidney stones now affect approximately 7–13% of adults in many high-income regions, with lifetime prevalence estimates near or above 10% in several cohorts. In US datasets, self-reported prevalence between 2017–2020 approached roughly 10%, with incidence around 1.8% annually, translating into tens of millions of individuals with historical stone disease and a steady annual inflow of new cases.
Epidemiologic analyses show recurrence rates that can exceed 30–50% over 5–10 years in untreated or suboptimally managed patients, meaning each prevalent patient represents multiple episodes over their lifetime and a large cumulative need for imaging, medical expulsive therapy, and procedural interventions.
This structurally expands the addressable pool for kidney stone management devices, pharmaceuticals, and digital follow-up tools, especially in North America, Western Europe, Gulf states, and urban APAC, where diagnostic capacity is high and patients are more likely to be referred to urology rather than managed conservatively in primary care.
For manufacturers and providers, rising prevalence and recurrence boost baseline procedural volumes and justify investments in capacity, such as additional lithotripters and flexible ureteroscopes, while also enabling recurring revenue models, such as disposables, service contracts, and follow-up imaging, that add an estimated 1.2 % points to the market CAGR relative to a flat-prevalence scenario in the 2026–2030 window.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising kidney stone prevalence & recurrence in high-risk populations | +1.2% | North America core, Western Europe, Gulf states, urban APAC | Medium term (2–4 years) |
| Metabolic disease & obesity linkages expanding interventional pool | +0.8% | North America core, EU, APAC corridors, Latin America urban | Medium term (2–4 years) |
| Guideline-driven thresholds for intervention and MET use | +0.6% | North America core, EU, Japan, selected Middle East | Short–Medium term (≤ 4 years) |
| Technology shift to miniaturized laser, flexible URS & imaging-guided ESWL | +0.7% | North America core, EU, APAC tertiary hubs | Long term (≥ 4 years) |
| Climate change, dehydration patterns & dietary westernization | +0.5% | APAC corridors, Middle East, Southern Europe, Latin America | Long term (≥ 4 years) |
| Ambulatory surgery, day-case pathways & payer cost-containment | +0.4% | North America core, EU, select APAC and Latin America | Medium term (2–4 years) |
Challenge
Interface and Dendrite Defects Limit Solid-State Battery Scaling
Interface and dendrite defects remain a critical technical friction because all-solid-state cells must simultaneously maintain interfacial resistances below approximately 10 ohm·cm² to support high-rate charging while suppressing lithium dendrite growth that can short cells in under 100–200 cycles if interfaces are poorly engineered, and this dual requirement is only being met reliably under narrow temperature and pressure windows on a subset of pilot lines.
Many oxide and sulfide electrolyte candidates have ionic conductivities in the 10⁻³–10⁻² S/cm range, but module-level testing shows 10–20% of early cells failing durability targets of 800–1000 cycles to 80% capacity under fast-charge regimes, forcing OEMs to derate charge rates to 2–3 C and operate within narrower state-of-charge windows that erode the headline 400–500 Wh/kg energy density advantages by 10–15% at the pack level.
Yield losses of 5–10 % points due to interfacial delamination, void formation, or microcracking under thermal cycling reduce effective throughput on pilot lines that only have tens of MWh per year of capacity, and this bottleneck alone can shave about 0.9 % points off otherwise achievable CAGR.
Mitigating this friction requires multi-year programs to develop compatible cathode–electrolyte chemistries, implement precision stacking or co-sintering processes with tolerances below 5 micrometers, and integrate in-line inspection capable of detecting interfacial defects at line speeds, which realistically places widespread resolution in the 2–4-year medium-term band.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| High-cost giga scaling | -1.6% | NA, EU, East Asia hubs | Long term |
| Materials supply volatility | -1.1% | Global Li–Ni–rare earth belt | Long term |
| Interface / dendrite defects | -0.9% | Global pilot lines | Medium term |
| Thermal / safety validation | -0.7% | NA, EU regulatory hubs | Medium term |
| Standards & certification lag | -0.6% | Global OEM programs | Medium term |
| Talent & ecosystem gaps | -0.5% | Emerging APAC, ROW | Long term |
Restraints
Capital Intensity Limits Advanced Kidney Stone Device Adoption
The capital intensity associated with next-generation kidney stone management technologies, including high-end digital flexible ureteroscopes, high-power holmium and thulium fiber lasers, and advanced imaging-guided ESWL platforms, creates a structural drag on market expansion as hospitals and ambulatory centers face tighter capital budgets, higher cost of borrowing, and competing priorities across service lines.
A comprehensive laser suite with 120–150 W systems, integrated imaging, and backup generators can require upfront CapEx in the USD 600,000–900,000 range per site, while premium digital flexible scopes and single-use devices add recurring per-case costs of USD 600–1,000, pushing total per-procedure economics to 1.3–1.5 times the cost of legacy platforms.
With higher interest rates through 2024–2025, many systems face weighted average capital costs in the 7–9% band, which, coupled with annual maintenance contracts of 8–12% of equipment value, stretches payback periods from 3–4 years historically to 6–8 years for many stone centers, especially in mid-volume facilities performing fewer than 250–300 complex stone cases annually.
In emerging APAC corridors and Latin America, foreign exchange volatility can add 10–20% effective price variability on imported equipment, forcing hospitals to delay purchases or opt for refurbished systems, while public-sector procurement cycles often extend 18–24 months, creating installation backlogs and underutilization risk.
Strategically, this high CapEx burden leads to staggered adoption curves, concentration of advanced modalities in top-tier urban centers, slower replacement of end-of-life equipment, and a tendency to extend asset utilization beyond recommended lifecycles, which caps available installed base growth and constrains procedural capacity uplift.
Net-net, the capital intensity restraint is modeled to shave roughly 1.9 % points off the potential CAGR over a ≥4-year horizon, globally but with particular weight in APAC growth corridors and capital-constrained tertiary care networks.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Procedure reimbursement pressure | -2.2% | North America, EU-5 | Medium term (2–4 years) |
| Capital intensity of advanced devices | -1.9% | Global tertiary care, APAC corridors | Long term (≥ 4 years) |
| Access gaps and care fragmentation | -1.6% | Emerging Asia, Latin America, MEA | Long term (≥ 4 years) |
| Regulatory and data-compliance drag | -1.4% | U.S., EU, selected APAC | Medium term (2–4 years) |
| Workforce and capacity constraints | -1.3% | North America core, EU, urban India | Short–Medium (≤ 4 years) |
| Preventive care dampening procedure volumes | -1.1% | China, high-income markets | Long term (≥ 4 years) |
Opportunity
Metabolic Prevention Platforms Expand Kidney Stone Care Opportunities
Metabolic and obesity-linked prevention platforms represent a structurally distinct opportunity from today’s procedure-focused kidney stone management market because they explicitly monetize the upstream link between obesity, diabetes, and stone formation rather than the acute stone event itself.
Leveraging the fact that lifetime kidney stone risk approaches 10% globally and has risen by roughly 20–30% over the past two decades in many industrialized populations as obesity and metabolic syndrome have become more prevalent.
Epidemiologic data show that between one third and two thirds of patients experience recurrence within five years depending on risk profile, and economic analyses estimate that kidney stones already generate direct and indirect annual costs in the multi-billion-dollar range in high-income markets.
Implying that even a 10% reduction in recurrence in high-risk cohorts, such as obese, diabetic, or hyperuricemic patients, could unlock several hundred million dollars in avoided acute-care costs that payers would be willing to share with integrated prevention platforms via risk-sharing or outcome-based contracts.
Strategically, this upside is not embedded in baseline forecasts because most current models assume continued fee-for-service treatment of acute episodes, with only limited penetration of structured metabolic clinics or endocrinology-urology collaborations.
However, the rapid diffusion of GLP-1 therapies and broader cardio-metabolic care programs by 2030 opens white space for urology providers, digital health companies, and pharma partners to create bundled “stone plus metabolic” care pathways that could capture incremental TAM of 5–10%.
Over today’s device-and-surgery-centric market by monetizing diagnostic workups, lab panels, digital coaching, and chronic medication adherence, yielding potential incremental EBITDA margins of 300–500 basis points for integrated providers that can reduce readmissions while sharing savings with payers.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Metabolic & Obesity-Linked Prevention Platforms | +1.8% | North America, EU, GCC, Urban APAC | Medium term |
| Integrated Stone-Recurrence Programs in Value-Based Care | +1.5% | US, UK, Nordics, Select APAC | Medium term |
| AI-Guided Imaging & Virtual Triage Networks | +1.3% | North America, EU, China, India | Short term |
| Ambulatory & Retail Lithotripsy Networks | +1.2% | North America, EU, Urban LATAM | Medium term |
| Emerging-Market Day-Surgery Expansion | +1.0% | India, SE Asia, MENA, LATAM | Long term |
| Home-Based Monitoring & Digital Adherence Tools | +0.9% | North America, EU, Affluent APAC | Long term |
Regional Analysis
In 2025, North America led the market, achieving over 37.1% share with a revenue of US$0.9 billion.
In 2025, North America region’s leadership is supported by a high prevalence of kidney stone disease, advanced healthcare infrastructure, and broad access to minimally invasive treatment technologies.
According to the U.S. National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK), kidney stones affect nearly one in eleven people in the United States during their lifetime, creating consistent demand for diagnostic imaging and surgical intervention.
The widespread availability of advanced treatment options such as extracorporeal shock wave lithotripsy (ESWL), ureteroscopy, percutaneous nephrolithotomy (PCNL), and laser lithotripsy has strengthened regional market growth. Hospitals and specialized urology centers continue to adopt modern laser systems and digital ureteroscopes that improve treatment precision, reduce hospital stays, and enhance patient outcomes.
Government-backed healthcare spending, favorable reimbursement policies, and increasing awareness of preventive kidney care further support market expansion. The rising incidence of obesity, diabetes, and dehydration-related disorders—major risk factors for kidney stone formation—has also increased the number of patients requiring diagnosis and treatment.
In addition, continuous clinical research, technological innovation, and the strong presence of leading medical device manufacturers position North America as the most influential regional market for kidney stone management throughout the forecast period.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global Kidney Stone Management Market is moderately consolidated, with established medical technology manufacturers competing through continuous innovation, product differentiation, and strategic collaborations. Companies are focusing on improving stone removal efficiency, reducing procedure time, and enhancing patient safety while supporting the growing adoption of minimally invasive treatments.
Competition is driven by investments in advanced lithotripsy systems, flexible ureteroscopes, laser technologies, imaging integration, and digital workflow solutions that improve clinical outcomes and hospital productivity.
Market participants also emphasize expanding their global distribution networks and strengthening relationships with hospitals, ambulatory surgical centers, and urology clinics through comprehensive service and training programs.
Leading companies including SIEMENS Healthineers, Richard Wolf, PolyDiagnost, OLYMPUS, Coloplast, KARL STORZ, EMS ELECTRO MEDICAL SYSTEMS, ELMED Medical Systems, Dornier MedTech, DirexGroup, COOK MEDICAL, Allengers, Boston Scientific, Becton, Dickinson and Company, and MEDISPEC are prioritizing research and development to introduce more precise, user-friendly, and minimally invasive kidney stone management technologies.
Their competitive strategies focus on product innovation through enhanced laser lithotripsy platforms, shock wave lithotripsy systems, endoscopic instruments, guidewires, stents, and stone retrieval devices. Partnerships with healthcare providers and research institutions help accelerate technology validation and clinical adoption.
Companies are increasingly integrating imaging, endoscopy, and digital workflow platforms to streamline diagnosis and treatment. Ecosystem-based competition is becoming more prominent, with manufacturers offering comprehensive urology portfolios, clinician training, after-sales support, and connected solutions that strengthen long-term customer relationships and improve procedural efficiency across diverse healthcare settings.
Top Key Players
- SIEMENS Healthineers
- Richard Wolf
- PolyDiagnost
- OLYMPUS
- Coloplast
- KARL STORZ
- EMS ELECTRO MEDICAL SYSTEMS
- ELMED Medical Systems
- Dornier MedTech
- DirexGroup
- COOK MEDICAL
- Allengers
- Boston Scientific
- Becton, Dickinson and Company
- MEDISPEC
Recent Developments
- In September 2025, Dornier MedTech America commercially launched the Hoover FANS (Flexible and Navigable Suction) Ureteral Access Sheath together with the Axis II Slim single-use ureteroscope, expanding minimally invasive solutions for kidney stone management.
- In March 2026, Boston Scientific received U.S. FDA 510(k) clearance for the Asurys™ Fluid Management System, designed for ureteroscopy, cystoscopy, and percutaneous nephrolithotomy (PCNL). The system integrates with the LithoVue™ Elite ureteroscope to help manage intrarenal pressure during kidney stone procedures.
- In March 2026, Dornier MedTech entered a strategic commercial partnership with Potent Medical to expand its endourology portfolio by adding comprehensive laser technologies for kidney stone treatment, strengthening its lithotripsy and laser offerings.
- In March 2026, Cook Medical announced the commercial launch of the Syfonix™ Suction Ureteral Access Sheath and the 7.5 Fr Ascend™ single-use flexible ureteroscope, enhancing its portfolio for endoscopic kidney stone treatment.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 2.5 Bn |
| Forecast Revenue (2035) | US$ 4.8 Bn |
| CAGR (2026-2035) | 6.8 % |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Treatment Type (Extracorporeal Shock Wave Lithotripsy (ESWL) , Percutaneous Nephrolithotomy (PCNL) , Ureteroscopy (URS) , Pharmacological treatment / medical dissolution therapy ,Laser lithotripsy / intracorporeal lithotripsy) By Diagnosis Method (CT scan / KUB imaging,Urine and blood analysis,Ultrasound,X-ray ,Others) By End User (Ambulatory Surgical Centers ,Hospitals ,Specialty clinics ,Others) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | SIEMENS Healthineers ,Richard Wolf ,PolyDiagnost ,OLYMPUS ,Coloplast ,KARL STORZ ,EMS ELECTRO MEDICAL SYSTEMS ,ELMED Medical Systems ,Dornier MedTech ,DirexGroup ,COOK MEDICAL ,Allengers ,Boston Scientific ,Becton, Dickinson and Company ,MEDISPEC |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








