


Report Overview
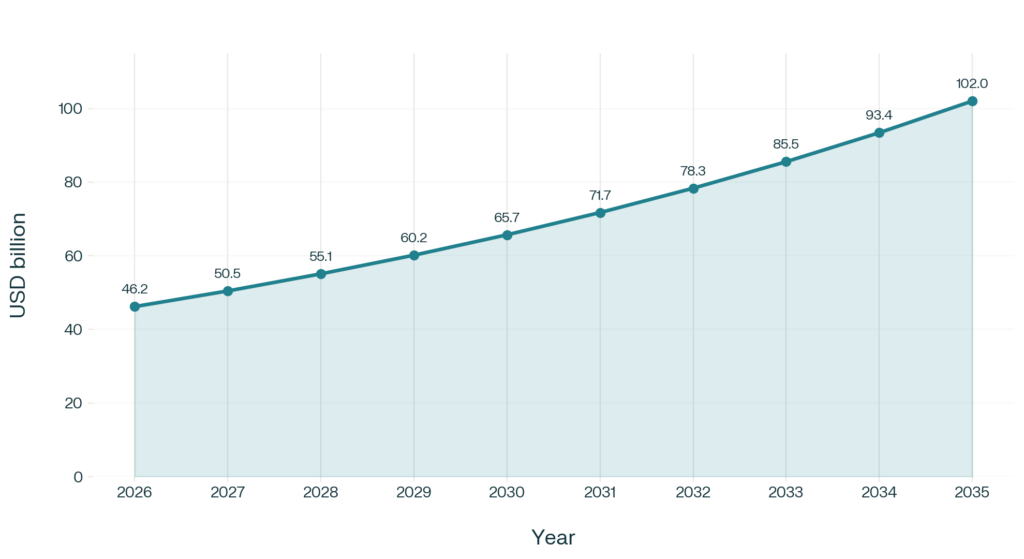
Japan Luxury Travel Market is valued at USD 46.20 billion in 2026 and is expected to reach USD 102.02 billion by 2035, expanding at a CAGR of 9.2% during 2026 to 2035. Luxury travel in Japan includes premium accommodation, curated transport, private guiding, wellness, cultural access, high-end dining, and destination-led itinerary design. The market creates value through bundled and scarce experiences rather than through hotel room demand alone.
Japan’s travel ecosystem provides a strong base for luxury travel growth. The World Travel and Tourism Council reported that travel and tourism contributed USD 343.1 billion to Japan’s economy in 2025, equal to 8.1% of GDP. This large service economy supports premium hotels, ryokan, airlines, private transport, guides, and dining partners, all of which are essential to high-value itinerary delivery.
Key Takeaways
- Japan Luxury Travel Market is valued at USD 46.20 billion in 2026.
- The market is projected to reach USD 102.02 billion by 2035.
- The forecast CAGR for 2026 to 2035 is 9.2%.
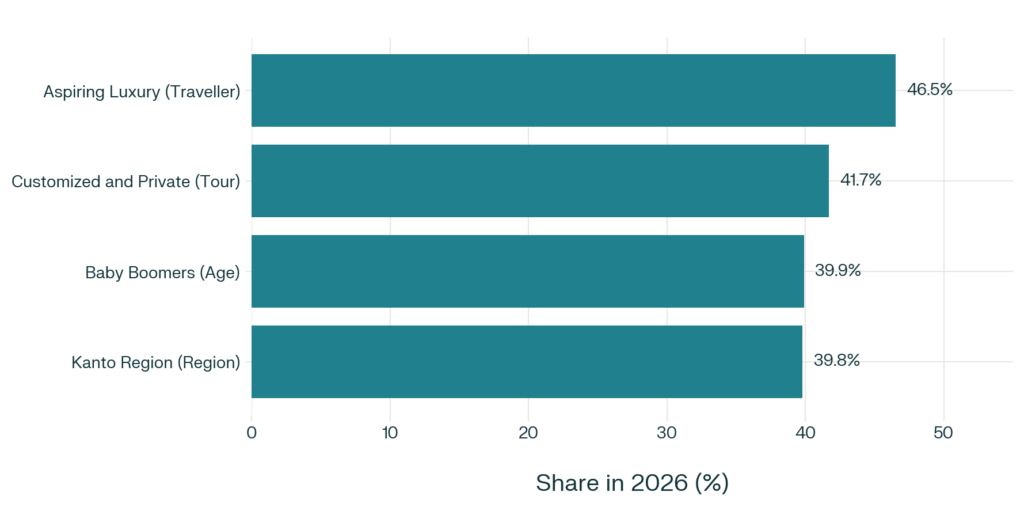
- Customized and Private Vacation leads the tour type segment with 41.7% share in 2026.
- Culinary Travel and Shopping is the fastest-growing tour type.
- Baby Boomers lead the age group segment with 39.9% share in 2026.
- Aspiring Luxury leads the traveller type segment with 46.5% share in 2026.
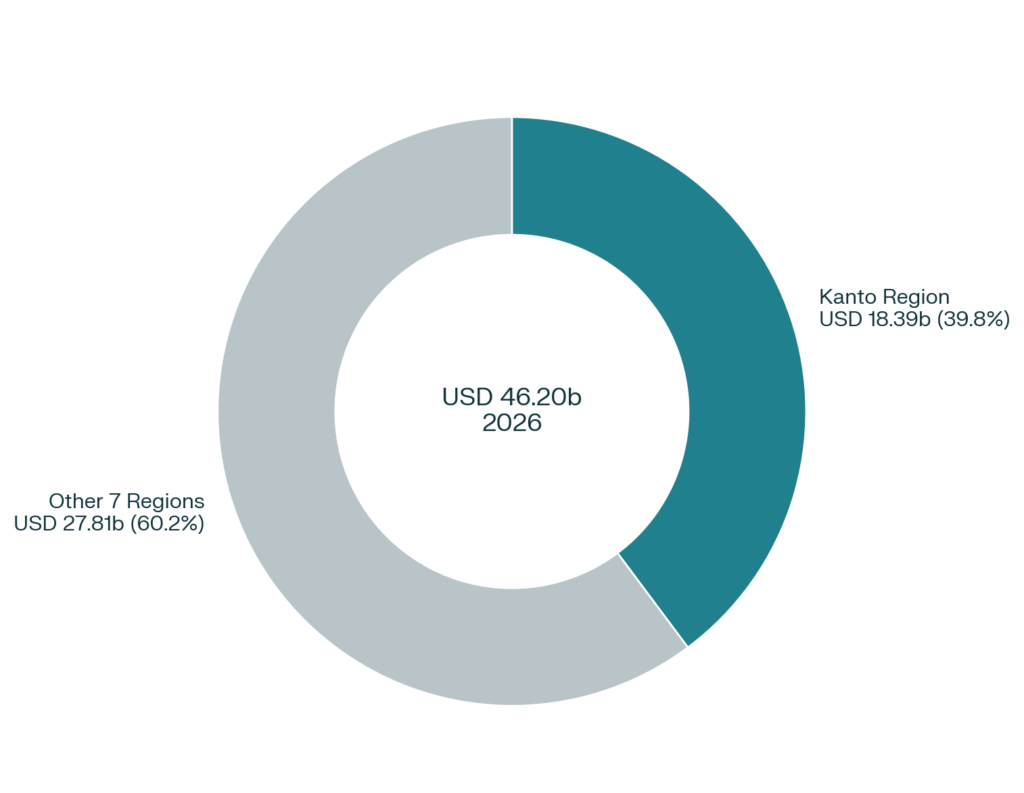
- Kanto Region leads the market with 39.8% share in 2026.
- Specialist hospitality talent shortages remain the most important operating constraint.
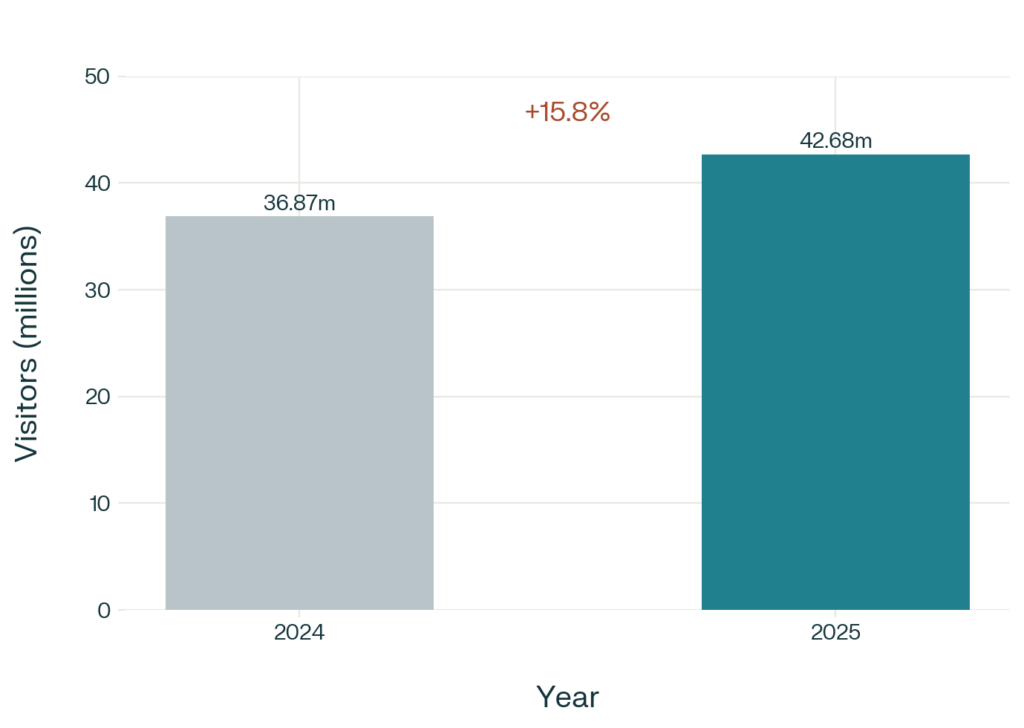
International access continues to strengthen the premium travel opportunity. The International Air Transport Association reported that international travel to Japan increased 15.8% in 2025 after rising 47.1% in 2024. JNTO separately reported that Japan received 42,683,600 inbound visitors in 2025, compared with 36,870,148 in 2024. Rising arrivals expand the conversion pool for premium itineraries, especially in gateway cities with strong air connectivity.
Japan’s policy direction also supports premium and regional tourism growth. OECD reported that Japan’s tourism strategy emphasizes higher visitor spending, improved regional attractiveness, transport network strengthening, and sustainable tourism development in regional areas. This improves the long-term operating environment for luxury travel operators that want to move demand beyond Tokyo and Kyoto into high-value regional circuits.
Minor Hotels announced an approximately 240-room Avani Kyoto development in June 2026, marking the Avani brand’s debut in Japan. Hoshino Resorts also announced the 48-suite HOSHINOYA Nara Prison project in January 2026, with room rates starting at JPY 147,000 per night. These developments show that new premium supply is being added in culturally important destinations where differentiated assets can support premium pricing.
Kanto Region dominates the market with a share of 39.8% in 2026, equal to about USD 18.39 billion based on the 2026 market value. UN Tourism reported that Japan’s international tourism receipts increased 34% year over year in the first quarter of 2025. Strong demand, large gateway capacity, and premium urban supply keep Kanto ahead, while regional policy and hotel investment continue to widen the luxury opportunity across the rest of Japan.
Investment Case
Japan offers a strong luxury travel investment case because it combines rising inbound demand with limited premium inventory and strong regional expansion potential. JTB projected that inbound travel to Japan would reach 40.2 million visitors in 2025, equal to 126.1% of 2019 levels. A larger international visitor base widens the premium conversion funnel for operators that can package accommodation, transport, and exclusive experiences into coherent luxury products.
The market also benefits from rising capital commitments to premium assets. Four Seasons reported that the Four Seasons Okinawa master plan carries an estimated development cost of USD 400 million and a gross development value of USD 1 billion. Large-scale resort investment indicates long-term confidence in destination-led luxury demand, especially in beach, wellness, and lifestyle-oriented travel.
Regional development creates the clearest upside beyond major urban gateways. OECD reported that Japan designated 11 regional Model Tourist Destinations to support luxury inbound tourism. This creates space for investors to build integrated circuits that connect premium accommodation, private transport, local dining, and guided access across less-penetrated regions.
Tour Type Analysis
Customized and Private Vacation dominates the Tour Type segment with 41.7% share in 2026. OECD reported that Japan identified 11 regional model destinations for luxury inbound tourism development. Private itineraries require high coordination across transport, accommodation, guides, and cultural access, which supports premium pricing and stronger customer retention.
Culinary Travel and Shopping is the fastest-growing tour type because it combines food access, local retail, cultural authenticity, and high spending intensity. UN Tourism reported that its gastronomy tourism study on Japan included 18 case studies, ranging from sake breweries to hotel trains. This segment grows quickly because reservation-led dining and localized retail experiences can raise spend per traveller without depending only on large-scale room additions.
Adventure and Safari in Japan is best interpreted as guided nature, mountain, wildlife, and outdoor premium travel. Hoshino Resorts reported that its first LUCY mountain hotel has 25 rooms, including 12 dormitory rooms, 10 twin rooms, and 3 four-person rooms. Small-capacity outdoor inventory supports premium pricing when operators combine guided activities with access, safety, and seasonal planning.
Age Group Analysis
Millennial travellers often prefer flexible premium experiences that combine food, design, culture, and convenience. UN Tourism reported that youth travel represents more than 23% of international tourists worldwide. For luxury operators, this segment is important because it responds well to curated upgrades, mobile-first booking, and visually distinctive experiences.
Baby Boomers dominate the Age Group segment with 39.9% share in 2026. OECD reported that Japan’s old-age dependency ratio rose from 28% in 2000 to 55% in 2023 and is projected to reach 79% by 2050. Mature travellers typically value comfort, planning certainty, and premium service reliability, which supports demand for private transfers, accessible hotels, and concierge-led itineraries.
Silver Hair travel depends on accessibility, wellness, lower itinerary complexity, and stronger service support. World Bank data show that people aged 65 and above represented about 29.99% of Japan’s population in 2025. This demographic statistic supports the domestic accessibility case and underlines why age-friendly service design matters in luxury travel, although it should not be treated as the exact age profile of inbound luxury travellers.
Traveller Type Analysis
Aspiring Luxury dominates the Traveller Type segment with 46.5% share in 2026. JTB projected 40.2 million inbound travellers in 2025, equal to 108.9% of 2024 and 126.1% of 2019 levels. This segment represents the largest upgrade pool because many travellers will pay more for better stays, easier logistics, and curated experiences without moving into full ultra-luxury travel.
Absolute Luxury travellers seek privacy, rare access, and highly personalized service. Accor reported that its Luxury and Lifestyle division generated EUR 1.598 billion in revenue in 2025, up 9.8% at constant currency. This supports continued expansion in top-tier accommodation and reinforces the value of scarce inventory, destination prestige, and concierge-led service.
Accessible Luxury combines quality accommodation and curated upgrades at a lower entry point than ultra-luxury travel. IATA reported that Japan was the world’s sixth-largest passenger market in 2024, with 205 million domestic and international air passengers, up 18.6% year over year. Strong air connectivity lowers friction for premium short breaks and supports the growth of simplified upscale packages.
Key Market Segments
By Tour Type
- Customized and Private Vacation
- Culinary Travel and Shopping
- Adventure and Safari
- Cruise and Ship Expedition
- Small Group Journey
- Celebration and Special Event
By Age Group
- Millennial (21 to 30)
- Generation X (31 to 40)
- Baby Boomers (41 to 60)
- Silver Hair (60 and Above)
By Traveller Type
- Aspiring Luxury
- Absolute Luxury
- Accessible Luxury
By Region
- Kanto Region
- Kansai/Kinki Region
- Central/Chubu Region
- Kyushu-Okinawa Region
- Tohoku Region
- Chugoku Region
- Hokkaido Region
- Shikoku Region
Regional Analysis
Kanto Region dominates the Japan Luxury Travel Market with a market share of 39.8% in 2026, equivalent to about USD 18.39 billion. ANA Holdings reported that its new Haneda routes to Milan, Stockholm, and Istanbul achieved an average load factor of about 80% in the quarter ended June 2025. Kanto benefits from international gateway access, high-end retail, premium dining, and dense hotel supply, all of which improve conversion into higher-value travel bookings.
Kansai/Kinki remains the strongest cultural luxury market outside Kanto. Four Seasons reported that Four Seasons Hotel Osaka opened with 175 guestrooms, including 21 rooms on its GENSUI modern-ryokan floor. The region benefits from Kyoto’s heritage strength and Osaka’s service infrastructure, which together support high-value cultural itineraries.
Central/Chubu benefits from mountains, onsen, and low-density wellness travel. Hoshino Resorts reported that the renovated KAI Matsumoto has 29 guestrooms, including 19 rooms with private outdoor baths. This region is well suited to intimate premium stays where privacy and local character justify stronger pricing.
Kyushu-Okinawa offers strong potential in resort, beach, and wellness travel. Four Seasons reported that its Okinawa master plan carries an estimated development cost of USD 400 million and a gross development value of USD 1 billion. This region is attractive for destination-led luxury models that combine longer stays with premium recreation.
Tohoku benefits from regional-dispersion policy, seasonal travel, and lower-density destination experiences. JTB reported that Tohoku recorded a 50.0% intra-regional travel score in its 2025 to 2026 year-end travel survey. This indicates strong domestic movement patterns that can support higher-value regional circuits.
Chugoku has opportunity in cultural, art, and coastal travel, especially around premium itineraries linked to Hiroshima and the wider Setouchi area. IHG reported that its announced Japan pipeline included 14 hotels totaling 2,355 rooms, including a planned voco Hiroshima property. This shows that branded supply is expanding in regions beyond the largest gateways.
Hokkaido benefits from winter sports, nature, and premium culinary travel. IHG reported that InterContinental Sapporo opened with 149 guestrooms, including 13 suites. This addition strengthens Hokkaido’s ability to serve premium urban and seasonal visitors beyond dedicated ski resorts.
Shikoku remains a smaller market but shows strong niche growth potential in slow travel, wellness, and spiritual circuits. Hoshino Resorts reported that it recorded 4 times as many international guests in Shikoku in 2025 as in 2024, while OMO7 Kochi posted 288% growth. This highlights the upside for selective premium products in less-penetrated regional markets.
Regional Opportunity Matrix
| Region | Demand Driver | Luxury Product Focus | Main Constraint | Investment Signal |
|---|---|---|---|---|
| Kanto | International gateway traffic | Urban hotels, dining, retail, concierge travel | High operating costs | Strong premium conversion economics |
| Kansai/Kinki | Heritage and cultural appeal | Ryokan, gastronomy, private guided travel | Peak-date congestion | High-value cultural packaging |
| Central/Chubu | Onsen and mountain travel | Wellness, ryokan, private nature stays | Transport coordination | Premium low-density positioning |
| Kyushu-Okinawa | Resort and wellness demand | Beach resorts, villas, premium leisure | Seasonality | Strong destination-led luxury upside |
| Tohoku | Regional dispersion policy | Rural circuits, snow and cultural travel | Limited premium distribution | Early-mover circuit opportunity |
| Chugoku | Setouchi and heritage itineraries | Art, coastal stays, cultural travel | Supplier fragmentation | Packaging-led monetization |
| Hokkaido | Nature and winter demand | Ski, wellness, culinary travel | Season concentration | High seasonal yield potential |
| Shikoku | Slow travel and spiritual tourism | Wellness, pilgrimage, private rural stays | Lower international visibility | Selective niche luxury opportunity |
Luxury Travel Value Chain
Luxury travel value creation begins with demand generation through airlines, loyalty programs, luxury travel advisors, destination marketing, and digital discovery. It then moves into product creation across hotels, ryokan, restaurants, cultural venues, wellness operators, guides, and transport providers. Premium value expands when these individual services are coordinated into a single high-quality itinerary.
| Layer | Participants | Main Margin Driver | Core Risk |
|---|---|---|---|
| Demand Generation | Airlines, luxury advisors, loyalty platforms, OTAs | Premium customer acquisition | Source-market volatility |
| Product Creation | Hotels, ryokan, dining, culture, wellness | Scarce experiences and room inventory | Capacity constraints |
| Distribution | DMCs, luxury agencies, concierges, operators | Package mark-up and itinerary bundling | Fragmented contracting |
| Delivery | Guides, chauffeurs, local teams, guest-relations staff | Service quality and retention | Labour shortage |
Buyer Decision Factors
Premium travellers typically evaluate Japan luxury travel on privacy, service quality, transport certainty, confirmed reservations, and authenticity of experience. They are often less price-sensitive than mass-market buyers but more sensitive to service failure and coordination gaps. This means booking conversion depends as much on trust and execution quality as on destination appeal.
- Privacy and exclusivity.
- Reliable premium accommodation.
- Confirmed restaurant and cultural reservations.
- Multilingual guide and transport availability.
- Flexible itinerary management.
- Accessibility and wellness support.
- Clear cancellation protections.
Market Dynamics
Japan’s luxury travel market faces a clear service-capacity challenge. JTB, citing Japan’s Ministry of Health, Labour and Welfare, reported that unfilled positions in Japan’s tourism and food-service industries exceeded 330,000. Luxury travel depends on trained people across hotels, dining, guest relations, guiding, and transport, so labour gaps can directly limit the number of premium itineraries that operators can deliver at a consistent standard.
Drivers
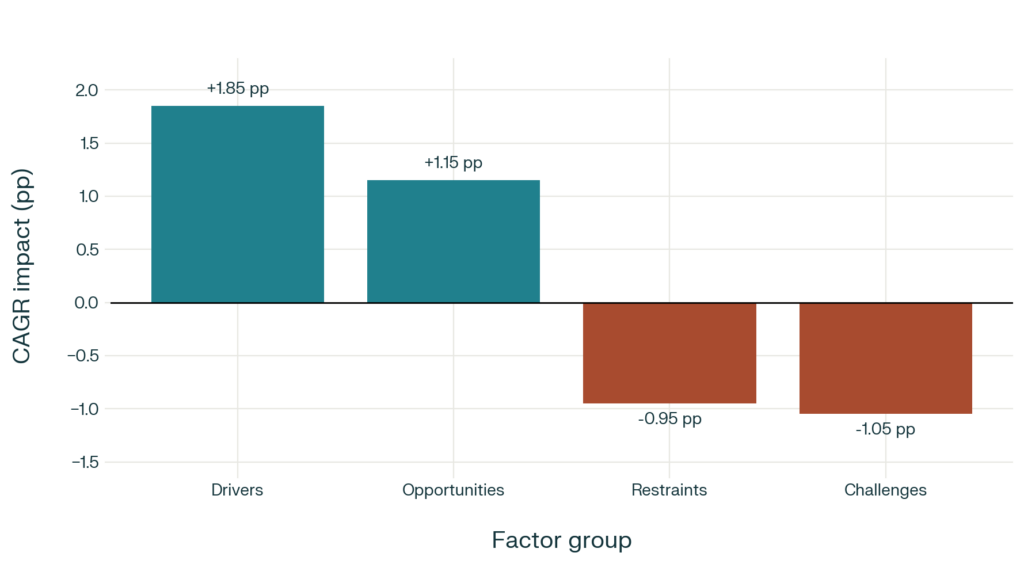
Inbound demand remains the strongest direct market driver. JNTO reported that Japan received 36,870,148 inbound visitors in 2024 and 42,683,600 in 2025, equal to annual growth of 15.8%. This creates a larger premium conversion pool for hotels, operators, and destination managers.
Luxury demand also grows when operators can package rooms, dining, transport, and exclusive access into integrated products. The strongest growth will likely come from better conversion of high-value travellers rather than from pure volume expansion.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Record inbound visitor demand | +0.65% | Nationwide; Tokyo, Kyoto, Osaka | Short term (≤ 2 years) |
| Established high-spending traveler penetration | +0.45% | Major metropolitan destinations | Short term (≤ 2 years) |
| International source-market diversification | +0.30% | Major international gateways | Short term (≤ 2 years) |
| Existing premium accommodation upgrades | +0.25% | Established hotel and ryokan destinations | Medium term (2–4 years) |
| Established experiential itinerary packaging | +0.20% | Kyoto, Tokyo, established resort destinations | Short term (≤ 2 years) |
Note: CAGR sensitivity values are analyst estimates and should not be treated as published market forecasts.
Restraints
Japan’s notified private lodging framework limits operating availability for residential luxury rentals. Under the Private Lodging Business Act, operators can provide lodging for a maximum of 180 days during a reporting year, equal to about 49.3% of a standard 365-day year. This limits year-round monetization for some upscale residential accommodation formats.
Additional municipal lodging restrictions, heritage-area access rules, peak-date room scarcity, and finite reservation-led experiences can all restrict itinerary design. Luxury operators therefore need early contracting, backup supply, and strong inventory management.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Annual operating caps on notified private lodging | -0.35% | Nationwide; notified residential rentals only | Short term (≤ 2 years) |
| Additional municipal private-lodging restrictions | -0.20% | Restrictive municipal jurisdictions | Short term (≤ 2 years) |
| Restricted access to private heritage lanes | -0.15% | Selected Gion lanes, Kyoto | Short term (≤ 2 years) |
| Peak-date premium room sellouts | -0.15% | Concentrated seasonal resort destinations | Short term (≤ 2 years) |
| Finite exclusive-experience reservation slots | -0.10% | Invitation-only dining and cultural venues | Short term (≤ 2 years) |
Note: CAGR sensitivity values are analyst estimates and should not be treated as published market forecasts.
Challenges
Labour availability remains the largest operating challenge in premium travel delivery. Japan’s 2026 tourism white paper reported that 72.2% of 522 surveyed accommodation facilities faced labour shortages, while 79.3% of those properties reported heavier peak-period workloads. This means service quality can deteriorate even when demand is healthy.
Regional luxury travel also depends on synchronized transport, guiding, accommodation, and dining capacity. Weather risk, rural access constraints, and seasonal concentration raise execution complexity in mountain, island, and remote cultural destinations.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Specialist hospitality talent shortages | -0.45% | Nationwide; regional luxury properties | Medium term (2–4 years) |
| Fragmented itinerary supplier coordination | -0.20% | Multi-destination private itineraries | Medium term (2–4 years) |
| Regional last-mile transport complexity | -0.15% | Rural, mountain, and island destinations | Medium term (2–4 years) |
| Natural hazard itinerary disruption | -0.15% | Earthquake, typhoon, and volcanic exposure zones | Long term (≥ 4 years) |
| Seasonal demand forecasting uncertainty | -0.10% | Snow, foliage, and blossom destinations | Medium term (2–4 years) |
Note: CAGR sensitivity values are analyst estimates and should not be treated as published market forecasts.
Opportunities
Integrated regional luxury circuits provide the strongest structural growth opportunity because they extend stay length and spread visitor spending beyond major gateway cities. Japan Tourism Agency data indicate that high-value visitors represented about 2% of inbound travellers but about 19% of inbound spending in 2023, and the agency selected 11 model destinations in 2023 before adding 3 more in 2024. This concentration of spending shows the strong monetization potential of well-managed premium travel.
Wellness travel, accessible multigenerational stays, premium coastal itineraries, and concierge subscriptions can also raise revenue per booking. Operators that standardize supplier coordination can target 2 to 3 additional paid nights per itinerary and reduce itinerary assembly costs by around 8% to 12% through better execution.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Integrated regional luxury circuits | +0.50% | Tohoku, Hokuriku, San’in, Kyushu | Medium term (2–4 years) |
| Clinical wellness travel partnerships | +0.20% | Medical hubs and wellness resorts | Medium term (2–4 years) |
| Accessible multigenerational luxury stays | +0.20% | Nationwide; adapted hotels and resorts | Medium term (2–4 years) |
| Private expedition yacht itineraries | +0.15% | Setouchi, Okinawa, coastal destinations | Long term (≥ 4 years) |
| Subscription-based travel concierge services | +0.10% | Repeat international and domestic clients | Medium term (2–4 years) |
Note: CAGR sensitivity values are analyst estimates and should not be treated as published market forecasts.
Pricing and Margin Logic
Luxury travel margins rise when operators control scarce services within a single package. Private guides, chauffeur transfers, premium dining allocations, room allotments, and invitation-led cultural access all create pricing power when availability is limited. This is why gross market growth does not automatically translate into strong profitability for all operators.
Longer itineraries further increase revenue density by adding nights, activities, transport legs, and concierge support within one customer relationship. Repeat business lowers acquisition costs and can improve lifetime value. The most important commercial KPIs include average booking value, gross margin per itinerary, ancillary spend per traveller, repeat booking rate, and the share of itinerary components contracted directly.
Key Company Insights
Accor
Accor plays a major role in Japan’s premium accommodation expansion through international brand strength and global distribution. Accor reported consolidated revenue of EUR 5.639 billion in 2025, representing 4.5% constant-currency growth. Its scale supports booking reach, loyalty capture, and service consistency in gateway-city luxury travel.
Accor also announced Fairmont Tokyo as a 217-room luxury hotel with 5 restaurants, 2 bars, and 3 outdoor terraces in January 2025. This strengthens international luxury supply in Tokyo and increases competition around branded urban premium stays.
ANA Holdings Inc.
ANA Holdings shapes luxury travel through long-haul access, domestic route connectivity, and premium air service. ANA reported record FY2024 revenue of JPY 2,261.8 billion, up JPY 205.9 billion from the previous fiscal year. Strong airline performance supports route development and premium customer service investment.
ANA also announced a five-year investment programme of JPY 2.7 trillion in January 2026, with around 50% allocated to international passenger and cargo businesses and JPY 270 billion to digital transformation. Better connectivity and digital service infrastructure can improve access to premium Japanese itineraries.
JTB Corp.
JTB remains central to Japan’s luxury travel value chain because it packages itineraries, manages destination relationships, and connects demand with local execution. JTB reported FY2025 sales of JPY 1.1333 trillion, up 6% year over year, with ordinary profit of JPY 17.3 billion. Its scale supports product breadth and stronger regional distribution capacity.
JTB also partnered with Airbnb Japan in January 2025 to expand regional hospitality infrastructure to 100 Japanese regions by 2028. This can improve regional stay availability and support the development of broader premium circuits beyond the largest cities.
| Company | Market Role | Key Metric | Strategic Relevance |
|---|---|---|---|
| Accor | Luxury accommodation | EUR 5.639 billion 2025 revenue | Branded premium supply and international distribution |
| ANA Holdings | Aviation and access | JPY 2.7 trillion investment programme | Long-haul and domestic connectivity |
| JTB Corp. | Itinerary packaging and distribution | JPY 1.1333 trillion FY2025 sales | Regional product aggregation and travel distribution |
Key Players
- Accor (Fairmont Tokyo)
- ANA Holdings Inc.
- JTB Corp.
- Luxury Escapes
- Revigorate (APCS Lda)
- Four Seasons Hotels and Resorts
- Nankai Electric Railway Co., Ltd.
- Unforgettable Travel
- Sky Vacations
- HIS Co., Ltd.
- InsideJapan Tours
- Scott Dunn
- Abercrombie & Kent
- Oku Japan
- Walk Japan
- TUI Group
- Butterfield & Robinson
- GeoEx (Geographic Expeditions)
- Hoshino Resorts
- Minor International
Geopolitical Impact Analysis
Global trade and travel conditions affect Japan’s luxury travel market through air connectivity, imported premium goods, exchange-rate movements, and source-market spending confidence. The World Trade Organization reported that travellers’ expenditure in foreign economies reached USD 1.74 trillion in 2024, up 13% in value and 11% in volume. It also projected international travel trade growth of 3.1% in 2025 and 4.4% in 2026. These trends support premium travel expansion but also intensify global destination competition.
Luxury travel also depends on global goods and services flows. UN Trade and Development reported that total trade in goods and services surpassed USD 35 trillion in 2025, with services growing by almost 9%. Imported wines, specialty foods, linens, spa products, guest amenities, and vehicle parts all feed premium travel operations. This means disruption in shipping, cross-border payments, or supply chains can raise operating costs and compress margins.
Currency conditions matter as well. The International Monetary Fund reported that Japan’s current-account surplus increased to 4.8% of GDP in 2025 from 4.5% in 2024.
Recent Developments
2026
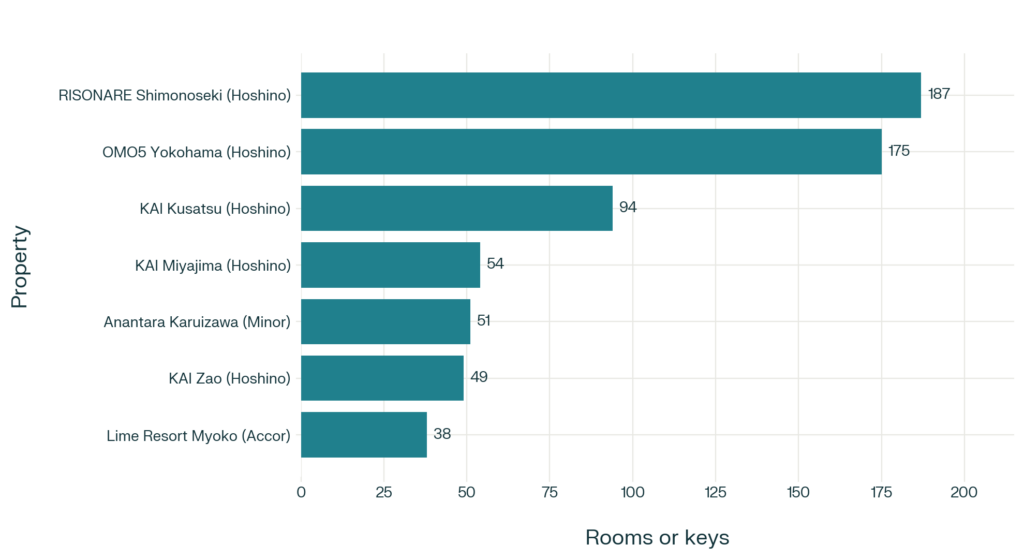
- January 2026: Hoshino Resorts opened the 175 room OMO5 Yokohama Bashamichi across 16,772 square metres. Hoshino Resorts.
- April 2026: Hoshino Resorts announced the 49 room KAI Zao for opening in October 2026. Hoshino Resorts.
- June 2026: Hoshino Resorts opened the 94 room KAI Kusatsu, including 18 rooms with private open air baths. Hoshino Resorts.
- July 2026: Hoshino Resorts opened the 54 room KAI Miyajima, including 30 rooms with private open air baths. Hoshino Resorts.
- September 2026: Four Seasons Hotels and Resorts launched a 9 day Japan itinerary covering Tokyo, Kyoto, and Osaka. Four Seasons Hotels and Resorts.
- January 2026: Accor announced the 38 room Lime Resort Myoko MGallery Collection for late 2026. Accor.
2025
- July 2025: Minor Hotels signed its first Anantara project in Japan, a 51 key retreat on a 10 acre Karuizawa site. Minor Hotels.
- July 2025: Hoshino Resorts announced the 187 room RISONARE Shimonoseki, its first RISONARE property in the Kyushu Yamaguchi area. Hoshino Resorts.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2026) | USD 46.20 Billion |
| Forecast Revenue (2035) | USD 102.02 Billion |
| CAGR (2026-2035) | 9.2% |
| Base Year for Estimation | 2026 |
| Historic Period | 2021-2025 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | Tour Type: Customized and Private Vacation, Culinary Travel and Shopping, Adventure and Safari, Cruise and Ship Expedition, Small Group Journey, Celebration and Special Event; Age Group: Millennial, Generation X, Baby Boomers, Silver Hair; Traveller Type: Aspiring Luxury, Absolute Luxury, Accessible Luxury; Region: Kanto, Kansai/Kinki, Central/Chubu, Kyushu Okinawa, Tohoku, Chugoku, Hokkaido, Shikoku |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Accor (Fairmont Tokyo), ANA Holdings Inc., JTB Corp., Luxury Escapes, Revigorate (APCS Lda), Four Seasons Hotels and Resorts, Nankai Electric Railway Co., Ltd., Unforgettable Travel, Sky Vacations, HIS Co., Ltd., InsideJapan Tours, Scott Dunn, Abercrombie & Kent, Oku Japan, Walk Japan, TUI Group, Butterfield & Robinson, GeoEx (Geographic Expeditions), Hoshino Resorts, Minor International |
| Customization Scope | Customization for segments, region / country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License | Multi-User License (Up to 5 Users) | Corporate Use License (Unlimited User and Printable PDF) |








