


Market Overview
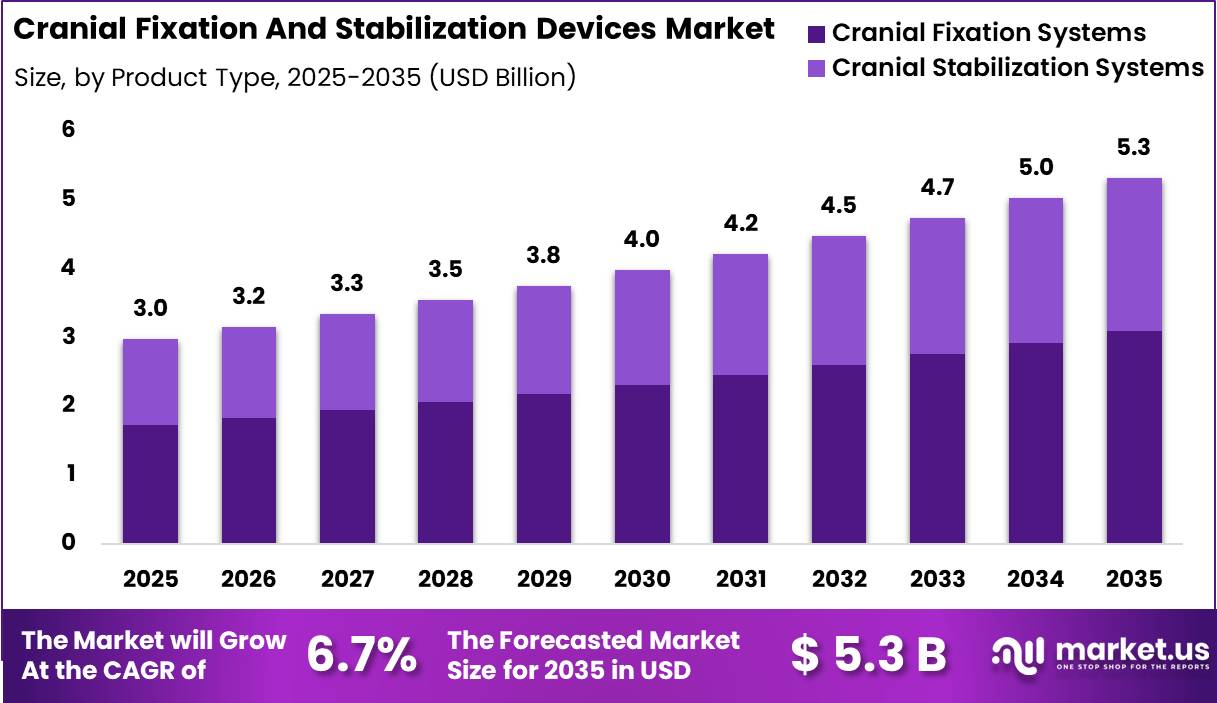
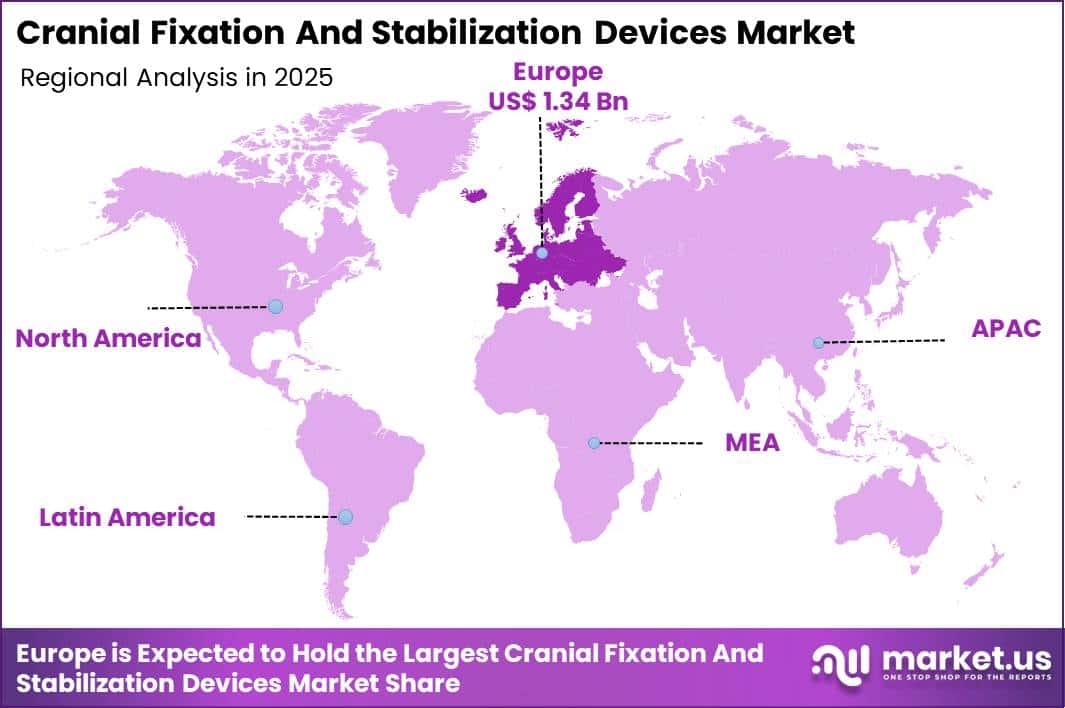
The Global Cranial Fixation and Stabilization Devices Market size is expected to be worth around US$ 5.33 Billion by 2035 from US$ 2.98 Billion in 2025, growing at a CAGR of 6.7% during the forecast period from 2026 to 2035. In 2025, Europe led the market, achieving over 45.23% share with a revenue of US$ 1.34 Billion.
Cranial fixation and stabilization devices are specialized medical implants and instruments used to secure bone flaps following neurosurgical procedures such as craniotomy, cranial reconstruction, and trauma-related skull surgeries.
These devices, including titanium plates, screws, clamps, meshes, and bioresorbable fixation systems, play a vital role in restoring skull integrity, protecting brain tissue, and supporting postoperative healing. Their adoption continues to expand as healthcare systems increase access to advanced neurosurgical care and improve surgical outcomes through technological innovation.
The growing burden of neurological disorders and traumatic brain injuries is a key factor supporting demand for cranial fixation and stabilization devices. According to the World Health Organization (WHO), neurological conditions are now among the leading causes of disability and illness worldwide, accounting for a substantial share of the global disease burden.
Meanwhile, the U.S. Centers for Disease Control and Prevention (CDC) reports that traumatic brain injury contributes to approximately 69,000 deaths annually in the United States, highlighting the ongoing need for effective neurosurgical interventions.
In addition, the World Federation of Neurosurgical Societies (WFNS) estimates that millions of neurosurgical procedures are performed each year globally, driven by brain tumors, cerebrovascular diseases, epilepsy, congenital abnormalities, and traumatic injuries.
Healthcare providers are increasingly adopting lightweight titanium fixation systems and bioresorbable implants that enhance biocompatibility, reduce postoperative complications, and improve patient recovery. Rising investments in hospital infrastructure, the expanding availability of image-guided neurosurgery, and increasing awareness of the importance of timely treatment for neurological conditions are further supporting the use of advanced cranial fixation and stabilization technologies.
Continuous product innovation, combined with growing demand for minimally invasive neurosurgical procedures, is expected to strengthen the long-term outlook for this medical device segment.
Key Takeaways
- Market Size: Cranial Fixation And Stabilization Devices Market size was US$ 2.98 billion in 2025.The market is projected to reach US$ 5.33 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 6.7%.
- By Product Type: Cranial Fixation Systems has the largest market share, accounting for 58.16% of total sales.
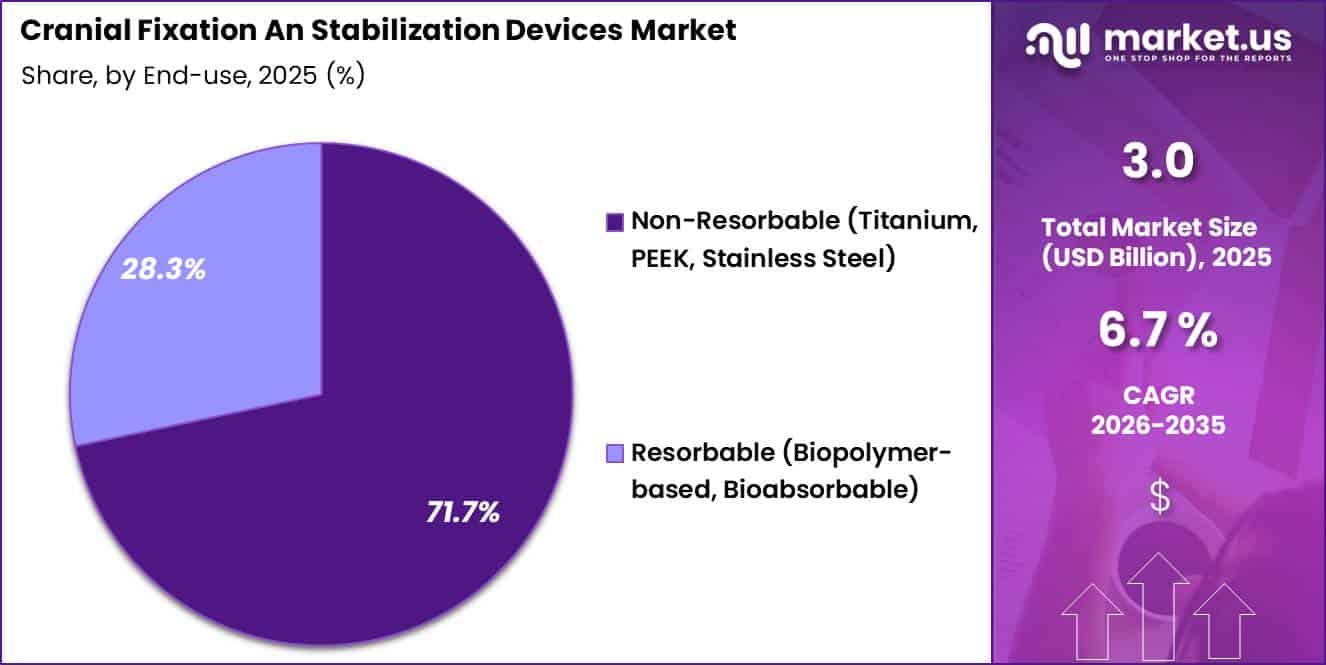
- By Material Type: Non-Resorbable (Titanium, PEEK, Stainless Steel), accounting for 71.72% of total revenue.
- By End User Process: Hospitals lead the segment, accounting for 67.75% of total revenue.
- By Distribution Channel: Direct Sales / Hospital Tenders leads the segment, accounting for 52.50% of total revenue.
- Regional: Europe is the dominant regional market, accounting for 45.23% of global sales.
By Product Type / Category Analysis
The Cranial Fixation Systems segment dominated the global Cranial Fixation and Stabilization Devices market, accounting for 58.16% of the market share in 2025. This leadership is driven by the widespread use of fixation plates, screws, meshes, and clamps in neurosurgical procedures requiring secure bone flap fixation following craniotomies.
These systems provide long-term mechanical stability, facilitate accurate bone alignment, and reduce postoperative complications, making them indispensable in trauma management, tumor resections, and reconstructive surgeries. Increasing volumes of complex neurosurgical procedures, coupled with growing adoption of patient-specific fixation solutions, continue to strengthen segment demand.
Technological advancements, including low-profile titanium plates and imaging-compatible fixation devices, have further improved surgical precision and patient outcomes. Meanwhile, the Cranial Stabilization Systems segment represented 41.84% of the market in 2025.
These systems are extensively utilized during neurosurgical operations to immobilize the patient’s head and maintain precise positioning throughout procedures. Rising demand for minimally invasive brain surgeries, advanced navigation-assisted operations, and robotic neurosurgery is supporting segment growth.
Continuous innovation in lightweight stabilization frames, improved ergonomic designs, and enhanced compatibility with imaging systems is expected to sustain demand across hospitals and specialized neurosurgical centers during the forecast period.
Material Type Analysis
The Non-Resorbable (Titanium, PEEK, Stainless Steel) segment held the largest share of the Cranial Fixation and Stabilization Devices market, capturing 71.72% of the market in 2025. The dominance of this segment is attributed to the exceptional mechanical strength, long-term stability, and proven clinical performance of these materials in cranial reconstruction and fixation procedures.
Titanium remains the preferred material due to its superior biocompatibility, corrosion resistance, and compatibility with advanced imaging technologies, while PEEK has gained traction for its radiolucency and bone-like mechanical properties.
Stainless steel continues to be used in selected cost-sensitive applications. These materials are particularly suitable for complex cranial trauma, tumor surgeries, and permanent fixation requirements. In contrast, the Resorbable (Biopolymer-based, Bioabsorbable) segment accounted for 20.00% of the market in 2025.
Demand for bioabsorbable fixation devices is increasing, particularly in pediatric neurosurgery, where eliminating the need for implant removal offers significant clinical advantages.
Ongoing research into advanced biodegradable polymers, improved strength retention, and enhanced healing characteristics is expected to support broader adoption of resorbable materials in specialized cranial procedures over the coming years.
End User Analysis
The Hospitals segment dominated the global Cranial Fixation and Stabilization Devices market, accounting for 67.75% of the market share in 2025. Hospitals remain the primary end users due to their comprehensive neurosurgical infrastructure, availability of advanced operating rooms, and access to multidisciplinary surgical teams capable of performing complex cranial procedures.
High patient admissions for traumatic brain injuries, brain tumors, congenital cranial abnormalities, and emergency neurosurgical interventions continue to drive demand within hospital settings. Large hospitals also invest in advanced surgical navigation systems, robotic-assisted technologies, and premium fixation devices that improve procedural accuracy and patient outcomes.
Furthermore, favorable reimbursement structures and increasing government investments in tertiary healthcare facilities contribute to sustained market leadership. The remaining market is supported by specialty neurosurgical centers, ambulatory surgical centers, and academic medical institutions that perform selected cranial procedures requiring specialized fixation and stabilization systems.
Growing demand for minimally invasive neurosurgery and expanding access to specialized neurological care are expected to support gradual growth across these alternative healthcare settings throughout the forecast period.
Distribution Channel Analysis
The Direct Sales / Hospital Tenders segment held the largest share of the Cranial Fixation and Stabilization Devices market, accounting for 52.50% of the market in 2025. This distribution channel dominates because manufacturers frequently establish direct relationships with hospitals, healthcare networks, and government procurement agencies to supply high-value neurosurgical devices.
Direct procurement enables healthcare providers to negotiate pricing, ensure consistent product availability, receive technical support, and access specialized training for surgeons. Large hospital systems also prefer long-term supply agreements that improve procurement efficiency while maintaining regulatory compliance and product quality.
Manufacturers benefit from direct engagement by strengthening customer relationships and introducing advanced product portfolios more effectively. Other distribution channels, including medical device distributors, specialty dealers, and regional supply partners, continue to play an important role in expanding market access, particularly in emerging economies and smaller healthcare facilities where direct manufacturer presence is limited.
The growing digitalization of procurement processes, increasing emphasis on value-based purchasing, and expansion of healthcare infrastructure are expected to enhance distribution efficiency and support sustained market growth during the forecast period.
Market Segmentations
By Product Type / Category
- Cranial Fixation Systems
- Screws
- Plates
- Meshes
- Flap Tube Clamps
- Cranial Stabilization Systems
- Skull Clamps
- Horseshoe Headrests
- Accessories (Adaptors, Arms, Base Units)
By Material Type
- Non-Resorbable (Titanium, PEEK, Stainless Steel)
- Resorbable (Biopolymer-based, Bioabsorbable)
By End User
- Hospitals
- Ambulatory Surgical Centers (ASCs)
- Specialty Clinics & Neurosurgery Centers
By Distribution Channel
- Direct Sales / Hospital Tenders
- Medical Distributors
- Online / E-commerce Platform
Driver
Trauma-Driven Cranial Case Expansion from Falls and Road Injuries
Traumatic brain injury remains a large structural demand engine for cranial access, decompression, and reconstruction workflows because moderate and severe head trauma often converts directly into burr-hole, craniotomy, or decompressive procedures that require plates, screws, clamps, or flap fixation systems.
CDC continues to classify TBI as a major cause of death and disability in the U.S., while global burden analysis published in 2025 estimated about 20.8 million head-injury cases worldwide in 2021, with 56.63% classified as moderate or severe; the same work identified falls and road traffic accidents among the leading causes, which matters because these etiologies disproportionately generate surgically actionable skull injury and intracranial pressure cases.
For device makers, this driver improves volume visibility more than pricing power because even if each fixation set remains a relatively small share of total neurosurgical case spend, higher trauma throughput lifts pull-through demand for standard titanium fixation kits, emergency inventory, and single-use sterile packs.
The strongest effect is in North America and dense APAC trauma corridors, where emergency neurosurgical referral systems are expanding, and the near-term CAGR lift is meaningful because trauma incidence feeds utilization immediately rather than waiting for long-cycle technology conversion.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Trauma-led cranial case expansion from falls and road-injury burden | +1.9% | North America core, EU, APAC urban corridors, Latin America spill-over | Short term (≤ 2 years) |
| Brain tumor and complex cranial oncology surgery intensity | +1.5% | North America core, Western Europe, Japan, South Korea, China tier-1 centers | Medium term (2-4 years) |
| Hospital shift toward low-profile titanium and resorbable fixation platforms | +1.3% | U.S., EU, Japan, GCC tertiary hospitals, private APAC neurosurgery hubs | Medium term (2-4 years) |
| Regulatory formalization and evidence-heavy neurology device pathways | +0.8% | U.S. core, EU notified-body markets, developed APAC | Medium term (2-4 years) |
| Aging population and high-acuity fall-driven neurosurgical utilization | +1.2% | U.S., EU-5, Japan, South Korea, urban China | Long term (≥ 4 years) |
| Reimbursement and hospital economics favoring procedural continuity | +0.9% | U.S. core, select OECD systems with DRG/procedure-linked payments | Short term (≤ 2 years) |
Challenge
Neurosurgeon Workforce Gap Limiting Cranial Device Adoption
Global access to cranial fixation and stabilization devices is constrained by structural neurosurgical workforce deficits, with approximately 72,967 neurosurgeons worldwide and a pooled density of 0.93 per 100,000 people, while many low- and lower-middle-income countries operate at or below 0.3 neurosurgeons per 100,000 against a functional need closer to 1.5–2.0 per 100,000 for timely cranial trauma and tumor care.
This gap translates into an estimated shortfall of 20,000–25,000 neurosurgeons globally, with Africa and Southeast Asia accounting for nearly 40% of the deficit, producing measurable throughput friction: in high-burden regions, annual demand of 300–500 cranial procedures per million population is often met at only 50–60% of required capacity, effectively capping device utilization growth by 1.0–1.5 % points below potential CAGR.
Operationally, average surgical wait times for urgent cranial cases can stretch from recommended windows of 24–72 hours to 7–10 days in constrained systems, and some tertiary centers report operating room utilization rates for neurosurgery stuck at 55–60% due to staffing bottlenecks rather than equipment availability, dampening unit-volume ramp-up even when the capital stock of fixation systems is adequate.
Strategically, manufacturers must plan for long-horizon mitigation through co-investment in training programs, tele-mentoring platforms that can compress decision times by 20–30%, and modular fixation kits tailored to mid-volume centers, while health systems embed neurosurgery into National Surgical, Obstetric, and Anesthesia Plans to raise workforce density by at least 0.3–0.4 neurosurgeons per 100,000 over 5–8 years, which gradually unlocks the latent device demand suppressed by workforce scarcity.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Neurosurgeon workforce gap | -1.3% | Africa, South Asia, LatAm public | Long term (≥ 4 years) |
| OR infrastructure variability | -0.8% | UpMIC/LoMIC hospitals, rural hubs | Medium term (2-4 years) |
| Multi-path regulatory complexity | -0.9% | U.S. FDA, EU MDR, Asia approvals | Medium term (2-4 years) |
| Implant cost-pressure misalignment | -1.0% | North America, EU payers, and emerging | Long term (≥ 4 years) |
| Supply chain sterilization/logistics | -0.7% | Global neurosurgical centers | Short term (≤ 2 years) |
| Data, traceability & safety reporting | -0.6% | OECD hospitals, large IDNs | Medium term (2-4 years) |
Restraints
Neurosurgical Supply Chain Shortages Disrupting Cranial Device Availability
Acute neurosurgical supply chain disruptions in 2025–2026, especially in consumables and sterile components critical to cranial procedures, are producing short-term friction that shaves an estimated 1.5 % points off market CAGR for cranial fixation and stabilization devices in 2026–2028.
The FDA has added neurosurgical patties, sponges, and strips to its Medical Device Shortages List, with regulators explicitly warning that manufacturing interruptions could destabilize neurosurgical scheduling across U.S. hospitals through at least Q4 2026, amplifying operating room underutilization and deferral of elective cranial cases where fixation hardware is used.
At the same time, OEMs supplying plates, screws, and skull clamps face intermittent raw-material bottlenecks, including titanium, specialty stainless steel, and polymer resins, with lead times stretching from 8–10 weeks to 14–18 weeks, and sterilization capacity constraints in contract facilities that can add another 4–6 weeks, converting what used to be a 3-month end-to-end supply cycle into a 5- to 6-month pipeline.
These delays force hospitals to increase safety stock by 20–30% at higher carrying costs or accept stockouts that directly translate into rescheduled or downgraded procedures, such as switching to more generic fixation systems or bundled cranio-spinal sets, eroding high-margin cranial implant utilization.
OEMs, for their part, are absorbing premium freight surcharges that can raise logistics costs per tray by US$10–25 and implementing overtime shifts in machining and cleanroom operations that lift cost of goods sold by 3–5%, yet they cannot fully pass this through to price in environments where group purchasing organizations (GPOs) cap annual price escalators at 3–4%.
The strategic outcome is short-term volume loss, rising backorders of often 5–8% of line items in neurosurgical catalogs, and eroded service levels, with procurement teams favoring vendors with diversified manufacturing footprints and dual-sourced components, thus penalizing niche cranial fixation specialists and dampening their growth trajectory across North America, the EU, and select APAC corridors.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Dual FDA–EU MDR regulatory drag | -1.8% | US, EU core | Medium term |
| Neurosurgical supply chain shortages | -1.5% | North America, EU, select APAC | Short term |
| Procedural volume & reimbursement pressure | -1.3% | US, EU, Japan | Medium term |
| Product recalls & post-market scrutiny | -0.9% | US, EU, global tier-1 centers | Medium term |
| Input cost inflation & OEM margin compression | -1.1% | Global, esp. US/EU importers | Short to medium term |
| Hospital CapEx deferral & procurement tightening | -1.0% | US, EU, Middle East | Medium to long term |
Opportunity
Digital Navigation Integrated Fixation Creating New Revenue Opportunities
Digital navigation integrated fixation represents the convergence of cranial fixation hardware with neuronavigation and intraoperative imaging platforms, a domain where neurosurgery markets are forecast to grow at around 5–6% through 2033, but where fixation OEMs have only limited direct monetization today.
High-income countries currently operate roughly 14 operating rooms per 100,000 population, with a substantial share undertaking cranial procedures supported by navigation systems, yet fixation devices are still sold as standalone hardware, leaving untapped value in integrated planning, guided drilling trajectories, and digital intraoperative documentation.
By embedding proprietary fixation planning modules, drill path templates, and post-op construct analytics into navigation software, priced for example as $75–$100 per procedure software fees or $15,000–$30,000 per OR annual licenses, OEMs can create recurring revenue layers that lift per-case economics by 10–20% without materially increasing hardware cost.
Assuming that by 2030, 40–50% of cranial cases in North America, Europe, and China routinely use navigation, a 30–40% attachment rate for integrated fixation modules could unlock $500–700 million of high-margin software-plus-service revenue, with EBIT margins potentially 10–15 % points higher than pure hardware, translating into 1.6 % points of incremental CAGR above today’s fixation forecasts.
This is a genuine opportunity rather than a driver because current market projections treat navigation and fixation as separate product lines; strategic co-development, data-sharing alliances with platform vendors, and bundled procedural contracting can create a new, digital-enabled cranial fixation category whose upside is not yet reflected in baseline growth expectations.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| LMIC neurotrauma access platforms | +1.8% | APAC, Latin America, Africa | Medium term (2-4 years) |
| Geriatric cranial fragility portfolios | +1.4% | North America, EU, Japan | Medium term (2-4 years) |
| Digital navigation–integrated fixation | +1.6% | North America core, EU, China | Short term (≤ 2 years) |
| Patient-specific 3D-printed cranial systems | +1.3% | North America, EU, GCC | Long term (≥ 4 years) |
| Value-based neuro bundles & risk sharing | +1.2% | North America, EU | Medium term (2-4 years) |
| Trauma-network M&A roll-up and OEMization | +1.5% | Global, especially APAC & LATAM | Long term (≥ 4 years) |
Regional Analysis
In 2025, Europe led the market, achieving over 45.23% share with a revenue of US$1.34 billion.
In 2025, Europe region’s leadership is supported by its advanced neurosurgical infrastructure, high adoption of innovative cranial fixation technologies, and a strong presence of leading medical device manufacturers. Countries such as Germany, France, the United Kingdom, and Italy continue to invest heavily in specialized neurological care, trauma treatment, and minimally invasive surgical procedures.
The growing incidence of traumatic brain injuries, brain tumors, and age-related neurological disorders has further increased the demand for reliable cranial fixation and stabilization devices across hospitals and specialized surgical centers. Favorable reimbursement systems, extensive research activities, and continuous product innovation also contribute to market expansion throughout Europe.
North America represents the second-largest regional market, driven by advanced healthcare facilities, increasing neurosurgical procedures, and widespread adoption of premium fixation systems.
The Asia-Pacific region is projected to witness the fastest growth during the forecast period due to expanding healthcare infrastructure, rising healthcare expenditure, increasing awareness of advanced neurosurgical treatments, and growing patient populations in countries such as China, India, and Japan.
Latin America is experiencing gradual market development through improving access to specialized healthcare services, while the Middle East and Africa are expected to register steady growth, supported by ongoing healthcare modernization, investments in hospital infrastructure, and increasing availability of advanced neurosurgical equipment.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The Cranial Fixation and Stabilization Devices Market is characterized by the presence of established global medical device manufacturers alongside specialized cranio-maxillofacial companies. Large companies leverage broad neurosurgical portfolios, international distribution networks, and established relationships with hospitals, while smaller manufacturers focus on specialized product offerings, regional expansion, and customized surgical solutions.
Competition is driven primarily by product performance, clinical reliability, regulatory compliance, and surgeon preference. Companies seek to strengthen their positions through continuous product development, expansion of manufacturing capabilities, collaborations with healthcare institutions, and geographic expansion. Rather than competing solely on price, manufacturers emphasize quality, procedural efficiency, and long-term clinical outcomes.
Innovation remains a key competitive priority. Companies are developing low-profile fixation plates, advanced titanium and PEEK-based implants, improved cranial stabilization systems, and precision surgical instruments designed to simplify neurosurgical procedures.
Many manufacturers also invest in digital surgical planning, patient-specific implant technologies, and workflow integration to support surgical accuracy and efficiency. In addition, comprehensive product portfolios that combine implants, fixation systems, instrumentation, and clinical training enable companies to build stronger relationships with healthcare providers and improve adoption across neurosurgical centers.
Top Key Players
- Medtronic PLC
- Stryker Corporation
- Johnson & Johnson (DePuy Synthes)
- Integra LifeSciences Holdings Corp.
- B. Braun Melsungen AG (Aesculap)
- Zimmer Biomet Holdings Inc.
- KLS Martin Group
- OsteoMed LLC
- Pro Med Instruments GmbH
- Evonos GmbH
- NEOS Surgery S.L.
- Medartis AG
- Adeor Medical AG
- Jeil Medical Corporation
- Changzhou Huida Medical Instrument
Recent Developments
- In July 2025, Zimmer Biomet Holdings Inc. announced a definitive agreement to acquire Monogram Technologies, expanding its robotics and navigation capabilities to enhance orthopedic and image-guided surgical technologies, supporting future innovation across surgical specialties.
- In September 2025, B. Braun Melsungen AG (Aesculap) acquired True Digital Surgery (TDS), strengthening its digital neurosurgery portfolio and accelerating development of the AEOS® digital surgical microscope platform used in neurosurgery, spine, and ENT procedures.
- In November 2025, KLS Martin Group received U.S. FDA 510(k) clearance for its MR Conditional Cranial Implants, expanding its patient-specific cranial reconstruction portfolio compatible with MRI environments.
- In February 2026, Medtronic PLC received U.S. FDA clearance for the Stealth AXiS™ Surgical System, an integrated planning, navigation, and robotics platform. While initially cleared for spine surgery, the platform was designed to support future cranial and ENT applications, reinforcing Medtronic’s neurosurgical technology roadmap.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 2.98 Billion |
| Forecast Revenue (2035) | US$ 5.33 Bllion |
| CAGR (2026-2035) | 6.7 % |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type / Category(Cranial Fixation Systems(Screws, Plates, Meshes, Flap Tube Clamps)Cranial Stabilization Systems(Skull Clamps, Horseshoe Headrests, Accessories (Adaptors, Arms, Base Units))By Material Type (Non-Resorbable (Titanium, PEEK, Stainless Steel), Resorbable (Biopolymer-based, Bioabsorbable)) By End User (Hospitals, Ambulatory Surgical Centers (ASCs), Specialty Clinics & Neurosurgery Centers)By Distribution Channel (Direct Sales / Hospital Tenders, Medical Distributors, Online / E-commerce Platform)) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Medtronic PLC, Stryker Corporation, Johnson & Johnson (DePuy Synthes) , Integra LifeSciences Holdings Corp., B. Braun Melsungen AG (Aesculap) , Zimmer Biomet Holdings Inc. ,KLS Martin Group, OsteoMed LLC,Pro Med Instruments GmbH, Evonos GmbH, NEOS Surgery S.L., Medartis AG , Adeor Medical AG,Jeil Medical Corporation, Changzhou Huida Medical Instrument |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








