


Report Overview
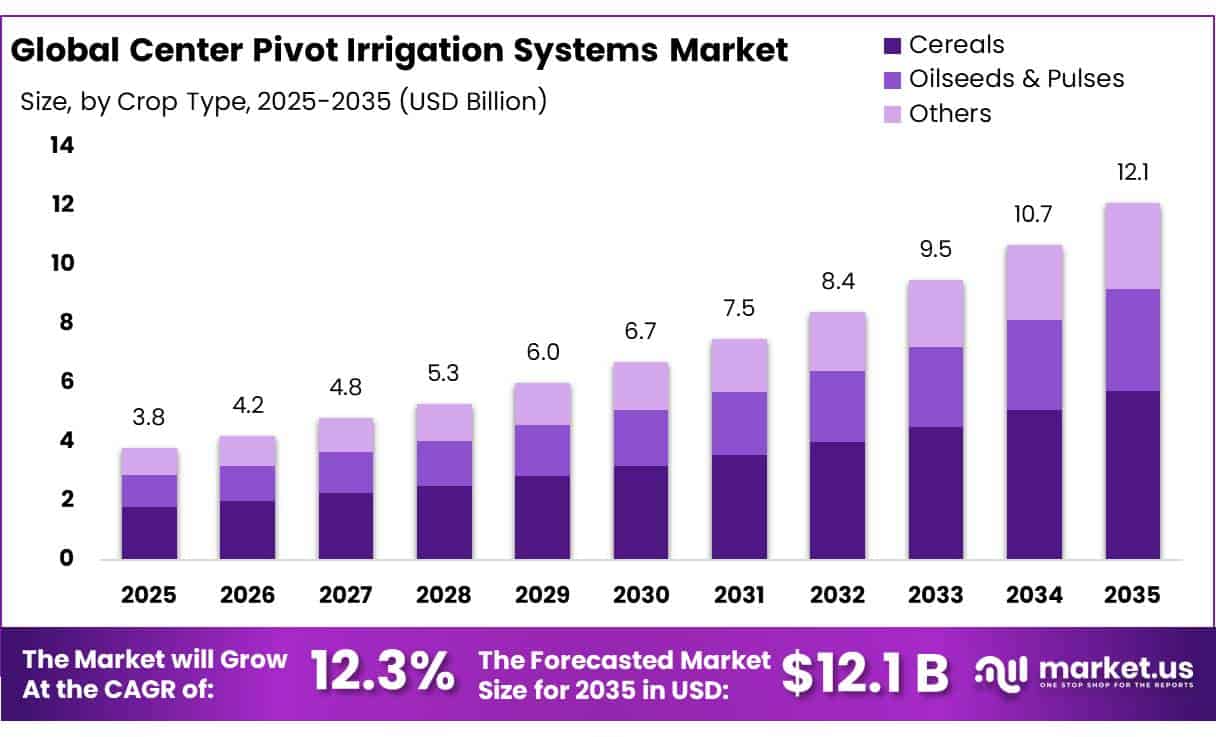
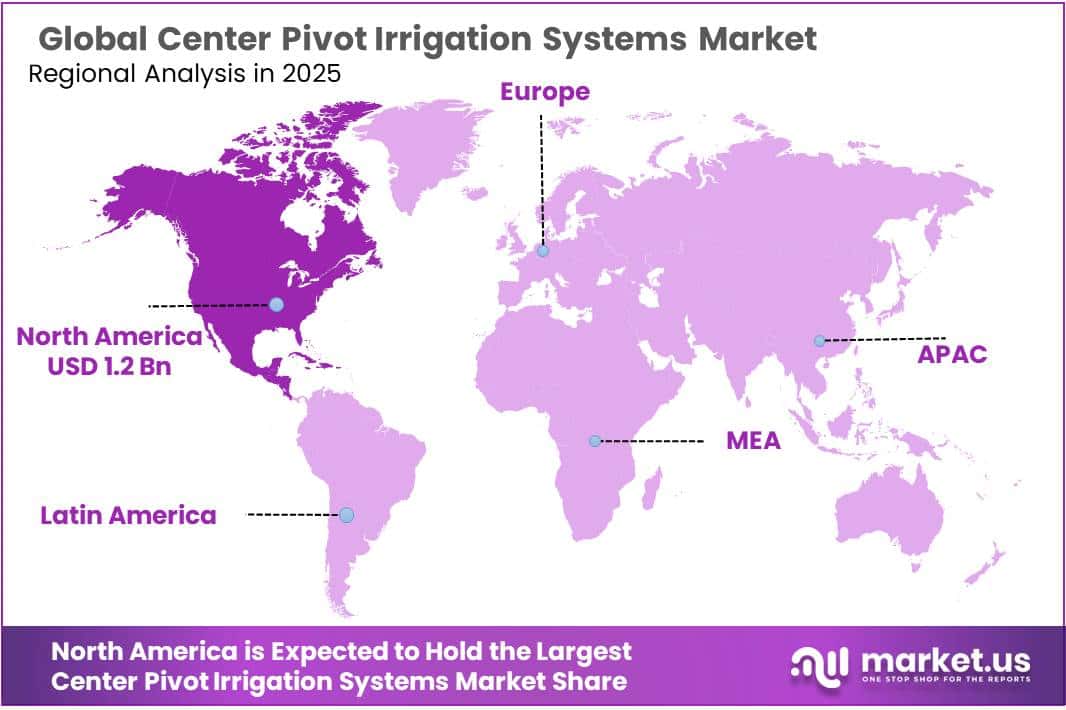
The Global Center Pivot Irrigation Systems Market size is expected to be worth around USD 12.1 Billion by 2035, from USD 3.8 Billion in 2025, growing at a CAGR of 12.3% during the forecast period from 2026 to 2035. In 2025, North America held a dominant market position, capturing more than a 32.34% share, holding USD 1.2 Billion revenue.
Center pivot irrigation systems have become an important part of mechanized agriculture, particularly across large farms growing cereals, grains, oilseeds, forage crops, and other field crops. The system rotates around a fixed central point and distributes water through sprinklers positioned along a long pipeline. The U.S. Geological Survey (USGS) notes that a typical center-pivot unit is around 1,250–1,300 feet long and can irrigate approximately 130 acres, making the technology suitable for large and relatively uniform fields.
- The Food and Agriculture Organization (FAO) reports that agriculture accounts for approximately 72% of global freshwater withdrawals, while about 1.2 billion people live in agricultural areas facing severe water constraints. FAO further estimates that agriculture will need to produce 50% more food, feed and fibre by 2050 compared with 2012 levels. These conditions are encouraging farmers to adopt irrigation systems that provide more controlled and consistent water application.
North America represents a well-established operating base for center-pivot technology. Updated USGS information shows that crop irrigation across the lower 48 U.S. states withdrew approximately 110,904 million gallons per day in 2020. Groundwater supplied around 70,434 million gallons per day, or 63.5%, while surface water contributed 40,470 million gallons per day, or 36.5%. Around 72% of irrigation withdrawals were estimated as consumptive use. These figures highlight the need for equipment capable of managing water more carefully, particularly in groundwater-dependent farming regions.
- Center pivots are also well established within pressure-based irrigation infrastructure. USDA Economic Research Service data show that pressure-sprinkler systems, including center pivots and other pressurized technologies, are used across 72% of irrigated acres nationally and 77% of irrigated acres in Western states. Around 50.4% of U.S. irrigated acreage uses irrigation systems classified as higher efficiency.
Future growth opportunities are increasingly linked with low-pressure sprinklers, variable-rate irrigation, soil-moisture monitoring, weather-based scheduling, remote controls, telemetry and automated pump management. USGS explains that low-pressure sprinkler configurations reduce losses because less water evaporates or is carried away by wind compared with high-pressure spraying.
Key Takeaways
- Center Pivot Irrigation Systems Market size is expected to be worth around USD 12.1 Billion by 2035, from USD 3.8 Billion in 2025, growing at a CAGR of 12.3%.
- Span held a dominant market position, capturing more than a 29.78% share.
- Cereals held a dominant market position, capturing more than a 47.45% share.
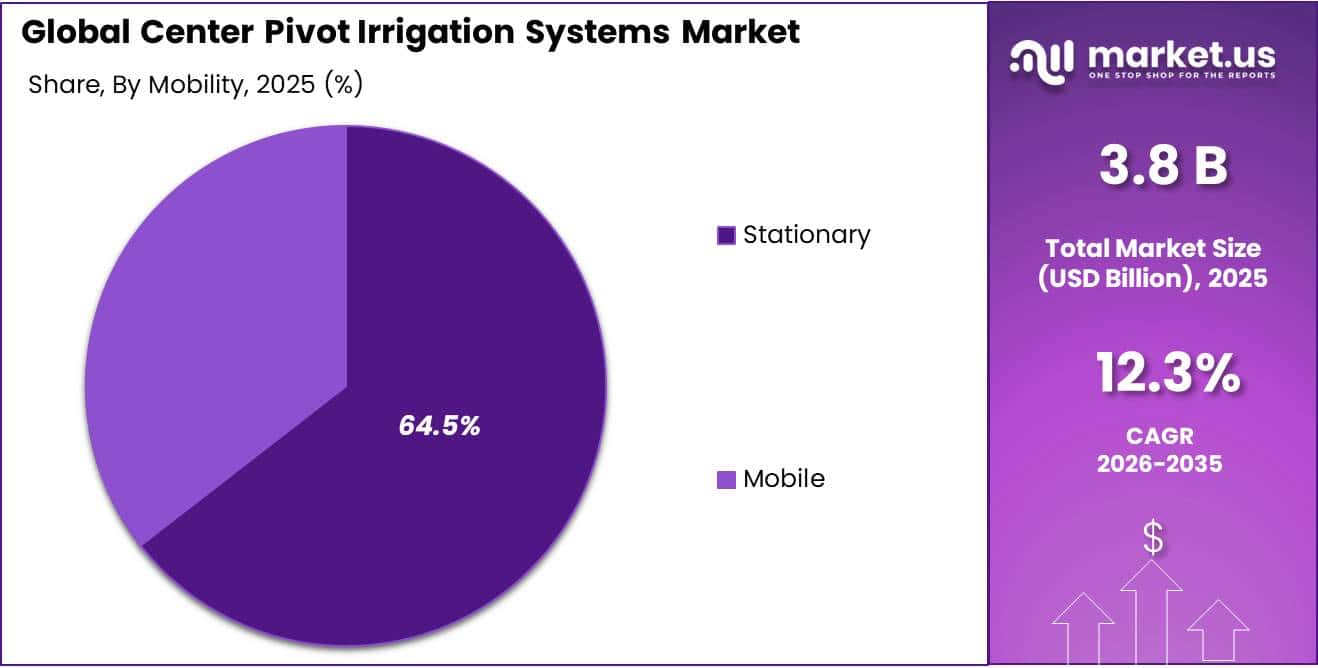
- Stationary held a dominant market position, capturing more than a 64.56% share.
- North America held a dominant position in the Center Pivot Irrigation Systems Market, capturing more than a 32.34% share and reaching USD 1.2 billion.
By Component Analysis
Span dominates Center Pivot Irrigation Systems with a 29.78% share as large fields require wider and durable water-distribution structures
In 2025, “Span” held a dominant market position, capturing more than a 29.78% share. The span remains a core structural component because it carries the irrigation pipeline across the field and connects multiple support towers, allowing water to be distributed over a wide circular area. Its importance increases on large commercial farms where longer and stronger structures are needed for reliable irrigation.
According to the U.S. Geological Survey, a typical center-pivot irrigation unit is approximately 1,250 to 1,300 feet long and can irrigate around 130 acres. The agency explains that the pipeline is supported above crops by towers positioned at fixed spacing and moved through a circular path. These operating requirements create steady demand for durable spans capable of supporting pipes, sprinklers, electrical systems, and moving equipment over large agricultural areas.
Government support also demonstrates the economic importance of center-pivot structures. Under USDA NRCS Agricultural Management Assistance rates for fiscal 2025 in Utah, a standard center-pivot sprinkler system was assigned a payment scenario cost of US$68.23 per foot, while a center pivot covering 101 acres or more was listed at US$739.17 per acre. These figures underline the substantial equipment investment associated with large center-pivot installations and support continued demand for span structures during new installation and system replacement.
Control Panels represent an increasingly important component of Center Pivot Irrigation Systems as farms adopt automated controls, variable-rate irrigation, sensors, GPS positioning, and remote water management. Modern panels allow operators to control pivot movement, irrigation timing, application rates, and field-specific watering programs from a central interface. This reduces manual intervention and gives growers greater control over water application across fields with different soil and crop conditions.
By Crop Type Analysis
Cereals dominate Center Pivot Irrigation Systems with a 47.45% share, supported by extensive corn and wheat cultivation
In 2025, “Cereals” held a dominant market position, capturing more than a 47.45% share. Cereals remain a major application for center pivot irrigation because crops such as corn, wheat, sorghum, barley, and oats are commonly grown across large fields where mechanized water application is practical. Center pivots help growers maintain more uniform watering while reducing labor requirements and improving control over irrigation schedules.
Government statistics demonstrate the large cultivation base supporting this segment. In June 2025, the U.S. Department of Agriculture estimated that farmers planted 95.2 million acres of corn, while 86.8 million acres were expected to be harvested for grain. Wheat covered another 45.5 million planted acres, including 33.3 million acres of winter wheat and 10.0 million acres of other spring wheat. By 2026, USDA reported that corn alone accounted for more than 95% of U.S. feed-grain production and use. This extensive cereal acreage creates a broad operating base for center pivots, particularly where growers need repeatable water application across large commercial fields.
Oilseeds & Pulses represent an important crop segment for Center Pivot Irrigation Systems, particularly across soybean, dry bean, peanut, canola, and other broad-acre production areas. These crops can benefit from controlled irrigation during flowering, pod development, and grain filling, making center pivots useful where rainfall is inconsistent. Their suitability for large mechanized farms also allows irrigation equipment to cover substantial areas without requiring intensive manual operation.
By Mobility Analysis
Stationary systems dominate Center Pivot Irrigation with a 64.56% share as permanent installations support large-scale irrigated farming
In 2025, “Stationary” held a dominant market position, capturing more than a 64.56% share. Stationary center pivots remain widely used because their fixed central point supports consistent irrigation over large circular fields and allows farmers to connect pumps, pipelines, sprinklers, sensors, and automated controls within one permanent system. This arrangement is particularly practical for commercial farms growing corn, wheat, soybeans, and forage crops over repeated production seasons.
Government data underline the large irrigation base supporting stationary systems. The U.S. Geological Survey reports that crop irrigation across the lower 48 states withdrew about 110,904 million gallons of water per day in 2020, with groundwater supplying 70,434 million gallons per day and surface water providing 40,470 million gallons per day.
USDA Economic Research Service data also show that pressure-sprinkler technologies, including center pivots, are used on 72% of irrigated acres nationwide and 77% of irrigated acres across Western states. This established infrastructure favors permanent center-pivot installations where farmers require dependable irrigation across the same fields year after year.
Mobile center pivots represent a flexible part of the Center Pivot Irrigation Systems Market, particularly for farms seeking to move irrigation equipment between fields rather than installing a dedicated pivot on every parcel. Towable configurations can help growers extend equipment utilization across smaller or separated fields, while reducing the requirement for multiple complete irrigation structures.
Key Market Segments
By Component
- Pivot Points
- Control Panels
- Span
- Sprinkler Drop
- Tower Drive Wheels
- Drive Train
- Others
By Crop Type
- Oilseeds & Pulses
- Cereals
- Others
By Mobility
- Stationary
- Mobile
Driver Analysis
Drought-Driven Water Efficiency
A conventional center pivot operating across a 130-acre quarter-section typically requires 7–10 towers, 1,300–1,700 feet of pipeline, 30–150 psi operating pressure, and 40–250 horsepower pumping depending on lift and flow; converting from gravity or inefficient sprinkler systems can reduce applied-water losses by an analyst-estimated 15–35%, while adding low-pressure sprinklers, pressure regulators, end-gun controls, and variable-rate packages can provide a further 5–15% reduction where soil, crop, and terrain variability are material.
For a 130-acre field using 1.0–2.5 acre-feet per acre annually, a 15% saving represents roughly 20–49 million gallons, and at USD 15–80 per acre-foot in pumping, delivery, water-right, or energy-equivalent cost, this can protect USD 300–3,900 annually before yield stabilization; where drought limits acreage, the higher value is preserving irrigation across 10–30 additional acres.
This changes supplier economics from one-time pivot sales to bundled hydraulics, water audits, pressure management, scheduling software, and remote service, with recurring digital and maintenance revenue potentially reaching 5–12% of initial equipment value annually. Drought-related efficiency investment is estimated to add +2.1 percentage points to center-pivot CAGR across the U.S. Plains and West, southern Europe, Australia, MENA, South Africa, and water-stressed Latin American regions over two to four years.
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Drought-driven water efficiency | +2.1 pp | U.S. Plains, Southern EU, MENA, Australia | Medium term (2–4 years) |
| Precision irrigation digitization | +1.7 pp | North America, EU, Brazil, Australia, China | Medium term (2–4 years) |
| U.S. conservation incentives | +1.5 pp | U.S. Plains, West, Midwest | Short term (≤ 2 years) |
| High-value crop conversion | +1.3 pp | Brazil, U.S., Spain, Mexico, MENA | Long term (≥ 4 years) |
| Energy-efficient pumping upgrades | +1.1 pp | North America, EU, India, Australia, South Africa | Medium term (2–4 years) |
| Water-resilience investment | +0.9 pp | EU, MENA, Africa, LATAM, Asia | Long term (≥ 4 years) |
Restraint Analysis
Upfront System-Capex Burden
A 130-acre quarter-section pivot typically requires 7–10 towers, 1,300–1,700 feet of span and overhang, a 40–250 horsepower pump, 30–150 psi operating pressure, and USD 80,000–250,000 for a conventional system; deep groundwater, grid extension, diesel generation, rocky soils, high lift, filtration, corner systems, remote controls, and variable-rate packages can raise total outlay to USD 250,000–500,000. For a grower financing USD 200,000 over seven years at 8–12%, annual debt service is approximately USD 38,000–43,000 before electricity, maintenance, labour, land rent, fertilizer, and crop-risk costs, requiring USD 290–330 per irrigated acre annually on a 130-acre field simply to service capital.
Conservation incentives do not eliminate this hurdle: FY2026 NRCS guidance specifies that EQIP financial assistance cannot be provided solely for installation of a center pivot, requires irrigation-related conservation practices to generate at least 10% modeled water savings, and generally requires three to five years of Irrigation Water Management after structural practices. The rule improves project quality but increases planning, modeling, documentation, and service costs by an estimated USD 5,000–25,000 per funded project, while farmers unable to prove historical irrigation can be excluded.
Vendors face slower conversion, dealer-financing exposure, and margin pressure when competing with lower-cost drip, hose-reel, flood, or rain-fed alternatives; leasing, used-pivot refurbishment, modular systems, processor-backed loans, and water-performance contracts can mitigate the problem but do not change the debt capacity of low-margin farms. Capital intensity is estimated to deduct -1.9 percentage points from center-pivot market CAGR across North America, Brazil, India, Africa, MENA, and emerging commercial-farming regions over two to four years.
Restraint Impact Analysis
| Restraint | (~) % Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Upfront system-capex burden | -1.9 pp | North America, Brazil, Africa, India, MENA | Medium term (2–4 years) |
| Water-right curtailment risk | -1.6 pp | U.S. High Plains, Spain, Australia, MENA | Long term (≥ 4 years) |
| Power-grid and diesel costs | -1.3 pp | India, Africa, LATAM, Australia, U.S. groundwater belts | Medium term (2–4 years) |
| Fragmented smallholder parcels | -1.1 pp | India, Africa, ASEAN, LATAM | Long term (≥ 4 years) |
| Steel and component inflation | -0.9 pp | Global OEMs, import-dependent markets | Short term (≤ 2 years) |
| Terrain and field-shape limits | -0.8 pp | Europe, Asia, Africa, fragmented farmland | Long term (≥ 4 years) |
Opportunity Analysis
Irrigation-as-a-Service
A provider owning a USD 180,000 installed system on 130 acres could charge USD 180–350 per acre annually over a 7–10-year term, creating USD 23,400–45,500 in yearly recurring revenue and USD 164,000–455,000 of contracted lifetime revenue before renewal, while a 70–80% utilization rate across a portfolio of 100 pivots can support USD 2.3–4.6 million annual recurring revenue.
The model lowers a farmer’s initial cash payment by 70–100%, shortens the sales cycle for credit-constrained operators, and can improve vendor lifetime value by 2–4 times versus a one-time equipment sale; suppliers can retain USD 20–60 per acre of verified water, energy, and maintenance savings while protecting gross margin through standardized 80–160-acre designs, remote diagnostics, 24-hour service-level tiers, and shared spare-parts pools. U.S. EQIP is relevant but does not itself create the opportunity: it provides technical and financial assistance for conservation practices, including water conservation and drought mitigation, making an equipment-plus-management contract easier to position as a documented resource-improvement programme.
The key risk is credit and water entitlement—if a farm loses allocation or fails to plant, the asset still incurs depreciation—so contracts need minimum acreage, crop-insurance linkage, water-right representations, buyout provisions, and satellite-based verification. This unpenetrated financing model could add +2.0 percentage points to center-pivot CAGR in the U.S., Brazil, Australia, MENA, and South Africa within two years.
Opportunity Impact Analysis
| Opportunity | (~) % Potential CAGR | Geographic Relevance | Execution Window |
|---|---|---|---|
| Irrigation-as-a-service | +2.0 pp | U.S., Brazil, Australia, MENA, South Africa | Short term (≤ 2 years) |
| Solar-pivot energy bundles | +1.7 pp | India, Africa, LATAM, MENA, Australia | Medium term (2–4 years) |
| Water-data monetization | +1.5 pp | U.S. Plains, EU, Australia, Brazil | Medium term (2–4 years) |
| Compact pivot platforms | +1.3 pp | India, ASEAN, Africa, LATAM, Europe | Long term (≥ 4 years) |
| Water-credit performance contracts | +1.1 pp | EU, U.S. West, Australia, MENA | Medium term (2–4 years) |
| Dealer-service roll-ups | +0.9 pp | North America, Brazil, Australia, Africa | Long term (≥ 4 years) |
Challenges Analysis
Water-Allocation Data Gaps
A 130-acre pivot applying 1.0–2.5 acre-feet per acre uses roughly 130–325 acre-feet annually, equivalent to 42–106 million gallons; a 5–15% flow-meter error can misstate annual use by 6.5–48.8 acre-feet, enough to distort a water-saving claim, trigger compliance risk, or undermine water-credit financing. USDA’s July 2026 Irrigation Water Management standard requires an IWM plan defining irrigation timing, amount, and application rate, requires records for each event—including depth or volume, duration, and date—and recognizes data logging, remote sensing, advanced imaging, yield monitoring, and other technologies as tools for more efficient application.
The problem is that assembling this evidence can add USD 5,000–25,000 per site for flow meters, pressure sensors, data gateways, water-right review, historic baselines, calibration, and farm-management integration; a 10,000-acre dealer territory may therefore need 75–150 meters, 20–50 telemetry gateways, and 2–5 dedicated data or compliance specialists before it can offer auditable services. The commercial risk is delayed installation, lower confidence in performance contracts, lender reluctance, and a shift toward lower-cost systems that do not require formal data infrastructure. M
Manufacturers must embed calibrated meters, tamper alerts, offline data capture, API-based reporting, allocation dashboards, and independent verification, but fragmented water governance and inconsistent enforcement make normalization a four-plus-year task. Allocation-data gaps are estimated to impose a -1.4-percentage-point CAGR friction in the U.S. Plains, California, southern Europe, Australia, MENA, and regulated groundwater basins.
Challenges Impact Analysis
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Water-allocation data gaps | -1.4 pp | U.S. Plains, EU, Australia, MENA | Long term (≥ 4 years) |
| Variable-rate agronomy deficit | -1.2 pp | North America, Brazil, EU, Australia | Long term (≥ 4 years) |
| Remote-service talent shortage | -1.1 pp | North America, Brazil, Africa, Australia | Long term (≥ 4 years) |
| Pump-system interoperability | -1.0 pp | Global retrofit markets, India, LATAM | Medium term (2–4 years) |
| Climate-driven water volatility | -0.9 pp | MENA, Africa, Australia, EU, U.S. West | Long term (≥ 4 years) |
| Multi-party project coordination | -0.8 pp | Emerging markets, U.S., EU, LATAM | Medium term (2–4 years) |
Geopolitical Impact Analysis
Russia–Ukraine War Disrupts Irrigation Infrastructure While Creating Long-Term Demand for Center Pivot Systems
The ongoing Russia–Ukraine war continues to affect the Center Pivot Irrigation Systems market in 2026 by damaging agricultural land, irrigation networks, pumping facilities, energy infrastructure, and farm equipment. Frontline farmers face higher production costs, power interruptions, limited access to fields, and difficulties replacing irrigation machinery. FAO reported in 2026 that agricultural output in Ukraine’s Kherson region had fallen by more than 98% since the full-scale invasion, with destruction of irrigation systems, drought, and explosive ordnance preventing thousands of hectares from being cultivated.
The damage is also creating a major reconstruction requirement. The World Bank, European Commission, United Nations, and Ukrainian government estimated in February 2026 that Ukraine would require more than US$55 billion for agricultural reconstruction and recovery over the coming decade. FAO has already supported more than 300,000 rural families and nearly 17,000 small agrifood enterprises with assistance including irrigation systems, generators, seeds, and other agricultural inputs.
Regional Insights
North America Leads Center Pivot Irrigation Systems with 32.34% Share and USD 1.2 Billion Market Value
In 2025, North America held a dominant position in the Center Pivot Irrigation Systems Market, capturing more than a 32.34% share and reaching USD 1.2 billion. Large commercial farms, groundwater-dependent agriculture, and widespread mechanized irrigation support regional demand. USGS data show that U.S. crop irrigation withdrawals reached 110,904 million gallons per day, including 70,434 million gallons per day from groundwater. USDA data further indicate that pressure-sprinkler technologies, including center pivots, are used across 72% of U.S. irrigated acres. These conditions encourage investment in efficient pivots, low-pressure sprinklers, automated controls, and precision water-management equipment.
North America’s established irrigation infrastructure also creates opportunities for replacement and modernization rather than only new installations. USDA reports that 50.4% of total U.S. irrigated acreage uses irrigation systems classified as higher efficiency. Center pivots are particularly suitable for large cereal, oilseed, forage, and feed-crop farms because they can provide repeatable water application over broad areas. Rising pressure on groundwater resources is encouraging growers to adopt variable-rate irrigation, remote monitoring, soil-moisture sensors, GPS controls, and lower-pressure sprinkler packages. This technology shift supports equipment upgrades while helping farmers manage water and energy more carefully.
Key Regions and Countries Insights
- North America
- US
- Canada
- Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Key Players Analysis
Valmont Industries maintains a major presence in center pivot irrigation through its Valley Irrigation business, supplying center pivots, linear systems, replacement parts, and precision agriculture technologies. In fiscal 2025, Valmont generated US$4.10 billion in total sales, while its Agriculture segment recorded US$1.02 billion. Irrigation equipment and parts contributed US$919.9 million, while agricultural technology products and services generated US$94.5 million. North American Agriculture sales reached US$506.3 million, demonstrating the company’s substantial commercial position across mechanized and technology-enabled irrigation systems.
Lindsay Corporation serves the center pivot irrigation industry primarily through its Zimmatic systems and FieldNET digital irrigation technologies. In fiscal 2025, company revenue reached US$676.4 million, increasing 11% from the previous year. Its Irrigation segment generated US$568.0 million, representing 84% of company revenue. International irrigation revenue increased 39% to US$294.2 million, while North American irrigation revenue reached US$273.8 million. Lindsay’s center pivots can be designed for fields ranging from 25 to more than 600 acres, supporting different commercial farming requirements.
Reinke Manufacturing Company is a privately held irrigation equipment manufacturer focused on center pivot and lateral move systems. Founded in 1954, the company operates through hundreds of dealers across more than 40 countries. Reinke combines irrigation structures with GPS guidance, satellite communications, touchscreen controls, and precision water-management technologies. Its E3 platform extends this focus toward precision center pivot and lateral irrigation. The company’s ESAC electronic swing-arm corner technology uses GPS-guided zone control and can provide irrigation coverage across as much as 98.7% of acres in irregularly shaped fields.
Top Key Players Outlook
-
- Valmont Industries
- Lindsay Corporation
- Reinke Manufacturing Company
- T-L Irrigation Company
- Pierce Corporation
- OCMIS Irrigation
- Alkhorayef Group
- Irritec
- Rivulis Irrigation
- Jain Irrigation Systems Ltd.
- Other Key Players
Recent Developments
- July 2026, Alkhorayef Water and Power Technologies received a SAR 65.59 million contract from the Saudi Irrigation Organization covering pumping, transmission and distribution systems for 60 months.
- In March 2025, the Nebraska-based company reported that its equipment was operating across 47 U.S. states and 80 countries, supported by around 200 U.S. dealers and 50 international dealers, while its workforce stood at approximately 225–300 employees.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 3.8 Bn |
| Forecast Revenue (2035) | USD 12.1 Bn |
| CAGR (2026-2035) | 12.3% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Component (Pivot Points, Control Panels, Span, Sprinkler Drop, Tower Drive Wheels, Drive Train, Others), By Crop Type (Oilseeds & Pulses, Cereals, Others), By Mobility (Stationary, Mobile) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | Valmont Industries, Lindsay Corporation, Reinke Manufacturing Company, T-L Irrigation Company, Pierce Corporation, OCMIS Irrigation, Alkhorayef Group, Irritec, Rivulis Irrigation, Jain Irrigation Systems Ltd., Other Key Players |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |





































