


Report Overview
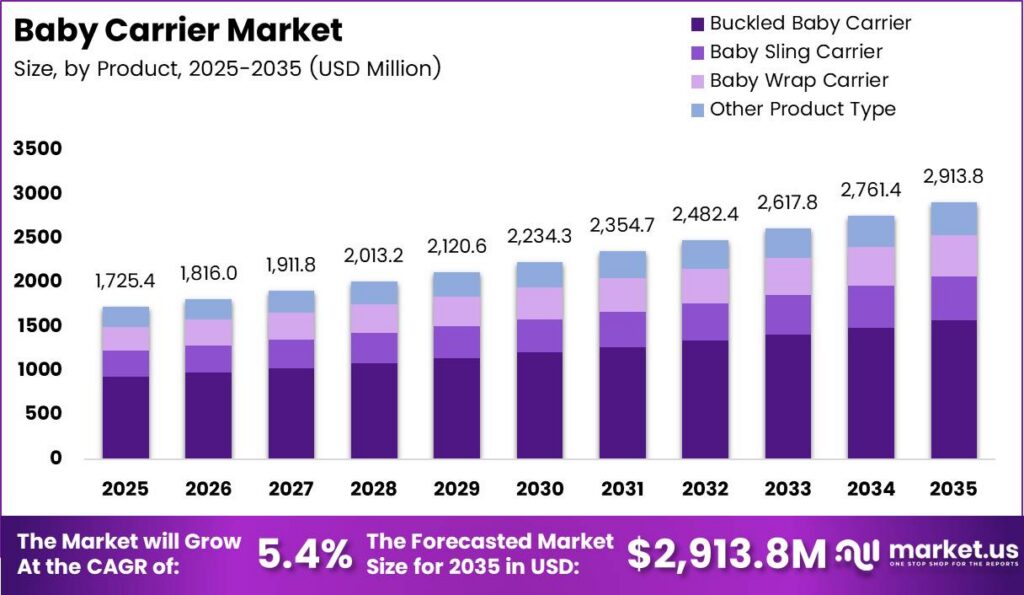
Global Baby Carrier Market size is expected to be worth around USD 2,913.8 Million by 2035 from USD 1,725.4 Million in 2025, growing at a CAGR of 5.4% during the forecast period 2026 to 2035. A baby carrier is a wearable textile or framed support device that holds infants and toddlers securely against a caregiver body to enable hands free mobility and ergonomic weight distribution. Consequently, manufacturers capture higher unit margins by turning daily infant transport into a health certified lifestyle purchase.
Commercial activity spans mass retail chains, specialty juvenile boutiques, postnatal hospital networks, and direct online storefronts serving household and outdoor travel buyers. According to UNICEF, global civil systems registered over 500 million children under age 5 across a 5 year window, while 150 million young children remained unregistered . Therefore, formalizing birth tracking across urbanizing economies expands the addressable customer pool for branded juvenile durables and structured infant gear.
Key Takeaways
- The global Baby Carrier Market reached a valuation of USD 1,725.4 Million in 2025.
- Global market revenue will reach USD 2,913.8 Million by 2035.
- Industry sales expand at a compound annual growth rate of 5.4% during the forecast period from 2026 to 2035.
- Buckled Baby Carrier led the product segment with a 53.45% market share in 2025.
- Mass tier models captured the largest price tier share at 67.89% in 2025.
- The Baby cohort aged 6 to 12 months accounted for a dominant 56.89% share in 2025.
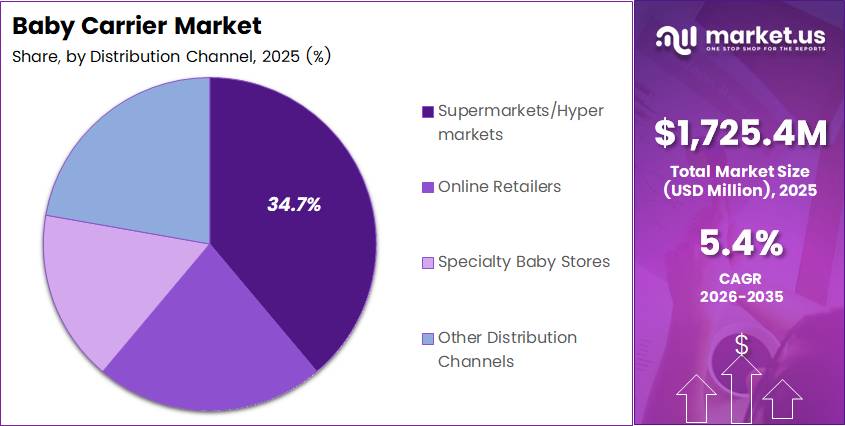
- Supermarkets/Hypermarkets led all distribution channels by holding a 34.78% revenue share in 2025.
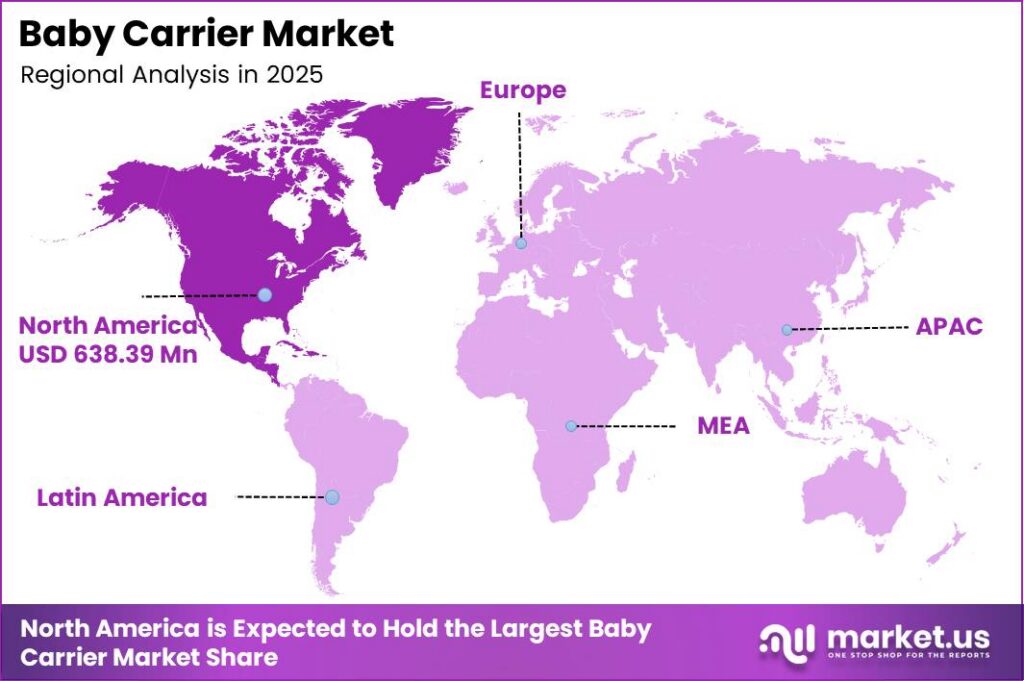
- North America dominated global regional performance in 2025 with a 37.09% share valued at USD 638.39 Million, while Asia Pacific registers the fastest regional expansion through 2035.
Public intellectual property frameworks and pediatric safety mandates actively shape product engineering and supplier qualification costs across major consumer territories. Data from WIPO shows global patent filings hit a record 3.7 million applications in 2024 with a 4.9% annual gain, alongside 3.3 million utility model filings. This signals intense patent protection around magnetic buckles, lumbar support belts, and breathable mesh weaves that lock out low cost imitators.
Private equity capital continues targeting established ergonomic gear portfolios that maintain broad omnichannel shelf space and recurring household trust. In December 2024, a Dallas private investment firm acquired a global ergonomic carrier platform spanning more than 1,800 retail doors across 75 countries at an enterprise valuation of USD 104.0 million. As a result, institutional investors validate premium babywearing brands as resilient cash flow assets despite broader demographic headwinds.
North America commands the leading global position with a 37.09% revenue share in 2025, supported by dual income household necessity and strict childcare economics. Based on ILO data, roughly 2.0 billion potential parents worldwide lack statutory paid leave protection, while 748 million adults stay outside the workforce for caregiving. Consequently, working North American families prioritize multi position ergonomic carriers to balance active commuting with daily infant care.
Product developers also refresh entry and mid priced lines to retain value conscious households facing elevated grocery and housing budgets. In February 2026, a major juvenile gear supplier introduced a cross back carrier supporting 7 to 40 lbs at USD 54.97 alongside a 4 mode convertible model priced at USD 39.99 . This creates intense price competition that forces mid tier brands to bundle lumbar support features without raising retail tags.
Product Analysis
Buckled Baby Carrier dominates with 53.45% share in 2025 due to superior lumbar weight distribution mechanics.
In 2025, Buckled Baby Carrier held a 53.45% share in the Product segment of the Baby Carrier Market. As reported by the U.S. Consumer Product Safety Commission, federal rule 16 CFR Part 1226 enforced revised standard ASTM F2236 24 after February 22, 2025, mandating stricter fastener and strap retention testing . Reinforced polymer buckles mechanically transfer infant body weight from caregiver shoulders directly onto the pelvic girdle. Consequently, compliant brands command higher retail prices while uncertified sellers face customs seizures.
Baby Sling Carrier serves parents seeking rapid one shoulder infant placement and registers the fastest expansion across all product styles. UNICEF found that 48% of newborns nurse within 1 hour of birth and 47% of infants under 6 months breastfeed exclusively , yet regulators recalled 18,650 Sunkids Factory mesh slings priced from USD 7 to USD 15 in February 2025 . Ring adjusted textile pouches allow immediate upright feeding posture without complex strap adjustments. Therefore, verified sling brands capture strong repeat sales by proving seam durability.
Baby Wrap Carrier functions as anunstiffened woven or knit fabric band favored by neonatal units and fourth trimester caregivers. Figures from WHO show over 20 million babies arrive annually weighing under 2.5 kg, prompting clinical Kangaroo Mother Care wrap guidelines for newborns at or under 2,000 g . Biaxial stretch fabrics conform evenly around fragile infant spines to regulate core body temperature through continuous chest contact. This means textile wrap makers gain reliable hospital pharmacy referrals before parents upgrade to structured gear.
Price Tier Analysis
Mass dominates with 67.89% share in 2025 due to broad supermarket shelf affordability.
In 2025, Mass held a 67.89% share in the Price Tier segment of the Baby Carrier Market. OECD indicates that real household disposable income per capita rose 1.8% in 2024 and 0.7% in late 2025 , while Momcozy promoted its PureHug carrier at USD 59.99 alongside a USD 89.99 gift set in November 2026 . Modest wage gains keep middle income families anchored to sub USD 70 polyester carriers that meet baseline safety rules. Consequently, high volume suppliers rely on automated Asian cut and sew plants to protect thin margins.
Premium represents the fastest expanding price tier as affluent urban households treat wearable baby gear as a fashion statement. According to Eurostat, European women reached an average age of 29.9 years at first childbirth in 2024, peaking at 31.9 years in Italy , supporting launches like the USD 400 Nuna CUDL luxe cashmere silk carrier in August 2024. Older first time parents accumulate higher savings and demand magnetic fasteners paired with natural thermoregulating fibers. Therefore, luxury juvenile brands insulate gross margins against declining birth volumes.
Mid to premium value migration reshapes product assortments as active outdoor brands bridge everyday infant carrying and trail performance. Data from the US Census Bureau shows average American family size stood at 3.1 persons in 2026 with overall households averaging 2.5 persons , encouraging Osprey to launch recycled Poco Soft carriers at USD 135 and USD 120 in January 2025. Smaller family sizes concentrate gear budgets onto fewer children and reward durable ripstop fabrics built for multi year wear. This signals strong crossover revenue for outdoor pack makers entering babywearing.
Age Group Analysis
Baby (6 to 12 months) dominates with 56.89% share in 2025 due to active seated neck control.
Infant models covering 0 to 6 months focus on cervical head support, airway clearance, and inward facing neonatal bonding. As reported by UNICEF, global mortality under age 5 reached 4.9 million in 2024, including 2.3 million newborn deaths during the first month of life . Fragile newborn neck muscles require tensioned upper back panels that prevent chin to chest slumping and keep nasal airways open. Consequently, manufacturers invest heavily in pediatric orthopedic certifications to win trust from anxious first time parents.
In 2025, Baby (6 to 12 months) held a 56.89% share in the Age Group segment of the Baby Carrier Market. Based on OECD data, average maternal employment across member nations reached 71%, rising to 73% among mothers raising 1 child . Once infants develop independent sitting stability at 6 months while parents return to work, daily transit shifts toward multi position outward and hip carrying. This creates peak retail turnover for structured all season carriers supporting up to 15 kg.
Toddler designs serving children aged 12 to 36 months post the fastest unit velocity across the age spectrum. WHO found that children aged 1 to 2 years require at least 180 minutes of daily physical movement and must not sit restrained in strollers beyond 1 continuous hour . Walking toddlers frequently tire during errands and require wide hip seats or high capacity back carriers allowing quick up and down transitions. Therefore, brands adding 20 kg toddler extensions extend customer lifetime value well past infancy.
Distribution Channel Analysis
Supermarkets/Hypermarkets dominates with 34.78% share in 2025 due to one stop family shopping convenience.
In 2025, Supermarkets/Hypermarkets held a 34.78% share in the Distribution Channel segment of the Baby Carrier Market. Figures from the US Census Bureau show general merchandise chains including supercenters generated USD 787.36 billion across the first 10 months of 2026, while grocery stores added USD 762.04 billion . High weekly foot traffic for diapers and formula allows hypermarkets to convert impulse purchases on entry priced buckled carriers through physical box inspection. Consequently, mass brands must fund endcap displays to defend retail shelf velocity.
Online Retailers deliver the fastest channel expansion as digital native parents compare ergonomic reviews and video fit guides from home. Eurostat indicates that 78% of European internet users aged 16 to 74 shopped online in 2025 , prompting Stokke to launch a bilingual Canadian online store with free shipping above CAD 50 in May 2026 . Direct digital checkout eliminates middleman retail markups and lets manufacturers sell full colorway catalogs without physical store inventory limits. As a result, direct online sales lift brand gross margins and capture first party parent data.
Specialty Baby Stores anchor high ticket sales by offering hands on torso fitting, weighted doll trials, and registry consultations. According to the US Census Bureau, specialty clothing and accessories retailers generated USD 244.15 billion during the first 10 months of 2026 with a 5.3% annual gain , aligning with Ergobaby adding Crate and Barrel Kids and Shoppers Drug Mart doors in April 2026 . Physical strap adjustments resolve caregiver fit anxiety before buyers commit over USD 180 on flagship structured gear. This means premium suppliers rely on specialty boutiques to validate price integrity.
Key Market Segments
By Product
- Buckled Baby Carrier
- Baby Sling Carrier
- Baby Wrap Carrier
- Other Product Type
By Price Tier
- Mass
- Premium
By Age Group
- Infant (0 to 6 months)
- Baby (6 to 12 months)
- Toddler (12 to 36 months)
By Distribution Channel
- Supermarkets/Hypermarkets
- Online Retailers
- Specialty Baby Stores
- Other Distribution Channels
Regional Analysis
North America Dominates the Baby Carrier Market with a Market Share of 37.09% in 2025, Valued at USD 638.39 Million
North America leads global revenue with a 37.09% market share valued at USD 638.39 Million in 2025. Data from the US Census Bureau shows quarterly American online retail sales reached USD 340.2 billion in Q2 2026, while CDC NCHS recorded 3,612,012 national live births in 2025 . Deep baby registry culture and strict federal ASTM safety enforcement steer American households toward certified multi position carriers priced above USD 150. Therefore, global juvenile brands prioritize U.S. omnichannel distribution to anchor baseline cash flow.
Europe represents a mature, design conscious babywearing territory where rising unit prices offset shrinking newborn cohorts. As reported by Eurostat, annual live births across the European Union fell 3.3% to 3.55 million in 2024, pushing the regional fertility rate down to 1.34 births per woman . Fewer births per household prompt European parents and gift givers to invest in organic linen wraps and pediatric certified Scandinavian carriers. Consequently, European manufacturers focus on premium sustainable textiles and certified resale loops rather than unit volume chases.
Asia Pacific registers the fastest regional expansion alongside steady urban adoption across Latin America and Middle East and Africa. World Bank found that East Asia and Pacific urban populations reached 1,548.59 million in 2025 with regional GDP per capita at USD 14,077.3, while Latin America hit 82% urbanization . Meanwhile, IMF and World Bank data show Sub Saharan Africa maintained a 4.3 fertility rate alongside 4.3% projected 2026 economic expansion. This signals massive multi year volume upside for breathable mesh carriers tailored to warm emerging cities.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Commercial performance across the juvenile babywearing sector balances premium orthopedic engineering against demographic headwinds, chemical rules, and uncertified online imports. Based on Minnesota Pollution Control Agency data, Amara Law banned intentionally added PFAS chemicals across 11 consumer categories including all juvenile products on January 1, 2025, with mandatory reporting enforced by September 15, 2026 . Consequently, carrier brands must reformulate stain resistant fabric coatings and audit textile mills to avoid state sales bans and costly inventory write downs.
Drivers
Clinical focus on infant hip dysplasia and parent back strain has turned orthopedic alignment into a mandatory baseline standard. Federal enforcement of ASTM F2236 24 under 16 CFR Part 1226 on February 22, 2025 pushed brands to build M position seat bases supporting 3.2 kg to 20.4 kg. Instead of selling USD 30 to USD 45 narrow carriers, brands now emphasize USD 160 to USD 240 ergonomic flagships. This shift lifts average selling prices by 18% to 24% and sustains gross margins at 53% to 58%.
Medical endorsements from spinal and orthopedic groups also lower digital marketing costs by 14% to 19% among millennial and Gen Z buyers. At the same time, households upgrade out of newborn wraps within 4 to 6 months, shortening replacement cycles and accelerating multi stage carrier revenue for compliant manufacturers.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Pediatric Orthopedic Ergonomic Standardization | +1.9% | North America, Europe, Developed APAC | Short term (≤ 2 years) |
| Dual-Income Urban Mobility & Hands-Free Childcare | +1.5% | Global Urban Centers | Medium term (2–4 years) |
| Multi-Position Newborn-to-Toddler Modular Architecture | +1.3% | North America, Western Europe | Short term (≤ 2 years) |
| Social Commerce Direct-to-Consumer Brand Acquisition | +1.0% | North America, China, Southeast Asia | Short term (≤ 2 years) |
| Breathable Performance Mesh & Thermoregulating Fabrics | +0.8% | Asia-Pacific, Latin America, Middle East | Medium term (2–4 years) |
Restraints
Falling birth rates across wealthy nations place a hard cap on first hand unit volume for infant durable goods. Average fertility across 38 industrialized countries dropped to 1.48 births per woman in 2024 against the 2.10 replacement mark, while East Asia and Southern Europe hit 0.72 to 1.20. Because newborns aged 0 to 12 months generate over 75% of primary carrier retail sales, smaller cohorts cut revenue by 3% to 10% at Western juvenile specialists across 2024 and 2025.
Shrinking baseline demand compresses specialty brand operating margins by 600 to 900 basis points, pulling benchmark margins down from 19% in 2023 to 10% in 2025. Consequently, executive teams freeze factory tooling budgets and delay mass retail shelf rollouts across mature territories.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Structural Fertility Decline Across Advanced Economies | -1.6% | OECD, East Asia, Europe | Long term (≥ 4 years) |
| State-Level Statutory PFAS Chemical Prohibitions | -1.1% | United States, European Union | Short term (≤ 2 years) |
| Informal Hand-Me-Down & Peer Resale Substitution | -0.9% | North America, Europe | Medium term (2–4 years) |
| Import Duty Escalation on Asian Cut-and-Sew Goods | -0.8% | United States | Short term (≤ 2 years) |
| Traditional Textile Sling Cultural Preference | -0.5% | Sub-Saharan Africa, Rural South Asia | Long term (≥ 4 years) |
Challenges
Open third party online marketplaces let overseas cut and sew sellers bypass Children Product Certificate lab testing and flood search pages with unsafe carriers. Across 2025 and 2026, safety agencies issued urgent stop use alerts on thousands of imported USD 27 to USD 59 units versus USD 120 to USD 220 certified models. Detached straps, weak buckles, and wide leg holes failed static load and 25 mm slippage rules under 16 CFR Parts 1226 and 1228.
Uncertified sub USD 50 listings raise paid search ad bidding costs by 22% to 30% for compliant makers and damage buyer trust after public fall warnings. Protecting market share forces legitimate brands to spend 3% to 5% of net sales on marketplace takedown tools, QR tracking tags, and lab batch tests costing USD 2,500 to USD 4,200 per colorway.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Unverified Cross-Border Marketplace Non-Compliance | -1.1% | North America, Europe | Short term (≤ 2 years) |
| Organic & Recycled Textile Cost Volatility | -0.8% | Global Supply Chain | Medium term (2–4 years) |
| Caregiver Fit Complexity & Misuse Liability | -0.7% | Global | Medium term (2–4 years) |
| Multi-Jurisdictional Safety Testing Fragmentation | -0.6% | United States, UK, EU, Australia | Medium term (2–4 years) |
| Seasonal Inventory & Colorway Obsolescence | -0.4% | North America, Western Europe | Short term (≤ 2 years) |
Opportunities
Peer to peer secondhand trading currently drains retail sales without paying manufacturers, leaving brand owned rental subscriptions and certified resale wide open. Infants outgrow newborn wraps in 6 to 9 months and structured carriers in 24 to 30 months, yet tough nylon and organic cotton frames last through 3 to 4 family cycles. Manufacturers can shift buyers from one time hardware purchases toward recurring access plans priced at USD 18 to USD 28 per month.
Running in house cleaning, buckle swaps, and safety recertification at USD 11 to USD 16 per returned carrier generates 1.6x to 2.1x lifetime revenue over a single USD 180 sale. This circular model expands lifecycle gross margins by 650 to 950 basis points while cutting customer acquisition costs by 25% to 35% through built in newborn to toddler stage upgrades.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Brand-Owned Circular Subscription & Certified Recommerce | +1.5% | North America, Western Europe | Medium term (2–4 years) |
| Paternal-Specific & Plus-Size Inclusive Sizing Lines | +1.2% | North America, Europe, Australia | Short term (≤ 2 years) |
| Tier-2 & Tier-3 Emerging Urban Retail Penetration | +1.1% | India, Southeast Asia, Brazil | Medium term (2–4 years) |
| Smart Biometric & Microclimate Sensor Integration | +0.8% | North America, East Asia | Long term (≥ 4 years) |
| Postpartum Hospital & Corporate Parental Benefit Bundling | +0.7% | United States, Nordics, Western Europe | Medium term (2–4 years) |
Key Company Insights
Artsana Group (Chicco)
Artsana Group anchors European and North American juvenile retail through its flagship Chicco and Boppy babywearing, travel, and nursing lines. Figures from Artsana Group financial and sustainability disclosures show consolidated worldwide net revenues totaled EUR 1,334 million in 2024 across 2,120 babycare employees and EUR 1,270 million in 2025, with 76% generated in Europe and 10.6% in the United States . Broad pharmacy and mass retail reach protects shelf visibility across entry and mid priced carriers.
In June 2026, controlling shareholders Investindustrial holding 60% and the Catelli family holding 40% completed a EUR 673 million financial strengthening package for Artsana Group, as reported by BeBeez and Il Messaggero . The recapitalization combined EUR 258 million in equity strengthening including EUR 50 million fresh cash with EUR 415 million in renewed bank credit lines targeting USD 95 million in U.S. revenue expansion . Consequently, Chicco gains deep balance sheet firepower to counter European fertility declines.
BabyBjörn AB
BabyBjörn AB specializes in Scandinavian ergonomic soft structured carriers, mesh newborn slings, and bouncers engineered for children aged 0 to 3 years. According to the BabyBjörn AB Annual Report, consolidated group net revenue reached SEK 1,049 million with operating profit of SEK 108 million in 2025, following SEK 1,077 million revenue in 2024 with 95% exported across over 50 countries. Tight product focus preserves premium brand equity across global specialty boutiques.
In September 2026, BabyBjörn AB marked its 65th anniversary by launching the vest style wrap around Baby Carrier Hold for 7 to 30 lbs at USD 179.99 alongside Bouncer Begin at USD 209.99, according to Business Wire. Tested with more than 400 families and rolled out through a Mothercare retail event, the hip healthy design simplifies solo newborn dressing . This signals disciplined product innovation aimed at capturing fourth trimester parents early.
Key Players
- Artsana Group (Chicco)
- BabyBjörn AB
- Ergobaby Inc.
- Goodbaby International Holdings Ltd
- Thrive International Inc. (Moby Wrap)
- Stokke AS
- Blue Box Corp. (Infantino)
- LILLEbaby LLC
- Boba Inc.
- Be Lenka s.r.o.
- WildBird LLC
- Storchenwiege
- Other Key Players
Recent Developments
2026
- November 2026: U.S. CPSC regulatory enforcement issued Product Safety Warning No. 27 079 instructing consumers to stop using Bambora Sling Carriers retailing between USD 59 and USD 118 due to strap detachment fall hazards, U.S. CPSC
- October 2026: Blue Box Corp. (Infantino) product launch expanded its babywearing range with the First Bloom Newborn Carrier for 7 to 25 lbs at USD 39.99, Swift Classic at USD 27.99, and Hip Rider Max Storage Hip Seat for 12 to 45 lbs at USD 52.99, PR Newswire
- October 2026: Stokke AS and Bonpoint partnership and product launch debuted the organic cotton Stokke Limas Carrier Flex Bonpoint Beige supporting infants from 4 kg to 20 kg at EUR 249.00, Stokke Official Newsroom
- September 2026: Goodbaby International Holdings Ltd. merger and privatization offer received a cash buyout proposal from Crystal Aurora International at HKD 1.50 per share representing a 38.89% premium and valuing 881.50 million scheme shares at HKD 1.32 billion, HKEX Official Filing
- September 2026: Baby Tula (Ergobaby Inc.) innovation and product launch executed a global brand relaunch featuring the Explore Carrier at USD 219 for 7 to 45 lbs, Original Carrier at USD 179, and Kid Carrier supporting up to 60 lbs at USD 179, GlobeNewswire
- August 2026: Ergobaby Inc. product launch introduced the breathable mesh and linen Omni Lite Carrier supporting newborn to toddler inward carry from 7 to 35 lbs without an insert at USD 139, GlobeNewswire
- April 2026: U.S. CPSC regulatory enforcement issued Product Safety Warning No. 26 463 covering 1,200 units of Yemkezo Infant and Toddler Carriers sold on Amazon near USD 50 for failing 16 CFR Part 1226 fastener and leg opening rules, U.S. CPSC
2025
- September 2025: Dorel Industries Inc. funding round closed a USD 75.0 million private placement of preferred shares with Alberta Investment Management Corporation to strengthen liquidity and fund juvenile product rollouts, Company Filing
Geopolitical Impact Analysis
Trade fragmentation and maritime container risks directly reshape outbound shipping schedules for Asian cut and sew baby carrier factories. Data from WTO shows world merchandise trade volume grew 4.6% in 2025 to USD 26.26 trillion and rises 3.9% in 2026, yet 2026 import volume surges 9.5% in Asia against just 1.4% in North America and 0.5% in Europe . Meanwhile, UNCTAD found that H1 2026 global goods trade hit USD 13.7 trillion with a 12.5% value jump driven by freight and price inflation across a 6,033 ship fleet holding 30.3 million TEU . As reported by the World Shipping Council, containers lost at sea more than doubled to 1,478 out of 280 million shipped in 2025, while lines committed USD 150 billion toward 1,126 dual fuel ships . Rerouted ocean voyages delay seasonal colorway deliveries of organic cotton wraps, padded nylon webbing, and aluminum sling rings, forcing Western juvenile distributors to carry 6 to 8 weeks of extra buffer stock.
Middle East energy chokepoint shocks also inflate petrochemical resin and synthetic mesh input bills across juvenile hardware supply chains. Based on IEA data, conflict disruptions near the Strait of Hormuz, which carried 20 million barrels per day in 2025, drove North Sea Dated crude up USD 26.17 to USD 116.89 per barrel in September 2026 and pushed wholesale diesel near USD 220 per barrel . IMF indicates that global economic expansion slows to 3.1% in 2026 with advanced economies at 2.1% and emerging nations at 3.7%, as global inflation climbs to 4.7% . Surging crude and diesel benchmarks raise supplier quotes for polyoxymethylene safety buckles, EVA lumbar foam, and 3D polyester air mesh, compelling carrier brands to lock multi quarter resin contracts or trim mass retail promotional discounts.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 1,725.4 Million |
| Forecast Revenue (2035) | USD 2,913.8 Million |
| CAGR (2026-2035) | 5.4% |
| Base Year for Estimation | 2025 |
| Historic Period | 2021-2025 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Product (Buckled Baby Carrier, Baby Sling Carrier, Baby Wrap Carrier, Other Product Type), By Price Tier (Mass, Premium), By Age Group (Infant 0 to 6 months, Baby 6 to 12 months, Toddler 12 to 36 months), By Distribution Channel (Supermarkets/Hypermarkets, Online Retailers, Specialty Baby Stores, Other Distribution Channels) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Artsana Group (Chicco), BabyBjörn AB, Ergobaby Inc., Goodbaby International Holdings Ltd, Thrive International Inc. (Moby Wrap), Stokke AS, Blue Box Corp. (Infantino), LILLEbaby LLC, Boba Inc., Be Lenka s.r.o., WildBird LLC, Storchenwiege, Other Key Players |
| Customization Scope | Customization for segments, region / country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License | Multi-User License (Up to 5 Users) | Corporate Use License (Unlimited User and Printable PDF) |








