


Report Overview
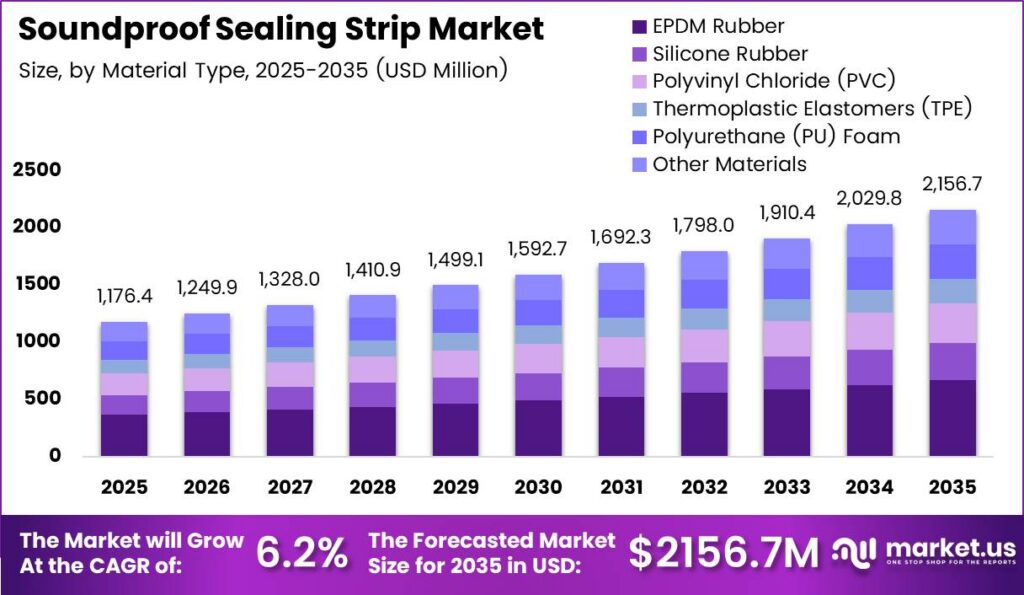
Global Soundproof Sealing Strip Market size is expected to be worth around USD 2,156.7 Million by 2035 from USD 1,176.4 Million in 2025, growing at a CAGR of 6.2% during the forecast period 2026 to 2035. A soundproof sealing strip is an engineered elastomeric or polymeric profile that compresses between structural frames and moving panels to block airborne noise, dampen mechanical vibration, and prevent thermal air leakage. Therefore, construction and automotive buyers treat these profiles as essential acoustic and thermal components that directly raise property valuations and vehicle cabin quality.
The market serves residential buildings, commercial towers, automotive assembly plants, and industrial machinery enclosures. According to IEA, buildings account for 30% of global final energy consumption, with residential spaces representing 70% of building energy demand and commercial structures taking 30% in 2025. Consequently, developers specify dual-purpose acoustic weatherstripping to reduce heating and cooling loads while blocking street noise. This means extrusion manufacturers that combine acoustic damping ratings with certified thermal insulation capture premium commercial supply contracts and protect gross margins against low-cost commodity imports.
Key Takeaways
- The global Soundproof Sealing Strip Market was valued at USD 1,176.4 Million in 2025.
- Global market revenue will reach a forecast value of USD 2,156.7 Million by 2035.
- The market will expand at a compound annual growth rate of 6.2% during the forecast period from 2026 to 2035.
- In the Material Type segment, EPDM Rubber led the market with a 31.00% share in 2025.
- In the Product Type segment, Self-Adhesive Sealing Strips held the dominant position with a 54.00% share in 2025.
- In the Application segment, Doors accounted for the largest share at 28.00% in 2025.
- In the End-Use Industry segment, Commercial Buildings led all categories with a 24.00% share in 2025.
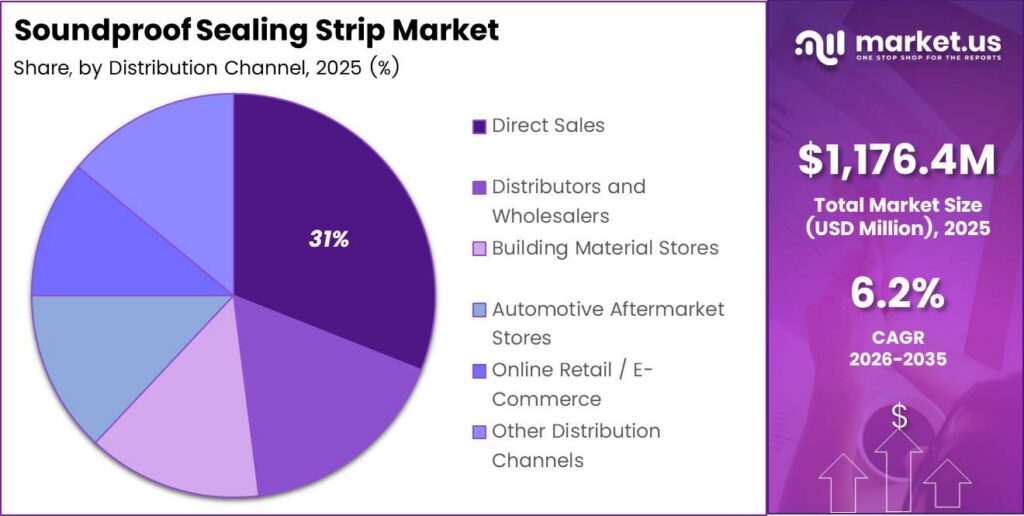
- In the Distribution Channel segment, Direct Sales captured the top share of 31.00% in 2025.
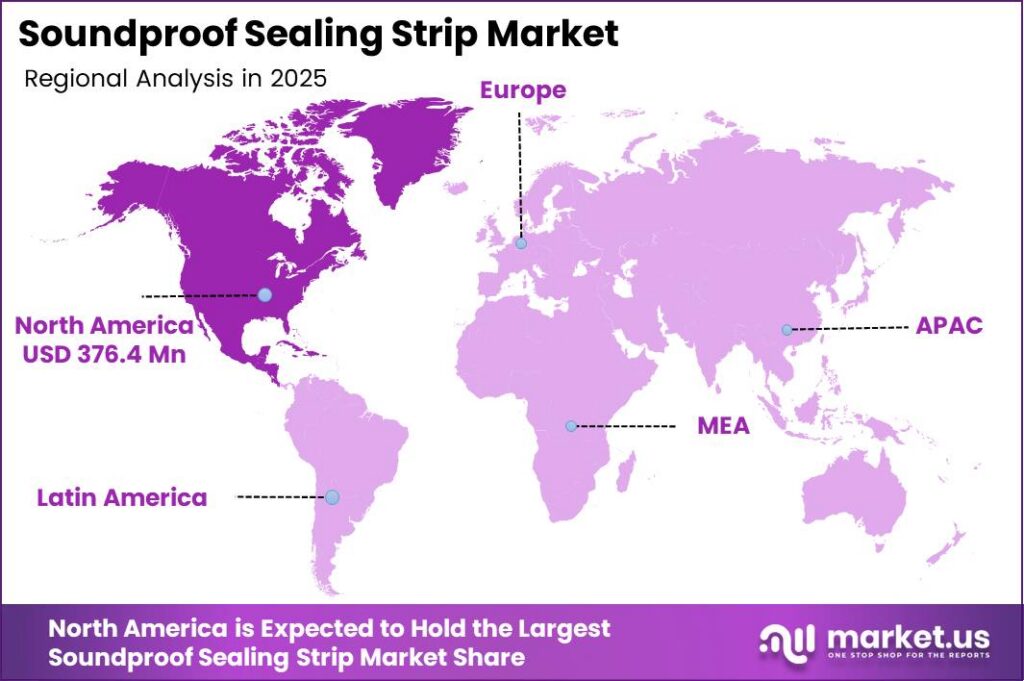
- North America dominated the regional landscape in 2025 with a 32.00% market share valued at USD 376.4 Million.
Strict public health noise standards and municipal acoustic building codes force property developers to upgrade window and door perimeter seals across urban centers. As reported by WHO and European Environment Agency, 109 million people across Europe face unhealthy transport noise levels of 55 dB or higher, while stricter 53 dB health thresholds cover 145 million residents in 2025. Therefore, municipal zoning authorities require higher sound transmission class ratings on residential facades. This creates guaranteed baseline volume for high-density co-extruded sealing strips in public housing and urban retrofit projects.
Strategic corporate consolidation continues to reshape global supply chains for building envelope and industrial sealing materials. In February 2025, a major construction materials group completed the acquisition of a global construction chemicals and sealants producer for EUR 960 million, equivalent to USD 1,025 million, adding 20 manufacturing plants and 3,000 employees to build a EUR 6.5 billion platform across 76 countries . Consequently, integrated building material suppliers can bundle perimeter sealing strips with structural sealants. This signals that independent regional extruders must specialize in custom profiles or face margin compression during large contractor tenders.
North America holds the dominant position in the global market, capturing a 32.00% share valued at USD 376.4 Million in 2025. Data from OICA shows global motor vehicle production rose 3.9% from 92.7 million units in 2024 to 96.4 million units in 2025, while global vehicle sales grew 4.7% to reach 99.8 million units . High North American production of acoustic-sensitive electric trucks, sport utility vehicles, and luxury sedans requires heavy per-vehicle linear meter usage of door weatherstripping. As a result, regional suppliers enjoy stable multi-year capacity utilization and high revenue visibility.
Material compounders are also acquiring specialized polymer processors to secure high-margin industrial and architectural capabilities. In May 2025, a leading polymer engineering group completed the acquisition of a European silicone rubber profile manufacturer generating SEK 280 million in annual sales with 330 employees . This reflects a broader industry shift away from standard rubber profiles toward extreme-temperature silicone extrusions for high-speed rail and medical equipment. Therefore, investors are rewarding sealing manufacturers that acquire proprietary silicone compounding assets to capture higher unit selling prices.
Material Type Analysis
EPDM Rubber dominates with 31.00% share in 2025 due to superior weather and ozone resistance.
In 2025, EPDM Rubber held a 31.00% share in the Material Type segment of the Soundproof Sealing Strip Market. US Census Bureau found that U.S. manufacturers monthly shipments of plastics and rubber products reached USD 25,259 million in March 2025, backed by material inventories of USD 15,399 million. Synthetic ethylene propylene diene monomer chains resist ultraviolet cracking and maintain elastic compression recovery across wide temperature swings in exterior door and automotive seals. Therefore, compounders locking in multi-year ethylene feedstock contracts protect operating margins while serving high-volume automotive and architectural buyers.
Silicone Rubber serves high-temperature and cleanroom sealing applications where standard elastomers lose elasticity and fail fire codes. Based on USGS data, global silicon metal production totaled 4,600 thousand metric tons in 2024, while China produced 4,000 thousand metric tons in 2025, accounting for 80% of global output . Siloxane polymer backbones require refined silicon metal feedstocks to achieve low compression set and non-toxic flame retardancy in hospital, aerospace, and high-speed rail door seals. Consequently, western extruders must diversify silicon precursor sourcing outside single-country suppliers to prevent supply bottlenecks and margin erosion.
Polyvinyl Chloride (PVC) provides cost-effective rigid and flexible co-extruded profiles for residential window frames and interior door sweeps. ECHA indicates that European Union REACH regulations effective November 2024 prohibit PVC articles containing lead concentrations of 0.1% or higher by weight, while PVC formulations consume 85% of total plasticizer volume . Replacing legacy heavy-metal stabilizers and restricted phthalate plasticizers alters melt viscosity during profile extrusion and requires calcium-zinc stabilizer reformulation. This means PVC strip manufacturers must invest in compliant compounding lines immediately or lose access to European retail and construction tenders.
Product Type Analysis
Self-Adhesive Sealing Strips dominates with 54.00% share in 2025 due to fast tool-free installation efficiency.
In 2025, Self-Adhesive Sealing Strips held a 54.00% share in the Product Type segment of the Soundproof Sealing Strip Market. Figures from Nitto Denko Corporation show first-half fiscal revenue rose 8.7% year-on-year to JPY 558.36 billion and operating profit grew 12.0% to JPY 105.84 billion, reaching a 19.0% operating margin in September 2026 . Pressure-sensitive acrylic and rubber adhesive backings bond instantly to painted metal, wood, and glass frames, eliminating mechanical fasteners and cutting contractor labor hours. Therefore, profile extruders that integrate in-line adhesive lamination capture higher retail margins and expand recurring aftermarket sales.
Non-Adhesive Sealing Strips rely on mechanical kerf slots, T-slots, and flanged retaining channels for heavy-duty architectural and automotive doors. According to ACC, the U.S. Chemical Production Index jumped from negative 21 to a record high of 34 in Q1 2026, as 45% of chemical manufacturers expanded output . Higher domestic elastomer and polymer resin output lowers raw compound costs for mechanically retained bulb and fin profiles that endure thousands of high-friction door closing cycles without adhesive peeling. Consequently, commercial door hardware manufacturers favor non-adhesive kerf profiles to reduce warranty replacement claims.
Others include magnetic acoustic perimeter seals and intumescent fire-and-smoke soundproof strips used in specialized commercial and industrial doors. As reported by WIPO, innovators worldwide filed a record 3.7 million patent applications in 2024, a 4.9% annual increase, pushing global patents in force up 6.0% to 19.7 million . Acoustic hardware engineers file patent claims on multi-chamber magnetic attraction profiles and graphite-infused intumescent cores that expand under heat while blocking mid-frequency speech transmission. This signals that specialty hardware brands can use patent-protected profile geometries to lock out generic extrusion competitors.
Application Analysis
Doors dominates with 28.00% share in 2025 due to strict commercial perimeter acoustic standards.
In 2025, Doors held a 28.00% share in the Application segment of the Soundproof Sealing Strip Market. Data from Eurostat shows seasonally adjusted construction production in the European Union increased by 2.0% month-on-month and 2.6% year-on-year in August 2026, led by a 2.9% annual rise in installation activities . Hinged and sliding doors create the largest structural air gaps in building envelopes, requiring continuous perimeter compression seals and automatic door bottoms to stop sound flanking across hallways. Therefore, sealing manufacturers that partner with commercial door OEMs secure high-volume factory pre-installation contracts.
Windows represent a primary residential and commercial application where multi-pane acoustic glazing requires airtight sash and frame compression gaskets. US DOE found that windows account for 10% of total energy use in buildings and directly govern heating, cooling, and lighting loads representing 40% of building energy consumption . Unsealed window perimeters allow both high-frequency traffic noise infiltration and conductive thermal drafts, forcing window fabricators to install dual-durometer finned weatherstripping across casement and tilt-turn frames. Consequently, suppliers offering co-extruded low-friction window seals gain preferred vendor status among energy-star window manufacturers.
Automotive Doors and Windows require precision-molded and extruded elastomeric weatherstrips to isolate vehicle cabins from wind, tire, and road noise. Based on ACEA data, new EU passenger car registrations rose 5.7% in the first half of 2026, with battery-electric vehicles capturing 20.7% share at 1,220,890 units and hybrids reaching 37.3% at 2,198,148 units . Electric powertrains eliminate engine masking noise, making high-speed aerodynamic wind noise around door glass run channels and frameless windows immediately audible to passengers. This means automotive tier-one sealing suppliers can command price premiums for flock-coated and micro-cellular acoustic profiles.
End-Use Industry Analysis
Commercial Buildings dominates with 24.00% share in 2025 due to office and hospital noise codes.
In 2025, Commercial Buildings held a 24.00% share in the End-Use Industry segment of the Soundproof Sealing Strip Market. US Census Bureau indicates that U.S. private nonresidential construction spending reached a seasonally adjusted annual rate of USD 738.8 billion in June 2025, alongside public construction spending of USD 514.3 billion . Healthcare patient rooms, corporate conference suites, and hotel corridors require certified acoustic door gasketing systems to meet speech privacy regulations and occupant sleep standards. Therefore, manufacturers supplying fire-rated and smoke-certified acoustic seals win lucrative institutional specification tenders across hospitals, schools, and office towers.
Residential end-users purchase soundproof sealing strips for multi-family apartment entry doors, street-facing bedroom windows, and home office retrofits. Figures from US Census Bureau show U.S. private residential construction spending operated at a seasonally adjusted annual rate of USD 883.1 billion in June 2025, accounting for 54.4% of USD 1,621.9 billion in total private construction . High-density multi-family condo developments and urban townhomes share party walls and common corridors, creating immediate buyer demand for peel-and-stick foam and rubber door seals. Consequently, brands packaging consumer-friendly acoustic weatherstripping kits achieve rapid inventory turnover across home improvement channels.
Industrial Facilities install heavy-duty elastomeric sealing profiles on compressor housings, generator cabinets, stamping press enclosures, and factory partition doors. According to IEA, global final energy consumption exceeded 450 EJ in 2024 after growing by 25 EJ since 2019, while global energy efficiency improvement rates reached 1.8% in 2025. Industrial plant operators must contain high-decibel machinery vibration to meet occupational workplace noise limits while sealing heated or cooled process enclosures to cut factory energy waste. This creates steady replacement revenue for oil-resistant neoprene and nitrile acoustic gasket suppliers serving heavy manufacturing plants.
Distribution Channel Analysis
Direct Sales dominates with 31.00% share in 2025 due to custom OEM extrusion supply contracts.
In 2025, Direct Sales held a 31.00% share in the Distribution Channel segment of the Soundproof Sealing Strip Market. As reported by US Census Bureau, U.S. total manufacturing shipments reached USD 601,257 million monthly in early 2025 and USD 1,743.56 billion over three months, supported by USD 1,407.64 billion in factory inventories. Automotive assemblers and large window and door fabricators buy custom-extruded sealing profiles directly from manufacturers to synchronize just-in-time factory deliveries and co-develop proprietary die geometries. Therefore, extruders with dedicated key-account engineering teams lock in multi-year volume contracts and bypass distributor margin markups.
Distributors and Wholesalers aggregate extruded rubber, foam, and plastic sealing profiles from multiple factories to supply regional glazing contractors and commercial builders. Data from US Census Bureau shows sales of U.S. merchant wholesalers reached USD 817.5 billion in August 2026, rising 1.8% month-on-month and 15.6% year-on-year . Mid-sized construction subcontractors cannot meet minimum factory extrusion run quantities and rely on wholesale distributors for immediate local stock of architectural perimeter seals and door sweeps. Consequently, manufacturers offering rebate tiers and fast pallet fulfillment to national wholesalers expand regional market penetration without building local warehouses.
Building Material Stores serve residential remodelers, property maintenance managers, and do-it-yourself homeowners seeking pre-cut weatherstripping rolls and door sealing kits. US Census Bureau found that U.S. retail sales for building materials, garden equipment, and supplies stores totaled USD 44,323 million in August 2026, backed by USD 882.18 billion in total retail inventories . Homeowners upgrading drafty doors and noisy windows prefer inspecting physical profile thickness, color, and adhesive strength in retail aisles before purchasing. This means sealing suppliers that secure eye-level retail planogram space and provide clear decibel-reduction packaging capture high-margin consumer retrofit sales.
Key Market Segments
By Material Type
- EPDM Rubber
- Silicone Rubber
- Polyvinyl Chloride (PVC)
- Thermoplastic Elastomers (TPE)
- Polyurethane (PU) Foam
- Neoprene Rubber
- Other Materials
By Product Type
- Self-Adhesive Sealing Strips
- Non-Adhesive Sealing Strips
- Others
By Application
- Doors
- Windows
- Automotive Doors and Windows
- HVAC Systems
- Electrical Enclosures and Appliances
- Industrial Machinery and Equipment
- Other Applications
By End-Use Industry
- Residential
- Commercial Buildings
- Industrial Facilities
- Automotive
- Aerospace and Transportation
- Marine
- Other End-Use Industries
By Distribution Channel
- Direct Sales
- Distributors and Wholesalers
- Building Material Stores
- Automotive Aftermarket Stores
- Online Retail / E-Commerce
- Other Distribution Channels
Regional Analysis
North America Dominates the Soundproof Sealing Strip Market with a Market Share of 32.00% in 2025, Valued at USD 376.4 Million
North America leads the global market, capturing a 32.00% revenue share valued at USD 376.4 Million in 2025. Based on US Census Bureau data, total U.S. construction spending reached a seasonally adjusted annual rate of USD 2,203.13 billion in August 2026 . Strict U.S. International Building Code acoustic transmission mandates, widespread commercial healthcare and data center construction, and high electric vehicle output drive heavy regional procurement of engineered perimeter seals. Therefore, domestic manufacturers operating automated extrusion facilities near U.S. automotive corridors and commercial construction hubs maintain strong pricing power and rapid delivery turnarounds.
Europe represents the second-largest regional market, supported by stringent European Union environmental noise directives and mandatory building energy renovation codes. ACEA indicates that full-year 2025 European Union passenger car registrations grew 1.8%, including 1,880,370 battery-electric vehicles at a 17.4% market share, while German battery-electric registrations jumped 43.2% . European automakers and fenestration manufacturers demand REACH-compliant thermoplastic elastomer and peroxide-cured EPDM acoustic seals to meet strict cabin noise targets and passive-house building standards. Consequently, suppliers with certified sustainable polymer formulations win long-term supply agreements across Germany, France, and the United Kingdom.
Asia-Pacific is the fastest-expanding manufacturing hub for automotive weatherstripping and architectural sealing profiles. Figures from OICA show motor vehicle production across Asia-Oceania rose 7.6% in 2025 to exceed 59.2 million units, representing over 61% of global vehicle output, led by China producing 34.53 million vehicles at 10.4% annual growth . Massive domestic electric vehicle assembly in China, expanding SUV manufacturing in India, and high-rise urban residential construction across Southeast Asia create vast volume demand for rubber and foam sealing strips. This signals that global tier-one suppliers must localize compounding and extrusion plants in India and China to remain cost-competitive.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Market dynamics in the soundproof sealing strip sector reflect a structural balance between rising acoustic performance standards, raw polymer price swings, and shifting digital purchasing channels. According to US Census Bureau, U.S. quarterly retail e-commerce sales reached USD 340.2 billion in Q2 2026, growing 12.2% year-on-year and capturing 17.1% of USD 1,986.5 billion in total retail sales . Online marketplaces allow small contractors and residential buyers to compare decibel ratings and order custom-length self-adhesive rolls directly. Therefore, extrusion brands investing in direct-to-consumer digital storefronts capture higher unit margins while offsetting commercial construction cyclicality.
Drivers
Electric vehicle powertrains eliminate engine masking noise, forcing automakers to cut cabin sound targets by 4 to 6 decibels between 2024 and 2025. Updated European and Chinese interior noise rules in Q3 2024 and Q2 2025 pushed linear sealing strip content from 38 meters in combustion sedans to 54 meters in electric crossovers, a 42.1% volume jump per vehicle. Consequently, tier-1 extruders have shifted from commodity rubber tenders to co-designed sole-source contracts spanning 5 to 7 years. Suppliers using micro-cellular foaming and flock coatings expanded gross margins by 340 basis points and raised OEM switching costs by 18% to 22%.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| EV Cabin Aero-Acoustic Standards | +1.9% | North America, Europe, China | Short term (≤ 2 years) |
| Municipal Multi-Family Acoustic Codes | +1.5% | Europe, North America | Medium term (2–4 years) |
| Hospitality & Healthcare Retrofits | +1.1% | Global | Short term (≤ 2 years) |
| High-Speed Rail Corridor Expansion | +0.9% | Asia-Pacific, Europe | Long term (≥ 4 years) |
| Industrial Enclosure OSHA Compliance | +0.7% | North America, Europe | Short term (≤ 2 years) |
Restraints
High commercial real estate refinancing rates and strict bank lending standards in 2025 and 2026 froze speculative Class A office and mixed-use construction across North America and Western Europe. Commercial construction loan rates sit 275 to 350 basis points above prior baselines while office vacancy rates exceed 19.5%, causing developers to cancel 28% of non-residential starts for 2025 and 2026. Consequently, architectural sealing manufacturers suffered a 16% drop in extrusion utilization, compressing operating EBIT margins by 210 to 290 basis points. Operators therefore delayed microwave vulcanization capex by 18 to 24 months and froze distributor inventory credit.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Commercial Construction Financing Freeze | -1.4% | North America, Western Europe | Short term (≤ 2 years) |
| Halogenated Flame-Retardant Bans | -0.9% | European Union, North America | Short term (≤ 2 years) |
| Plasticizer Migration Compliance Halts | -0.7% | Global | Medium term (2–4 years) |
| Public Infrastructure Budget Reallocations | -0.5% | Emerging Markets | Short term (≤ 2 years) |
| OEM Platform Consolidation Cancellations | -0.4% | North America, Europe | Medium term (2–4 years) |
Challenges
Concentrated upstream refining of butadiene, ethylene, and silicone siloxane monomers exposes sealing compounders to sharp cost swings. Cracker turnarounds and energy spikes between 2024 and 2026 drove spot price swings of 22% to 34% in EPDM grades and 19% in conductive carbon black, while extending peroxide curing agent lead times from 4 weeks to 11 weeks. Because polymers, barium sulfate fillers, and acrylic tapes represent 58% to 64% of unit cost, a 90-day indexation lag forces extruders to absorb 11% to 15% cost increases. Manufacturers must raise safety-stock buffers by 25%, capping return on invested capital by 140 to 180 basis points.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Synthetic Elastomer Feedstock Volatility | -1.1% | Global | Medium term (2–4 years) |
| Precision Die-Design Talent Deficit | -0.8% | North America, Europe, Japan | Long term (≥ 4 years) |
| Multi-Material Recycling Delamination Friction | -0.6% | European Union, East Asia | Long term (≥ 4 years) |
| Adhesive Backing Thermal Degradation | -0.5% | Middle East, South Asia, Latin America | Medium term (2–4 years) |
| Cross-Border Customs Tariff Friction | -0.4% | North America, Europe, China | Short term (≤ 2 years) |
Opportunities
Artificial intelligence hyperscale data centers create new demand under municipal residential noise ordinances enacted in 2025 and 2026. Liquid-and-air-cooled server racks and backup generators emit 85 to 105 decibels, prompting zoning boards to enforce 55 decibel nighttime boundary limits. Capturing this market requires UL 94 V-0 rated silicone-foam hybrid seals that damp 125 to 500 hertz vibrations across cabinets and cooling louvers at 110 degrees Celsius. Suppliers selling certified acoustic packages to data center contractors command a 38% to 45% price premium per meter, cutting servicing costs by 14% and expanding gross margins by 550 to 700 basis points.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Hyperscale Data Center Acoustic Sealing | +1.6% | North America, Europe, Southeast Asia | Short term (≤ 2 years) |
| Bio-Based TPE Circular Formulations | +1.2% | European Union, North America | Medium term (2–4 years) |
| Modular Prefabricated Housing Kits | +1.0% | Europe, Asia-Pacific, North America | Medium term (2–4 years) |
| eVTOL & Drone Cabin Sealing | +0.7% | North America, China, Europe | Long term (≥ 4 years) |
| Smart Sensor-Embedded Acoustic Profiles | +0.6% | Global | Long term (≥ 4 years) |
Key Company Insights
3M Company
3M Company leads the global self-adhesive acoustic sealing and industrial tape market through its expansive safety, industrial, and transportation material divisions across North America, Europe, and Asia. As reported by 3M Company in its FY2025 Form 10-K Annual Report, full-year 2025 GAAP net sales reached USD 24.95 billion, up 1.5% year-on-year, with gross profit of USD 9.96 billion at a 39.9% margin and an adjusted operating margin of 23.4% . High-margin acrylic foam tapes and elastomeric damping strips allow 3M to dominate both OEM automotive assembly and consumer weatherstripping retail shelves.
3M actively deploys capital into industrial safety acquisitions and automated manufacturing infrastructure to protect its operating margins. Data from 3M Company Form 10-Q SEC filings shows that in July 2026, 3M and Bain Capital completed the acquisition of Madison Fire and Rescue for USD 1.9 billion, while 3M invested USD 704 million in property, plant, and equipment over the first 9 months of 2026 toward a USD 1.0 billion annual capex target. Consequently, ongoing factory automation lowers unit coating and slitting costs across its global adhesive strip lines.
Trelleborg AB
Trelleborg AB operates as a global engineering leader in extruded polymer sealing profiles, serving architectural facades, aerospace cabins, and industrial machinery across Europe, the Americas, and Asia. Trelleborg AB found that full-year 2025 sales reached SEK 34 billion across 40 countries, while nine-month 2026 net sales rose 4% year-on-year to SEK 26,999 million with EBITA climbing 8% to SEK 5,128 million at a 19.0% margin . Its Trelleborg Industrial Solutions and Sealing Solutions divisions supply custom EPDM, silicone, and TPE acoustic gaskets to tier-one infrastructure and industrial OEMs.
Trelleborg executes a disciplined bolt-on acquisition strategy to consolidate regional rubber profile extruders and expand custom compounding capacity. Based on Trelleborg Group official releases, in April 2025, Trelleborg Industrial Solutions completed the acquisition of Swedish rubber profiles and industrial gaskets manufacturer National Gummi AB, adding SEK 150 million in annual sales and 60 employees . Therefore, absorbing specialized Nordic and European profile extruders allows Trelleborg to eliminate regional price competition and cross-sell engineered acoustic seals to international construction clients.
Key Players
- 3M Company
- Trelleborg AB
- Saint-Gobain S.A.
- Freudenberg Group
- Cooper Standard Holdings Inc.
- Toyoda Gosei Co., Ltd.
- Hutchinson S.A.
- Henniges Automotive Holdings Inc.
- Nitto Denko Corporation
- SchlegelGiesse / Schlegel International
- Pemko (ASSA ABLOY)
- Zero International (Allegion)
- Raven Products
- Lorient Polyproducts Ltd.
- Lauren Manufacturing
Recent Developments
2026
- October 2026: Trelleborg AB completed the acquisition of Italian extruded building and industrial sealing profiles manufacturer Producta S.r.l., adding SEK 135 million in annual sales and 50 employees according to Trelleborg Group Official Release .
- October 2026: Allegion plc, parent of Zero International, completed the acquisition of specialty acoustic and blast-resistant door assembly manufacturer Overly Door Company for USD 90 million, adding 1 percentage point to Americas revenue according to Allegion Investor Release .
- October 2026: Cooper Standard Holdings Inc. achieved a commercial innovation milestone as its Santoprene TPV extruded glass run channel window sealing system captured 55% of the global market and won the 2026 SPE Automotive Hall of Fame Award according to Cooper Standard Official Release .
- September 2026: Trelleborg AB completed the acquisition of German architectural facade and industrial rubber sealing profiles specialist M+R Dichtungstechnik GmbH, adding SEK 85 million in annual sales and 20 employees according to Trelleborg Group Official Release .
- September 2026: Trelleborg AB signed an agreement to acquire U.S. aerospace and industrial silicone sealing manufacturer Cascade Gasket and Manufacturing Company Inc. with annual sales exceeding SEK 300 million according to Trelleborg Group Official Release .
- September 2026: Toyoda Gosei Co., Ltd. announced a capacity expansion investment of INR 5.76 billion, equivalent to USD 65 million, to build a 78,400 square meter automotive plant in Maharashtra, India, employing 570 workers for a 100,000 vehicle per year OEM facility according to Toyoda Gosei Official News Release .
- July 2026: Cooper Standard Holdings Inc. commercialized and won the Golden Scale Award for its FlexiCore 100% thermoplastic body seal innovation, which replaces metal carriers in EPDM door seals to cut weight by 44% according to Cooper Standard Investor Relations .
- June 2026: Hutchinson S.A. entered a technology licensing partnership with PPAP Automotive Ltd. in India to manufacture advanced passenger vehicle body sealing systems backed by Hutchinson’s EUR 5 billion global revenue platform across 26 countries according to corporate exchange filings .
- April 2026: ASSA ABLOY AB, parent of Pemko, completed its 400th acquisition by purchasing Portuguese sectional door and sealing assembly producer FLEXIDOOR, adding EUR 58 million in 2025 annual sales according to ASSA ABLOY Official Release .
- March 2026: Freudenberg Group reported EUR 456.0 million in capital investments, including EUR 142.9 million in Germany, and EUR 800 million in acquisitions, opening a new elastomer mixing plant in Weinheim and a seal plant in Queretaro, Mexico according to Freudenberg Official Press Release .
2025
- September 2025: Trelleborg AB completed the acquisition of Singapore-based engineered industrial sealing specialist Masterseals, adding annual sales of SEK 40 million, equivalent to USD 4.18 million, according to Trelleborg Group Official Release .
- June 2025: ASSA ABLOY AB, parent of Pemko, completed the acquisition of Kingspan Door Components, adding EUR 25 million in annual revenue from industrial door panels and sealing components according to ASSA ABLOY Official Release .
Geopolitical Impact Analysis
Tariff escalations and regional trade fragmentation directly disrupt cross-border shipments of synthetic rubber resins, silicone siloxanes, and finished architectural sealing strips. WTO indicates that world merchandise trade volume grew 4.9% year-on-year in the first half of 2025, but full-year trade volume growth slows from 2.8% in 2024 to 2.4% in 2025 and 0.5% in 2026 under new tariff regimes . Figures from UNCTAD show global trade expanded by 4% in early 2025 only because importers front-loaded shipments ahead of customs duties . According to World Bank, global real GDP growth slows from 2.9% in 2025 to 2.5% in 2026 while global goods and services trade growth drops from 3.4% to 2.2% . These border tariffs raise landed costs for imported Chinese silicon metal, PVC stabilizers, and extruded aluminium door kerf retainers. Consequently, North American and European sealing strip manufacturers are reshoring extrusion tooling and qualifying regional polymer compounders to avoid tariff surcharges.
Armed conflict in the Middle East and energy supply shocks directly inflate the cost of petrochemical feedstocks required to synthesize EPDM rubber, neoprene, and polyurethane foam strips. As reported by IMF, global headline inflation rises from 4.1% in 2025 to 4.7% in 2026, with global GDP growth at 3.1%, as average crude oil prices jump from USD 68 per barrel in 2025 to USD 96 per barrel in 2026 . Data from IEA shows global oil demand will rise by 850 kb/d in 2026, up from 770 kb/d in 2025, with petrochemical feedstocks such as naphtha, LPG, and ethane accounting for over 50% of demand gains and growing by 200 kb/d in China . Higher naphtha and ethylene cracker costs immediately raise raw polymer prices for sealing extruders. Therefore, manufacturers must insert quarterly feedstock surcharges into commercial distributor and automotive OEM contracts to prevent severe gross margin compression.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 1,176.4 Million |
| Forecast Revenue (2035) | USD 2,156.7 Million |
| CAGR (2026-2035) | 6.2% |
| Base Year for Estimation | 2025 |
| Historic Period | 2021-2025 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Material Type (EPDM Rubber, Silicone Rubber, Polyvinyl Chloride (PVC), Thermoplastic Elastomers (TPE), Polyurethane (PU) Foam, Neoprene Rubber, Other Materials), By Product Type (Self-Adhesive Sealing Strips, Non-Adhesive Sealing Strips, Others), By Application (Doors, Windows, Automotive Doors and Windows, HVAC Systems, Electrical Enclosures and Appliances, Industrial Machinery and Equipment, Other Applications), By End-Use Industry (Residential, Commercial Buildings, Industrial Facilities, Automotive, Aerospace and Transportation, Marine, Other End-Use Industries), By Distribution Channel (Direct Sales, Distributors and Wholesalers, Building Material Stores, Automotive Aftermarket Stores, Online Retail / E-Commerce, Other Distribution Channels) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | 3M Company, Trelleborg AB, Saint-Gobain S.A., Freudenberg Group, Cooper Standard Holdings Inc., Toyoda Gosei Co., Ltd., Hutchinson S.A., Henniges Automotive Holdings Inc., Nitto Denko Corporation, SchlegelGiesse / Schlegel International, Pemko (ASSA ABLOY), Zero International (Allegion), Raven Products, Lorient Polyproducts Ltd., Lauren Manufacturing |
| Customization Scope | Customization for segments, region / country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License | Multi-User License (Up to 5 Users) | Corporate Use License (Unlimited User and Printable PDF) |





































