


Report Overview
Global Sapphire Jewelry Market size is expected to be worth around USD 1.9 Billion by 2035 from USD 1.0 Billion in 2025, growing at a CAGR of 6.5% during the forecast period 2026 to 2035. Sapphire jewelry combines faceted natural or synthetic corundum gemstones with precious metal mountings to serve bridal engagement, luxury fashion, and heritage wealth preservation buyers worldwide. Retail chains and custom jewelers therefore capture higher unit margins compared to commoditized clear stones.
Wholesale gemstone dealers, lapidary cutting centers, and fine jewelry retailers form a tightly integrated value chain serving bridal, milestone gifting, and high-jewelry auction buyers. According to USGS, U.S. imports for consumption of gemstones totaled USD 11.0 Billion in 2025, dropping 44% from USD 19.6 Billion in 2024 as apparent consumption hit USD 9.4 Billion. Consequently, diamond import contraction pushes retail buyers toward higher-margin colored corundum inventory to protect store revenue.
Key Takeaways
- Global Sapphire Jewelry Market was valued at USD 1.0 Billion in 2025.
- Market revenue is projected to reach USD 1.9 Billion by 2035.
- Global sales will expand at a CAGR of 6.5% during the forecast period from 2026 to 2035.
- Rings led the Type of Jewellery segment with a 41.23% market share in 2025, while Necklaces represent the fastest growing category.
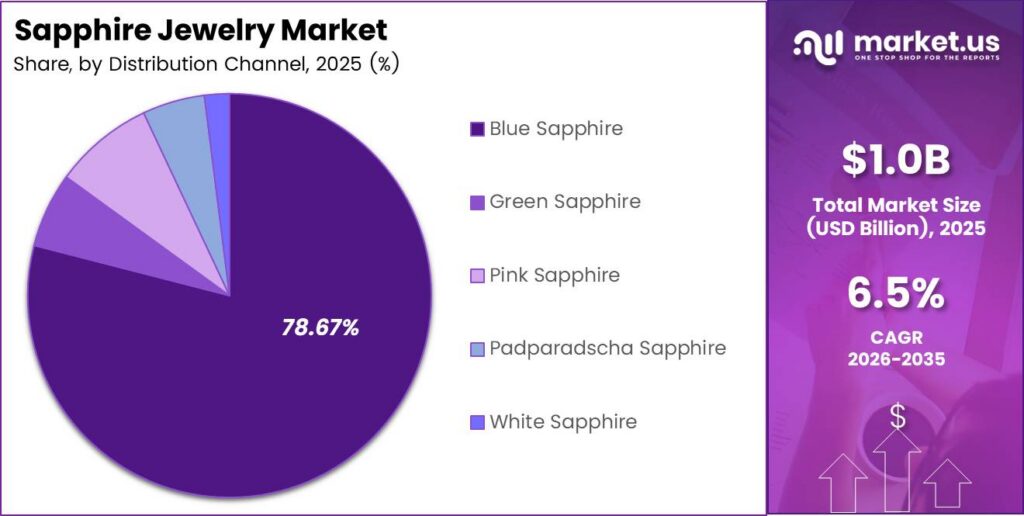
- Blue Sapphire dominated the Sapphire Color segment with a 78.67% share in 2025, whereas Green Sapphire is the fastest growing color segment.
- Specialty Jewelry Stores captured a 67.34% share of the Distribution Channel segment in 2025, while Brick-and-Mortar Retailers represent the fastest growing channel.
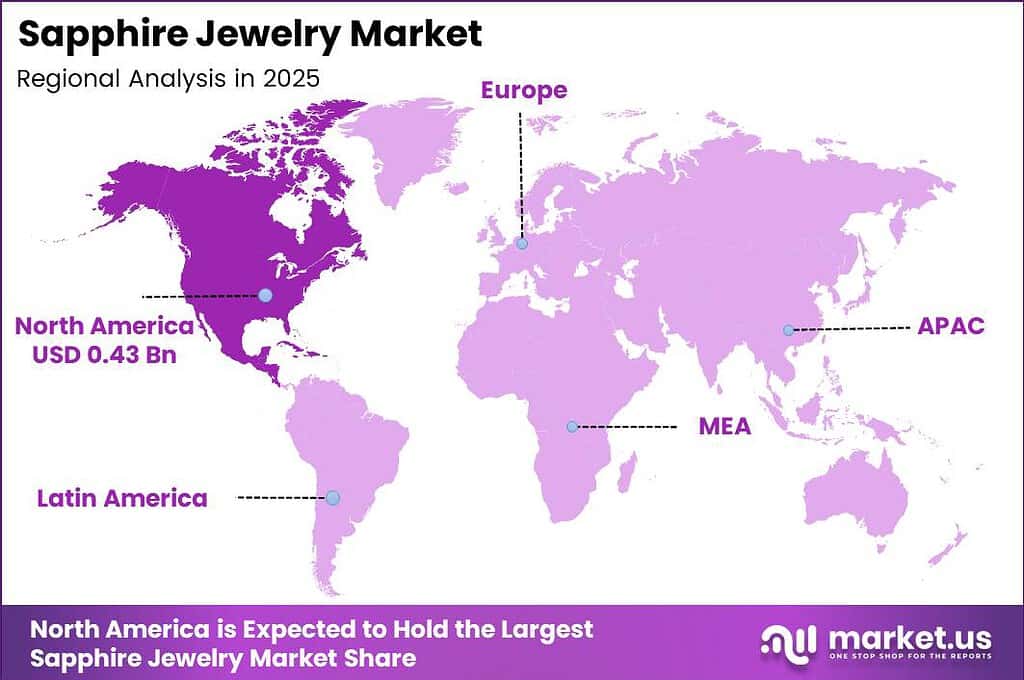
- North America dominated the global market in 2025 with a 43.78% share valued at USD 0.43 Billion, while Middle East and Africa is the fastest growing region.
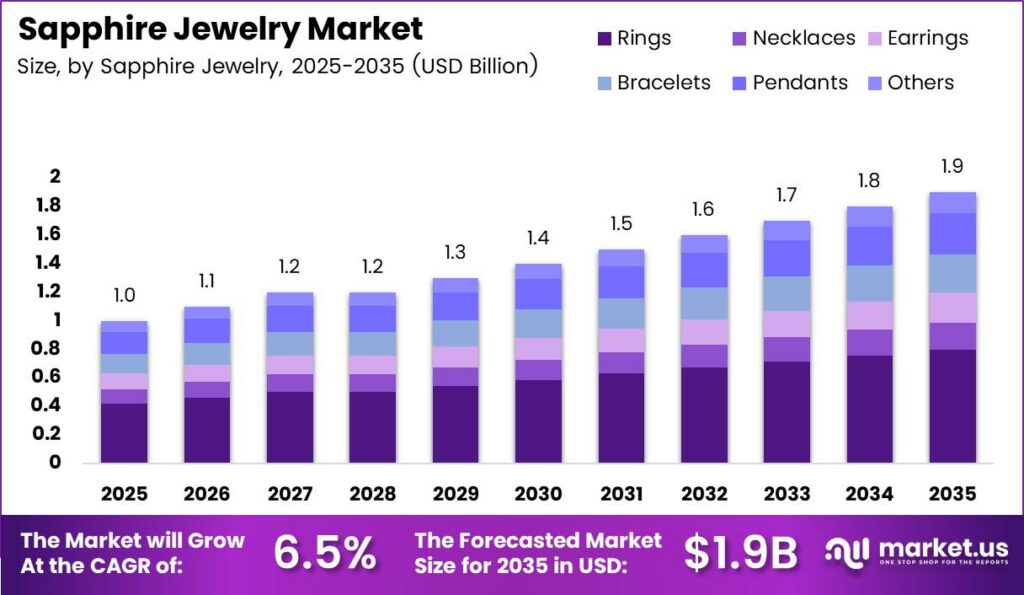
Central bank monetary policies, bullion reserve accumulation, and cross-border customs duties directly govern precious metal mounting costs and retail pricing strategies across jewelry manufacturing hubs. As reported by World Bank, global precious metal prices jumped 41% in 2025 and are projected to climb another 5% in 2026 after gold passed USD 4,300 per ounce . Therefore, jewelry manufacturers must engineer lighter 14-karat settings and semi-mount frameworks to preserve consumer affordability and protect wholesale margins.
Upstream mining operators are standardizing rough corundum grading to give mid-tier jewelry manufacturers predictable commercial parcel supply. In June 2026, Gemfields Group held its first Trade Select auction introducing commercial sapphire categories alongside rubies, generating USD 23.1 Million across 348,409 carats sold with 93.2% weight clearance across 82 of 89 lots . This signals that organized rough auctions reduce supply bottlenecks for calibrated jewelry makers and stabilize seasonal wholesale procurement budgets.
North America leads the global market with a 43.78% revenue share in 2025, supported by deep bridal customization spending and concentrated specialty retail chains. Data from NRF shows U.S. shoppers were projected to spend a record USD 7.5 Billion on Mother’s Day jewelry in 2026, up 10% from USD 6.8 Billion in 2025 across USD 38.0 Billion in holiday outlays. This reflects resilient holiday gifting budgets that sustain premium sapphire turnover for regional jewelers.
Major luxury houses are simultaneously expanding vertical production capacity in Europe to secure master goldsmith labor and shorten bespoke delivery lead times. In May 2025, an Italian luxury jeweler inaugurated its expanded Valenza manufacturing complex, growing floor space from 14,000 to 33,000 square meters to double output and hire 500 artisans by 2029 while unveiling a 123-carat Sri Lankan sapphire. Consequently, vertically integrated manufacturers lock in skilled lapidary capacity ahead of independent rivals.
Type of Jewellery Analysis
Rings dominates with 41.23% share in 2025 due to strong bridal center-stone substitution demand.
In 2025, Rings held a 41.23% share in the Type of Jewellery segment of the Sapphire Jewelry Market. NRF found that U.S. shoppers planned to spend USD 7.0 Billion on Valentine’s Day jewelry in 2026, up 8% from USD 6.5 Billion in 2025, while Signet Jewelers agreed in May 2026 to buy bespoke ring jeweler The Clear Cut with a USD 30,000 average order value . Corundum hardness of 9 on the Mohs scale resists daily wear in bridal prongs, letting jewelers expand custom margins.
Necklaces represent the fastest growing category in the Type of Jewellery segment as affluent collectors acquire statement collar pieces and layered gemstone chains. Based on UN Comtrade data, UK precious-metal jewelry exports reached USD 3.91 Billion in 2025 including USD 703.91 Million to Saudi Arabia, while Tiffany unveiled a 184.15-carat unheated Sri Lankan sapphire platinum necklace in September 2026 . Articulated gold links distribute heavy carat loads across the collarbone, enabling luxury maisons to command seven-figure bespoke prices.
Earrings serve as a core repeat-purchase category for self-purchasing women and milestone gift buyers seeking matched calibrated sapphire studs and drop silhouettes. UN Comtrade indicates that Hong Kong imported USD 8.38 Billion, or 80,514 kilograms, of precious-metal jewelry articles from mainland China in 2025 alongside USD 376.57 Million imported by Macao . Matched pair calibration requires precise optical color sorting of small rough parcels, allowing wholesalers with automated grading hardware to capture steady replenishment orders.
Sapphire Color Analysis
Blue Sapphire dominates with 78.67% share in 2025 due to royal heritage and bridal preference.
In 2025, Blue Sapphire held a 78.67% share in the Sapphire Color segment of the Sapphire Jewelry Market. Figures from UN Comtrade show Sri Lanka exported USD 98.31 Million across 1,644,330 carats of worked rubies, sapphires, and emeralds in 2024, while Graff Diamonds debuted a Paris Couture suite featuring a 31-carat unheated blue sapphire in January 2026 . Trace titanium and iron charge transfers create stable royal blue saturation during heat treatment, giving jewelers reliable color consistency and strong resale liquidity.
Green Sapphire stands as the fastest growing category in the Sapphire Color segment as younger bridal buyers seek earthy, traceable alternatives to traditional stones. According to UN Comtrade, Australia exported USD 3.24 Million of worked rubies, sapphires, and emeralds in 2024, led by USD 1.21 Million shipped to Hong Kong and USD 869.51 Thousand sent to Thailand . Higher ferric iron concentrations in basaltic alluvial deposits produce distinctive olive and teal hues, letting independent jewelers differentiate custom bridal lines at accessible price points.
Pink Sapphire attracts fashion-forward luxury consumers and bridal halo designers looking for vivid pastel to magenta gemstones with superior durability over tourmaline. As reported by UN Comtrade, global top-five hubs imported USD 126.64 Million of worked corundum and emeralds from Madagascar in 2024, including 1,015,000 carats worth USD 29.59 Million shipped into Thailand . Trace chromium impurities within aluminum oxide crystal lattices generate bright pink fluorescence, allowing jewelry brands to market feminine pavé collections with minimal stone breakage during setting.
Distribution Channel Analysis
Specialty Jewelry Stores dominates with 67.34% share in 2025 due to certified gemological advisory services.
In 2025, Specialty Jewelry Stores held a 67.34% share in the Distribution Channel segment of the Sapphire Jewelry Market. Data from US Census Bureau shows U.S. specialty jewelry stores under NAICS 44831 generated USD 39.53 Billion in annual retail sales across employer establishments in 2024 . High-value natural sapphires exhibit complex pleochroism and origin price spreads that require in-person loupe inspection under calibrated store lighting, enabling specialized jewelers to defend full retail markups and attach extended warranty plans.
Brick-and-Mortar Retailers represent the fastest growing channel as luxury department stores and mono-brand boutiques invest in VIP experiential salons to capture affluent foot traffic. Eurostat found that EU calendar-adjusted retail trade volume rose 0.9% year-over-year in September 2026, while Tiffany opened a 15,000-square-foot flagship store at South Coast Plaza in California in June 2026 . Physical try-on reduces buyer hesitation on five-figure gemstone mountings, prompting retail landlords and luxury groups to prioritize prime shopping district leases.
Online Retailers capture digitally native engagement shoppers who compare loose gemstone certificates, 360-degree high-magnification videos, and custom 3D ring settings before purchasing from home. Based on US Census Bureau data, U.S. quarterly retail e-commerce sales reached USD 340.2 Billion in Q2 2026, climbing 12.2% year-over-year to claim 17.1% of USD 1,986.5 Billion in total retail trade . Direct digital fulfillment eliminates physical showroom overhead on calibrated loose sapphires, allowing omnichannel jewelers to price competitively while scaling national customer acquisition.
Key Market Segments
By Type of Jewellery
- Rings
- Necklaces
- Earrings
- Bracelets
- Pendants
- Others
By Sapphire Color
- Blue Sapphire
- Green Sapphire
- Pink Sapphire
- Padparadscha Sapphire
- White Sapphire
By Distribution Channel
- Specialty Jewelry Stores
- Brick-and-Mortar Retailers
- Online Retailers
- Others
Regional Analysis
North America Dominates the Sapphire Jewelry Market with a Market Share of 43.78% in 2025, Valued at USD 0.43 Billion
North America leads the global market with a 43.78% share valued at USD 0.43 Billion in 2025, propelled by widespread non-diamond bridal adoption and concentrated mall and independent jewelers. UN Comtrade indicates that U.S. precious-metal jewelry imports hit USD 12.78 Billion across 297,279 kilograms in 2024, while Canadian imports reached USD 1.14 Billion across 21,370 kilograms . Therefore, overseas lapidary exporters prioritize calibrated Montana and Ceylon sapphire assortments tailored to North American bespoke bridal wholesalers.
Middle East and Africa represents the fastest growing region as duty-free Gulf retail hubs, tourist wealth inflows, and cultural gemstone consumption accelerate luxury jewelry turnover. Figures from UN Comtrade show UAE precious-metal jewelry imports reached USD 16.43 Billion in 2024, alongside USD 1.70 Billion across 75,859 kilograms into Saudi Arabia and USD 719.07 Million into Qatar . Consequently, global jewelry houses are expanding flagship boutiques and regional wholesale distribution hubs across Dubai, Riyadh, and Doha.
Europe, Asia Pacific, and Latin America provide vital manufacturing scale and expanding middle-class demand. According to OECD, European retail serves 450 Million consumers spending 33.3% of household budgets in shops, while Brazil’s GDP will grow 1.6% in 2026 and 2.1% in 2027 . As reported by UN Comtrade, India exported USD 11.04 Billion of precious-metal jewelry in 2024 as China imported USD 3.58 Billion . This creates balanced global demand for sapphire exporters.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Pricing power and inventory margins in the sapphire jewelry sector depend heavily on raw precious metal costs, alluvial rough availability, and shifting bridal preferences away from clear stones. Data from World Bank shows overall global commodity prices were projected in October 2026 to climb 23% during 2026 as supply shocks push metals and minerals benchmarks to all-time peaks . Consequently, jewelry manufacturers must balance rising gold mounting costs against premium colored gemstone customization margins to protect profitability.
Drivers
Natural diamond wholesale benchmarks fell 26% between 2024 and 2026 alongside steep synthetic diamond retail discounting, steering bridal buyers toward colored corundum center stones. Industry surveys through 2025 and 2026 show up to 38% of engagement shoppers evaluate sapphires as primary center stones. Independent and chain jewelers therefore shifted budgets from pre-mounted diamond solitaires to loose Montana, Sri Lankan, and Madagascar sapphires in custom settings, cutting acquisition costs by 12% to 18% and lifting gross margins by 450 to 700 basis points.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Non-Diamond Bridal Center-Stone Substitution | +2.1% | North America, Europe, Australia | Short term (≤ 2 years) |
| Fancy-Color Parti and Teal Sapphire Demand | +1.5% | United States, United Kingdom, Japan | Short term (≤ 2 years) |
| Omnichannel Bespoke 3D Ring Customization | +1.2% | Global | Medium term (2–4 years) |
| Astrological and Cultural Heritage Consumption | +1.0% | India, Southeast Asia, Middle East | Short term (≤ 2 years) |
| High-Jewelry Auction Price Spillover | +0.8% | Switzerland, Hong Kong, France | Medium term (2–4 years) |
Restraints
International gold benchmarks climbed 67% in 2025 and held near USD 3,913 per troy ounce in October 2026, raising retail prices for finished sapphire gold jewelry. Because 14-karat and 18-karat mountings represent 50% to 75% of commercial manufacturing cost, every USD 100 bullion gain adds USD 3.22 per gram to alloy cost, cutting global fabrication tonnage by 17% to 18%. Mid-tier wholesalers and chains consequently faced 165 to 270 basis points of margin compression and a 16.7% rise in inventory financing outlays, delaying store expansion.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Record Bullion Input Cost Inflation | -1.6% | Global | Short term (≤ 2 years) |
| Section 301 Forced-Labor Jewelry Tariffs | -1.1% | United States, India, Thailand, Sri Lanka | Short term (≤ 2 years) |
| Cross-Border De Minimis Duty Repeal | -0.7% | United States, China, Hong Kong | Short term (≤ 2 years) |
| Alluvial Export Licensing Suspensions | -0.6% | Madagascar, Sri Lanka, East Africa | Medium term (2–4 years) |
| Elevated Working-Capital Financing Rates | -0.5% | India, Europe, North America | Short term (≤ 2 years) |
Challenges
Depletion of near-surface alluvial gravel deposits in Madagascar’s Ilakaka and Sakaraha basins and Sri Lanka’s Ratnapura pockets has created severe scarcity for clean unheated rough above 5 to 10 carats. Field checks from late 2025 and 2026 show 50-carat to 100-carat parcels have disappeared, while low-mechanization pits achieve cuttable yields below 15% to 22% after heat treatment. Luxury houses face 90 to 150 day sourcing delays, forcing shifts toward mine off-take retainers, optical rough scanners saving 4% to 7% yield, and melee cluster settings.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Fine Large-Carat Rough Depletion | -1.2% | Madagascar, Myanmar, Sri Lanka | Long term (≥ 4 years) |
| Artisanal Supply Chain Opacity | -0.9% | East Africa, South Asia, Europe | Medium term (2–4 years) |
| Undisclosed Beryllium Treatment Fraud | -0.7% | Global | Medium term (2–4 years) |
| Master Lapidary Talent Deficit | -0.6% | Thailand, Sri Lanka, India | Long term (≥ 4 years) |
| Multi-Lab Origin Grading Divergence | -0.4% | Switzerland, United States, Hong Kong | Medium term (2–4 years) |
Opportunities
Large reserves of estate, heirloom, and post-consumer sapphire jewelry sit unmonetized outside branded channels across Western and Japanese wealth cohorts. Structured buyback, precision optical recutting of worn vintage crowns, and certified pre-owned resale remain fragmented across pawn and auction houses. Early retail movers building trade-in programs can buy secondary sapphires at 30% to 45% below primary wholesale cost, spend USD 45 to USD 110 per stone on repolishing and lab certification, and pair them with recycled 18-karat gold to expand gross margins by 800 to 1,200 basis points.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Certified Pre-Owned Recut Monetization | +1.6% | North America, Western Europe, Japan | Medium term (2–4 years) |
| Blockchain Digital Product Passports | +1.3% | European Union, United States, Switzerland | Medium term (2–4 years) |
| Precision Lab-Grown Contemporary Demi-Fine | +1.1% | Global | Short term (≤ 2 years) |
| Men’s Luxury Signet and Watch-Set Lines | +0.9% | Middle East, East Asia, North America | Medium term (2–4 years) |
| Duty-Exempt Bilateral Hub Relocation | +0.7% | United Arab Emirates, European Union, India | Short term (≤ 2 years) |
Key Company Insights
Tiffany & Co.
Tiffany & Co. anchors the ultra-luxury bridal and high-jewelry corundum tier through global flagship salons across the Americas, Europe, and Asia. LVMH Annual Shareholder Report found that LVMH Watches and Jewelry generated EUR 10,486 Million, or USD 12.56 Billion, in 2025 revenue with 3% organic expansion and EUR 1,514 Million in recurring operating profit at a 14.4% margin . Strong divisional cash generation lets Tiffany outbid smaller rivals for unheated Kashmir, Burmese, and Sri Lankan sapphires.
Tiffany continues scaling experiential Asian flagship real estate to capture domestic VIP collectors and inbound luxury tourists. Based on LVMH Official Newsroom data, Tiffany opened its largest Asian flagship store in Ginza, Tokyo in July 2025, featuring over 2,500 square meters of retail space inside a 66-meter architectural glass tower . Dedicated private high-jewelry viewing salons inside mega-flagships accelerate conversion rates on multi-million-dollar sapphire suites while insulating the maison from mid-tier mall traffic slowdowns.
Cartier
Cartier leads global hard-luxury jewelry design with iconic panther motifs, royal heritage sapphire commissions, and an extensive boutique network spanning Europe, North America, Japan, and the Middle East. Richemont Financial Filings indicates that Richemont Jewellery Maisons posted EUR 9.15 Billion, or USD 10.08 Billion, in H1 FY2027 sales, climbing 18% with a 35.3% operating margin after EUR 15,328 Million in FY2025 revenue . Industry-leading operating margins fund multi-year rough sapphire stockpiling and proprietary lapidary R&D.
Cartier regularly stages museum-grade high-jewelry exhibitions in top Asian wealth hubs to drive bespoke collector commissions. Figures from Cartier show the maison unveiled its Le Choeur des Pierres Chapter II high-jewelry collection at Kyoto’s National Museum in October 2026, headlined by the Stellara diamond necklace holding a 41.01-carat Ceylon sapphire and the Tutti Chaya necklace requiring 2,000 artisan hours . Exclusive collector events lock in ultra-high-net-worth pre-orders before rare sapphire creations ever reach public boutiques.
Key Players
- Tiffany & Co.
- Cartier
- Harry Winston
- Bulgari
- Chopard
- Graff Diamonds
- Van Cleef & Arpels
- Blue Nile
- Swarovski
- Kay Jewelers
- Other Key Players
Recent Developments
2026
- September 2026: Pandora completed a capacity expansion by investing USD 150 Million in a Ho Chi Minh City fine jewelry facility creating 7,000 jobs and 60 Million pieces in annual capacity for a 50% group output boost according to Pandora Group .
- September 2026: Signet Jewelers signed a consolidated consumer credit agreement with Bread Financial running through December 31, 2035 to add private-label financing to Blue Nile following USD 1.53 Billion in Q2 sales according to Signet Jewelers .
- May 2026: Cartier completed a retail capacity expansion by opening a 406-square-meter boutique at Chatswood Chase in Sydney as its 7th Australian store according to Cartier .
- May 2026: Chopard executed a product launch for its 2026 Red Carpet Collection themed Miracles featuring 79 one-of-a-kind Haute Joaillerie gemstone and sapphire creations crafted in Geneva according to Chopard .
- January 2026: Van Cleef & Arpels advanced a EUR 55 Million French workshop capacity expansion across Chateauneuf-sur-Isere spanning 66,000 square feet and Thiers to create over 600 direct artisan jobs according to Van Cleef & Arpels .
2025
- November 2025: Tiffany & Co. won municipal regulatory approval in Beverly Hills to build a 30,468-square-foot, 3-story Rodeo Drive flagship store over a 28-month construction timeline according to Beverly Hills municipal filings .
- August 2025: Harry Winston completed a capacity expansion by opening a 3-floor, 869-square-meter flagship salon in Ginza across its 8-store Japan network after a 451-square-meter Zurich salon expansion according to Harry Winston .
- July 2025: Titan Company Limited signed a definitive acquisition agreement for a 67% stake in UAE luxury jeweler Damas LLC for AED 1,038 Million, or USD 283.2 Million, adding 123 GCC retail stores according to Titan Company filings .
Geopolitical Impact Analysis
Escalating tariff regimes and fragmenting trade blocs directly raise landed duties on faceted sapphires and finished precious-metal mountings moving between Asian cutting centers and Western retail markets. According to WTO, world merchandise trade volume expansion will slow from 4.6% at USD 26.26 Trillion in 2025 to 1.9% in 2026, or 1.4% under severe Middle East conflict, as MFN trade drops to 72% . As reported by UNCTAD, global export tariffs climbed 10% for developed nations, 16% for developing nations, and 18% for least-developed exporters in 2025, while non-tariff measures raised compliance costs across 88% of countries . Higher border levies hit rough corundum mined in Madagascar and Sri Lanka and gold mountings cast in India and Thailand. Jewelry wholesalers must therefore shift finishing workflows into bilateral free-trade hubs to protect landed retail margins.
Maritime chokepoint disruptions and bilateral trade contractions simultaneously inflate armored freight insurance, bullion hedging costs, and cross-border parcel delivery times for sapphire jewelry distributors. Data from UNCTAD shows Strait of Hormuz shipping disruptions pushed global trade price inflation up 3.6% quarter-on-quarter in Q1 2026 and 5.1% in Q2 2026 even as H1 2026 goods trade reached USD 13.7 Trillion . IMF found that global GDP expansion will ease to 3.1% in 2026 with 4.7% headline inflation, alongside a 22% drop in Chinese exports to the U.S. and a 25% drop in U.S. exports to China . Pricier air-freight security surcharges on loose calibrated sapphires and 18-karat gold findings squeeze working capital, forcing retail chains to hold buffer gemstone stock closer to domestic bespoke workshops.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 1.0 Billion |
| Forecast Revenue (2035) | USD 1.9 Billion |
| CAGR (2026-2035) | 6.5% |
| Base Year for Estimation | 2025 |
| Historic Period | 2021-2025 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Type of Jewellery (Rings, Necklaces, Earrings, Bracelets, Pendants, Others), By Sapphire Color (Blue Sapphire, Green Sapphire, Pink Sapphire, Padparadscha Sapphire, White Sapphire), By Distribution Channel (Specialty Jewelry Stores, Brick-and-Mortar Retailers, Online Retailers, Others) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Tiffany & Co., Cartier, Harry Winston, Bulgari, Chopard, Graff Diamonds, Van Cleef & Arpels, Blue Nile, Swarovski, Kay Jewelers, Other Key Players |
| Customization Scope | Customization for segments, region / country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License | Multi-User License (Up to 5 Users) | Corporate Use License (Unlimited User and Printable PDF) |








