


Market Overview
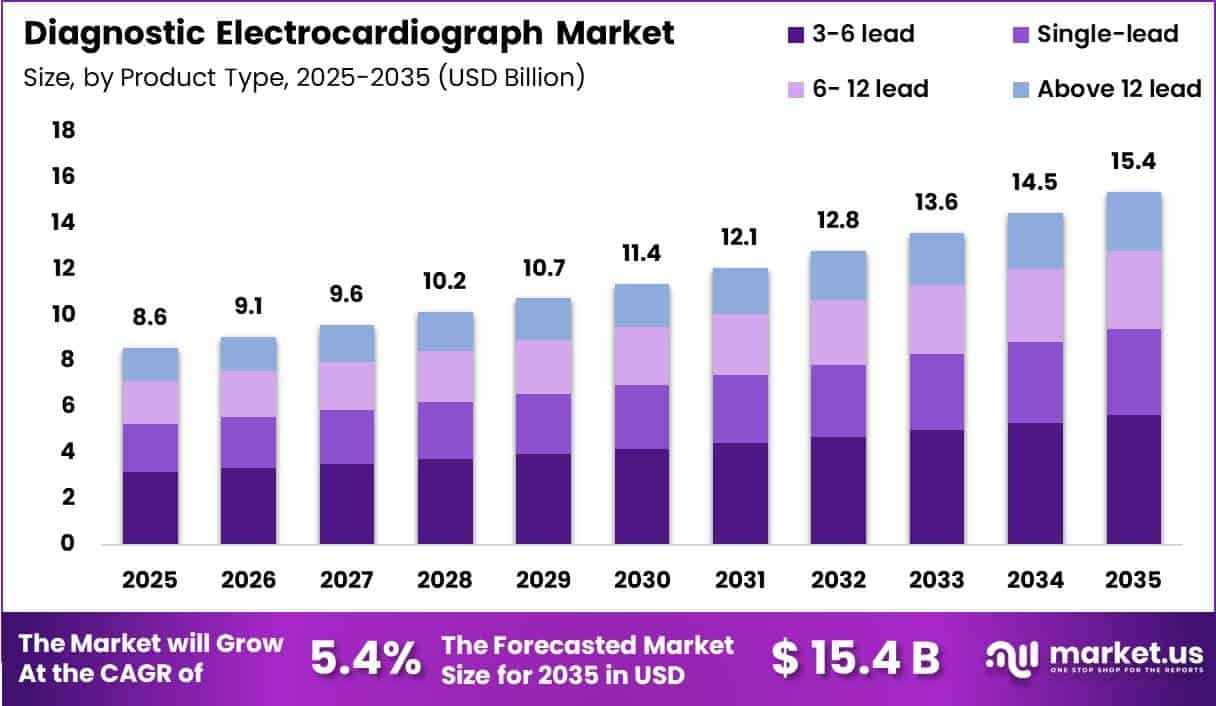
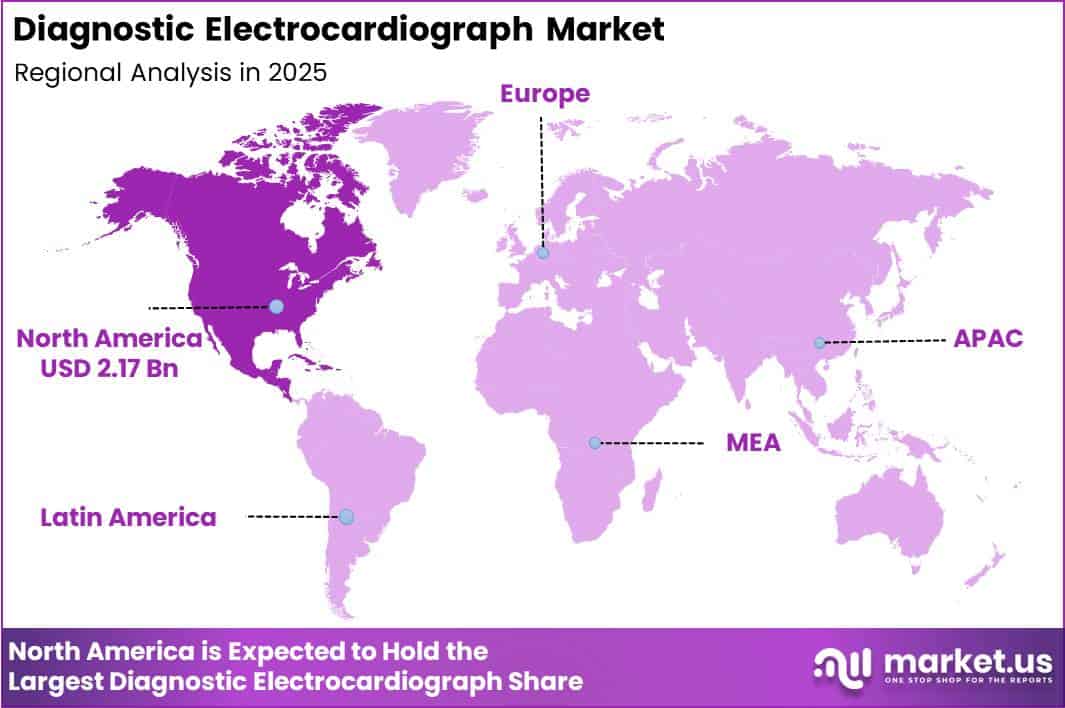
The Global Diagnostic Electrocardiograph Market size is expected to be worth around US$ 15.4 Billion by 2035 from US$ 8.6 Billion in 2025, growing at a CAGR of 5.4% during the forecast period from 2026 to 2035. In 2025, North America led the market, achieving over 31.6% share with a revenue of US$2.7 Billion.
The Diagnostic Electrocardiograph (ECG) market is expanding steadily as cardiovascular diseases continue to be one of the leading causes of illness and death worldwide. Electrocardiographs are essential diagnostic devices that record the heart’s electrical activity, helping healthcare professionals detect arrhythmias, myocardial infarction, heart failure, and other cardiac abnormalities.
The increasing emphasis on early diagnosis, preventive healthcare, and continuous cardiac monitoring is driving wider adoption of ECG systems across hospitals, specialty cardiac centers, outpatient clinics, and ambulatory care settings.
According to the World Health Organization (WHO), cardiovascular diseases cause approximately 17.9 million deaths every year, accounting for nearly 32% of all global deaths, highlighting the growing need for timely cardiac diagnosis.
The U.S. Centers for Disease Control and Prevention (CDC) reports that about 805,000 people experience a heart attack annually in the United States, while one person dies from cardiovascular disease approximately every 33 seconds. These statistics reinforce the importance of reliable ECG testing in both emergency and routine clinical practice.
Technological advancements are further strengthening market growth. Modern diagnostic electrocardiographs now feature digital connectivity, cloud-based data storage, artificial intelligence-assisted ECG interpretation, wireless transmission, and integration with electronic health records, enabling faster clinical decision-making and improved workflow efficiency.
Healthcare providers are also adopting portable and compact ECG devices to support point-of-care testing and remote patient monitoring. Rising healthcare investments, expanding cardiovascular screening programs, and growing awareness of heart health among aging populations are expected to support sustained demand for diagnostic electrocardiographs across developed and emerging healthcare markets throughout the coming decade.
Key Takeaways
- Market Size: Diagnostic Electrocardiograph Market size was US$ 8.6 billion in 2025. The market is estimated to grow to US$ 15.4 billion by 2035.
- Market Share: The Compound Annual Growth Rate (CAGR) of the market from 2026 to 2035 will be 5.4%.
- By product type, Resting ECG has the largest market share, accounting for 45% of total sales.
- By Lead Type:3-6 lead, accounting for 36.7% of total revenue.
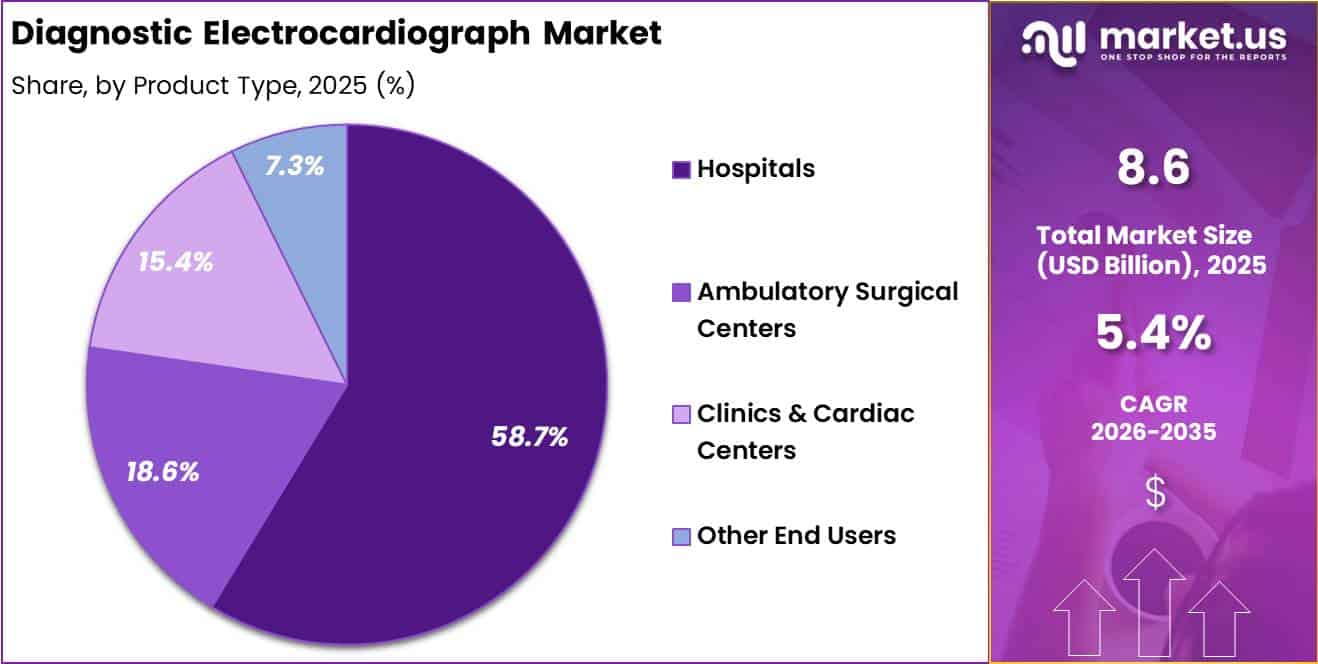
- By end user: hospitals lead the segment, accounting for 58.7% of total revenue.
- Regional: North America is the dominant regional market, accounting for 31.6% of global sales.
Product Analysis
The product segment of the Diagnostic Electrocardiograph Market is led by Resting ECG systems, which accounted for 45.0% of the market share in 2025. Their dominance is driven by their widespread use as the primary diagnostic tool for routine cardiac examinations in hospitals, clinics, and physician offices.
Resting ECG devices provide rapid, non-invasive, and cost-effective assessment of heart rhythm, making them essential for detecting arrhythmias, myocardial infarction, and other cardiovascular conditions. Their ease of operation, availability across healthcare settings, and integration with digital hospital information systems further strengthen market demand.
The increasing prevalence of cardiovascular diseases and the growing emphasis on preventive health screenings continue to support the adoption of resting ECG equipment globally.
Among the remaining product categories, Stress ECG Devices captured 16.8% of the market due to their important role in diagnosing exercise-induced cardiac abnormalities. Smart ECG Monitors represented 10.2%, benefiting from advances in wearable technology and remote patient monitoring.
Holter Monitors held 9.1%, supported by continuous ambulatory cardiac monitoring requirements. Implantable Loop Recorders accounted for 8.4%, driven by long-term arrhythmia detection in high-risk patients. Event Monitors contributed 7.6%, while Mobile Cardiac Telemetry (MCT) Devices represented 2.9%, reflecting their specialized application in continuous real-time cardiac monitoring.
Lead Type Analysis
The lead type segment of the Diagnostic Electrocardiograph Market was dominated by 3–6 lead ECG systems, accounting for 36.7% of the market share in 2025. These systems offer an effective balance between diagnostic capability, portability, and affordability, making them widely adopted in hospitals, emergency departments, ambulances, and outpatient facilities.
They provide sufficient cardiac information for rapid clinical assessment while remaining easier to operate than higher-lead configurations. Their suitability for emergency care, routine monitoring, and point-of-care diagnosis has made them a preferred choice across both developed and emerging healthcare markets. Growing demand for portable diagnostic equipment and faster cardiac evaluations continues to strengthen this segment’s leadership.
Single-lead ECG systems accounted for 24.5% of the market, supported by rising demand for wearable devices, home monitoring, and telemedicine applications. 6–12 lead ECG systems captured 22.1%, as they provide more comprehensive cardiac assessments and are widely used in hospitals and specialized cardiac care centers for accurate diagnosis.
Above 12 lead ECG systems represented 16.7% of the market, primarily serving advanced clinical settings where detailed electrophysiological evaluation is required for complex cardiac conditions. Increasing investments in digital healthcare infrastructure and improvements in portable multi-lead technologies are expected to support steady demand across all lead type categories.
End User Analysis
The end user segment of the Diagnostic Electrocardiograph Market was led by Hospitals, which accounted for 58.7% of the market share in 2025. Hospitals remain the largest users of diagnostic ECG equipment due to their high patient volumes, advanced diagnostic capabilities, and comprehensive cardiac care services.
Emergency departments, intensive care units, cardiology departments, and inpatient monitoring units rely heavily on ECG systems for rapid diagnosis and continuous cardiac assessment. The growing burden of cardiovascular diseases, expanding hospital infrastructure, and increasing investments in digital healthcare technologies continue to reinforce the dominance of this segment.
Hospitals also benefit from greater purchasing capacity, enabling the adoption of advanced ECG systems with integrated digital reporting and electronic medical record connectivity.
Ambulatory Surgical Centers accounted for 18.6% of the market, supported by increasing outpatient cardiac procedures and pre-operative cardiovascular assessments. Clinics & Cardiac Centers represented 15.4%, driven by growing demand for accessible diagnostic services and routine cardiac screening.
Other End Users, including diagnostic laboratories, home healthcare providers, research institutions, and community healthcare facilities, collectively contributed 7.3% of the market. Rising adoption of portable ECG devices, expanding preventive healthcare programs, and broader access to cardiac diagnostics are expected to support growth across all end-user segments over the forecast period.
Market Segmentations
By Product
- Stress ECG Devices
- Resting ECG
- Implantable Loop Recorders
- Smart ECG Monitors
- Event Monitors
- Holter Monitors
- MCT Devices
By Lead Type
- Single-lead
- 3-6 lead
- 6- 12 lead
- Above 12 lead
By End User
- Hospitals
- Ambulatory Surgical Centers
- Clinics & Cardiac Centers
- Other End Users
Drivers
Remote Monitoring Reimbursement and Connected ECG Workflows
Remote monitoring reimbursement is reshaping electrocardiograph (ECG) utilization by shifting it from episodic, clinic-based diagnostics to continuous, digitally connected cardiovascular care. In the U.S., CMS has established reimbursement pathways for remote patient monitoring (RPM) that cover both chronic and acute conditions, provided that data is collected through an FDA-defined connected medical device and transmitted with sufficient frequency typically at least two days of recorded data within a 30-day billing window.
Importantly, CMS structures RPM reimbursement into separate components for device supply, setup, and ongoing clinical management, which improves economic feasibility for providers deploying connected ECG systems at scale.
This creates a stable recurring revenue layer rather than a single-use capital equipment transaction. For ECG vendors, this policy shift changes the value proposition from standalone diagnostic hardware to integrated digital platforms that combine ECG capture, cloud-based data transmission, automated analytics, and clinician review workflows.
As a result, adoption is increasingly driven by outpatient networks, primary care groups, and chronic disease management programs rather than only cardiology departments. This transition reduces purchasing friction, supports higher device utilization, and encourages replacement of legacy offline ECG systems with connected alternatives.
It also improves revenue predictability through subscription-based software and monitoring services, reducing reliance on cyclical capital expenditure budgets. Overall, reimbursement-backed connected ECG ecosystems are estimated to contribute approximately 1.5 % points of incremental CAGR, driven by broader deployment of remote monitoring programs and stronger integration of ECG data into longitudinal cardiovascular care pathways.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| CVD burden + earlier cardiac detection demand | +1.9% | Global; North America core, EU, APAC urban systems, LMIC spill-over | Short term |
| Remote monitoring reimbursement + connected ECG workflows | +1.5% | North America core; EU selective, APAC private corridors | Short term |
| AI-enabled ECG interpretation + software-led upgrades | +1.3% | North America core, EU tertiary centers, East Asia advanced hospitals | Medium term |
| Home and ambulatory ECG form-factor expansion | +1.1% | North America, EU, Japan, South Korea, urban China | Medium term |
| Emergency-care throughput and door-to-ECG compliance | +0.9% | North America, EU, Gulf hospitals, large APAC tertiary networks | Short term |
| LMIC primary-care cardiovascular screening build-out | +0.8% | South Asia, ASEAN, Africa, Latin America | Long term |
Challenges
Legacy ECG Infrastructure Overload and Its Impact on Digital Cardiology Adoption
Legacy ECG infrastructure overload is a persistent constraint in cardiovascular diagnostics, driven by the widespread use of outdated electrocardiograph systems that are often more than a decade old and lack modern connectivity, cybersecurity features, and integrated data workflows.
This issue is especially pronounced in low- and middle-income countries, where budget limitations and competing healthcare priorities result in 30 to 50 % of ECG devices remaining legacy systems that rely on manual printouts and fragmented record storage.
Operationally, these systems introduce measurable inefficiencies. Device aging, electrode degradation, and limited digital capability contribute to 5 to 10 % monthly downtime per unit, while inconsistent signal quality increases repeat testing requirements.
Compared with modern digital ECG platforms, each exam can take 5 to 10 additional minutes of staff time, and consumable inefficiencies can increase electrode usage by 10 to 15 % per test, raising hidden operational costs across high-volume facilities.
From a commercial standpoint, this slows full system replacement cycles. Many hospitals prioritize partial upgrades such as improved leads, cables, or connectivity add-ons rather than full platform replacement, which delays high-value capital sales and limits adoption of software-enabled ECG ecosystems.
Overall, legacy infrastructure overload is estimated to reduce potential ECG market CAGR by approximately 0.9 % points, primarily through delayed procurement cycles and constrained digital transformation.
Addressing this requires phased modernization strategies, including trade-in programs, incremental device replacement schedules, and modular upgrades that minimize downtime while demonstrating clear workflow and cost-efficiency improvements.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Fragmented cardiovascular workflows | -1.2% | North America, EU, APAC metros | Medium term (2-4 years) |
| Chronic cardiology talent gaps | -1.0% | North America, EU, India, LATAM | Long term (≥ 4 years) |
| Legacy ECG infrastructure overload | -0.9% | Public hospitals, LMICs | Long term (≥ 4 years) |
| Data governance & AI validation drag | -1.3% | US, EU regulatory hubs | Medium term (2-4 years) |
| Reimbursement complexity for digital ECG | -1.1% | US CMS, OECD payers | Medium term (2-4 years) |
| Supply chain variability in critical components | -0.8% | APAC manufacturing corridors | Short term (≤ 2 years) |
Restraints
Supply Chain Volatility in Key ECG Components and Its Impact on Market Growth
Supply chain volatility in critical ECG components remains a persistent structural restraint on market expansion, affecting both manufacturing efficiency and end-user adoption timelines.
Key inputs such as printed circuit boards (PCBs), patient cables, disposable electrodes, and power modules are still heavily dependent on concentrated supplier networks, particularly across Asia-Pacific electronics hubs. This dependence creates exposure to periodic disruptions, logistics bottlenecks, and quality inconsistencies that directly impact production continuity.
During disruption cycles, lead times for these components can extend from a typical 8 to 10 weeks to 16 to 24 weeks, significantly slowing manufacturing throughput and delaying device delivery to hospitals and clinics. At the same time, freight costs and global logistics volatility remain structurally above pre-pandemic levels, adding sustained pressure on input costs and pricing strategies.
Medical device-grade quality requirements further amplify the issue, as ECG systems must maintain very low defect rates, often under 5 %, leading to occasional batch rejections and production rescheduling when component variability exceeds tolerance thresholds.
These inefficiencies increase working capital needs as manufacturers build higher safety stock buffers and diversify suppliers.In response, OEMs are increasingly pursuing dual-sourcing strategies, selective component reshoring, and expanded inventory holding, but these measures raise the cost of goods sold by an estimated 3 to 5 % and slow operational agility.
Overall, supply chain volatility is estimated to reduce ECG market CAGR by approximately 0.9 % points, primarily through delayed deliveries, higher costs, and more cautious procurement behavior from healthcare systems in both developed and emerging markets.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Complex AI/Software regulatory pathway | -1.4% | North America core, EU, advanced APAC | Medium term (2-4 years) |
| Reimbursement drag for routine ECG & AI add-ons | -1.1% | North America, EU, selected LATAM | Medium term (2-4 years) |
| Supply chain volatility in key components | -0.9% | Global, APAC corridors, EU import-reliant | Short to medium term (≤ 4 years) |
| Hospital CapEx deferrals & budget tightening | -0.7% | North America, EU public hospitals | Short term (≤ 2 years) |
| Data privacy & cybersecurity compliance burden | -0.5% | North America, EU, high-income APAC | Long term (≥ 4 years) |
Opportunity
Integrated RPM ECG Care Bundles for Chronic Cardiovascular Disease
Integrated remote patient monitoring RPM and ECG care bundles represent an emerging commercial model that combines diagnostic hardware, wearable sensors, analytics software, and clinical services into a single longitudinal care offering.
This approach aligns with evolving reimbursement frameworks, particularly in the U.S., where CMS RPM CPT codes collectively enable approximately US$99–180 per patient per month for chronic monitoring programs.
Today, however, ECG data is often underutilized within RPM programs, which tend to focus more heavily on metrics like blood pressure, glucose, or weight. This creates an opportunity for ECG-centered bundles that continuously assess arrhythmia burden, detect ischemic events, and track adherence in high-risk cardiovascular populations over 6–12 month care cycles.
If even a modest share, around 5 % of chronic cardiovascular patients in the U.S. and EU by 2035 (roughly 10–12 million individuals) were enrolled in such ECG-integrated RPM programs, the resulting recurring revenue opportunity could exceed US$12–20 billion annually, with operating margins in the 25–35 % range due to scalable software and monitoring infrastructure.
Clinically, these models are also associated with meaningful system-level savings, including estimated reductions of 10–20 % in hospital admissions and 8–15 % fewer emergency visits in managed cohorts, improving payer willingness to adopt bundled reimbursement structures.
Because these programs require workflow redesign, cardiology integration, and risk-sharing agreements, they are not yet fully reflected in baseline ECG market assumptions. However, they are realistically scalable between 2026 and 2030 as reimbursement stabilizes and providers shift toward value-based chronic disease management, contributing an estimated 1.8 % points of additional CAGR upside.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| AI-enhanced ECG risk stratification platforms | +2.0% | North America, EU, urban APAC | Medium term (2–4 years) |
| Integrated RPM-ECG care bundles for chronic CVD | +1.8% | North America, EU, select LATAM | Short–medium term (≤ 4 years) |
| Preventive ECG screening in high-burden LMICs | +1.5% | South Asia, Sub-Saharan Africa, Southeast Asia | Long term (≥ 4 years) |
| ECG-embedded virtual cardiology and tele-triage | +1.4% | North America core, EU, GCC, APAC metros | Short–medium term (≤ 4 years) |
| Value-based ECG analytics for payers and ACOs | +1.2% | US, EU (select markets) | Medium term (2–4 years) |
| Enterprise ECG data monetization and APIs | +1.1% | Global tertiary centers, device OEM hubs | Long term (≥ 4 years) |
Regional Analysis
In 2025, North America led the market, achieving over 31.6% share with a revenue of US$2.7 billion.
North America’s leadership is driven by its advanced healthcare infrastructure, widespread availability of cardiac diagnostic services, and high adoption of technologically advanced electrocardiograph systems across hospitals, specialty cardiac centers, and ambulatory care facilities.
The growing prevalence of cardiovascular diseases, including arrhythmias, coronary artery disease, and heart failure, has significantly increased the demand for accurate and timely ECG diagnostics.
The United States represents the largest contributor to the regional market due to strong healthcare spending, favorable reimbursement policies, and continuous investments in digital healthcare technologies.
Healthcare providers are increasingly adopting portable, wireless, and AI-enabled electrocardiographs to improve workflow efficiency and support early detection of cardiac abnormalities. Rising use of remote patient monitoring and telecardiology solutions is further expanding the application of diagnostic ECG devices beyond traditional hospital settings.
Canada also contributes steadily to market growth through government-supported healthcare initiatives, increasing awareness of preventive cardiovascular screening, and expanding access to diagnostic services in both urban and rural regions.
In addition, ongoing product innovations by leading medical device manufacturers, coupled with regulatory approvals for advanced ECG technologies, continue to strengthen market expansion. The increasing elderly population, growing burden of chronic diseases, and emphasis on early diagnosis and continuous cardiac monitoring are expected to maintain North America’s leading position throughout the forecast period.
Key Regions and Countries
North America
- The US
- Canada
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Russia & CIS
- Rest of Europe
Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
Latin America
- Brazil
- Mexico
- Rest of Latin America
Key Player Analysis
The global Diagnostic Electrocardiograph Market is moderately fragmented, with established multinational manufacturers and specialized regional companies competing through continuous technological innovation, product differentiation, and expanded clinical capabilities. Market participants are focusing on developing advanced ECG systems that provide faster diagnostics, improved signal accuracy, and seamless integration with digital healthcare platforms.
Competition is increasingly centered on enhancing workflow efficiency, supporting remote patient monitoring, and delivering user-friendly solutions for hospitals, diagnostic laboratories, specialty clinics, and ambulatory care settings.
Rising demand for early cardiovascular disease detection and connected healthcare is encouraging manufacturers to strengthen their innovation pipelines while expanding their global distribution networks.
Koninklijke Philips N.V., Bio-Medical Electronics Co., Innomed Medical Inc., Bionet Co., Ltd., Scottcare Corp, Spacelabs Healthcare Inc, VectraCor, Inc., Allengers Medical Systems, Ltd., and Other Key Players are investing heavily in research and development to improve ECG accuracy, portability, wireless connectivity, and AI-assisted interpretation capabilities.
Strategic partnerships with healthcare providers, technology companies, and digital health platforms are helping these firms enhance interoperability and broaden their clinical reach. Product innovation remains focused on compact diagnostic electrocardiographs, cloud-enabled data management, touchscreen interfaces, and integrated reporting features that simplify clinician workflows.
Companies are also emphasizing ecosystem-based competition by connecting ECG devices with electronic health records, hospital information systems, and telemedicine platforms, enabling seamless data exchange and supporting value-based healthcare.
Continuous software upgrades, regulatory compliance, and service expansion further strengthen competitive positioning while addressing the evolving needs of modern cardiovascular diagnostics.
Top Key Players
- Koninklijke Philips N.V.
- Bio-Medical Electronics Co.
- Innomed Medical Inc.
- Bionet Co., Ltd.
- Scottcare Corp
- Spacelabs Healthcare Inc
- VectraCor, Inc.
- Allengers Medical Systems, Ltd.
- Other Key Players.
Recent Developments
- Koninklijke Philips N.V.(January 2026) – Philips completed acquisition of SpectraWAVE after signing in December 2025, expanding its coronary interventional portfolio with advanced imaging capabilities and strengthening its position across cardiovascular diagnosis and treatment pathways.
- Bio-Medical Electronics Co.(August 2026) – Shenzhen Mindray Bio-Medical Electronics highlighted its Latin American ecosystem strategy in São Paulo, signaling continued regional commercial expansion; no ECG-specific acquisition, merger, or standalone diagnostic electrocardiograph launch was identified publicly.
- Bionet Co., Ltd. (May 2026) – Bionet introduced O’Pet Curv, a cloud-connected wireless veterinary vital-sign monitor incorporating ECG functionality, demonstrating expansion of the company’s wireless monitoring technologies into veterinary-care applications.
- Spacelabs Healthcare Inc.(February 2026) – Spacelabs launched CardioExpress 4012 and 5012 resting ECG machines, combining one-touch workflow, secure Wi-Fi and EMR connectivity, Glasgow interpretation, real-time arrhythmia detection, HRV analysis, mobility, and extended battery operation.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 8.6 Bn |
| Forecast Revenue (2035) | US$ 15.4 Bn |
| CAGR (2026-2035) | 5.4% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Product (Stress ECG Devices, Resting ECG, Implantable Loop Recorders, Smart ECG Monitors, Event Monitors, Holter Monitors, MCT Devices) By Lead Type (Single-lead,3-6 lead,6- 12 lead, Above 12 lead) By End User (Hospitals, Ambulatory Surgical Centers, Clinics & Cardiac Centers, Other End Users) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Koninklijke Philips N.V., Bio-Medical Electronics Co., Innomed Medical Inc., Bionet Co., Ltd., Scottcare Corp, Spacelabs Healthcare Inc, VectraCor, Inc., Allengers Medical Systems, Ltd., Other Key Players. |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








