


Report Overview
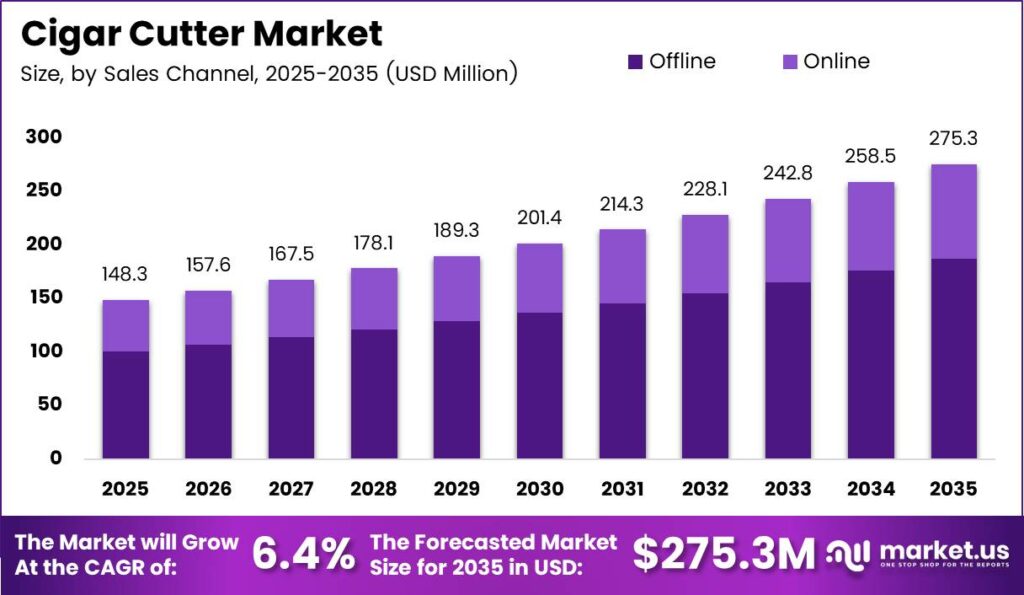
Global Cigar Cutter Market size is expected to be worth around USD 275.3 Million by 2035 from USD 148.3 Million in 2025, growing at a CAGR of 6.4% during the forecast period 2026 to 2035.
The cigar cutter market encompasses all manual and mechanical cutting instruments designed to prepare cigars for smoking by removing the cap. Products span entry-level pocket guillotines, multi-format tabletop cutters, V-cutters, punch cutters, and specialty blade designs. Buyers range from casual adult smokers to collectors and hospitality operators. Distribution runs through brick-and-mortar tobacconists and online specialty retailers. Product durability, blade precision, and ring-gauge compatibility define competitive positioning across all price tiers.
Regulation shapes this market’s commercial boundaries at every level. Advertising restrictions, point-of-sale display bans, and age-verification mandates narrow the retail channels through which cutter brands can reach new adult consumers. As a result, premium accessory makers concentrate marketing efforts on trade events, specialist publications, and direct-to-consumer online channels. This shift creates a structural advantage for brands with strong direct relationships and punishes those reliant on mass-retail exposure. Compliance costs add operating pressure on smaller importers and constrain margin flexibility.
Key Takeaways
- The Global Cigar Cutter Market is valued at USD 148.3 Million in 2025 and is forecast to reach USD 275.3 Million by 2035, expanding at a CAGR of 6.4% during the forecast period 2026 to 2035.
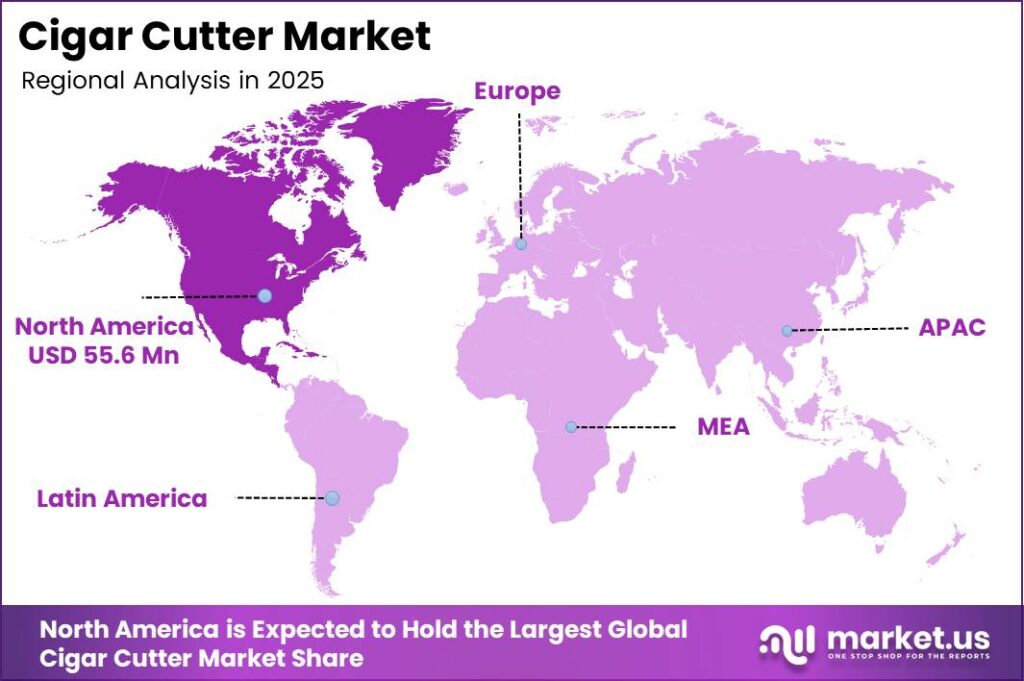
- Asia-Pacific dominates the global Cigar Cutter Market, holding a 37.56% share valued at USD 55.6 Million in 2025, supported by its dual role as a manufacturing hub and end-consumer market.
- Middle East & Africa is the fastest-growing region, driven by expanding cigar-lounge culture and rising disposable income among adult consumers in Gulf Cooperation Council urban centers.
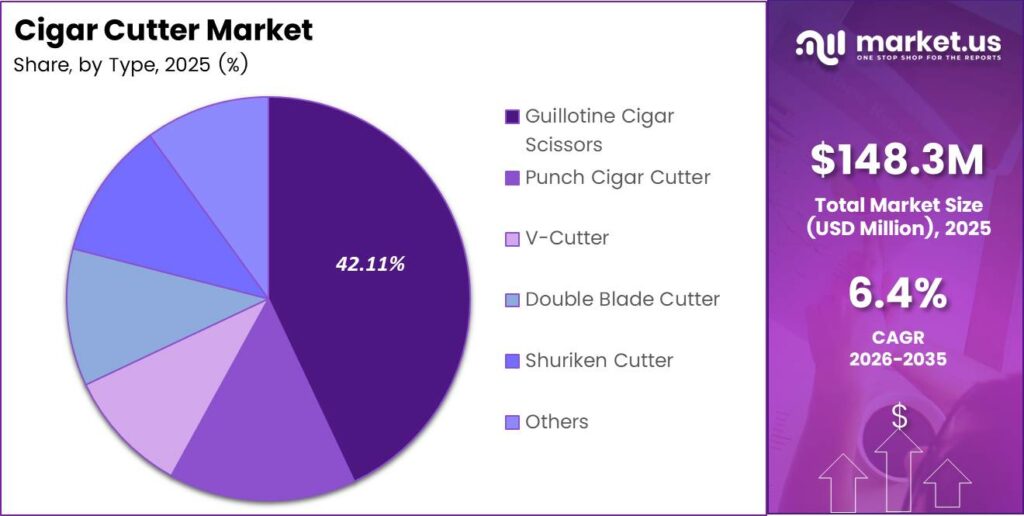
- By Type, Guillotine Cigar Scissors leads with a 42.11% market share and is also the fastest-growing type segment, supported by broad ring-gauge compatibility and strong first-purchase preference among adult consumers.
- By Sales Channel, Offline channels dominate with a 67.89% share, while Online is the fastest-growing channel, driven by direct-to-consumer brand programs and time-limited release strategies.
As per our research, CigarMedics priced its il Maestro single-guillotine cutter at $124.99 when shipment was confirmed in June 2025, positioning it squarely within the accessible-premium tier. This price point illustrates the widening gap between mass-market cutters and collector-grade pieces. In April 2025, Elie Bleu made its Year of the Snake C-4 Cutter Snake available for U.S. shipment at $260, signaling sustained consumer appetite for limited-edition accessories well above everyday price thresholds.
In April 2026, Les Fines Lames introduced La Guillotine–Rotor, a double-guillotine cutter priced at $79, designed for cigars up to 80 ring gauge and offered in chrome and matte-black finishes. This mid-market entry demonstrates that premium-heritage brands are widening their price architecture to capture value-oriented adult buyers without abandoning their luxury credentials. Brands that execute this dual-tier strategy effectively will capture both the replacement cycle and the aspirational first-purchase segment simultaneously.
Type Analysis
Guillotine Cigar Scissors dominates with 42.11% due to broad ring-gauge compatibility and familiar user mechanics.
In 2025, Guillotine Cigar Scissors held a dominant market position in the By Type segment of the Cigar Cutter Market, with a 42.11% share. This format suits the widest range of ring gauges in standard production and delivers a clean, straight cut without requiring mechanical adjustment. As per our research, the guillotine remains the first-purchase default for most adult consumers entering the premium cigar segment, making it the highest-volume category by unit count. Brands that price guillotines accessibly across multiple finishes hold a structural stocking advantage with tobacconists.
Punch cutters serve consumers who prefer a smaller, circular draw opening and favor compact, keychain-format tools. This sub-segment targets daily carry and on-the-go use cases, where portability outweighs versatility. In May 2025, Elie Bleu introduced the EBC1 Blue Grid cutter at $350, extending its existing cutter line with a blue ion-plated finish rather than a new cutting mechanism, which confirms that finish differentiation, not format innovation, drives incremental revenue in this tier. Brands commanding repeat purchases in this sub-segment invest heavily in finish variety and material perceived quality.
V-cutters and Double Blade Cutters address experienced smokers who prefer a wedge or dual-action cut for enhanced draw control on larger ring-gauge cigars. The redesigned Palió Quad Tabletop Cutter, announced January 21, 2026, carries a manufacturer’s suggested retail price of $249.99 and provides 4 cutting options across 2 straight-cut and 2 V-cut openings, with 52– and 60-ring-gauge options per cut type. This multi-format offer illustrates the commercial logic of consolidating cut types into one premium SKU to raise average transaction value at the point of sale.
Shuriken Cutters and other specialty formats address niche collector and gifting demand, contributing the remaining market share collectively alongside Double Blade and miscellaneous formats. These categories rely on design differentiation and limited-edition positioning to justify premium price points. Distribution for these items skews toward direct-to-consumer online channels and curated boutique retailers where presentation and storytelling complement the product’s visual appeal and support full-margin sell-through without heavy promotional discounting.
Sales Channel Analysis
Offline dominates with 67.89% due to in-store tactile evaluation driving purchase confidence.
In 2025, Offline held a dominant market position in the By Sales Channel segment of the Cigar Cutter Market, with a 67.89% share. Brick-and-mortar tobacconists and cigar lounges allow adult buyers to handle cutting tools, test blade action, and assess weight and finish before committing to a purchase. As per our research, physical retail also benefits from staff recommendation at point of sale, which increases average transaction value by steering customers toward higher-margin premium cutters. Retailers that invest in trained floor staff generate significantly stronger accessory attachment rates than self-service formats.
Online channels are the fastest-growing distribution route in this market, driven by wider SKU availability and direct-to-consumer brand programs that bypass traditional wholesale margin structures. In January 2026, Les Fines Lames announced Le Tag–Clip, a clip-equipped cutter priced at $120, with a structured sales window running from February 9 through August 9, 2026. Time-limited online windows of this kind create urgency-driven purchase cycles that offline shelf inventory cannot replicate. Brands using exclusive online release calendars build proprietary demand signals and reduce price competition with physical retail partners.
Key Market Segments
By Type
- Guillotine Cigar Scissors
- Punch Cigar Cutter
- V-Cutter
- Double Blade Cutter
- Shuriken Cutter
- Others
By Sales Channel
- Offline
- Online
Regional Analysis
Asia-Pacific Dominates the Cigar Cutter Market with a Market Share of 37.56%, Valued at USD 55.6 Million
Asia-Pacific leads the global cigar cutter market with 37.56% share and a base value of USD 55.6 Million in 2025. The region combines manufacturing scale with a growing base of adult premium-cigar consumers in markets including China, Japan, and South Korea. This dual role as both production hub and end-market creates cost efficiencies unavailable to Western competitors sourcing from the region. Brands with regional manufacturing footprints gain direct supply-chain control, shorter replenishment cycles, and stronger retailer margin positions across the Asia-Pacific retail tier.
The Middle East & Africa region is the fastest-growing market in this sector. Expanding cigar lounge culture in Gulf Cooperation Council markets, combined with growing disposable income among adult consumers in urban centers, drives accessory demand ahead of the global baseline rate. In June 2025, Vandermarliere Cigar Family completed its full acquisition of Les Fines Lames, bringing the French cigar-knife maker entirely under VCF ownership after an initial minority stake in 2023. This consolidation positions VCF-aligned product lines for stronger international distribution into emerging premium accessory markets, including MEA-focused channels.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Market Opportunity Analysis - Collector editions, accessible-premium pricing, and emerging regional markets offer structured entry points for new brand investment
The collector and limited-edition sub-segment operates on scarcity mechanics that generate full-margin sales without retail price competition. As established in the Type Analysis, design-led releases such as national-flag series and album-art cutters sell at price points from $79 to $189, well above the mass-market tier, with time-limited availability replacing discount-driven clearance. New entrants that structure one to two annual limited releases with defined production windows can capture collector demand without building deep standing inventory, reducing capital exposure while testing price elasticity in premium channels.
The accessible-premium tier between $79 and $130 remains underpopulated relative to both the entry-level and luxury-collector segments. As identified in the Report Overview, mid-market guillotines and clip-equipped formats at these price points attract first-upgrade buyers stepping out of sub-$30 commodity cutters. Brands that engineer compelling finish variety at this tier, rather than competing on cutting mechanism alone, occupy a gap that neither mass-market volume players nor high-end heritage brands currently fill with full-range coverage.
The Middle East & Africa region carries the fastest growth trajectory in this market, as established in the Regional Analysis, but currently accounts for a disproportionately small share of global premium accessory distribution. Gulf Cooperation Council markets combine high disposable income among adult consumers with an expanding cigar-lounge hospitality sector that purchases cutting tools at commercial rather than personal-use quantities. This creates a B2B hospitality channel opportunity for tabletop and multi-format cutters that does not depend on building a retail distribution network from scratch.
The online channel, identified as the fastest-growing sales route in the Sales Channel Analysis, enables direct-to-consumer brand programs that compress the wholesale margin layer and allow smaller specialty brands to compete nationally without physical retail footprints. New entrants targeting online-first distribution can use time-windowed release calendars to generate purchase urgency, collect first-party consumer data, and scale without the minimum-order and listing-fee requirements of traditional wholesale. This structural shift lowers the capital threshold for brand entry and accelerates the competitive response cycle for established players.
Technology and Innovation Landscape - Ring-gauge expansion, multi-format integration, and precision engineering define the next competitive tier in cigar cutting
Precision ring-gauge capability has become a primary technical differentiator in the premium cutter segment. The HALO cigar cutter, specified in February 2026, measures 58 × 58 × 10 mm, weighs approximately 84 g, and delivers a 23 mm cutting diameter accommodating cigars of approximately 58–60 ring gauge. These specifications represent the upper boundary of standard production cigars and signal that blade engineering, not body size, now carries the most commercial differentiation. Manufacturers that achieve consistent blade alignment at this diameter create a defensible quality benchmark that commodity producers cannot replicate at low cost.
Multi-format integration in a single tabletop unit is emerging as a premium hospitality and collector-tier proposition. The redesigned Palió Quad Tabletop Cutter, announced January 21, 2026, delivers 4 cutting options across 2 straight-cut openings and 2 V-cut openings, with 52– and 60-ring-gauge variants for each cut type. Combining multiple formats in one chassis increases the per-unit selling price while reducing the number of SKUs a lounge or retailer needs to stock. This integration logic favors manufacturers capable of precision multi-blade engineering over single-format specialists competing on cost alone.
Extended ring-gauge accommodation beyond conventional specifications is opening a distinct super-gauge product tier. The Palió PRO Trevi’s integrated deep V-cutter, launched December 15, 2025, accommodates cigars up to 64 ring gauge. Les Fines Lames extended this further, with La Guillotine–Vanguard cutters reaching 80 ring gauge and the Le Tag cutter accommodating up to 100 ring gauge as reported in September 2026. These upper limits push blade engineering, body tolerances, and hinge durability well beyond standard production requirements, creating a technology moat that restricts credible competition to a small number of precision-capable manufacturers.
Budget-tier engineering innovation is compressing the performance gap between value and premium segments. Vector-KGM’s Cutter-MAX, released October 6, 2026, accommodates cigars up to 76 ring gauge using a stainless-steel straight-cut blade at an estimated retail price of $7.60 for the Cutter-80 variant. Delivering ring-gauge capacity formerly associated with premium-priced tools at a mass-market price point shifts consumer expectations across the entire market. Established premium brands must respond with clearer material, finish, and durability differentiation to justify price gaps that ring-gauge specifications alone no longer fully support.
Drivers
Premium-cigar consumption in the United States has reached a stable plateau that sustains consistent accessory demand. The Cigar Association of America reports approximately 430.0 million premium cigars imported in 2024 and 429.8 million in 2025. Volume stability at this level signals an established adult consumer base that replaces and upgrades cutting accessories on a recurring cycle. Vendors and retailers can forecast accessory attachment demand with higher confidence than in an accelerating-volume environment, making inventory planning more precise and reducing markdown exposure on premium SKUs.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Sustained premium-cigar consumption | +0.65% | North America; premium-cigar export markets | Short term (≤ 2 years) |
| Multi-format cutter premiumization | +0.40% | North America; Europe | Short term (≤ 2 years) |
| Specialist-retailer accessory attachment | +0.30% | Established cigar retail markets | Short term (≤ 2 years) |
| Online specialty-channel accessibility | +0.25% | North America; Europe; selected Asian markets | Medium term (2–4 years) |
| Design-led collector purchases | +0.20% | Premium accessory markets globally | Medium term (2–4 years) |
Restraints
A shrinking global tobacco-user population limits first-time entry into premium cigar consumption and reduces the addressable buyer pool for personal cutter ownership. WHO’s 2025 report estimates tobacco users fell from 1.38 billion in 2000 to 1.2 billion in 2024, drawing on 2,034 national surveys covering 97% of the global population. This long-run contraction places greater commercial weight on retaining and upgrading existing adult consumers rather than recruiting new ones. Accessory brands that invest in loyalty programs and trade-up pathways will outperform those dependent on first-time buyer acquisition.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Declining tobacco-user participation | -0.45% | Global; mature tobacco markets | Long term (≥ 4 years) |
| Long product-replacement cycles | -0.35% | Global; durable premium cutters | Long term (≥ 4 years) |
| Discretionary purchase deferral | -0.25% | Price-sensitive consumer markets | Short term (≤ 2 years) |
| Pre-cut cigar substitution | -0.20% | Machine-made cigar markets | Medium term (2–4 years) |
| Shared-cutter purchase displacement | -0.15% | Lounge-oriented consumption markets | Short term (≤ 2 years) |
Challenges
Maritime disruptions extend replenishment cycles and raise freight costs for import-dependent cutter distributors, compressing margins even when existing inventory permits ongoing sales. UNCTAD reported that by mid-2024, ship capacity transiting the Suez Canal had fallen 70%, Cape of Good Hope arrivals had increased 89%, and the Shanghai Containerized Freight Index had more than doubled from late 2023. For compact cutter importers, a 14-day extension against a 60-day planning cycle increases pipeline inventory requirements by approximately 23% at unchanged sales velocity. Distributors that build regional safety stocks and multi-route sourcing absorb these shocks without sacrificing shelf availability.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Maritime Replenishment Route Volatility | -0.35% | Asia–Europe sourcing; global importers | Short term (≤ 2 years) |
| Blade Alignment Yield Variability | -0.25% | Global precision-manufacturing networks | Medium term (2–4 years) |
| Warranty Reverse Logistics Complexity | -0.20% | Cross-border premium accessory channels | Medium term (2–4 years) |
| Finish Variant Inventory Fragmentation | -0.15% | Multi-channel accessory retailers | Short term (≤ 2 years) |
| Cross-Border Currency Margin Volatility | -0.10% | Import-dependent distribution markets | Short term (≤ 2 years) |
Opportunities
A replaceable blade-cartridge platform could convert a one-time cutter sale into a recurring aftermarket revenue stream without requiring the customer to replace the entire tool. An illustrative cartridge priced at 25–35% of a complete cutter unit, with manufacturing and fulfillment costs at 35–45% of cartridge revenue, delivers a gross margin of 55–65% compared with an assumed 45–50% on a complete product sale. This margin expansion of 5–20 percentage points on qualifying aftermarket transactions creates a compelling financial case for first-mover brands willing to invest in interface standardization and safety validation.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Modular blade-cartridge platforms | +0.40% | North America; Europe; premium global channels | Medium term (2–4 years) |
| Contracted hospitality equipment fleets | +0.30% | Licensed cigar hospitality destinations | Medium term (2–4 years) |
| Authenticated pre-owned cutter programs | +0.25% | Established luxury resale markets | Medium term (2–4 years) |
| Adaptive-grip accessible cutter designs | +0.20% | Mature adult-consumer markets | Long term (≥ 4 years) |
| Specialist accessory-brand consolidation | +0.15% | Fragmented regional accessory markets | Long term (≥ 4 years) |
Key Company Insights
Les Fines Lames has built a differentiated position in the premium cigar-knife and cutter segment through extreme ring-gauge capability and design-led limited editions. Its La Guillotine–Vanguard accommodates cigars up to 80 ring gauge and its Le Tag cutter reaches 100 ring gauge, setting technical benchmarks competitors have not publicly matched as of September 2026. In May 2026, the brand’s Le Petit World Cup series offered 48 national-flag designs at $189 each, demonstrating that time-limited collector releases generate full-margin sell-through without permanent inventory exposure.
In May 2025, S.T. Dupont confirmed shipment of its Slim Perfect Cutter Collection to retailers, priced at $285 per unit across black, black/gold, and black/chrome finishes. The single-guillotine design features a closed back, adjustable cutting depth, and a 22 mm blade diameter. This specification set positions S.T. Dupont directly in the accessible-luxury tier, where adjustable depth appeals to both novice and experienced smokers. Finish variety across 3 colorways ensures placement in gift-purchase occasions as well as personal upgrade cycles, supporting broader seasonal sell-through patterns.
Key Players
- Alfred Dunhill
- Boveda Inc.
- Colibri Group
- CREDO
- Davidoff of Geneva USA
- Lotus Group
- Palió
- Porsche Design Group
- Quality Importers Trading Co.
- S.T. Dupont
- Visol Products
- XIKAR
- Zino Davidoff
- Other Key Players
Recent Developments
- October 2026: Vector-KGM released 4 budget cigar cutters including the Cutter-80, Cutter-MAX, VCut440, and Cutter-Rest, with suggested retail prices ranging from $5.80 to $12; the Cutter-MAX accommodates cigars up to 76 ring gauge using a stainless-steel straight-cut blade, and the Cutter-80 includes a built-in cigar rest for cigars up to 80 ring gauge.
- October 2026: SIGLO Accessory, a division of Pacific Cigar Co. Limited, announced the Seki Cutter Golden Hana at $462, a Japanese-made single-guillotine cutter featuring an angled stainless-steel blade, a gold floral-patterned body, and a silk pouch produced by a Kyoto kimono maker, scheduled for mid-November 2026 availability.
- July 2026: Scrim by HutcH announced a Led Zeppelin album-art cutter collection limited to 100 pieces, targeting the collector segment with a fixed-production scarcity model that creates secondary-market demand alongside primary sales.
- May 2025: Elie Bleu released the Fuente OpusX Angel’s Share EBC-4 Cutter and matching cigar scissors, priced at $310 and $600 respectively, each limited to 212 pieces and listed as in stock and ready to ship as part of its collaboration with Arturo Fuente.
Geopolitical Impact Analysis
Trade policy shifts directly affect the landed cost and availability of precision-engineered cigar cutters sourced from Asia-Pacific manufacturing networks. According to UNCTAD, U.S. tariff escalation rounds targeting Chinese manufactured goods have raised effective import duty rates on metal hand tools by 25% or more in successive review cycles. For cutter importers, a 25% duty increase on a product with a 3% freight-to-cost ratio and 40–50% gross margins compresses per-unit net margin by approximately 10–15 percentage points unless pricing is adjusted. Brands without alternative sourcing in tariff-exempt jurisdictions absorb this directly or pass it through to retailers, risking volume loss at the price-sensitive end of the market.
Regional conflict and energy volatility continue to extend maritime transit times on Asia-to-Europe trade lanes critical for cutter supply chains. Data from the World Shipping Council indicates that rerouting around the Cape of Good Hope adds approximately 10–14 transit days versus Suez Canal routing, raising container fuel surcharges by an estimated 15–20% per voyage. For compact, high-value accessories such as premium cutters, the freight cost impact is modest in absolute terms but the extended lead time forces distributors to carry 20–30% more pipeline inventory. This ties up working capital and increases the risk of overstocking when demand signals shift mid-cycle.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 148.3 Million |
| Forecast Revenue (2035) | USD 275.3 Million |
| CAGR (2026-2035) | 6.4% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Type (Guillotine Cigar Scissors, Punch Cigar Cutter, V-Cutter, Double Blade Cutter, Shuriken Cutter, Others), By Sales Channel (Offline, Online) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Alfred Dunhill, Boveda Inc., Colibri Group, CREDO, Davidoff of Geneva USA, Lotus Group, Palió, Porsche Design Group, Quality Importers Trading Co., S.T. Dupont, Visol Products, XIKAR, Zino Davidoff, Other Key Players |
| Customization Scope | Customization for segments, region / country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License | Multi-User License (Up to 5 Users) | Corporate Use License (Unlimited User and Printable PDF) |








