


Market Overview
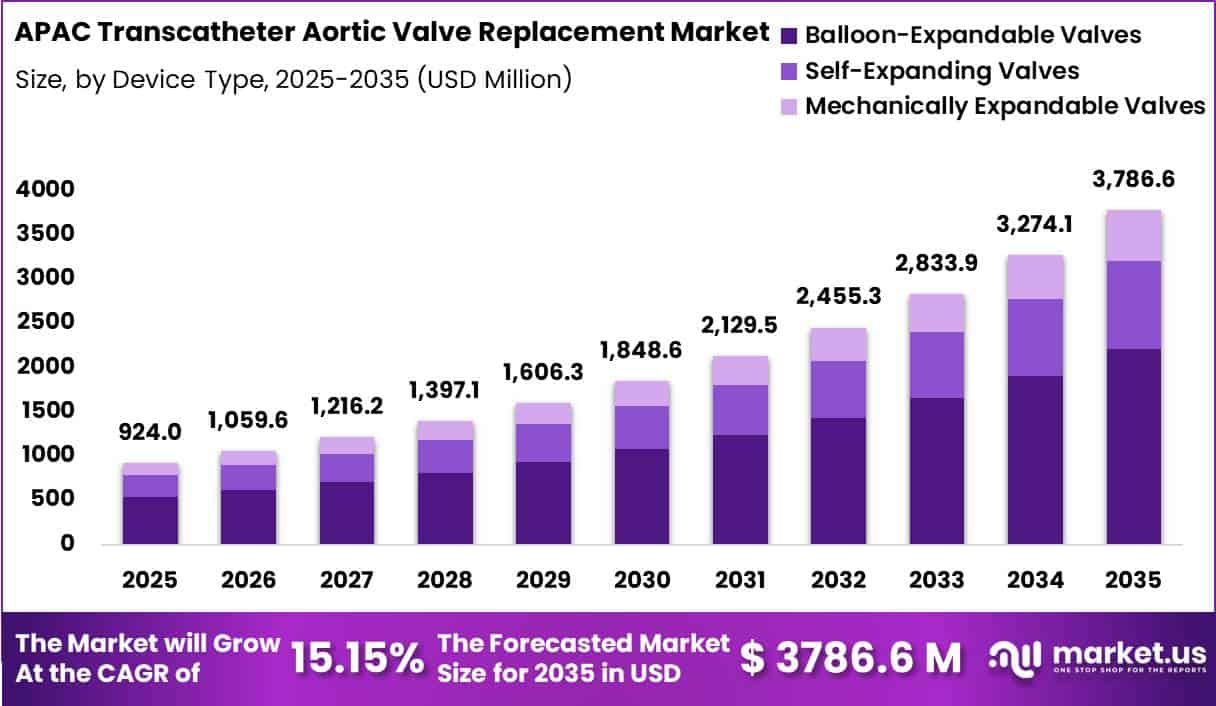
APAC Transcatheter Aortic Valve Replacement Market size is expected to be worth around US$ 3786.56 Million by 2035 from US$ 924.00 Million in 2025, growing at a CAGR of 15.15% during the forecast period from 2026 to 2035.
The Asia-Pacific (APAC) Transcatheter Aortic Valve Replacement (TAVR) market is witnessing strong momentum as healthcare systems focus on expanding access to minimally invasive cardiac procedures for patients with severe aortic stenosis (AS).
The region is experiencing rapid population aging, increasing cardiovascular disease burden, and greater adoption of structural heart interventions, all of which are supporting the wider use of TAVR. According to the Asian Pacific Society of Cardiology (APSC), TAVR has become an established treatment for severe symptomatic aortic stenosis, and its adoption is accelerating across APAC, although access and reimbursement policies still differ between countries.
The disease burden is expected to rise significantly as the elderly population expands. A recent review published in JACC: Asia reported that a national survey in China involving 34,994 adults aged 35 years and older found an overall aortic stenosis prevalence of 0.7%, increasing to 1.5% among people aged 65–74 years and 3.4% among those aged 75 years and above.
Researchers also noted that the actual burden across Asia-Pacific may be higher because of underdiagnosis, improving detection rates, and the region’s rapidly aging population of more than 1.5 billion East Asian residents.
Clinical evidence continues to strengthen confidence in TAVR. The Asia Pacific TAVI Registry reported a 97.5% 30-day survival rate among 1,125 patients, demonstrating outcomes comparable with international standards.
In addition, recent long-term clinical evidence presented by the American College of Cardiology showed that the Evolut Low Risk trial enrolled 1,478 patients across 86 centers and found similar five-year rates of death or disabling stroke between TAVR and surgical valve replacement in low-risk patients, supporting broader clinical adoption.
Governments, healthcare providers, and cardiac societies across the region are also investing in specialized heart teams, imaging capabilities, and catheter-based treatment infrastructure. As awareness of minimally invasive valve therapies increases and hospitals expand structural heart programs, APAC is expected to remain one of the fastest-growing regions for TAVR, supported by technological innovation, improving clinical expertise, and expanding access to advanced cardiovascular care.
Key Takeaways
- Market Size : APAC Transcatheter Aortic Valve Replacement Market size is expected to be worth around US$ 3786.56 Million by 2035 from US$ 924.00 Million in 2025.
- Market Share : The market is growing at a CAGR of 15.15% during the forecast period from 2026 to 2035.
- Device Type Analysis : The Balloon-Expandable Valves segment dominated the APAC Transcatheter Aortic Valve Replacement (TAVR) market with 58.35% of the market share in 2025.
- Procedure Type Analysis : The Transfemoral segment accounted for the largest share of 42.00% in 2025.
- Material Analysis : The Cobalt Chromium segment held the largest market share of 52.10% in 2025.
- Risk Category Analysis : The High Surgical Risk segment dominated the APAC TAVR market with 38.10% of the market share in 2025.
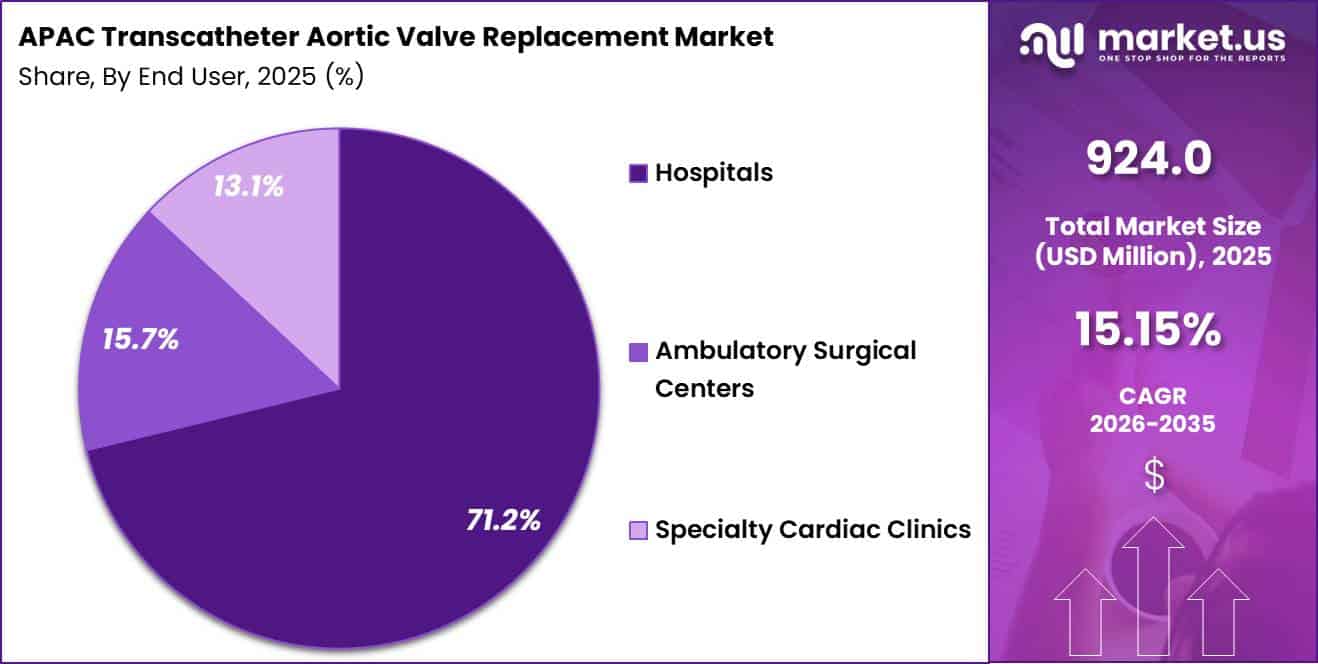
- End User Analysis : The Hospitals segment accounted for the largest share of 71.20% in 2025.
- Country Analysis : China dominated the APAC Transcatheter Aortic Valve Replacement market with 31.20% of the market share in 2025.
Device Type Analysis
The Balloon-Expandable Valves segment dominated the APAC Transcatheter Aortic Valve Replacement (TAVR) market with 58.35% of the market share in 2025. These valves are widely preferred because they offer precise deployment, excellent positioning accuracy, and strong clinical outcomes, particularly in patients with favorable anatomical characteristics.
Balloon-expandable valves have gained broad acceptance in countries such as Japan, Australia, and Singapore, where experienced heart teams and advanced imaging support complex structural heart procedures.
The growing use of newer-generation balloon-expandable systems with improved sealing and reduced paravalvular leakage has further strengthened segment growth. China’s approval of its first domestically developed balloon-expandable TAVR system also reflects increasing regional innovation.
Self-Expanding Valves represent the second-largest segment due to their ability to adapt to varying annulus sizes and heavily calcified valves. These devices are extensively used in China, where locally developed products from companies such as Venus Medtech, MicroPort, and Peijia have expanded availability.
Mechanically Expandable Valves account for a smaller share because of their limited commercial availability and narrower clinical adoption. However, ongoing technological improvements, physician experience, and broader reimbursement policies across APAC are expected to support continued growth across all valve categories.
Procedure Type Analysis
The Transfemoral segment accounted for the largest share of 42.00% in 2025. This approach remains the preferred access route because it is minimally invasive, avoids open-chest surgery, shortens hospital stays, and enables faster patient recovery.
Clinical guidelines across Asia-Pacific recommend transfemoral access whenever anatomically feasible, and improvements in low-profile delivery systems have increased its use even in patients with smaller peripheral vessels. Most commercially available TAVR systems in the region are designed primarily for transfemoral implantation, supporting its leadership.
The Transapical segment continues to serve patients whose femoral arteries are unsuitable because of severe vascular disease or anatomical limitations. Transaortic procedures remain limited and are generally performed only in selected complex cases requiring direct aortic access.
The Subclavian/Axillary segment is gaining gradual acceptance as an alternative access route for patients who cannot undergo transfemoral procedures while still avoiding transapical surgery.
Growing physician expertise, advanced imaging technologies, and better patient selection are expected to increase the use of alternative access techniques across major APAC cardiac centers, although transfemoral procedures are expected to remain the dominant approach throughout the forecast period.
Material Analysis
The Cobalt Chromium segment held the largest market share of 52.10% in 2025. This material is widely used in balloon-expandable valve frames because it provides high radial strength, durability, excellent fatigue resistance, and precise valve expansion.
These characteristics allow accurate positioning and stable long-term performance, making cobalt chromium the preferred material for several leading balloon-expandable TAVR systems used throughout Asia-Pacific. Continued adoption of advanced balloon-expandable technologies has reinforced demand for cobalt chromium frames.
Nitinol represents the second-largest material segment owing to its shape-memory and superelastic properties. These features enable self-expanding valves to adapt effectively to varying patient anatomies while maintaining consistent radial force.
Many domestically developed Chinese TAVR systems, including those from Venus Medtech, MicroPort, and Peijia, utilize nitinol frames, supporting segment growth. Other materials, including specialized alloys and polymer-based components, account for a relatively small market share and are mainly incorporated into selected valve designs and delivery systems.
Continuous advances in biomaterials, valve durability, and frame engineering are expected to enhance long-term clinical outcomes and support future innovation across all material categories.
Risk Category Analysis
The High Surgical Risk segment dominated the APAC TAVR market with 38.10% of the market share in 2025. TAVR was initially developed for patients considered unsuitable or at high risk for conventional surgical aortic valve replacement, making this group the largest contributor to current procedure volumes.
Elderly patients with multiple comorbidities continue to benefit significantly from minimally invasive valve replacement, especially across countries with aging populations such as Japan and China. Clinical guidelines across Asia-Pacific continue to recommend TAVR as a standard treatment option for many high-risk patients.
The Intermediate Surgical Risk segment has expanded steadily as long-term evidence demonstrates favorable safety and effectiveness compared with surgery. Hospitals across APAC are increasingly offering TAVR to appropriately selected intermediate-risk patients through multidisciplinary heart teams.
The Low Surgical Risk segment is experiencing the fastest future growth, supported by clinical trial evidence and regulatory approvals extending TAVR use to younger and healthier patient populations. As physician confidence, reimbursement coverage, and long-term durability data continue to improve, patient eligibility is expected to broaden across all surgical risk groups during the forecast period.
End User Analysis
The Hospitals segment accounted for the largest share of 71.20% in 2025. Most TAVR procedures require specialized catheterization laboratories or hybrid operating rooms, advanced cardiac imaging, intensive perioperative monitoring, and multidisciplinary heart teams consisting of interventional cardiologists, cardiac surgeons, anesthesiologists, and imaging specialists.
Large tertiary hospitals possess the infrastructure and clinical expertise required to perform these complex procedures safely, making them the primary treatment centers throughout Asia-Pacific.
Ambulatory Surgical Centers represent a smaller share because TAVR remains a highly specialized cardiovascular procedure requiring advanced emergency support and post-procedure monitoring. However, improvements in minimally invasive techniques and shorter recovery times may gradually increase outpatient procedural potential for selected low-risk patients.
Specialty Cardiac Clinics continue to play an important role in patient diagnosis, referral, follow-up care, and long-term valve monitoring rather than performing the procedure itself. Continued investments in structural heart programs, hospital infrastructure, physician training, and advanced imaging technologies across APAC are expected to strengthen hospital leadership while expanding the overall treatment network.
Country Analysis
China dominated the APAC Transcatheter Aortic Valve Replacement market with 31.20% of the market share in 2025. The country’s leadership is supported by its large elderly population, increasing prevalence of severe aortic stenosis, expanding number of TAVR centers, and rapid development of domestic valve manufacturers including Venus Medtech, MicroPort, Peijia Medical, and Shanghai NewMed Medical. Strong regulatory support and continued product approvals have accelerated market growth.
Japan represents the second-largest market due to its highly developed healthcare infrastructure, early adoption of TAVR, and one of the world’s oldest populations. India is witnessing rapid growth as more tertiary hospitals establish structural heart programs and awareness increases.
South Korea continues to expand TAVR through advanced cardiac centers and growing clinical expertise, while Australia benefits from favorable healthcare infrastructure and increasing use of minimally invasive valve therapies.
The Rest of Asia Pacific, including Singapore, Taiwan, Thailand, Malaysia, and other emerging markets, is steadily increasing TAVR adoption through expanding reimbursement, physician training, and improved access to advanced cardiovascular care.
Market Segmentations
By Device Type
- Balloon-Expandable Valves
- Self-Expanding Valves
- Mechanically Expandable Valves
By Procedure Type
- Transfemoral
- Transapical
- Transaortic
- Subclavian / Axillary
By Material
- Cobalt Chromium
- Nitinol
- Others
By Risk Category
- High Surgical Risk
- Intermediate Surgical Risk
- Low Surgical Risk
By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Cardiac Clinics
By Country
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
Drivers
Better APAC procedural outcomes and transfemoral standardization
Outcome visibility is now strong enough to act as a commercial growth driver because physicians, hospital administrators, and payers can justify expansion using local and regional evidence rather than relying only on Western registries.
The Asia meta-analysis covering 15,297 patients reported procedural success of 95.28%, 30-day mortality of 1.66%, 1-year mortality of 8.79%, stroke of 1.98%, major vascular complications of 2.58%, major bleeding of 3.88%, and pacemaker implantation of 7.76%; the APSC paper also cites 97.5% 30-day survival in the Asia Pacific TAVI Registry across 1,125 patients.
Just as important operationally, 81.8% of procedures in the meta-analysis used transfemoral access, which lowers procedural complexity, reduces surgical backup intensity, and supports faster patient turnover.
The commercial consequence is lower learning-curve risk for new centers and better utilization metrics for established centers, making procurement approvals easier and supporting adjacent revenue streams in imaging, cerebral protection, and follow-up management.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid ageing and severe AS case expansion | +2.4% | Japan core, South Korea, China tier-1 cities, Singapore, Taiwan, Australia; India/ASEAN spill-over | Long term (≥ 4 years) |
| Guideline broadening toward older and selected lower-risk cohorts | +1.9% | Japan, South Korea, Australia, Singapore, Taiwan, China tertiary centers | Medium term (2-4 years) |
| Reimbursement depth and public funding pathways | +2.1% | Japan core; Australia, South Korea, Taiwan selective support; China/India mixed access | Medium term (2-4 years) |
| Better APAC procedural outcomes and transfemoral standardization | +1.6% | Japan, Korea, Singapore, Hong Kong, Taiwan, China high-volume centers | Short term (≤ 2 years) |
| CT-led planning and anatomy-specific fit in Asian patients | +1.3% | China, Japan, Korea, Singapore, India referral hubs | Short term (≤ 2 years) |
| Regional center build-out and heart-team capacity scaling | +1.7% | China, India, Southeast Asia emerging corridors; Japan replacement-cycle support | Medium term (2-4 years) |
Challenge
Structural Under-Referral Limits TAVR Candidate Identification
Despite rising recognition of TAVR, multiple observational datasets and regional expert consensus statements show that a large proportion of symptomatic severe aortic stenosis patients in Asia never reach a valve team, with under-referral rates in some countries estimated at 40–60% due to late echocardiographic diagnosis, limited primary-care awareness, and fragmented cardiology networks.
Average patient ages at first specialist contact in published Asian cohorts are approximately 3–5 years younger than in European registries but with similar or higher comorbidity burdens, suggesting delayed recognition of disease progression and higher pre-intervention risk.
In lower-resource settings, fewer than 30–40 echocardiograms per 100,000 people per year are performed compared with >100 per 100,000 in more developed health systems, directly constraining pipeline identification and creating a 20–25% shortfall in addressable TAVR volumes relative to modeled epidemiologic need.
This systemic leakage exerts an estimated 1.3-point drag on CAGR by limiting growth in early-stage and intermediate-risk cases that typically expand volumes fastest once indications broaden.
Mitigation requires deployment of standardized AS screening protocols in primary care, such as mandated yearly auscultation and referral for 65+ patients with murmurs, expansion of portable echo programs in rural districts, and formalization of regional heart-team pathways with defined referral time standards, for example, <4 weeks from severe AS diagnosis to multidisciplinary board review, supported by digital referral platforms that integrate primary clinics with tertiary centers and reduce administrative lag by 10–15 days per patient.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Limited TAVR center density | -1.6% | Japan, South Korea, Tier-1 China, ANZ | Long term (≥ 4 years) |
| Structural under-referral of candidates | -1.3% | India, ASEAN, China inland | Medium term (2-4 years) |
| Device cost–reimbursement misalignment | -1.8% | India, ASEAN, China, selective OECD APAC | Long term (≥ 4 years) |
| Cath-lab and heart-team talent bottleneck | -1.4% | Broad APAC tertiary hubs | Long term (≥ 4 years) |
| Procedural outcome variability and registry gaps | -0.9% | Emerging APAC implants sites | Medium term (2-4 years) |
| Supply chain and logistics complexity | -0.7% | Wider APAC import-dependent markets | Short term (≤ 2 years) |
Restraints
High device and procedure cost with limited reimbursement
The single largest drag on APAC TAVR penetration is the combination of high per-procedure economics and patchy reimbursement, with average all-in TAVR episode costs in large Asian centers still in the range of 30,000–45,000 USD equivalent compared with 10–15 times median annual income in many emerging APAC economies, which directly limits eligible patient pools despite evidence of 95%+ procedural success and sub-3% 30-day mortality in Asian cohorts.
Japan is a notable outlier, as its universal insurance reimburses TAVR at close to 100% of allowable cost, but in China and India the self-pay share typically remains above 30–50% even when some public or private coverage is available, and in lower-income ASEAN markets out-of-pocket (OOP) spending can exceed 60% of total health expenditure, creating a structural affordability barrier for a therapy that competes with much cheaper medical management or delayed surgery.
Our modeling assumes that in 2026 only 10–15% of clinically eligible severe aortic stenosis patients in China and India actually receive TAVR, primarily due to cost and coverage gaps, and that each 10 %-point improvement in third-party coverage, public or private, lifts TAVR procedure volume by roughly 7–9% with an 18–24 month lag as centers ramp capacity and referral pathways normalize.
Strategically, this cost-coverage mismatch compresses margins because multinational OEMs face intense pressure to discount valves by 15–25% in national or provincial tenders to win volume, while hospitals often cross-subsidize TAVR programs from higher-margin interventional cardiology services and delay incremental cath-lab CapEx; we therefore haircut the baseline APAC TAVR CAGR by about 2 % points over 2026–2032 to reflect slower adoption in price-sensitive segments and a longer payback period, often 5–7 years instead of 3–4, for new TAVR programs in emerging markets.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High device and procedure cost with limited reimbursement | -2.0% | China, India, ASEAN, Rest of APAC | Medium term (2–4 years) |
| Regulatory and HTA approval delays for new valves | -1.2% | China, South Korea, ASEAN, Australia/NZ | Medium term (2–4 years) |
| Shortage of TAVR-capable centers and operators | -1.5% | India, ASEAN, secondary Chinese cities | Long term (≥ 4 years) |
| Procedural risk, comorbidity burden and data gaps | -0.8% | Emerging APAC, elderly high-risk cohorts | Short–Medium term (≤ 4 years) |
| Macro health-budget constraints and OOP exposure | -1.0% | Emerging APAC (India, ASEAN, rural China) | Long term (≥ 4 years) |
Opportunity
Mid-Income Self-Pay TAVR Segment Expands APAC Access
Today, TAVR access in APAC is concentrated in fully reimbursed systems, Japan and selected private hospitals in Australia/Singapore, and high-income urban patients, while most middle-income and rural populations face prohibitive out-of-pocket costs, limited reimbursement, and underdeveloped insurance products.
Yet valvular heart disease prevalence across APAC is high, with rheumatic and degenerative aortic stenosis reported at several cases per 1,000 in major economies, implying a structurally large “missing” cohort that is clinically eligible but financially excluded.
If manufacturers and hospitals co-develop tiered TAVR offerings, lower-cost device portfolios, bundled procedure pricing around USD 12,000–20,000 per case, and micro-insurance or community health financing models that reduce upfront out-of-pocket exposure by 40–60%, they could unlock an incremental APAC TAM of USD 2–3 billion by 2035 beyond current forecasts, assuming penetration into just 10–15% of the presently untreated, hemodynamically severe AS pool.
Because baseline market projections typically assume continuation of current reimbursement and high-cost structures, capturing this mid-income self-pay segment represents a true opportunity.
It requires new financial engineering, installment plans, micro-insurance riders, regional philanthropic co-funding, and differentiated unit economics where CAC per eligible patient can be cut by 25–30% through targeted referral networks and primary-care channel partnerships, shifting the margin profile from 20% contribution margins today to potentially 30–35% on standardized, higher-volume mid-tier offerings.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Mid-income self-pay & micro-insurance TAVR segment | +2.8% | India, Southeast Asia, China tier-2/3 | Medium term (2-4 years) |
| Day-care / minimalist TAVR pathways | +2.2% | Japan, South Korea, Australia, urban China | Short term (≤ 2 years) |
| Younger low-risk & rheumatic AS population expansion | +3.5% | India, China, Southeast Asia, Central Asia | Long term (≥ 4 years) |
| Regional manufacturing+design hubs for value TAVR | +2.0% | China, India, Singapore, South Korea | Medium term (2-4 years) |
| Digital/remote structural heart networks & triage | +1.8% | APAC emerging (Indonesia, Vietnam, Philippines) | Medium term (2-4 years) |
| Valve lifetime management (TAVR-in-TAVR & long-term bundles) | +2.4% | Developed APAC (Japan, Australia, South Korea) | Long term (≥ 4 years) |
Key Countries
- China
- India
- Japan
- South Korea
- ASEAN
- Australia & New Zealand
- Rest of Asia Pacific
Key Player Analysis
The APAC Transcatheter Aortic Valve Replacement (TAVR) market is highly competitive, with leading global and regional companies focusing on product innovation, physician training, and expanding access to minimally invasive heart valve therapies.
Edwards Lifesciences Corporation and Medtronic plc remain key market participants due to their broad TAVR product portfolios, strong clinical evidence, and collaborations with hospitals across Asia-Pacific. Abbott Laboratories and Boston Scientific Corporation support the structural heart segment through advanced cardiovascular technologies, imaging solutions, and catheter-based treatment platforms that strengthen procedural outcomes.
Regional manufacturers are also gaining market presence by developing products tailored to local healthcare needs. MicroPort Scientific Corporation, Venus Medtech (Cayman) Inc., Peijia Medical Limited, and Suzhou Jiecheng Medical Technology are investing in next-generation transcatheter valve systems, clinical studies, and regulatory approvals across major APAC countries.
These companies are expanding manufacturing capabilities and working closely with healthcare providers to improve treatment availability. Continuous technological improvements, physician education programs, and growing investments in structural heart care are expected to intensify competition and support further growth of the APAC TAVR market.
Top Key Players
- Edwards Lifesciences Corporation
- Medtronic plc
- Abbott Laboratories
- Boston Scientific Corporation
- MicroPort Scientific Corporation
- Venus Medtech (Cayman) Inc.
- Peijia Medical Limited
- Suzhou Jiecheng Medical Technology
- Meril Life Sciences Pvt. Ltd.
- Shanghai NewMed Medical
- Shenzhen Core Medical Technology
- Braile Biomédica
Recent Developments
- In March 2025, Medtronic plc announced five-year results from the Evolut Low Risk Trial, showing the Evolut™ TAVR system achieved a 15.5% rate of all-cause mortality or disabling stroke versus 16.4% for surgery at five years, with sustained valve performance in low-risk severe aortic stenosis patients. The results were presented at ACC.25 and simultaneously published in JACC.
- In May 2025, Edwards Lifesciences Corporation announced that the U.S. FDA approved the SAPIEN 3 TAVR system for patients with asymptomatic severe aortic stenosis, making it the first TAVR therapy approved for this indication and expanding treatment eligibility before symptom onset.
- In June 2025, Meril Life Sciences Pvt. Ltd. launched MyClip, India’s first Transcatheter Edge-to-Edge Repair (TEER) system for severe mitral regurgitation. The launch strengthens Meril’s structural heart portfolio alongside its Myval transcatheter heart valve platform and expands minimally invasive valve therapy offerings across Asia.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | US$ 924.00 Million |
| Forecast Revenue (2035) | US$ 3786.56 Million |
| CAGR (2026-2035) | 15.15% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Device Type (Balloon-Expandable Valves, Self-Expanding Valves, Mechanically Expandable Valves), By Procedure Type (Transfemoral, Transapical, Transaortic, Subclavian / Axillary), By Material (Cobalt Chromium, Nitinol, Others), By Risk Category (High Surgical Risk, Intermediate Surgical Risk, Low Surgical Risk), By End User (Hospitals, Ambulatory Surgical Centers, Specialty Cardiac Clinics), By Country (China, Japan, India, South Korea, Australia, Rest of Asia Pacific) |
| Regional Analysis | North America – The US, Canada; Europe – Germany, France, U.K., Italy, Spain, Russia & CIS, Rest of Europe; Asia Pacific – China, India, Japan, South Korea, ASEAN, Australia & New Zealand, Rest of Asia Pacific; Middle East & Africa – GCC, South Africa, Rest of Middle East & Africa; Latin America – Brazil, Mexico, Rest of Latin America |
| Competitive Landscape | Edwards Lifesciences Corporation, Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, MicroPort Scientific Corporation, Venus Medtech (Cayman) Inc., Peijia Medical Limited, Suzhou Jiecheng Medical Technology, Meril Life Sciences Pvt. Ltd., Shanghai NewMed Medical, Shenzhen Core Medical Technology, Braile Biomédica |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








