Report Overview
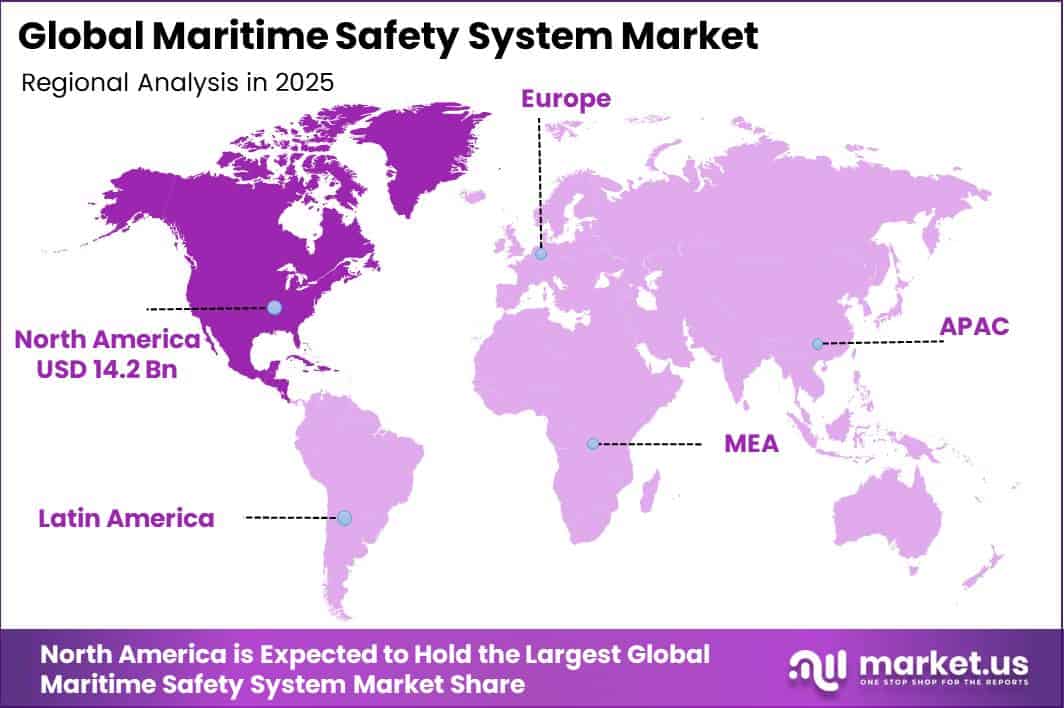
In 2025, the Global Maritime Safety System Market was valued at USD 31.5 billion. The market is projected to grow at a CAGR of 7.6% during 2026–2035, reaching approximately USD 65.5 billion by 2035. North America dominated the global market in 2025, accounting for more than 45.3% of the total market share and generating approximately USD 14.2 billion in revenue.
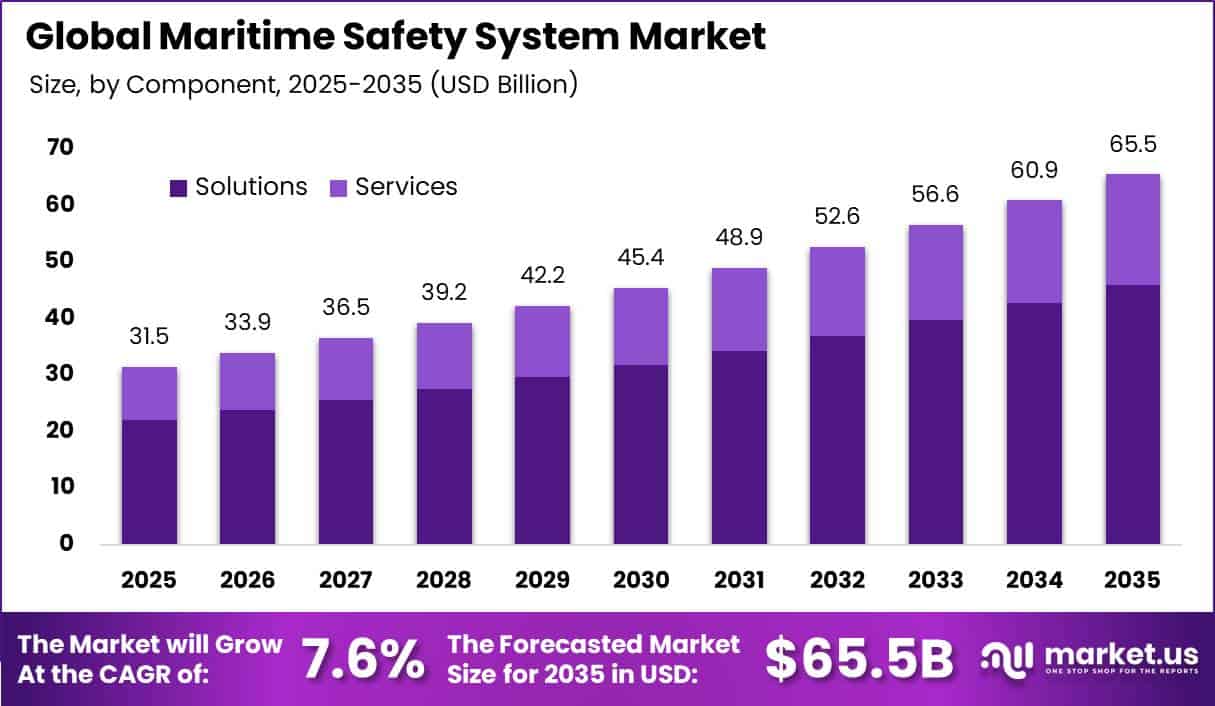
Market growth is closely linked to rising global seaborne trade and the increasing number of commercial vessels. According to the United Nations Conference on Trade and Development (UNCTAD), global seaborne trade exceeded 12.7 billion tons in 2024, the highest level recorded, and is expected to grow at an average annual rate of 2% between 2026 and 2030.
Shipping route disruptions also increased ton-mile demand by 5.9% in 2024, mainly due to Red Sea diversions around the Cape of Good Hope. As of January 2025, the global merchant fleet included around 112,500 ships with combined capacity of 2.4 billion deadweight tons. These vessels must comply with International Maritime Organization (IMO) safety requirements covering life-saving, fire protection, emergency communication, and navigation equipment, creating steady demand for maritime safety systems.
Key Takeaway
- The Maritime Safety System Market was valued at USD 31.5 billion in 2025 and is projected to reach USD 65.5 billion by 2035, growing at a CAGR of 7.6%.
- The Solutions segment was dominated by components, holding a 70.2% share of the market.
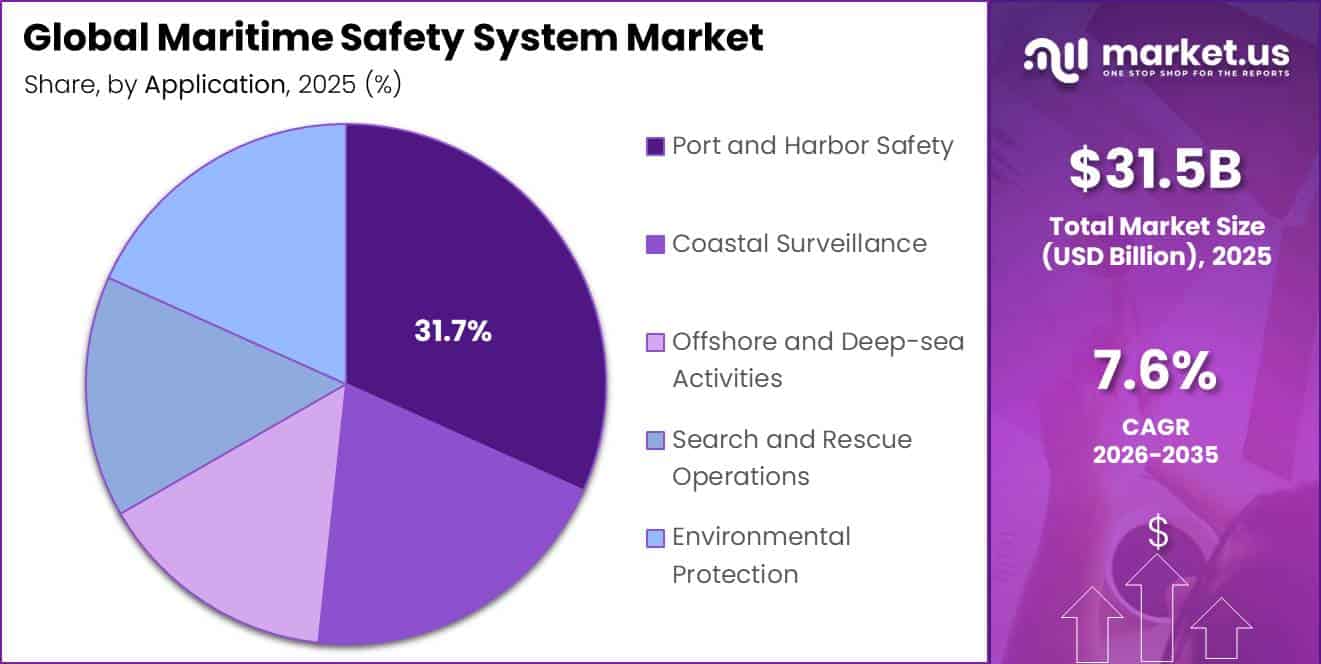
- Port and Harbor Safety led by application, capturing a 31.7% share.
- Commercial Vessels held the largest end-user share at 43.1%.
- North America led the market in 2025 with a 45.3% share, generating approximately USD 14.2 billion in revenue.
By Component
The Solutions segment held a dominant 70.2% share of the Maritime Safety System Market, mainly because maritime safety compliance depends heavily on physical equipment and onboard systems. Port State Control inspection data supports this trend.
The Paris Memorandum of Understanding recorded 16,508 inspections in 2024, with fire-safety equipment failures under SOLAS Chapter II-2 accounting for 17.2% of reported deficiencies, followed by problems related to life-saving appliances.
Across five major Port State Control regimes, more than 71,730 inspections in 2024 resulted in over 150,000 deficiencies, with fixed fire installations, lifeboat conditions, and fire pumps among the frequently identified issues.
In addition, the United Nations Conference on Trade and Development reported that 71.7 million gross tons of new vessels were delivered in 2024. Each newly delivered vessel requires a complete safety-equipment package before certification and commercial operation.
By Application
The Port and Harbor Safety segment held a leading 31.7% share of the Maritime Safety System Market, supported by rising cargo volumes and increasingly congested port operations. According to the United Nations Conference on Trade and Development, global container port throughput reached 920 million TEUs in 2024, increasing by 6.9%, while container ship port calls remained close to a record 260,000 per half-year.
Higher vessel traffic and faster cargo movement increase operational pressure at major terminals and raise the risk of collisions, fires, grounding incidents, and berthing accidents. Lloyd’s List reported that the world’s top 20 ports handled approximately 414.6 million TEUs in 2024, representing growth of 8.1%.
By End-User
The Commercial Vessels segment held a dominant 43.1% share of the Maritime Safety System Market, mainly due to its large presence in the global shipping fleet and strict safety requirements. According to UNCTAD, bulk carriers accounted for 42.5% of global fleet capacity, equal to around 1.04 billion dwt, while oil tankers represented another 27.5%, or approximately 670 million dwt, as of January 2025.
These commercial vessels are required to carry certified fire protection, life-saving, emergency communication, and navigation systems to meet international maritime regulations. The global container ship fleet also expanded by 9.7% year-on-year to reach 363.8 million dwt, showing continued investment in new commercial vessels.
Key Market Segments
By Component
- Solutions
- Services
By Application
- Port and Harbor Safety
- Coastal Surveillance
- Offshore and Deep-sea Activities
- Search and Rescue Operations
- Environmental Protection
By End-User
- Commercial
- Defense
- Government
- Other
Geopolitical Impact Analysis
Ongoing Red Sea tensions are continuing to reshape the maritime safety equipment supply chain by increasing shipping time, operating costs, and equipment demand. As of May 2025, Suez Canal transits remained around 70% below 2023 levels, forcing many vessels to reroute around the Cape of Good Hope.
According to UNCTAD, these diversions can add around 10–14 days to a voyage and increase fuel costs by as much as USD 1 million per voyage. Longer routes have increased Southeast Asia-to-US East Coast transit times by 47% and China-to-Europe transit times by 25%, slowing the movement of fire-suppression systems, life rafts, EPIRBs, and other safety components supplied from Asian manufacturing centers.
Longer voyages also increase equipment usage and wear, supporting faster replacement cycles. On the manufacturing side, US Section 232 tariffs restructured on April 2, 2026, introduced a 50% duty on selected steel, aluminum, and copper inputs under Annex I-A and a 25% duty on derivative products, including fabricated safety-equipment housings and lifeboat davits, under Annex I-B.
The weighted average US tariff rate reached 10.8% in 2026, its highest level since 1969, while Russian-origin aluminum inputs face tariffs of 200%. These pressures are raising input and landed costs across maritime safety supply chains, while longer and higher-risk shipping routes are simultaneously supporting stronger demand for compliant safety equipment.
Regional Analysis
North America remained the dominant region in the Maritime Safety System Market, accounting for 45.3% of the market and generating approximately USD 14.2 billion in 2025. The region’s strong position is supported by its large commercial and government vessel fleet, advanced port infrastructure, and strict maritime safety regulations.
The US Coast Guard operated around 241 cutters and nearly 1,508 smaller vessels, all requiring certified life-saving, fire protection, communication, and navigation equipment under federal maritime safety rules. Large deep-water ports, busy shipping routes, and regular compliance inspections by the US Coast Guard and Transport Canada also support steady replacement and upgrade demand for maritime safety systems.
Asia Pacific is the fastest-growing region, mainly driven by strong shipbuilding activity in East Asia. China completed approximately 53.6 million deadweight tons of new vessels in 2025, representing 56.1% of global shipbuilding output. Chinese shipyards also secured around 69% of global new ship orders and held 66.8% of the total orderbook.
South Korea accounted for about 20% of new orders, while Japan contributed roughly 5–9%. Every new vessel must install SOLAS-compliant fire safety, life-saving, and navigation systems before certification. This large construction pipeline, combined with rising container trade and expanding port capacity across South and Southeast Asia, is supporting faster demand growth for maritime safety equipment across Asia Pacific.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Drivers
| Driver | (~) % CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| IMO SOLAS retrofit and newbuild compliance cycle | +2.1% | Global | Short term (2 years or less) |
| Record shipyard delivery volumes in East Asia | +1.8% | Asia Pacific | Short term (2 years or less) |
| Port State Control enforcement intensity | +1.2% | Europe, North America | Medium term (2 to 4 years) |
| Rising ton-mile demand from route rerouting | +0.9% | Global | Short term (2 years or less) |
| Naval and coast guard fleet recapitalization budgets | +0.7% | North America, Europe | Medium term (2 to 4 years) |
IMO SOLAS retrofit and newbuild compliance cycle
The strongest active driver in the Maritime Safety System Market is the mandatory SOLAS-linked equipment cycle. Every new vessel and ship undergoing periodic certification must carry approved life-saving, fire-suppression, and navigation systems before receiving flag-state clearance.
This makes safety equipment spending largely non-discretionary and is estimated to add around 2.1% incremental growth above the market’s 7.6% baseline CAGR. Port State Control inspections further support recurring demand, as fire-safety and life-saving equipment deficiencies remain major causes of vessel detention.
Shipowners therefore need to repair or replace non-compliant systems within limited survey windows. This recurring certification cycle helps safety-system suppliers build steadier aftermarket revenue and could support gross margins around 200 to 300 basis points higher than more discretionary marine equipment categories.
Restraints
| Restraint | (~) % CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Steel, aluminum, and copper input tariffs | -1.4% | North America | Short term (2 years or less) |
| High interest rate environment delaying fleet CapEx | -0.8% | Global | Short term (2 years or less) |
| Shipowner capital rationing amid freight rate softness | -0.6% | Global | Medium term (2 to 4 years) |
| Export licensing restrictions on dual-use safety electronics | -0.4% | Europe, Asia Pacific | Medium term (2 to 4 years) |
Steel, aluminum, and copper input tariffs
A major near-term challenge in the Maritime Safety System Market is the rise in Section 232-linked metal tariffs. Core steel and aluminum inputs can face duties of up to 50%, while some derivative safety-equipment housings and davit assemblies face an additional 25% tariff.
Higher material costs are estimated to reduce gross margins for North American safety-system manufacturers by around 300 to 400 basis points. In response, companies may delay capacity expansion, absorb part of the cost, or shift component sourcing closer to domestic markets. These adjustments could postpone capital investment decisions over the next 18 to 24 months, creating short-term pressure on production capacity and market growth.
Challenges
| Challenge | (~) % CAGR | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Marine electronics engineering talent shortage | -0.7% | Europe, North America | Long term (4 years or more) |
| Red Sea rerouting logistics disruption | -0.6% | Global | Medium term (2 to 4 years) |
| Fragmented regional certification standards | -0.5% | Asia Pacific, Africa | Long term (4 years or more) |
| Legacy fleet retrofit complexity | -0.4% | Global | Medium term (2 to 4 years) |
Marine electronics engineering talent shortage
A key structural challenge in the Maritime Safety System Market is the shortage of skilled marine electronics and systems-integration engineers. Limited engineering capacity can extend project timelines by an estimated 4 to 8 additional weeks for each vessel-class certification project, slowing order conversion and revenue recognition.
To reduce this pressure, companies are expected to increase automation in design and testing, expand apprenticeship and technical training programs, and shift lower-complexity assembly work to lower-cost locations. Until then, the shortage of qualified technical staff could create an estimated 0.7% drag on the market’s achievable growth potential.
Opportunities
| Opportunity | (~) % CAGR | Geographic Relevance | Execution Window |
|---|---|---|---|
| Predictive safety-as-a-service subscription monetization | +1.6% | Global | Medium term (2 to 4 years) |
| Autonomous and remotely operated vessel safety retrofits | +1.1% | Europe, Asia Pacific | Long term (4 years or more) |
| Inland waterway and offshore wind vessel expansion | +0.8% | Europe, Asia Pacific | Medium term (2 to 4 years) |
| Emerging-market coast guard modernization roll-ups | +0.6% | Southeast Asia, Africa, Middle East | Long term (4 years or more) |
Predictive safety-as-a-service subscription monetization
A major untapped opportunity in the Maritime Safety System Market is the shift from one-time hardware sales toward predictive, subscription-based monitoring services. Compared with hardware-only sales, software and data services could improve blended gross margins by an estimated 500 to 800 basis points, supported by higher-margin industrial IoT business models.
To capture this opportunity, suppliers would need to move from capital equipment contracts toward multi-year service agreements with shipowners. Although adoption remains at an early pilot stage, the global merchant fleet of around 112,500 vessels offers a large potential customer base.
Key Players Analysis
The Maritime Safety System Market is led by a Tier-1 group of large defense and marine electronics companies with strong exposure to naval and commercial shipping. Kongsberg Gruppen reported full-year 2025 revenue of NOK 58.6 billion, with underlying growth of 17%. Its Kongsberg Maritime business generated NOK 27.1 billion, up 10% year-on-year, while aftermarket services represented 54% of segment revenue.
Thales Group recorded 2025 sales of EUR 22.1 billion, while its Defence segment reported order intake of EUR 15.1 billion and a book-to-bill ratio of 1.24, showing continued demand across naval and safety-related systems. Wärtsilä ended 2025 with net sales of EUR 6.9 billion, while Marine and Energy order intake also reached EUR 6.9 billion, increasing 17% on strong demand from cruise, container, and LNG-bunkering vessels.
Tier-2 companies are expanding through specialized surveillance, tracking, and navigation solutions. SRT Marine Systems increased revenue by 426% to GBP 78.0 million for the year ended June 2025. Its Maritime Domain Awareness business contributed GBP 68.5 million, while navigation safety generated GBP 9.5 million.
Gross margin improved to 31% from 28%. Other major competitors include Honeywell, Saab, Northrop Grumman, BAE Systems, Leonardo, and Elbit Systems, which mainly supply maritime safety technologies through larger defense and naval contracts.
Top Key Players in the Market
- Kongsberg Gruppen
- Honeywell International Inc.
- Saab AB
- Thales Group
- Northrop Grumman Corporation
- Raytheon Technologies Corporation
- Wärtsilä Corporation
- BAE Systems
- Leonardo S.p.A.
- Elbit Systems Ltd.
- Navico
- SRT Marine Systems
Recent Developments
- In 2026, SRT Marine Systems signed a new US$261 million maritime surveillance contract with a new sovereign customer for a national SRT-MDA system. The final contract value increased from an earlier estimate of around US$200 million.
- SRT also signed a separate US$20.5 million follow-on contract with an existing sovereign customer to expand an established maritime surveillance system, showing continued demand for national-scale maritime safety and monitoring solutions.
- In 2026, Kongsberg Maritime became an independently listed maritime technology company on Euronext Oslo Børs on April 23, 2026, following its separation from Kongsberg Gruppen. Later, on July 12, 2026, the company agreed to acquire Swedish propulsion specialist Berg Propulsion.
- Berg generated approximately EUR 160 million in revenue in 2025 and has an installed base of around 4,000 vessels, while Kongsberg Maritime systems operate on more than 30,000 vessels. The acquisition is expected to strengthen Kongsberg Maritime’s propulsion, vessel-control, and lifecycle service portfolio.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 31.5 Billion |
| Forecast Revenue (2035) | USD 65.5 Billion |
| CAGR (2026-2035) | 7.6% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Component: (Solutions, Services); By Application: (Port and Harbor Safety, Coastal Surveillance, Offshore and Deep-sea Activities, Search and Rescue Operations, Environmental Protection); (By End-User: Commercial, Defense, Government, Other) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | Kongsberg Gruppen, Honeywell International Inc., Saab AB, Thales Group, Northrop Grumman Corporation, Raytheon Technologies Corporation, Wärtsilä Corporation, BAE Systems, Leonardo S.p.A., Elbit Systems Ltd., Navico, SRT Marine Systems |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited Users and Printable PDF) |