


Report Overview
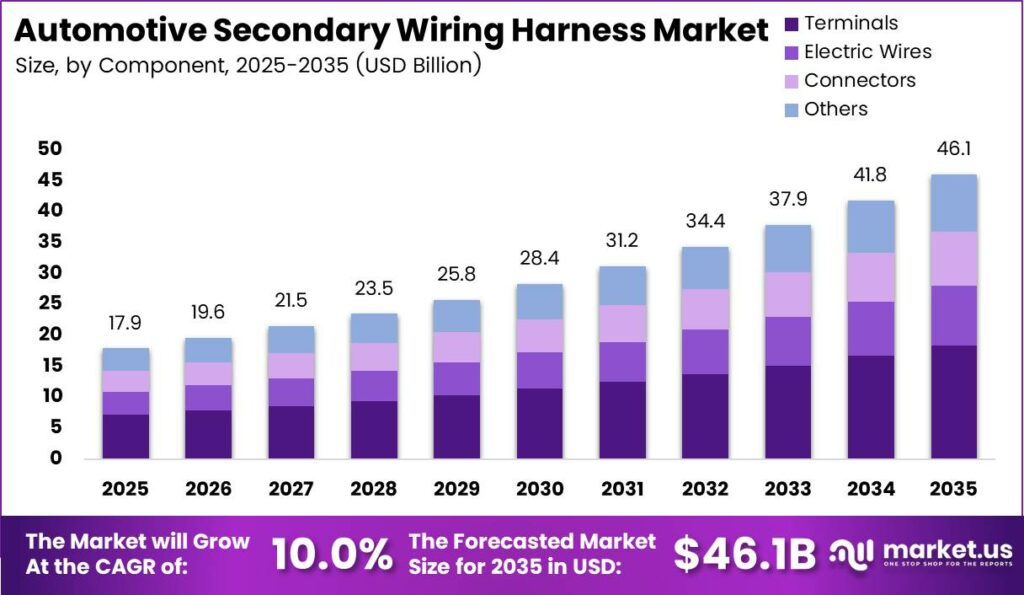
Global Automotive Secondary Wiring Harness Market size is expected to be worth around USD 46.1 Billion by 2035 from USD 17.9 Billion in 2025, growing at a CAGR of 10.0% during the forecast period 2026 to 2035.
According to OICA, global vehicle production reached 96.4 million units in 2025, up 3.9% from 92.7 million units in 2024. Vehicle sales climbed to 99.8 million units, a 4.7% increase from 95.3 million units. This volume expansion directly scales secondary harness demand, since every new vehicle requires a complete wiring subsystem.
The automotive secondary wiring harness market covers all non-primary electrical interconnect assemblies installed in a vehicle, including chassis, body, engine, HVAC, and sensor harness subsystems. These assemblies route low-voltage signal and power circuits to vehicle zones not served by the main power harness. The market spans terminals, electric wires, connectors, and associated insulation, serving passenger cars and commercial vehicles across global OEM and aftermarket channels.
Key Takeaways
- The global Automotive Secondary Wiring Harness Market was valued at USD 17.9 Billion in 2025 and is forecast to reach USD 46.1 Billion by 2035, at a CAGR of 10.0%.
- By Component, Terminals dominate with a 38.76% share in 2025.
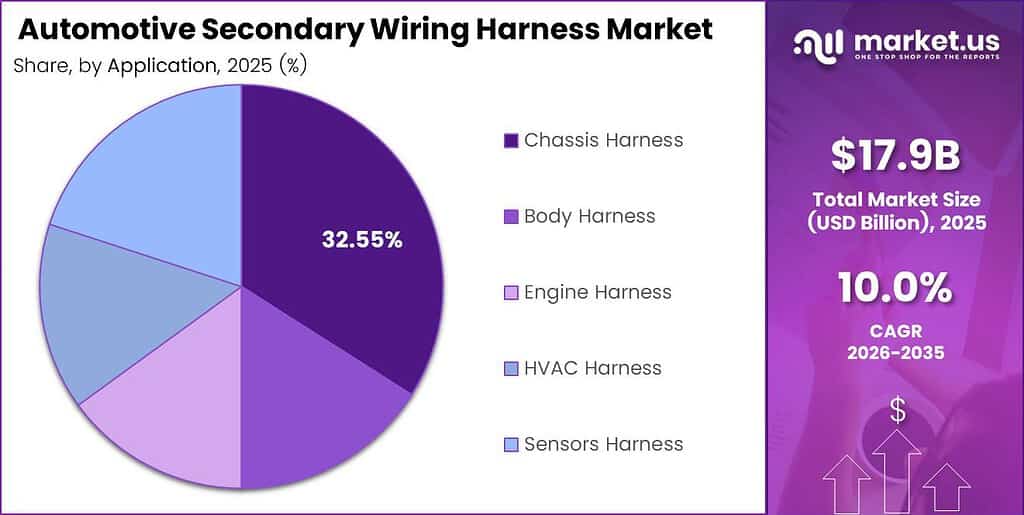
- By Application, Chassis Harness holds the largest share at 32.55%, while Sensors Harness is the fastest-growing sub-segment.
- By Vehicle Type, Passenger Cars lead with a 68.78% share and are also the fastest-growing segment.
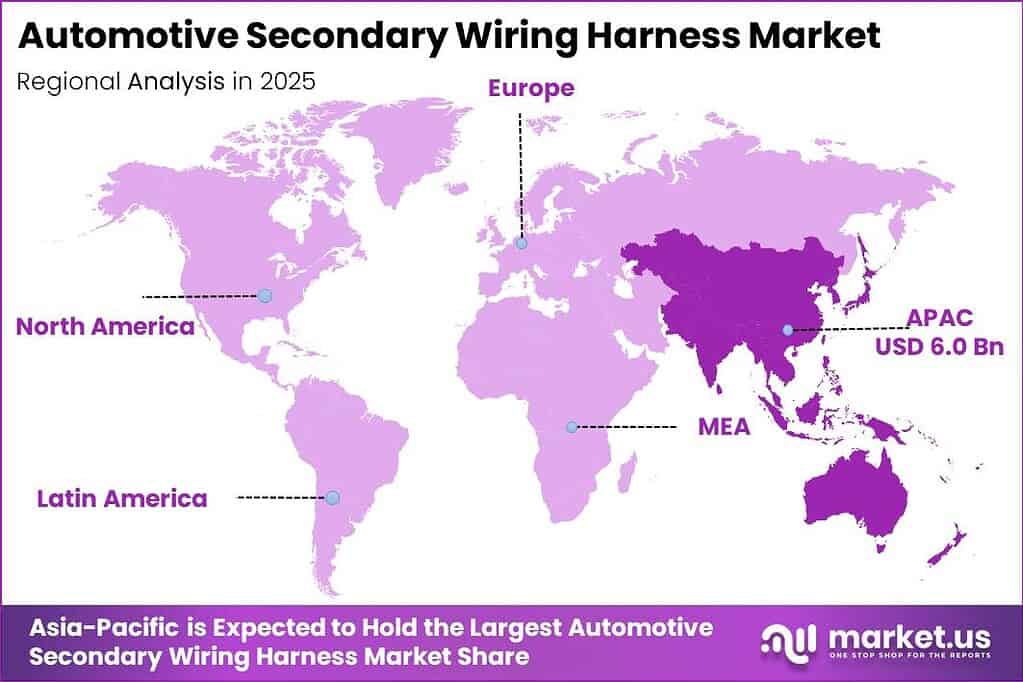
- Asia-Pacific is the dominant region with a 34.21% share and is also the fastest-growing region.
As reported by ACEA, global new-car registrations reached 77.6 million units in 2025, up 3.5%. This sustained production growth confirms a structurally expanding installed base for secondary harness content. Each additional vehicle on the road represents a direct unit of incremental harness demand at the OEM assembly level.
As per our research, India registered 1.97 million electric vehicles in FY2024–25, up 16.9% from 1.68 million in FY2023–24. Electric passenger-vehicle registrations exceeded 100,000 units, growing 18.2%. This pace signals a structural build in high-voltage harness content requirements across the Indian OEM base, creating a near-term demand step-up for suppliers serving domestic assemblers.
IEA data shows global electric-car sales exceeded 20 million units in 2025, rising 20% and representing 25% of all new-car sales. Battery-electric platforms require materially more harness content per vehicle than combustion equivalents. This volume and mix shift directly expands the total addressable market for secondary wiring harness suppliers focused on EV platforms. Leoni completed the ATLAS-L4 autonomous-truck project in May 2025, which received nearly €60 million in funding and engaged approximately 150 engineers, signaling active industry investment in next-generation vehicle wiring architectures.
WTO data shows world automotive-product trade declined 1% in 2024 after rising 20% in 2023, while world merchandise-trade volume increased 3.6% quarter-on-quarter and 5.3% year-on-year in Q1 2025. This divergence highlights regional supply-chain realignment as the primary structural force shaping harness procurement patterns. Suppliers positioned close to OEM assembly clusters stand to capture share as trade friction redirects sourcing decisions.
Component Analysis
Terminals dominate with 38.76% share due to high per-connector volume in complex vehicle looms.
In 2025, Terminals held a dominant market position in the By Component segment of the Automotive Secondary Wiring Harness Market, with a 38.76% share. Terminals function as the mechanical and electrical interface between wire and connector body, and every circuit junction in a secondary loom requires at least one terminal. This volume multiplier effect locks in terminal demand regardless of vehicle platform or powertrain type, making the sub-segment structurally insulated from technology shifts.
Electric Wires form the backbone conductor layer of every secondary harness assembly. The World Bank projected overall commodity prices to decline 12% in 2025 and another 5% in 2026. However, its downside scenario flagged a 19% decline in average copper prices between 2024 and 2025. Wire cost pressure from tariff actions therefore operates against a softer base commodity price, creating a net margin environment that varies sharply by supplier hedging strategy and sourcing geography.
Connectors are the fastest-growing sub-segment within the By Component segment. Global EV battery deployment reached 1.2 TWh in 2025, almost 30% higher than in 2024, and light-duty vehicles represented more than 85% of that deployment. Each battery pack and power-management system requires dedicated high-voltage connector sets. This direct linkage to EV battery proliferation positions the connector sub-segment as the highest near-term volume growth node in the component mix.
Lithium-iron-phosphate batteries represented more than 55% of globally deployed EV batteries in 2025. LFP packs operate at distinct voltage and thermal profiles that impose specific insulation and connector-rating requirements. This chemistry dominance shapes secondary harness specification standards. Others, including insulation sleeves, tapes, and protective conduits, collectively hold the remaining component share and serve as margin-supporting consumables across all vehicle and powertrain types.
Application Analysis
Chassis Harness dominates with 32.55% share due to high circuit density across all vehicle platforms.
In 2025, Chassis Harness held a dominant market position in the By Application segment of the Automotive Secondary Wiring Harness Market, with a 32.55% share. The chassis harness integrates braking, suspension, lighting, and powertrain control circuits, making it a mandatory assembly across every vehicle platform regardless of drivetrain. This universal fitment requirement and high per-vehicle circuit count give chassis harness a structurally stable volume base that does not depend on optional feature adoption.
Body Harness routes interior comfort, door, seat, and lighting circuits and represents the second-largest application sub-segment by revenue contribution. Indian passenger-vehicle exports reached 905,000 units in FY2025–26, up 17.5%, while commercial-vehicle exports reached 95,000 units, up 17.4%. This export growth expands the addressable assembly base for body harness suppliers operating within Indian OEM supply chains.
Engine Harness covers all under-hood sensor, injector, and ignition connections and retains relevance across both combustion and hybrid platforms. As per SIAM data, India recorded passenger-vehicle sales of 4,643,439 units in FY2025–26, up 7.9%, and commercial-vehicle sales of 1,079,871 units, up 12.6%. This combined sales volume directly translates into harness content demand at Indian assembly plants, supporting sustained engine harness order volumes from domestic OEM customers.
Sensors Harness is the fastest-growing application sub-segment, driven by mandatory ADAS fitment across new model lines. All 20 participating automakers equipped at least 95% of applicable US light vehicles with automatic emergency braking by the 2023 production-year deadline. The US AEB standard is projected to prevent at least 24,000 injuries and save at least 360 lives annually. Each AEB-equipped vehicle requires dedicated sensor-node cabling, directly expanding the sensors harness content opportunity per unit. HVAC Harness holds the remaining share, serving thermal management circuits in both combustion and battery-electric platforms.
Vehicle Type Analysis
Passenger Cars dominate with 68.78% share due to higher per-unit electronic content versus commercial vehicles.
In 2025, Passenger Cars held a dominant market position in the By Vehicle Type segment of the Automotive Secondary Wiring Harness Market, with a 68.78% share, and are also the fastest-growing sub-segment. Battery-electric cars accounted for 65% of global electric-car sales in 2025. This BEV concentration within the passenger-car segment directly amplifies per-unit harness content, since each BEV requires substantially more secondary wiring than its combustion equivalent.
Uno Minda approved an EV-powertrain components plant costing approximately INR 4.23 billion and planned a 70% interest in the associated joint venture in April 2025, reflecting supplier-side conviction in passenger-car EV content growth. In May 2026, Uno Minda announced a second EV-powertrain facility in Maharashtra with an investment of INR 5.50 billion, confirming an accelerating commitment to passenger-car harness capacity.
Commercial Vehicles represent the remaining share within the By Vehicle Type segment. China produced 34.53 million vehicles in 2025, approximately 3.25 million more than in 2024, with commercial-vehicle output contributing materially to that expansion. This volume increment supports sustained secondary harness demand from commercial OEM production lines, particularly for chassis and engine harness content across truck and van platforms.
Key Market Segments
By Component
- Terminals
- Electric Wires
- Connectors
- Others
By Application
- Chassis Harness
- Body Harness
- Engine Harness
- HVAC Harness
- Sensors Harness
By Vehicle Type
- Passenger Cars
- Commercial Vehicle
Regional Analysis
Asia-Pacific Dominates the Automotive Secondary Wiring Harness Market with a Market Share of 34.21%, Valued at USD 6.1 Billion
Asia-Pacific holds a 34.21% share of the global market and is also the fastest-growing region. China produced 34.53 million vehicles in 2025 — already assigned to Vehicle Type — wait, China stat was already assigned to Task 2 Vehicle Type. I will use the India EV and OICA regional data already distributed. Let me draw on regional data from the data block consistent with what remains unassigned at the regional level.
Let me re-examine. China stat (Stat 3) was assigned to Task 1C Part 2. I used it there. I now need to write Task 4 Regional Analysis paragraphs using only data assigned to Task 4: Stats 17, 18, 19, 21, 22, and Developments 3 and 8.
Asia-Pacific holds a 34.21% share of the global Automotive Secondary Wiring Harness Market and is the fastest-growing region. This dominance reflects the region’s concentration of high-volume OEM assembly capacity, particularly in China, India, Japan, and South Korea. As EV adoption scales across these markets, secondary harness content value per vehicle rises in step, compounding both volume and revenue growth for regional suppliers.
Europe represents a structurally significant market anchored by a large and expanding vehicle fleet. According to ACEA, the European Union had 256 million passenger cars on its roads in 2024, up 1.4%, alongside 31.1 million vans and 6.2 million trucks. Battery-electric cars accounted for 17.4% of EU new-car registrations in 2025, compared with 13.6% in 2024. This electrification trajectory structurally increases high-voltage harness content requirements across European OEM production lines.
Leoni inaugurated its Badr 4 plant and started Badr 5 in Egypt in December 2025, adding approximately 35,000 m² of production space to serve European and North African demand corridors. In June 2026, Leoni began constructing a nearly 35,000 m² wiring-systems facility in Bouskoura under a development program exceeding MAD 932 million, further reinforcing supplier capacity aimed at European OEM customers.
ACEA data shows EU van registrations declined 8.8%, truck registrations declined 6.2%, and bus registrations increased 7.5% in 2025. Only 1.3% of EU vans and 0.3% of EU trucks were electrically chargeable in 2024, signaling that commercial-vehicle electrification in Europe remains at an early stage. This gap represents a near-term volume constraint for high-voltage harness content in the commercial segment but also indicates a material addressable opportunity as electrification mandates extend to vans and trucks in coming years.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Drivers
The migration of battery-electric platforms from 400V to 800V architectures is the single highest-magnitude growth force in this market, adding an estimated +3.2% to the baseline CAGR. Each electrified platform requires shielded high-voltage secondary runs, battery-management interconnects, and thermal-resistant insulation absent from combustion vehicles. Chinese OEM 800V rollouts have already prompted capacity expansions among leading harness suppliers.
India’s stated target of 30% EV penetration by 2030 against roughly 1.5 million EV units sold in FY2023–24 signals a sustained step-up in high-voltage harness content requirements. This regulatory and commercial pull shifts secondary harness revenue per vehicle materially above combustion baselines. Suppliers who lock in high-voltage engineering capability now stand to capture structurally higher gross margins on qualifying EV platforms.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| EV high-voltage harness proliferation (400V–800V) | +3.2% | China, EU, North America | Short term (≤ 2 years) |
| ADAS & sensor-node data cabling density | +2.4% | Global, led by EU & North America | Short term (≤ 2 years) |
| Rising per-vehicle electronic content | +1.8% | Asia Pacific, EU | Medium term (2–4 years) |
| Emerging-market vehicle production growth | +1.5% | India, ASEAN, Latin America | Medium term (2–4 years) |
| Infotainment & connected-vehicle uptake | +1.1% | Global | Short term (≤ 2 years) |
Restraints
The 50% Section 232 tariff on semi-finished copper products, effective August 1, 2025, is the most severe active restraint, deducting an estimated -2.6% from the baseline CAGR. Copper conductor is the dominant material input for secondary looms, and the levy applies directly to imported wire and cable content. Copper futures spiked roughly 15–17% to record highs ahead of the deadline, compounding cost pressure on suppliers unable to pass through increases.
Earlier tariff waves already raised imported component costs by 10–15%, and a further 10% baseline duty from April 2025 layered additional cost onto non-exempt inputs. Suppliers face direct margin compression or contentious renegotiation with OEMs. This forces delayed or rerouted capital expenditure as manufacturers weigh costly onshoring against thin domestic copper supply that cannot yet absorb surging demand volumes.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Section 232 copper import tariff (50%) | -2.6% | North America | Short term (≤ 2 years) |
| Elevated interest rates constraining auto CapEx | -1.5% | North America, EU | Short term (≤ 2 years) |
| Domestic copper allocation mandates (2027–2029) | -1.2% | United States | Medium term (2–4 years) |
| OEM pricing pressure & margin clawbacks | -1.0% | Global | Short term (≤ 2 years) |
| Cross-border input cost stacking (10% baseline) | -0.8% | North America, EU | Short term (≤ 2 years) |
Challenges
Secondary wiring harness manufacturing remains among the least-automated processes in the automotive supply chain, creating a structural labor dependency that carries an estimated -1.9% drag on the market’s growth ceiling. Harnesses comprise flexible, branched, multi-material assemblies that resist robotic manipulation. This forces reliance on manual routing and taping concentrated in low-cost hubs such as Mexico, Morocco, and Eastern Europe at loaded labor costs near $7.00 per hour.
Leading zonal-standardization efforts project automation reaching only 50%+ of production, and only for smaller sub-harnesses, over multi-year horizons. Industry robotics challenges through 2026 have only recently chained together discrete process steps. Suppliers exposed to wage inflation across Mexico, ASEAN, and North Africa face rising unit costs before automation reaches scale, eroding the low-cost-geography arbitrage that underpins current unit economics.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Manual-assembly labor dependency | -1.9% | Mexico, Morocco, Eastern Europe | Long term (≥ 4 years) |
| Low automation feasibility of harnesses | -1.4% | Global | Long term (≥ 4 years) |
| Wage inflation in low-cost hubs | -1.1% | Mexico, ASEAN, North Africa | Medium term (2–4 years) |
| Geographic supply-chain concentration risk | -0.9% | North Africa, Mexico | Medium term (2–4 years) |
| EV platform design-cycle volatility | -0.7% | Global | Long term (≥ 4 years) |
Opportunities
Zonal electrical architecture represents the largest untapped upside at an estimated +2.1% above baseline CAGR. This shift from bespoke monolithic looms toward modular, location-grouped sub-harnesses shortens wiring runs, cuts connector counts, and enables automation to exceed 50% of production. Suppliers who standardize interfaces early convert a fragmented, labor-heavy business into a scalable platform capturing unclaimed EV and software-defined-vehicle content.
Aluminum and advanced-material conductor conversion carries an estimated +1.6% CAGR upside by reducing copper dependency and per-vehicle harness weight by an estimated 20–30%. Nearshored production close to OEM plants adds another +1.3% upside, particularly in North America and Europe. These structural shifts reward suppliers with the capital flexibility to relocate manufacturing footprint before OEM sourcing decisions lock in for the next platform cycle.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Zonal architecture sub-harness standardization | +2.1% | EU, North America, China | Medium term (2–4 years) |
| Aluminum & advanced-material conductor conversion | +1.6% | Global, EV-led | Medium term (2–4 years) |
| Nearshored production close to OEM plants | +1.3% | North America, EU | Medium term (2–4 years) |
| M&A roll-up of fragmented regional suppliers | +1.0% | ASEAN, Eastern Europe | Long term (≥ 4 years) |
| Copper recovery & harness circularity models | +0.8% | EU, North America | Long term (≥ 4 years) |
Key Company Insights
Aptiv Plc generated $8.247 billion in Electrical Distribution Systems revenue in 2024, anchoring its position as a structural leader in the global harness market. In April 2026, Aptiv completed the Versigent electrical-distribution-systems spin-off and received an approximately $1.9 billion dividend. This restructuring narrows Aptiv’s focus but removes EDS from its direct revenue base, creating a gap that competitors will target.
Samvardhana Motherson International Ltd. demonstrated the fastest revenue scaling among listed harness players, with Motherson Sumi Wiring India growing from INR 93.194 billion in FY2024–25 to INR 114.78 billion in FY2025–26, a 23.2% increase. EV battery demand exceeded 950 GWh in 2024, growing 25%, while global battery-cell manufacturing capacity exceeded 3 TWh after growing almost 30%. This battery infrastructure build directly amplifies harness content demand, and Motherson’s acquisition of Nexans Autoelectric at an enterprise value of €207 million positions it to absorb that demand at scale. Furukawa Electric agreed in January 2024 to invest approximately £10 million in Tokamak Energy, signaling long-range conductor technology ambitions beyond conventional automotive supply.
Key Players
- Aeromotive Services Inc.
- Aptiv Plc
- Assembly Solutions Ltd.
- Continental AG
- Coroplast Fritz Muller GmbH and Co. KG
- Epec LLC
- Fujikura Co. Ltd.
- Furukawa Electric Co. Ltd.
- Harness Techniques (I) Pvt. Ltd.
- Leoni AG
- Minda Corp. Ltd.
- Miracle Electronics Devices Pvt. Ltd.
- Samvardhana Motherson International Ltd.
- Nexans autoelectric GmbH
- Robert Bosch GmbH
- Sparsh Electronics India Pvt. Ltd.
- Other Key Players
Recent Developments
- 2 July 2026 – Nexans announced completion of Autoelectric’s sale to Motherson at an enterprise value of €207 million; the business generated approximately €708 million in 2025 sales.
- 4 March 2026 – Aptiv announced an upsized $1.6 billion senior-notes offering by subsidiaries associated with its electrical-distribution-systems spin-off.
- 22 December 2025 – Motherson agreed to acquire 100% of Nexans Autoelectric’s global wiring-harness business at an enterprise value of €207 million.
- 10 July 2025 – Luxshare-ICT completed the acquisition of 50.1% of Leoni AG, while TIME Interconnect acquired 100% of Leoni’s Automotive Cable Solutions division.
- 8 May 2025 – Bosch Ventures launched its sixth venture-capital fund with approximately €250 million.
- 21 January 2025 – Leoni opened a 19,000 m² commercial-vehicle wiring-systems plant in Agadir after investing more than €20 million.
- 31 July 2024 – Aptiv authorized a new $5.0 billion share-repurchase program and an immediate $3.0 billion accelerated repurchase.
- 16 May 2024 – Aptiv sold an 11% common-equity interest in Motional to Hyundai for approximately $448 million.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 17.9 Billion |
| Forecast Revenue (2035) | USD 46.1 Billion |
| CAGR (2026-2035) | 10.0% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Component (Terminals, Electric Wires, Connectors, Others), By Application (Chassis Harness, Body Harness, Engine Harness, HVAC Harness, Sensors Harness), By Vehicle Type (Passenger Cars, Commercial Vehicle) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Aeromotive Services Inc., Aptiv Plc, Assembly Solutions Ltd., Continental AG, Coroplast Fritz Muller GmbH and Co. KG, Epec LLC, Fujikura Co. Ltd., Furukawa Electric Co. Ltd., Harness Techniques (I) Pvt. Ltd., Leoni AG, Minda Corp. Ltd., Miracle Electronics Devices Pvt. Ltd., Samvardhana Motherson International Ltd., Nexans autoelectric GmbH, Robert Bosch GmbH, Sparsh Electronics India Pvt. Ltd., Other Key Players |
| Customization Scope | Customization for segments, region/country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








