


Report Overview
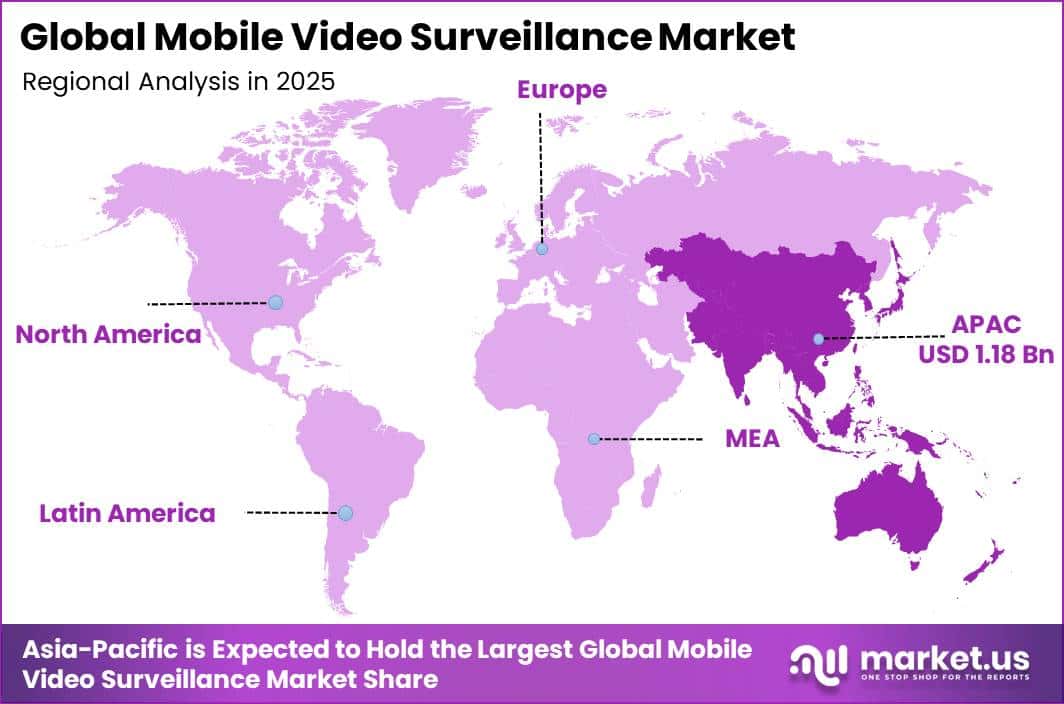
In 2025, the Global Mobile Video Surveillance Market was valued at USD 3.2 billion. The market is projected to grow at a CAGR of 8.1% during 2026–2035, reaching approximately USD 6.9 billion by 2035. Asia-Pacific dominated the global market in 2025, accounting for more than 37.0% of the total market share and generating approximately USD 1.18 billion in revenue.
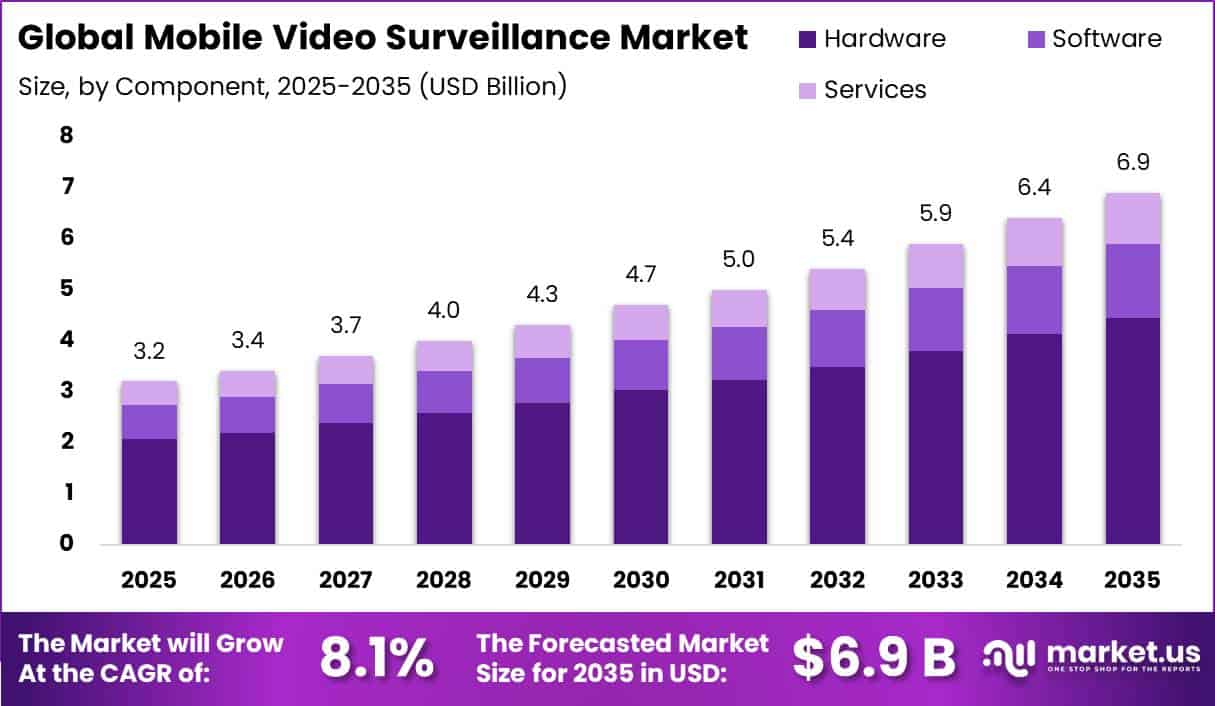
Market growth is being supported by the rising number of commercial vehicles and mobile assets requiring live monitoring, video recording, driver-safety support, and remote surveillance. According to OICA, global vehicle production increased from 92.7 million units in 2024 to 96.4 million units in 2025.
This expanding vehicle base is creating demand for in-vehicle cameras, digital video recorders, storage systems, connectivity solutions, and video-management software. China produced 34.5 million vehicles, while India produced 6.4 million vehicles during the same year. Strong vehicle manufacturing, rising public transportation activity, and expanding freight fleets are supporting mobile surveillance adoption across the region.
In addition, the United Nations reported that 19 of the world’s 33 megacities were located in Asia in 2025, strengthening the need for real-time monitoring across buses, delivery fleets, emergency vehicles, and other moving assets.
Key Takeaway
- The Mobile Video Surveillance Market was valued at USD 3.2 billion in 2025 and is projected to reach USD 6.9 billion by 2035, growing at an 8.1% CAGR.
- Hardware held a dominant 64.5% share by component, driven by demand for onboard cameras, recorders, and storage equipment.
- IP video surveillance held a dominant 62.1% share by system type, supported by expanding mobile broadband and 5G coverage.
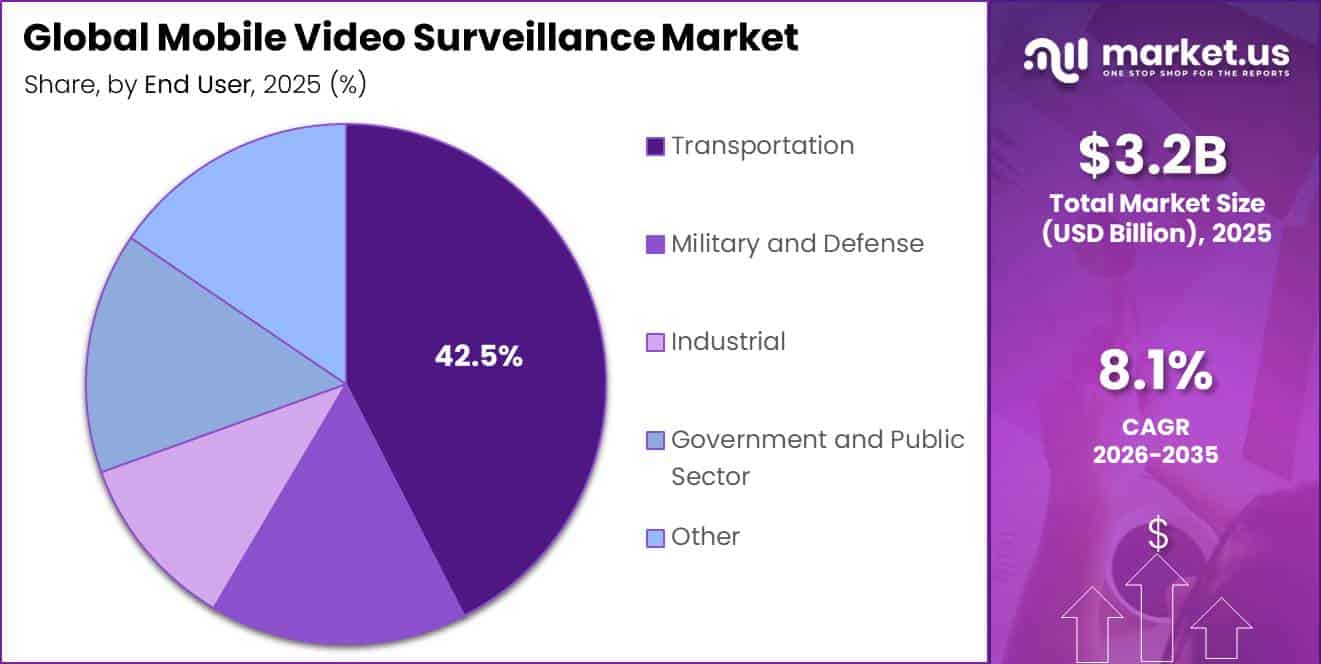
- Transportation held a dominant 42.5% share by end-user, driven by growing passenger, cargo, and fleet monitoring needs.
- Asia-Pacific led the market in 2025 with more than 37.0% share, generating approximately USD 1.18 billion in revenue.
Market Statistics and Data Insights
- Samsara found that dual-facing dash cameras produced more than 2× the crash-rate reduction achieved by front-facing cameras alone, indicating stronger fleet interest in systems that monitor both the driver and road environment.
- In 2026, SG Haulage reported a 50% reduction in average fleet collision risk within 6 months after deploying connected video telematics across a fleet of more than 40 vehicles.
- During 2026, camera footage helped SG Haulage defend drivers in 3 disputed incidents and avoid an estimated £10,000 in potential insurance-related costs.
- In February 2025, Luminator and Gauzy reported that their Smart-Vision camera-monitor system was already operating on approximately 300 public buses in the United States.
- Luminator and Gauzy also reported pending Smart-Vision regulatory approvals in 21 additional U.S. states in 2025, supporting further retrofit and new-bus deployments.
- Axis Communications’ AXIS F9111-R Mk II mobile-ready camera unit, introduced in February 2025, can record 720p video at 180 frames per second or HDTV 1080p video at 60 frames per second.
- In the 2026 Verizon Connect Fleet Technology Trends research, 74% of video-telematics users said the technology helped improve driver safety, while 41% rated it extremely or very beneficial for improving driver-coaching sessions. This shows that fleets are using onboard video as an active safety-management tool rather than only for post-accident evidence.
- Verizon Connect reported in 2026 that 48% of surveyed fleets said video telematics helped them reduce accident costs. This directly supports the financial value of mobile cameras for commercial fleet operators.
- Samsara analyzed more than 2,600 fleets across North America, the UK, Western Europe, and Mexico in 2025. Fleets with 175+ vehicles using its complete AI safety solution, including dual-facing cameras, in-cab alerts, and AI coaching, achieved a 73% decrease in crash rates over 30 months.
- In 2025, ITU reported that 55% of the global population was covered by 5G, while 93% had 4G coverage and 96% had access to 3G-or-better mobile broadband. These network levels support live video transmission, remote camera access, and cloud-connected fleet surveillance.
By Component
Hardware held a dominant 64.5% share of the mobile video surveillance market, mainly because every surveillance system depends on physical equipment for operation. Cameras capture video, while recorders, storage drives, displays, mounts, cables, and power units help store and manage footage inside moving vehicles.
Although software can control several camera feeds from a single platform, each bus, truck, rail car, or emergency vehicle still requires separate cameras and recording hardware. According to the U.S. Federal Transit Administration, 119,834 transit vehicles were recorded in maximum service in 2023, showing the large equipment base available for onboard surveillance systems.
In Europe, road freight activity reached 1,869 billion tonne-kilometres in 2024, highlighting the scale of commercial transport operations. Growing freight movement and public transport activity are increasing the need for durable onboard cameras and recording equipment to monitor cargo, review accidents, improve driver safety, and record security incidents.
By System Type
IP video surveillance held a dominant 62.1% share of the mobile video surveillance market, supported by its ability to connect cameras directly with digital networks. Unlike traditional analogue systems, IP cameras convert video into digital data at the device level, allowing operators to view live footage, store recordings centrally, search video files, and add new cameras more easily.
This flexibility is especially useful for large fleets operating across different routes and locations, as it can reduce system expansion and maintenance requirements. Stronger mobile connectivity is also supporting wider adoption. According to the International Telecommunication Union, 96% of the global population had access to mobile broadband coverage in 2025, while 5G networks covered around 55% of the population.
By End-User
Transportation accounted for a dominant 42.5% share of the mobile video surveillance market, supported by the growing need to monitor passengers, vehicles, and cargo while in motion. Buses, trains, aircraft, and freight fleets operate across public areas where accidents, theft, security incidents, and passenger complaints often require quick video verification.
Mobile surveillance systems help operators record onboard activity, transmit live footage to control centres, and provide evidence for safety reviews and insurance claims. According to IATA, global airline passenger traffic, measured in revenue passenger kilometres, increased by 10.4% in 2024 and remained 3.8% above 2019 levels.
Public transport also creates a large surveillance base. UITP reported that metro systems carried around 190 million passengers per day in 2019. Large passenger volumes and expanding transport fleets continue to strengthen demand for onboard cameras, recording systems, and remote monitoring solutions used for passenger protection, fleet management, incident investigation, and operational security.
Key Market Segments
By Component
- Hardware
- Software
- Services
By System Type
- IP Video Surveillance
- Analog Video Surveillance
By End-User
- Transportation
- Military and Defense
- Industrial
- Government and Public Sector
- Other
Geopolitical Impact Analysis
Geopolitical tensions are increasing both the cost and delivery time of mobile video surveillance hardware. Cameras, image sensors, processors, memory chips, circuit boards, wireless modules, DVRs, and power units often depend on supply chains spread across several countries. This makes the market sensitive to trade restrictions, tariffs, and changes in international sourcing conditions.
In the United States, the Section 301 tariff on selected Chinese semiconductors rose to 50% in 2025, increasing import costs for surveillance equipment that uses affected chips and electronic components. As a result, manufacturers are moving sourcing and final assembly to alternative countries.
Global shipping disruptions are adding further pressure. UNCTAD reported that Suez Canal transit tonnage declined by 70% by mid-2024, while Gulf of Aden tonnage fell by 76% as ships were redirected around the Cape of Good Hope. These longer routes increased global container-ship demand by around 12%, making the movement of surveillance hardware more expensive and less predictable.
The Shanghai Containerized Freight Index also more than doubled from late 2023, while Shanghai-to-South Africa freight rates increased by about 199.6% to USD 5,426 per TEU in July 2024. Energy prices remain another risk, as the World Bank estimated that a 2% global oil-supply disruption could push Brent crude to USD 92 per barrel, compared with a USD 73 baseline, representing a 26% increase and raising freight, installation, and field-service costs.
Regional Analysis
Asia-Pacific remained the dominant region in the mobile video surveillance market, accounting for 37.0% of global revenue and nearly USD 1.18 billion in 2025. The region benefits from a large base of public transport systems, freight fleets, delivery vehicles, rail networks, and emergency-response services that require continuous video monitoring.
China, India, Japan, South Korea, and Southeast Asian countries are expanding connected fleet-management and urban-security systems, supporting demand for onboard cameras, mobile digital video recorders, IP connectivity devices, and video-management platforms. High population density and large cities also increase the need to monitor passenger safety, driver behaviour, cargo movement, traffic incidents, and vandalism.
North America is expected to be the fastest-growing region, supported by fleet modernization, stronger safety requirements, and the replacement of older analogue systems with IP-based mobile surveillance solutions. The U.S. Bipartisan Infrastructure Law authorized up to USD 108 billion for public transportation programs, creating a favorable investment environment for transit upgrades and connected safety equipment.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Drivers
| Driver | (~) % CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Mobile broadband reach | +1.2% | Global | Short term (2 years or less) |
| Fleet safety digitization | +1.0% | North America, Europe, Asia-Pacific | Short term (2 years or less) |
| Edge analytics adoption | +0.9% | Global | Medium term (2 to 4 years) |
| Transit modernization | +0.7% | North America, Asia-Pacific | Medium term (2 to 4 years) |
| Freight traceability demand | +0.6% | Europe, North America | Short term (2 years or less) |
Mobile broadband reach
Mobile-broadband reach is the largest active driver because it converts onboard cameras from isolated recorders into connected operating assets. The International Telecommunication Union reported that more than 96% of the world’s population had mobile-broadband coverage in 2025, while 5G coverage reached 55%; this supports live video upload, remote health checks, and alarm-based review rather than costly manual footage retrieval.
Per International Air Transport Association data, global passenger traffic increased 10.4% in 2024, and Eurostat recorded 1,869 billion tonne-kilometres of EU road freight in the same year, expanding the number of moving assets where fast incident verification has direct operating value. This connectivity shift supports recurring device-management, storage, and analytics revenue and plausibly contributes roughly 1.2 percentage points to the stated 8.1% baseline growth rate.
Restraints
| Restraint | (~) % CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Restricted equipment authorization | -1.4% | United States | Short term (2 years or less) |
| Biometric-use restrictions | -0.8% | European Union | Short term (2 years or less) |
| Upfront fleet CapEx | -0.7% | Global | Medium term (2 to 4 years) |
| Lengthy public tenders | -0.5% | Global | Medium term (2 to 4 years) |
| Data-residency fragmentation | -0.4% | Europe, Middle East | Medium term (2 to 4 years) |
Restricted equipment authorization
Restricted equipment authorization is the most immediate sales restraint because it removes eligible products and suppliers from defined U.S. deployments before a fleet tender can be awarded. The Federal Communications Commission has prohibited new equipment authorization for covered telecommunications and video-surveillance equipment, blocking the import, marketing, sale, or operation of newly authorized covered products in the United States.
The U.S. Court of Appeals upheld the authorization restriction in 2024, reinforcing procurement risk for critical-infrastructure and public-safety applications. Separately, the Office of the U.S. Trade Representative raised the tariff on specified Chinese semiconductors to 50% in 2025, which can compress system-integrator margins where covered electronic inputs cannot be substituted quickly. The combined market-access and sourcing constraint plausibly removes roughly 1.4 percentage points from attainable CAGR in affected U.S. channels.
Challenges
| Challenge | (~) % CAGR | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Maritime logistics volatility | -1.0% | Global | Medium term (2 to 4 years) |
| Cybersecurity patch burden | -0.7% | Global | Long term (4 years or more) |
| Vehicle power constraints | -0.5% | Global | Medium term (2 to 4 years) |
| Multi-vendor interoperability | -0.4% | Global | Long term (4 years or more) |
| Installer capability gaps | -0.3% | Emerging markets | Medium term (2 to 4 years) |
Maritime logistics volatility
Maritime logistics volatility creates continuing friction rather than a sales freeze because camera modules, processors, storage media, enclosures, cables, and vehicle recorders can still move, but with uncertain cost and replenishment timing.
UN Trade and Development reported that Red Sea rerouting raised demand for additional container-ship capacity by 12% between mid-December 2023 and June 2024. According to UN Trade and Development freight-rate tracking, the Shanghai–South Africa container rate increased about 199.6% to USD 5,426 per TEU in July 2024.
UN Trade and Development also reported that container freight rates had more than doubled by mid-2024 versus late 2023. These fluctuations force manufacturers to hold more buffer inventory, regionalize final assembly, and accept lower inventory turns, creating a plausible 1.0-percentage-point drag on the market’s maximum growth potential.
Opportunities
| Opportunity | (~) % CAGR | Geographic Relevance | Execution Window |
|---|---|---|---|
| Legacy-fleet video retrofit | +1.3% | Global | Medium term (2 to 4 years) |
| Video evidence subscriptions | +1.0% | North America, Europe | Medium term (2 to 4 years) |
| School-bus safety bundles | +0.8% | North America | Short term (2 years or less) |
| Cold-chain sensor fusion | +0.7% | Europe, Asia-Pacific | Long term (4 years or more) |
| Temporary drone deployments | +0.6% | Global | Medium term (2 to 4 years) |
Legacy-fleet video retrofit
Legacy-fleet retrofit remains an untapped opportunity because many older vehicles still use analogue recorders, disconnected cameras, or no onboard video systems. The U.S. Federal Transit Administration’s 2023 fleet data tracks vehicle age and lifetime mileage, helping transit agencies plan targeted replacements. Global metro ridership reached around 190 million passengers per day in 2019, while EU road freight carried more than 13.1 billion tonnes in 2024, showing a large retrofit opportunity beyond new vehicle sales.
A manufacturer-financed 36-month retrofit subscription could reduce upfront customer costs by an estimated 35% to 45% and improve supplier gross margins by around 10 to 15 percentage points through installation, storage, maintenance, and evidence-management services. If adopted at scale, this model could contribute nearly 1.3 percentage points above the 8.1% baseline growth rate.
Key Players Analysis
The mobile video surveillance market has two clear competitive groups. Tier-1 scale leaders, including Hikvision, Dahua, Axis Communications, and Hanwha Vision, benefit from strong purchasing power, broad product portfolios, and wide distribution networks. Hikvision reported revenue of RMB 92.5 billion in 2024, including RMB 67.9 billion from its core products and services business.
Hikvision’s international revenue reached RMB 25.9 billion, representing 28.1% of total sales, while its R&D spending stood at RMB 11.8 billion, equal to 12.8% of revenue. This level of investment supports the development of AI-enabled cameras, thermal imaging, edge processing, and advanced video surveillance systems.
Dahua reported RMB 32.18 billion in revenue in 2024, while its Smart IoT products and solutions generated RMB 12.03 billion during the first half of 2024. Axis Communications also maintains a strong global position, with reported total revenue of USD 2.1 billion and sales coverage across 180 countries.
Tier-2 mobility specialists, including Safe Fleet, Luminator Technology Group, Apollo Video Technology, Pro-Vision, March Networks, and CP PLUS, compete through specialized solutions for buses, police vehicles, rail systems, waste fleets, and commercial trucks. Hanwha Vision also remains an important challenger, reporting consolidated revenue of KRW 493.3 billion during its four-month 2024 reporting period following corporate restructuring.
Top Key Players in the Market
- Hangzhou Hikvision Digital Technology Co., Ltd.
- Axis Communications AB
- Zhejiang Dahua Technology Co., Ltd.
- Luminator Technology Group
- Hanwha Vision
- Pro-Vision
- March Networks
- Apollo Video Technology
- Safe Fleet
- CP PLUS
Recent Developments
- In 2026, Dahua Technology launched DSS V8.8 and introduced its new DSS Ultimate security-management platform. The system can support up to 300,000 video channels and includes 32 types of vehicle-violation detection and 22 types of road-incident detection. Dahua also increased DSS OneBox access-control capacity from 16 channels to 64 channels.
- In 2025, Axis Communications acquired Prague-based FF Group to strengthen its traffic surveillance and intelligent video capabilities. The acquisition expands Axis Communications’ traffic analytics capabilities and supports its global organization of around 5,000 employees across more than 50 countries.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 3.2 Billion |
| Forecast Revenue (2035) | USD 6.9 Billion |
| CAGR (2026-2035) | 8.1% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Competitive Landscape, Recent Developments |
| Segments Covered | By Component – (Hardware, Software, Services); By System Type – (IP Video Surveillance, Analog Video Surveillance); By End-User – (Transportation, Military and Defense, Industrial, Government and Public Sector, Other) |
| Regional Analysis | North America – US, Canada; Europe – Germany, France, The UK, Spain, Italy, Rest of Europe; Asia Pacific – China, Japan, South Korea, India, Australia, Singapore, Rest of APAC; Latin America – Brazil, Mexico, Rest of Latin America; Middle East & Africa – GCC, South Africa, Rest of MEA |
| Competitive Landscape | Hangzhou Hikvision Digital Technology Co., Ltd., Axis Communications AB, Zhejiang Dahua Technology Co., Ltd., Luminator Technology Group, Hanwha Vision, Pro-Vision, March Networks, Apollo Video Technology, Safe Fleet, CP PLUS |
| Customization Scope | Customization for segments, region/country-level will be provided. Moreover, additional customization can be done based on the requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited Users and Printable PDF) |









