


Report Overview
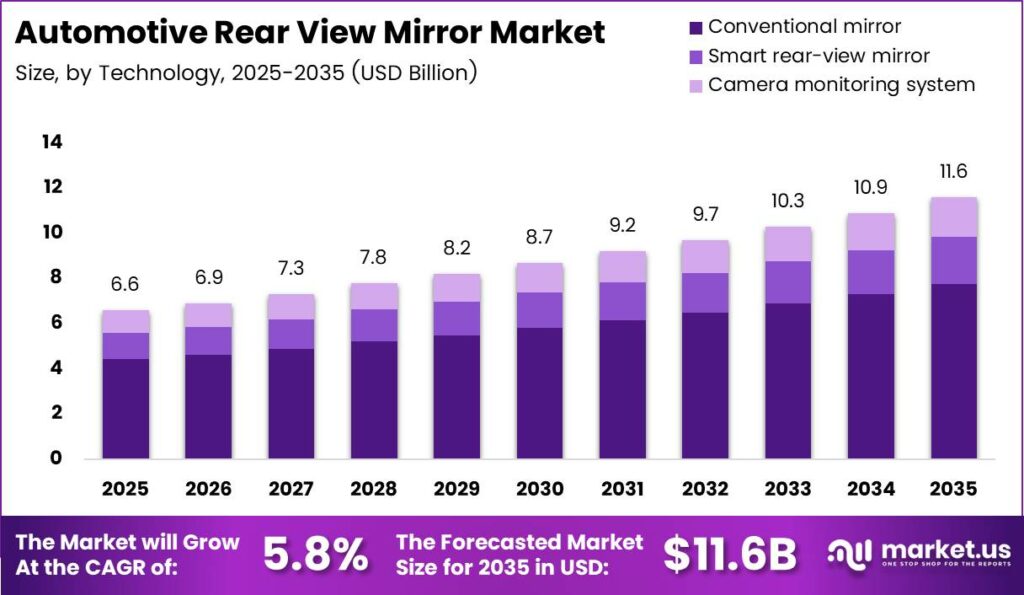
Global Automotive Rear View Mirror Market size is expected to be worth around USD 11.6 Billion by 2035 from USD 6.6 Billion in 2025, growing at a CAGR of 5.8% during the forecast period 2026 to 2035.
The automotive rear-view mirror market covers exterior and interior mirror assemblies, camera-monitor systems, and digital display mirrors fitted to passenger cars, light commercial vehicles, and heavy commercial vehicles. Products span conventional glass mirrors, auto-dimming variants, and fully electronic systems integrated with driver-assistance functions. The market serves OEM fitment and aftermarket replacement channels across all global regions.
Key Takeaways
- The global Automotive Rear View Mirror Market was valued at USD 6.6 Billion in 2025 and is forecast to reach USD 11.6 Billion by 2035.
- The market is growing at a CAGR of 5.8% from 2026 to 2035.
- By Product Type, Exterior Rear-View Mirror dominates with a 72.00% share.
- By Mounting Position, Door-Mounted mirrors dominate with a 76.00% share.
- By Technology, Conventional Mirror leads with a 67.00% share.
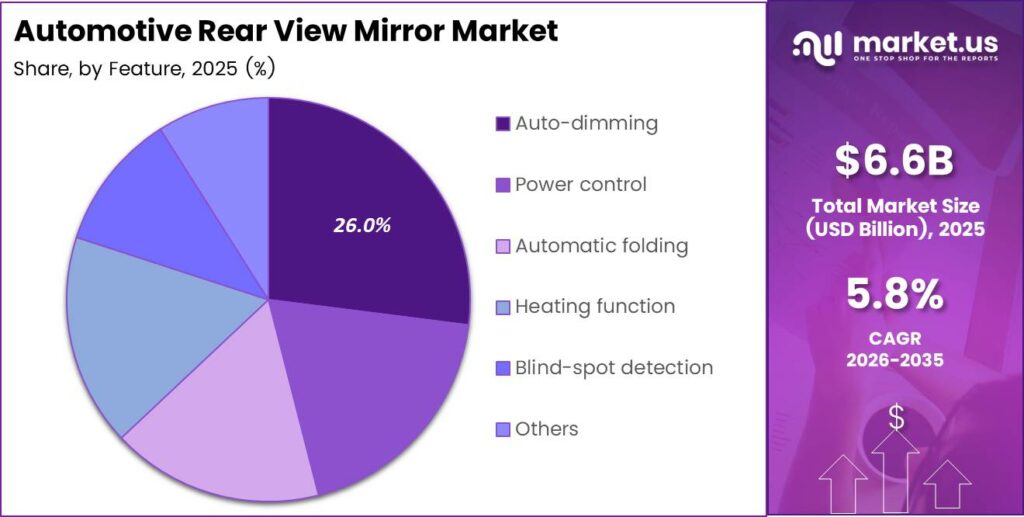
- By Feature, Auto-Dimming holds the leading share at 26.00%.
- By Vehicle Type, Passenger Cars dominate with a 72.00% share.
- By Powertrain, Internal Combustion Engine Vehicles hold a 76.00% share.
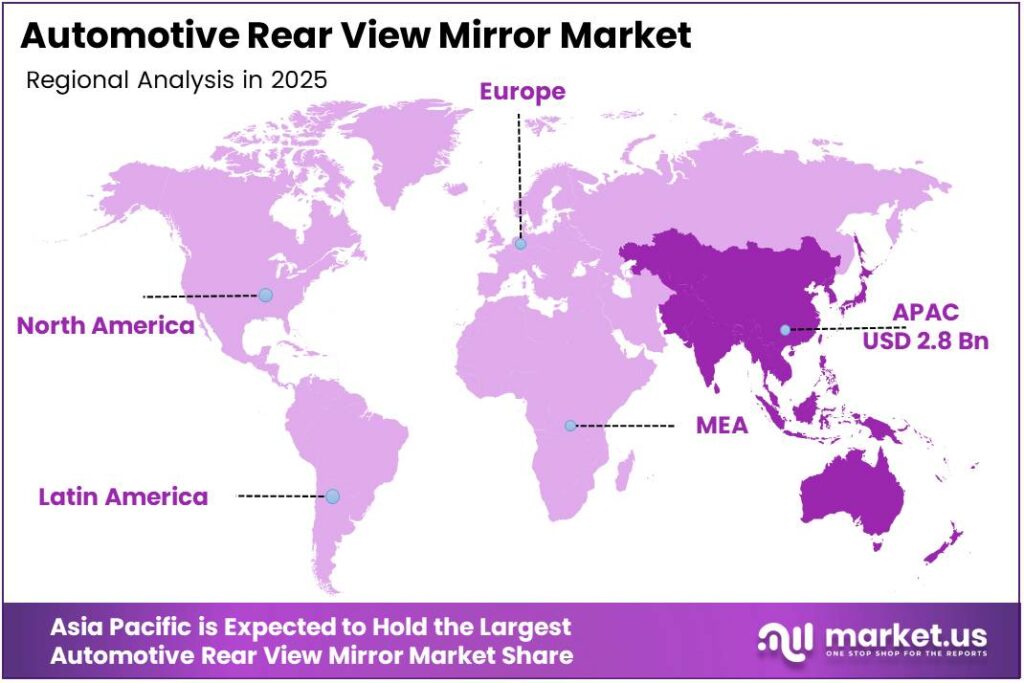
- Asia Pacific is the dominant region with a 42.50% market share, valued at USD 2.8 Billion.
According to oica.net, global motor-vehicle production reached 96,383,650 units in 2025, up 4% from 2024. Each additional production unit adds direct demand for exterior and interior mirror assemblies. This volume floor gives Tier-1 mirror suppliers a stable fitment base to absorb tooling costs across high-feature variants.
As per our research, NHTSA’s automatic-emergency-braking standard requires compliance by September 2029 and mandates lead-vehicle collision avoidance at speeds up to 62 mph, applying to nearly all light vehicles with a gross vehicle weight rating of 10,000 pounds or less. This deadline converts regulatory intent into a hard engineering timeline. Suppliers that build camera-ready mirror platforms before 2027 will capture first-mover qualification slots on new vehicle programs.
As reported by iea.org, global electric-car sales exceeded 21 million units in 2025, accounting for one in four cars sold. Electric platforms prioritize aerodynamic efficiency and full digital integration, pulling demand toward camera-monitor systems over conventional glass. This shift accelerates electronic content per mirror assembly and raises average selling prices across OEM programs. On 6 January 2026, Gentex introduced its next-generation Full Display Mirror, available after the earlier system had reached more than 140 vehicle models, signaling that digital mirror adoption is moving from niche to mainstream fitment.
Data from the WTO shows world merchandise-trade volume is forecast to grow 1.9% in 2026 under its baseline scenario. This tempered trade environment raises input-cost risk for mirror suppliers dependent on cross-border component flows. However, the IMF projected global economic growth of 3.0% in 2026 and 3.4% in 2027, suggesting underlying vehicle demand will hold firm enough to sustain OEM production schedules through the forecast period.
Product Type Analysis
Exterior Rear-View Mirror dominates with 72.00% due to mandatory fitment on every production vehicle.
In 2025, Exterior Rear-View Mirror held a dominant market position in the By Product Type segment of the Automotive Rear View Mirror Market, with a 72.00% share. Every passenger car, commercial van, and truck sold globally requires at least two exterior mirrors as standard equipment under national road safety regulations. This mandatory fitment base means exterior mirrors generate the largest and most predictable revenue stream for Tier-1 suppliers, regardless of technology cycle shifts.
Interior Rear-View Mirror completes the product structure by providing forward-facing cabin monitoring and, in smart variants, full digital display capability. Interior mirrors carry higher average selling prices in auto-dimming and full-display configurations. Euro NCAP’s driver-monitoring assessment allocated 25 points, including 15 points for transient driver states, creating a direct qualification incentive for interior mirror suppliers to embed camera and sensor hardware into their assemblies.
Mounting Position Analysis
Door-Mounted mirrors dominate with 76.00% due to universal adoption across all vehicle body styles.
In 2025, Door-Mounted held a dominant market position in the By Mounting Position segment of the Automotive Rear View Mirror Market, with a 76.00% share. Door mounting provides the widest rearward field of view and accommodates powered folding, heating, indicator lighting, and camera-monitor functionality within a single module. This integration capacity makes the door-mounted position the primary platform for feature-content growth across all vehicle classes.
Body-Mounted mirrors serve specialty applications including heavy trucks, buses, and off-road vehicles where door geometry does not permit standard mounting. Nearly 22 million electric cars were produced worldwide in 2025, more than 25% above 2024, and many electric commercial platforms use body-mounted camera systems to reduce aerodynamic drag. This creates a secondary but expanding demand channel for body-mounted mirror and camera-monitor modules in commercial and electric vehicle programs.
Technology Analysis
Conventional Mirror dominates with 67.00% due to low cost and universal OEM acceptance.
In 2025, Conventional Mirror held a dominant market position in the By Technology segment of the Automotive Rear View Mirror Market, with a 67.00% share. Glass-based mirror assemblies carry minimal electronics content, require no software validation, and fit within tight OEM cost targets for mass-market vehicles. This cost profile keeps conventional mirrors dominant across volume segments in Asia, Latin America, and developing markets where price pressure is most acute.
Smart Rear-View Mirror systems embed auto-dimming electrochromic glass, heating elements, integrated cameras, and connectivity modules into a single assembly. Global electric-vehicle battery deployment reached 1.2 TWh in 2025, almost 30% above 2024, reflecting the pace at which electrified platforms are entering production. Electric vehicles carry higher electronic content per unit, and smart mirror fitment rates on EV programs run significantly above the overall market average, creating a structural upgrade path for this segment.
Camera Monitoring System replaces the glass mirror entirely with exterior cameras feeding interior display screens. Electric heavy-freight trucks accounted for approximately 1.5% of European sales in 2025, up from 1% in 2024, and European regulations already permit camera-monitor systems as a legal mirror substitute for new type approvals. This regulatory clearance in a major market validates the commercial pathway for camera-monitor system suppliers targeting premium and commercial vehicle programs.
Feature Analysis
Auto-Dimming dominates with 26.00% due to strong take-rate on premium and mid-range programs.
In 2025, Auto-Dimming held a dominant market position in the By Feature segment of the Automotive Rear View Mirror Market, with a 26.00% share. Auto-dimming mirrors use electrochromic technology to reduce glare from following vehicles, and this safety benefit drives high fitment rates as a standard or low-cost option on mid-range and premium cars. Suppliers with electrochromic glass production scale hold a cost and quality advantage in this the largest feature sub-segment.
Power Control mirrors allow electric adjustment from inside the cabin and represent a near-universal fitment on new vehicles above entry-level trim. Automatic Folding adds convenience and damage-prevention value in dense urban environments, driving higher take rates in European and Asian city-car segments. Heating Function mirrors protect visibility in cold climates and are standard fitment in northern European, North American, and Northeast Asian markets, making this feature a reliable high-volume revenue line for suppliers in those geographies.
Blind-Spot Detection embeds radar or ultrasonic sensors into the mirror housing to alert drivers to vehicles in adjacent lanes, and fitment rates are rising with NCAP safety protocol updates. Integrated Indicator mirrors display turn signals visible to pedestrians and cyclists, and their fitment is increasingly mandated by urban traffic regulations in Europe and Asia. These two features, along with other specialized variants, hold the remaining share collectively and represent the fastest feature-content growth areas within the By Feature segment.
Vehicle Type Analysis
Passenger Cars dominate with 72.00% due to the highest global production and sales volumes.
In 2025, Passenger Cars held a dominant market position in the By Vehicle Type segment of the Automotive Rear View Mirror Market, with a 72.00% share. China’s vehicle sales increased 9.4% to 34.4 million units in 2025, and passenger cars represent the core of that volume, making China the single largest demand generator for mirror assemblies worldwide. Suppliers with China-based manufacturing or sourcing partnerships are best positioned to capture this growth at competitive landed cost.
Light Commercial Vehicles serve last-mile delivery, ride-hailing, and small-fleet operators, and their production volumes are rising in line with e-commerce growth across Asia and Latin America. This segment commands higher mirror content per unit than standard passenger cars because operators specify heated, powered, and camera-ready assemblies to minimize downtime risk. Heavy Commercial Vehicles require large-format exterior mirrors and increasingly specify camera-monitor systems to meet blind-zone safety regulations, adding premium unit value to a lower-volume but structurally growing segment.
Powertrain Analysis
Internal Combustion Engine Vehicles dominate with 76.00% due to the large global installed production base.
In 2025, Internal Combustion Engine Vehicles held a dominant market position in the By Powertrain segment of the Automotive Rear View Mirror Market, with a 76.00% share. ICE vehicles remain the production majority across nearly all global markets and will continue to drive the bulk of OEM mirror fitment volumes through the mid-forecast period. Suppliers that maintain ICE-platform relationships while building electric-vehicle capability protect revenue continuity during the powertrain transition.
Electric Vehicles carry more electronic content per unit than ICE equivalents, and mirror assemblies on EV programs increasingly include auto-dimming, camera, and connectivity features as standard fitment. This higher content per unit raises average mirror assembly revenue even as ICE volumes continue to represent the production majority. Hybrid Vehicles share many EV platform characteristics and follow a similar feature-content trajectory, adding to the combined premium fitment opportunity across electrified powertrains.
Sales Channel Analysis
OEM supply chains account for the dominant share of automotive rear-view mirror revenue because every new vehicle requires certified mirror assemblies as a condition of production release. OEM contracts provide volume visibility across multi-year platform cycles, allowing suppliers to invest in tooling and process automation with predictable payback timelines. Platform sourcing lock-ins also create structural barriers that protect incumbent suppliers from displacement during mid-cycle refreshes.
The Aftermarket channel serves replacement demand from vehicle collisions, wear, and feature upgrades across the global vehicle parc. Aftermarket margins are typically higher than OEM on a per-unit basis, but the channel faces competition from unbranded replacement parts in price-sensitive markets across South Asia, Southeast Asia, and Africa. Suppliers that build strong brand recognition through OEM supply relationships carry a quality-perception advantage that supports aftermarket pricing power across their product lines.
Key Market Segments
By Product Type
- Exterior Rear-View Mirror
- Interior Rear-View Mirror
By Mounting Position
- Door-Mounted
- Body-Mounted
By Technology
- Conventional Mirror
- Smart Rear-View Mirror
- Camera Monitoring System
By Feature
- Auto-Dimming
- Power Control
- Automatic Folding
- Heating Function
- Blind-Spot Detection
- Integrated Indicator
- Others
By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
By Powertrain
- Internal Combustion Engine Vehicles
- Electric Vehicles
- Hybrid Vehicles
By Sales Channel
- OEM
- Aftermarket
Regional Analysis
Asia Pacific Dominates the Automotive Rear View Mirror Market with a Market Share of 42.50%, Valued at USD 2.8 Billion
Asia Pacific holds the largest regional share at 42.50%, valued at USD 2.8 Billion, driven by the concentration of global vehicle manufacturing in China, Japan, South Korea, and India. Asia-Oceania produced 59,210,250 motor vehicles in 2025, up 8% from 2024, the strongest regional production growth recorded that year. This output scale makes Asia Pacific the most critical region for mirror supplier capacity planning and OEM qualification investment. On 28 May 2025, Visteon launched Chennai production lines for 1.3 MP to 8 MP automotive cameras and display-backlight units with an initial USD 10 million investment, reinforcing the region’s role as a manufacturing hub for advanced mirror-adjacent technologies.
China produced 34,530,738 motor vehicles in 2025, up 10% from 2024, making it the single largest national production market and the primary demand driver for mirror assemblies within Asia Pacific. Japan produced 8,410,232 motor vehicles in 2025, up 2% from 2024, and its OEM base continues to specify precision mirror assemblies across domestic and export platforms. Emerging countries and regions produced 58,228,107 motor vehicles in 2025, up 8% from 2024, and the bulk of this growth concentrated in Asia, widening the production gap between emerging and developed markets. On 18 February 2026, Valeo announced an investment exceeding €200 million in India and targeted approximately €700 million in Indian sales by 2028, signaling that Tier-1 suppliers view India as the next high-growth production hub within the region.
Developed countries and regions produced 38,155,543 motor vehicles in 2025, down 1% from 2024, reflecting the continued migration of volume production to lower-cost emerging-market locations. This output decline does not reduce the value opportunity in developed markets, where premium and smart mirror fitment rates are highest and regulatory mandates drive feature-content upgrades. Europe remains a critical regulatory setter for the global market, and Gentex’s January 2026 assumptions forecast European light-vehicle production of 16.9 million units in 2026, providing a volume planning baseline for suppliers serving that region.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Drivers
Global vehicle production increased from 92.7 million units in 2024 to 96.4 million units in 2025, a 3.9% expansion, while vehicle sales advanced by 4.7%, enlarging the OEM fitment base before accounting for richer mirror content. Each additional 1 million vehicles creates demand for approximately 2 million exterior mirror assemblies and as many as 1 million interior mirror positions. Sustained production near the 2025 level could raise supplier line utilization by an estimated 5 to 8 percentage points and reduce conversion cost per assembly by approximately 3% to 6%, supporting standardized-module business models and protecting margins despite OEM price pressure.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Vehicle Production Rebound | +0.8% | Global, led by Asia | Short term (≤ 2 years) |
| Mandatory Rear-Visibility Fitment | +0.5% | Europe, North America, East Asia | Short term (≤ 2 years) |
| EV Electronic-Content Growth | +0.4% | China, Europe, North America | Medium term (2–4 years) |
| SUV Blind-Zone Mitigation | +0.3% | North America, China, Middle East | Short term (≤ 2 years) |
| Premium Auto-Dimming Adoption | +0.2% | Global premium-vehicle segments | Medium term (2–4 years) |
| Harsh-Weather Feature Demand | +0.1% | Northern Europe, North America, Northeast Asia | Medium term (2–4 years) |
Restraints
Camera-enabled and digital mirror systems add image sensors, processors, displays, heaters, wiring, safety software, and electromagnetic-compatibility qualification to conventional glass assemblies, creating an estimated 2 to 4 times bill-of-materials multiple and an incremental vehicle-level cost of roughly USD 100 to USD 300. On a mass-market program producing 250,000 vehicles annually, even a USD 120 incremental cost adds USD 30 million to yearly direct-material expenditure. EU registrations grew only 1.8% in 2025 and remained below pre-pandemic volumes, reinforcing affordability sensitivity in the most regulation-intensive mirror market. The modeled -0.5% CAGR deduction reflects an immediate affordability barrier that can compress supplier gross margins by an estimated 2 to 4 percentage points unless scale procurement reduces unit costs.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Smart-Mirror BOM Premium | -0.5% | Global mass-market segments | Short term (≤ 2 years) |
| Weak New-Vehicle Affordability | -0.3% | Europe, Latin America, Africa | Short term (≤ 2 years) |
| OEM Price-Down Requirements | -0.2% | Global Tier-1 supply chains | Short term (≤ 2 years) |
| Long Platform Sourcing Lock-Ins | -0.2% | Europe, Japan, North America | Medium term (2–4 years) |
| Insurance Repair-Cost Resistance | -0.1% | North America, Europe, Australia | Medium term (2–4 years) |
| Unbranded Replacement Competition | -0.1% | South Asia, Southeast Asia, Africa | Short term (≤ 2 years) |
Challenges
A modern vehicle can contain as many as 3,000 semiconductor devices, while critical inputs and manufacturing stages remain concentrated among a limited number of suppliers. Automotive microcontroller and processor bottlenecks have produced lead-time ranges of approximately 16 to 26 weeks, exposing camera-based mirror modules to shipment stoppages when image sensors, serializers, or power-management devices are unavailable. Sustained mitigation requires at least 2 qualified sources for critical components and 8 to 12 weeks of targeted buffer inventory, potentially raising near-term engineering expenditure by 5% to 10% but reducing future line-stop exposure.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Concentrated Semiconductor Supply | -0.3% | Global electronics supply chains | Medium term (2–4 years) |
| Lens Soiling and Weather | -0.2% | Global, especially extreme climates | Medium term (2–4 years) |
| Safety Software Validation | -0.2% | Europe, North America, Japan | Long term (≥ 4 years) |
| Display Latency Human Factors | -0.1% | Global digital-mirror programs | Medium term (2–4 years) |
| Vehicle-Variant Tooling Proliferation | -0.1% | Global multi-platform manufacturers | Medium term (2–4 years) |
| Functional-Safety Talent Gaps | -0.1% | Europe, North America, emerging Asian hubs | Long term (≥ 4 years) |
Opportunities
Commercial fleet camera-monitor retrofits represent a white-space revenue channel beyond current OEM fitment cycles. Camera-monitor systems can improve heavy-truck energy efficiency by up to approximately 1.5%, while alternative system designs cite fuel-consumption reductions of up to 2% through lower aerodynamic drag. Suppliers that combine hardware with diagnostics, lens-cleaning support, and software services can shift gross margin from approximately 18% to 24% for stand-alone hardware to 25% to 32% for bundled offerings, adding recurring service revenue equal to 5% to 10% of initial unit value annually.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Commercial Fleet CMS Retrofits | +0.5% | Europe, North America, developed Asia | Medium term (2–4 years) |
| Autonomous Mobility Sensor Fusion | +0.3% | China, North America, Europe | Long term (≥ 4 years) |
| Off-Highway Visibility Systems | +0.25% | North America, Australia, Middle East | Medium term (2–4 years) |
| Circular Lightweight Mirror Modules | +0.2% | Europe, Japan, South Korea | Medium term (2–4 years) |
| Localized Emerging-Market Assembly | +0.15% | India, Southeast Asia, Latin America | Medium term (2–4 years) |
| Predictive Maintenance Services | +0.1% | Global connected-fleet operators | Long term (≥ 4 years) |
Key Company Insights
Gentex Corporation generated consolidated net sales of USD 2.534 billion in 2025, up 10% from 2024, with VOXX contributing USD 267.2 million to that total following its April 2025 acquisition. Gentex shipped 44.825 million auto-dimming mirrors in 2025, including 16.217 million exterior and 19.882 million international interior units, despite a 6% year-on-year volume decline that signals ASP expansion offsetting unit pressure. The January 2026 introduction of the next-generation Full Display Mirror, already available across more than 140 vehicle models, cements Gentex’s position as the technology reference for interior digital mirror systems globally.
Magna International Inc. generated total sales of USD 42.010 billion in 2025, with its Power and Vision segment contributing USD 15.198 billion. Magna invested USD 1.313 billion in fixed-asset additions in 2025 and its 2026 outlook assumed North American light-vehicle production of 15.0 million units, reflecting confidence in platform volume stability. Ford’s extended-warranty program covered up to approximately 14.9 million vehicles equipped with Magna-supplied rear-view cameras, exposing a quality-risk dimension that Magna addressed through its ongoing Mercedes-Benz partnership expansion after producing more than 500,000 G-Class vehicles at its Graz facility. On 20 October 2025, Continental announced an investment exceeding USD 85 million to expand its Mount Pleasant, Iowa facility, reinforcing North American manufacturing commitments across the Tier-1 mirror supply base.
Key Players
- Gentex Corporation
- Magna International Inc.
- Samvardhana Motherson Reflectec
- Ficosa International S.A.
- Murakami Corporation
- MEKRA Lang GmbH & Co. KG
- Valeo S.A.
- Continental AG
- Ichikoh Industries, Ltd.
- Tokai Rika Co., Ltd.
- SL Corporation
- Mitsuba Corporation
- FLABEG Automotive Glass Group
- Lumax Industries Limited
- Ishizaki Honten Company, Ltd.
Recent Developments
- December 2025 – HARMAN agreed to acquire ZF’s ADAS business for €1.5 billion, consolidating advanced driver-assistance system capabilities under a single electronics platform provider.
- 28 March 2024 – Valeo opened its Daegu ADAS-sensor plant in South Korea following a USD 56 million investment agreement, adding regional production capacity for radar and camera sensing modules.
- November 2024 – Lumax Industries announced planned Phase 2 capital expenditure of ₹100 crore to ₹125 crore for its Chakan facility, adding capacity for approximately 250,000 vehicle sets.
- November 2025 – Lumax Auto Technologies approved an investment of up to ₹0.93 crore for an equity stake of up to 26% in a strategic partner entity.
- November 2025 – Gentex and Genie added Aladdin Connect to the HomeLink ecosystem, which had approximately 110 million units operating on the road, extending connected-home integration across the installed mirror base.
- 25 March 2026 – Samvardhana Motherson and Hellmann executed a 51:49 automotive-logistics joint venture with USD 10 million authorized capital and USD 1 million paid-up capital.
- 10 March 2026 – Ichikoh Industries reported FY2025 capital investment of ¥3.235 billion, reflecting continued plant and tooling reinvestment across its mirror manufacturing operations.
- 9 April 2026 – Mutares signed agreements to acquire two Magna businesses with combined expected 2025 revenue of approximately USD 320 million.
- 10 April 2026 – Bosch and Qualcomm expanded their ADAS partnership after delivering more than 10 million Snapdragon-powered cockpit computers, advancing integrated sensor and display platform development.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 6.6 Billion |
| Forecast Revenue (2035) | USD 11.6 Billion |
| CAGR (2026-2035) | 5.8% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Product Type (Exterior Rear-View Mirror, Interior Rear-View Mirror), By Mounting Position (Door-Mounted, Body-Mounted), By Technology (Conventional Mirror, Smart Rear-View Mirror, Camera Monitoring System), By Feature (Auto-Dimming, Power Control, Automatic Folding, Heating Function, Blind-Spot Detection, Integrated Indicator, Others), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), By Powertrain (Internal Combustion Engine Vehicles, Electric Vehicles, Hybrid Vehicles), By Sales Channel (OEM, Aftermarket) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Gentex Corporation, Magna International Inc., Samvardhana Motherson Reflectec, Ficosa International S.A., Murakami Corporation, MEKRA Lang GmbH & Co. KG, Valeo S.A., Continental AG, Ichikoh Industries Ltd., Tokai Rika Co. Ltd., SL Corporation, Mitsuba Corporation, FLABEG Automotive Glass Group, Lumax Industries Limited, Ishizaki Honten Company Ltd. |
| Customization Scope | Customization for segments, region/country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








