


Report Overview
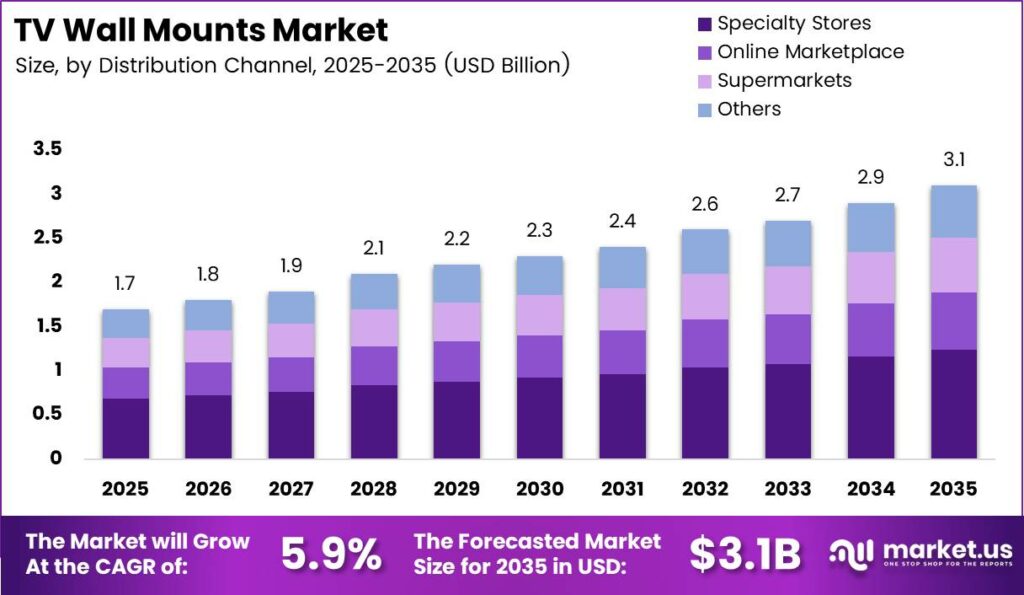
Global TV Wall Mounts Market size is expected to be worth around USD 3.1 Billion by 2035 from USD 1.7 Billion in 2025, growing at a CAGR of 5.9% during the forecast period 2026 to 2035.
The TV wall mounts market covers brackets, arms, and mounting hardware designed to secure flat-panel televisions to walls and vertical surfaces. Products span fixed, tilting, and full-motion configurations and serve residential users, commercial offices, educational institutions, and healthcare facilities. Distribution runs through specialty AV retailers, mass-market chains, online marketplaces, and direct installation channels. The market connects hardware manufacturers, retail distributors, and professional installers across global supply chains.
Key Takeaways
- The Global TV Wall Mounts Market was valued at USD 1.7 Billion in 2025 and is projected to reach USD 3.1 Billion by 2035, growing at a CAGR of 5.9% during the forecast period 2026 to 2035.
- By Cut Height, Fixed TV Mounts dominated the market with a 62.34% share in 2025, while Full Motion TV Mounts represented the fastest-growing segment.
- By TV Size Compatibility, the 32 to 54 Inches segment held the largest share at 52.34% in 2025, while the 55 Inches and Above segment recorded the fastest growth.
- By Distribution Channel, Specialty Stores led with a 36.45% share in 2025, while Online Marketplace emerged as the fastest-growing channel.
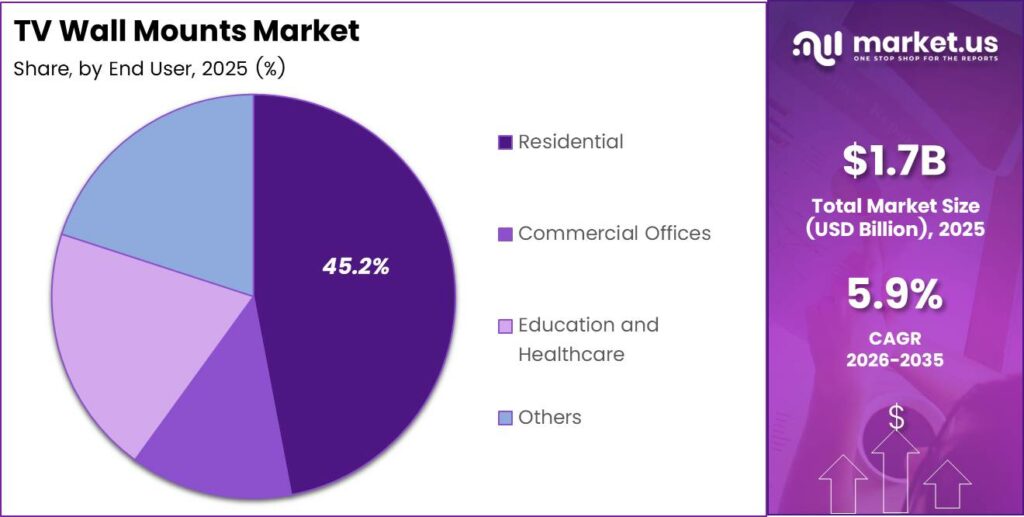
- By End User, Residential accounted for the largest share at 40.22% in 2025 and also represented the fastest-growing end-user segment.
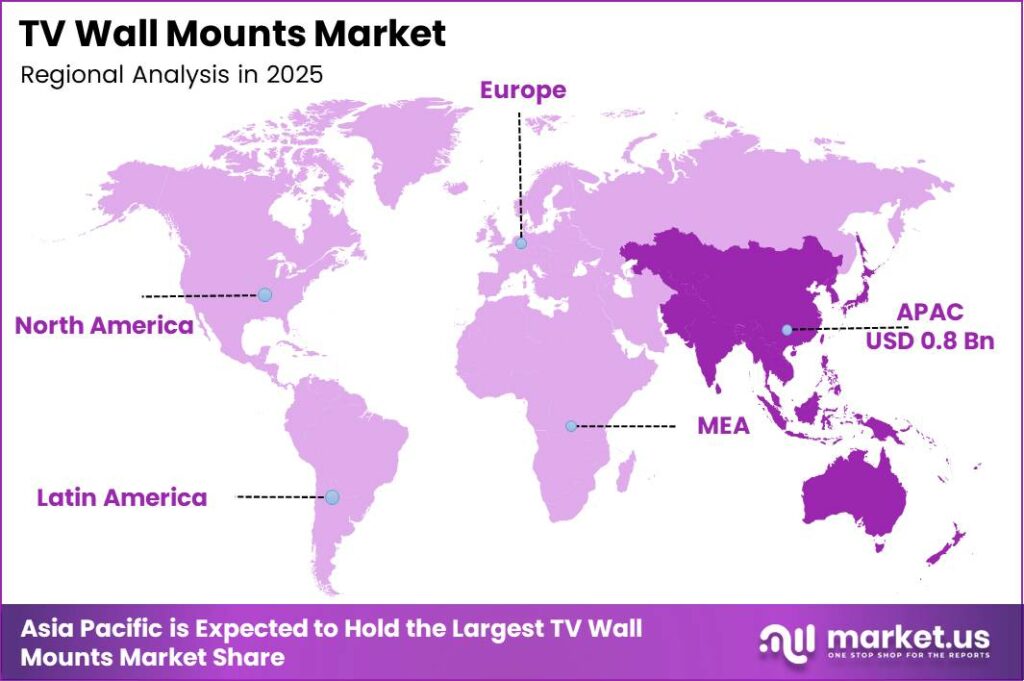
- Asia-Pacific dominated the global market with a 47.56% share, valued at USD 0.80 Billion in 2025, while Middle East & Africa recorded the fastest regional growth.
However, government and regulatory activity shapes installation safety standards that directly affect product design and procurement. Compliance with load-testing standards such as UL 2442 determines whether commercial and institutional buyers will specify a product. Buyers in public-sector segments including education and healthcare increasingly require certified products, giving compliant manufacturers a structural procurement advantage over uncertified lower-cost alternatives.
As a result, the convergence of larger television purchases and urban space constraints accelerates mount adoption across both replacement and new-installation cycles. As per our research, e-commerce accounted for 16.6% of seasonally adjusted total U.S. retail sales in the fourth quarter of 2025. This share signals that online channels now carry meaningful wall mount discovery and purchase volume. Meanwhile, LG Electronics announced U.S. pricing for its OLED evo G6 and C6 televisions in March 2026, with the G6 starting at $2,499 across five sizes from 55 to 97 inches, confirming that premium large-screen hardware continues to enter the market and expand the addressable mount-upgrade base.
This reflects broader television hardware trends. Residential consumers replacing furniture-based setups with wall installations drive repeat purchase cycles across the fixed and full-motion mount segments. This creates predictable volume for distributors and installers who bundle mounting services with television sales. Retailers that integrate installation offers at point of sale capture higher average transaction values than those selling hardware alone.
Consequently, the commercial and institutional end-user segments add procurement stability to the residential growth base. Offices, hospitality venues, and healthcare networks purchase mounts in bulk and on replacement cycles tied to display refresh schedules. This layered demand structure reduces the market’s dependence on any single buyer category and supports consistent revenue across both specialty and online distribution channels.
Cut Height Analysis
Fixed TV Mounts dominate with 62.34% due to low cost and simple installation.
In 2025, Fixed TV Mounts held a dominant market position in the By Cut Height segment of the TV Wall Mounts Market, with a 62.34% share. Fixed mounts deliver a stable, flush profile that suits the majority of residential rooms and commercial display installations. JEITA reported that Japan’s domestic 4K television shipments totaled 2.429 million units in 2025, confirming that mainstream consumers are purchasing advanced display hardware that benefits from clean, permanent wall positioning. Fixed mounts remain the first-choice accessory for buyers who prioritize cost control and installation simplicity over viewing-angle flexibility.
Full Motion TV Mounts represent the fastest-growing sub-segment in this category, driven by consumer demand for adjustable viewing angles across open-plan residential and multi-occupancy commercial spaces. Vogel’s UP Full Motion mounts offer rotation up to 120°, while UP Full Motion+ models extend rotation to 180°, providing measurable flexibility that fixed alternatives cannot match. These technical specifications translate directly into higher average selling prices and wider installation margins for dealers. Buyers in premium residential and hospitality segments increasingly specify full-motion hardware as a standard rather than an upgrade.
TV Size Compatibility Analysis
32 to 54 Inches dominates with 52.34% due to high residential mid-size screen prevalence.
In 2025, the 32 to 54 Inches segment held a dominant market position in the By TV Size Compatibility segment of the TV Wall Mounts Market, with a 52.34% share. This size band aligns with the broadest range of household room dimensions and budget brackets globally. JEITA data shows Japan’s domestic shipments of 40–49 inch televisions totaled 1.222 million units in 2025, confirming that mid-size screens remain the highest-volume category in a developed market. Mount manufacturers targeting this segment command the largest installed base and the most frequent replacement cycle.
The 55 Inches and Above segment is the fastest-growing size category, fueled by consumer premiumization and a widening product range from major television brands. JEITA reported Japan’s domestic shipments of 60-inch-and-above televisions at 616,000 units in 2025, while Samsung America announced its S95H, S90H, and S85H OLED series in April 2026, covering sizes from 42 to 83 inches. This expansion of large-format models broadens the addressable market for heavy-duty and motorized mounts. Suppliers who develop higher-rated brackets for this tier early will secure attach rates before the segment matures.
The Below 32 Inches sub-segment serves secondary display applications including kitchens, bedrooms, and small commercial spaces. JEITA’s domestic shipments in the sub-29-inch television category totaled 421,000 units in Japan in 2025. This segment supports steady low-ticket volume rather than margin expansion. Manufacturers that bundle compact mounts with small-screen television retail packages can capture incremental attach revenue without requiring dedicated channel investment in this tier.
Distribution Channel Analysis
Specialty Stores dominate with 36.45% due to expert consultation driving premium attach rates.
In 2025, Specialty Stores held a dominant market position in the By Distribution Channel segment of the TV Wall Mounts Market, with a 36.45% share. Specialty AV retailers convert higher proportions of television purchases into bundled mount and installation sales because trained staff can match bracket specifications to display models. Best Buy operated 1,117 stores across its Domestic and International segments at the end of fiscal 2025, illustrating the physical-retail footprint through which mount attach rates are generated at scale. This store network gives category-leading brands consistent shelf presence and installation referral volume that online-only players cannot replicate.
Online Marketplaces represent the fastest-growing distribution channel, driven by competitive pricing, consumer familiarity with self-installation, and broad SKU availability. The U.S. Census Bureau reported U.S. retail e-commerce sales at an estimated $316.1 billion in the fourth quarter of 2025, with e-commerce representing 16.6% of total seasonally adjusted retail sales. Approximately 6.0 billion people worldwide used the internet in 2025, according to ITU, expanding the addressable digital shopper base for mount vendors in every geography. Brands that optimize product listings, installation guides, and customer reviews for online platforms will capture disproportionate share as digital channel penetration widens.
Supermarkets and other channel formats hold the remaining distribution share. Data from Eurostat shows 77% of EU internet users bought or ordered goods or services online in 2024, confirming that even generalist retail channels benefit from cross-channel traffic between physical browsing and digital purchase. This means mount suppliers who maintain omnichannel availability, including supermarket shelf space and online marketplace listings, reduce the risk of losing a sale to channel friction at the point of decision.
End User Analysis
Residential dominates with 40.22% due to mass-market television replacement and upgrade cycles.
In 2025, Residential held a dominant market position in the By End User segment of the TV Wall Mounts Market, with a 40.22% share. Home owners and renters upgrading to larger flat-panel televisions generate the broadest and most frequent mount purchase cycles in the market. Sony India launched its 98-inch BRAVIA 5 Mini LED television in July 2025 at INR 6,49,990, with a three-year warranty as part of the launch promotion, demonstrating that high-price large-screen products are actively entering residential segments in major emerging markets. This price point signals a widening residential premium tier that demands heavy-duty, aesthetically finished mounting solutions.
Commercial Offices, Education and Healthcare, and Other end-user segments collectively serve institutional procurement buyers who purchase mounts in planned bulk cycles. These segments prioritize certified load ratings, compatibility with digital signage hardware, and structured maintenance contracts over price. The institutional channel offers mount manufacturers predictable order volumes tied to infrastructure refresh schedules. Suppliers that develop product lines with explicit load certification and offer installation and service packages will hold a competitive advantage over commodity hardware vendors in this portion of the market.
Key Market Segments
By Cut Height
- Full Motion TV Mounts
- Fixed TV Mounts
By TV Size Compatibility
- 55 Inches and Above
- 32 to 54 Inches
- Below 32 Inches
By Distribution Channel
- Specialty Stores
- Online Marketplace
- Supermarkets
- Others
By End User
- Residential
- Commercial Offices
- Education and Healthcare
- Others
Regional Analysis
Asia-Pacific Dominates the TV Wall Mounts Market with a Market Share of 47.56%, Valued at USD 0.80 Billion
Asia-Pacific leads the global TV Wall Mounts Market with a 47.56% share, supported by a large and active consumer electronics base across China, Japan, South Korea, India, and Australia. ITU data confirms internet use reached 77% of the Asia-Pacific population in 2025, enabling online mount discovery and purchase at scale across the region’s urban markets. Samsung India launched 72 television models in May 2026 across Micro RGB, OLED, Neo QLED, and other categories, with Micro RGB sizes starting at INR 124,990, confirming that high-volume product introductions continue to stimulate mount demand. Manufacturers and distributors that align product availability with Asia-Pacific television launch cycles will capture attach-rate revenue ahead of competitors who rely on post-purchase retrofit demand.
The Middle East and Africa region represents the fastest-growing market for TV wall mounts globally. The IMF projected 1.4% economic growth for the Middle East and North Africa aggregate in 2026, and internet use reached 70% of the Arab States population in 2025 according to ITU, creating a digital-purchase-ready consumer base that is still early in the mount adoption curve. Samsung announced The Frame HL03H hospitality television at HITEC 2026 in June, covering 43-, 55-, 65-, and 75-inch sizes with a Slim Fit Wall Mount and a global rollout planned from the second half of 2026. This hospitality product specifically targets the hotel and commercial display segment where mount procurement is a built-in requirement.
By contrast, Africa’s internet use stood at 36% of the population in 2025, per ITU, indicating a market where digital channel penetration remains constrained and physical retail distribution carries disproportionate importance. This structural difference means mount suppliers entering Sub-Saharan African markets must prioritize specialty and general-trade physical distribution rather than digital-led go-to-market models. North America and Europe remain mature, high-value regions where installation bundling, product certification, and commercial account management drive incremental revenue.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Market Dynamics
Market Opportunity Analysis - Fixed mount dominance and underpenetrated emerging regions signal entry points for focused players
Fixed TV Mounts hold a 62.34% share of the mount-type segment, yet the product category remains commoditized at the lower end of the price spectrum. Suppliers who introduce fixed mounts with enhanced cable management, tool-free level adjustment, or pre-assembled hardware bundles can command price premiums above the commodity tier without requiring buyers to upgrade to full-motion configurations. This product differentiation opportunity sits within an already-dominant volume segment, reducing market development risk for manufacturers with existing distribution access.
The Below 32 Inches sub-segment generates steady low-ticket volume across kitchen, bedroom, and small-office applications without attracting significant product investment from leading brands. This neglect creates a white-space position for regional manufacturers or value-focused entrants to build category leadership in compact mount configurations. Bundling small-bracket SKUs with secondary display products or smart-home accessories could accelerate attachment rates in this sub-segment without requiring dedicated channel investment.
The Middle East and Africa region carries the fastest regional growth rate in the market while remaining at an early stage of mount-category penetration. Commercial hospitality and retail display investment in Gulf Cooperation Council markets, combined with Samsung’s planned second-half 2026 rollout of the Frame HL03H hospitality television with an integrated Slim Fit Wall Mount, creates a clear hardware-driven pull for locally available commercial bracket inventory. Distributors who establish stocking positions in GCC markets ahead of this hospitality hardware cycle will capture first-mover share before global competitors activate regional logistics.
The Online Marketplace channel is the fastest-growing distribution format but remains underdeveloped as a post-sale service and installation conversion channel. Brands that add installation booking integrations, compatibility verification tools, and review-led content to their online marketplace listings can increase attach rates without adding physical retail overhead. This digital service layer turns a transactional channel into a recurring customer relationship asset, particularly for the residential segment where repeat purchases follow each television upgrade cycle.
Technology and Innovation Landscape - Flush-profile engineering, motorized systems, and digital configuration tools define the next competitive cycle
Vogel’s ELITE Fixed TV wall mounts position compatible televisions 1.3 cm from the wall, a specification that responds directly to consumer demand for flush aesthetics in premium residential and hospitality installations. This near-zero gap engineering requires tighter tolerances on bracket geometry and cable routing than standard fixed designs, creating a technical barrier that commodity manufacturers cannot clear without dedicated tooling investment. Brands that achieve certified ultra-slim profiles will command specification preference in hotel, gallery, and high-end residential projects where aesthetic integration outweighs cost sensitivity.
Full-motion mount engineering has advanced to support rotation arcs of 120° on standard configurations and 180° on enhanced models in the Vogel’s UP series, enabling wall-mount deployment in room configurations that previously required ceiling or floor-standing alternatives. This extended range of motion opens new installation contexts in open-plan commercial spaces, healthcare waiting areas, and multi-use residential rooms. Manufacturers who certify full-motion brackets for the growing inventory of 65-inch-and-above televisions will serve the intersection of the two highest-growth product dimensions in the market.
Peerless-AV’s SEAMLESS Connect Universal dvLED Mounting System, launched in May 2025, introduced a minimum depth of 40 mm, 40 mm of Z-axis adjustment, and 13 mm of wall-plate height adjustment into the video-wall segment. These precision adjustment specifications reduce on-site installation time and rework costs for commercial AV integrators, translating a hardware feature into a measurable labor-cost benefit. Products that reduce installer time-on-site will gain preference in commercial procurement where labor cost is a significant component of total project cost.
Vogel’s Automated Video Wall Engineer service, introduced in April 2024, delivers customized video-wall mounting quotations within 24 hours, including parts lists and assembly drawings. This digital configuration capability converts a complex, manually scoped commercial project into a repeatable, fast-response sales process. Manufacturers who invest in digital configuration and quoting platforms will shorten commercial sales cycles, reduce pre-sales engineering cost, and compete more effectively against generalist AV hardware suppliers who rely on manual specification processes.
Drivers
Large-screen television mix expansion is the primary demand driver for TV wall mounts. As television manufacturers shift their shipment mix toward 65-inch and larger models, buyers require higher-rated brackets that exceed the load and dimensional specifications of mounts purchased with previous displays. TCL reported that its global television shipments grew 14.8% in 2024, with shipments of 65-inch-and-above models rising 21.3% and 75-inch-and-above models rising 39.8%. This mix shift creates both new attach sales and replacement demand for undersized existing mounts.
Retail attachment and installation bundling add direct conversion lift to organic mount demand. Specialty retailers and e-commerce platforms that bundle mount sales with television purchases remove the friction of a separate purchasing decision, accelerating close rates. Residential floor-space constraints in dense urban markets across Asia-Pacific and Europe also push buyers toward wall-mounted solutions over furniture placement. Full-motion viewing preferences reinforce this transition, as buyers in open-plan layouts require adjustable bracket configurations to maintain comfortable sightlines from multiple seating positions.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Large-screen television mix expansion | +0.45% | Global; strongest in North America, China and Europe | Short term (≤ 2 years) |
| Retail attachment and installation bundling | +0.20% | North America, Europe and urban Asia-Pacific | Short term (≤ 2 years) |
| Residential floor-space optimization | +0.15% | Dense urban markets across Asia-Pacific and Europe | Medium term (2–4 years) |
| Full-motion viewing-position preferences | +0.12% | Global residential markets | Short term (≤ 2 years) |
| Established commercial display procurement | +0.08% | North America, Europe and developed Asia-Pacific | Medium term (2–4 years) |
Restraints
Unsuitable wall structures are the primary physical constraint on TV wall mount conversion rates. Buildings constructed with lightweight partition walls, hollow-core doors, or plasterboard-only surfaces cannot support full-motion bracket configurations without remedial reinforcement, and many buyers abandon the purchase rather than incur additional structural costs. SANUS advises against using full-motion mounts with its steel-stud installation kit due to stud-twisting risks, while approving fixed and tilting configurations for loads up to 175 pounds. This product-level restriction illustrates how substrate limitations reduce completed transactions across the market.
Landlord restrictions on permanent wall alterations further reduce mount conversion in urban rental markets across North America, Europe, and Asia-Pacific. Renters who cannot drill or anchor into walls are excluded from fixed and full-motion mount categories entirely. Household discretionary-spending constraints add cyclical pressure on mid-ticket mount purchases, while compatible installed-mount reuse limits replacement frequency in mature television ownership markets. Together, these structural and behavioral barriers reduce addressable volume below the level implied by raw television shipment data alone.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Unsuitable wall structures blocking installation | -0.22% | Global; material in lightweight-partition buildings | Short term (≤ 2 years) |
| Landlord restrictions on wall alterations | -0.15% | Rental housing across major urban markets | Short term (≤ 2 years) |
| Household discretionary-spending constraints | -0.12% | Price-sensitive emerging and developed markets | Short term (≤ 2 years) |
| Compatible installed-mount reuse | -0.10% | Mature television ownership markets | Long term (≥ 4 years) |
| Furniture-based television placement substitution | -0.06% | Global residential markets | Medium term (2–4 years) |
Challenges
Load-validation and fatigue engineering represent the most capital-intensive ongoing challenge for TV wall mount manufacturers. UL 2442 requires mounts rated for televisions at 100 pounds or less to be tested at at least 4 times the rated load, meaning a 100-pound-rated product must survive a test load of at least 400 pounds without cracking, bending, or distortion. A mount rated for 150 pounds must survive at least 500 pounds under the heavier-unit requirement. These test thresholds create a cost floor that limits how aggressively manufacturers can reduce bill-of-materials costs without compromising certification.
Mounting-interface compatibility fragmentation and steel-input cost volatility add supply-chain and engineering overhead that affects product margins across the category. Different television brands use varying VESA hole patterns and panel depths, requiring manufacturers to maintain broad SKU portfolios or accept narrowed compatibility. Steel procurement volatility creates input cost uncertainty that is difficult to pass fully to retail price-sensitive buyers. Installer scheduling constraints and freight synchronization challenges further slow commercial project completion rates, reducing repeat-order cadence from institutional accounts.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Load-validation and fatigue engineering | -0.18% | Global; strongest in safety-sensitive procurement | Medium term (2–4 years) |
| Mounting-interface compatibility fragmentation | -0.12% | Global television and bracket supply chains | Medium term (2–4 years) |
| Steel-input procurement cost volatility | -0.09% | Global; concentrated manufacturing hubs | Short term (≤ 2 years) |
| Installer scheduling and training | -0.07% | North America, Europe and dispersed urban markets | Medium term (2–4 years) |
| Freight and inventory synchronization | -0.04% | Import-dependent markets and cross-border channels | Short term (≤ 2 years) |
Opportunities
Contracted mount lifecycle services represent the clearest incremental revenue opportunity for manufacturers and distributors with existing commercial account relationships. Rather than counting a single bracket sale per installation, suppliers can develop inspection, relocation, and display-refresh contracts that generate recurring revenue from the same account. Standard AV’s 3-year warranty for metal video-wall mounts, which excludes relocation and wear, illustrates the boundary between current product protection and the wider service offering that remains undeveloped. Suppliers who build technician partnerships and asset-tracking records can convert warranty expiry into contract renewal events.
Accessible motorized positioning systems and specialized healthcare bedside applications open two distinct institutional segments that commodity mount manufacturers have not systematically addressed. Aging-population markets in Japan, Western Europe, and North America create demand for motorized brackets that users can operate without physical exertion. Hospital networks require hygiene-compliant, height-adjustable bedside mounts that existing residential product lines do not satisfy. Early movers who develop certified healthcare and accessibility configurations will establish specification-list positions that are difficult for late entrants to displace once procurement frameworks are set.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Contracted mount lifecycle services | +0.30% | North America, Europe and developed Asia-Pacific | Medium term (2–4 years) |
| Accessible motorized positioning systems | +0.18% | Aging-population markets and accessible housing | Medium term (2–4 years) |
| Refurbishment and certified resale channels | +0.14% | Europe and organized secondary-equipment markets | Medium term (2–4 years) |
| Specialized healthcare bedside applications | +0.10% | Hospital networks across developed and emerging markets | Long term (≥ 4 years) |
| Regional aftermarket distributor consolidation | +0.08% | Fragmented Asia-Pacific and Latin American channels | Medium term (2–4 years) |
Key Company Insights
Legrand AV operates within Legrand Group, which reported an adjusted operating margin of 20.7% after acquisitions in 2025 across its full group operations. This margin profile signals a parent organization with financial capacity to fund product development and distribution expansion in the AV mounting category. Legrand Group’s June 2026 acquisition of Girtz Industries, a U.S. modular-power specialist generating nearly $80 million in annual revenue, reflects a broader infrastructure integration strategy that reinforces Legrand AV’s commercial installation channel positioning.
LG Electronics reported consolidated sales of KRW 89,201 billion in 2025 across all divisions, providing the balance-sheet depth to invest in proprietary mounting system development aligned with its television hardware roadmap. LG announced the Gallery TV ahead of CES 2026, offering 55– and 65-inch flush-mount models with customizable magnetic frames, a design move that creates a tighter dependency between LG display hardware and compatible mounting accessories. This vertical integration approach limits third-party mount substitution risk and builds a defensible ecosystem position for LG’s AV and mounting product lines.
Key Players
- Legrand AV
- Vogels
- Peerless AV
- Milestone AV Technologies
- Samsung Electronics
- LG Electronics
- Sony Corporation
- Ergotron
- AVF Group
- Loctek Ergonomic Technology
- Mounting Dream
- OmniMount
- VideoSecu
- Kanto Solutions
- Sanus Systems
- Other Key Players
Geopolitical Impact Analysis
Global shipping disruptions directly affect the cost and lead time of TV wall mount hardware, which depends on steel fabrication and assembly concentrated in Asia-Pacific manufacturing hubs. According to UNCTAD’s Review of Maritime Transport 2025, shipping moves more than 80% of the world’s merchandise trade, and port congestion events have extended average container transit times measurably across key trade lanes. Steel input cost volatility compounds this logistics pressure. The WTO reported that global merchandise trade volume growth slowed to under 2% in recent periods of peak geopolitical disruption, constraining the supply-side economics of bracket manufacturers reliant on cross-border component flows.
Trade tariff escalation between major economies adds a structurally higher landed-cost burden for import-dependent markets purchasing mounts manufactured in China or other single-country production hubs. ITU data confirms internet use reached 70% across Arab States in 2025, signaling that digital retail channels in the Middle East and Africa region are active and growing, but the physical supply chain serving those markets faces tariff and routing complexity that increases minimum viable price points. As a result, manufacturers who diversify production across Vietnam, Mexico, or Eastern Europe reduce single-origin tariff exposure and gain pricing flexibility in markets where margin compression from trade policy is most acute.
Recent Developments
- January 4, 2026: LG Electronics unveiled the OLED evo W6 True Wireless Wallpaper TV with a 9 mm-class body, an improved flush-fitting wall mount, and support for a 4K 165 Hz refresh rate.
- January 22, 2026: Peerless-AV announced the SmartMount STS680 Ultra-Slim Scissor Wall Mount for displays measuring 49 inches to 120 inches and above, with extension up to 325 mm from the wall for servicing.
- April 2, 2026: Samsung Electronics America announced refreshed The Frame Pro and The Frame televisions, adding a 55-inch The Frame Pro and a 98-inch The Frame. The Frame included a Slim Fit Wall Mount and the 98-inch model was listed at $4,499.99.
- May 26, 2026: Samsung India launched 72 television models across Micro RGB, OLED, Neo QLED, The Frame, Mini LED, and UHD categories. Its Micro RGB range covered sizes from 55 to 115 inches and started at INR 124,990.
- August 3, 2026: Sony India announced the 115-inch BRAVIA 9II True RGB television, expanding its Indian True RGB portfolio to sizes from 55 to 115 inches, with a listed price of INR 28,99,990.
- May 20, 2025: Peerless-AV launched the SEAMLESS Connect Universal dvLED Mounting System with a minimum depth of 40 mm, 40 mm of Z-axis adjustment, and 13 mm of wall-plate height adjustment.
- April 2024: Vogel’s introduced its Automated Video Wall Engineer service, offering customized video-wall mounting quotations within 24 hours, including parts lists and view, detail, and assembly drawings.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 1.7 Billion |
| Forecast Revenue (2035) | USD 3.1 Billion |
| CAGR (2026-2035) | 5.9% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Cut Height (Full Motion TV Mounts, Fixed TV Mounts), By TV Size Compatibility (55 Inches and Above, 32 to 54 Inches, Below 32 Inches), By Distribution Channel (Specialty Stores, Online Marketplace, Supermarkets, Others), By End User (Residential, Commercial Offices, Education and Healthcare, Others) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Legrand AV, Vogels, Peerless AV, Milestone AV Technologies, Samsung Electronics, LG Electronics, Sony Corporation, Ergotron, AVF Group, Loctek Ergonomic Technology, Mounting Dream, OmniMount, VideoSecu, Kanto Solutions, Sanus Systems, Other Key Players |
| Customization Scope | Customization for segments, region / country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License | Multi-User License (Up to 5 Users) | Corporate Use License (Unlimited User and Printable PDF) |








